
 Rail Glazing Market | 2026-2036
Rail Glazing Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Glazing Market Analysis
Aftermarket glazing refurbishment and software-defined tinting controls are restructuring how rail operators procure cabin transparency systems. AGC Inc. leverages its integrated chemical-to-glass pipeline to dominate high-clarity substrate supply for East Asian bullet-train builders. Saint-Gobain S.A. anchors European demand through its specialized laminated safety lines certified to stringent UIC frameworks. Fuyao Glass Industry Group Co., Ltd. competes on cost-engineered tempered products for domestic Chinese freight and passenger retrofit programs.
Rail glazing comprises engineered transparent assemblies—typically laminated soda-lime or chemically strengthened sheets bonded with polyvinyl butyral interlayers—that seal against pressure differentials, acoustic intrusion, and ballistic impact while maintaining optical clarity for operators and passengers. Laminated glass commands the premium tier due to post-breakage retention requirements in high-speed applications, while double glazed units capture expanding share as thermal efficiency mandates tighten across Northern European and East Asian networks. Tempered glass occupies the mature freight-wagon segment where cost minimization outweighs acoustic or thermal performance priorities.
The European Union's ECHA enforces REACH compliance on glazing interlayers and coatings, while China's NMPA and GB standards govern fire-smoke toxicity thresholds for cabin materials in new rolling stock. Japan's METI coordinates JIS certification with railway operators to ensure seismic-load resilience in glazing frames. Stakeholders must monitor divergence between regional test protocols, as a product qualified under EN 15152 faces additional validation cycles for China's CRRC supply base or Japan's JR Group procurement channels.
Market Dynamics
High-speed rail fleet expansion across China, Germany, and Japan is compressing certification cycles while tightening acoustic and impact-performance specifications for cabin transparency systems.
Growth Catalysts
- UIC 566 acoustic mandates:European rail operators must retrofit existing fleets with laminated glazing meeting stringent sound-dampening thresholds, generating replacement demand across Deutsche Bahn and SNCF networks.
- China's CRRC bullet-train procurement:Domestic OEMs source double-glazed thermal assemblies for new 350 km/h rolling stock programs, concentrating volume in state-backed supply chains.
- Chemically strengthened substrates:Advances in ion-exchange hardening processes enable thinner, lighter glazing profiles without sacrificing post-breakage retention performance.
Market Restraints
- PVB interlayer cost volatility:Polyvinyl butyral resin prices fluctuate with petrochemical feedstock markets, squeezing margin structures for laminated glass fabricators.
- East Asian supply concentration:Specialty soda-lime substrate production clusters in coastal China and South Korea, creating single-source vulnerability for European and North American glazing integrators.
- Tempered glass substitution ceiling:Freight wagon operators prioritize cost-minimized tempered units over laminated alternatives, capping premium product penetration in cargo segments.
Strategic Opportunities
- India's Dedicated Freight Corridors:The country's national rail infrastructure expansion creates first-mover positioning for glazing suppliers meeting BIS thermal and impact standards on new locomotive builds.
- Electrochromic tinting convergence:Integration of software-defined opacity controls with laminated safety glass opens premium retrofit contracts for luxury passenger coaches.
- EU Green Deal thermal mandates:Tightening energy-efficiency requirements for rolling stock HVAC loads accelerate specification of triple-pane vacuum-insulated glazing in Nordic networks.
Industry Challenges
- Multi-jurisdiction certification timelines:Products qualified under EN 15152 require redundant validation cycles for China's GB standards and Japan's JIS frameworks, extending commercialization lead times.
- Laminated assembly skill scarcity:Specialized technicians capable of autoclave bonding large-format curved glazing remain concentrated in legacy automotive and aerospace supply bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Glazing Market |
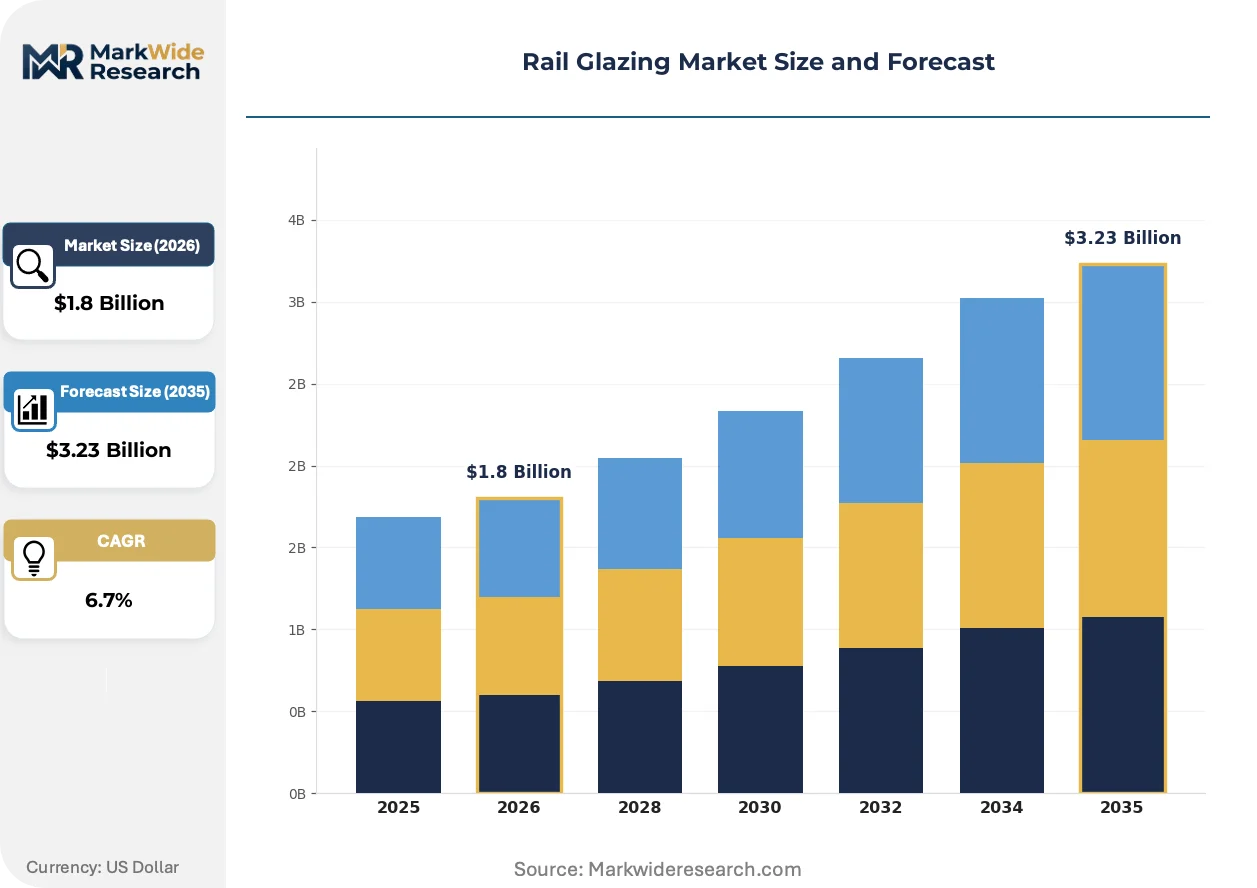
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Safety Glass, Laminated Glass, Double Glazed Units, Tempered Glass Application: Passenger Coaches, Freight Wagons, Locomotives, High-Speed Trains End User: Rail Operators, Manufacturers, Maintenance Providers, Contractors Installation Type: OEM, Aftermarket, Retrofit, Custom Solutions |
| Companies Covered | AGC Inc., Saint-Gobain S.A., Nippon Sheet Glass Co., Ltd., Dellner Romag Ltd., Fuyao Glass Industry Group Co., Ltd., Guardian Industries, Schott AG, Lippert Components Inc., Pilkington Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Glazing Market Emerging Trajectories
Active glass technologies and software-integrated cabin systems are redefining how rail operators specify transparency assemblies, shifting procurement criteria from passive safety to dynamic environmental control.
Electrochromic glazing is expanding into high-speed passenger coaches as operators seek real-time solar heat gain management without mechanical shading systems. Deutsche Bahn and JR East are piloting fleet-wide retrofits of voltage-tintable laminated units, compressing the traditional static-glazing replacement cycle and enabling outcome-based energy performance contracts with glazing suppliers.
REACH compliance enforcement by ECHA is tightening disclosure requirements for glazing interlayer chemistries and anti-reflective coatings, forcing reformulation of legacy PVB and EVA compounds. Manufacturers serving SNCF and Trenitalia contracts are accelerating migration to halogen-free flame-retardant interlayers, with Northern European operators most exposed to supply disruption during qualification transitions.
Aftermarket refurbishment contracts are fragmenting traditional OEM-tied supply relationships as specialized glazing service firms capture rolling-stock life-extension programs. Independent retrofitters in Germany and Japan now source direct from substrate manufacturers, bypassing integrated railcar builders and compressing channel margins across the value chain.
Rail Glazing Market Segmentation
Rail glazing procurement splits sharply across product performance tiers and installation channels, with high-speed operators demanding certified laminated assemblies while freight segments tolerate lower-specification alternatives. Understanding these fault lines exposes where margin pools concentrate and which customer relationships anchor long-term revenue.
Product Type:
Supply concentration in ion-exchange hardening and autoclave lamination capacity shapes competitive positioning across substrate categories, with chemically strengthened and multi-layer products commanding premium placement in bullet-train programs.
- Laminated Glass:Multi-layer soda-lime assemblies bonded with polyvinyl butyral interlayers retain structural integrity post-fracture under UIC 566 impact protocols. Deutsche Bahn and JR East procurement for 300 km/h-plus fleets specifies these units exclusively, compressing qualification timelines for certified suppliers.
- Double Glazed Units:Sealed dual-pane configurations with argon or krypton gas fills address thermal transmittance mandates in Northern European and Chinese high-speed networks. CRRC's 350 km/h rolling stock programs source these assemblies through state-vetted domestic integrators, locking out unqualified foreign competitors.
- Safety Glass:Chemically or thermally treated substrates meeting EN 15152 fragmentation standards for operator visibility panels and emergency exit glazing.
- Tempered Glass:Cost-minimized monolithic units serving freight wagon and legacy passenger retrofit segments where acoustic and thermal performance carry lower specification weight.
Laminated glass absorbs the bulk of installed capacity; double glazed units are expanding most quickly.
Application:
Speed tier and passenger density determine glazing specification intensity, with thermal and acoustic mandates tightening proportionally to operational velocity and fleet renewal cycles.
- High-Speed Trains:Pressure-sealed laminated assemblies with electrochromic tinting layers manage solar heat gain across China's Fuxing and Germany's ICE 4 platforms. These programs demand concurrent EN 15152, GB, and UIC certification, extending commercialization timelines for new entrants.
- Passenger Coaches:Regional and intercity fleets balance cost against comfort specifications, with SNCF and Trenitalia retrofit programs migrating toward laminated solutions as REACH-compliant interlayers displace legacy formulations.
- Locomotives:Operator cabin visibility panels prioritize optical clarity and impact resistance over thermal performance, typically specifying chemically strengthened safety glass.
- Freight Wagons:Minimal specification environments where tempered glass dominates due to procurement cost ceilings and absence of passenger comfort mandates.
Passenger coaches absorb the bulk of installed capacity; high-speed trains are climbing the fastest.
End User:
Procurement authority fragmentation between state rail operators and private maintenance contractors is restructuring channel relationships and specification influence across the value chain.
- Rail Operators:Deutsche Bahn, SNCF, and China State Railway Group hold direct specification authority for new-build fleets, leveraging volume concentration to demand outcome-based energy performance guarantees from glazing suppliers.
- Manufacturers:CRRC, Alstom, and Siemens Mobility integrate glazing through captive supply agreements or qualified vendor lists, with certification reciprocity determining supplier eligibility across multiple production sites.
- Maintenance Providers:Independent retrofitters in Germany and Japan now source substrates directly from AGC and Saint-Gobain, bypassing railcar builders and capturing life-extension program margins.
- Contractors:Project-specific installers serving infrastructure expansion programs in India's Dedicated Freight Corridors, subject to BIS thermal and impact qualification requirements.
Rail operators absorb the bulk of installed capacity; maintenance providers are gaining share fastest.
Installation Type:
Channel economics diverge sharply between OEM-tied specification cycles and aftermarket refurbishment, with service-based contracts offering faster payback despite lower per-unit revenue.
- OEM:New rolling stock programs in China and Germany lock in multi-year supply commitments during design phases, with glazing specifications frozen 24-36 months before fleet entry into service.
- Aftermarket:Independent service firms capture rolling-stock life-extension demand across SNCF and JR East networks, sourcing laminated replacements outside manufacturer channels.
- Retrofit:Electrochromic tinting upgrades and thermal efficiency improvements target existing high-speed fleets, with Deutsche Bahn piloting voltage-tintable laminated retrofits.
- Custom Solutions:Specialty curved and oversized glazing for heritage restoration and luxury tourist rail applications, requiring manual autoclave bonding from aerospace-qualified technicians.
OEM absorbs the bulk of installed capacity; aftermarket is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qingdao's coastal manufacturing corridor anchors rail glazing substrate production, feeding CRRC's domestic bullet-train assembly lines while specialized laminators in Germany's Ruhr Valley serve Deutsche Bahn's retrofit mandates.
China
CRRC's 350 km/h Fuxing fleet expansion drives procurement of double-glazed thermal assemblies through state-vetted domestic integrators. NMPA fire-smoke toxicity standards govern cabin materials for new rolling stock. Qingdao and Changchun manufacturing clusters concentrate ion-exchange hardening capacity for chemically strengthened substrates.
Germany
Deutsche Bahn's UIC 566 acoustic retrofit program generates replacement demand for laminated glazing across ICE 4 platforms. ECHA REACH compliance enforces disclosure requirements for interlayer chemistries and anti-reflective coatings. Ruhr Valley fabricators specialize in autoclave bonding for curved high-speed cabin assemblies.
Japan
JR East pilots voltage-tintable electrochromic retrofits for real-time solar heat gain management. METI coordinates JIS certification with railway operators to ensure seismic-load resilience in glazing frames. Nagoya industrial zone hosts precision laminators serving Shinkansen maintenance programs.
India
Dedicated Freight Corridor locomotive builds create first-mover positioning for suppliers meeting BIS thermal and impact standards. The national infrastructure expansion prioritizes cost-engineered tempered units for freight wagon specifications. Gujarat and Maharashtra industrial corridors attract glazing integrators targeting retrofit opportunities.
France
SNCF's regional fleet migration toward laminated solutions accelerates as REACH-compliant interlayers displace legacy PVB formulations. ECHA enforcement tightens disclosure mandates for glazing coatings. Auvergne-Rhône-Alpes hosts specialized service firms capturing rolling-stock life-extension contracts outside manufacturer channels.
Rail Glazing Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the rail glazing value chain. Integrated glass manufacturers with captive chemical-to-substrate pipelines dominate high-clarity supply for bullet-train builders, while specialized laminators and retrofit service firms fragment the aftermarket. Three archetypes define competitive positioning: chemical-integrated substrate specialists, certified laminators with autoclave scale, and independent refurbishment contractors. Dominant moves include backward integration into interlayer formulation and direct sourcing relationships that bypass railcar builders.
Among Japanese and European chemical-integrated producers, AGC Inc., Nippon Sheet Glass Co., Ltd., and Schott AG occupy positions anchored by substrate manufacturing scale. AGC exemplifies the integrated archetype with upstream control over soda-lime production. Nippon Sheet Glass represents East Asian laminators serving seismic-resilient specifications. Schott AG sits within the specialty glass tier with heritage in chemically strengthened applications.
| Leading Market Players |
|---|
| AGC Inc. |
| Saint-Gobain S.A. |
| Nippon Sheet Glass Co., Ltd. |
| Dellner Romag Ltd. |
| Fuyao Glass Industry Group Co., Ltd. |
| Guardian Industries |
| Schott AG |
| Lippert Components Inc. |
| Pilkington Group Limited |
| Others |
Supply Flow & Price Mechanics
Specialized autoclave bonding technicians concentrated in Germany's Ruhr Valley and Japan's Nagoya industrial zone command wage premiums that compress margin structures for curved laminated assemblies, widening the spread between premium certified units and commodity tempered alternatives.
Pricing Analysis
Outcome-based energy performance guarantees anchor pricing for high-speed rail contracts, with Deutsche Bahn and China State Railway Group tying supplier payments to verified thermal and acoustic metrics. Certification grade under EN 15152, UIC 566, and GB standards drives sharp price differentiation between qualified and unqualified suppliers. Cost compression in the freight wagon segment intensifies as operators substitute laminated specifications with tempered alternatives. Maintenance providers exhibit highest price sensitivity due to fragmented procurement authority, while state rail operators absorb premium tiers through volume concentration.
Supply Chain Analysis
Dual-sourcing requirements mandated by Deutsche Bahn and JR East force glazing integrators to qualify secondary substrate suppliers beyond their primary chemical-integrated partners. Production clusters in coastal China, South Korea, and Germany's Ruhr Valley supply ion-exchange hardened soda-lime substrates and autoclave lamination capacity. The chain draws from petrochemical feedstocks for PVB interlayers, rare gas fills for thermal assemblies, and specialty coatings for electrochromic layers. Single-source vulnerability in East Asian soda-lime production creates exposure to logistics disruption. Distribution runs through railcar builder captive channels for OEM programs and direct substrate sourcing for independent retrofitters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rail glazing sector sits in a technology-transition phase as electrochromic tinting displaces static solar-control glazing across high-speed passenger fleets.
For Market Incumbents: Anticipate margin erosion from independent aftermarket retrofitters bypassing railcar builder channels by securing direct specification relationships with state rail operators for life-extension programs. Backward integration into halogen-free flame-retardant interlayer formulation protects against REACH-driven supply disruption. Capacity expansion in India's Gujarat and Maharashtra corridors captures Dedicated Freight Corridor locomotive demand before foreign competitors qualify under BIS standards. For New Entrants and Emerging Players: Enter via India's freight locomotive build programs where BIS thermal and impact qualification barriers remain lower than EN 15152 or UIC 566 certification cycles. Target the aftermarket refurbishment channel serving SNCF and Trenitalia regional fleets migrating toward laminated solutions. Deploy electrochromic retrofit service capabilities as the primary go-to-market angle, compressing payback through outcome-based energy performance contracts rather than capital-intensive substrate manufacturing. For Investors and Strategic Acquirers: The window for entry favors certified laminators with autoclave scale and existing multi-jurisdiction qualification reciprocity. Long-term viability hinges on positioning ahead of EU Green Deal thermal mandates accelerating triple-pane vacuum-insulated glazing specification across Nordic networks. Watch for electrochromic retrofit contract velocity at Deutsche Bahn and JR East as the inflection signal indicating technology-transition maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Interlayer Formulation | REACH compliance forces reformulation of legacy PVB compounds for SNCF and Trenitalia contracts. |
| Multi-Jurisdiction Certification Investment | Concurrent EN 15152, GB, and JIS qualification unlocks CRRC, Deutsche Bahn, and JR East procurement channels. |
| Aftermarket Service Capability Buildout | Independent retrofitters in Germany and Japan capture rolling-stock life-extension margins outside OEM channels. |
| Electrochromic Technology Partnership | Voltage-tintable laminated integration enables outcome-based energy contracts with state rail operators. |
| Geographic Capacity Expansion in India | BIS-qualified production in Gujarat and Maharashtra corridors secures Dedicated Freight Corridor locomotive supply. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across plant managers at laminating facilities, procurement leads at CRRC and Alstom, aftermarket service heads in Germany and Japan, and technical R&D directors at substrate manufacturers. Secondary sources included UIC certification registries, ECHA REACH disclosure databases, NMPA fire-smoke toxicity filings, and import-export records for soda-lime and chemically strengthened glass. Bottom-up unit economics triangulated against top-down fleet replacement schedules and infrastructure investment pipelines.
Data-stream reconciliation across production volume disclosures, rolling stock delivery schedules, and retrofit contract awards shaped the analytical framework. Segmentation dimensions modeled include product type, speed tier application, procurement channel, and regional regulatory cluster. CAGRs derived from fitted growth curves calibrated to announced fleet expansion programs and mandate-driven replacement cycles. Industry-specific inputs incorporated electrochromic retrofit pilot results and thermal transmittance specification trajectories under EU Green Deal implementation.
Forecast precision tightens around the base case; tail outcomes carry wider variance under PVB resin price volatility and East Asian logistics disruption scenarios. Projections reflect assumptions on certification timeline compression, interlayer chemistry reformulation costs, and state rail operator procurement centralization. Deviation in electrochromic technology adoption rates or REACH enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Railway Draft Gears Market
Railway
Railroad Brake Shoe Market
Railway
Train Exterior Lighting Market
Railway
Connected Rail Market
Railway
Solar Train Market
Railway
Trams Market
Railway
Rail Freight Slot and Path Optimization Platforms Market
Railway
Europe Intermodal Terminals Market
Railway
Gearbox for Rail Vehicles Market
Railway
Railway Buffer Stops Market
Railway
Freight Wagon Market
Railway
Railway Axle Market
Railway
Railway Pantograph Market
Railway
Hydrogen Fuel Cell Train Market
Railway
Global Train Control and Management Systems Market
Railway
Maglev Train Market