
 Automotive Disc Brake Market | 2026-2036
Automotive Disc Brake Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Disc Brake Market Intelligence
The adoption of high-performance carbon composite materials is rotating the market towards premium and aftermarket segments. Brembo S.p.A. specializes in this high-performance niche, particularly for luxury and sports vehicles. Robert Bosch GmbH leverages its extensive R&D in electronic braking systems to compete across multiple vehicle types. Continental AG sustains its market position through large-scale manufacturing and integrated safety system offerings.
An automotive disc brake is a kinetic energy conversion system that uses a hydraulic caliper to press friction pads against a rotating disc coupled to the wheel hub. Its primary function is to decelerate a vehicle by converting motion into heat through friction. Within vehicle types, the SUV segment now constitutes a major source of demand due to vehicle weight and performance expectations. While cast iron remains the dominant material for volume production, carbon composite and aluminum variants command significant price premiums in performance and lightweight applications.
Regulations such as the US NHTSA's Federal Motor Vehicle Safety Standards and Europe's UNECE R13-H mandate stringent performance and durability criteria. In China, GB standards for braking systems dictate market access and product design, influencing material selection and testing protocols. Component suppliers must now decide how to allocate R&D between refining conventional hydraulic systems and developing novel brake-by-wire solutions for electric architectures.
Market Dynamics
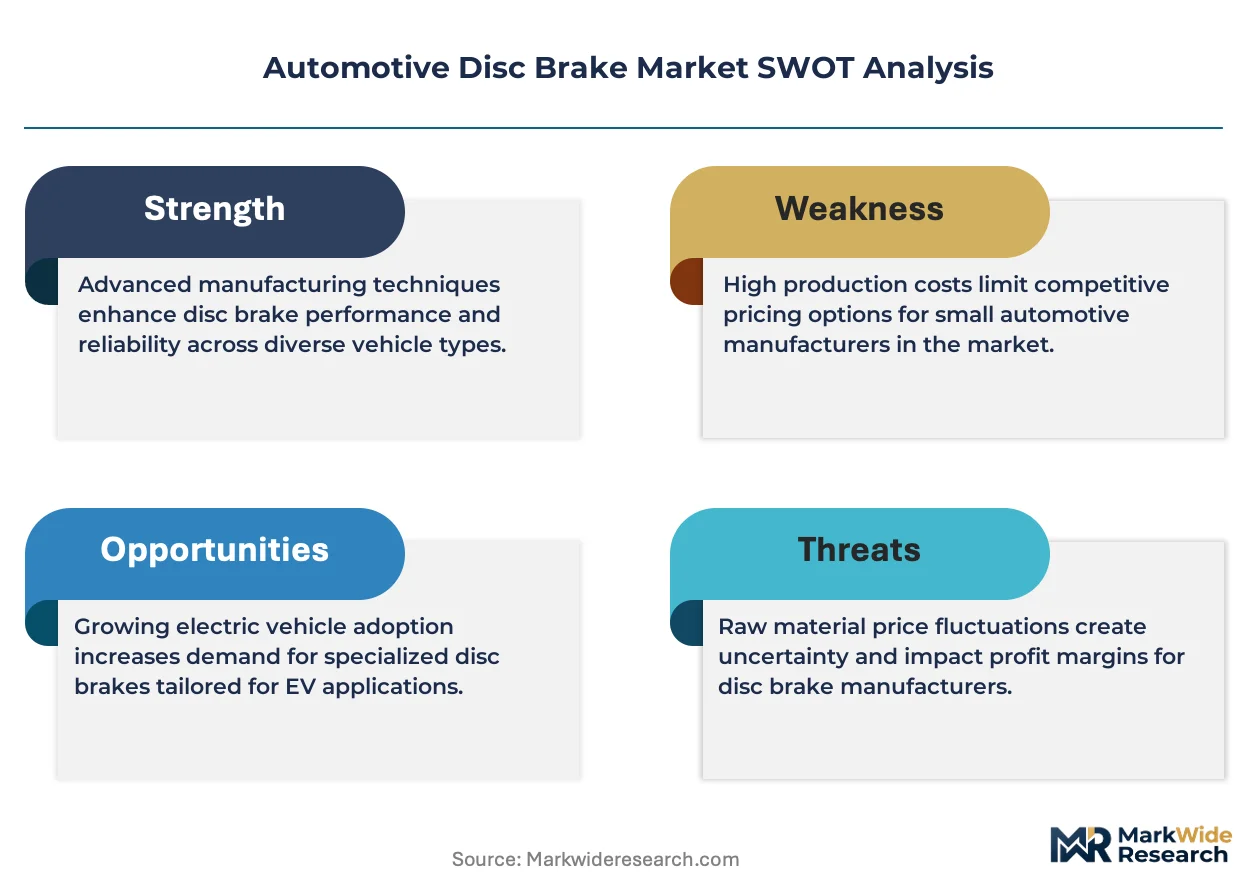
The central dynamic shaping the automotive disc brake market is the technological bifurcation driven by vehicle electrification. This forces suppliers to simultaneously invest in refining cost-effective cast iron hydraulic systems for internal combustion engines and developing advanced brake-by-wire solutions for EVs.
Growth Catalysts
- SUV Segment Expansion:The rising global sales of heavier and more powerful Sport Utility Vehicles necessitate higher-performance braking systems, driving demand for larger discs and multi-piston calipers to ensure safety and performance.
- Chinese Automotive Dominance:China's position as the world's largest vehicle producer and a leader in electric vehicle manufacturing creates immense, concentrated demand for all types of disc brake systems, from basic to advanced.
- Stringent Safety Mandates:Regulations like Europe's UNECE R13-H and the US NHTSA's FMVSS establish rigorous performance standards, compelling continuous innovation in brake reliability, fade resistance, and durability across all vehicle classes.
Market Restraints
- Raw Material Price Volatility:Fluctuations in the cost of essential materials like cast iron and aluminum directly impact manufacturer margins, creating pricing pressure and complicating long-term supply agreements for volume production.
- Regenerative Braking Integration:The technical complexity of seamlessly blending traditional friction braking with EV regenerative systems to provide consistent pedal feel and optimal energy recovery remains a significant engineering hurdle.
- Carbon Composite Supply Bottlenecks:Production of high-performance carbon-ceramic discs is concentrated among a few specialized suppliers, limiting availability and keeping prices prohibitive for all but the luxury and supercar segments.
Strategic Opportunities
- Brake-by-Wire Systems:The development of fully electronic brake-by-wire systems offers opportunities for enhanced safety through faster response times and deeper integration with autonomous driving platforms and stability control.
- Aftermarket in Developing Economies:Expanding and aging vehicle fleets in regions like Southeast Asia and Latin America present a significant opportunity for aftermarket suppliers of replacement pads, discs, and calipers.
- Lightweighting for Electric Vehicles:The push to maximize EV battery range creates a market for lightweight aluminum calipers and even advanced composite discs that reduce unsprung mass and improve overall vehicle efficiency.
Industry Challenges
- Navigating Global Regulatory Divergence:Component suppliers face significant compliance costs and design complexity in meeting disparate braking standards, such as China's GB standards versus North American FMVSS requirements.
- Dual R&D Investment Burden:Companies are forced to allocate significant capital expenditure to two parallel R&D tracks: incremental improvements in mature hydraulic systems and ground-up development of electronic braking architectures.
- Software Integration Expertise Gap:A shortage of software engineers with the specific skills to develop and validate the complex control logic for brake-by-wire and integrated regenerative braking systems hinders rapid development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Disc Brake Market |
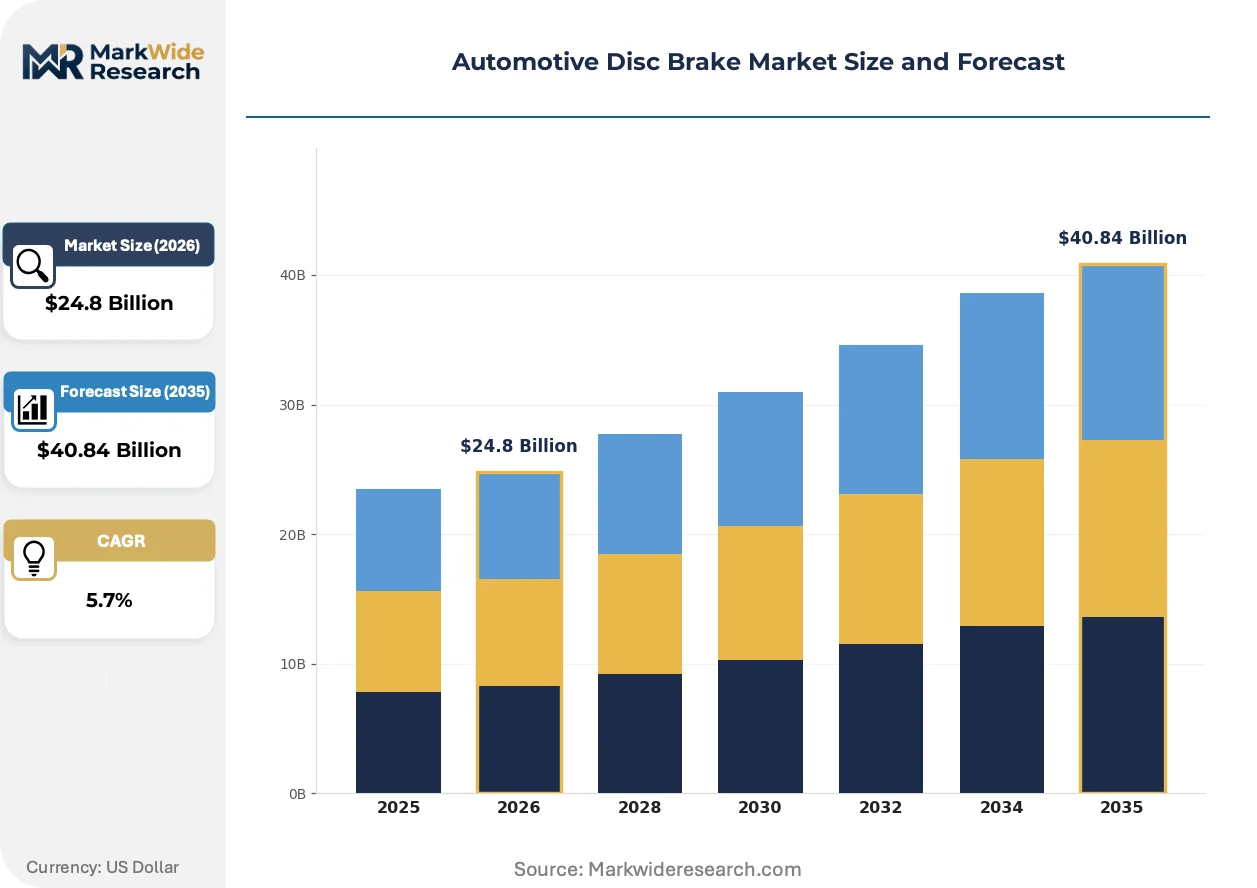
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $40.84 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ventilated, Slotted, Cross-Drilled, Solid Vehicle Type: Sedan, SUV, Truck, Motorcycle Material: Cast Iron, Carbon Composite, Aluminum, Steel Brake System: Hydraulic, Air, Electric, Mechanical |
| Companies Covered | Continental AG, Aisin Seiki Co., Ltd., Robert Bosch GmbH, Mando Corporation, Hitachi Astemo, Ltd., Brembo S.p.A, Knorr-Bremse AG, Nissin Kogyo Co., Ltd., ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Disc Brake Market Strategic Shifts & Innovations
The market's evolution is defined by a fundamental split in innovation pathways. One path refines mature hydraulic technologies for the vast internal combustion engine market, while the other pioneers novel electronic braking architectures essential for the transition to electric and autonomous vehicles.
Brake-by-wire technology functions by replacing the direct hydraulic link between the pedal and the brake caliper with electronic sensors and actuators. Electric vehicle manufacturers are the primary adopters, leveraging the system's rapid response and inherent compatibility with regenerative braking. This technology is decomposing the monolithic hydraulic brake system into a distributed network of intelligent components, creating new value in software and system integration.
Forthcoming regulations, including Europe’s Euro 7 standards, are introducing first-ever limits on non-exhaust particulate emissions from brake wear. This is compelling a fundamental redesign of friction materials and encouraging exploration of novel enclosed brake systems to capture dust. The aftermarket segment is particularly impacted, facing the challenge of developing compliant replacement pads that do not compromise on performance or affordability.
A notable shift in the service channel involves the move from discrete component replacement to integrated system-level diagnostics. This pivot challenges independent repair shops that lack the proprietary software and training required to service complex electronic braking systems found in modern EVs and advanced driver-assistance system equipped cars. This trend is most pronounced in North America and Europe, where vehicle electronic complexity is highest.
Automotive Disc Brake Market Segmentation
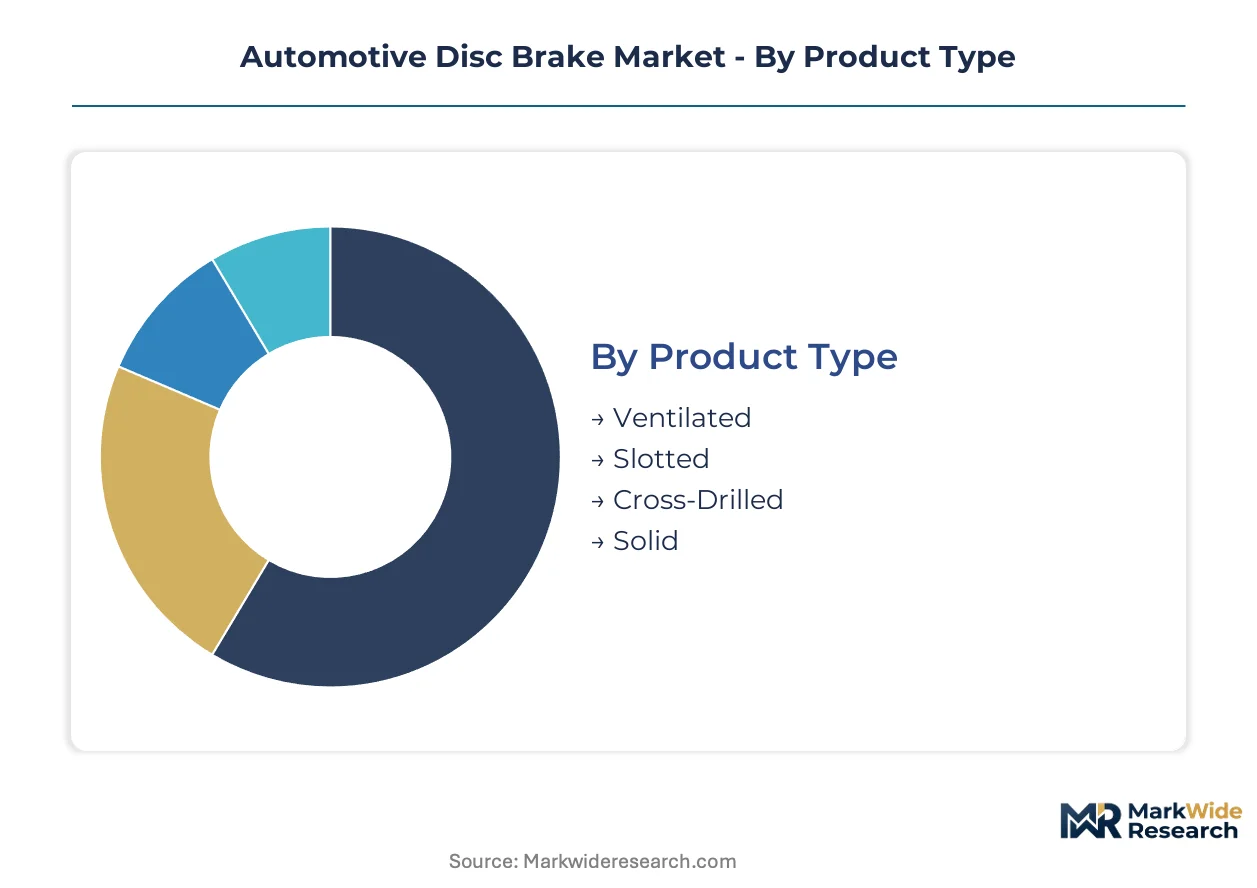
The automotive disc brake market segments reflect diverse technical requirements and vehicle applications. Understanding these distinctions helps pinpoint specific demand drivers and technological priorities. Each segment faces unique regulatory pressures and material science advancements.
Product Type:
Margin pools within product types concentrate on performance-oriented and specialized designs. These designs offer enhanced heat dissipation and braking efficiency.
- Ventilated:These discs feature internal channels between two friction surfaces, promoting airflow for superior heat dissipation during heavy braking. Passenger vehicles and light commercial vehicles widely adopt ventilated discs for their balanced performance and cost.
- Cross-Drilled:Drilled holes on the disc surface improve cooling and provide an escape route for brake dust and gases, enhancing initial bite and wet performance. Performance cars and premium SUVs frequently incorporate cross-drilled rotors for their aesthetic and functional benefits.
- Slotted:Slots on the disc surface continuously clean the brake pad surface, preventing glazing and maintaining consistent friction. Racing applications and heavy-duty vehicles utilize slotted discs for sustained performance under extreme conditions.
- Solid:Solid discs consist of a single piece of cast iron, offering a cost-effective and durable solution for lighter vehicles or rear axles where heat management is less critical.
Solid discs hold installed capacity. Ventilated discs are rotating up the share rankings.
Vehicle Type:
Application scope defines demand patterns across different vehicle types, each with distinct braking requirements.
- SUV:Sport Utility Vehicles demand robust braking systems due to their heavier curb weight and higher center of gravity, necessitating larger calipers and discs. The SUV segment is a primary growth catalyst for high-performance disc brake systems globally.
- Truck:Trucks require heavy-duty braking components designed for significant payloads and continuous operation, often involving air brake systems integrated with disc brakes for enhanced stopping power. Commercial trucking fleets prioritize durability and reliability in their braking solutions.
- Sedan:Sedans represent a high-volume segment, utilizing a range of disc brake configurations optimized for efficiency and passenger comfort. This segment drives demand for cost-effective and reliable hydraulic systems.
- Motorcycle:Motorcycles employ compact and lightweight disc brake systems, prioritizing precise control and rapid deceleration.
The SUV segment exhibits the fastest-growing trajectory. Sedan volume remains foundational.
Material:
Cost tier differentiation heavily influences material selection for disc brakes, balancing performance with production economics.
- Cast Iron:This material dominates the market due to its excellent thermal capacity, wear resistance, and cost-effectiveness for mass-produced vehicles. Most passenger cars and light commercial vehicles use cast iron discs.
- Carbon Composite:Composed of carbon fibers and ceramic matrix, these discs offer exceptional heat resistance, lightweight properties, and fade resistance, primarily serving luxury sports cars and supercars. The specialized manufacturing process and raw material costs make them a premium offering.
- Aluminum:Aluminum calipers are favored for their lightweight properties, contributing to reduced unsprung mass and improved fuel efficiency in electric vehicles. Their adoption is increasing in performance-oriented and EV applications.
- Steel:Steel is used in specific applications, often for brake hats or in conjunction with other materials for specialized lightweight rotors.
Cast iron materials drive volume. Carbon composite adoption is gaining momentum.
Brake System:
Technology maturity dictates the investment profile and innovation pathways within different brake system types.
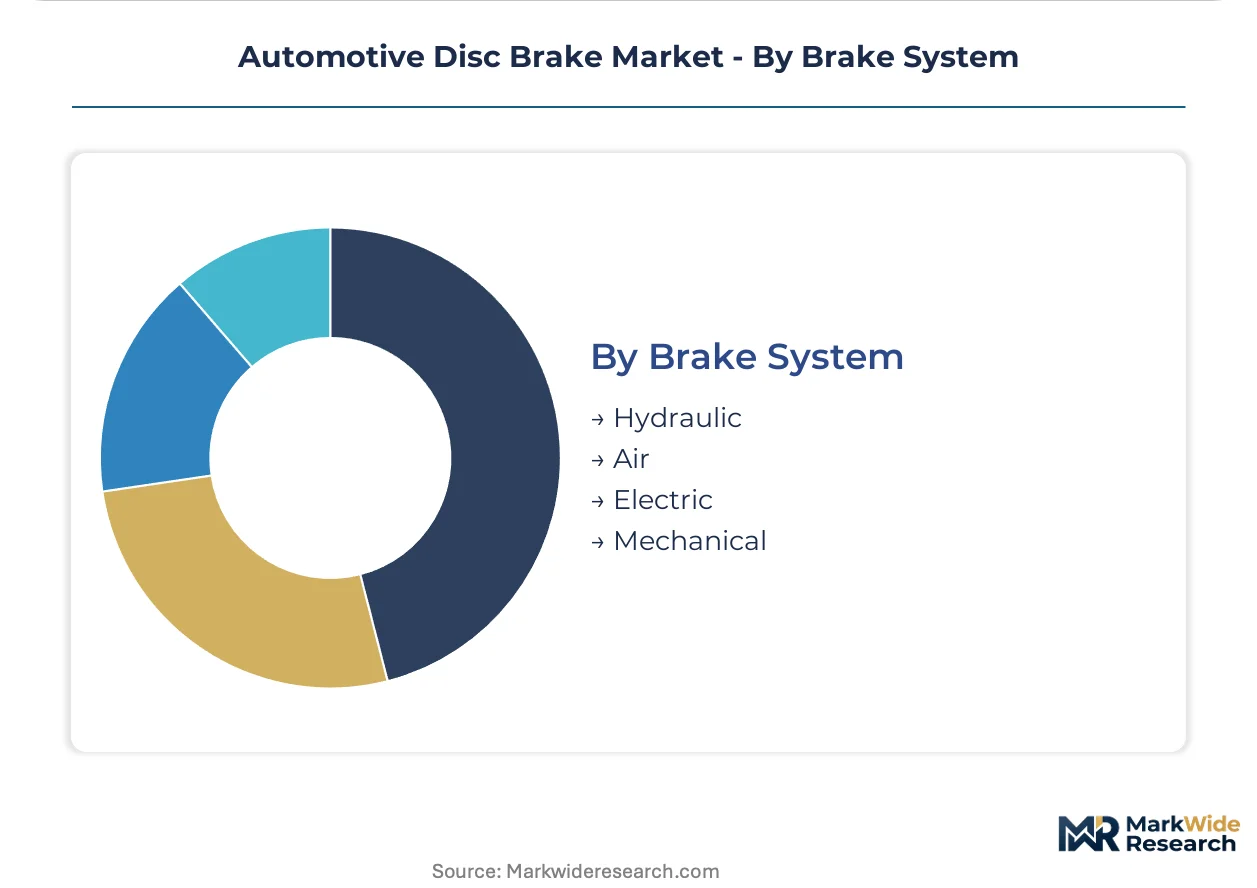
- Hydraulic:These systems rely on fluid pressure to actuate calipers, representing the long-standing conventional braking technology across most vehicle types. Hydraulic systems continue to see incremental refinements for efficiency and safety.
- Electric:Electric brake systems, including brake-by-wire, replace mechanical linkages with electronic signals, enabling faster response times and seamless integration with regenerative braking in EVs. Electric systems require advanced software and sensor technology.
- Air:Air brake systems utilize compressed air to apply braking force, primarily found in heavy commercial vehicles due to their robust stopping power for large loads. These systems offer reliability and durability for demanding applications.
- Mechanical:Mechanical brakes use cables or rods to transmit force, typically found in parking brakes or very light vehicles.
Hydraulic systems hold the largest market share. Electric brake systems are experiencing significant expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's significant automotive production and leadership in electric vehicles drives considerable demand for disc brake systems, influencing global trade flows. The market's regional dynamics reflect varied regulatory environments and vehicle fleet compositions. Each major automotive manufacturing hub contributes uniquely to disc brake system advancements and consumption patterns.
China
China's automotive sector expansion demands a vast array of disc brake solutions, from basic to advanced. Its GB standards for braking systems dictate material selection and testing protocols for market access. The Yangtze River Delta region, particularly around Shanghai, remains a critical hub for both traditional automotive manufacturing and cutting-edge EV component development.
The German automotive sector
The German automotive sector, known for its premium and high-performance vehicles, drives innovation in disc brake technology. UNECE R13-H standards mandate stringent performance and durability criteria for all braking systems. Stuttgart and Munich serve as central points for advanced automotive R&D and manufacturing, fostering new brake system designs.
United States
United States demand for disc brakes is significantly influenced by the expanding SUV segment, requiring robust braking solutions. US NHTSA's Federal Motor Vehicle Safety Standards (FMVSS) ensure high safety and reliability benchmarks. Detroit continues as a traditional automotive manufacturing stronghold, while California leads in electric vehicle adoption and related component innovation.
Japanese vehicle manufacturers
Japanese vehicle manufacturers emphasize precision engineering and long-term reliability in their disc brake systems. JIS standards guide component design and quality control across the industry. The Nagoya region anchors major automotive OEM production, focusing on efficient and durable braking solutions for global markets.
India's expanding
India's expanding domestic automotive market, fueled by rising disposable incomes, creates substantial demand for cost-effective and reliable disc brakes. BIS standards ensure product quality and safety for locally manufactured and imported components. Chennai and Pune stand as significant automotive manufacturing hubs, supporting both domestic and export vehicle production.
Automotive Disc Brake Market Key Industry Players
Listed leaders compete with private specialists across technology development and market reach in the automotive disc brake market. The industry structure features a tiered landscape, with global Tier-1 suppliers at the top and numerous specialized component manufacturers. Strategic archetypes include integrated system providers, performance brake specialists, and high-volume component manufacturers. Dominant competitive moves involve significant R&D investment in electronic braking systems and strategic partnerships for vehicle integration.
Within the global Tier-1 supplier archetype, Robert Bosch GmbH and Continental AG exemplify companies leveraging extensive R&D and large-scale manufacturing capabilities. Brembo S.p.A. occupies a position as a specialized performance component manufacturer, focusing on luxury and sports vehicle applications. These entities anchor distinct segments of the market, from mass-market hydraulic systems to advanced electronic brake-by-wire solutions.
| Leading Market Players |
|---|
| Continental AG |
| Aisin Seiki Co., Ltd. |
| Robert Bosch GmbH |
| Mando Corporation |
| Hitachi Astemo, Ltd. |
| Brembo S.p.A |
| Knorr-Bremse AG |
| Nissin Kogyo Co., Ltd. |
| ZF Friedrichshafen AG |
| Others |
Cost & Logistics Intelligence
The automotive disc brake market benefits from economies of scale in mass production, which concentrates manufacturing capacity among large Tier-1 suppliers and establishes competitive price floors for conventional systems. This scale also influences the global distribution of advanced material production.
Pricing Analysis
A clear technology-generation pricing gap exists, with conventional hydraulic cast iron systems operating on a per-unit transactional model, while advanced brake-by-wire solutions command a significant premium due to R&D intensity and software integration. Pricing stratifies across premium, standard, and economy tiers, driven by material composition like carbon composite versus cast iron, and brand premium from specialized manufacturers such as Brembo S.p.A. Pricing pressure stems from raw material price volatility, particularly for cast iron and aluminum, impacting manufacturer margins. Mass-market OEM procurement teams and aftermarket distributors exhibit high price sensitivity, whereas luxury vehicle manufacturers are less sensitive to component cost.
Supply Chain Analysis
Just-in-time inventory strategies dominate for high-volume conventional disc brake components, reflecting OEM demands for lean manufacturing, while specialized carbon composite production may involve more strategic stockpiling due to lead times. Geographic supply concentration for cast iron components centers on China and Germany, with high-performance carbon composite production concentrated in Europe. The market sources key raw materials like cast iron, aluminum, and various friction material compounds. A structural risk involves single-source vulnerability for specialized carbon composite suppliers, and distribution for OEM components runs through direct supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive disc brake market is poised for cyclical recovery, driven by post-pandemic rebound in global vehicle production and consumer demand for new automobiles. This resurgence creates opportunities across both OEM and aftermarket segments.
For Market Incumbents:Fortify existing market share in conventional hydraulic systems by optimizing cost structures and investing in advanced material science for improved durability and Euro 7 compliance. Pursue strategic partnerships with EV manufacturers to integrate brake-by-wire solutions early in vehicle development, countering the threat of new electronic braking specialists. Leverage extensive R&D in electronic braking systems and invest in software integration expertise to maintain competitive positioning against agile tech-focused competitors.
For New Entrants and Emerging Players:Anchor in niche segments focusing on lightweighting solutions for electric vehicles, such as aluminum calipers and advanced composite discs, where established players face legacy system inertia. Target the aftermarket in developing economies like Southeast Asia, which presents a highly penetrable segment due to aging vehicle fleets and less stringent regulatory barriers. A direct-to-consumer online sales channel for specialized performance components can bypass traditional distribution hurdles and build brand loyalty.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors specialized suppliers with deep expertise in brake-by-wire systems and advanced materials for a viable 5-10 year investment horizon. Acquisition targets should be innovative mid-cap firms excelling in software integration for electronic braking architectures or advanced carbon composite manufacturing capabilities. The increasing adoption rate of Euro 7-compliant brake systems, driven by non-exhaust particulate emission limits, serves as a crucial inflection indicator for future market shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Automotive OEMs can reduce component costs and simplify integration across diverse vehicle models, enhancing overall manufacturing efficiency. |
| Software-Defined Brake Investment | Investing in software for brake-by-wire systems enables deeper integration with autonomous driving platforms and regenerative braking. |
| Advanced Material R&D | Developing new carbon composite and aluminum materials reduces unsprung mass, improving EV range and vehicle performance. |
| Geographic Manufacturing Expansion | Establishing production facilities in China supports market access and caters to the immense local demand for brake systems. |
| Aftermarket Channel Optimization | Streamlining distribution to independent repair shops in Southeast Asia captures demand from aging vehicle fleets. |
Research Approach
The analysis maps automotive disc brake product types and vehicle applications, each validated through direct interviews with Tier-1 supplier procurement leads, OEM platform engineers, and aftermarket distributors. This approach combined primary insights with secondary validation from vehicle production databases, regulatory filings like US NHTSA reports, and material science journals. Bottom-up data aggregation and top-down market sizing ensured comprehensive triangulation.
Consistency checks against external economic and automotive industry benchmarks informed the forecast framework, ensuring robust projections across the analysis window. The model segmented by product type, vehicle class, material, and brake system, incorporating regional production clusters. Compound Annual Growth Rates were derived from historical trends and projected technological adoption. Electric vehicle adoption rates and non-exhaust particulate regulations served as key inputs.
Decision-makers should treat outputs as directional under current macroeconomic stability and regulatory pathways; material deviation would warrant model refresh. Forecasts reflect assumptions regarding raw material supply and sustained automotive production. Revision becomes warranted when significant shifts in EV adoption or new safety mandates cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Norway Automotive Engine Oils Market
Automotive Parts
Automotive Forging Market
Automotive Parts
Center and Drag Link Market
Automotive Parts
UAE Automotive Lubricants Market
Automotive Parts
Struts System Market
Automotive Parts
Automotive Control Arms Market
Automotive Parts
Global Fuel and Oil Filters Market
Automotive Parts
Europe Automotive Aftermarket Spare Parts Market
Automotive Parts
Colombia Commercial Vehicles Lubricants Market
Automotive Parts
Brake Fluids Market
Automotive Parts
Connecting Rods Market
Automotive Parts
France Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Canister Market
Automotive Parts
Automotive Ignition Coil Market
Automotive Parts
External Combustion Engine Market
Automotive Parts
Middle East Automotive Engine Oils Market