
 Topical Pain Relief Cream Market | 2026-2036
Topical Pain Relief Cream Market Size, Share, and Industry Trends Forecast 2026-2036
Topical Pain Relief Cream Market Analysis
A widening R&D-to-manufacturing capability gap is reorganizing competitive hierarchies in topical analgesics. Johnson & Johnson leverages its consumer health infrastructure to sustain shelf dominance across mass retail pharmacy networks. Pfizer Inc anchors its position through prescription-to-OTC switching expertise in diclofenac-based formulations. Sun Pharmaceutical Industries Ltd competes on cost-optimized production of generic topical NSAIDs for emerging markets.
Topical pain relief creams are semi-solid dermatological preparations containing active pharmaceutical ingredients such as menthol, capsaicin, salicylates, or NSAIDs in emulsion or gel bases designed for percutaneous absorption and localized analgesic effect without systemic exposure. These formulations serve commercial and clinical purposes by delivering targeted pain management for musculoskeletal conditions while minimizing gastrointestinal and cardiovascular adverse effects associated with oral analgesics. Analgesic creams lead volume across product types due to established consumer familiarity with menthol and camphor formulations, while combination creams capture expanding margin pools by merging counterirritant mechanisms with anti-inflammatory actives in single-dose convenience formats. Joint pain applications drive the fastest structural growth as osteoarthritis prevalence rises among active aging populations seeking non-surgical intervention pathways.
The FDA OTC monograph reform process governs active ingredient safety and efficacy determinations for non-prescription topical analgesics in the United States, while the EMA and national competent authorities such as Germany's BfArM regulate marketing authorizations for prescription topical NSAIDs across European markets. REACH compliance shapes excipient sourcing and formulation chemistry for manufacturers distributing within the European Economic Area. Stakeholders must monitor evolving monograph finalization timelines and bioequivalence study requirements to preserve market access and optimize pipeline allocation between OTC and prescription positioning strategies.
Market Dynamics
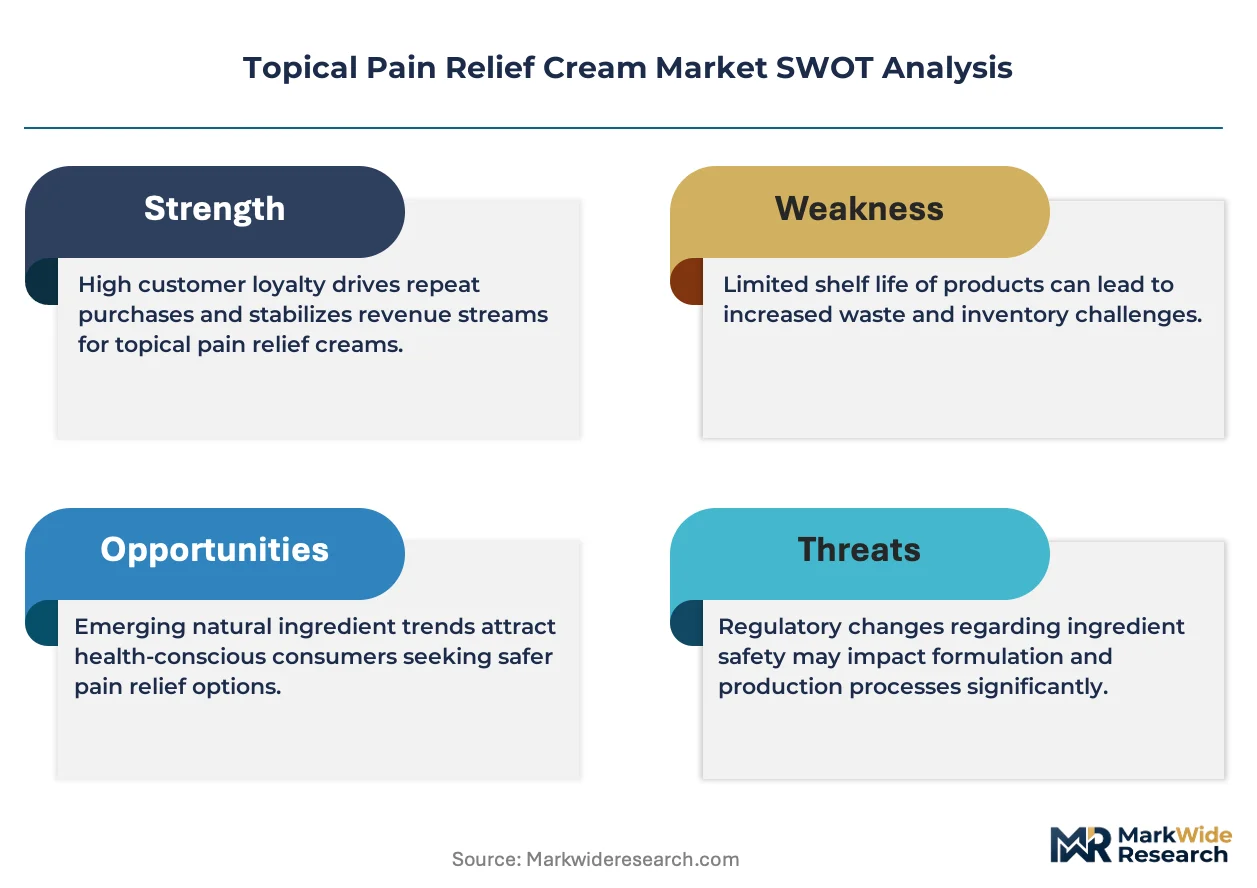
The FDA's OTC monograph reform is compressing formulation timelines while forcing manufacturers to revalidate active ingredient dossiers, creating a bifurcation between compliant incumbents and reformulation-lagged challengers.
Growth Catalysts
- Sports medicine protocol expansion:Clinics in the United States are integrating topical analgesics into acute injury management pathways, replacing oral NSAIDs for ligament and tendon trauma.
- REACH-compliant excipient innovation:European manufacturers are reformulating with bio-based penetration enhancers to maintain EEA market access under evolving chemical safety registrations.
- Osteoarthritis prevalence:Aging populations in Germany and Japan are driving demand for non-surgical joint pain interventions, expanding the addressable patient base for prescription and OTC topical NSAIDs.
Market Restraints
- API supply concentration:Diclofenac and capsaicin active pharmaceutical ingredients concentrate among Indian and Chinese bulk manufacturers, exposing formulators to geopolitical supply disruptions.
- Permeation variability:Skin barrier heterogeneity across patient populations limits bioequivalence predictability, complicating generic topical NSAID development and FDA approval timelines.
- Oral analgesic substitution:Low-cost oral ibuprofen and acetaminophen remain first-line therapy in emerging markets, constraining topical cream penetration in price-sensitive healthcare systems.
Strategic Opportunities
- Direct-to-consumer pharmacy channels:E-commerce platforms and subscription models in the United States are bypassing traditional retail gatekeepers, enabling niche formulation brands to capture margin pools.
- Combination mechanism convergence:Menthol-capsaicin-diclofenac triple-action formulations are opening premium positioning opportunities as clinicians seek simplified polypharmacy regimens for chronic pain patients.
- EMA prescription-to-OTC switching pathways:Regulatory frameworks in Europe are enabling lower-strength topical NSAIDs to migrate to non-prescription status, expanding accessible volume in pharmacy chains.
Industry Challenges
- Bioequivalence study execution:FDA draft guidance on topical product equivalence requires specialized dermatopharmacokinetic trials, straining mid-tier manufacturers without in-house clinical infrastructure.
- Formulation scientist scarcity:Expertise in transdermal delivery system design and emulsion stability engineering is concentrating among contract research organizations, inflating R&D labor costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Topical Pain Relief Cream Market |
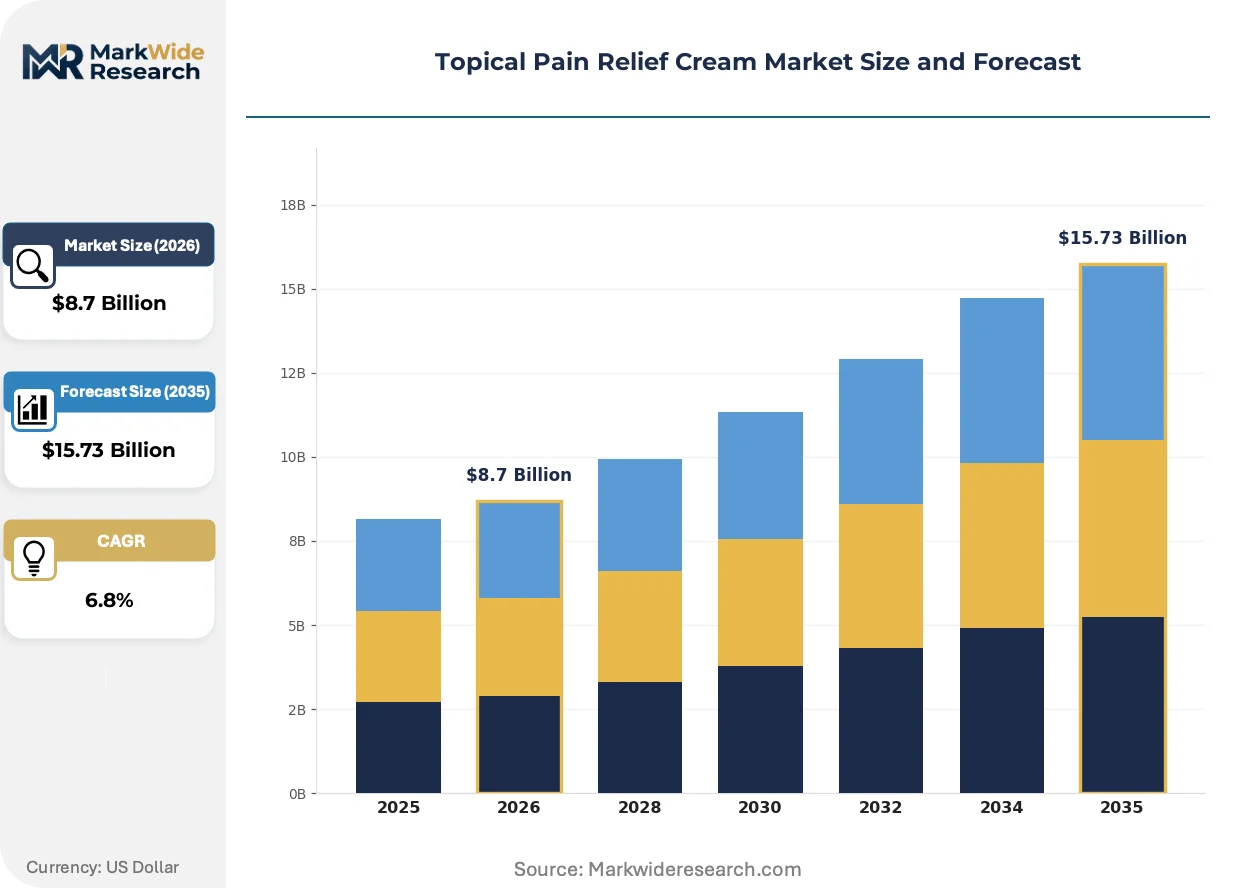
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesic Creams, Anti-Inflammatory Ointments, Herbal Formulations, Combination Creams Application: Muscle Pain, Joint Pain, Back Pain, Arthritis Pain End User: Hospitals, Clinics, Pharmacies, Home Users Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesalers |
| Companies Covered | Johnson & Johnson, Pfizer Inc, GlaxoSmithKline Plc, Sanofi S.A., Reckitt Benckiser Group Plc, Sun Pharmaceutical Industries Ltd, Novartis AG, Hisamitsu Pharmaceutical Co., Topical Biomedics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Topical Pain Relief Cream Market Emerging Trajectories
Nanoencapsulation and microneedle delivery systems are redefining percutaneous absorption benchmarks, while regulatory data requirements and channel fragmentation are simultaneously compressing commercialization windows.
Nanoemulsion technology is miniaturizing active ingredient particle sizes to sub-100 nanometer scales, enhancing dermal penetration rates for lipophilic NSAIDs. Sports medicine clinics and physical therapy chains are piloting these formulations for acute soft-tissue injuries. The technology is miniaturizing the effective dose required for analgesic onset, enabling smaller package formats and reduced manufacturing material costs.
REACH authorization timelines for novel penetration enhancers are extending excipient qualification cycles to 18-24 months in the European Economic Area. Manufacturers are pre-emptively reformulating with existing monographed ingredients to avoid pipeline stalls. Generic topical NSAID developers targeting Germany and France are absorbing the highest compliance burden, delaying product launches versus OTC markets.
Subscription-based replenishment models are displacing episodic pharmacy purchases for chronic pain patients in the United States. Direct-to-consumer brands are bundling topical creams with telehealth consultations and wearable pain tracking devices. This behavioral shift is most pronounced among Medicare-eligible populations in Florida and Arizona seeking convenience-driven adherence solutions.
Topical Pain Relief Cream Market Segmentation
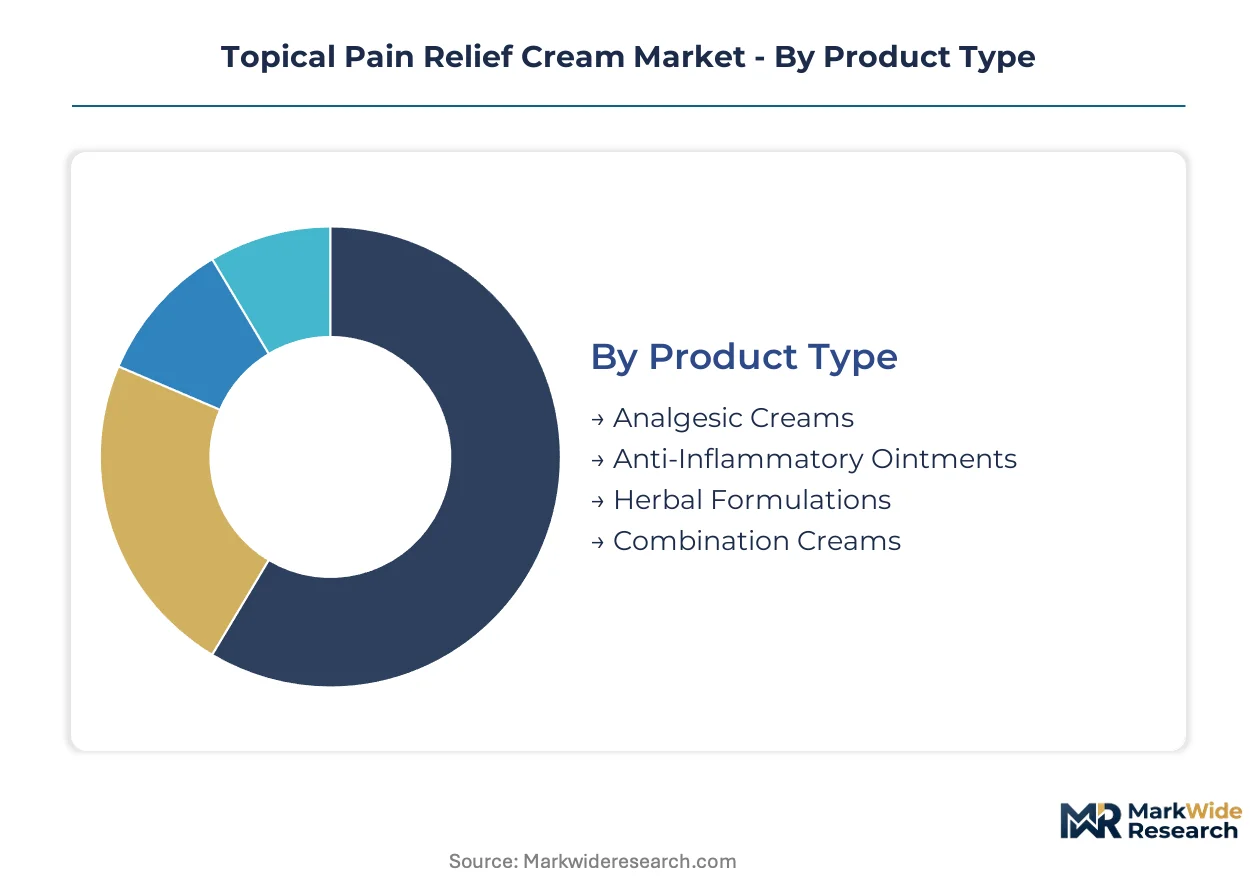
Topical pain relief cream manufacturers configure product portfolios around distinct absorption kinetics and regulatory pathways. Segment-specific formulation requirements determine whether development resources flow toward OTC monograph compliance or prescription bioequivalence studies.
Product Type:
Analgesic creams dominate domestic pharmacy channels across the United States and Germany, while herbal formulations and combination creams concentrate in export-led growth to Asia-Pacific markets.
- Analgesic Creams:These formulations rely on counterirritant mechanisms through menthol, camphor, or methyl salicylate in hydroalcoholic or emulsion bases. Demand concentrates in United States mass retail pharmacies where aging consumers self-select for familiar sensory cooling effects. Shelf turnover rates in Walgreens and CVS networks exceed specialty channels by a factor of three.
- Combination Creams:Dual or triple-action formulations merge NSAIDs with counterirritants in single-application formats. German sports medicine clinics and Japanese orthopedics practices are driving adoption as they seek to reduce oral polypharmacy burden in osteoarthritis protocols. Regulatory complexity in the European Economic Area limits competitor entry.
- Anti-Inflammatory Ointments:Diclofenac and ibuprofen-based prescription topicals target localized inflammation with minimal systemic exposure.
- Herbal Formulations:Arnica, capsaicin, and turmeric extracts serve consumers seeking botanical alternatives in India and Southeast Asian markets.
Analgesic creams command the established base. The steepest expansion runs through combination creams.
Application:
Cost tier stratification separates premium prescription NSAID positioning from economy OTC penetration, with joint pain applications capturing the highest per-unit margins.
- Joint Pain:Osteoarthritis-driven demand in Germany, Japan, and the United States is expanding the addressable patient base for hyaluronic acid and diclofenac combination therapies. Knee and hand osteoarthritis protocols in Munich and Tokyo academic medical centers now prioritize topical NSAIDs as first-line before oral escalation.
- Muscle Pain:Acute soft-tissue injuries in athletic populations favor rapid-onset menthol formulations. United States sports medicine clinics in Florida and Arizona are replacing oral ibuprofen with topical protocols for ligament sprains.
- Back Pain:Chronic lumbar conditions drive recurring purchase patterns through subscription pharmacy models.
- Arthritis Pain:Rheumatoid and psoriatic variants require prescription-strength topical NSAIDs with insurance reimbursement pathways.
Joint pain applications command the established base. The steepest expansion runs through muscle pain as sports medicine protocol adoption accelerates.
End User:
Customer type fragmentation creates distinct formulation specifications, with hospital procurement requiring bulk sterile packaging and home users driving single-dose convenience innovation.
- Home Users:Direct-to-consumer channels in the United States are displacing traditional pharmacy gatekeepers. Medicare-eligible populations in Florida subscribe to topical cream replenishment bundled with telehealth consultations. Package sizing and pump dispenser ergonomics dominate purchase decisions.
- Clinics:Physical therapy and sports medicine practices in Germany and the United States are standardizing topical analgesic protocols for post-surgical rehabilitation. Procurement concentrates in GPO-negotiated contracts with formulary restrictions.
- Hospitals:Inpatient acute pain management requires sterile, unit-dose packaging with barcode medication administration compatibility.
- Pharmacies:Community and hospital outpatient dispensaries serve as the primary education point for proper application technique and drug interaction screening.
Home users command the established base. The steepest expansion runs through clinics as protocol standardization spreads.
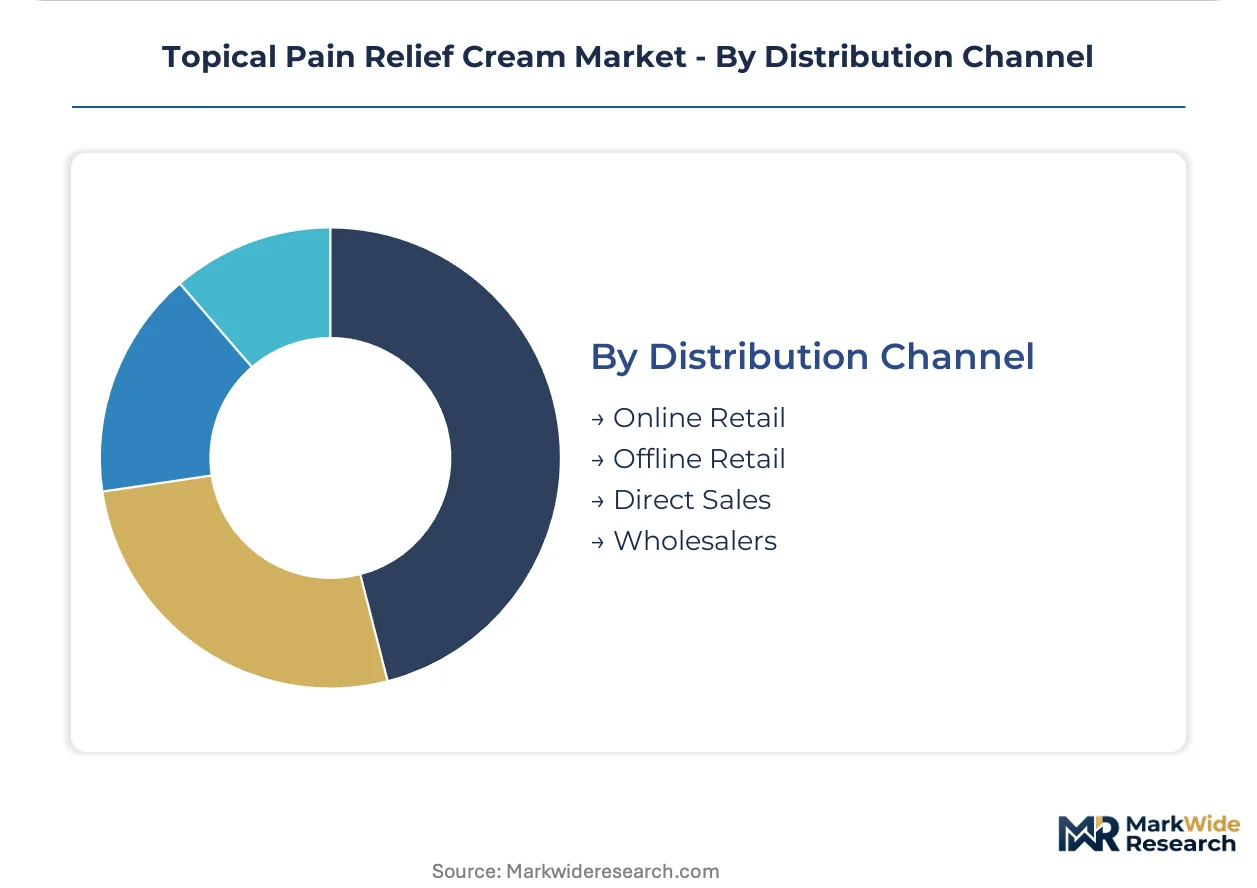
Distribution Channel:
Supply concentration in Indian and Chinese API manufacturing shapes channel economics, with direct sales capturing institutional volume and online retail fragmenting consumer access.
- Online Retail:Amazon, Walmart.com, and specialized pain management platforms in the United States are enabling niche brands to bypass slotting fee barriers. Subscription models with wearable pain tracking integration are capturing chronic patient adherence. Search engine optimization for "arthritis cream" and "back pain relief" determines discoverability.
- Offline Retail:Mass pharmacy chains in the United States and Germany maintain category captain relationships with Johnson & Johnson and Pfizer Consumer Health. Planogram positioning and end-cap displays drive impulse purchase conversion for acute pain episodes.
- Direct Sales:Institutional contracts with hospital systems and sports medicine clinic chains concentrate volume in fewer, larger transactions.
- Wholesalers:McKesson, AmerisourceBergen, and regional distributors maintain inventory buffers for pharmacy replenishment cycles.
Offline retail commands the established base. The steepest expansion runs through online retail as direct-to-consumer infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany while manufacturing cost advantages cluster in India and China, creating asymmetric margin capture across the topical analgesic value chain.
United States
Medicare-eligible populations in Florida and Arizona drive subscription-based replenishment models for chronic pain management. The FDA's OTC monograph reform is compressing formulation timelines and forcing active ingredient dossier revalidation. Boston and Minneapolis academic medical centers are piloting nanoencapsulated diclofenac protocols for post-surgical rehabilitation.
Germany
Osteoarthritis prevalence among active aging populations expands demand for prescription topical NSAIDs in Munich and Berlin outpatient clinics. The BfArM regulates marketing authorizations for diclofenac-based formulations under EMA harmonized standards. REACH compliance is extending excipient qualification cycles to 18-24 months for manufacturers sourcing novel penetration enhancers.
Japan
Joint pain applications capture premium positioning as Tokyo and Osaka orthopedics practices prioritize non-surgical intervention pathways. The PMDA oversees marketing authorizations for prescription topical NSAIDs with bioequivalence study requirements. Hisamitsu Pharmaceutical anchors domestic production of transdermal delivery systems for the Asia-Pacific export market.
India
Cost-optimized generic topical NSAID production serves emerging market volume demand from Sun Pharmaceutical's Mumbai and Gujarat manufacturing bases. The CDSCO regulates manufacturing licenses for domestic distribution and export qualification. Bulk API concentration for diclofenac and capsaicin exposes formulators to geopolitical supply disruption risks.
China
Domestic consumption of herbal-formulation topical analgesics is rising in Shanghai and Guangzhou pharmacy chains. The NMPA governs registration requirements for OTC and prescription dermatological preparations. Yangtze River Delta chemical parks concentrate excipient manufacturing for regional formulation supply.
Topical Pain Relief Cream Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with R&D-intensive multinationals commanding premium positioning while generic specialists capture volume in price-sensitive segments. The market structure consolidates around three tiers: global consumer health conglomerates with pharmacy shelf dominance, mid-cap prescription-to-OTC switch specialists, and emerging market cost-optimized manufacturers. Two strategic archetypes define competitive positioning: formulation innovators investing in nanoencapsulation and microneedle delivery systems, and supply-chain integrators controlling API-to-finished-goods verticality. M&A activity concentrates on dermatology-focused contract research organizations and regional generic portfolio acquisitions.
Within the global consumer health tier, Johnson & Johnson and Pfizer Inc occupy positions as archetype anchors for mass retail pharmacy network penetration and prescription-to-OTC switching expertise respectively. Sun Pharmaceutical Industries Ltd represents the emerging market cost-leadership archetype, with its corporate structure signaling generic-focused manufacturing scale. These three entities exemplify the strategic divergence between premium branded positioning and volume-driven generic supply that characterizes competitive dynamics across formulation types and geographic markets.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Pfizer Inc |
| GlaxoSmithKline Plc |
| Sanofi S.A. |
| Reckitt Benckiser Group Plc |
| Sun Pharmaceutical Industries Ltd |
| Novartis AG |
| Hisamitsu Pharmaceutical Co. |
| Topical Biomedics Inc. |
| Others |
Supply Flow & Price Mechanics
Natural penetration enhancers replacing synthetic excipients under REACH timelines are simultaneously relocating formulation sourcing to European bio-refineries and compressing margin structures for manufacturers dependent on legacy chemical supply chains. This substitution dynamic redistributes cost advantage toward incumbents with pre-qualified sustainable ingredient portfolios while forcing price repositioning across OTC and prescription tiers.
Pricing Analysis
The customization-premium spread separates standard menthol-camphor OTC formulations from configured combination therapies merging NSAIDs with counterirritants. Pricing stratifies across premium, standard, and economy tiers based on active ingredient complexity and regulatory pathway certification. Cost compression in economy OTC segments is intensifying because of oral analgesic substitution pressure in emerging markets. Home users through subscription channels demonstrate lowest price sensitivity; hospital procurement via GPO contracts demands highest volume discounts.
Supply Chain Analysis
Strategic stockpiling of diclofenac and capsaicin APIs is displacing just-in-time inventory models as formulators buffer against geopolitical disruption in Indian and Chinese bulk manufacturing. Active pharmaceutical ingredient supply draws from India, China, and specialized European chemical parks. Excipient sourcing rests on petrochemical derivatives and emerging bio-based alternatives. Single-source vulnerability concentrates in Yangtze River Delta and Gujarat manufacturing clusters. Distribution runs through McKesson and AmerisourceBergen wholesaler networks to pharmacy and institutional endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against oral NSAID erosion and emerging transdermal patch formats. Incumbents must fortify formulation differentiation while new entrants exploit service-layer fragmentation.
For Market Incumbents: Consolidate API-to-finished-goods backward integration to secure diclofenac supply chains against Indian and Chinese export disruption. Deepen penetration enhancer R&D partnerships with REACH-compliant European bio-refineries to preempt regulatory disqualification of legacy excipients. Channel control through direct-to-consumer pharmacy subscription infrastructure defends margin pools against retail gatekeeper compression.
For New Entrants and Emerging Players: Telehealth-integrated adherence coaching represents a service-layer gap where incumbents under-serve chronic pain patients seeking protocol guidance beyond product dispensing. Target Medicare-eligible populations in Florida and Arizona through bundled topical cream and remote consultation offerings. The most penetrable entry vector runs through online retail search optimization for condition-specific queries bypassing mass pharmacy planogram barriers.
For Investors and Strategic Acquirers: FDA OTC monograph finalization reshapes the acquisition landscape by distinguishing compliant incumbents from reformulation-lagged challengers facing dossier revalidation costs. Long-term viability centers on dermatology-focused contract research organizations possessing transdermal delivery expertise and established bioequivalence study infrastructure. The signal to watch is EMA prescription-to-OTC switching pathway acceleration for lower-strength topical NSAIDs expanding accessible pharmacy volume.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Excipient Reformulation | Preserves EEA market access as ECHA tightens chemical safety registrations for penetration enhancers. |
| Nanoencapsulation Technology Licensing | Accelerates diclofenac absorption kinetics for sports medicine clinic protocol adoption. |
| Direct-to-Consumer Channel Expansion | Bypasses Walgreens and CVS slotting fees through Amazon and specialized pain platform partnerships. |
| Prescription-to-OTC Switch Execution | Captures pharmacy volume expansion as EMA frameworks enable non-prescription topical NSAID migration. |
| API Supply Chain Vertical Integration | Reduces exposure to Indian and Chinese bulk manufacturer geopolitical disruption risk. |
Methodological Framework
The analysis maps analgesic creams, combination therapies, anti-inflammatory ointments, and herbal formulations, each validated through formulation scientists, sports medicine clinic procurement directors, and pharmacy category buyers. Primary interviews with regulatory affairs specialists at FDA and EMA, supplemented by secondary validation from FDA OTC monograph proceedings, EMA marketing authorization databases, ClinicalTrials.gov dermatopharmacokinetic study records, and REACH authorization timelines, anchor the evidence base. Bottom-up prescription and OTC volume modeling triangulates against top-down pharmaceutical market sizing from national health expenditure data.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segments by product type, application, end user, and distribution channel, with regional regulatory cluster as an additional modeling dimension. CAGRs derive from patient population epidemiology, protocol adoption curves in sports medicine, and channel shift elasticity estimates. Forecast inputs incorporate osteoarthritis prevalence trajectories and FDA monograph reform implementation pacing.
Underlying assumptions cover stable REACH authorization timelines and continued Medicare reimbursement for topical NSAID prescriptions, with deviation risk concentrated in API export restriction events from India or China. Revision becomes warranted when FDA monograph finalization timelines accelerate or delay beyond current regulatory guidance thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Advanced Cancer Pain Management Market
Pain Management
Pain Therapeutic Injectables Market
Pain Management
Pain Relievers for Teeth Market
Pain Management
Lumbosacral Radicular Pain Management Market
Pain Management
Asia-Pacific Chronic Disease Management Market
Pain Management
Chinese Fibromyalgia Market
Pain Management
Pain Patches Market
Pain Management
Pain Management Devices Market
Pain Management
Topical Pain Relief Market
Pain Management
Pain Relief Oil Market
Pain Management
Non Opioid Pain Treatment Market
Pain Management
Radiofrequency Ablation Devices for Pain Management Market
Pain Management
Chronic Pain Treatment Market
Pain Management
Global Postoperative Pain Management Market
Pain Management
Migraine Management Market
Pain Management
Global Non-Opioid Pain Patch Market