
 Global Pain Management Market | 2026-2036
Global Pain Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pain Management Market Outlook
Software-defined dosing algorithms embedded in connected infusion pumps is rebalancing how pharmaceutical companies monetize chronic pain therapy. Pfizer Inc. leverages its established biologics manufacturing infrastructure to sustain supply security for long-acting injectable formulations. Johnson & Johnson Services, Inc. anchors its competitive stance through deep vertical integration across surgical and pharmaceutical pain modalities. Abbott Laboratories differentiates via proprietary neuromodulation platforms that compete directly with Medtronic's spinal cord stimulation portfolio.
Pain management encompasses pharmacological, interventional, and device-based modalities engineered to modulate nociceptive signaling across acute and chronic conditions, with therapeutic indices calibrated to patient-specific metabolic profiles and comorbidity burdens. The discipline serves industrial purposes spanning perioperative recovery, oncology palliation, and functional restoration in degenerative disorders. Analgesics occupy the largest revenue pool within product type segmentation, though transdermal delivery modes capture disproportionate margin expansion due to formulation complexity and patent-protected absorption technologies. Neuropathic pain therapy areas demonstrate the fastest structural growth trajectory, driven by diabetic population expansion and expanded diagnostic coding for peripheral nerve disorders.
The FDA maintains stringent REMS protocols for opioid analgesics, while the EMA's pharmacovigilance framework shapes European access conditions for novel non-opioid molecules. China's NMPA accelerates review timelines for innovative pain devices under revised Class III medical device pathways, altering competitive entry sequencing across Asia-Pacific markets. Stakeholders must monitor evolving reimbursement thresholds for digital therapeutics as health technology assessment bodies in Germany, the United Kingdom, and Japan incorporate real-world evidence requirements into coverage determinations.
Market Dynamics
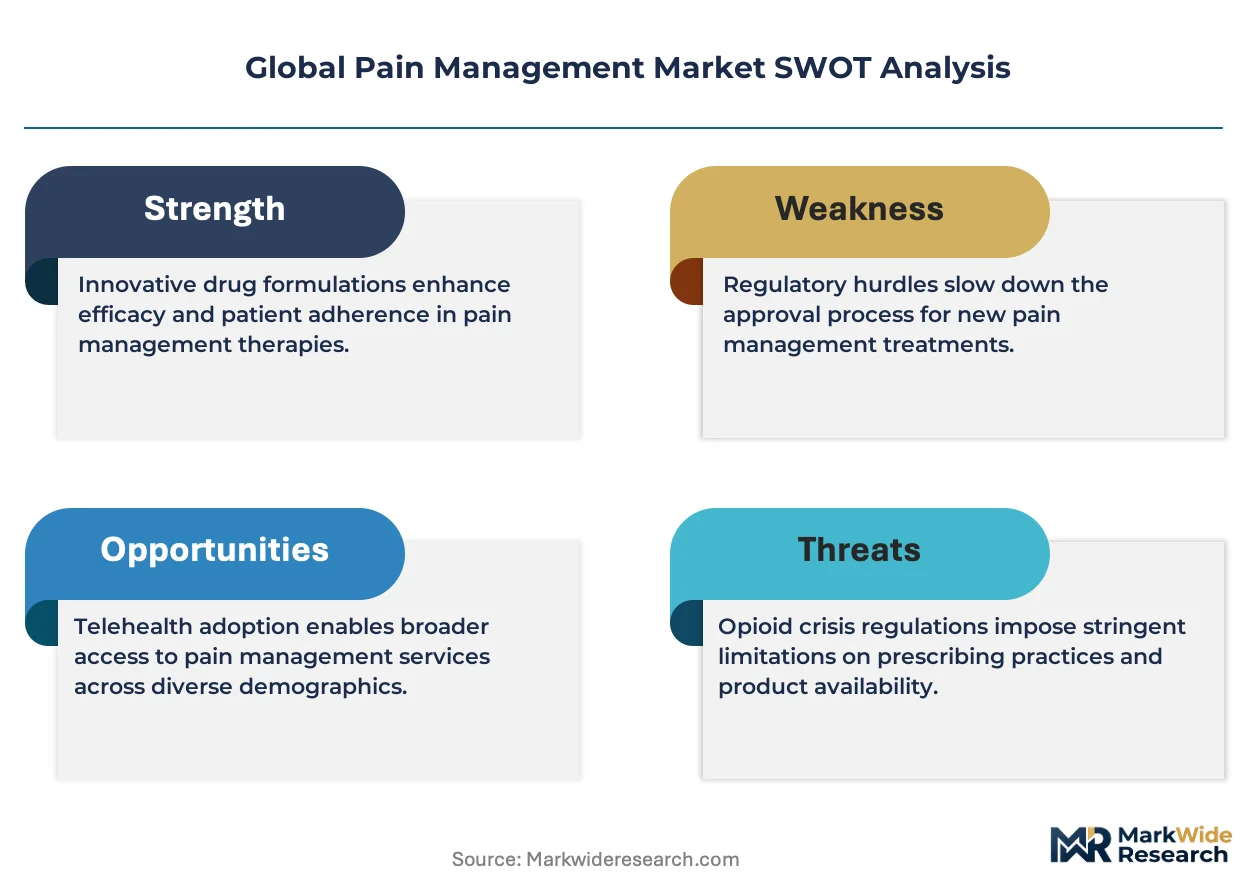
The FDA's Risk Evaluation and Mitigation Strategy for extended-release opioids has triggered a wholesale reconfiguration of prescribing protocols, forcing pharmaceutical manufacturers to pivot toward non-opioid formulations and device-based alternatives while hospital formularies tighten controlled-substance access.
Growth Catalysts
- Germany's statutory health insurance expansion:Reimbursement coverage for neuromodulation devices now extends to chronic neuropathic conditions, broadening patient access beyond prior restrictive criteria.
- Multimodal analgesia protocols:Tertiary hospitals in the United States, Japan, and Australia now mandate combination therapy approaches for post-surgical recovery, driving demand across pharmaceutical and device categories simultaneously.
- Connected infusion pump algorithms:Software-defined dosing systems embedded in smart pumps enable real-time pharmacokinetic adjustments, reducing adverse events and supporting chronic therapy adherence.
Market Restraints
- Active pharmaceutical ingredient concentration:Synthesis of long-acting opioid formulations depends on concentrated supply from Indian and Chinese bulk manufacturers, creating vulnerability to export restriction cascades.
- Neuromodulation device reimbursement lag:France's ANSM and Italy's AIFA maintain narrower indication approvals than Germany, fragmenting market access across otherwise integrated European economies.
- Transdermal patch formulation complexity:Patent-protected absorption technologies limit generic competition, sustaining elevated price points that constrain volume expansion in price-sensitive markets.
Strategic Opportunities
- Brazil's ANVISA accelerated pathway:Streamlined review timelines for Class III pain devices create first-mover advantage for manufacturers establishing Latin American manufacturing presence.
- Digital therapeutics integration:Cognitive behavioral therapy platforms delivered via prescription digital therapeutic pathways in the United Kingdom and Japan complement pharmacological interventions for chronic pain.
- Bioresorbable nerve scaffolds:Convergence of tissue engineering with interventional pain medicine opens perioperative applications previously served solely by systemic analgesia.
Industry Challenges
- Pain medicine specialist scarcity:Fellowship-trained interventionalists remain concentrated in urban academic centers, limiting rural and community hospital access to advanced neuromodulation procedures.
- REMS compliance infrastructure:Pharmaceutical manufacturers must maintain separate distribution, prescriber certification, and patient monitoring systems for opioid products, duplicating operational overhead.
- Legacy electronic health record integration:Connected infusion pumps and neuromodulation programming interfaces require costly interoperability upgrades to exchange data with hospital information systems.
Report Scope
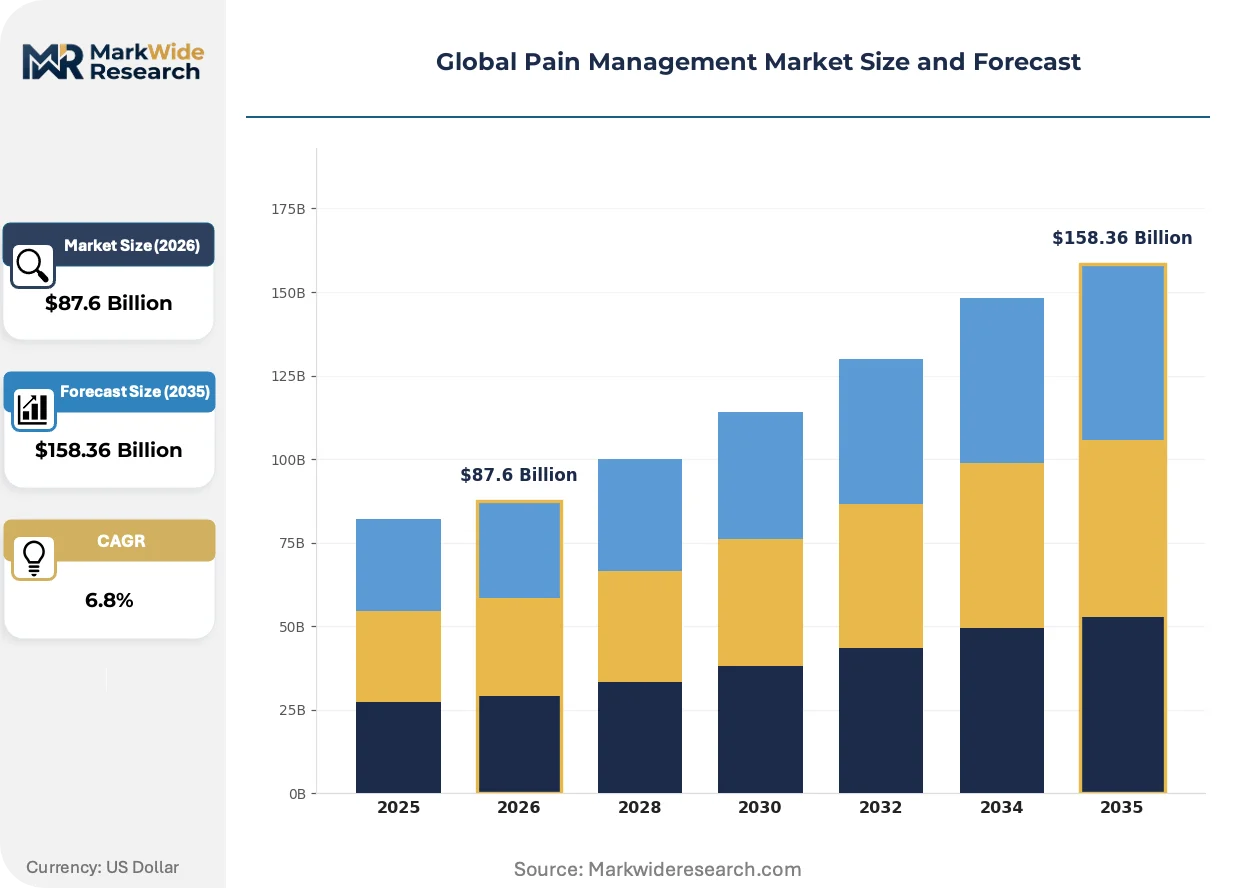
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pain Management Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analgesics, Antidepressants, Anticonvulsants, Topical Agents Delivery Mode: Injection, Oral, Transdermal, Inhalation End User: Hospitals, Clinics, Homecare, Rehabilitation Centers Therapy Area: Neuropathic Pain, Cancer Pain, Chronic Pain, Acute Pain |
| Companies Covered | Pfizer Inc., Johnson & Johnson Services, Inc., Abbott Laboratories, Medtronic, Boston Scientific Corporation, GSK plc, Novartis AG, Eli Lilly and Company, Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pain Management Market Strategic Shifts
Software-defined dosing systems and closed-loop neuromodulation hardware are compressing the traditional separation between pharmaceutical and device-based pain therapy, creating hybrid therapeutic categories that demand new regulatory frameworks and reimbursement models.
Closed-loop spinal cord stimulation platforms with embedded evoked compound action potential sensing are consolidating market share among implantable pain devices. Academic medical centers in Germany, the Netherlands, and Switzerland now prioritize these systems for complex regional pain syndrome cases. The technology is consolidating formerly separate diagnostic and therapeutic procedures into single-session interventions, reducing total cost of care while raising hardware procurement thresholds.
China's NMPA revised Class III medical device review timelines compress approval cycles for innovative pain technologies from thirty-six to eighteen months. Domestic manufacturers in Shenzhen and Suzhou now achieve parity with multinational submissions for neuromodulation hardware. Korean and Australian regulators are harmonizing technical documentation requirements with this accelerated framework, shifting competitive entry sequencing across Asia-Pacific markets.
Hospital procurement committees now unbundle pain device purchasing from exclusive vendor service contracts, forcing manufacturers to compete on capital equipment cost rather than bundled technical support. This pattern is most visible in National Health Service trusts across England and Scotland, where centralized procurement frameworks mandate transparent pricing for implantable pulse generators and leads. Independent service organizations are capturing maintenance revenue previously retained by original equipment manufacturers.
Global Pain Management Market Segmentation
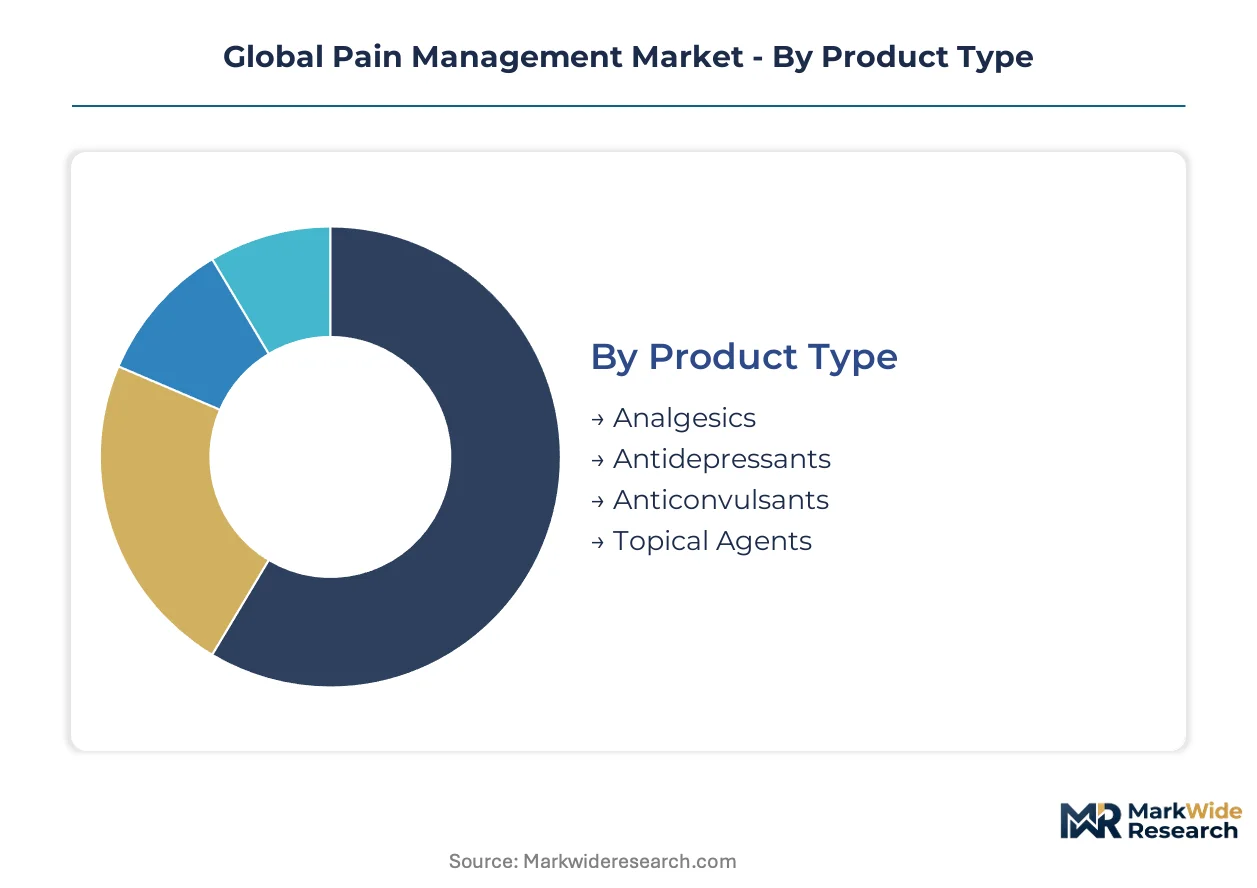
Pain management segmentation reflects divergent capital requirements across pharmaceutical manufacturing, device fabrication, and service delivery infrastructure. Each category demands distinct regulatory pathways and reimbursement negotiations that shape competitive entry costs.
Product Type:
Analgesics command the heaviest upfront investment due to API synthesis facilities, sterile manufacturing suites, and REMS compliance infrastructure. Antidepressants and anticonvulsants repurposed for neuropathic indications require lower capital barriers but face crowded generic competition.
- Analgesics:Opioid and non-opioid molecules synthesized through multi-step chemical processes requiring dedicated containment facilities. Demand concentrates in United States hospital formularies where multimodal protocols mandate combination therapy. FDA REMS infrastructure adds recurring compliance overhead that sustains incumbent advantages.
- Anticonvulsants:Gabapentinoids manufactured through conventional pharmaceutical processes with established generic supply chains. German statutory insurance reimbursement for neuropathic pain indications drives prescription volume in European markets. Patent cliffs on originator molecules have compressed margins while expanding access.
- Antidepressants:Tricyclics and SNRIs with dual mechanisms for chronic pain modulation. Japanese PMDA approvals for fibromyalgia indications support regional demand concentration.
- Topical Agents:Local anesthetics and capsaicin formulations requiring specialized compounding or patch manufacturing. Brazil ANVISA accelerated pathways enable faster entry for novel delivery formats.
Most installed capacity flows through analgesics. Expansion is steepest in anticonvulsants.
Delivery Mode:
Route of administration determines manufacturing complexity, patient adherence profiles, and reimbursement coding. Injection and transdermal modes carry premium pricing but require specialized production assets.
- Transdermal:Matrix and reservoir patch technologies demanding solvent-handling capabilities and precision coating equipment. United Kingdom NHS procurement frameworks unbundle device purchasing from service contracts, pressuring manufacturers on capital equipment cost. Patent-protected absorption technologies limit generic substitution.
- Injection:Long-acting depot formulations and connected infusion pumps with embedded dosing algorithms. Tertiary hospitals in Australia and Japan now mandate smart pump integration for post-surgical protocols. Software-defined systems enable real-time pharmacokinetic adjustments.
- Oral:Immediate and extended-release tablets with established high-volume manufacturing. Indian and Chinese API suppliers dominate bulk material supply.
- Inhalation:Nebulized and intranasal formulations for rapid-onset acute pain. Limited penetration outside oncology palliation and emergency medicine.
Oral formulations retain the largest installed base. Connected infusion systems are gaining share fastest.
End User:
Site of care influences regulatory classification, reimbursement rates, and competitive dynamics between pharmaceutical and device manufacturers.
- Hospitals:Tertiary centers with centralized pharmacy and interventional pain services. Germany's university hospitals anchor neuromodulation device adoption through statutory insurance coverage expansion.
- Homecare:Infusion pump rentals and transdermal patch dispensing requiring logistics networks and patient monitoring infrastructure. United States Medicare reimbursement codes shape competitive positioning.
- Clinics:Ambulatory surgery centers and pain medicine practices performing interventional procedures. Fellowship-trained specialist scarcity limits rural access.
- Rehabilitation Centers:Physical therapy integration with pharmacological and device-based modalities. China's NMPA Class III device pathways accelerate hardware approvals for this channel.
Hospital procurement committees control the largest volume. Homecare channels are expanding most quickly.
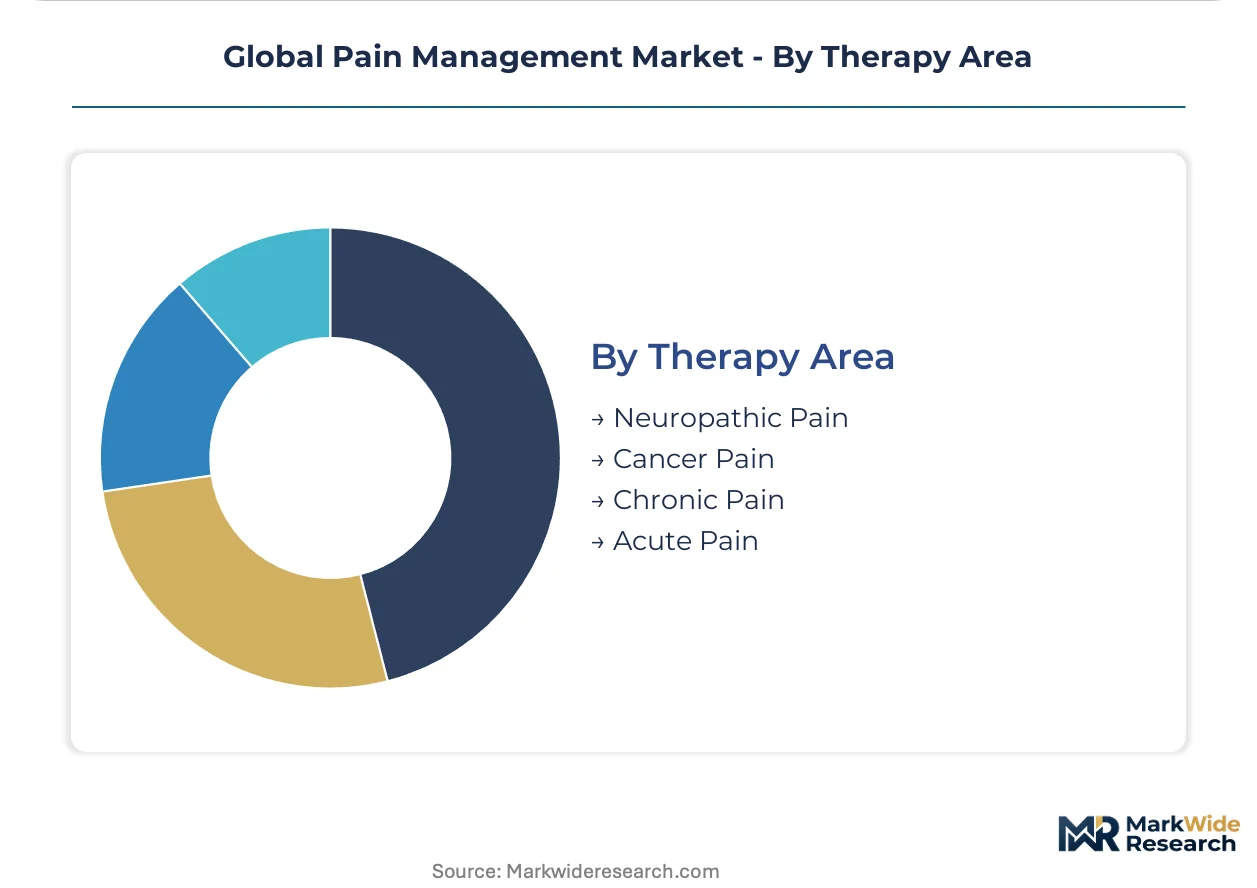
Therapy Area:
Underlying pathophysiology determines treatment duration, polypharmacy requirements, and device candidacy. Neuropathic and cancer pain segments sustain premium pricing through unmet medical need.
- Neuropathic Pain:Peripheral and central sensitization conditions including diabetic neuropathy and post-herpetic neuralgia. Diabetic population expansion in India and China drives diagnostic coding growth. Closed-loop spinal cord stimulation platforms consolidate share among implantable devices.
- Cancer Pain:Nociceptive and neuropathic components requiring escalation from WHO analgesic ladder to interventional techniques. Palliative care integration in Netherlands and Switzerland academic centers prioritizes multimodal approaches.
- Chronic Pain:Persistent non-cancer conditions including low back pain and osteoarthritis. United Kingdom prescription digital therapeutic pathways for cognitive behavioral therapy complement pharmacological management.
- Acute Pain:Post-surgical and trauma-related indications with defined treatment windows. Multimodal protocols in Australian tertiary hospitals mandate combination therapy.
Chronic pain carries the largest patient volume. Neuropathic indications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting pain device manufacturing toward jurisdictions with streamlined Class III approval pathways, while reimbursement fragmentation across statutory health systems creates divergent market access conditions for pharmaceutical and neuromodulation portfolios.
United States
Hospital formularies at tertiary centers in Boston, Houston, and Cleveland now mandate multimodal analgesia protocols for post-surgical recovery, compressing demand for standalone opioid formulations. The FDA's REMS infrastructure for extended-release opioids forces manufacturers to maintain separate distribution and prescriber certification systems, elevating compliance costs for new entrants. Philadelphia and Research Triangle Park anchor the largest concentration of pain medicine clinical trial infrastructure.
Germany
Statutory health insurance expansion for neuromodulation devices has broadened patient access beyond prior restrictive criteria for chronic neuropathic conditions. The Federal Joint Committee (G-BA) now mandates health technology assessment evidence for novel non-opioid molecules entering the statutory reimbursement catalog. Munich and Heidelberg university hospitals anchor closed-loop spinal cord stimulation adoption for complex regional pain syndrome cases.
China
Shenzhen and Suzhou manufacturers now achieve parity with multinational submissions for neuromodulation hardware under NMPA's compressed eighteen-month Class III review timelines. The diabetic population expansion in Shanghai and Beijing diagnostic centers drives coding growth for peripheral neuropathy indications. Domestic production of long-acting injectable formulations concentrates in Jiangsu province API synthesis clusters.
Japan
PMDA approvals for fibromyalgia indications support regional demand concentration for antidepressant-class pain modulators in Tokyo and Osaka metropolitan prescribing networks. Tertiary hospitals in Yokohama and Nagoya now mandate smart infusion pump integration for perioperative protocols. The Ministry of Health, Labour and Welfare's reimbursement pricing for connected dosing systems lags European benchmarks, constraining hardware penetration.
Brazil
ANVISA's accelerated pathway for Class III pain devices creates first-mover positioning for manufacturers establishing Latin American manufacturing presence. São Paulo and Rio de Janeiro pain medicine practices concentrate fellowship-trained interventionalists, limiting rural access to advanced neuromodulation procedures. Transdermal patch formulation demand concentrates in Minas Gerais pharmaceutical distribution corridors serving the statutory health system.
Global Pain Management Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical incumbents defending position through REMS compliance infrastructure while device makers compete on capital equipment cost under unbundled procurement frameworks. The vendor base organizes around three archetypes: diversified healthcare conglomerates with vertical control across surgical and pharmaceutical modalities, pure-play neuromodulation hardware specialists, and generic API suppliers serving formulation-dependent markets. Dominant competitive moves include portfolio diversification into non-opioid molecules and strategic partnerships for digital therapeutic integration.
Among diversified healthcare conglomerates, Pfizer Inc. and Johnson & Johnson Services, Inc. occupy positions that exemplify the integrated pharmaceutical-device archetype, with the former leveraging biologics manufacturing infrastructure and the latter anchoring competitive stance through control across surgical and pharmaceutical pain modalities. Abbott Laboratories represents the neuromodulation hardware specialist tier, differentiating via proprietary platforms that compete directly with Medtronic's spinal cord stimulation portfolio.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Johnson & Johnson Services, Inc. |
| Abbott Laboratories |
| Medtronic |
| Boston Scientific Corporation |
| GSK plc |
| Novartis AG |
| Eli Lilly and Company |
| Merck & Co., Inc. |
| Others |
Value Chain & Pricing Dynamics
EMA pharmacovigilance mandates for novel non-opioid molecules gate qualified supply access and premium-tier pricing for manufacturers seeking European market entry, compressing margin structures for firms lacking REMS-compliant distribution infrastructure or health technology assessment documentation.
Pricing Analysis
Capacity additions in Indian API synthesis clusters are reshaping price floors for oral analgesic formulations while transdermal patch manufacturers defend premium positioning through patent-protected absorption technologies. Pricing stratifies across premium, standard, and economy tiers based on formulation complexity and FDA REMS certification status. Cost compression in generic gabapentinoids is intensifying because of Chinese bulk manufacturer export expansion. Hospital procurement committees demonstrate highest price sensitivity, while homecare infusion pump rentals sustain lowest sensitivity due to reimbursement code bundling.
Supply Chain Analysis
China's NMPA domestic-content requirements for Class III medical devices are reshaping sourcing patterns for neuromodulation hardware manufacturers, forcing multinational assemblers to qualify Shenzhen and Suzhou component suppliers. Active pharmaceutical ingredient production draws from India, China, and Italy. Long-acting injectable formulations rest on concentrated bupivacaine and morphine sulfate supplies. Single-source vulnerability pervades connected infusion pump microcontroller sourcing. Distribution runs through hospital procurement committees, GPO contracts, and specialty pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as tertiary hospital formularies shift procurement criteria toward closed-loop neuromodulation platforms with embedded sensing capabilities.
For Market Incumbents: Lock in REMS compliance infrastructure as a defensive moat against non-opioid entrants lacking prescriber certification systems. Deepen backward integration into biologics manufacturing to secure long-acting injectable supply security against Indian and Chinese API export restriction cascades. For New Entrants and Emerging Players: Enter via Brazil's ANVISA accelerated pathway for Class III pain devices to establish Latin American manufacturing presence before multinational incumbents localize production. Target cognitive behavioral therapy platform integration as the most penetrable digital therapeutics segment. For Investors and Strategic Acquirers: Roll-up economics work for neuromodulation hardware specialists because hospital procurement committee unbundling of device purchasing from service contracts fragments vendor maintenance revenue streams. Five-to-ten year viability hinges on closed-loop spinal cord stimulation platform adoption curves. Watch Germany's Federal Joint Committee health technology assessment evidence requirements as the inflection indicator for European non-opioid molecule reimbursement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Infrastructure Investment | FDA-mandated distribution systems create compliance barriers that sustain incumbent pricing power. |
| Closed-Loop Platform Development | Evoked compound action potential sensing consolidates market share among German academic medical centers. |
| Digital Therapeutic Integration | United Kingdom prescription pathways for cognitive behavioral therapy complement pharmacological interventions. |
| Latin American Manufacturing Localization | ANVISA accelerated timelines enable first-mover positioning in São Paulo and Rio de Janeiro markets. |
| Health Technology Assessment Preparation | Germany's G-BA evidence requirements determine statutory reimbursement catalog inclusion for novel molecules. |
Study Parameters
Bottom-up hospital formulary modeling reconciled against top-down API production tracking forms the analytical core of this study. Primary interviews with pain medicine specialists, hospital procurement managers, GPO contracts directors, and regulatory affairs leads at pharmaceutical manufacturers were validated against FDA REMS documentation, EMA pharmacovigilance filings, ClinicalTrials.gov protocol registries, and NMPA Class III device approval databases. Secondary triangulation incorporated customs trade data for bulk analgesic imports and hospital procurement database extracts from National Health Service trusts.
Input-output matrices mapped product-type demand across delivery modes and therapy areas throughout the forecast period. Segmentation dimensions modeled include pharmacological class, route of administration, site of care, and underlying pain pathophysiology. CAGRs were derived from slope-intercept analysis of installed base expansion and replacement cycles. Forecast inputs incorporated diabetic population growth projections and neuromodulation device reimbursement threshold trajectories.
Inputs from regulatory filing databases and hospital procurement systems were available through the study window; gaps in real-world evidence for digital therapeutics introduce uncertainty bands around cognitive behavioral therapy platform adoption curves. Forecasts reflect documented assumptions regarding statutory insurance expansion timelines and REMS protocol evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Chronic Pain Treatment Market
Pain Management
Visceral Pain Market
Pain Management
Opioid Induced Side Effects Treatment Market
Pain Management
Topical Pain Relief Market
Pain Management
OTC Painkiller Market
Pain Management
Global Fibromyalgia Treatment Market
Pain Management
Global Morphine Market
Pain Management
Pain Management Devices Market
Pain Management
Topical Pain Relief Cream Market
Pain Management
Cluster Headache Market
Pain Management
Non Opioid Pain Treatment Market
Pain Management
Lumbosacral Radicular Pain Management Market
Pain Management
Cancer Pain Market
Pain Management
Chinese Fibromyalgia Market
Pain Management
Plantar Fasciitis Treatment Market
Pain Management
Medicated Pain Relieving Plasters Market