
 Axial Spondyloarthritis Management Market | 2026-2036
Axial Spondyloarthritis Management Market Size, Share, and Industry Trends Forecast 2026-2036
Axial Spondyloarthritis Management Market Outlook
Subscription-based patient support programs is rebalancing how pharmaceutical firms monetize chronic disease management beyond the pill. AbbVie leverages integrated care platforms to sustain adherence rates across its immunology portfolio. Novartis Pharmaceuticals Corporation anchors European market access through specialized distribution networks for biologic therapies. Eli Lilly and Company differentiates via digital companion tools that extend clinical engagement between infusion cycles.
Axial spondyloarthritis management encompasses diagnostic, therapeutic, and monitoring interventions targeting inflammatory spine and sacroiliac joint disease, with biologics typically administered via subcutaneous injection or IV infusion at specified dosing intervals to inhibit IL-17 or TNF-alpha pathways. The primary purpose centers on preventing irreversible spinal fusion while preserving functional mobility in patients with non-radiographic and radiographic disease phenotypes. Biologics command the dominant margin pool despite JAK inhibitors gaining share in oral convenience segments. Injectable delivery modes retain clinical preference for biologic agents, though oral formulations reshape home care utilization patterns where patient self-administration reduces site-of-care dependency.
FDA oversees biologic licensing and REMS requirements for TNF-alpha and IL-17 inhibitors, while EMA's MDR framework shapes post-market surveillance obligations across European markets. The FDA's accelerated approval pathways and EMA's adaptive licensing models compress development timelines for novel mechanism agents. Payers and providers must monitor how CMS reimbursement adjustments and national health technology assessments in Germany and Japan influence site-of-care migration from hospitals to home settings.
Market Dynamics
Biologic therapy pipelines are compressing development timelines through FDA accelerated approval and EMA adaptive licensing pathways, while site-of-care migration from infusion centers to home settings reshapes distribution economics across rheumatology practices.
Growth Catalysts
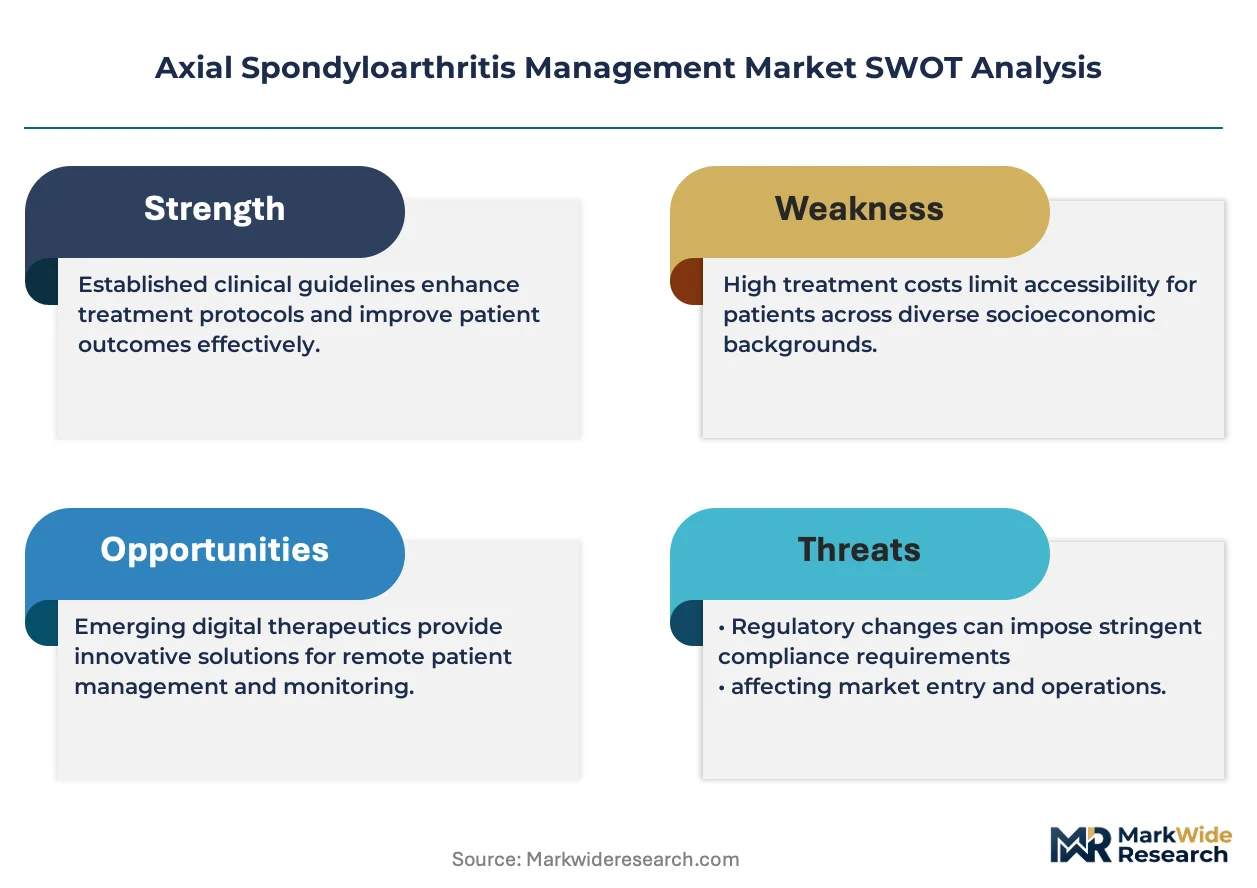
- EMA Adaptive Licensing:The European framework enables conditional market entry for novel IL-23 and JAK inhibitor mechanisms, compressing Phase III-to-commercialization intervals for mechanism-of-action innovators targeting non-radiographic axial spondyloarthritis.
- Subcutaneous Formulation Engineering:Rheumatology practices are adopting patient-administered biologics at accelerating velocity, reducing site-of-care dependency and expanding treatable patient populations beyond urban infusion center catchments.
- Japan Specialist Infrastructure:METI-coordinated rheumatology networks in Tokyo, Osaka, and Fukuoka create concentrated demand pools for advanced biologic administration, anchoring Asia-Pacific adoption curves.
Market Restraints
- Biosimilar Price Compression:FDA interchangeability designations for adalimumab biosimilars are eroding originator margin pools, forcing portfolio restructuring among TNF-alpha incumbent developers.
- Cold Chain Concentration:Distribution of IL-17 and IL-12/23 inhibitors depends on a limited network of certified logistics providers, creating single-point vulnerability in temperature-controlled last-mile delivery.
- Diagnostic Delay Fracture:Average seven-year intervals between symptom onset and rheumatologist referral in primary care settings limit addressable patient pools for early-intervention biologics.
Strategic Opportunities
- German HTA Alignment:IQWiG benefit assessment frameworks for biologics in axSpA create reimbursement clarity that incentivizes outcome-based contracting between manufacturers and statutory health insurers.
- Digital Therapeutic Adjuncts:Convergence of wearable activity monitoring with patient-reported outcome platforms enables remote disease activity scoring, supporting between-visit clinical decision-making.
- Home Infusion Services:Specialty pharmacy networks are building nurse-administered home biologic capabilities, capturing site-of-care economics previously retained by hospital outpatient departments.
Industry Challenges
- Rheumatology Workforce Density:Specialist physician supply constraints in secondary and tertiary care settings create patient access bottlenecks that limit biologic initiation rates despite diagnostic availability.
- REMS Compliance Complexity:FDA-mandated Risk Evaluation and Mitigation Strategies for JAK inhibitors impose prescriber certification and pharmacy verification burdens that increase administrative overhead per prescription.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Axial Spondyloarthritis Management Market |
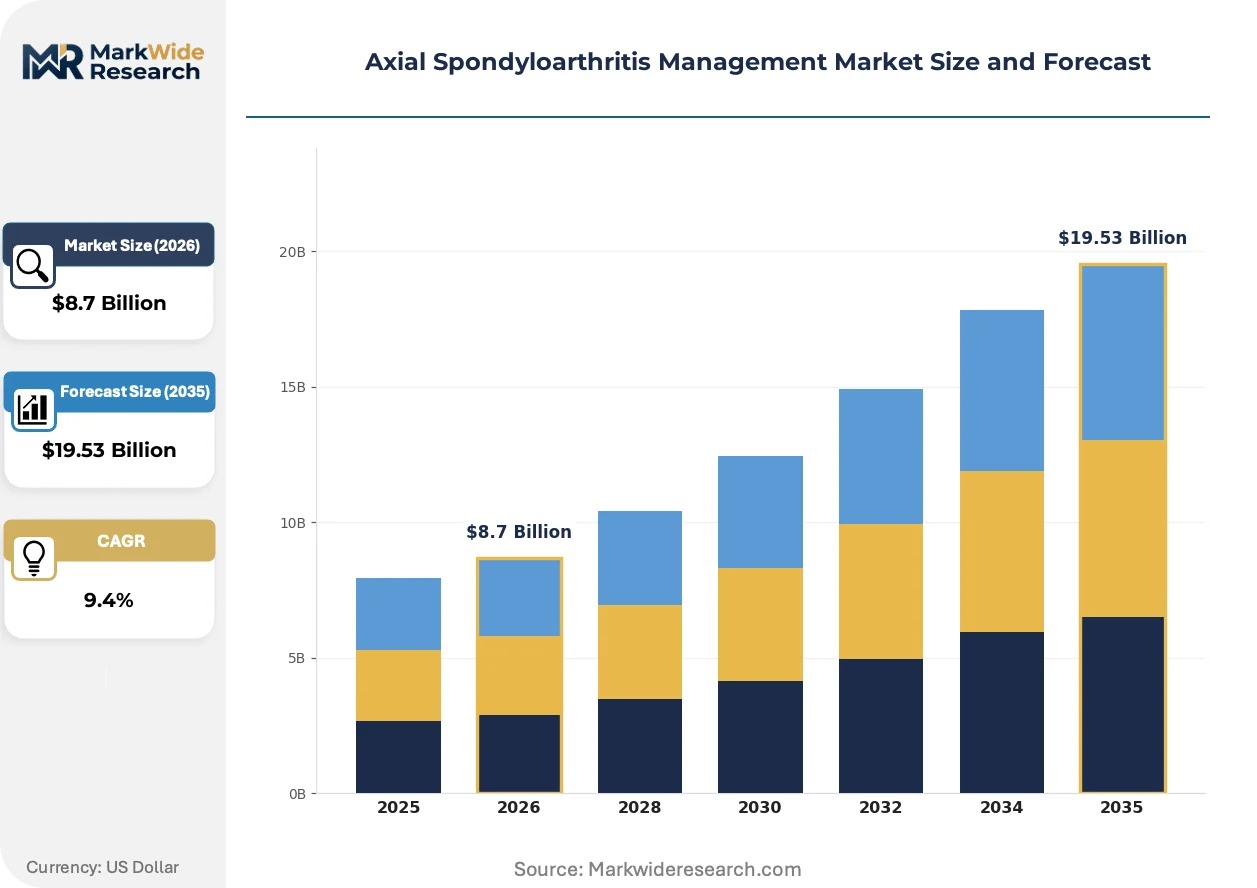
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: NSAIDs, DMARDs, Biologics, JAK Inhibitors Therapy Area: Rheumatology, Pain Management, Immunology, Physiatry End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Delivery Mode: Injectable, Oral, Topical, IV Infusion |
| Companies Covered | AbbVie, Novartis Pharmaceuticals Corporation, UCB, Johnson & Johnson, Janssen Biotech, Pfizer, Eli Lilly and Company, Amgen, Kyowa Kirin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Axial Spondyloarthritis Management Market Strategic Shifts
Machine learning applications in radiographic scoring and biomarker stratification are compressing diagnostic uncertainty windows, while regulatory frameworks on both sides of the Atlantic accelerate novel mechanism review timelines.
Artificial intelligence algorithms applied to sacroiliac joint MRI interpretation are automating radiographic progression assessment that previously required centralized specialist review. Rheumatology departments at academic medical centers are deploying these tools to triage imaging backlogs and standardize inflammation scoring across geographically dispersed reading sites. This automation is compressing time-to-diagnosis intervals and enabling earlier biologic eligibility determination in non-radiographic disease phenotypes.
EMA's Medical Device Regulation framework is tightening post-market surveillance obligations for combination products involving drug-device delivery systems. Manufacturers of autoinjector platforms for IL-17 inhibitors must now submit periodic safety update reports that integrate device malfunction data with adverse event reporting. Subcutaneous biologic developers with integrated delivery systems face disproportionate compliance burden compared to intravenous formulations.
Patient co-payment assistance restructuring is altering pharmacy benefit manager negotiation dynamics for specialty biologics. Employers and health plans in the United States are migrating toward accumulator and maximizer programs that shift manufacturer subsidy liability, forcing rheumatology practices to navigate more complex prior authorization workflows. This behavioral shift is most visible in commercial insurance segments where high-deductible health plan penetration exceeds fifty percent.
Axial Spondyloarthritis Management Market Segmentation
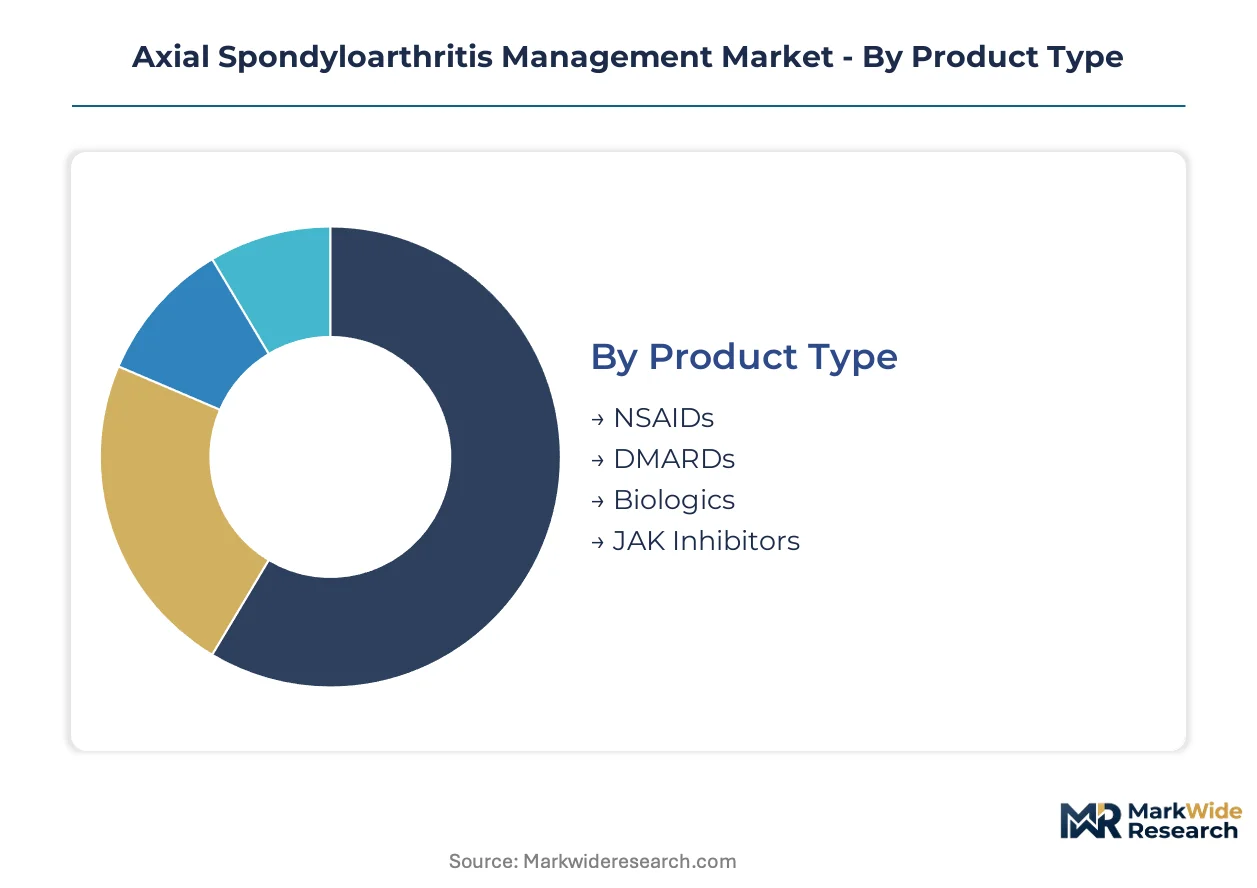
Segmentation in axial spondyloarthritis management reveals how clinical decision-making splits across mechanism-of-action preferences, site-of-care economics, and patient self-administration capabilities. Understanding these divides exposes where biologic margin pools concentrate versus where oral convenience reshapes utilization patterns.
Product Type:
Volume concentrates in legacy oral therapies, yet premium economics flow to biologic and targeted synthetic agents that command specialist oversight and reimbursement complexity.
- NSAIDs:First-line anti-inflammatory therapy comprising ibuprofen, naproxen, and celecoxib formulations that manage pain and stiffness without disease modification. Demand clusters in primary care gatekeeping systems across Germany and Japan where rheumatology referral delays extend symptom management intervals.
- DMARDs:Conventional synthetic agents including sulfasalazine and methotrexate that modulate peripheral joint involvement in spondyloarthritis spectrum presentations. Prescription volume is accelerating in India and Brazil where cost containment priorities favor non-biologic immunomodulation before biologic escalation pathways.
- Biologics:Monoclonal antibodies and fusion proteins targeting TNF-alpha, IL-17, and IL-23 pathways via subcutaneous or intravenous administration.
- JAK Inhibitors:Oral small-molecule agents including tofacitinib and upadacitinib that inhibit intracellular signaling cascades.
Today's leader: Biologics. Tomorrow's challenger: JAK Inhibitors.
Therapy Area:
Clinical ownership patterns determine where prescribing authority resides, with rheumatology's diagnostic primacy creating gatekeeper dynamics that other specialties navigate through referral relationships.
- Rheumatology:Specialist discipline holding diagnostic authority for inflammatory back pain classification and biologic eligibility determination. Academic medical centers in the United States and university hospitals in Germany anchor protocol development that shapes treatment algorithms adopted across secondary care networks.
- Pain Management:Interventional and pharmacologic approaches addressing mechanical complications and neuropathic components of advanced disease. Multidisciplinary clinics in Japan and the United Kingdom integrate these services with rheumatology to manage spinal fusion sequelae.
- Immunology:Mechanism-focused therapeutic selection bridging rheumatologic and dermatologic expertise for patients with overlapping psoriasis.
- Physiatry:Rehabilitation medicine emphasizing functional preservation through exercise prescription and assistive device optimization.
Rheumatology retains diagnostic primacy. Pain management is gaining referral volume fastest.
End User:
Site-of-care migration is redistributing where biologic administration occurs, with home settings capturing economics previously retained by hospital outpatient departments.
- Hospitals:Tertiary centers managing complex infusion protocols, REMS-mandated monitoring, and comorbidity assessment before biologic initiation. Major teaching hospitals in the United States and Japan concentrate IL-17 inhibitor first doses under observation protocols.
- Clinics:Community rheumatology practices and infusion centers handling maintenance dosing and disease activity monitoring. Independent clinic networks in Germany are expanding nurse-administered subcutaneous capabilities to compete with hospital outpatient departments.
- Home Care:Patient self-administration of subcutaneous biologics and oral therapies reducing site-of-care dependency.
- Rehabilitation Centers:Post-acute facilities addressing functional decline and spinal mobility preservation.
Clinics dominate maintenance volume. Home care is climbing the fastest.
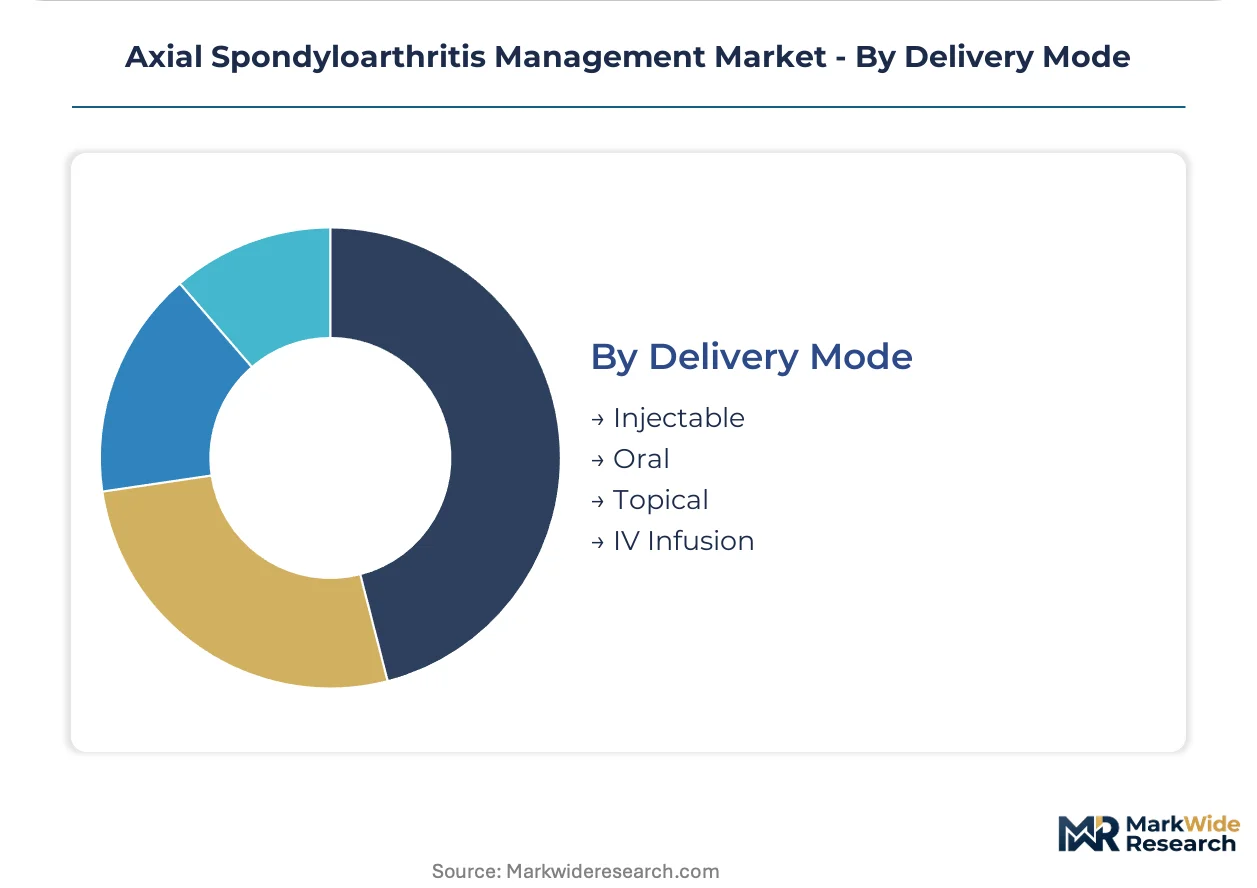
Delivery Mode:
Formulation engineering is compressing the convenience gap between biologic and oral therapies, with autoinjector platforms reshaping patient self-administration economics.
- Injectable:Subcutaneous administration via prefilled syringes and autoinjector devices for TNF-alpha and IL-17 inhibitors. Patient-administered formulations from specialty pharmacies in the United States and Germany are displacing infusion center visits for maintenance dosing.
- IV Infusion:Intravenous delivery reserved for loading doses, mechanism switches, and patients with needle phobia or subcutaneous contraindications. Hospital outpatient departments in Japan retain preference for infliximab and other infusion-dependent agents.
- Oral:Small-molecule formulations including NSAIDs, JAK inhibitors, and conventional DMARDs enabling home-based management.
- Topical:Localized delivery for peripheral manifestations and symptomatic relief.
Injectable captures biologic volume. Oral formulations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps between the FDA and EMA are redirecting clinical trial investments and biologic manufacturing capacity toward jurisdictions with adaptive licensing frameworks. Site-of-care economics and specialist workforce density further differentiate national market attractiveness for advanced therapy developers.
United States
Commercial insurance dominance and high-deductible plan proliferation concentrate biologic demand in employer-sponsored segments. FDA REMS requirements for JAK inhibitors impose prescriber certification burdens that slow initiation rates. Major academic medical centers in Boston and the Research Triangle anchor protocol development that shapes rheumatology practice patterns nationwide.
Germany
Statutory health insurance integration and IQWiG benefit assessment frameworks create reimbursement predictability for biologic manufacturers. EMA centralized procedures enable rapid market access across member states from German regulatory submissions. University hospitals in Berlin and Munich concentrate specialized rheumatology capacity that drives adoption curve formation for novel mechanisms.
Japan
METI-coordinated rheumatology networks and centralized specialist referral systems compress diagnostic delay intervals compared to Western markets. PMDA consultation pathways for biologics align with EMA timelines, attracting parallel development programs. Tokyo, Osaka, and Fukuoka clusters concentrate infusion center infrastructure and patient-administered biologic training programs.
United Kingdom
NICE technology appraisals and NHS England specialized commissioning create tiered access pathways that differentiate biologic eligibility criteria. MHRA post-Brexit regulatory autonomy enables accelerated access schemes for IL-17 and IL-23 inhibitors. London and Manchester academic centers anchor real-world evidence generation that influences commissioning guidance updates.
Canada
Provincial formulary harmonization through the Common Drug Review reduces reimbursement fragmentation for biologic manufacturers. Health Canada alignment with FDA labeling creates regulatory efficiency for sponsors with US-first strategies. Ontario and Quebec concentrate rheumatology specialist supply and biologic infusion capacity relative to prairie and maritime provinces.
Axial Spondyloarthritis Management Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with originator biologic developers defending margin pools against biosimilar erosion while specialty pharmacy networks capture site-of-care economics. Market structure concentrates around TNF-alpha incumbents facing IL-17 and IL-23 mechanism challengers, with JAK inhibitors occupying oral convenience positioning. Three archetypes dominate: integrated immunology portfolios, mechanism-focused biologic specialists, and oral small-molecule convenience players. Competitive moves center on subcutaneous formulation engineering to enable patient self-administration, and outcome-based contracting with statutory payers to secure preferential formulary positioning.
Within the integrated immunology tier, AbbVie and Novartis Pharmaceuticals Corporation represent portfolio breadth strategies that span multiple autoimmune indications. Eli Lilly and Company occupies a position emphasizing digital companion tools and patient engagement platforms that extend clinical contact between dosing intervals. These three anchors exemplify how competitive differentiation increasingly depends on service-layer investments rather than mechanism-of-action novelty alone.
| Leading Market Players |
|---|
| AbbVie |
| Novartis Pharmaceuticals Corporation |
| UCB |
| Johnson & Johnson |
| Janssen Biotech |
| Pfizer |
| Eli Lilly and Company |
| Amgen |
| Kyowa Kirin |
| Others |
Value Chain & Pricing Dynamics
Originator-biosimilar bifurcation in biologic therapies splits pricing power between patent-protected IL-17 inhibitors and interchangeable adalimumab alternatives, with this divergence mapping directly onto cold-chain infrastructure investments versus commoditized distribution networks. Manufacturers of novel mechanism agents anchor margin defense in REMS-mandated prescriber certification programs that limit price transparency, while biosimilar sponsors compete on pharmacy benefit manager rebate positioning.
Pricing Analysis
Specialty pharmacy markup layers dominate biologic economics, with three-tier pricing structure across originator premium, authorized generic, and interchangeable biosimilar levels reflecting FDA designation status and payer formulary tier placement. Price differentiation hinges on REMS complexity and JAK inhibitor oral convenience versus subcutaneous administration burden. Cost compression in TNF-alpha originators is intensifying because CMS reimbursement adjustments favor lowest-net-cost alternatives. Commercial insurance segments with accumulator programs demonstrate highest price sensitivity; hospital outpatient departments with 340B pricing show lowest.
Supply Chain Analysis
Dual-sourcing requirements for IL-12/23 and IL-17 inhibitors mandate qualification of at least two certified cold-chain logistics providers per regional distribution hub, reflecting FDA temperature excursion protocols. Manufacturing concentrates in the United States, Switzerland, and Ireland where biologics capacity clusters around existing monoclonal antibody infrastructure. Raw material dependencies span Chinese hamster ovary cell lines, single-use bioreactor systems, and pharmaceutical-grade polysorbate stabilizers. Single-source vulnerability in certified last-mile cold chain creates distribution risk. Product flows through specialty pharmacy networks with patient hub services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The axial spondyloarthritis management market functions as a regulatory compounder where FDA accelerated approval and EMA adaptive licensing pathways compress development timelines and expand addressable patient pools beyond traditional diagnostic delay windows.
For Market Incumbents: Anchor portfolio resilience through backward integration into autoinjector device manufacturing and captive cold-chain logistics networks that reduce third-party dependency. Defend against IL-23 mechanism challengers by expanding indication breadth across psoriasis and psoriatic arthritis to leverage rheumatology prescriber relationships. Prioritize outcome-based contracting with German statutory health insurers to secure IQWiG benefit assessment advantages. For New Entrants and Emerging Players: Digital therapeutic adjuncts offering wearable-integrated disease activity monitoring represent the most penetrable wedge for technology-first market entry, targeting home care settings where patient self-administration reduces site-of-care dependency. White-space concentration exists in non-radiographic axial spondyloarthritis where diagnostic delay creates untreated populations. Pursue direct-to-patient support program partnerships with specialty pharmacy networks to bypass rheumatology workforce bottlenecks. For Investors and Strategic Acquirers: Consolidation pressure builds where biosimilar price erosion erodes originator margin pools below sustainable R&D reinvestment thresholds. Long-term viability favors developers with mechanism-of-action diversification spanning TNF-alpha, IL-17, and JAK inhibitor portfolios. Acquisition targets include mid-cap biologic specialists with integrated delivery system capabilities. Watch FDA interchangeability designation velocity as inflection indicator for competitive intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Engineering | Patient-administered biologics reduce infusion center dependency and expand rural access. |
| REMS Compliance Infrastructure | FDA-mandated prescriber certification programs create administrative barriers for competitors. |
| Outcome-Based Contracting | German IQWiG frameworks enable preferential statutory health insurance positioning. |
| Digital Companion Platform Development | Wearable-integrated monitoring extends clinical engagement between dosing intervals. |
| Biosimilar Interchangeability Pursuit | FDA designation unlocks automatic substitution at pharmacy level without prescriber intervention. |
Study Parameters
Coverage spans the United States, Germany, Japan, and the United Kingdom, with primary inputs from each market's rheumatology specialists and payer organizations. Drug development executives, regulatory affairs leads, formulary directors at major pharmacy benefit managers, and hospital procurement managers provided structured interviews on biologic adoption patterns and reimbursement dynamics. Secondary validation drew from FDA biologic licensing files, EMA centralized procedure assessments, ClinicalTrials.gov protocol registries, and German IQWiG benefit assessment documents. Bottom-up patient flow modeling and top-down pharmaceutical expenditure analysis were triangulated to anchor volume estimates.
Rate-of-change decomposition across therapy lines, administration routes, patient phenotypes, and regional regulatory clusters shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate blending with cross-correlation to rheumatology workforce density and diagnostic infrastructure expansion metrics. Modeled inputs included biologic initiation rates by disease severity, JAK inhibitor oral convenience elasticity, and site-of-care migration velocity from hospital outpatient to home administration settings.
The model holds under stable FDA and EMA regulatory timelines; deviation in accelerated approval withdrawal triggers or biosimilar interchangeability reversals would shift competitive intensity assumptions. Forecasts reflect documented assumptions regarding rheumatology referral pathway efficiency and cold-chain logistics capacity expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Companion Animal Postoperative Pain Management Therapeutics Market
Pain Management
Global Analgesic Infusion Pumps Market
Pain Management
OTC Painkiller Market
Pain Management
Chinese Fibromyalgia Market
Pain Management
Global Postoperative Pain Management Market
Pain Management
Asia-Pacific Tattoo Numbing Cream Market
Pain Management
Medical Morphine Market
Pain Management
Muscle Tension Dysphonia Treatment Market
Pain Management
Erythromelalgia Treatment Market
Pain Management
Intravenous (IV) Ibuprofen Market
Pain Management
Postoperative Pain Market
Pain Management
Cluster Headache Market
Pain Management
Global Post Herpetic Neuralgia Treatment Market
Pain Management
Pain Management Devices Market
Pain Management
Heat Therapy Market
Pain Management
Topical Pain Relief Market