
 Pain Management Devices Market | 2026-2036
Pain Management Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Pain Management Devices Market Intelligence
Software-defined programming and remote patient monitoring is hardening as the decisive service layer in pain management device monetization. Medtronic leverages its proprietary CareLink remote monitoring ecosystem to sustain recurring revenue streams across its neuromodulation installed base. Boston Scientific Corporation anchors its competitive posture through deep R&D investment in closed-loop spinal cord stimulation algorithms. Abbott differentiates via its proprietary low-energy burst waveform technology that occupies a distinct clinical positioning against conventional tonic stimulation protocols.
Pain management devices encompass electrotherapeutic and interventional instruments engineered to modulate nociceptive signaling through targeted energy delivery or pharmaceutical infusion, with spinal cord stimulators typically operating at pulse widths of 60–1000 microseconds and frequencies spanning 2–1200 Hz to achieve paresthesia-free analgesia. Their primary commercial purpose centers on reducing opioid dependency while restoring functional mobility in patients with refractory chronic pain conditions. Radiofrequency ablation devices command premium margin pools due to their disposable electrode consumables and outpatient procedural economics, while transcutaneous electrical nerve stimulators represent the most mature product category with commoditized pricing and direct-to-consumer channel saturation. Opioid-free therapies within the technology dimension are capturing disproportionate growth as institutional formularies and payer policies pivot toward non-pharmacological alternatives.
The FDA's 510(k) premarket notification framework and the EU Medical Device Regulation govern device safety profiles, clinical evidence requirements, and post-market surveillance obligations that directly shape product development budgets and market access timelines. The Centers for Medicare and Medicaid Services national coverage determinations for spinal cord stimulation establish reimbursement thresholds that condition physician adoption rates and hospital capital allocation decisions. Stakeholders must monitor evolving FDA guidance on breakthrough device designation for closed-loop neuromodulation systems, as this regulatory pathway will determine which manufacturers can compress time-to-market for next-generation platforms.
Market Dynamics
The migration from institutional to home-based pain management is restructuring reimbursement pathways and hardware specifications simultaneously. CMS national coverage determinations for spinal cord stimulation now explicitly incorporate remote monitoring capabilities, forcing manufacturers to embed connectivity as a core feature rather than an accessory.
Growth Catalysts
- FDA Breakthrough Device Designation:The FDA's accelerated pathway for closed-loop neuromodulation systems compresses premarket review timelines from 180 days to 90 days for qualifying hardware.
- Opioid Prescription Limits:State-level prescribing caps in the United States are channeling refractory chronic pain patients toward implantable neurostimulation alternatives.
- Radiofrequency Ablation:Outpatient procedural economics for lumbar facet joint denervation are expanding addressable patient populations beyond surgical candidates.
Market Restraints
- Implantable Battery Supply Concentration:Lithium-ion cell production for neuromodulation devices clusters in East Asian contract manufacturers, creating single-source vulnerability.
- Reimbursement Variability:Medicare Advantage plans apply divergent prior authorization criteria for spinal cord stimulator implantation across United States counties.
- Transcutaneous Device Commoditization:Direct-to-consumer TENS units from unbranded Asian manufacturers are eroding pricing power in the retail channel.
Strategic Opportunities
- India's Device Manufacturing Corridors:The PLI scheme for medical electronics offers 5-20% incentive on incremental sales for domestic production of pain management hardware.
- Closed-Loop Algorithm Convergence:Integration of accelerometer feedback with spinal cord stimulation waveforms enables posture-responsive dosing adjustments.
- Telehealth-Integrated Remote Programming:Virtual device parameter adjustment sessions are unlocking rural patient access previously constrained by specialist geography.
Industry Challenges
- Biomedical Engineer Talent Scarcity:Firmware development for implantable neurostimulation systems requires rare expertise in low-power wireless communication and biocompatibility protocols.
- 510(k) Clinical Evidence Burden:FDA demands for predicate device equivalence documentation are extending submission preparation cycles for next-generation waveform platforms.
- Legacy EMR Integration Complexity:Proprietary data formats from neuromodulation ecosystems resist seamless incorporation into hospital electronic medical record workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pain Management Devices Market |
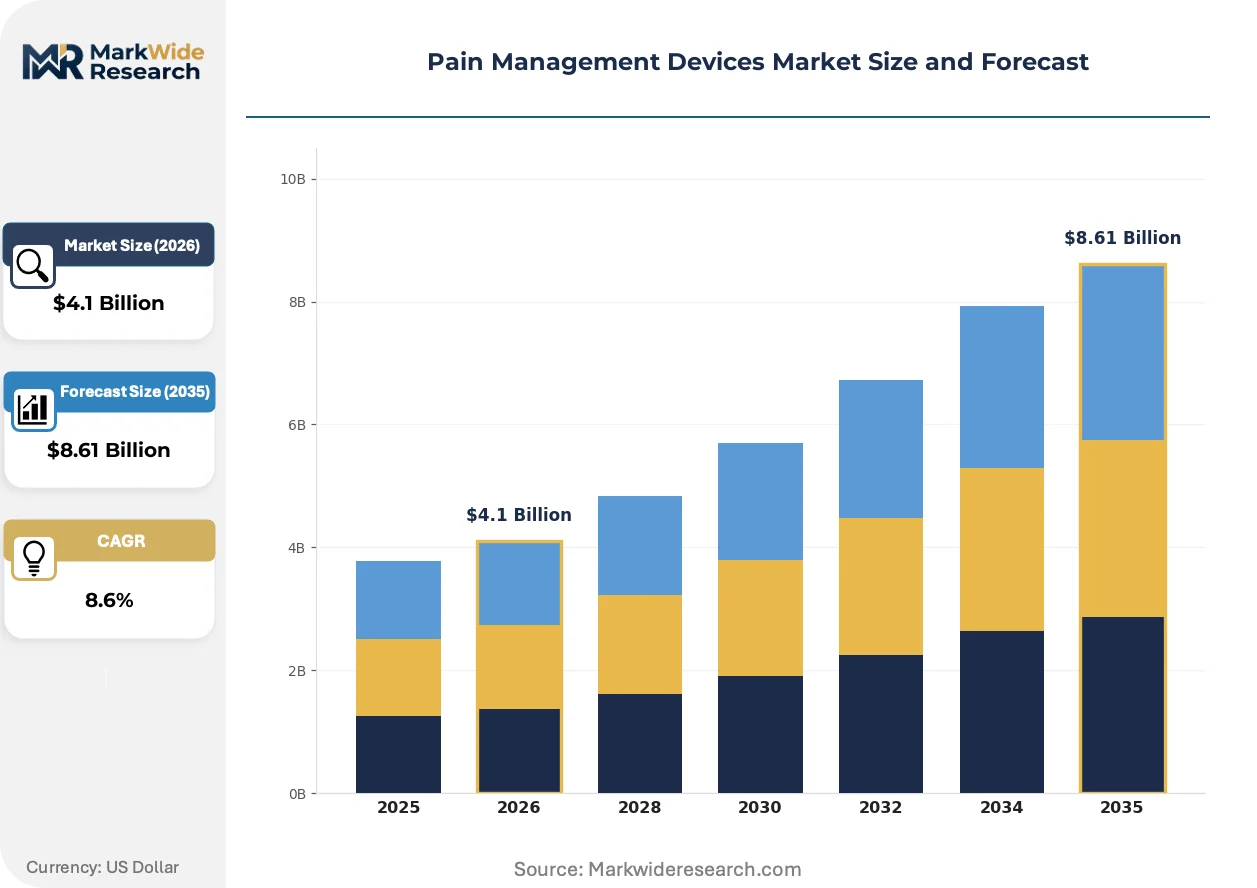
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $8.61 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transcutaneous Electrical Nerve Stimulators, Spinal Cord Stimulators, Radiofrequency Ablation Devices, Infusion Pumps End User: Hospitals, Clinics, Home Care Settings, Rehabilitation Centers Technology: Electrical Stimulation, Radiofrequency, Cryotherapy, Opioid-Free Therapies Application: Chronic Pain Management, Postoperative Pain Relief, Cancer Pain Control, Neuropathic Pain Treatment |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott, Stryker, Baxter International, B Braun Melsungen AG, Nevro Corp, LivaNova, ICU Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pain Management Devices Market Strategic Shifts & Innovations
Software-defined functionality is displacing fixed-parameter hardware as the primary locus of competitive differentiation. Three convergent developments are compressing product lifecycles and expanding serviceable revenue pools.
Paresthesia-free burst waveform protocols are overtaking conventional tonic stimulation as the default programming approach for spinal cord stimulators. Pain specialists in academic medical centers are adopting burst configurations within 18 months of device implantation. This shift is compressing differentiation timelines for manufacturers still dependent on amplitude-modulated legacy platforms.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic collection of real-world performance data across implantable neuromodulation cohorts. Manufacturers must now fund prospective registries or risk certificate suspension. High-volume implanting centers in Germany and France are consolidating purchasing authority to negotiate data-sharing agreements as a condition of device procurement.
Hospital procurement committees are unbundling device acquisition from long-term service contracts for the first time in spinal cord stimulation history. Third-party remote monitoring vendors are capturing recurring revenue streams previously retained by original equipment manufacturers. This disintermediation is most advanced in United States integrated delivery networks with captive payer relationships.
Pain Management Devices Market Segmentation
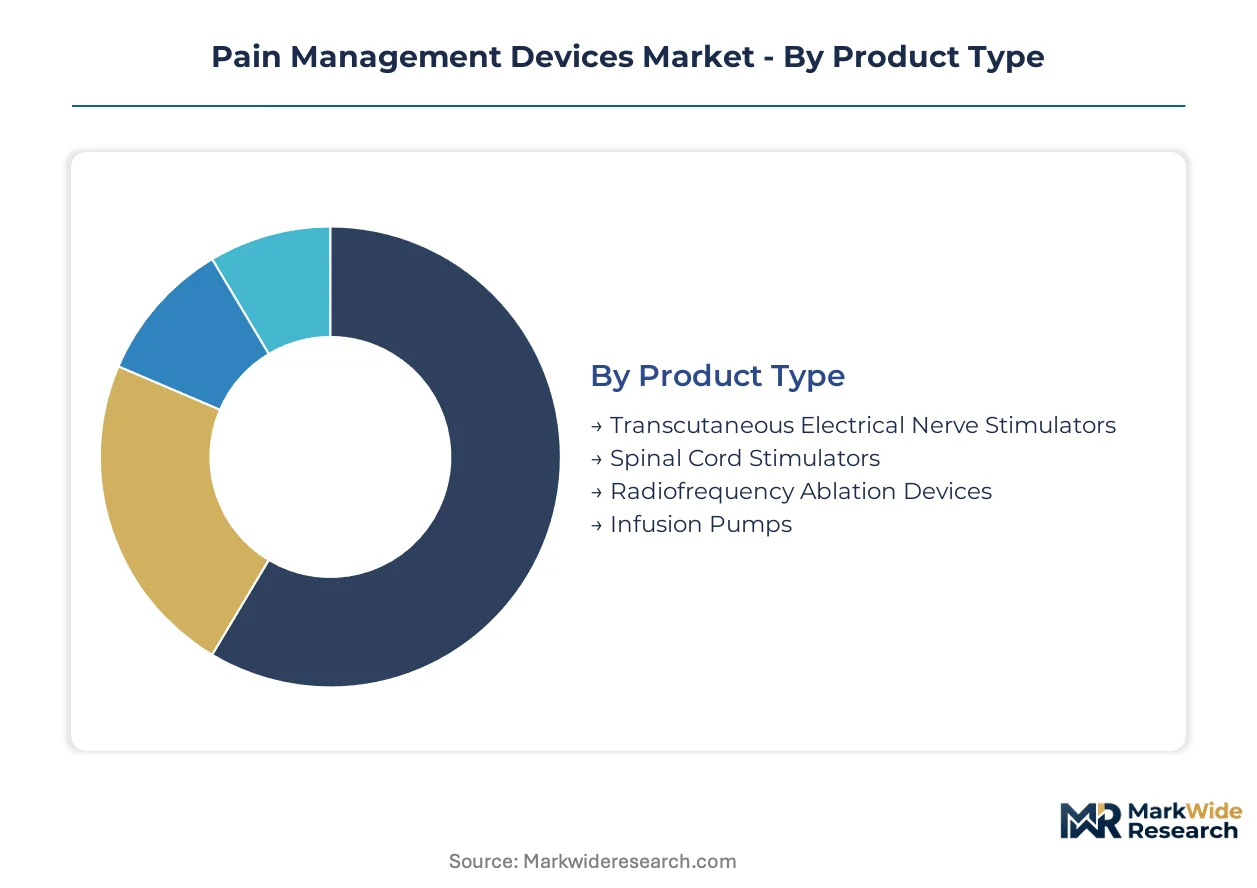
Segmentation in pain management devices reveals how hardware specifications, care delivery sites, and therapeutic mechanisms intersect to determine purchasing authority and reimbursement pathways. Manufacturers must align product portfolios across multiple dimensions simultaneously to capture volume in institutional settings while penetrating the expanding home care channel.
Product Type:
Supply concentration in implantable neuromodulation hardware tilts manufacturing capacity toward advanced stimulation platforms with embedded connectivity modules.
- Spinal Cord Stimulators:Implantable pulse generators deliver electrical impulses to the dorsal column via percutaneous or paddle leads, with rechargeable lithium-ion batteries enabling multi-year operational lifespans. Demand concentrates in United States academic medical centers where CMS reimbursement coverage for failed back surgery syndrome patients drives implant volumes; FDA breakthrough device designation for closed-loop systems is compressing competitive timelines for predicate-dependent manufacturers.
- Radiofrequency Ablation Devices:Thermal lesioning systems deploy monopolar or bipolar energy delivery through disposable cannula electrodes to denervate medial branch nerves. Outpatient surgical centers in Texas and Florida are expanding procedural throughput for lumbar facet joint indications; disposable electrode consumables generate recurring revenue streams that offset capital equipment depreciation cycles.
- Transcutaneous Electrical Nerve Stimulators:Surface electrode systems modulate nociceptive signaling through cutaneous stimulation without implantation.
- Infusion Pumps:Programmable drug delivery systems administer intrathecal analgesics directly to the spinal fluid.
Spinal cord stimulators absorb the bulk of installed capacity; radiofrequency ablation devices are expanding most quickly.
End User:
Reimbursement pathway fragmentation across care settings is redistributing device procurement authority away from hospital supply chains.
- Home Care Settings:Patients operate external neurostimulation chargers and remote monitoring applications outside institutional supervision. United States Medicare Advantage plans in Arizona and Nevada are expanding prior authorization flexibility for home-based spinal cord stimulator programming; CMS national coverage determinations now explicitly incorporate remote patient monitoring as a covered service element.
- Hospitals:Inpatient surgical suites and interventional pain suites manage complex implantation procedures with full sterile field requirements. Tertiary care centers in California and New York maintain purchasing committees that unbundle device acquisition from long-term service contracts; proprietary EMR integration capabilities are becoming decisive vendor selection criteria.
- Clinics:Ambulatory pain management practices perform trial stimulation screening and device programming adjustments.
- Rehabilitation Centers:Post-acute facilities incorporate TENS and cryotherapy into functional restoration protocols.
Hospitals retain the dominant share of implantable device procurement; home care settings are climbing the fastest.
Technology:
Regulatory evidence requirements under EU MDR and FDA 510(k) frameworks are stratifying development investment across energy delivery modalities.
- Electrical Stimulation:Waveform-based therapies encompass tonic, burst, and closed-loop parameter configurations with distinct paresthesia profiles. Burst waveform protocols are displacing conventional amplitude modulation in United States pain fellowship training programs; proprietary low-energy algorithms are creating defensible intellectual property positions against commodity stimulation hardware.
- Opioid-Free Therapies:Non-pharmacological intervention platforms address institutional formulary restrictions and payer opioid reduction mandates. United Kingdom National Health Service integrated care boards are prioritizing neurostimulation coverage for chronic lower back pain; state-level prescribing caps in Ohio and Pennsylvania are channeling refractory patients toward device-based alternatives.
- Radiofrequency:Thermal and pulsed energy delivery systems target specific nerve structures with anatomical precision.
- Cryotherapy:Cold-induced analgesia systems reduce inflammation and nerve conduction velocity in acute injury management.
Electrical stimulation commands the largest installed base; opioid-free therapies are gaining share fastest.
Application:
Clinical evidence requirements and reimbursement coding specificity vary substantially across pain etiologies, conditioning manufacturer trial design priorities.
- Chronic Pain Management:Refractory conditions persisting beyond three months drive the majority of implantable neurostimulation utilization. Failed back surgery syndrome and complex regional pain syndrome patients in United States spine specialty practices are the primary screening population; prospective registry data collection under EU MDR post-market surveillance obligations is mandating long-term outcome documentation.
- Neuropathic Pain Treatment:Peripheral and central nerve injury indications represent expanding off-label utilization with accumulating real-world evidence. Diabetic peripheral neuropathy cohorts in Germany and France are entering manufacturer-sponsored access programs; systematic literature compilation is supporting regulatory submissions for formal indication expansion.
- Postoperative Pain Relief:Acute surgical recovery protocols incorporate multimodal analgesia with device-based components.
- Cancer Pain Control:Palliative care integration of intrathecal drug delivery addresses opioid tolerance and systemic side effects.
Chronic pain management absorbs the bulk of clinical trial investment; neuropathic pain treatment is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of implantable pulse generators and radiofrequency ablation hardware concentrates in established medtech corridors, while demand for opioid-free pain therapies expands fastest in markets with restrictive prescribing policies and mature reimbursement infrastructure for neuromodulation.
United States
Chronic pain prevalence exceeding 50 million adults and CMS national coverage determinations for spinal cord stimulation create the world's largest implantable neuromodulation market. FDA breakthrough device designation for closed-loop systems compresses regulatory timelines for qualifying manufacturers. The Minneapolis-St. Paul corridor hosts concentrated R&D operations for waveform algorithm development.
Germany
EU Medical Device Regulation post-market surveillance obligations mandate systematic registry data collection from implanting centers across Bavaria and Baden-Württemberg. The country's statutory health insurance system maintains favorable reimbursement for radiofrequency ablation procedures. High-volume pain clinics in Berlin and Munich are consolidating purchasing authority to negotiate data-sharing agreements with device vendors.
India
The PLI scheme for medical electronics offers 5-20% incentive on incremental sales for domestic production of neurostimulation hardware. CDSCO regulatory harmonization with IMDRF standards is accelerating market entry timelines for multinational manufacturers. Manufacturing corridors in Maharashtra and Karnataka are attracting contract assembly operations for transcutaneous electrical nerve stimulators.
United Kingdom
National Health Service integrated care boards are prioritizing neurostimulation coverage for chronic lower back pain under value-based procurement frameworks. NICE technology appraisals for spinal cord stimulators condition regional commissioning decisions. Specialist pain centers in London and Manchester are piloting remote monitoring reimbursement pathways for home-based device programming.
Japan
PMDA's Sakigake designation system provides prioritized consultation for innovative neuromodulation systems, reducing total review time by approximately 50%. METI's healthcare technology assessment framework is expanding reimbursement for paresthesia-free burst waveform protocols. The Kansai region's medical device cluster around Osaka supports precision manufacturing of implantable leads and electrodes.
Pain Management Devices Market Key Industry Players
Top-tier vendors anchor the implantable neuromodulation segment, while mid-scale specialists and regional contract manufacturers populate the transcutaneous and disposable electrode tiers. Market structure reflects pronounced R&D intensity barriers in closed-loop algorithm development alongside commoditized pricing in surface stimulation hardware. Strategic archetypes include integrated neuromodulation platforms with captive remote monitoring ecosystems, procedural device specialists focused on radiofrequency ablation consumables, and diversified medtech conglomerates leveraging hospital supply chain relationships. Dominant competitive moves encompass strategic partnerships for EMR integration capabilities and geographic licensing arrangements for waveform intellectual property.
Among diversified medtech conglomerates, Medtronic, Boston Scientific Corporation, and Abbott exemplify distinct competitive positioning archetypes. Medtronic represents the integrated platform model with proprietary remote monitoring infrastructure. Boston Scientific Corporation occupies a position emphasizing algorithmic R&D investment in adaptive stimulation systems. Abbott exemplifies differentiation through proprietary waveform technology that creates defensible clinical positioning. Each anchors a distinct approach to sustaining recurring revenue streams across installed device bases.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott |
| Stryker |
| Baxter International |
| B Braun Melsungen AG |
| Nevro Corp |
| LivaNova |
| ICU Medical |
| Others |
Cost & Logistics Intelligence
Closed-loop algorithm development is concentrating manufacturing investment in United States and German R&D corridors while simultaneously elevating firmware engineering costs as a share of total device economics. This technology transition compresses margin structures for manufacturers lacking captive waveform IP, forcing supply chain reconfigurations toward software-capable contract partners.
Pricing Analysis
Price erosion across transcutaneous electrical nerve stimulators traces to direct-to-consumer channel saturation by unbranded Asian manufacturers. The market operates on a three-tier pricing structure across premium implantable neuromodulation systems, standard radiofrequency ablation platforms, and economy transcutaneous devices. Premium tiers command defensible positioning through FDA breakthrough device designation and proprietary burst waveform protocols, while hospital procurement committees unbundle device acquisition from service contracts. Academic medical centers exhibit lowest price sensitivity due to reimbursement coverage under CMS national coverage determinations; retail consumers drive commoditization pressure.
Supply Chain Analysis
Freight cost volatility from East Asian lithium-ion cell manufacturers is elevating working capital requirements for implantable pulse generator assembly. Supply concentrates in China for rechargeable battery cells, Malaysia for sterile lead manufacturing, and Ireland for European distribution hub operations. Raw material dependencies span lithium cobalt oxide cathodes, platinum-iridium electrode alloys, and biocompatible silicone elastomers. Single-source vulnerability in East Asian contract cell production creates tariff exposure risk. Distribution runs through hospital supply chains and specialized medical device distributors to ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Implantable neurostimulation hardware faces supply constraints from biomedical engineer talent scarcity, propping pricing power for manufacturers with captive firmware development capabilities.
For Market Incumbents: Cement algorithmic differentiation through closed-loop waveform IP acquisition before predicate-dependent competitors secure FDA breakthrough device designation. Defensive consolidation should target remote monitoring platform vendors to prevent third-party disintermediation of recurring revenue streams. Capacity addition in India's PLI scheme corridors secures cost position against East Asian battery supply concentration. For New Entrants and Emerging Players: The EU Medical Device Regulation's post-market surveillance obligations in Germany and France open a window for registry data analytics specialists to enter as service-layer vendors. White-space targets include telehealth-integrated remote programming for rural United States pain practices and disposable electrode consumables for Texas and Florida outpatient surgical centers. A hospital EMR integration-first go-to-market angle bypasses incumbent service contract lock-in. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified medtech conglomerates seeking neuromodulation platform completeness. The five-to-ten year viability window favors targets with proprietary waveform algorithms and installed base scale above ten thousand active devices. The signal to watch is CMS national coverage determination expansion for diabetic peripheral neuropathy indications as inflection indicator for addressable market growth.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Compresses premarket review timelines for closed-loop spinal cord stimulation systems to ninety days. |
| Hospital System Partnership | Unlocks purchasing committee access and unbundles device acquisition from long-term service contracts. |
| Software Companion Development | Enables remote patient monitoring reimbursement under CMS national coverage determinations. |
| CE Marking Pathway | Mandates systematic registry data collection under EU Medical Device Regulation post-market surveillance. |
| Reimbursement Strategy | Secures Medicare Advantage prior authorization flexibility for home-based spinal cord stimulator programming. |
Research Approach
FDA 510(k) filings, CMS Medicare reimbursement databases, and EU Medical Device Regulation certificate registries formed the secondary backbone for market sizing validation. Primary interviews with pain management clinicians, hospital purchasing committee members, biomedical engineers at implantable device manufacturers, and GPO contracts managers supplied forward-looking demand signals. Bottom-up and top-down triangulation cross-validated volume estimates against installed base replacement cycles and procedural throughput data from ambulatory surgical centers.
Bottom-up modeling segmented the market by product type, end user setting, technology modality, and pain etiology application across the projection horizon. Analytical frameworks incorporated rechargeable battery replacement cycles, trial-to-permanent conversion rates for spinal cord stimulators, and disposable electrode utilization per radiofrequency ablation procedure. CAGRs derived from regression analysis of historical implant volumes against chronic pain prevalence and reimbursement policy shifts.
The model assumes a particular technology adoption path for closed-loop neuromodulation systems; alternative pathways for fixed-parameter hardware retention would alter the outlook. Forecasts reflect assumptions regarding FDA breakthrough device designation expansion and CMS coverage determination stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pain Management
Cold Pain Therapy Market
Pain Management
Cancer Pain Management Market
Pain Management
Central Pain Syndrome Management Market
Pain Management
Axial Spondyloarthritis Management Market
Pain Management
Asia-Pacific Chronic Disease Management Market
Pain Management
Pain Relief Oil Market
Pain Management
Companion Animal Postoperative Pain Management Therapeutics Market
Pain Management
Pain Therapeutic Solutions Market
Pain Management
Global Fibromyalgia Treatment Market
Pain Management
Medical Morphine Market
Pain Management
Global Chiropractic Care Market
Pain Management
Global Postoperative Pain Management Market
Pain Management
Topical Pain Relief Cream Market
Pain Management
Opioid Induced Side Effects Treatment Market
Pain Management
Asia-Pacific Tattoo Numbing Cream Market
Pain Management
Pain Patches Market