
 Global Radiofrequency Ablation Devices Market | 2026-2036
Global Radiofrequency Ablation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Radiofrequency Ablation Devices Market Foresight
Aftermarket service revenue is tilting from capital equipment sales toward disposable catheter and electrode replacement cycles. Medtronic leverages its integrated electrophysiology ecosystem to capture recurring consumable spend. Boston Scientific Corporation anchors its position through specialized mapping and ablation catheter portfolios. Abbott differentiates via temperature-controlled RF platforms that command premium positioning in cardiac rhythm management.
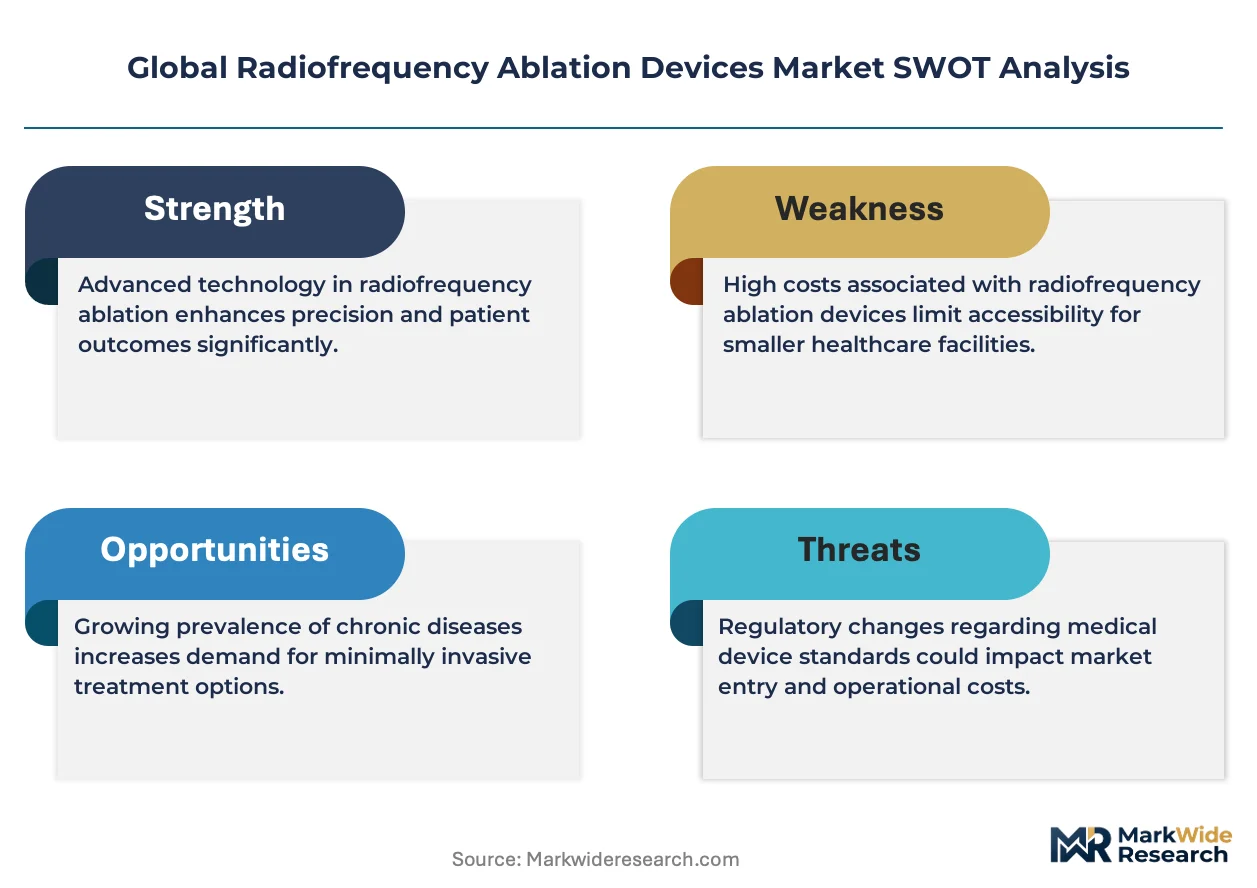
Radiofrequency ablation devices generate thermal energy via alternating current at frequencies between 300 kHz and 500 kHz to induce controlled tissue necrosis through resistive heating. These systems serve primarily to treat cardiac arrhythmias, oncologic lesions, and chronic pain syndromes through percutaneous or intraoperative delivery. Monopolar configurations dominate procedural volumes due to established clinical protocols and broader physician training, while multipolar arrays represent the fastest-expanding segment in oncology applications where larger ablation zones reduce retreatment rates. Temperature-controlled technology commands the highest installed base, though pulsed radiofrequency systems are gaining traction in pain management for their non-destructive neuromodulation capabilities.
The FDA, EMA, and Japan's PMDA each enforce distinct biocompatibility and electromagnetic compatibility standards that fragment product registration requirements across major markets. ISO 14155 clinical investigation protocols and the EU MDR's heightened post-market surveillance obligations are extending development timelines and compliance costs for manufacturers. Stakeholders must monitor evolving reimbursement determinations from CMS and parallel agencies in Germany and Japan, as these decisions directly shape hospital capital allocation and procedural adoption curves for advanced ablation modalities.
Market Dynamics
Disposable catheter economics are restructuring revenue flows across the radiofrequency ablation device ecosystem, tilting manufacturer priorities from capital equipment placement toward recurring consumable attachment rates and long-term account penetration.
Growth Catalysts
- Atrial Fibrillation Procedure Expansion:Tertiary hospital cardiology departments are scaling catheter-based ablation programs. United States, Germany, and Japan reimbursement alignment supports sustained procedural volume expansion.
- EU MDR Post-Market Surveillance:Heightened clinical evidence requirements are accelerating consolidation among manufacturers with robust quality management systems. Compliance-ready firms capture displaced competitor share.
- Pulsed Radiofrequency Neuromodulation:Non-destructive thermal protocols are extending RF device utility into chronic pain management. Pain clinics represent an emerging high-frequency utilization segment.
Market Restraints
- Biocompatibility Testing Cost Escalation:ISO 10993 cytotoxicity and sensitization studies for novel electrode materials impose six-figure validation burdens. Early-stage developers face capital access constraints.
- Supply Concentration in Precision RF Generators:High-frequency power electronics manufacturing clusters in Germany and Japan create geographic vulnerability. Single-source dependencies amplify disruption risk.
- Electromagnetic Interference Limitations:Monopolar configurations generate stray current artifacts requiring extensive shielding. Operating room retrofit costs deter community hospital adoption.
Strategic Opportunities
- India Electrosurgery Infrastructure Buildout:Government hospital modernization programs under Ayushman Bharat create tender opportunities. Price-sensitive procurement favors localized manufacturing partnerships.
- Multipolar Oncology Arrays:Larger ablation zone coverage reduces hepatocellular carcinoma retreatment rates. Interventional radiology suites represent an underpenetrated deployment setting.
- Japan PMDA Sakigake Designation:Expedited review pathways for breakthrough therapeutic devices compress registration timelines. First-mover advantage accrues to firms with established Tokyo clinical investigator networks.
Industry Challenges
- Electrophysiology Fellowship Training Bottlenecks:Complex three-dimensional mapping and ablation workflows require 2-3 year subspecialization. Academic medical center capacity constraints limit qualified operator supply.
- Legacy Capital Equipment Integration:New catheter generations must maintain backward compatibility with installed RF generator bases. Firmware interoperability testing extends product release cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Radiofrequency Ablation Devices Market |
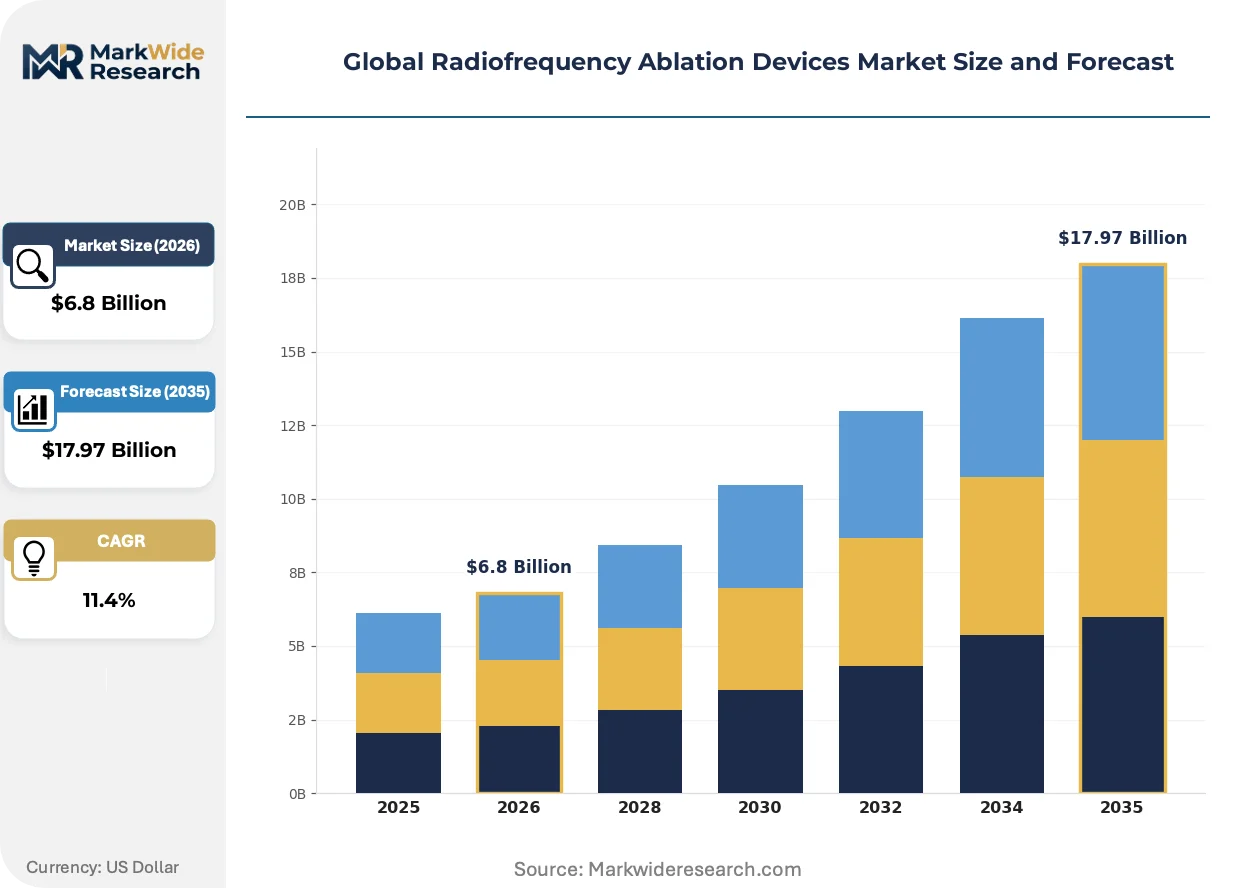
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monopolar, Bipolar, Multipolar, Single Electrode, Multi-Electrode, Combination Application: Cardiology, Pain Management, Oncology, Dermatology, Urology, Neurology End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Diagnostic Centers, Research Institutes Technology: Temperature-Controlled, Impedance-Controlled, Power-Controlled, Bipolar Energy, Pulsed Radiofrequency |
| Companies Covered | Medtronic, Boston Scientific Corporation, Abbott, Johnson & Johnson, Stryker, AtriCure, Inc., Avanos Medical, Inc., AngioDynamics, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Radiofrequency Ablation Devices Market Shifts & Advancements
Temperature-controlled RF platforms are yielding to next-generation energy delivery modalities, while regulatory frameworks and procurement behaviors undergo parallel recalibration across major markets.
Radiofrequency ablation systems are migrating from continuous thermal delivery toward pulsed energy protocols that modulate tissue heating without irreversible neuronal damage. Pain management specialists in the United States and Germany are adopting these platforms for chronic neuropathic conditions. The technology is migrating from destructive lesion creation to reversible neuromodulation, expanding addressable indications beyond traditional ablation boundaries.
Japan's PMDA has tightened electromagnetic compatibility certification requirements for implantable RF electrodes under revised ministerial ordinances. Manufacturers must now submit comprehensive shielding effectiveness data and clinical electromagnetic interference assessments. Cardiac rhythm management device suppliers with Tokyo-based regulatory affairs teams are accelerating compliance investments to maintain market access.
Hospital procurement committees are unbundling capital equipment acquisitions from multi-year catheter supply agreements. United States health systems now favor modular purchasing with competitive re-sourcing clauses at 18-month intervals. This restructuring compresses manufacturer contract tenures and elevates price transparency as a decisive vendor selection criterion.
Global Radiofrequency Ablation Devices Market Segmentation
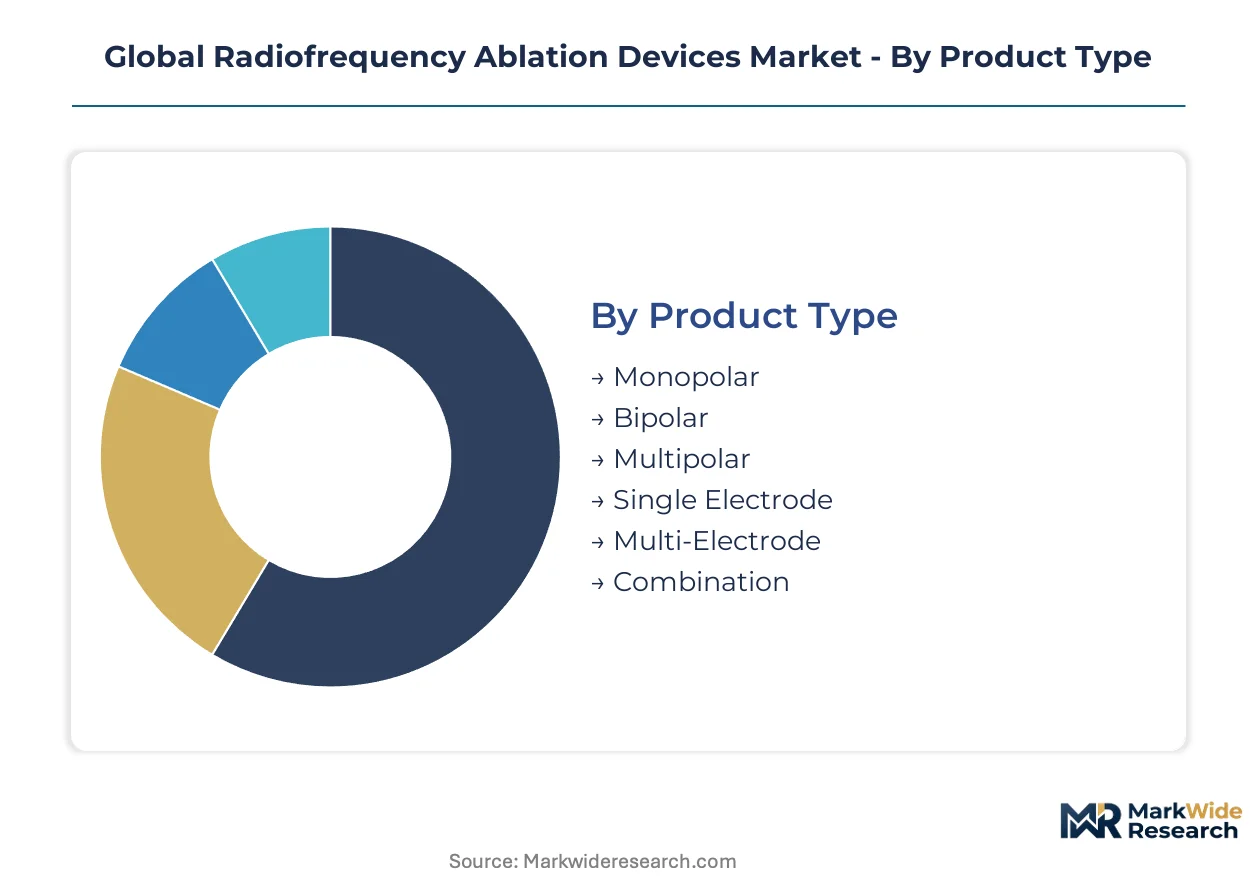
Radiofrequency ablation device segmentation reflects divergent clinical workflows across cardiac rhythm management, interventional oncology, and chronic pain protocols. Each dimension—electrode configuration, therapeutic application, care setting, and energy modulation—carries distinct reimbursement codes, regulatory pathways, and capital intensity requirements that reshape vendor go-to-market strategies.
Product Type:
Mature monopolar platforms anchor procedural volumes in tertiary hospitals, while emerging multipolar arrays redefine ablation zone economics in interventional radiology.
- Monopolar:Single active electrode with large dispersive return pad generates concentrated thermal lesions through resistive heating. Demand concentrates in United States cardiac electrophysiology labs where established catheter protocols and physician training sustain high utilization rates despite electromagnetic interference shielding requirements.
- Multipolar:Arrays of active electrodes create overlapping thermal zones without repositioning, reducing hepatocellular carcinoma retreatment rates. Interventional radiology suites in Germany and Japan are adopting these configurations for larger tumor volumes, though capital equipment costs exceed monopolar baselines.
- Bipolar:Current flows between paired electrodes on the same device, eliminating return pad requirements and reducing stray current artifacts.
- Single Electrode:Standard configuration for percutaneous pain management and small-volume cardiac ablations.
- Multi-Electrode:Clustered probe designs enable simultaneous multi-site activation for complex arrhythmia substrates.
- Combination:Modular systems supporting electrode interchangeability across monopolar, bipolar, and multipolar modes.
Monopolar configurations retain volume leadership; multipolar arrays hold the steepest expansion curve.
Application:
Application segmentation tracks reimbursement alignment and procedural complexity gradients across therapeutic specialties.
- Cardiology:Catheter-based atrial fibrillation ablation consumes the largest device volumes, with Medicare severity-adjusted DRG codes supporting hospital capital recovery. Tertiary centers in the United States, Germany, and Japan are expanding electrophysiology suite capacity to address aging demographic demand.
- Pain Management:Chronic neuropathic conditions drive adoption of pulsed radiofrequency protocols that modulate nociceptive signaling without neuronal destruction. Pain clinics in the United States and Germany represent high-frequency utilization segments with shorter procedure times than surgical interventions.
- Oncology:Percutaneous tumor ablation for hepatocellular carcinoma and renal cell carcinoma leverages imaging-guided electrode placement.
- Dermatology:Aesthetic and lesion removal applications utilize lower-power RF systems with superficial penetration depths.
- Urology:Benign prostatic hyperplasia and renal mass applications require specialized electrode geometries.
- Neurology:Movement disorder and epilepsy applications remain investigational with limited commercial device availability.
Cardiology commands installed base dominance; pain management applications are climbing the fastest.
End User:
End user segmentation reveals divergent procurement authority and capital allocation timelines across care delivery settings.
- Hospitals:Integrated delivery networks in the United States and university hospitals in Germany control the majority of RF generator installed bases. These institutions negotiate multi-year catheter supply agreements with competitive re-sourcing clauses at 18-month intervals, compressing manufacturer contract tenures.
- Ambulatory Surgical Centers:Freestanding facilities in the United States are expanding cardiac and pain management service lines under Medicare ASC payment reforms. Lower overhead structures support favorable per-procedure economics for high-volume ablation specialists.
- Specialty Clinics:Dedicated pain management and cardiology practices concentrate in metropolitan markets with dense specialist populations.
- Diagnostic Centers:Imaging-equipped facilities provide ablation planning and post-procedure surveillance without therapeutic device ownership.
- Research Institutes:Academic medical centers in Japan and Germany conduct clinical investigations under ISO 14155 protocols and EU MDR post-market surveillance frameworks.
Hospitals retain capital equipment concentration; ambulatory surgical centers are gaining share fastest.
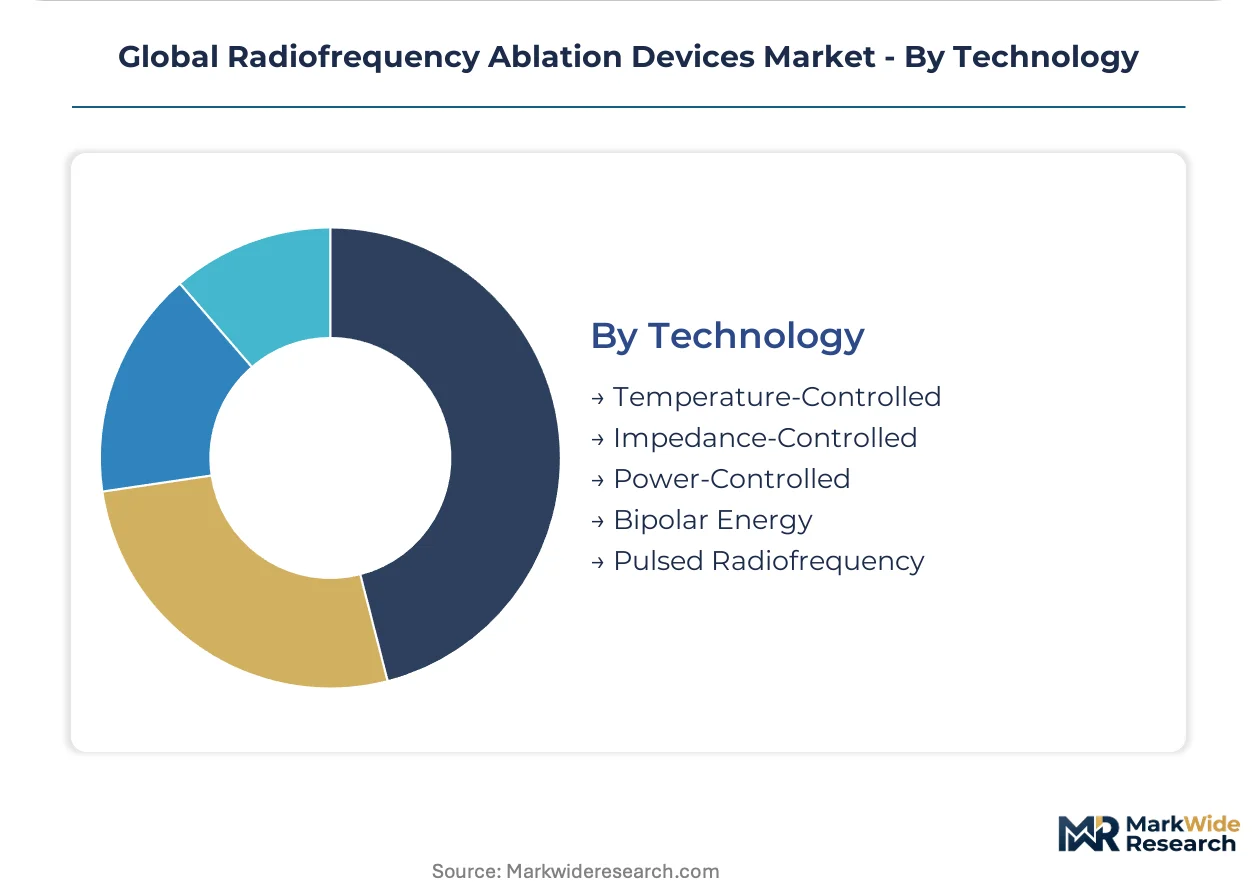
Technology:
Technology segmentation tracks the shift from continuous thermal delivery toward modulated energy protocols with expanded indication boundaries.
- Temperature-Controlled:Closed-loop feedback systems maintain target tissue temperatures through automated power adjustment, commanding premium positioning in cardiac rhythm management. These platforms hold the largest installed base across United States electrophysiology labs.
- Pulsed Radiofrequency:Intermittent energy delivery with cooling intervals enables neuromodulation without irreversible tissue destruction. Pain management specialists in Germany and the United States are adopting these systems for chronic neuropathic conditions previously resistant to conventional ablation.
- Impedance-Controlled:Tissue resistance monitoring determines endpoint criteria, common in oncology applications.
- Power-Controlled:Fixed wattage delivery with operator-determined duration, standard in legacy cardiac systems.
- Bipolar Energy:Confined current pathways reduce collateral thermal damage in sensitive anatomical regions.
Temperature-controlled platforms retain installed base leadership; pulsed radiofrequency systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major markets. The United States prioritizes cardiac electrophysiology with high procedural volumes, Germany emphasizes oncology applications with multipolar arrays, and Japan concentrates on neuromodulation and pain management protocols.
United States
Medicare severity-adjusted DRG codes sustain hospital capital recovery for atrial fibrillation ablation programs. The FDA's evolving 510(k) clearance pathways compress product development timelines for minimally invasive therapeutic devices. Tertiary centers in Cleveland Clinic and Mayo Clinic networks are expanding electrophysiology suite capacity to address aging demographic demand.
Germany
University hospitals prioritize interventional radiology suites for hepatocellular carcinoma retreatment reduction using multipolar configurations. The EU MDR's heightened post-market surveillance obligations extend compliance timelines but accelerate consolidation among quality-ready manufacturers. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia concentrate precision RF generator manufacturing capabilities.
Japan
Pain clinics adopt pulsed radiofrequency protocols for chronic neuropathic conditions resistant to conventional ablation. The PMDA's Sakigake designation expedites review pathways for breakthrough therapeutic devices. Tokyo-based clinical investigator networks provide first-mover advantage access for compliance-invested cardiac rhythm management suppliers.
India
Government hospital modernization programs under Ayushman Bharat create tender opportunities for price-sensitive procurement. The CDSCO enforces biocompatibility standards aligned with ISO 10993 protocols for novel electrode materials. Localized manufacturing partnerships in Maharashtra and Gujarat serve emerging electrosurgery infrastructure buildout.
United Kingdom
NHS Integrated Care Systems negotiate modular purchasing with competitive re-sourcing clauses at 18-month intervals. The MHRA operates post-Brexit regulatory frameworks with transitional alignment to EU MDR surveillance obligations. London and Southeast England academic medical centers conduct ISO 14155 clinical investigations under extended development timelines.
Global Radiofrequency Ablation Devices Market Competitive Landscape
Capability concentration sits with integrated electrophysiology ecosystem providers; scale advantage sits with diversified medical technology conglomerates. The vendor base structures across three tiers: premium-positioned temperature-controlled platform suppliers, mid-tier disposable catheter specialists, and emerging regional fabricators. Two strategic archetypes dominate competitive positioning: ecosystem-integrated players capturing recurring consumable attachment rates, and mapping-technology specialists anchoring specialized catheter portfolios. Consolidation accelerates through strategic partnerships for regulatory compliance readiness and geographic expansion into government tender markets.
Within the ecosystem-integrated tier, Medtronic and Boston Scientific Corporation occupy positions defined by recurring revenue capture from disposable catheter replacement cycles. Abbott anchors the premium-technology vector through temperature-controlled RF platform positioning. These three entities exemplify divergent strategic postures: consumable-driven account penetration, specialized mapping portfolio depth, and premium cardiac rhythm management differentiation respectively.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| Abbott |
| Johnson & Johnson |
| Stryker |
| AtriCure, Inc. |
| Avanos Medical, Inc. |
| AngioDynamics |
| Olympus Corporation |
| Others |
Supply & Pricing Matrix
Trans-Pacific freight corridors connecting precision electronics manufacturing clusters in Baden-Württemberg and Tokyo to United States distribution hubs impose variable logistics cost burdens that amplify price stratification between temperature-controlled premium platforms and standard monopolar systems. These corridor dynamics concentrate pricing power with RF generator manufacturers possessing captive supply chain control over high-frequency power electronics, while forcing price-sensitive procurement committees in Indian government hospitals toward localized assembly partnerships.
Pricing Analysis
Long-term catheter supply agreements with competitive re-sourcing clauses at 18-month intervals dominate hospital procurement, though ambulatory surgical centers increasingly favor spot purchasing for disposable electrodes. Price differentiation separates FDA-cleared temperature-controlled platforms from CE-marked standard systems and economy-tier unipolar pain management devices. Pricing pressure stems from unbundling of capital equipment from consumable contracts, compressing manufacturer margins on generator placements. Community hospitals exhibit highest price sensitivity due to capital budget constraints, while tertiary electrophysiology labs prioritize clinical performance over unit cost.
Supply Chain Analysis
Export control regimes restricting high-frequency semiconductor shipments to Chinese medical device assemblers fragment component sourcing strategies for RF generator manufacturers. Precision power electronics concentrate in Germany, Japan, and the United States, with specialized electrode materials drawing from platinum-iridium suppliers in South Africa and nickel-titanium shape-memory alloy producers in Japan. Single-source vulnerability in ceramic capacitor feedstock creates disruption risk for pulsed radiofrequency system production. Distribution runs through hospital procurement committees and group purchasing organizations in developed markets, with direct government tender channels dominating emerging economy access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Radiofrequency Ablation Devices Market is recovering from procedural volume suppression as aging demographics in developed economies drive sustained atrial fibrillation treatment demand. Elective procedure backlogs and catheter inventory replenishment cycles reinforce this cyclical upswing.
For Market Incumbents: Build regulatory compliance moats through accelerated EU MDR technical documentation investments and Tokyo-based PMDA Sakigake pathway positioning. Consolidate displaced competitor share by acquiring quality-system-ready catheter specialists facing capital access constraints from ISO 10993 testing cost escalation. Defend against pulsed radiofrequency neuromodulation substitution by embedding temperature-controlled platforms into integrated electrophysiology ecosystem workflows.
For New Entrants and Emerging Players: Government hospital modernization programs under India's Ayushman Bharat scheme represent the most penetrable geographic entry point, with price-sensitive tender procurement favoring localized manufacturing partnerships. Target multipolar oncology arrays for hepatocellular carcinoma applications in German interventional radiology suites, where retreatment reduction economics justify premium positioning. Establish go-to-market presence through distributor relationships with established electrosurgery equipment channels rather than direct hospital sales force buildout.
For Investors and Strategic Acquirers: Disposable catheter specialists with robust quality management systems and established Tokyo clinical investigator networks present optimal acquisition targets for platform expansion. Long-term viability hinges on recurring consumable attachment rates rather than capital equipment placement velocity. Monitor FDA 510(k) clearance pathway evolution for minimally invasive therapeutic devices as the primary inflection signal; accelerated review timelines would compress development cycle returns and favor compliance-ready incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compresses product development timelines for catheter-based atrial fibrillation platforms in United States tertiary centers. |
| EU MDR Technical Documentation Investment | Captures displaced competitor share through post-market surveillance compliance readiness in German hospital networks. |
| Tokyo Clinical Investigator Network Expansion | Secures PMDA Sakigake designation access for breakthrough neuromodulation device priority review. |
| Localized Manufacturing Partnership | Addresses price-sensitive procurement under India's Ayushman Bharat government hospital modernization tenders. |
| Disposable Catheter Supply Agreement Restructuring | Aligns with unbundled procurement committee preferences for 18-month competitive re-sourcing clauses. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with electrophysiologists, hospital purchasing committee members, biomedical engineers, and group purchasing organization contracts managers; and secondary validation through FDA 510(k) clearance databases, PMDA approval registries, CMS Medicare DRG reimbursement schedules, and EU MDR notified body technical documentation filings. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Forecast inputs incorporated procedural volume trajectories, catheter replacement cycle frequencies, and capital equipment depreciation schedules across temperature-controlled, pulsed radiofrequency, and impedance-controlled technology modalities. Segmentation dimensions spanned electrode configuration, therapeutic application, care setting, and energy modulation protocol. CAGRs derived from logarithmic trend fitting across the projection horizon, with sensitivity testing against reimbursement determination timelines and regulatory pathway velocity assumptions.
Practitioners should monitor FDA 510(k) pathway evolution, EU MDR post-market surveillance enforcement intensity, and Japanese PMDA electromagnetic compatibility ordinance revisions for early signals requiring forecast recalibration. Material shifts in Medicare severity-adjusted DRG reimbursement alignment or catheter supply agreement unbundling velocity would require updated modeling.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pressure Ulcer Devices Market
Medical Devices
Infusion Management Market
Medical Devices
Bone Fixation Plates Market
Medical Devices
Implantable Neurostimulators Market
Medical Devices
Implant-Borne Prosthetics Market
Medical Devices
Americas Wearable Medical Device Market
Medical Devices
Manometry System Market
Medical Devices
Global Angioplasty Balloons Market
Medical Devices
India Static Compression Therapy Market
Medical Devices
Global Medical Device Security Market
Medical Devices
Italy Drug Delivery Devices Market
Medical Devices
Mexico Aesthetic Devices Market
Medical Devices
Smart Pill Boxes and Bottles Market
Medical Devices
Neurointerventional Devices Market
Medical Devices
Wheelchair and Components Market
Medical Devices
Asia-Pacific Electroencephalography Devices Market