
 Pituitary Cancer Market | 2026-2036
Pituitary Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Pituitary Cancer Market Analytics
North American oncology infrastructure is reshaping competitive dynamics in pituitary cancer care. Novartis AG leverages its radioligand therapy platform to anchor presence in peptide receptor treatments. Pfizer Inc. sustains R&D intensity through targeted small-molecule programs against aggressive pituitary carcinomas. Merck & Co., Inc. competes via immuno-oncology pipelines exploring checkpoint inhibition in refractory cases.
Pituitary cancer comprises malignant neoplasms arising from the pituitary gland, typically classified as pituitary carcinomas or aggressive pituitary adenomas, with diagnosis requiring histopathological confirmation of metastatic spread or extensive local invasion beyond the sella turcica. These tumors disrupt hypothalamic-pituitary axis function, causing hormonal dysregulation, mass effect symptoms, and visual pathway compression that necessitate multidisciplinary management. Surgery dominates initial intervention, with transsphenoidal resection representing the standard of care for accessible lesions, while radiation therapy captures expanding utility in adjuvant settings where complete excision proves unfeasible. Immunotherapy represents the fastest-evolving segment, though hormonal imbalance management retains the deepest margin pool through chronic pharmacologic replacement and suppression protocols.
FDA orphan drug designation frameworks and EMA rare disease pathways shape clinical trial incentives and accelerated review timelines for pituitary carcinoma therapeutics. The EPA governs radioactive isotope handling in radiopharmaceutical manufacturing, constraining production site licensing and supply security for ligand-based treatments. Stakeholders must monitor evolving reimbursement policies for combination therapy regimens and radiopharmaceutical administration as treatment paradigms shift toward precision-targeted approaches.
Market Dynamics
FDA orphan drug designation frameworks are accelerating therapeutic pipelines for pituitary carcinoma, while radioligand manufacturing constraints around isotope supply security reshape competitive positioning across North American oncology networks.
Growth Catalysts
- Orphan Drug Incentives:FDA tax credits and market exclusivity provisions compress clinical trial timelines for rare neuroendocrine malignancies, drawing venture capital into pituitary carcinoma drug development.
- Neuro-Oncology Infrastructure:United States metropolitan hospital networks are establishing dedicated pituitary tumor protocols, creating referral concentration that sustains procedure volumes and specialist training pipelines.
- Radioligand Platform Expansion:Peptide receptor radionuclide therapy manufacturing capabilities are scaling across EPA-licensed production sites, securing supply chains for targeted alpha- and beta-emitter treatments.
Market Restraints
- Isotope Supply Concentration:Molybdenum-99 and lutetium-177 production clusters in Canada and European reactors create single-point-of-failure vulnerability for radiopharmaceutical availability.
- Diagnostic Cost Burden:PET-CT imaging with gallium-68 DOTATATE requires capital-intensive cyclotron infrastructure, limiting patient access outside major academic medical centers.
- Pathological Confirmation Barriers:Distinguishing aggressive pituitary adenoma from carcinoma demands specialized neuropathology expertise that concentrates in tertiary referral centers, delaying definitive diagnosis.
Strategic Opportunities
- Checkpoint Inhibition Protocols:Immuno-oncology combinations exploring PD-1/PD-L1 blockade in refractory pituitary carcinoma represent unlabeled indication expansion with accelerated approval pathway potential.
- Telemedicine Integration:Remote endocrinology consultation platforms are extending hormonal management follow-up to rural and underserved regions, decoupling chronic care from surgical center geography.
- Biomarker-Guided Segmentation:Somatic mutation profiling and Ki-67 proliferation indices are enabling risk-stratified treatment algorithms that differentiate surveillance intensity and adjuvant therapy selection.
Industry Challenges
- Skull Base Surgical Workforce:Fellowship-trained transsphenoidal surgeons concentrate in coastal United States academic institutions, creating access inequities for patients in interior states requiring complex resection.
- Reimbursement Fragmentation:Radiopharmaceutical administration coding separates isotope cost from technical fees, complicating bundled payment negotiations and site-of-service economics for hospital outpatient departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pituitary Cancer Market |
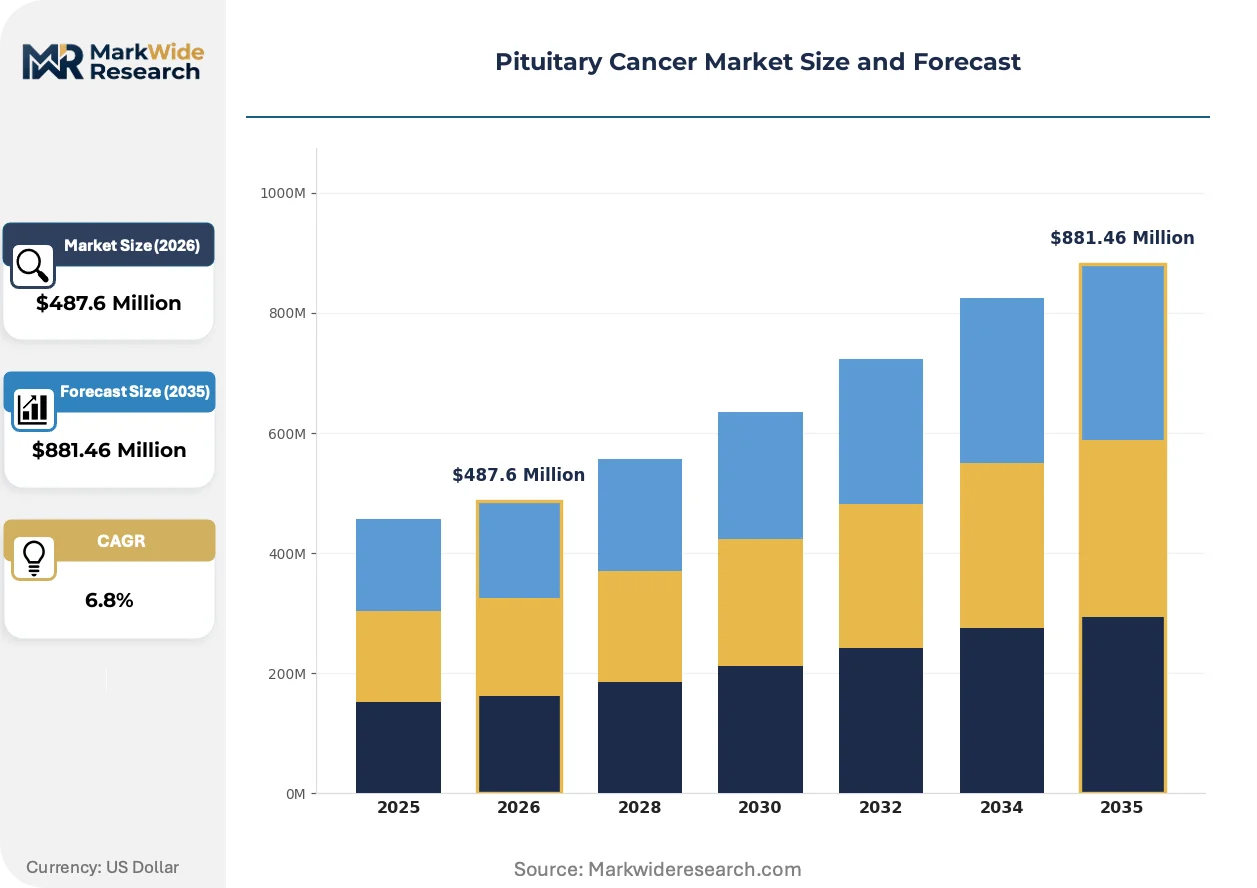
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgery, Radiation Therapy, Chemotherapy, Immunotherapy End User: Hospitals, Oncology Centers, Research Institutions, Ambulatory Surgical Centers Therapy Area: Adrenocorticotropic Hormone Excess, Growth Hormone Deficiency, Visual Disturbances, Hormonal Imbalance Treatment Stage: Diagnostic, Active Treatment, Remission, Follow-Up Care |
| Companies Covered | Novartis AG, Pfizer Inc., Merck & Co., Inc., Ipsen Biopharmaceuticals Inc., Bristol-Myers Squibb Company, Eli Lilly and Company, AstraZeneca PLC, Crinetics Pharmaceuticals, Corcept Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pituitary Cancer Market Evolving Landscape
Precision-targeted radiotherapy and molecular diagnostics are compressing treatment paradigms, while regulatory incentives and care delivery reconfiguration accelerate adoption curves across neuro-oncology networks.
Next-generation sequencing panels detecting AIP, MEN1, and PRKAR1A mutations are rendering obsolete empirical hormonal suppression protocols that treated all functional adenomas identically. Endocrinology practices at Cleveland Clinic and MD Anderson are integrating somatic profiling into initial workup, compressing time to targeted therapy selection. Molecular stratification is enabling enrollment into genotype-matched clinical trials that were previously inaccessible to pituitary tumor patients.
EMA's Orphan Medicinal Product designation parallels FDA incentives, creating dual-approval pathway synergies for developers targeting aggressive pituitary neoplasms. European reference pricing mechanisms for radiopharmaceuticals are pressuring manufacturers to demonstrate incremental cost-effectiveness against conventional radiation modalities. German and French hospital networks are consolidating peptide receptor therapy administration into designated competence centers, concentrating volume and expertise.
Patient navigation programs are compressing multidisciplinary care coordination timelines, replacing serial specialist referrals with same-day endocrine surgery and radiation oncology consultation. United States cancer centers including Memorial Sloan Kettering and UCSF are implementing pituitary tumor boards with embedded genetic counseling, reducing time from imaging to treatment initiation. Value-based oncology models in Medicare Advantage contracts are rewarding episode-of-care efficiency metrics that favor integrated practice units over fragmented referral patterns.
Pituitary Cancer Market Segmentation
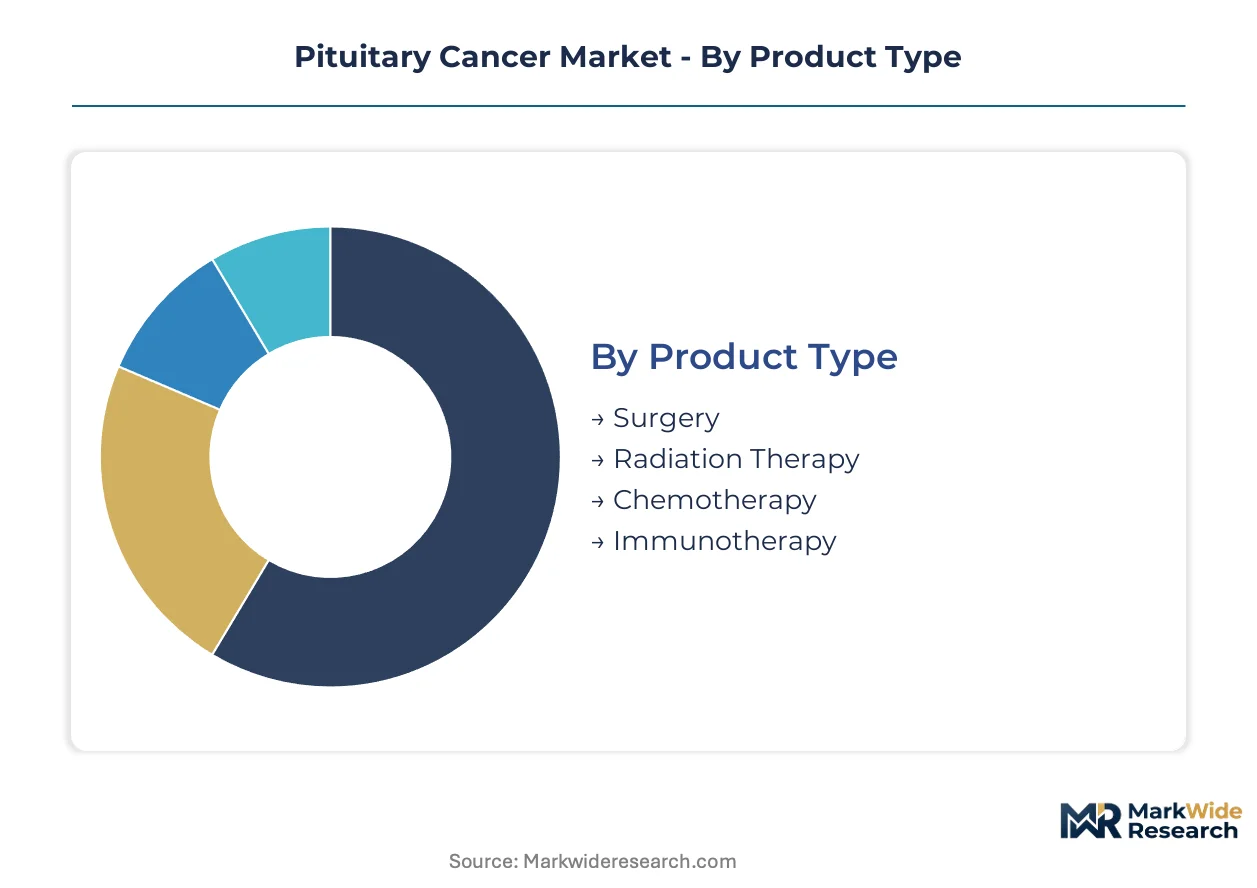
Pituitary cancer care requires precise patient stratification across treatment modalities and care settings. Segmentation reveals where capital deployment concentrates and which therapeutic categories command premium pricing.
Product Type:
After-sales service intensity varies sharply across modalities, with implantable devices and radiopharmaceuticals demanding specialized technical support that reshapes vendor selection criteria.
- Surgery:Transsphenoidal resection and transcranial approaches constitute the intervention backbone. Demand clusters in United States metropolitan hospital networks with fellowship-trained skull base programs. Reimbursement coding complexity and 90-day episode accountability create vendor stickiness for instrument maintenance contracts.
- Radiation Therapy:Stereotactic radiosurgery and fractionated radiotherapy target residual or recurrent disease. United States academic medical centers with Gamma Knife and CyberKnife installations capture referral volume from surrounding states. Linear accelerator uptime guarantees and physics support contracts differentiate equipment suppliers.
- Chemotherapy:Systemic agents address metastatic pituitary carcinoma with limited efficacy profiles.
- Immunotherapy:Checkpoint inhibitors and targeted biologics represent emerging protocols for refractory cases.
By volume, Surgery leads. By growth pace, Immunotherapy is ahead.
End User:
Cost tier stratification separates capital-intensive inpatient facilities from outpatient settings where procedure economics favor lower acuity interventions.
- Hospitals:Tertiary centers with dedicated neurosurgery and endocrinology departments manage complex resections and hormonal emergencies. United States coastal academic institutions concentrate transsphenoidal expertise. Emergency department integration and 24-hour neurosurgical coverage justify premium reimbursement rates.
- Oncology Centers:Specialized facilities deliver radiation therapy and systemic treatment protocols. United States metropolitan networks with NCI-designated cancer center status attract out-of-region referrals. Clinical trial access and molecular tumor board infrastructure differentiate patient acquisition.
- Research Institutions:Academic medical centers conduct investigator-initiated trials and biomarker discovery.
- Ambulatory Surgical Centers:Outpatient settings handle select transsphenoidal cases with favorable anatomy and limited comorbidity.
By patient volume, Hospitals dominate. By margin expansion, Oncology Centers are climbing the fastest.
Therapy Area:
Application severity determines treatment urgency and specialist referral patterns, with life-threatening hormonal crises commanding immediate intervention resources.
- Adrenocorticotropic Hormone Excess:Cushing's disease manifestations from corticotroph tumors require urgent biochemical control. United States pituitary centers at Cleveland Clinic and MD Anderson prioritize ACTH-secreting adenomas for surgical scheduling. Cardiovascular complication risk and perioperative mortality drive aggressive management protocols.
- Growth Hormone Deficiency:Post-surgical hypopituitarism necessitates chronic hormone replacement. Pediatric endocrinology practices across United States children's hospitals manage longitudinal growth optimization. Recombinant hormone costs and injection training requirements sustain specialty pharmacy relationships.
- Visual Disturbances:Optic chiasm compression mandates rapid surgical decompression.
- Hormonal Imbalance:Panhypopituitarism and selective pituitary deficits require endocrine monitoring.
By clinical acuity, Adrenocorticotropic Hormone Excess leads. By chronic revenue stability, Growth Hormone Deficiency is expanding most quickly.
Treatment Stage:
Customer type transitions from acute intervention seekers to chronic disease managers, with lifetime value concentrating in long-term surveillance populations.
- Diagnostic:MRI with dedicated pituitary protocol and endocrine functional testing establishes tumor characterization. United States neuroradiology practices with subspecialty head-and-neck expertise improve microadenoma detection rates. Gadolinium contrast protocols and dynamic imaging sequences differentiate diagnostic accuracy.
- Active Treatment:Multimodal therapy combining surgery, radiation, and pharmacologic intervention addresses tumor burden. United States multidisciplinary pituitary tumor boards coordinate synchronous specialist consultation. Episode-of-care bundling in Medicare Advantage contracts rewards treatment initiation efficiency.
- Remission:Biochemical and radiographic surveillance confirms disease control.
- Follow-Up Care:Longitudinal endocrine replacement and recurrence monitoring extend patient relationships.
By immediate resource consumption, Active Treatment leads. By patient lifetime value, Follow-Up Care is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiopharmaceutical manufacturing clusters concentrate in select jurisdictions with EPA-licensed production infrastructure, while neuro-oncology referral networks expand across metropolitan hospital systems with dedicated pituitary tumor protocols.
United States
FDA orphan drug tax credits accelerate therapeutic development timelines for aggressive pituitary carcinomas, drawing venture capital into rare neuroendocrine malignancy programs. Memorial Sloan Kettering and MD Anderson anchor multidisciplinary pituitary tumor boards that compress time from imaging to treatment initiation. NCI-designated cancer centers in coastal metropolitan areas concentrate transsphenoidal surgical expertise and radioligand therapy administration.
Germany
EMA orphan medicinal product designation parallels FDA incentives, creating dual-approval pathway synergies for developers targeting refractory pituitary neoplasms. German hospital networks consolidate peptide receptor radionuclide therapy into designated competence centers, concentrating volume and expertise. The KBA regulates radioactive isotope transport, constraining distribution logistics for lutetium-177 based treatments across federal states.
Japan
PMDA accelerated review pathways for rare diseases compress regulatory timelines for pituitary carcinoma therapeutics, aligning with METI innovation promotion frameworks. Tokyo and Osaka metropolitan medical centers integrate somatic mutation profiling into initial pituitary tumor workup. Domestic production of gallium-68 generators remains limited, creating dependency on cyclotron infrastructure at select academic institutions.
Switzerland
Swissmedic maintains stringent radiopharmaceutical manufacturing standards that exceed baseline EMA requirements, favoring established producers with dedicated isotope handling capabilities. Basel and Zurich anchor pharmaceutical R&D clusters with radioligand therapy platform investments. The country's central European location positions it as a distribution hub for lutetium-177 supply chains serving adjacent markets.
United Kingdom
NHS England specialized commissioning frameworks concentrate pituitary tumor surgery in designated neurosurgical centers, creating referral concentration from peripheral regions. London academic medical centers lead investigator-initiated trials exploring checkpoint inhibition in refractory pituitary carcinoma. MHRA post-Brexit regulatory autonomy enables tailored approval pathways for orphan oncology indications.
Pituitary Cancer Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in radiopharmaceutical isotope supply and surgical instrumentation. The vendor base stratifies across three tiers: multinational pharmaceutical conglomerates with radioligand therapy platforms, mid-cap biotech firms with targeted small-molecule programs, and specialized neurosurgical device manufacturers. Dominant competitive moves include strategic partnerships securing isotope supply chains and portfolio diversification into peptide receptor radionuclide therapy manufacturing capabilities.
Among Swiss-based pharmaceutical conglomerates, Novartis AG anchors the radioligand therapy platform segment. Pfizer Inc. and Merck & Co., Inc. occupy positions within the immuno-oncology and targeted therapy archetypes, with the latter exploring checkpoint inhibition protocols. These three entities exemplify the scale-driven tier where FDA orphan drug incentives compress development timelines for rare neuroendocrine malignancies.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| Merck & Co., Inc. |
| Ipsen Biopharmaceuticals Inc. |
| Bristol-Myers Squibb Company |
| Eli Lilly and Company |
| AstraZeneca PLC |
| Crinetics Pharmaceuticals |
| Corcept Therapeutics |
| Others |
Value Network & Pricing Analysis
Basel and Zurich anchor radiopharmaceutical manufacturing clusters where Swissmedic licensing requirements create supply scarcity that sustains premium pricing for lutetium-177 based therapies. FDA orphan drug designation compresses development timelines for aggressive pituitary carcinomas, concentrating pricing power with developers who secure market exclusivity provisions.
Pricing Analysis
FDA reimbursement coding frameworks dictate the pricing tier structure for pituitary cancer therapeutics, separating radiopharmaceutical isotope costs from technical administration fees. Pricing stratifies across academic medical center premium tiers, community hospital standard tiers, and outpatient clinic economy tiers based on cyclotron proximity and neurosurgical case volume. Cost compression in community hospital tiers is intensifying because PET-CT infrastructure requirements limit patient access outside metropolitan referral networks. Oncology centers with NCI designation exhibit lowest price sensitivity due to clinical trial revenue offsets, while rural ambulatory surgical centers face acute margin pressure from travel reimbursement gaps.
Supply Chain Analysis
Export controls on high-enriched uranium and medical isotope technology limit molybdenum-99 flows from Canadian NRU-derived production to United States radiopharmaceutical manufacturers. Supply concentrates in Ontario reactor facilities, South African Safari-1, and European HFR Petten, with raw material dependencies on highly enriched uranium targets, chemical processing reagents, and DOTATATE peptide precursors. Single-source vulnerability in Canadian reactor maintenance schedules creates supply chain risk for lutetium-177 availability. Distribution runs through EPA-licensed radiopharmaceutical production sites that require specialized handling protocols for alpha- and beta-emitter therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pituitary cancer care fragments across metropolitan academic centers and community settings, with telemedicine integration creating service niches in hormonal management follow-up that bypass geographic concentration of surgical expertise.
For Market Incumbents: Insulate radioligand therapy market position through backward integration into gallium-68 generator production and captive supply of peptide receptor radionuclide therapy manufacturing capacity. Secure EPA production site licensing in secondary United States markets to preempt competitor entry. Vertical integration into isotope handling infrastructure defends against supply disruption threats from Canadian reactor maintenance cycles. For New Entrants and Emerging Players: Pursue checkpoint inhibition protocol development for refractory pituitary carcinoma as an unlabeled indication with accelerated approval pathway potential. Target ambulatory surgical center settings for transsphenoidal case volume where favorable anatomy and limited comorbidity support outpatient migration. Telemedicine-enabled endocrinology consultation platforms offer the most penetrable go-to-market angle for decoupling chronic hormonal management from surgical center geography. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors radiopharmaceutical platform developers with established isotope supply relationships over immuno-oncology concept-stage assets. Long-term viability over a multi-year horizon rests on FDA orphan drug exclusivity periods and EMA parallel designation pathways. Acquisition target archetype: mid-cap biotech firms with peptide receptor radionuclide therapy manufacturing capabilities and existing EPA licensing. The signal to watch is reimbursement policy evolution for combination therapy regimens as treatment paradigms shift toward precision-targeted approaches.| Strategic Initiative | Industry Significance |
|---|---|
| Peptide Receptor Radionuclide Therapy Manufacturing Scale-Up | EPA production site licensing secures supply chain control for lutetium-177 therapies. |
| Checkpoint Inhibition Clinical Trial Advancement | PD-1/PD-L1 blockade protocols in refractory cases access FDA accelerated approval pathways. |
| Telemedicine Platform Integration | Remote endocrinology consultation extends hormonal management to underserved rural regions. |
| Orphan Drug Regulatory Approval Pathway | FDA tax credits and market exclusivity compress development timelines for rare neuroendocrine malignancies. |
| Hospital System Partnership | NCI-designated cancer center alliances concentrate referral volume and specialist training pipelines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with neuro-oncology department heads, pituitary tumor board coordinators, radiopharmaceutical manufacturing executives, and endocrinology practice managers. Secondary validation drew from FDA orphan drug designation filings, EMA orphan medicinal product submissions, ClinicalTrials.gov protocol registries, and CMS reimbursement coding databases. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation anchored market size estimation.
Calibration against historical treatment initiation rates and referral pattern shifts informed projection methodology across the analysis window. Segmentation dimensions modeled include treatment modality, care setting tier, hormonal dysfunction type, and regional regulatory cluster. CAGRs were derived from slope analysis of intervention volume trends and pricing trajectory assumptions. Forecast inputs incorporated radioligand therapy adoption curves and skull base surgical workforce pipeline data.
Sensitivities concentrate around isotope supply disruption events, reimbursement policy revisions for radiopharmaceutical administration, and diagnostic coding changes affecting episode-of-care bundling. Forecasts reflect documented assumptions regarding referral network expansion and telemedicine regulatory clarity. Material shifts in FDA orphan drug incentive structures or EPA radiopharmaceutical licensing requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Global Cancer Treatment Market
Oncology
Global Metastatic Melanoma Drugs Market
Oncology
Global Metastatic Cancer Treatment Market
Oncology
Vulvar Cancer Market
Oncology
Oncology Apoptosis Modulators Market
Oncology
South America Bladder Cancer Therapeutics and Diagnostics Market
Oncology
Breast Cancer Therapy Market
Oncology
Europe Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Colorectal Cancer Market
Oncology
Ewing Sarcoma Treatment Market
Oncology
Cancer/Tumor Profiling Market
Oncology
Single-Room Proton Therapy Systems Market
Oncology
Global Hurthle Cell Carcinoma Treatment Market
Oncology
Peritoneal Cancer Treatment Market
Oncology
France Radiation Oncology Market
Oncology
Colorectal Cancer Treatment Market