
 Oncology Devices Market | 2026-2036
Oncology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Oncology Devices Market Outlook
The direct-to-hospital procurement channel is narrowing as integrated delivery networks consolidate vendor contracts across multi-site systems. Boston Scientific leverages its interventional oncology portfolio to sustain catheter-based ablation supply agreements with major hospital groups. Medtronic anchors radiation therapy equipment sales through long-term service contracts that lock in replacement cycles. Siemens Healthineers competes on imaging-diagnostic integration, bundling MRI-guided surgery platforms with oncology informatics workflows.
Oncology devices encompass instruments and systems engineered for cancer diagnosis, treatment, and monitoring, typically operating within precision tolerances of sub-millimeter targeting accuracy and real-time tissue feedback loops. These devices serve the primary commercial purpose of enabling localized tumor intervention while preserving surrounding healthy tissue. Diagnostic imaging devices command the largest installed base, though targeted drug delivery systems represent the fastest-expanding margin pool as biologics-compatible infusion architectures gain clinical traction. Precision oncology platforms are displacing legacy chemotherapy infusion pumps in tertiary care settings where biomarker-directed protocols standardize treatment selection.
FDA premarket notification and EU MDR technical documentation requirements shape product development timelines, with both agencies intensifying software-as-medical-device scrutiny for AI-enabled imaging tools. The EPA and OSHA maintain parallel jurisdiction over radiation-emitting equipment workplace safety standards, adding compliance layers to domestic manufacturing and clinical deployment. Stakeholders must monitor evolving reimbursement coding for tumor ablation procedures, as coverage determinations increasingly differentiate between inpatient and ambulatory site-of-care economics.
Market Dynamics
Integrated delivery networks are consolidating vendor contracts across multi-site hospital systems, compressing procurement channels and forcing manufacturers to restructure pricing architectures around enterprise-level service agreements rather than single-site equipment sales.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited review pathways for AI-enabled diagnostic tools accelerate commercialization timelines for imaging software developers seeking premarket clearance.
- Academic Medical Center Expansion:Tertiary care institutions in the United States are standardizing biomarker-directed protocols that require precision oncology platform upgrades.
- Carbon Ion Therapy:Heavy particle radiation systems are gaining clinical validation for radioresistant tumors, driving hospital capital expenditure in advanced beam delivery infrastructure.
Market Restraints
- EU MDR Technical Documentation Burden:Conformity assessment requirements for Class III devices extend approval timelines and inflate regulatory compliance costs for manufacturers.
- Isotope Supply Concentration:Molybdenum-99 production relies on aging nuclear reactors in Canada and the Netherlands, creating vulnerability in radiopharmaceutical tracer availability.
- Linear Accelerator Hardware Limitations:Legacy cobalt-60 units face obsolescence as magnetic resonance-guided delivery systems demand complete facility retrofitting.
Strategic Opportunities
- India PLI Scheme for Medical Devices:Production-linked incentives for domestic manufacturing of cancer diagnostic equipment attract contract manufacturers seeking cost-advantaged export hubs.
- Ambulatory Surgery Center Infusion:Site-of-care migration for tumor ablation procedures opens channel expansion beyond traditional hospital procurement.
- MRI-Linac Convergence:Real-time soft-tissue imaging integration with radiation delivery systems creates premium pricing tiers for integrated platform vendors.
Industry Challenges
- Medical Physicist Talent Scarcity:Specialized training requirements for commissioning and calibrating particle therapy systems outpace university program output.
- Legacy PACS Integration Complexity:AI-enabled imaging tools face interoperability friction with hospital enterprise archive systems, delaying clinical workflow adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oncology Devices Market |
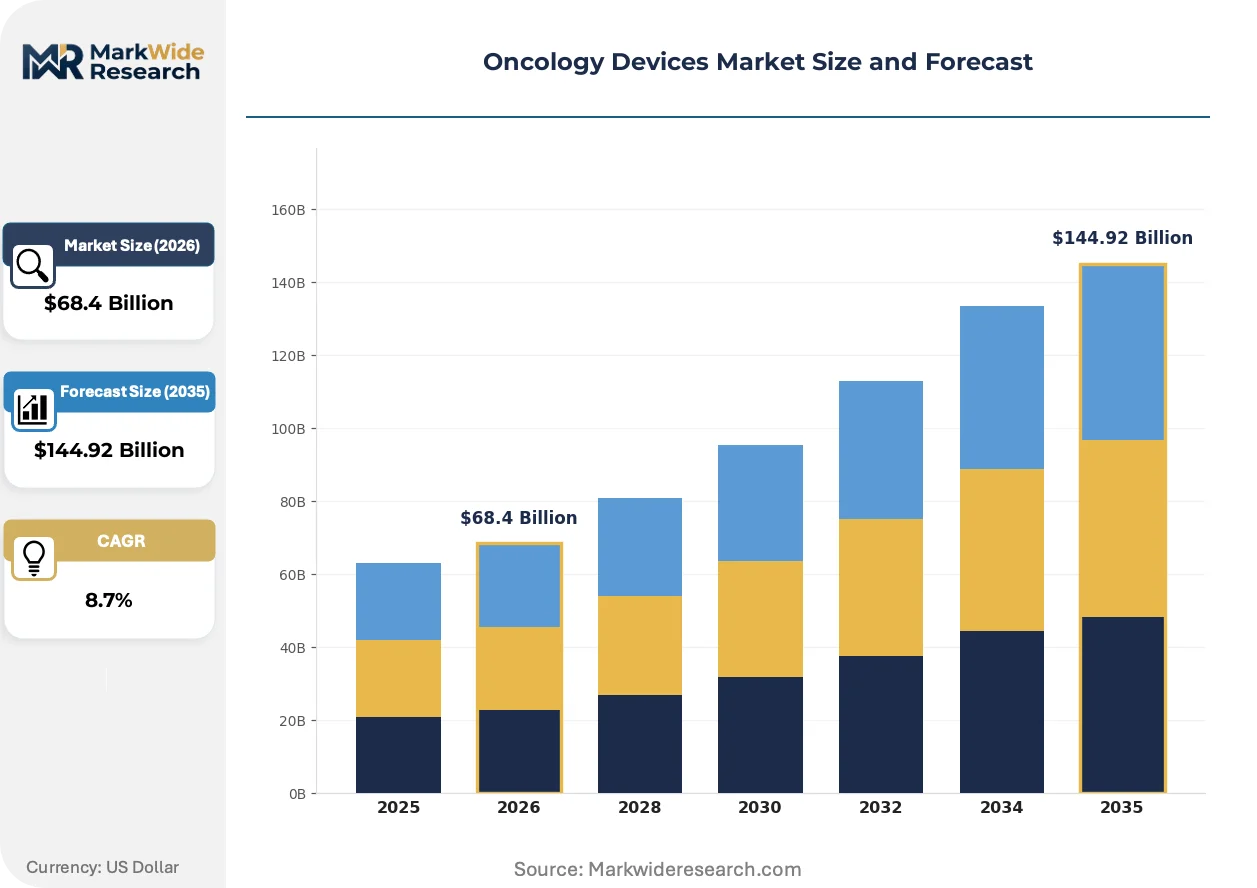
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiation Therapy Equipment, Surgical Oncology Instruments, Diagnostic Imaging Devices, Targeted Drug Delivery Systems Technology: Radiofrequency Ablation, MRI-guided Surgery, Chemotherapy Infusion Pumps, Precision Oncology Platforms End User: Hospitals, Oncology Treatment Centers, Research Institutions, Homecare Settings Application: Tumor Ablation, Chemotherapy Administration, Imaging, Patient Monitoring |
| Companies Covered | Boston Scientific, Medtronic, AngioDynamics, Merit Medical Systems, Terumo, Siemens Healthineers, Cook Group, Johnson & Johnson, Stryker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oncology Devices Market Strategic Shifts
Software-defined functionality is displacing hardware-centric product architectures across diagnostic and therapeutic device categories, compressing replacement cycles while expanding recurring revenue streams for platform vendors.
Flash radiotherapy delivery systems is hybridizing ultra-high dose rate physics with conventional linear accelerator platforms, enabling sub-second tumor treatments that minimize normal tissue exposure. Major cancer centers in Germany and the United States are piloting clinical protocols. Equipment manufacturers are compressing development timelines to secure first-mover positioning in next-generation beam modulation.
EU MDR Article 10 post-market surveillance requirements are mandating systematic clinical follow-up data collection for implantable oncology devices. Manufacturers must now maintain active registries or face certificate suspension. European notified bodies are prioritizing software-as-medical-device audits, diverging resource allocation from traditional hardware assessments.
Hospital procurement committees are unbundling equipment sales from long-term service contracts, forcing vendors to compete on discrete maintenance pricing rather than locked-in total cost of ownership models. Integrated delivery networks in the United States are driving this disintermediation through centralized capital allocation committees. Radiation therapy vendors are responding with modular upgrade pathways that preserve account relationships without mandatory multi-year attachments.
Oncology Devices Market Segmentation
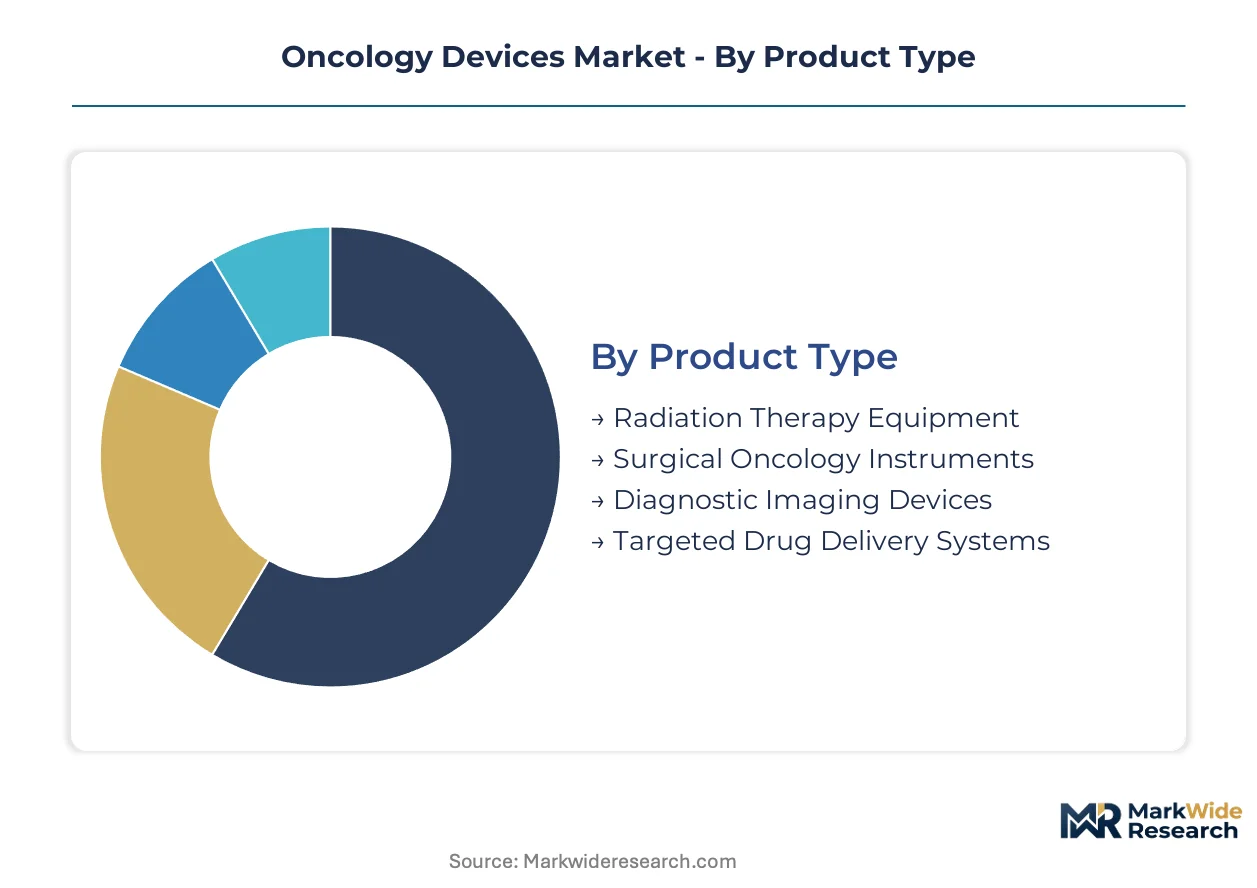
Oncology device segmentation reveals divergent commercial architectures across therapeutic and diagnostic modalities. Product categories span capital-intensive radiation systems through disposable drug delivery consumables, each commanding distinct procurement cycles and margin profiles.
Product Type:
Mature installed-base segments coexist with emerging precision platforms, creating bifurcated investment horizons across hospital capital committees.
- Diagnostic Imaging Devices:MRI, CT, and PET-CT systems form the diagnostic backbone with sub-millimeter resolution requirements. United States academic medical centers drive replacement demand as software-defined upgrades extend hardware lifecycles beyond traditional depreciation schedules.
- Radiation Therapy Equipment:Linear accelerators and proton therapy systems deliver targeted ionizing radiation with millimeter-scale beam steering accuracy. Heavy particle centers in Germany and Japan validate carbon ion protocols, accelerating hospital capital expenditure in next-generation beam delivery infrastructure.
- Surgical Oncology Instruments:Electrosurgical units and robotic platforms enable minimally invasive tumor resection with integrated margin assessment capabilities.
- Targeted Drug Delivery Systems:Biologics-compatible infusion architectures and implantable pumps support biomarker-directed protocols.
Diagnostic imaging devices retain volume leadership; targeted drug delivery systems hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium integrated platforms from standalone therapeutic modalities, with reimbursement differentials reinforcing the price architecture.
- Precision Oncology Platforms:AI-enabled treatment planning systems integrate genomic data with real-time adaptive dosing algorithms. United States integrated delivery networks standardize these platforms as condition of participation in precision medicine networks.
- MRI-guided Surgery:Intraoperative magnetic resonance imaging enables real-time soft-tissue visualization during tumor resection with continuous navigation feedback. Tertiary centers in Boston and Heidelberg deploy these systems for glioblastoma and prostate procedures.
- Radiofrequency Ablation:Percutaneous thermal ablation systems deliver localized tissue necrosis through catheter-based electrode deployment.
- Chemotherapy Infusion Pumps:Programmable ambulatory pumps administer cytotoxic agents with dose-error reduction software.
Precision oncology platforms command premium pricing tiers; MRI-guided surgery is gaining share fastest in tertiary settings.
End User:
Customer type fragmentation creates channel complexity, with procurement authority shifting from individual hospitals toward consolidated enterprise systems.
- Hospitals:Integrated delivery networks and academic medical centers dominate capital equipment procurement, leveraging multi-site service agreements to compress vendor pricing. United States health systems centralize radiation therapy equipment decisions through corporate capital committees.
- Oncology Treatment Centers:Dedicated cancer hospitals and freestanding radiation centers concentrate specialized procedure volume, achieving economies in medical physicist staffing and protocol standardization.
- Research Institutions:National cancer institutes and university hospitals host clinical trial infrastructure for investigational device protocols.
- Homecare Settings:Subcutaneous infusion devices and remote monitoring systems enable outpatient chemotherapy administration.
Hospitals retain volume leadership; homecare settings present the steepest expansion trajectory as site-of-care migration accelerates.
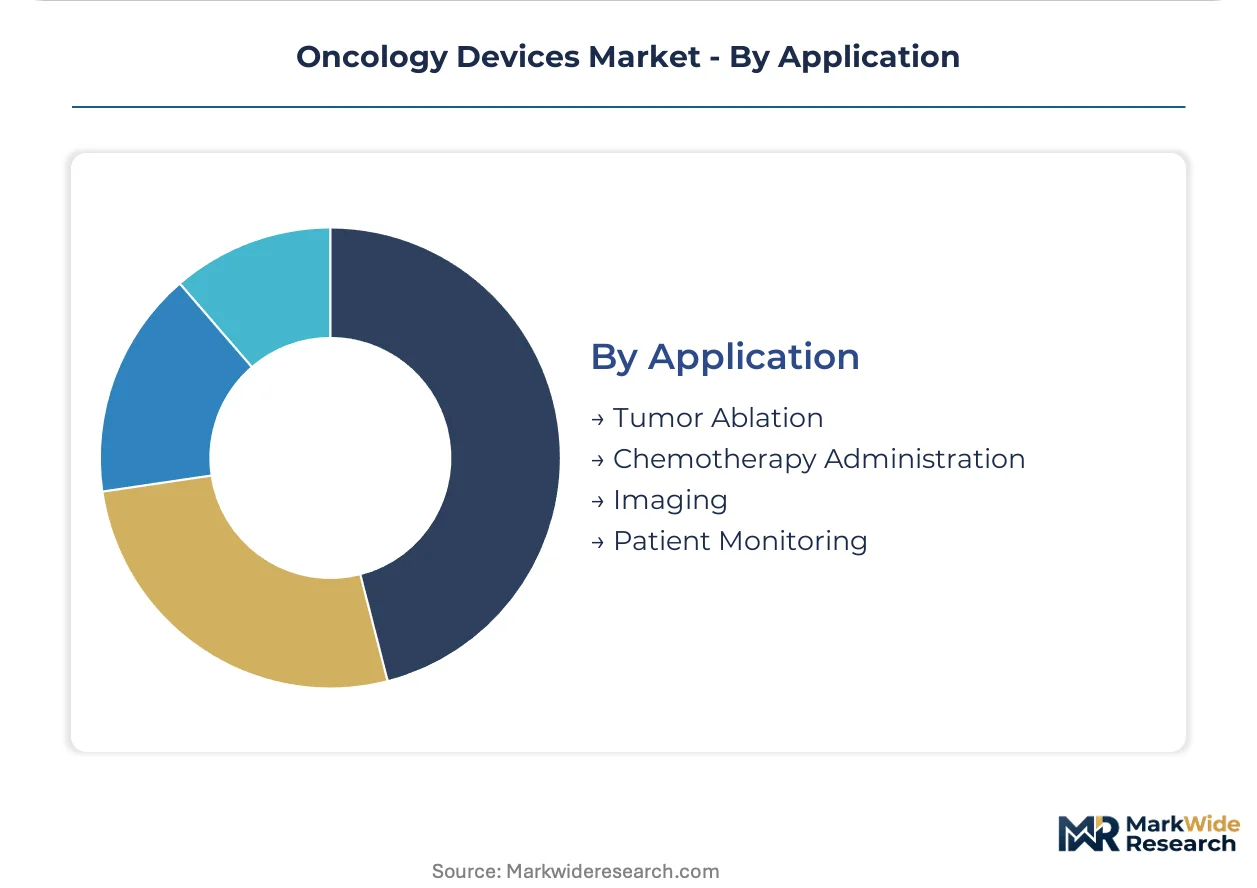
Application:
Margin concentration varies sharply across the therapeutic continuum, with interventional procedures commanding superior reimbursement relative to supportive care monitoring.
- Tumor Ablation:Percutaneous and intraoperative thermal destruction techniques treat solid organ malignancies without surgical resection. Ambulatory surgery centers in Florida and Texas expand cryoablation and microwave ablation capacity under streamlined licensing frameworks.
- Imaging:Diagnostic radiology and interventional imaging support staging, treatment planning, and response assessment across the care pathway.
- Chemotherapy Administration:Systemic drug delivery encompasses infusion pump programming, vascular access device management, and toxicity monitoring protocols.
- Patient Monitoring:Wearable sensors and remote telemetry track treatment response and adverse event emergence between clinic visits.
Imaging retains volume leadership; tumor ablation holds the steepest expansion curve as reimbursement codes differentiate site-of-care economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA premarket review pathways and production-linked incentives in Asia are redirecting capital flows toward compliant manufacturing hubs and precision oncology infrastructure upgrades.
United States
Academic medical centers in Boston and Houston drive carbon ion therapy validation while integrated delivery networks consolidate vendor contracts. FDA Breakthrough Device Designation accelerates AI-enabled imaging software commercialization. The Texas Medical Center anchors proton therapy expansion with heavy particle research protocols.
Germany
University hospitals in Heidelberg and Munich validate flash radiotherapy protocols for radioresistant tumors. EU MDR Article 10 post-market surveillance mandates systematic clinical follow-up data collection for implantable devices. The Heidelberg Ion-Beam Therapy Center advances carbon ion beam delivery infrastructure.
Japan
National cancer institutes in Chiba and Hyogo concentrate heavy particle therapy volume with government-subsidized facility construction. PMDA software-as-medical-device scrutiny intensifies for AI-enabled diagnostic tools. The Chiba Prefecture hosts clinical validation for next-generation beam modulation systems.
India
Contract manufacturers leverage PLI scheme incentives for domestic production of cancer diagnostic equipment. CDSCO medical device rules streamline import substitution for radiation therapy components. Gujarat and Karnataka emerge as cost-advantaged export hubs for oncology device assembly.
China
Tertiary hospitals in Beijing and Shanghai integrate MRI-Linac platforms for real-time adaptive radiation delivery. NMPA intensifies premarket review for AI-enabled imaging tools under revised medical device regulations. The Yangtze River Delta concentrates proton therapy center construction with state-backed capital deployment.
Oncology Devices Market Competitive Environment
On the supply side, the industry is consolidating around multi-product platform vendors capable of bundling imaging, therapeutic, and informatics workflows. Tiered competitive positioning separates integrated system architects from specialized component suppliers. Equipment manufacturers and interventional device specialists represent the dominant strategic archetypes. M&A activity targets AI-enabled software capabilities while service contract restructuring preserves account relationships.
Within the integrated platform tier, Siemens Healthineers and Medtronic occupy positions spanning diagnostic imaging through therapeutic delivery systems. Boston Scientific exemplifies the interventional specialization archetype with catheter-based ablation technologies. These three anchors represent contrasting strategic postures: bundled ecosystem control, long-term service lock-in, and procedure-focused disposable architectures.
| Leading Market Players |
|---|
| Boston Scientific |
| Medtronic |
| AngioDynamics |
| Merit Medical Systems |
| Terumo |
| Siemens Healthineers |
| Cook Group |
| Johnson & Johnson |
| Stryker |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Antwerp corridor freight costs compress margin structures for EU-bound radiation therapy equipment while amplifying price spreads between FDA-certified and CE-marked product tiers. Integrated delivery networks exploit this logistics differential to extract volume discounts from manufacturers with concentrated European assembly footprints.
Pricing Analysis
Certification level creates the primary spread across oncology device tiers, with FDA-grade imaging systems commanding substantial premiums over CE-marked equivalents in United States procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by software-defined functionality and service bundling intensity. Pricing pressure stems from hospital procurement committees unbundling equipment sales from mandatory maintenance contracts. Academic medical centers exhibit lowest price sensitivity due to precision protocol requirements, while ambulatory surgery centers drive cost compression through competitive bidding.
Supply Chain Analysis
Contract manufacturing concentration rests with Jabil, Flex, and Sanmina for radiation therapy component assembly across Mexico, Malaysia, and Poland facilities. Molybdenum-99 isotope production draws from aging Canadian and Dutch nuclear reactors, while rare earth magnet supply hinges on Chinese processing capacity. Single-source vulnerability in isotope supply chains threatens radiopharmaceutical tracer availability. Distribution runs through integrated delivery network central procurement offices and GPO contract frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oncology device fragmentation creates entry niches as site-of-care migration splinters historically concentrated hospital procurement channels. Ambulatory surgery centers and homecare infusion segments now operate outside integrated delivery network vendor lock-in.
For Market Incumbents: Insulate service revenue streams by modularizing hardware upgrade pathways that preserve account relationships without mandatory multi-year attachments. Deepen backward integration into AI-enabled imaging software development to defend against pure-play algorithm vendors. Carbon ion therapy infrastructure represents the critical capability gap to close. For New Entrants and Emerging Players: Pursue ambulatory surgery center infusion pumps and subcutaneous drug delivery systems as the most penetrable white space outside IDN contract coverage. Target Florida and Texas licensing frameworks for cryoablation capacity expansion. Lead with remote monitoring integration to differentiate from legacy pump manufacturers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming medical device divisions holding dormant FDA 510(k) clearances. Five-to-ten year viability favors precision oncology platform vendors with biomarker-directed protocol integration. Monitor CMS reimbursement coding decisions for tumor ablation site-of-care differentials as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation Pathway | Expedited review accelerates AI-enabled imaging software commercialization timelines for developers. |
| CE Marking Technical Documentation Investment | EU MDR Article 10 compliance preserves market access for implantable oncology device manufacturers. |
| Hospital System Partnership | Multi-site service agreements with IDNs lock in replacement cycles for radiation therapy equipment. |
| Software Companion Development | AI-enabled treatment planning integration differentiates precision oncology platform offerings. |
| Reimbursement Strategy | CPT code differentiation between inpatient and ambulatory ablation procedures shapes site-of-care economics. |
Study Parameters
A spread of perspectives from radiation oncologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers converged on the working assumptions for demand modeling. Secondary validation drew from FDA 510(k) databases, CMS Medicare reimbursement files, hospital procurement registries, and EU MDR notified body audit disclosures. Bottom-up equipment installation counts triangulated against top-down health system capital expenditure surveys.
Demand-supply balance across the projection horizon anchored the analytical framework, with segmentation across product type, technology tier, end-user setting, and application area. CAGRs derived from replacement cycle analysis and biomarker-directed protocol adoption curves. Modeled inputs included linear accelerator depreciation schedules and precision oncology platform software attach rates.
Macroeconomic conditions sit as an overlay; deviation in hospital capital expenditure budgets or isotope supply continuity would shift the trajectory. Quarterly review of FDA premarket submission backlogs and CMS coverage determinations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Tumor Lysis Syndrome Market
Oncology
Global Particle Therapy Market
Oncology
Gallbladder Cancer Treatment Market
Oncology
North America Bone Metastasis Market
Oncology
Single-Room Proton Therapy Systems Market
Oncology
Metastatic Breast Cancer Market
Oncology
Global Hurthle Cell Carcinoma Treatment Market
Oncology
Global Interventional Oncology Market
Oncology
Global Metastatic Melanoma Drugs Market
Oncology
Global Nasopharyngeal Cancer Market
Oncology
Ewing Sarcoma Treatment Market
Oncology
Radiation Therapy Software Market
Oncology
Tumor Ablation Market
Oncology
Lung Cancer Treatment Market
Oncology
Pharyngeal Neoplasm Market
Oncology
Pancreatic Cancer Therapeutics Market