
 Radiotherapy Positioning Devices Market | 2026-2036
Radiotherapy Positioning Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Radiotherapy Positioning Devices Market Analytics
Oncology department investment is broadening beyond traditional hospital settings into dedicated radiation therapy centers. Elekta leverages its installed base of linear accelerators to bundle positioning accessories with equipment service contracts. Qfix competes through specialized immobilization devices for head-and-neck and breast protocols. Mizuho OSI sustains manufacturing scale in Asia-Pacific while navigating FDA clearance pathways for U.S. market entry.
Radiotherapy positioning devices are patient stabilization systems manufactured from thermoplastic, foam, or carbon-fiber composites, designed to immobilize anatomy within sub-millimeter tolerances during fractionated or single-session radiation delivery. Laser alignment systems and electromagnetic tracking represent the fastest-expanding technology categories as clinics pursue real-time motion management. Immobilization devices occupy the largest product segment by unit volume, though AI-assisted positioning commands premium pricing due to integration complexity with 3D imaging workflows. Motion management systems are displacing static positioning in stereotactic body radiotherapy applications where respiratory gating demands dynamic patient interfaces.
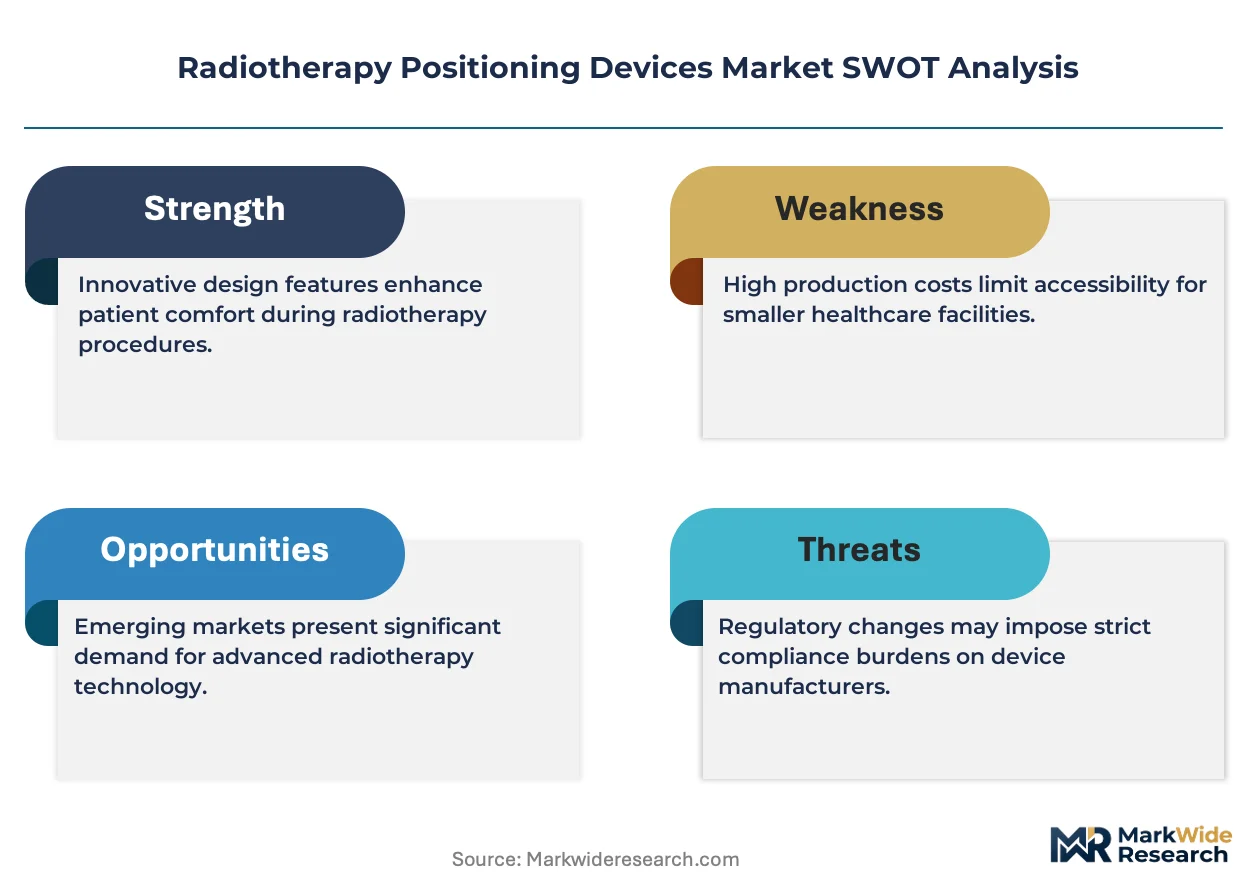
FDA 510(k) requirements and EU MDR conformity assessments govern material safety and electromagnetic compatibility for reusable positioning products, extending development timelines for new entrants. ISO 13485 quality management standards and IEC 60601-1-2 electromagnetic compatibility directives shape manufacturing protocols and market access documentation for international suppliers. Stakeholders must monitor reimbursement shifts toward hypofractionated protocols, which alter immobilization durability requirements and replacement cycles across installed device bases.
Market Dynamics
Proton therapy and stereotactic body radiotherapy programs are compressing positioning tolerances from millimeters to sub-millimeter ranges, forcing immobilization systems to incorporate real-time motion tracking and adaptive interfaces that respond to respiratory and cardiac cycles.
Growth Catalysts
- EU MDR biocompatibility mandates:Tighter material safety standards for reusable thermoplastic devices are accelerating hospital replacement cycles and opening procurement windows for certified suppliers.
- Hypofractionated protocols:Compressed treatment schedules in head-and-neck oncology require more durable carbon-fiber composites that withstand repeated daily use without deformation.
- China proton therapy expansion:New particle therapy centers in Shanghai and Guangzhou are importing precision positioning systems to meet clinical commissioning requirements.
Market Restraints
- Carbon-fiber supply concentration:Aerospace and automotive sectors dominate Toray and Hexcel output, leaving medical device manufacturers with extended lead times for high-modulus composite feedstock.
- FDA 510(k) pathway length:Electromagnetic tracking devices face 14-18 month review cycles due to IEC 60601-1-2 electromagnetic compatibility documentation demands.
- Reusable-to-disposable substitution:Single-use foam cushions are displacing thermoplastic masks in community clinics seeking to eliminate sterilization infrastructure.
Strategic Opportunities
- AI-assisted positioning convergence:Machine vision alignment systems that integrate with 3D cone-beam CT workflows command premium pricing in academic medical centers.
- India radiation therapy infrastructure:Government PLI scheme incentives for medical device manufacturing are attracting contract manufacturers to establish thermoplastic molding capacity near Mumbai and Hyderabad.
- Direct-to-clinic distribution:E-commerce procurement platforms are bypassing traditional durable medical equipment distributors for replacement cushion and strap consumables.
Industry Challenges
- Medical physics talent scarcity:Qualified professionals who can calibrate electromagnetic tracking systems against linac isocenters command salaries that strain community hospital budgets.
- Legacy linac integration complexity:Retrofitting twenty-year-old linear accelerators with respiratory gating interfaces requires custom mechanical adapters that extend installation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiotherapy Positioning Devices Market |
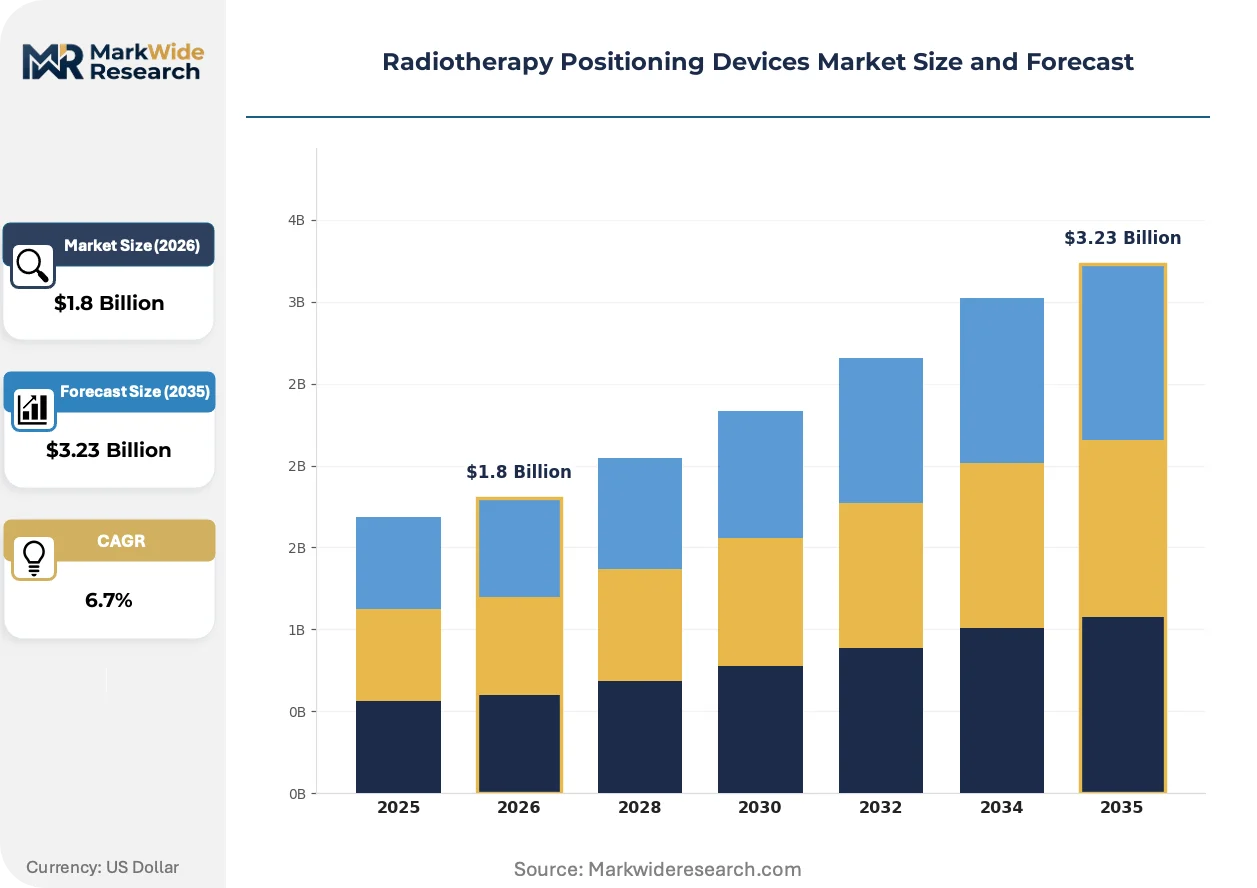
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Positioning Cushions, Immobilization Devices, Laser Alignment Systems, Securement Devices End User: Hospitals, Radiation Therapy Centers, Diagnostic Imaging Centers, Academic Institutions Application: Targeted Radiation Therapy, Intensity-Modulated Radiotherapy, Stereotactic Body Radiotherapy, palliative treatment Technology: 3D Imaging, Motion Management Systems, AI-Assisted Positioning, Electromagnetic Tracking |
| Companies Covered | Elekta, Mizuho OSI, CIVCO Radiotherapy, Bionix Radiation Therapy, CDR Systems, Qfix, Klarity Medical, Landauer, Orfit Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiotherapy Positioning Devices Market Evolving Landscape
Real-time patient monitoring is displacing static immobilization across advanced radiation therapy modalities. Clinicians now demand positioning systems that communicate continuously with treatment delivery platforms rather than simply holding anatomy in place.
Electromagnetic tracking arrays are integrating with linac control systems to enable beam-holding during respiratory motion. Academic medical centers in Boston and Heidelberg are deploying these interfaces for liver and lung stereotactic treatments. The technology is compressing planning margins and enabling dose escalation protocols that were previously limited by motion uncertainty.
EU MDR technical documentation requirements are forcing manufacturers to revalidate biocompatibility testing for legacy thermoplastic formulations. Small and mid-sized suppliers face six-figure conformity assessment costs that favor consolidated product portfolios. German notified bodies are experiencing 12-month backlogs for positioning device CE marking renewals.
Hospital procurement departments are unbundling service contracts from equipment purchases. Radiation therapy centers now source positioning accessories through separate RFP processes that prioritize total cost of ownership over upfront capital expenditure. This shift is most pronounced in United States integrated delivery networks managing fifty-plus linac fleets across multi-state footprints.
Radiotherapy Positioning Devices Market Segmentation
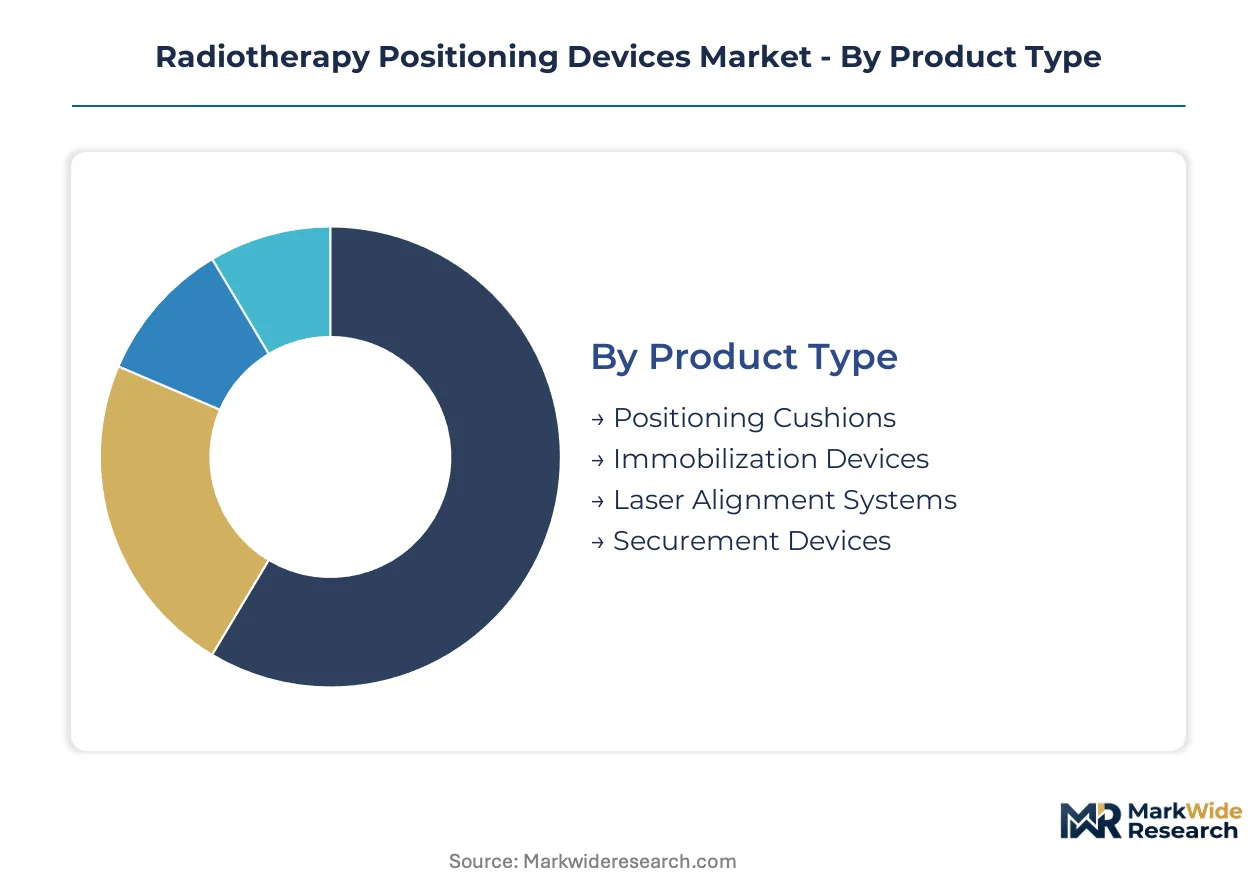
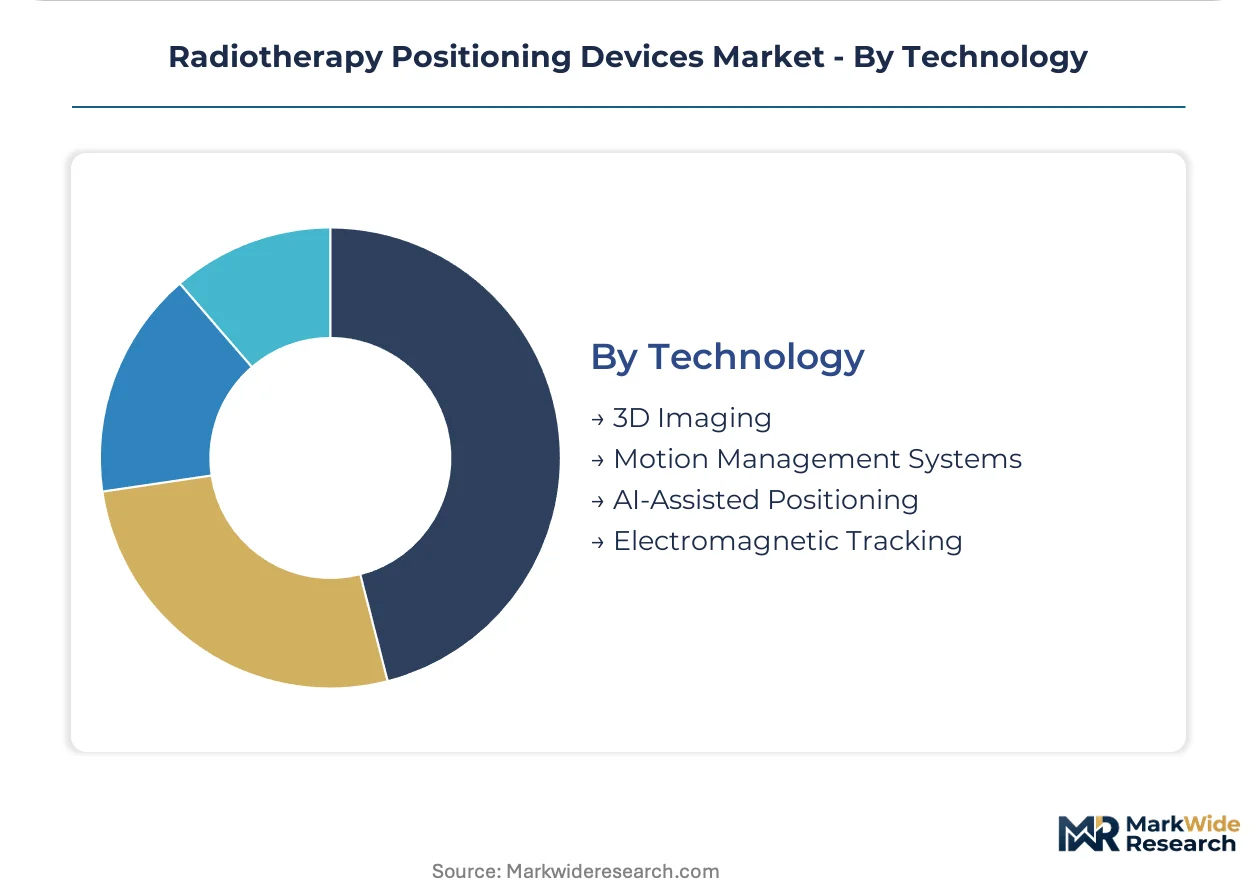
Segmentation in radiotherapy positioning devices reflects divergent capital requirements across technology tiers and care settings. Product type and technology categories demand heavy upfront engineering investment, while end-user and application segments distribute volume across facility types with varying procurement sophistication.
Product Type:
Capital intensity varies sharply across this category, with carbon-fiber composite systems and integrated laser arrays requiring multimillion-dollar manufacturing infrastructure.
- Immobilization Devices:Thermoplastic masks and carbon-fiber cradles manufactured to sub-millimeter tolerances anchor patient stabilization during fractionated treatment. Demand clusters in proton therapy centers in the United States and Germany where beam delivery precision mandates rigid anatomy fixation. EU MDR biocompatibility revalidation is accelerating replacement cycles for legacy thermoplastic formulations.
- Laser Alignment Systems:Room-mounted diode arrays project isocenter reference planes for patient setup verification. Academic medical centers in Boston and Heidelberg deploy these for stereotactic protocols requiring spatial accuracy below one millimeter. FDA 510(k) electromagnetic compatibility documentation extends development timelines for new optical tracking entrants.
- Positioning Cushions:Foam and vacuum-fixed supports enable rapid patient repositioning across treatment fractions.
- Securement Devices:Straps and belts provide supplementary stabilization for extremity and torso immobilization.
Most installed capacity flows through Immobilization Devices. Expansion is steepest in Laser Alignment Systems.
End User:
Procurement sophistication separates this category, with radiation therapy centers operating dedicated capital budgets distinct from general hospital medical device purchasing.
- Radiation Therapy Centers:Standalone facilities with concentrated linac fleets drive premium positioning system adoption. Centers in Shanghai and Guangzhou are importing precision immobilization systems for proton therapy commissioning. Unbundled service contracts now allow separate RFP processes for positioning accessories.
- Hospitals:Integrated oncology departments within multi-service institutions manage positioning device procurement through centralized supply chains. Community hospitals in the United States face medical physics talent scarcity when calibrating electromagnetic tracking against legacy linac isocenters.
- Academic Institutions:Research-focused centers pilot AI-assisted positioning convergence with 3D cone-beam CT workflows.
- Diagnostic Imaging Centers:Imaging-only facilities require basic immobilization for simulation and planning scans.
Radiation Therapy Centers command the highest per-facility spending. Academic Institutions are gaining share fastest through research procurement.
Application:
Clinical protocol complexity determines positioning tolerance requirements, with stereotactic applications demanding dynamic interfaces that static immobilization cannot satisfy.
- Stereotactic Body Radiotherapy:High-dose, few-fraction treatments for lung and liver lesions require respiratory-gated positioning with real-time motion compensation. Liver and lung programs in academic centers are displacing static immobilization with electromagnetic tracking arrays that communicate continuously with linac control systems.
- Intensity-Modulated Radiotherapy:Computer-optimized beam modulation for head-and-neck and prostate protocols relies on reproducible patient setup across twenty-plus fractions. Hypofractionated schedules are compressing replacement cycles for carbon-fiber composites that withstand repeated daily use.
- Targeted Radiation Therapy:Image-guided dose delivery integrates positioning systems with onboard cone-beam CT verification.
- Palliative Treatment:Comfort-focused protocols prioritize rapid setup over sub-millimeter precision.
Intensity-Modulated Radiotherapy carries the largest installed base. Stereotactic Body Radiotherapy is climbing the fastest as respiratory gating technology matures.
Technology:
Integration complexity with existing linac architectures creates divergent margin profiles across this category.
- Motion Management Systems:Respiratory and cardiac cycle tracking interfaces enable beam-holding during patient movement. Dynamic patient interfaces are displacing static positioning in stereotactic applications where gating demands real-time adaptive response. FDA 510(k) review cycles for electromagnetic compatibility documentation stretch fourteen to eighteen months.
- AI-Assisted Positioning:Machine vision alignment systems integrate with 3D imaging workflows to automate patient setup verification. Academic medical centers command premium pricing for these systems due to software validation requirements and physics integration complexity.
- 3D Imaging:Cone-beam CT and surface scanning systems provide volumetric setup verification before beam delivery.
- Electromagnetic Tracking:Wireless sensor arrays monitor internal or surface anatomy without ionizing radiation exposure.
3D Imaging dominates current installed capacity. AI-Assisted Positioning shows the steepest expansion trajectory as machine vision validation protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting thermoplastic molding capacity toward jurisdictions with streamlined medical device clearance pathways. Manufacturers are relocating production to exploit gaps between FDA 510(k) timelines and faster national equivalency programs.
United States
Proton therapy centers in Boston and Houston are commissioning precision immobilization systems for stereotactic protocols. FDA 510(k) electromagnetic compatibility documentation extends review cycles to fourteen-to-eighteen months for electromagnetic tracking entrants. Academic medical centers in California are piloting AI-assisted positioning convergence with cone-beam CT workflows.
Germany
Heidelberg University Hospital deploys respiratory-gated positioning arrays for liver stereotactic treatments. EU MDR biocompatibility revalidation mandates are accelerating replacement cycles for legacy thermoplastic masks. Notified bodies in Munich face twelve-month backlogs for positioning device CE marking renewals.
China
New proton therapy centers in Shanghai and Guangzhou are importing carbon-fiber immobilization systems for clinical commissioning. NMPA medical device registration requirements are tightening material documentation for reusable positioning products. Thermoplastic molding clusters in Shenzhen are expanding capacity to serve domestic radiation therapy infrastructure buildout.
India
Government PLI scheme incentives are attracting contract manufacturers to establish thermoplastic molding capacity near Mumbai and Hyderabad. CDSCO medical device rules are converging with international standards for biocompatibility testing. Regional radiation therapy centers in Karnataka are procuring basic immobilization devices through centralized hospital supply chains.
Japan
PMDA quality management requirements are shaping manufacturing protocols for carbon-fiber composite positioning systems. METI industrial policy is supporting domestic production of high-modulus composite feedstock for medical applications. Osaka-based fabricators are supplying immobilization devices to proton therapy centers across East Asia.
Radiotherapy Positioning Devices Market Competitive Landscape
Strategic partnerships dominate the current landscape as equipment manufacturers bundle positioning accessories with linear accelerator service contracts. The vendor base separates into three tiers: integrated radiation therapy platform suppliers, specialized immobilization device fabricators, and regional thermoplastic molding specialists. Two archetypes anchor competitive positioning—multinational platform bundlers leveraging installed linac bases, and focused specialists commanding premium pricing in head-and-neck and breast protocols. Portfolio diversification and backward integration into carbon-fiber composite supply represent the dominant competitive moves.
Among multinational platform suppliers, Elekta leverages its installed linear accelerator base to bundle positioning systems with equipment service agreements. Qfix occupies a specialist position in thermoplastic immobilization for anatomically complex treatment sites. Mizuho OSI represents the Asia-Pacific manufacturing scale archetype while navigating FDA clearance pathways for United States market entry.
| Leading Market Players |
|---|
| Elekta |
| Mizuho OSI |
| CIVCO Radiotherapy |
| Bionix Radiation Therapy |
| CDR Systems |
| Qfix |
| Klarity Medical |
| Landauer |
| Orfit Industries |
| Others |
Value Network & Pricing Analysis
Carbon-fiber composite manufacturing migration from aerospace-dominated suppliers to medical-specialized fabricators is simultaneously compressing material costs and fragmenting sourcing concentration across Germany, Japan, and China. This transition enables positioning device manufacturers to negotiate dual-source arrangements for high-modulus feedstock while FDA 510(k) documentation requirements add fixed compliance costs that inflate final system pricing.
Pricing Analysis
Distributor markups on replacement thermoplastic masks and vacuum cushions range from thirty to fifty percent above manufacturer net pricing in United States radiation therapy centers. Three-tier pricing structure across premium, standard, and economy levels separates AI-assisted positioning systems with cone-beam CT integration from basic immobilization cradles and disposable foam alternatives. Price compression in the standard tier intensifies because community hospitals are unbundling service contracts and sourcing accessories through direct e-commerce channels. Academic medical centers exhibit lowest price sensitivity due to research procurement budgets, while independent radiation therapy centers in India and Southeast Asia prioritize total cost of ownership metrics.
Supply Chain Analysis
Direct-to-clinic distribution channels handle consumable cushion and strap demand for replacement cycles, while capital equipment flows through specialized durable medical equipment distributors with biomedical engineering support capabilities. Manufacturing concentration rests on Germany for precision-machined carbon-fiber cradles, Japan for high-modulus composite feedstock, and China for thermoplastic molding capacity serving Asia-Pacific expansion. Raw material dependencies include Toray carbon-fiber prepreg, medical-grade thermoplastic pellets, and electromagnetic sensor arrays. Single-source vulnerability in aerospace-qualified carbon-fiber supply creates procurement risk when automotive and defense sectors absorb capacity. Distribution runs through regional hospital supply chains in Europe, GPO contracts in the United States, and government tender processes in China and India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The radiotherapy positioning devices market functions as a regulatory compounder where EU MDR biocompatibility revalidation mandates are accelerating replacement cycles and opening procurement windows for certified suppliers.
For Market Incumbents: Extend certification coverage across legacy thermoplastic formulations to capture EU MDR-driven replacement demand before notified body backlogs clear. Consolidate position by acquiring regional thermoplastic molding specialists in India and Southeast Asia to exploit PLI scheme incentives and localize production for price-sensitive procurement channels. Carbon-fiber supply concentration from Toray and Hexcel represents a margin threat that backward integration into composite feedstock partnerships can mitigate. For New Entrants and Emerging Players: Distributor partnerships with established durable medical equipment networks provide immediate access to radiation therapy center procurement committees without fourteen-month FDA 510(k) investment. Target India's regional radiation therapy infrastructure buildout through contract manufacturing arrangements with Mumbai and Hyderabad thermoplastic clusters. Position AI-assisted positioning modules as software companion offerings that integrate with existing linac installations rather than competing for capital equipment budgets. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-sized European thermoplastic specialists facing six-figure EU MDR conformity assessment costs that favor consolidated product portfolios. Long-term viability centers on software-enabled positioning convergence rather than commodity immobilization hardware. Monitor FDA 510(k) clearance timelines for electromagnetic tracking entrants as an inflection signal for motion management system adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR CE Marking Pathway | Accelerates replacement cycles for legacy thermoplastic masks in German and French radiation centers. |
| Hospital System Partnership | Elekta's service contract bundling with linac fleets locks in positioning accessory procurement volumes. |
| Software Companion Development | Machine vision alignment modules command premium pricing through 3D cone-beam CT workflow integration. |
| Backward Integration into Composites | In-house carbon-fiber prepreg capacity insulates margin from aerospace sector demand surges. |
| Direct-to-Clinic Distribution | E-commerce platforms bypass distributor markups for replacement cushion and strap consumables. |
Research Methodology
Bottom-up radiation therapy center modeling reconciled against top-down carbon-fiber composite supply tracking forms the analytical core of this study. Primary interviews with clinical medical physicists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers were cross-validated against secondary sources including FDA 510(k) filings, EU MDR notified body databases, hospital procurement records, and NMPA medical device registration data. Triangulation between demand-side installation tracking and supply-side manufacturing capacity ensures segmentation integrity.
Historical trendline analysis of immobilization device replacement cycles and laser alignment system adoption rates informed the projection framework. Segmentation modeling spans product type, technology tier, end-user facility category, and clinical application complexity across the projection horizon. CAGRs were derived from installed base growth, protocol shift impacts on equipment specifications, and reimbursement trajectory assumptions for hypofractionated treatments. Forecast inputs include proton therapy center commissioning timelines and electromagnetic tracking regulatory clearance patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR implementation delays, carbon-fiber supply allocation shifts, and proton therapy infrastructure buildout pace in China. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Spinal Surgery Devices Market
Medical Devices
Ultrasonic Dissection Devices Market
Medical Devices
Spinal Fusion Bone Graft Substitutes Market
Medical Devices
Asia-Pacific Bathroom and Toilet Assist Devices Market
Medical Devices
Dental Implants and Prosthetics Contract Manufacturing Market
Medical Devices
Global Cardiac Holter Monitor Market
Medical Devices
Brazil Artificial Organs and Bionic Implants Market
Medical Devices
Intravenous Stopcock Market
Medical Devices
Power Smart Bed Market
Medical Devices
Implantable Neurostimulators Market
Medical Devices
Surgical Devices Market
Medical Devices
Latin America Implantable Medical Devices Market
Medical Devices
Skull Clamp Market
Medical Devices
Asia-Pacific Refractive Surgery Devices Market
Medical Devices
Mexico Aesthetic Devices Market
Medical Devices
Stool Management Systems Market