
 Hadron Therapy Market | 2026-2036
Hadron Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Hadron Therapy Market Analysis
A shortage of certified medical physicists and proton therapy specialists is unwinding installation timelines at new treatment centers. Mevion Medical Systems leverages compact superconducting synchrocyclotron design to reduce vault construction costs and accelerate site commissioning. Ion Beam Applications sustains its installed base advantage through long-term service contracts and accelerator refurbishment programs. Hitachi anchors proton beam delivery innovation with spot-scanning systems that improve dose conformity for complex tumor geometries.
Hadron therapy deploys accelerated charged particles—protons or heavier ions such as carbon—to deposit energy at precise tissue depths via the Bragg peak effect, sparing adjacent healthy structures. Clinical systems operate at beam energies of 70–250 MeV for protons and require gantry rotational freedom to access tumors from multiple angles. Proton therapy dominates current installed capacity owing to lower infrastructure complexity and established reimbursement pathways. Carbon ion therapy represents the fastest-growing modality where centers in Japan and Germany demonstrate superior outcomes for radioresistant tumors. Beam delivery systems capture concentrated margin pools as vendors integrate real-time imaging and adaptive planning software.
The FDA governs proton accelerator safety and clinical trial endpoints for new indications in the United States. Japan's PMDA and Germany's national radiation protection authority enforce facility licensing and personnel certification standards that shape market access timelines. The EU MDR and CE marking requirements for beam delivery control systems add compliance layers for European installations. Stakeholders must weigh cyclotron versus synchrotron technology bets against evolving reimbursement for hypofractionated treatment protocols.
Market Dynamics
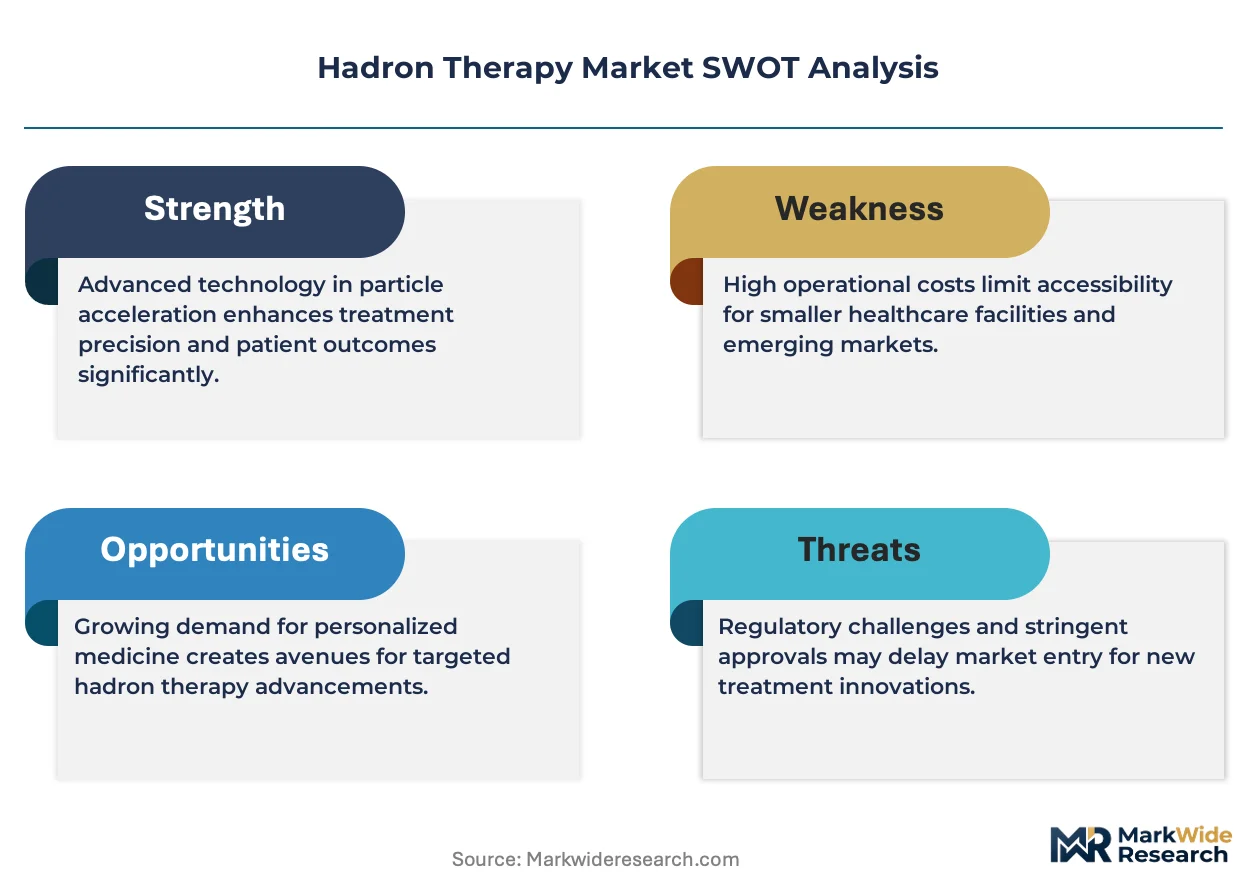
Compact superconducting cyclotron technology is compressing facility footprints from football-field dimensions to single-room installations, collapsing capital barriers that previously restricted proton center deployment to major academic medical centers.
Growth Catalysts
- Japan's PMDA fast-track oncology pathway:Accelerated approval timelines for pediatric proton indications are expanding treatable patient populations and center reimbursement eligibility.
- Hypofractionated treatment protocols:Compressed treatment courses from 30+ sessions to 5-8 sessions are improving patient throughput and center economics.
- Carbon ion modality expansion:Heidelberg and Chiba demonstration centers are validating superior outcomes for radioresistant skull-base and pelvic tumors, pulling replication demand.
Market Restraints
- Superconducting magnet supply concentration:Niobium-titanium wire production concentrates among three Japanese and European specialty suppliers, creating single-source vulnerability.
- Facility licensing complexity:Germany's national radiation protection authority requires 18-24 month environmental impact assessments that delay commissioning regardless of equipment readiness.
- Linear accelerator substitution:Advanced linac-based stereotactic body radiotherapy systems are capturing lower-complexity cases at one-tenth the capital cost.
Strategic Opportunities
- Underpenetrated US metropolitan markets:Dallas, Atlanta, and Phoenix lack operational proton centers despite population density sufficient to support viable patient volumes.
- Real-time MRI guidance convergence:Integration of 1.5T MRI scanners with proton beam lines is enabling on-table adaptive planning for moving tumors.
- EU MDR transition window:Beam delivery control systems face recertification requirements that favor vendors with established quality management systems.
Industry Challenges
- Medical physicist certification bottleneck:American Board of Radiology proton therapy subspecialty examination capacity constrains staffing for new US installations.
- Legacy cobalt-60 vault retrofit complexity:Converting aging teletherapy bunkers to proton specifications requires structural reinforcement that exceeds original construction documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hadron Therapy Market |
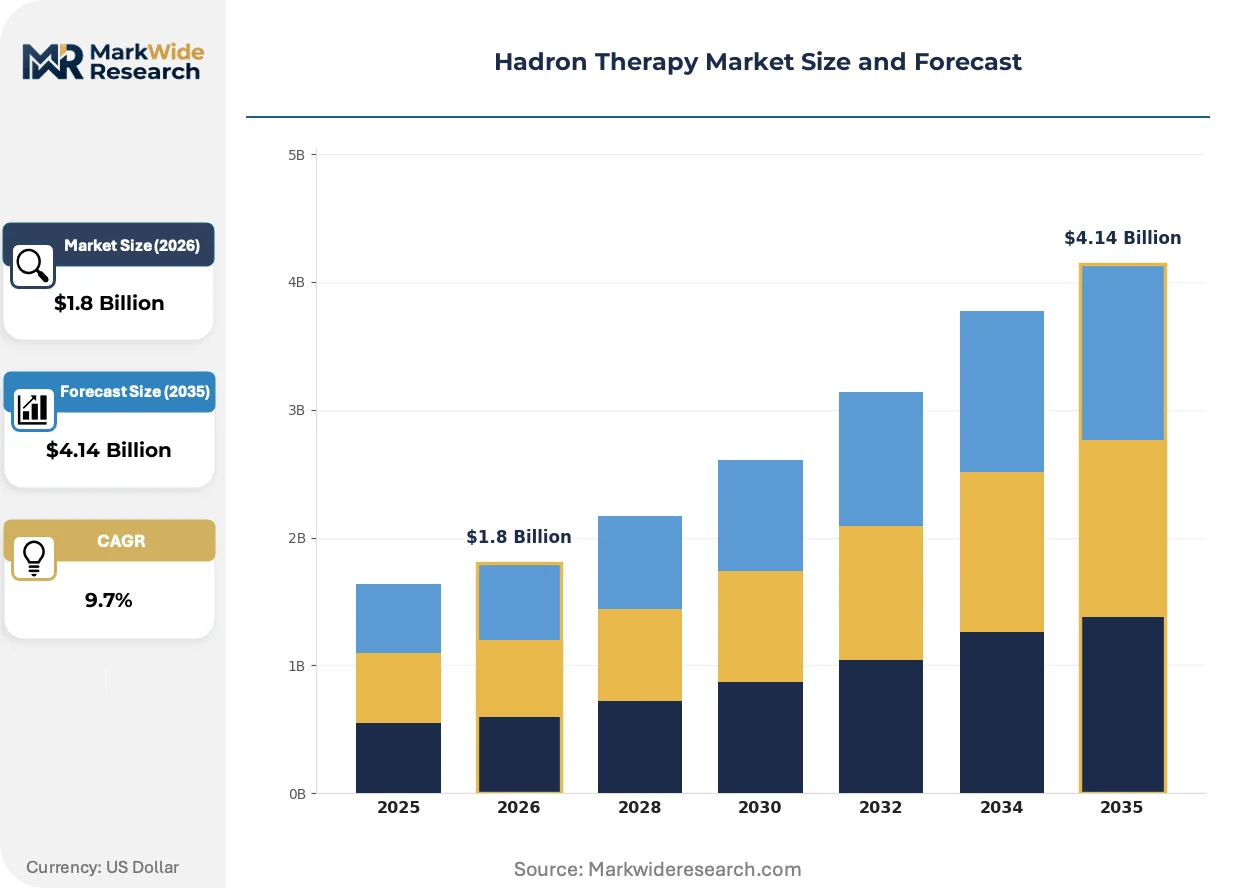
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proton Therapy, Heavy Ion Therapy, Carbon Ion Therapy, Neutron Therapy End User: Hospitals, Cancer Treatment Centers, Research Institutes, Academic Institutions Technology: Synchrotron, Cyclotron, Linear Accelerators, Beam Delivery Systems Application: Oncology, Neurotherapy, Pediatric Treatment, Research |
| Companies Covered | Mevion Medical Systems, Mitsubishi Heavy Industries, Ion Beam Applications, ProTom International, Advanced Oncotherapy, Hitachi, Sumitomo Heavy Industries, Provision Healthcare, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hadron Therapy Market Emerging Trajectories
Particle therapy systems are converging with intra-fraction imaging and artificial intelligence-driven dose calculation, collapsing the latency between patient positioning and beam delivery that previously compromised treatment precision.
Superconducting synchrocyclotron technology is miniaturizing proton sources from warehouse-scale to gantry-integrated dimensions. Community hospital systems are adopting these compact systems to avoid the $150-200 million capital commitments of legacy facilities. This compression is enabling distributed deployment models that place treatment capacity within 50 miles of patient populations rather than concentrating at regional academic hubs.
The EU MDR's tightened clinical evidence requirements for active implantable medical devices are extending conformity assessment timelines for beam delivery control systems. Notified body capacity constraints are forcing manufacturers to front-load clinical validation studies. European proton center procurement cycles are elongating 6-12 months as vendors navigate recertification backlogs.
Hospital purchasing committees are unbundling equipment procurement from long-term service contracts, fragmenting vendor revenue streams that previously locked in 15-year maintenance agreements. Independent service organizations are capturing refurbishment and spare parts markets. This disintermediation is most pronounced in Germany and Japan where installed base density supports third-party technical specialization.
Hadron Therapy Market Segmentation
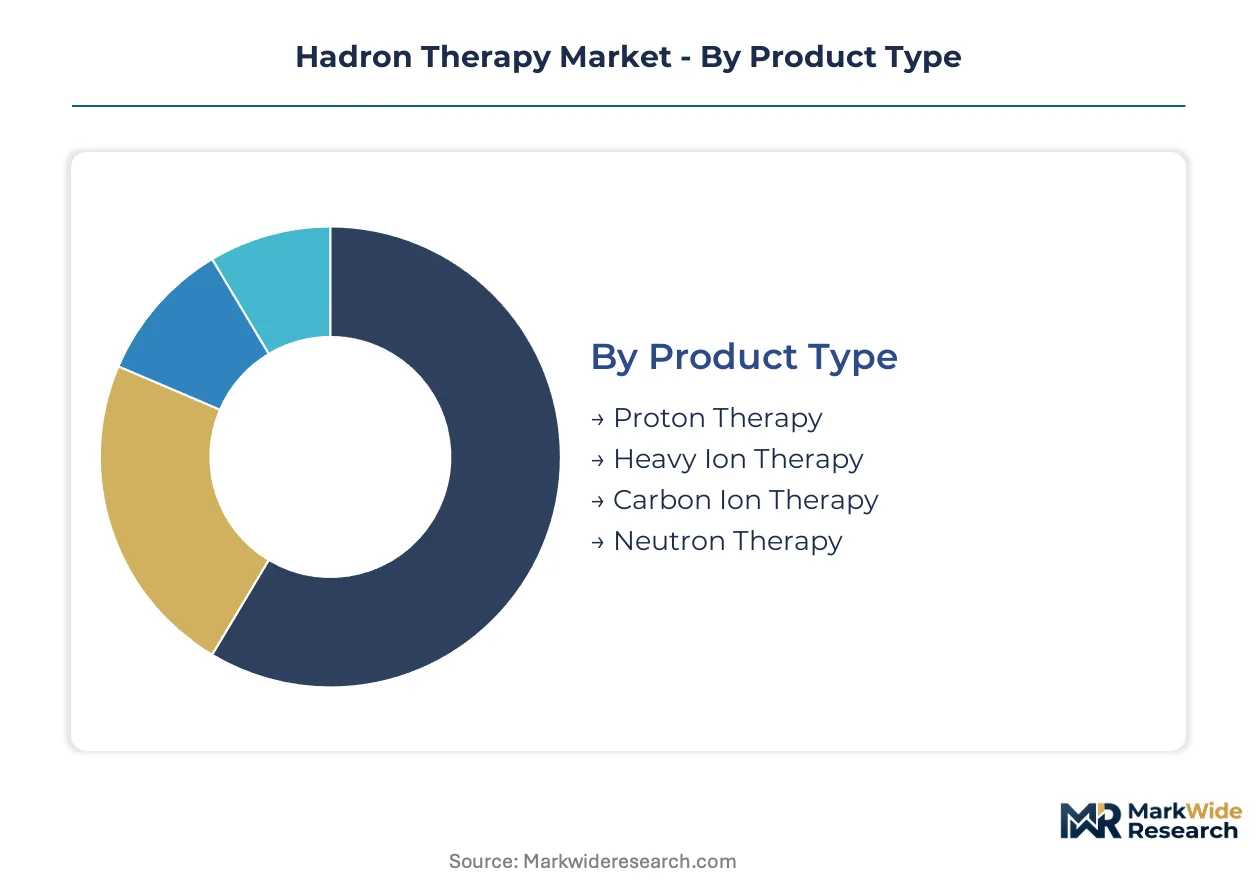
Hadron therapy segmentation reveals distinct capital intensity tiers and reimbursement pathways that determine facility viability. Technology choices lock centers into specific patient populations and service contract structures for decades.
Product Type:
Proton therapy faces intensifying substitution pressure from advanced linear accelerator systems in lower-complexity oncology cases, forcing vendors to defend clinical differentiation through hypofractionation protocols and pediatric indications.
- Proton Therapy:Beam energies of 70–250 MeV deposit dose via the Bragg peak effect, sparing adjacent healthy tissue. Demand concentrates in Germany, Japan, and the United States where operational centers are expanding treatment capacity and PMDA fast-track pathways accelerate pediatric reimbursement eligibility.
- Heavy Ion Therapy:Accelerated particles heavier than protons deliver higher linear energy transfer for radioresistant tumors. Heidelberg and Chiba demonstration centers are validating superior outcomes for skull-base and pelvic malignancies, pulling replication demand across Asia-Pacific and European markets.
- Carbon Ion Therapy:The modality demonstrates steepest expansion trajectory among product types, with Japan's National Institute of Radiological Sciences and Germany's Heidelberg Ion-Beam Therapy Center establishing clinical evidence for radioresistant indications.
- Neutron Therapy:Boron neutron capture therapy applications remain confined to research protocols in limited Japanese and European installations.
Proton therapy anchors the volume base while carbon ion therapy gains share at the steepest rate.
End User:
Capital requirements stratify end users into distinct procurement tiers, with community hospital systems now accessing single-room proton systems that previously demanded academic medical center balance sheets.
- Hospitals:Integrated health systems deploy proton capacity as regional destination services, capturing referral networks across 50-mile catchment radii. Mevion's compact superconducting synchrocyclotron enables community hospital entry without $150–200 million legacy facility commitments.
- Cancer Treatment Centers:Specialized oncology facilities optimize patient throughput through hypofractionated protocols, compressing treatment courses from 30-plus sessions to 5–8 sessions and improving center economics.
- Research Institutes:Beam time allocation prioritizes clinical trial endpoints for FDA and PMDA submission pathways.
- Academic Institutions:Training pipeline constraints for certified medical physicists limit expansion velocity regardless of equipment commissioning schedules.
Hospitals dominate installed capacity while cancer treatment centers expand most quickly through distributed deployment models.
Technology:
Superconducting magnet supply concentration among three Japanese and European specialty suppliers creates technology selection risk that extends commissioning timelines regardless of accelerator readiness.
- Synchrotron:Large-circumference facilities deliver variable beam energies through slow extraction, enabling intensity-modulated proton therapy. Germany's national radiation protection authority requires 18–24 month environmental impact assessments that delay commissioning.
- Cyclotron:Continuous beam output supports higher dose rates and simpler vault shielding requirements. Compact superconducting designs compress footprints from football-field dimensions to single-room installations, collapsing capital barriers.
- Linear Accelerators:Advanced linac-based stereotactic body radiotherapy systems capture lower-complexity cases at one-tenth the capital cost of proton alternatives.
- Beam Delivery Systems:Real-time imaging integration and adaptive planning software capture concentrated margin pools as vendors differentiate through spot-scanning precision for complex tumor geometries.
Cyclotron technology anchors current deployment volume while beam delivery systems command premium pricing through software differentiation.
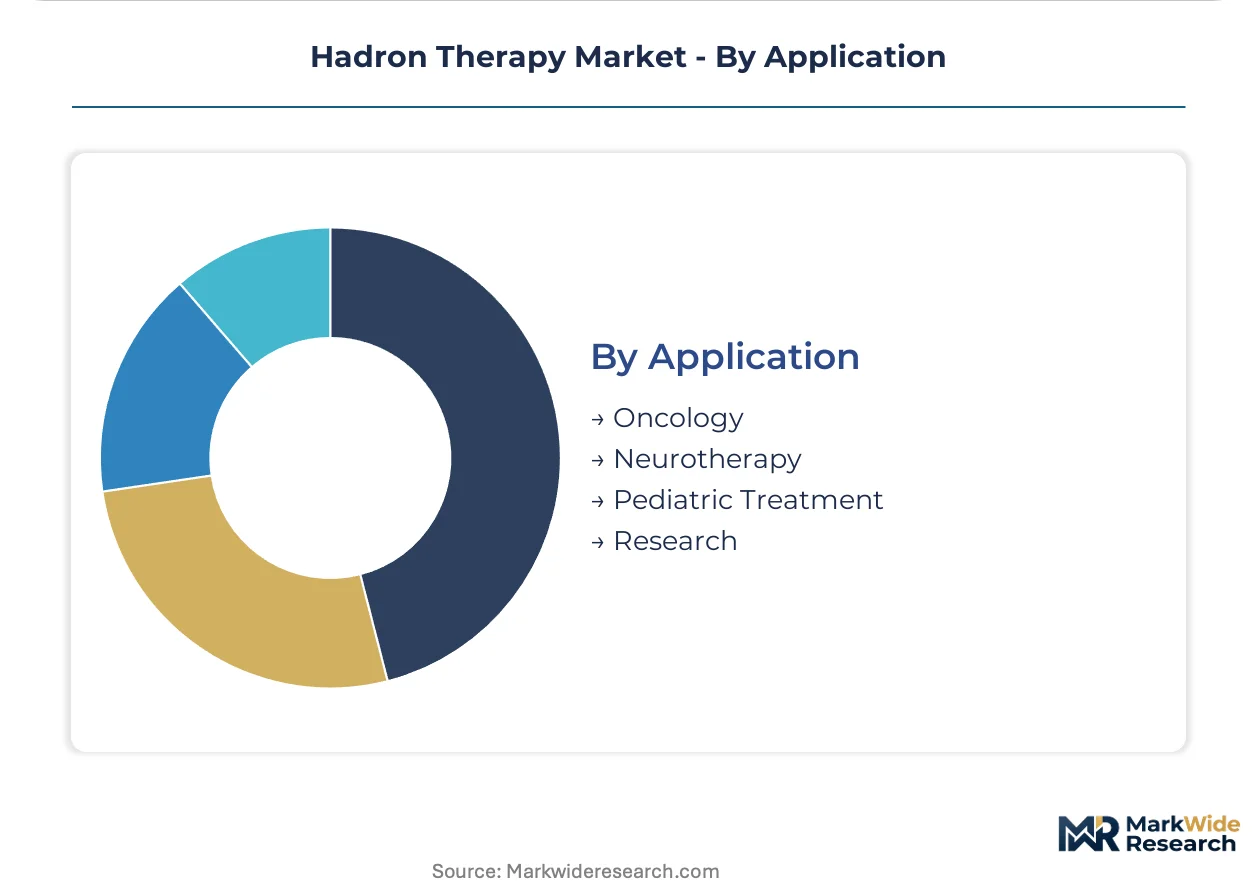
Application:
Reimbursement pathway maturity determines application prioritization, with pediatric oncology securing accelerated regulatory timelines that adult indications lack.
- Oncology:Solid tumor indications drive treatment volume, with prostate, lung, and head-and-neck malignancies representing core reimbursable categories in US Medicare and German statutory health insurance frameworks.
- Neurotherapy:Skull-base and central nervous system tumors exploit the Bragg peak's tissue-sparing properties where critical structure proximity limits photon therapy tolerance.
- Pediatric Treatment:Japan's PMDA fast-track oncology pathway accelerates approval timelines, expanding treatable patient populations and center reimbursement eligibility for medulloblastoma and rhabdomyosarcoma protocols.
- Research:Beam time allocation supports carbon ion radiobiology studies and FLASH ultra-high dose rate investigations.
Oncology anchors the volume base while pediatric treatment gains share at the steepest rate through regulatory preference pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands pricing premiums for carbon ion therapy that Japanese proton centers cannot replicate, while United States reimbursement arbitrage attracts cross-border patient flows from Canada and Mexico.
United States
Metropolitan clusters in Dallas, Atlanta, and Phoenix lack operational proton centers despite population density sufficient to support viable patient volumes. FDA oversight of accelerator safety and clinical trial endpoints shapes market access timelines for new indications. MD Anderson Cancer Center in Houston anchors the Southwest treatment corridor with expanding pediatric oncology protocols.
Japan
PMDA fast-track oncology pathways accelerate approval timelines for pediatric proton indications, expanding treatable patient populations and center reimbursement eligibility. METI industrial policy supports domestic superconducting magnet supply chains that feed accelerator manufacturing. Chiba's National Institute of Radiological Sciences validates carbon ion outcomes for radioresistant skull-base tumors.
Germany
Heidelberg Ion-Beam Therapy Center demonstrates superior outcomes for pelvic malignancies, pulling replication demand across European markets. The national radiation protection authority requires 18-24 month environmental impact assessments that delay commissioning regardless of equipment readiness. Bavaria's clinical research cluster anchors German-language training pipelines for certified medical physicists.
Switzerland
Swissmedic facility licensing enforces personnel certification standards that extend procurement cycles for beam delivery control systems. EU MDR transition requirements add compliance layers for European installations through notified body capacity constraints. Geneva's cross-border healthcare infrastructure captures French and Italian patient referrals for specialized neurotherapy protocols.
Hadron Therapy Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with superconducting synchrocyclotron specialists commanding premium positioning against conventional cyclotron fabricators. The vendor base stratifies across three tiers: integrated industrial conglomerates with nuclear engineering heritage, pure-play proton therapy system specialists, and emerging compact-system disruptors targeting community hospital entry. Two dominant competitive moves are reshaping positioning: long-term service contract unbundling that fragments legacy revenue streams, and real-time imaging integration that captures margin pools through software differentiation.
Among integrated industrial conglomerates, Mitsubishi Heavy Industries and Hitachi occupy positions defined by gantry rotational systems and spot-scanning precision. Mevion Medical Systems exemplifies the compact-system disruptor archetype, compressing facility footprints to enable distributed deployment models within 50 miles of patient populations rather than academic hub concentration.
| Leading Market Players |
|---|
| Mevion Medical Systems |
| Mitsubishi Heavy Industries |
| Ion Beam Applications |
| ProTom International |
| Advanced Oncotherapy |
| Hitachi |
| Sumitomo Heavy Industries |
| Provision Healthcare |
| Siemens Healthineers |
| Others |
Supply Flow & Price Mechanics
Eighteen-month lead times for niobium-titanium superconducting wire translate directly into pricing power concentration among Japanese and European specialty suppliers, compressing margins for proton center developers while inflating vault construction contingencies.
Pricing Analysis
German carbon ion therapy commands substantial premiums over Japanese proton centers due to superior outcomes documentation and restricted facility licensing. Three-tier pricing structure across premium, standard, and economy levels separates Heidelberg-style research-integrated centers from community hospital single-room installations and refurbished legacy systems. Price differentiation rests on certification grade under EU MDR and FDA quality system regulations, with after-sales service bundling capturing fifteen-year maintenance revenue streams. Cost compression in the standard tier is intensifying because independent service organizations are unbundling refurbishment markets.
Supply Chain Analysis
Japan and Germany anchor superconducting magnet fabrication, with METI industrial policy supporting domestic niobium-titanium wire production that feeds accelerator manufacturing. Raw material dependencies center on niobium ore concentrates from Brazil and Canada, helium-3 isotope supply for cryogenic cooling systems, and precision-cast vacuum chambers from specialized European foundries. Single-source vulnerability in superconducting wire production creates supply chain risk that extends commissioning timelines regardless of equipment readiness. Distribution runs through direct vendor-hospital procurement committees, with GPO contracts emerging in United States metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hadron therapy operates as a defensive-moat market where regulatory entrenchment through FDA accelerator safety certification and EU MDR beam delivery control system requirements creates prohibitive switching costs for incumbent vendors.
For Market Incumbents: Compound installed base advantages through long-term service contract extensions and accelerator refurbishment programs that lock out independent service organizations. Ion Beam Applications sustains market position by integrating real-time imaging software with spot-scanning hardware, defending against compact cyclotron disruptors like Mevion Medical Systems. Prioritize backward integration into superconducting magnet supply chains to mitigate niobium-titanium wire concentration risk. For New Entrants and Emerging Players: Differentiate on hypofractionated protocol software and pediatric indication specialization that commands reimbursement premiums under PMDA fast-track pathways. Underpenetrated United States metropolitan markets in Dallas, Atlanta, and Phoenix present the most penetrable geography, with community hospital systems seeking single-room proton installations below legacy capital thresholds. Pursue hospital system partnership go-to-market angles that bundle equipment procurement with physicist training pipeline commitments. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture infrastructure play because FDA and PMDA certification timelines extend competitive moats beyond typical medical device cycles. Acquisition target archetypes include compact superconducting synchrocyclotron specialists with gantry-integrated footprints and software-defined beam delivery control vendors. Watch PMDA pediatric indication expansion velocity as the inflection signal for reimbursement arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Compact System FDA Submission | Accelerated 510(k) pathways for single-room proton installations reduce capital barriers for community hospital entry. |
| EU MDR Recertification Investment | Beam delivery control systems require notified body validation that favors vendors with established quality management systems. |
| Hospital System Partnership | Integrated health networks in underpenetrated metropolitan markets capture 50-mile catchment radii for regional destination services. |
| Real-Time MRI Integration | 1.5T scanner convergence with proton beam lines enables on-table adaptive planning for moving tumors. |
| Medical Physicist Training Pipeline | American Board of Radiology subspecialty examination capacity constraints limit staffing for new installations regardless of equipment readiness. |
Methodological Framework
The analysis maps proton therapy, carbon ion therapy, heavy ion therapy, and neutron therapy modalities, each validated through medical physicists, hospital purchasing committee members, accelerator manufacturing engineers, and GPO contracts managers. Primary interviews with proton center clinical directors and vendor service operations executives combined with secondary validation from FDA 510(k) filings, PMDA approval databases, EU MDR notified body registers, and hospital procurement databases. Bottom-up facility commissioning timelines and top-down national reimbursement pathway analysis provided triangulation across data sources.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled technology type, end-user capital tier, application indication, and regional regulatory cluster segmentation dimensions. CAGRs derived from facility installation pipeline tracking and reimbursement eligibility expansion curves, with carbon ion modality replication demand and hypofractionated protocol adoption rates serving as key forecast inputs.
Material uncertainties — PMDA fast-track pathway revisions, superconducting magnet supply disruptions, and linear accelerator substitution thresholds — sit outside the modeled envelope. Forecasts reflect assumptions regarding stable reimbursement frameworks and physicist certification pipeline expansion. Recalibration cycles align with material shifts in regulatory approval timelines and compact system commissioning velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Global Nasopharyngeal Cancer Market
Oncology
Particle Therapy Systems Market
Oncology
America Cancer Immunotherapy Market
Oncology
Pancreatic Cancer Treatment Market
Oncology
Kinase Inhibitors for Cancer Treatment Market
Oncology
Peritoneal Cancer Treatment Market
Oncology
Stomach Cancer Treatment Market
Oncology
Pancreatic Cancer Therapeutics Market
Oncology
Sterile Oncology Injectable Market
Oncology
Oncology Apoptosis Modulators Market
Oncology
Middle East and Africa Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Breast Cancer Liquid Biopsy Market
Oncology
PD1 Non-Small Cell Lung Cancer Treatment Market
Oncology
South Korea Radiotherapy Market
Oncology
Breast Cancer Therapy Market
Oncology
Germany Radiotherapy Market