
 Radiotherapy Market | 2026-2036
Radiotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Radiotherapy Market Analysis
The EU Medical Device Regulation is realigning compliance burdens for radiotherapy equipment manufacturers across European cancer treatment facilities. Varian Medical Systems leverages its proton therapy installed base to sustain service revenue streams. Elekta AB anchors its position through specialized linear accelerator configurations for emerging markets. Siemens Healthineers competes by integrating diagnostic imaging with radiation delivery platforms.
Radiotherapy encompasses the clinical use of ionizing radiation to destroy malignant cells, typically delivered via linear accelerators generating 6-25 MV photon beams or through proton and heavy ion beams that exploit the Bragg peak to spare adjacent healthy tissue. External Beam Radiation technology dominates current installations, while Proton Therapy represents the fastest-expanding segment as capital costs decline and clinical evidence accumulates for pediatric and central nervous system indications. Linear Accelerators remain the mature revenue backbone, whereas Stereotactic Techniques command premium positioning due to shorter fractionation schedules and higher reimbursement per course.
The FDA governs device clearance and software-as-medical-device classification for AI-enhanced treatment planning, while the EMA and notified bodies enforce CE marking and post-market surveillance under MDR across European markets. Japan's PMDA maintains distinct technical standards for heavy ion therapy systems that shape export eligibility for manufacturers. Stakeholders must weigh capital intensity against clinical differentiation as proton and carbon ion modalities challenge conventional photon economics.
Market Dynamics
Proton therapy capital costs are compressing faster than reimbursement parity can expand, forcing manufacturers to defend service revenue through software-locked treatment planning ecosystems rather than hardware margins alone.
Growth Catalysts
- MDR Compliance Deadlines:European cancer centers are accelerating replacement cycles for legacy linear accelerators ahead of full EU Medical Device Regulation enforcement, pulling forward demand that would otherwise spread across later years.
- Pediatric Oncology Protocols:Bragg peak physics is displacing photon beams for central nervous system tumors in children, with proton therapy now standard-of-care at major pediatric hospitals in the United States and Germany.
- AI-Enhanced Contouring:Automated segmentation algorithms are reducing planning time from hours to minutes, enabling treatment centers to expand patient throughput without proportional staffing increases.
Market Restraints
- Isotope Supply Concentration:Molybdenum-99 production clusters at aging research reactors in the Netherlands and South Africa, creating vulnerability for gamma knife maintenance and diagnostic imaging calibration.
- Proton Center Economics:Single-facility capital requirements exceed $200 million with decade-long breakeven timelines, restricting viable addressable markets to metropolitan areas with payer density above 3 million covered lives.
- Reimbursement Compression:CMS site-neutral payment policies are eroding hospital outpatient department premiums for stereotactic body radiation therapy, compressing per-fraction revenue.
Strategic Opportunities
- Carbon Ion Therapy:Japan's PMDA approval pathway for heavy ion systems is creating export eligibility for European manufacturers seeking differentiation beyond proton modalities.
- Mobile Linear Accelerators:Truck-mounted radiotherapy units are penetrating rural markets in India and Brazil where fixed infrastructure investment is economically unviable.
- Software-as-Medical-Device:FDA 510(k) clearance for AI-driven adaptive planning is opening recurring revenue streams independent of hardware replacement cycles.
Industry Challenges
- Medical Physics Talent Scarcity:Board-certified dosimetrists and radiation physicists are concentrated at academic medical centers, leaving community hospitals dependent on teleradiology services with latency constraints.
- Legacy System Interoperability:DICOM-RT data migration from 1990s-era planning systems to cloud-native architectures requires manual recontouring that disrupts active patient schedules.
- Supply Chain Reconfiguration:Tungsten collimator manufacturing has shifted from German specialty metalworkers to Chinese powder metallurgy suppliers, introducing quality variance into beam-shaping precision.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiotherapy Market |
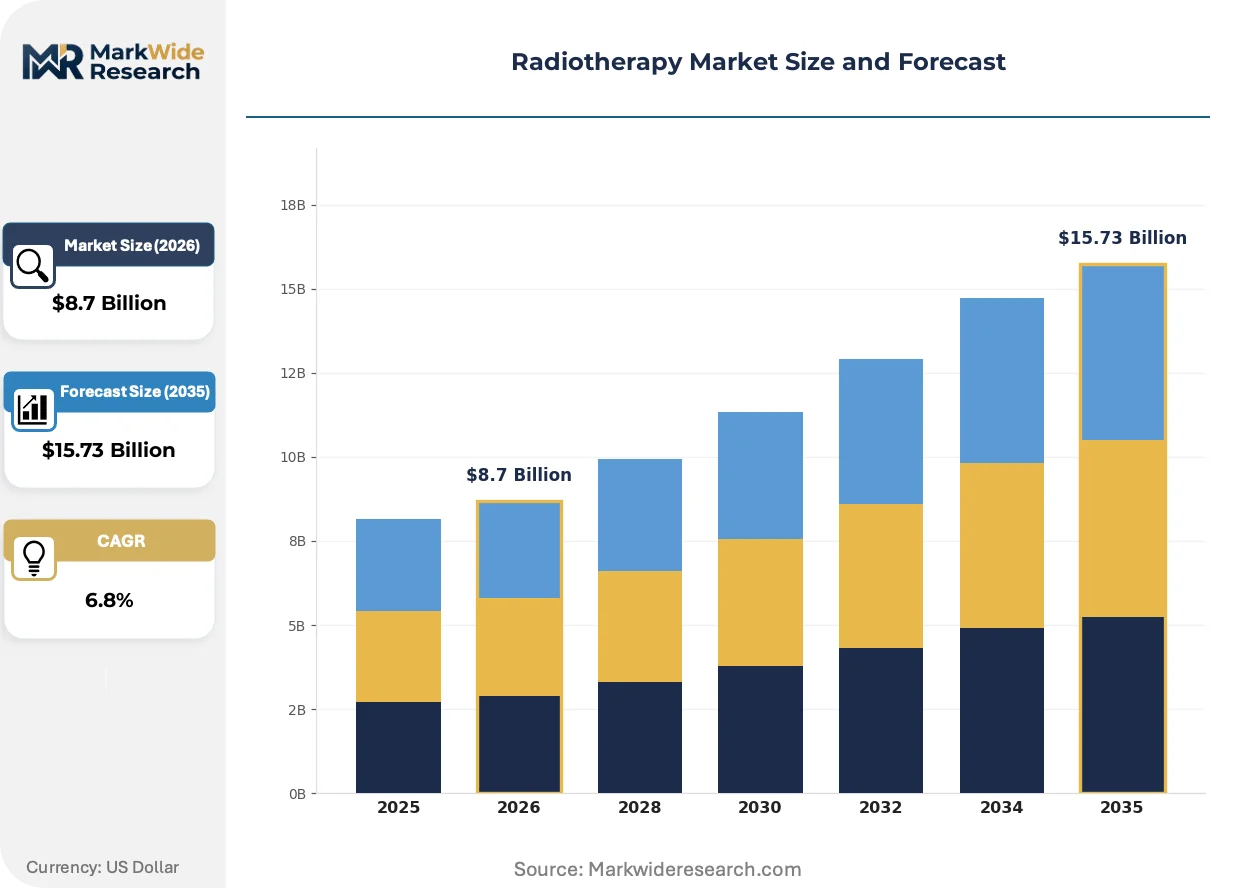
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
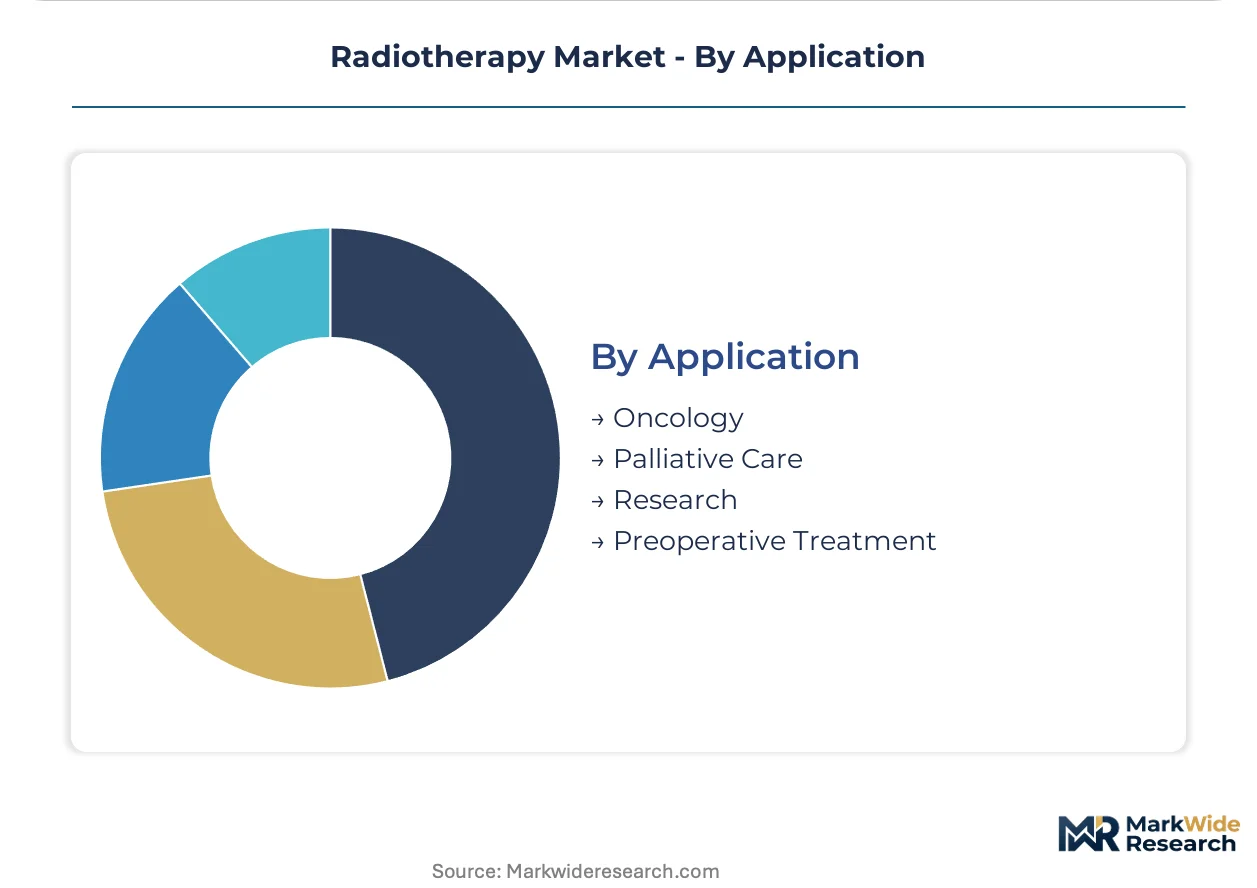
| Segmentation | Product Type: Linear Accelerators, Brachytherapy, Radiosurgery Systems, Ion Therapy Systems Technology: External Beam Radiation, Internal Radiation, Proton Therapy, Stereotactic Techniques End User: Hospitals, Clinics, Research Centers, Cancer Treatment Facilities Application: Oncology, Palliative Care, Research, Preoperative Treatment |
| Companies Covered | Varian Medical Systems, Elekta AB, Accuray Incorporated, Siemens Healthineers, GE Healthcare, IBA, Koninklijke Philips N.V., Hitachi High-Tech Corporation, Canon Medical Systems Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiotherapy Market Emerging Trajectories
Adaptive radiotherapy workflows are compressing the gap between simulation and treatment delivery, with daily imaging reshaping how clinicians respond to tumor shrinkage and anatomical shifts during fractionated courses.
Magnetic resonance-guided linear accelerators are consolidating real-time soft-tissue visualization with megavoltage beam delivery. Academic medical centers in the United States and the Netherlands are adopting MR-linac configurations for abdominal and pelvic sites where motion management is critical. This convergence is consolidating vendor portfolios as standalone imaging and radiation companies pursue integrated platform strategies.
The EU Medical Device Regulation is elevating post-market surveillance burdens for treatment planning software. Manufacturers must now maintain clinical evidence registries across CE-marked installations, with notified bodies demanding prospective safety data for algorithm updates. Radiation oncology departments in France and Italy are delaying procurement decisions until MDR transition timelines clarify, compressing near-term order visibility.
Hospital procurement committees are unbundling service contracts from hardware purchases, with third-party independent service organizations capturing maintenance revenue previously captive to original equipment manufacturers. This shift is most visible in Germany's university hospital networks, where multi-vendor fleet standardization is reducing spare parts inventory costs and expanding technician cross-training requirements.
Radiotherapy Market Segmentation
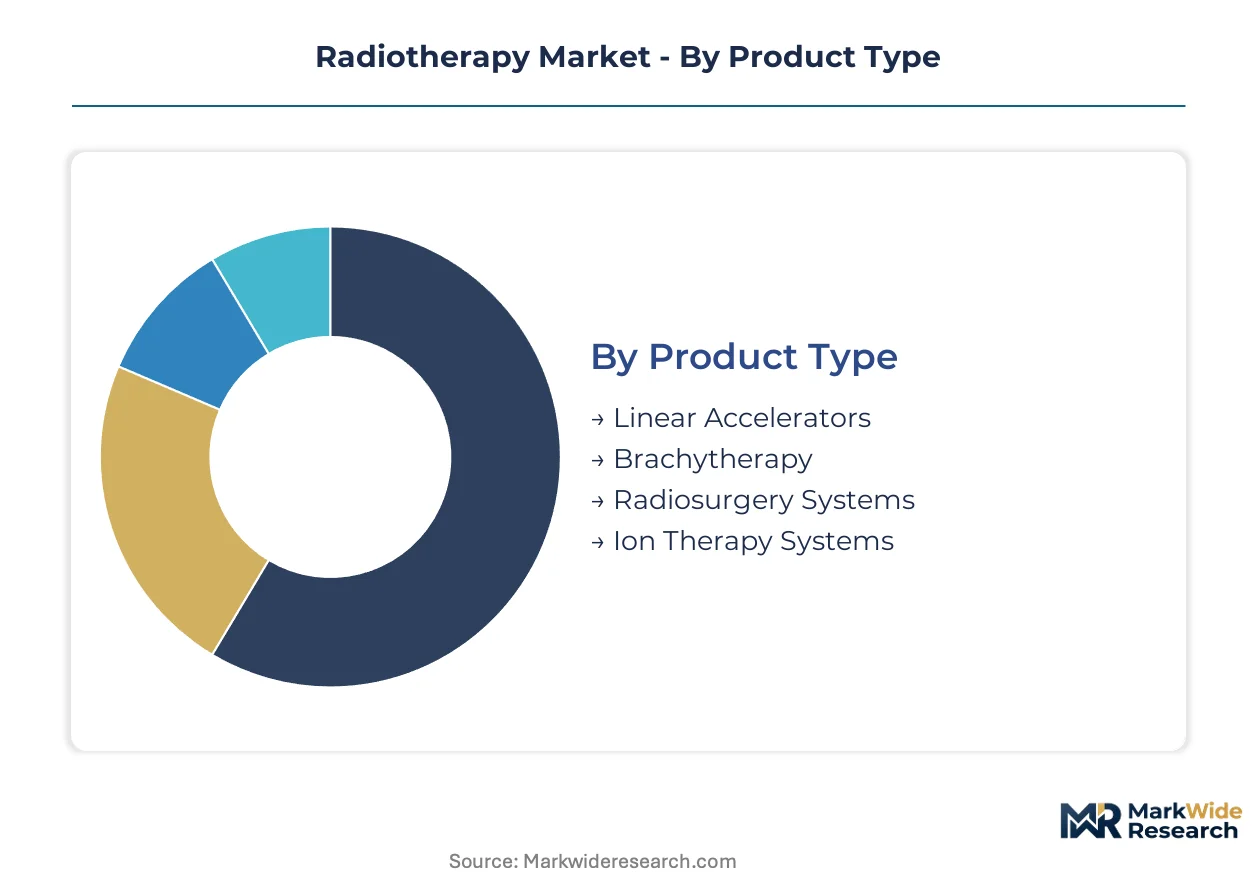
Segmentation in radiotherapy reveals how capital intensity, clinical complexity, and reimbursement economics fragment purchasing authority across distinct buyer profiles. Equipment selection varies sharply between academic medical centers pursuing proton therapy differentiation and community hospitals optimizing photon beam throughput.
Product Type:
Capital deployment cycles and service revenue potential drive procurement committee priorities across hardware categories.
- Linear Accelerators:These devices generate 6-25 MV photon beams through microwave-accelerated electrons striking high-density targets. Demand concentrates in United States community hospitals and German oncology networks seeking replacement of cobalt-60 units ahead of EU MDR enforcement deadlines.
- Ion Therapy Systems:Proton and carbon ion accelerators exploit the Bragg peak to deposit energy at precise tissue depths. Pediatric oncology departments at MD Anderson Cancer Center and Heidelberg University Hospital anchor installed base expansion as clinical evidence accumulates for central nervous system indications.
- Brachytherapy:Sealed radioactive sources deliver localized dose via interstitial or intracavitary placement.
- Radiosurgery Systems:Gamma Knife and CyberKnife platforms enable single-fraction intracranial treatment without invasive incision.
Volume sits with Linear Accelerators; growth tilts toward Ion Therapy Systems.
Technology:
Reimbursement per fraction and treatment duration reshape technology adoption curves across delivery modalities.
- External Beam Radiation:Conventional photon therapy from linear accelerators remains the dominant installed modality. United States hospital outpatient departments and National Health Service trusts in England sustain replacement demand as legacy systems age beyond 15-year service lifecycles.
- Proton Therapy:Pencil beam scanning and intensity-modulated proton therapy reduce integral dose to organs at risk. New York Proton Center and University of Florida Health Proton Therapy Institute exemplify the metropolitan concentration required to justify $200 million-plus facility investments.
- Internal Radiation:Brachytherapy and systemic radiopharmaceutical administration target malignancies from within tissue compartments.
- Stereotactic Techniques:SBRT and SRS deliver ablative doses across 1-5 fractions with sub-millimeter precision.
External Beam Radiation commands installed base dominance; Proton Therapy exhibits the steepest expansion trajectory.
End User:
Patient volume thresholds and payer mix density determine viable addressable markets for capital equipment vendors.
- Hospitals:Academic medical centers and integrated delivery networks consolidate proton therapy and MR-linac investments. United States News-ranked cancer centers and German university hospitals anchor premium technology adoption as they compete for complex case referrals.
- Cancer Treatment Facilities:Freestanding radiation oncology centers unbundle from hospital systems to capture site-specific reimbursement advantages. Texas Oncology and 21st Century Oncology operate multi-facility photon beam networks optimized for throughput economics.
- Clinics:Smaller-volume sites rely on teleradiology physics support and extended service contracts.
- Research Centers:National laboratories and proton therapy research consortia advance beam delivery physics.
Hospitals retain capital deployment leadership; Cancer Treatment Facilities gain share fastest through site-neutral payment arbitrage.
Application:
Clinical indication and curative intent reshape treatment planning complexity and reimbursement coding.
- Oncology:Curative and adjuvant radiotherapy for solid malignancies drives procedure volume. United States National Cancer Institute-designated centers and French comprehensive cancer centers prioritize adaptive planning workflows for lung and prostate sites.
- Palliative Care:Pain and symptom control for metastatic disease requires rapid treatment initiation. Community hospitals in England and hospices in Germany deploy single-fraction bone metastasis protocols to reduce patient travel burden.
- Research:Clinical trials for hypofractionation and combination immunoradiotherapy protocols.
- Preoperative Treatment:Neoadjuvant radiotherapy to downstage locally advanced tumors prior to surgical resection.
Oncology dominates procedure volume; Palliative Care expands most quickly as population aging concentrates metastatic case burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heidelberg anchors proton therapy infrastructure development in Germany, with the Heidelberg Ion Beam Therapy Center serving as a reference site for European heavy ion adoption. Academic medical centers across three continents are expanding external beam programs as reimbursement frameworks tighten and regulatory deadlines accelerate replacement cycles.
United States
MD Anderson Cancer Center and Memorial Sloan Kettering Cancer Center anchor proton therapy demand for pediatric and central nervous system indications. FDA 510(k) pathways for AI-enhanced treatment planning systems are elevating software validation requirements for domestic manufacturers. The New York Proton Center and University of Florida Health Proton Therapy Institute exemplify metropolitan concentration necessary to justify capital-intensive facility investments.
Germany
University hospitals in Munich and Berlin are replacing legacy linear accelerators ahead of full EU Medical Device Regulation enforcement deadlines. Heidelberg University Hospital maintains Europe's most extensive carbon ion therapy installation, creating export eligibility benchmarks for heavy ion system manufacturers. The country's national pharmaceutical regulator enforces post-market surveillance for algorithm updates through notified body oversight.
China
Proton therapy center construction is accelerating in Shanghai and Beijing as capital costs decline and clinical evidence accumulates for precision indications. The National Medical Products Administration maintains distinct technical standards for heavy ion therapy systems that shape domestic procurement eligibility. Yangtze River Delta medical clusters are integrating diagnostic imaging with radiation delivery platforms through integrated hospital networks.
Japan
The Pharmaceuticals and Medical Devices Agency approval pathway for heavy ion systems has established reference protocols for carbon ion therapy export markets. National Institute of Radiological Sciences facilities in Chiba anchor clinical research for hypofractionation protocols. Kanto region academic centers are adopting magnetic resonance-guided linear accelerator configurations for abdominal and pelvic sites where motion management is critical.
India
Mobile linear accelerator units are penetrating rural markets in Maharashtra and Karnataka where fixed infrastructure investment is economically unviable. The Central Drugs Standard Control Organization regulates device importation and software-as-medical-device classification for adaptive planning systems. Tata Memorial Centre in Mumbai anchors pediatric oncology protocols that are displacing photon beams for central nervous system tumors in children.
Radiotherapy Market Vendor Landscape
Premium-margin players sit above commodity-margin players across service contract bundling and software-locked ecosystems. The vendor base concentrates around integrated platform specialists and standalone equipment fabricators with divergent strategies for recurring revenue capture. Three archetypes dominate: proton therapy system integrators, linear accelerator manufacturers with diagnostic imaging ties, and software-native adaptive planning vendors. M&A activity targets treatment planning algorithm capabilities, while geographic expansion focuses on emerging market service infrastructure.
Among diversified health technology conglomerates, Siemens Healthineers and GE Healthcare exemplify platform integration strategies that combine diagnostic imaging with radiation delivery. Varian Medical Systems occupies a position within the proton therapy installed base tier, sustaining service revenue through specialized linear accelerator configurations. Elekta AB anchors the dedicated radiotherapy equipment segment, with its Swedish corporate structure reflecting European engineering concentration in precision beam delivery systems.
| Leading Market Players |
|---|
| Varian Medical Systems |
| Elekta AB |
| Accuray Incorporated |
| Siemens Healthineers |
| GE Healthcare |
| IBA |
| Koninklijke Philips N.V. |
| Hitachi High-Tech Corporation |
| Canon Medical Systems Corporation |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between MDR-compliant systems and legacy equipment manifests in both pricing power and supply chain sourcing strategies. Premium-tier vendors command service-locked contracts through software-validated treatment planning ecosystems, while commodity-tier manufacturers compete on hardware margins with limited aftermarket capture.
Pricing Analysis
Throughput-based pricing anchors proton therapy contracts, with reimbursement per fraction tied to patient volume guarantees rather than capital depreciation schedules. Three-tier pricing structure across premium, standard, and economy levels separates MR-linac configurations from conventional linear accelerators and refurbished cobalt-60 units. Cost compression in photon beam systems is intensifying because hospital procurement committees are unbundling service contracts from hardware purchases. Community hospitals exhibit highest price sensitivity, whereas academic medical centers prioritize clinical differentiation over per-unit economics.
Supply Chain Analysis
Dual-sourcing requirements for tungsten collimators and microwave power tubes mandate multi-supplier qualification across German specialty metalworkers and Chinese powder metallurgy producers. Manufacturing concentration in Sweden, Germany, and the United States feeds from rare earth magnet supplies and high-purity copper for accelerator cavities. Single-source vulnerability persists for Molybdenum-99 isotope production clustered at aging research reactors in the Netherlands and South Africa. Distribution runs through original equipment manufacturer service networks and emerging third-party independent service organizations capturing maintenance revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around software-locked ecosystem providers as EU MDR compliance costs force smaller hardware fabricators toward exit or acquisition.
For Market Incumbents: Deploy adaptive planning software as the primary retention lever. Lock service revenue through cloud-native treatment planning architectures that raise switching costs for hospital customers. Deepen backward integration into tungsten collimator manufacturing to offset Chinese supplier quality variance. Counter third-party independent service organizations by embedding predictive maintenance algorithms requiring proprietary hardware access. For New Entrants and Emerging Players: Enter via mobile linear accelerator deployment for rural India and Brazil where fixed infrastructure investment is economically unviable. Target cancer treatment facilities pursuing site-neutral payment arbitrage through unbundled photon beam networks. Capture share in carbon ion therapy as European manufacturers seek differentiation beyond proton modalities. Pursue FDA 510(k) clearance for AI-driven adaptive planning to open recurring revenue streams independent of hardware replacement cycles. For Investors and Strategic Acquirers: Re-rating potential sits with software-native adaptive planning vendors given FDA 510(k) pathway expansion for AI-enhanced contouring algorithms. Long-term viability favors platforms combining diagnostic imaging integration with radiation delivery rather than standalone equipment fabricators. Target acquisition archetype: treatment planning algorithm specialists with installed base integration capabilities. Monitor proton therapy center breakeven timelines as the signal to watch for capital deployment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Software-as-Medical-Device Development | FDA 510(k) clearance for AI-driven adaptive planning opens recurring revenue streams independent of hardware cycles. |
| Proton Therapy Center Partnership | Metropolitan concentration requirements at MD Anderson and Memorial Sloan Kettering justify $200 million-plus facility investments. |
| MDR Compliance Certification | CE marking under EU Medical Device Regulation elevates post-market surveillance burdens that compress near-term order visibility. |
| Mobile Linear Accelerator Deployment | Truck-mounted units penetrate rural Maharashtra and Karnataka where fixed infrastructure investment is economically unviable. |
| Carbon Ion Therapy Export Eligibility | Japan's PMDA approval pathway creates differentiation benchmarks for European heavy ion system manufacturers. |
Methodological Framework
Document review covered FDA 510(k) filings, EU MDR notified body guidance, and hospital procurement databases, complemented by interviews with radiation oncology department heads, biomedical engineers, GPO contracts managers, and medical physics specialists. Secondary sources included CMS Medicare reimbursement data, proton therapy center financial disclosures, and customs records for linear accelerator component trade flows. Bottom-up installed base estimates were triangulated against top-down capital expenditure projections across the analysis window.
Cross-referencing historical replacement cycle patterns with expert panel input on MDR transition timelines shaped the forecast framework. Segmentation dimensions modeled include product type, technology modality, end-user facility tier, and clinical application across the projection horizon. CAGRs were derived from capital deployment trajectories and reimbursement policy shifts. Industry-specific inputs incorporated proton therapy clinical evidence accumulation rates and AI-enhanced planning adoption curves.
Revisions become necessary when EU MDR enforcement timelines accelerate, proton therapy reimbursement parity expands faster than capital cost compression, or isotope supply disruptions from aging research reactors materialize. Deviation in hospital procurement committee unbundling of service contracts would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Gynecological Cancers Market
Oncology
Radiation Therapy Software Market
Oncology
North America Veterinary Oncology Market
Oncology
Lung Cancer Treatment Market
Oncology
Oncology Market
Oncology
Radiation Oncology Market
Oncology
Gallbladder Cancer Treatment Market
Oncology
Bone Metastasis Market
Oncology
North America Tumor Ablation Market
Oncology
Immuno-Oncology Market
Oncology
Hadron Therapy Market
Oncology
North America Proton Therapy Market
Oncology
Asia-Pacific Radiation Oncology Market
Oncology
Solid Tumor Market
Oncology
Ovarian Cancer Market
Oncology
South Korea Radiotherapy Market