
 Oncology Apoptosis Modulators Market | 2026-2036
Oncology Apoptosis Modulators Market Size, Share, and Industry Trends Forecast 2026-2036
Oncology Apoptosis Modulators Market Analytics
The EU Green Deal's pharmaceutical sustainability requirements is pivoting oncology drug manufacturers toward greener synthesis routes for apoptosis modulators. AbbVie Inc. leverages its venetoclax manufacturing expertise to sustain leadership in Bcl-2 inhibitor supply chains. Roche Holding AG anchors European production capacity through specialized biologics facilities in Switzerland and Germany. Bristol-Myers Squibb competes on checkpoint-apoptosis combination portfolios across North American and Asian trial networks.
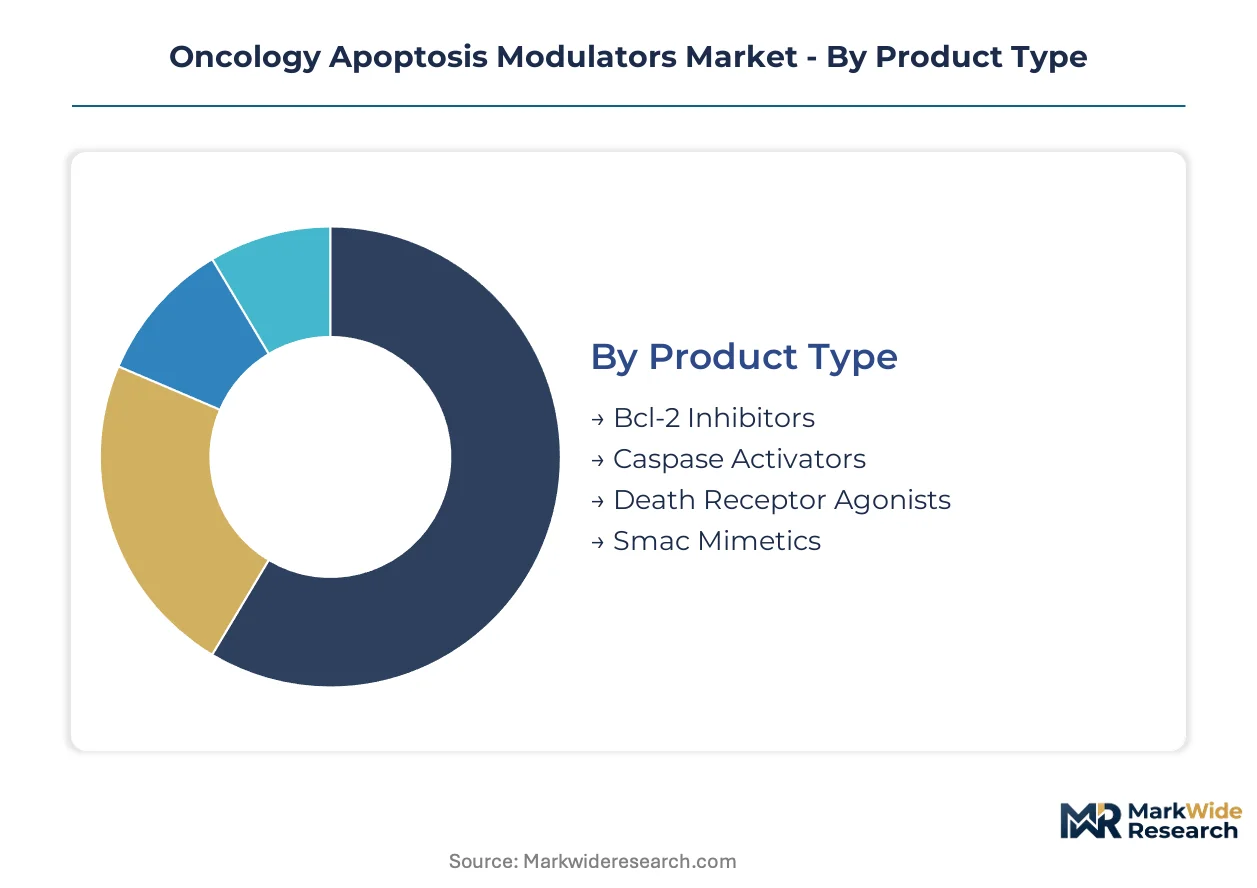
Oncology apoptosis modulators comprise small molecules and biologics that restore programmed cell death in malignant tissues by inhibiting anti-apoptotic proteins or activating pro-apoptotic caspase cascades, typically formulated for intravenous or oral delivery at dose ranges determined by tumor type and patient biomarker profiles. Bcl-2 inhibitors occupy the largest revenue share due to established venetoclax formulations in hematologic malignancies, while caspase activators represent the fastest-expanding category as next-generation agents enter Phase II trials for solid tumors. Death receptor agonists concentrate in research laboratory procurement, reflecting their earlier-stage clinical positioning.
FDA accelerated approval pathways, EMA conditional marketing authorization, and China's NMPA breakthrough therapy designation collectively compress development timelines and reshape competitive entry dynamics for apoptosis-targeted agents. These frameworks reward biomarker-defined patient subsets, pushing developers to invest in companion diagnostic capabilities alongside therapeutic candidates. Stakeholders must monitor evolving reimbursement criteria for combination regimens as payers scrutinize incremental survival benefits relative to monotherapy costs.
Market Dynamics
Biomarker-driven patient stratification is compressing clinical trial timelines and reshaping how apoptosis modulators achieve regulatory clearance, with FDA's accelerated approval pathways rewarding developers who integrate companion diagnostics into their therapeutic platforms.
Growth Catalysts
- Accelerated Approval Frameworks:The FDA's breakthrough therapy designation and EMA's conditional marketing authorization compress development cycles for apoptosis-targeted agents. Developers now prioritize biomarker-defined subsets to secure faster market entry.
- Hospital Procurement Expansion:Cancer treatment centers in the United States, China, and Germany are expanding targeted therapy procurement. These institutions host the largest clinical trial infrastructures and maintain robust reimbursement frameworks for novel therapeutics.
- Green Synthesis Mandates:The EU Green Deal's pharmaceutical sustainability requirements are pivoting manufacturers toward environmentally optimized production routes for small-molecule apoptosis modulators.
Market Restraints
- High Manufacturing Complexity:Bcl-2 inhibitors and caspase activators require specialized biologics facilities with stringent containment protocols. Switzerland and Germany host limited qualified production sites, creating supply concentration risk.
- Reimbursement Scrutiny:Payers in Germany and the United States are tightening evaluation criteria for combination regimens. Incremental survival benefits must now justify costs relative to established monotherapies.
- Technical Efficacy Limitations:Death receptor agonists face persistent challenges in solid tumor penetration. Their earlier-stage clinical positioning restricts near-term commercial viability despite mechanistic promise.
Strategic Opportunities
- China's NMPA Pathways:Breakthrough therapy designation in China offers streamlined entry for apoptosis modulators with demonstrated efficacy in hematologic malignancies. Domestic clinical trial infrastructure supports accelerated local development.
- Caspase Activator Expansion:Next-generation agents entering Phase II trials for solid tumors represent underexploited therapeutic white space beyond established Bcl-2 inhibitor applications.
- Companion Diagnostic Integration:Biomarker testing platforms are converging with therapeutic development. Developers who control diagnostic capabilities alongside drug candidates capture preferential positioning in precision oncology procurement.
Industry Challenges
- Talent Scarcity in Translational Biology:The intersection of apoptosis mechanism expertise and clinical biomarker development requires specialized skill sets. Competition for qualified scientists intensifies across Boston, Basel, and Shanghai research clusters.
- IP Licensing Complexity:Patent estates covering Bcl-2 inhibitor scaffolds and caspase cascade modulation involve overlapping university and corporate holdings. Freedom-to-operate analyses consume substantial legal resources before trial initiation.
- Legacy System Integration:Hospital IT infrastructure for biomarker result reporting often lacks interoperability with electronic health records. Treatment decision workflows require manual data reconciliation, delaying therapy initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oncology Apoptosis Modulators Market |
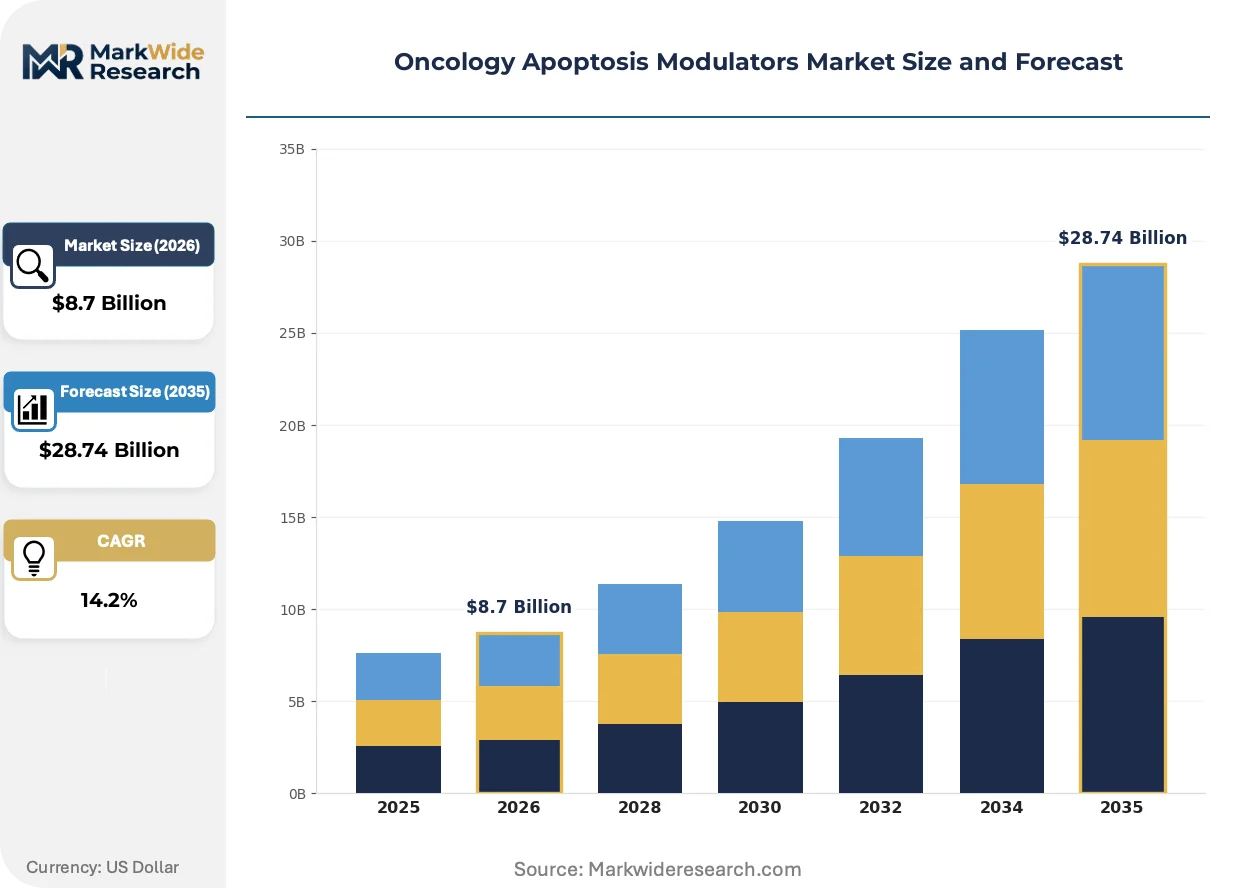
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bcl-2 Inhibitors, Caspase Activators, Death Receptor Agonists, Smac Mimetics Application: Breast Cancer, Lung Cancer, Leukemia, Lymphoma End User: Hospitals, Research Laboratories, Cancer Treatment Centers, Clinics Delivery Mode: Intravenous, Oral, Subcutaneous, Topical |
| Companies Covered | AbbVie Inc., AstraZeneca plc, Novartis AG, Roche Holding AG, Merck & Co., Inc., Boehringer Ingelheim, Bristol-Myers Squibb, Johnson & Johnson, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oncology Apoptosis Modulators Market Evolving Landscape
Modular manufacturing platforms and adaptive trial designs are converging to reshape how apoptosis modulators advance from discovery to commercial supply, with sustainability mandates adding new technical constraints to production decisions.
Continuous bioprocessing technology is modularizing the production of complex biologic apoptosis modulators. Swiss and German specialized facilities are adopting single-use bioreactor systems to reduce batch contamination risk and accelerate changeover between product campaigns. This shift is compressing capital requirements for multi-product manufacturing sites while enabling faster response to clinical supply demands.
REACH regulation amendments targeting pharmaceutical active ingredient sustainability are forcing reformulation of small-molecule synthesis routes. European manufacturers must now document solvent recovery rates and waste stream characterization for regulatory filings. Bcl-2 inhibitor production facilities in Basel and Ludwigshafen are investing in closed-loop solvent systems to maintain compliance without sacrificing yield efficiency.
Hospital procurement committees are consolidating vendor relationships for targeted oncology therapies. Large academic medical centers in the United States are negotiating enterprise-wide contracts spanning companion diagnostics and therapeutic agents. This concentration is displacing fragmented purchasing across individual oncology divisions, with pharmacy benefit managers inserting themselves as intermediaries in price negotiations.
Oncology Apoptosis Modulators Market Segmentation
Oncology apoptosis modulators exhibit distinct capital requirements across product categories, with biologics manufacturing demanding specialized containment infrastructure while small molecules face sustainability-driven reformulation costs. Patient stratification by biomarker status further fragments addressable populations, reshaping how developers allocate clinical trial investment across tumor types and delivery modalities.
Product Type:
Capital intensity varies sharply across this category, with biologics requiring single-use bioreactor systems and closed-loop solvent recovery infrastructure while small-molecule synthesis demands continuous processing upgrades to meet EU Green Deal mandates.
- Bcl-2 Inhibitors:Small-molecule compounds targeting anti-apoptotic Bcl-2 proteins in hematologic malignancies. Hospital procurement in the United States and Germany concentrates demand for venetoclax-based regimens as first-line CLL therapy, though reimbursement scrutiny tightens when combined with antibody agents.
- Caspase Activators:Biologic and small-molecule agents that directly initiate executioner caspase cascades in malignant cells. Phase II trial networks in China and the United States are expanding investigator interest for solid tumor applications, particularly lung cancer combinations where apoptosis resistance limits checkpoint inhibitor efficacy.
- Death Receptor Agonists:TRAIL receptor-targeting biologics under early-stage clinical evaluation.
- Smac Mimetics:IAP antagonists designed to sensitize tumors to TNF-mediated cell death.
Bcl-2 inhibitors absorb the bulk of installed capacity; caspase activators are expanding most quickly.
Application:
Clinical development priorities reflect unmet need severity and biomarker prevalence, with hematologic cancers offering faster path-to-proof while solid tumors promise larger addressable populations upon mechanistic validation.
- Leukemia:Chronic lymphocytic leukemia and acute myeloid leukemia represent the most mature indication for Bcl-2 inhibitor deployment. FDA accelerated approval pathways have compressed development timelines for venetoclax combinations in the United States, with companion diagnostic requirements now standard for enrollment.
- Lung Cancer:Non-small cell lung cancer trials are testing caspase activators as resistance-breaking agents after PD-1/PD-L1 progression. Chinese NMPA breakthrough therapy designation has attracted domestic trial investment for next-generation apoptosis modulators in this indication.
- Breast Cancer:Triple-negative subtypes show early signal for Smac mimetic combinations.
- Lymphoma:Mantle cell and follicular variants follow leukemia in Bcl-2 inhibitor adoption curves.
Leukemia commands the deepest clinical investment; lung cancer is climbing the fastest.
End User:
Procurement authority concentration shapes vendor access, with integrated delivery networks consolidating purchasing decisions while research laboratories retain fragmented supplier relationships for preclinical agents.
- Hospitals:Academic medical centers in the United States and university hospitals in Germany negotiate enterprise-wide contracts spanning companion diagnostics and therapeutic agents. Pharmacy benefit managers increasingly intermediate price negotiations for outpatient oral apoptosis modulators.
- Cancer Treatment Centers:Specialized oncology facilities in China are expanding targeted therapy procurement as NMPA approval timelines compress. These institutions maintain dedicated clinical trial units that accelerate patient enrollment for apoptosis-targeted studies.
- Research Laboratories:Preclinical and translational groups source death receptor agonists for mechanism-of-action studies.
- Clinics:Community oncology practices depend on hospital-affiliated infusion centers for intravenous Bcl-2 inhibitor administration.
Hospitals anchor commercial volume; cancer treatment centers are gaining share fastest.
Delivery Mode:
Formulation complexity drives manufacturing site qualification requirements, with parenteral products demanding aseptic fill-finish capacity while oral dosage forms face bioavailability optimization challenges for poorly soluble apoptosis modulators.
- Intravenous:Bcl-2 inhibitors and death receptor agonists require infusion center infrastructure with cardiac monitoring capabilities. Swiss and German specialized biologics facilities produce the majority of sterile drug substance for this route.
- Oral:Venetoclax tablet formulations enable outpatient chronic lymphocytic leukemia management. United States hospital procurement committees increasingly bundle oral oncology agents with specialty pharmacy distribution networks.
- Subcutaneous:Emerging delivery format for caspase-activating biologics in development.
- Topical:Preclinical evaluation for cutaneous T-cell lymphoma applications.
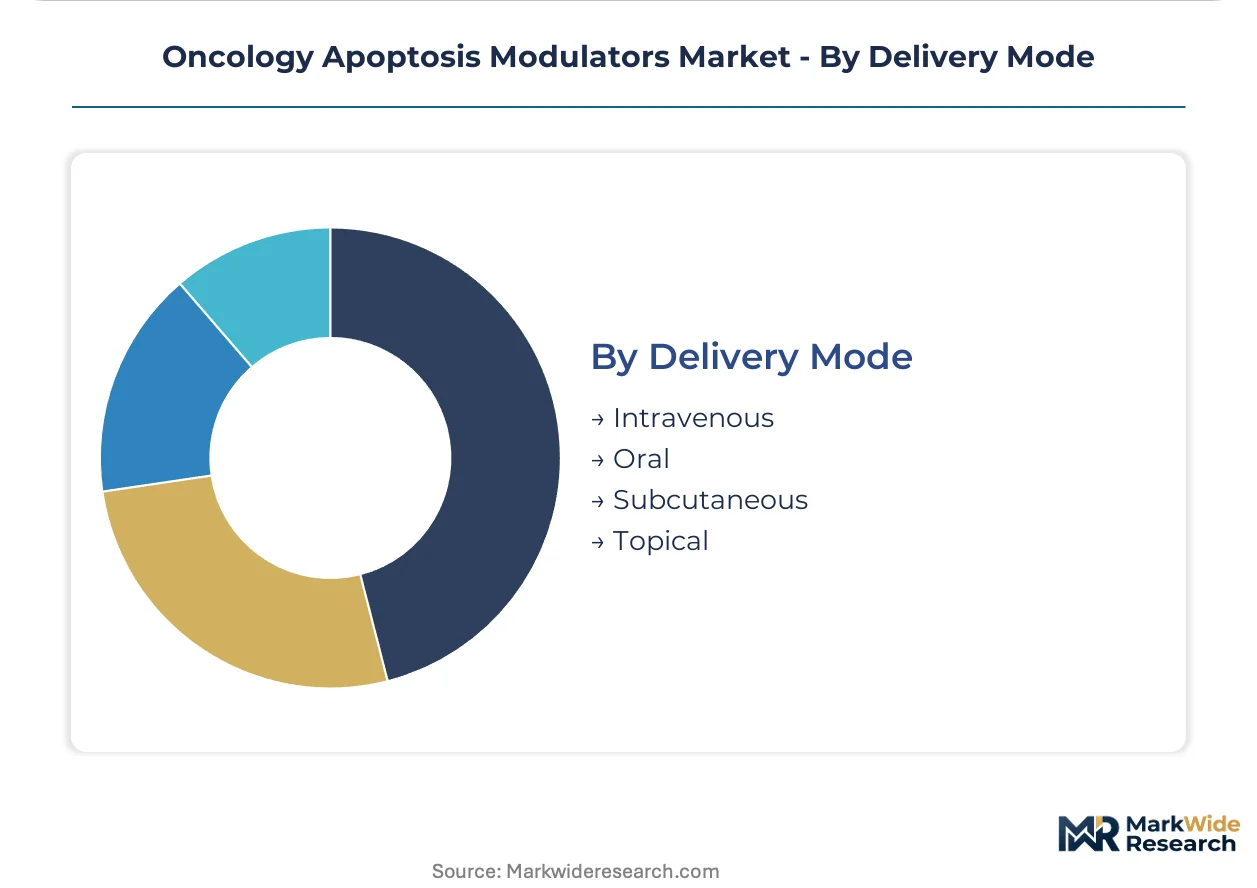
Intravenous delivery dominates current supply; oral formulations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized biologics production clusters in Switzerland and Germany supply drug substance for intravenous apoptosis modulators, while hospital procurement expansion in the United States and China absorbs the bulk of commercial volume. Regulatory acceleration pathways in these markets compress development timelines and reshape competitive entry dynamics.
United States
Academic medical centers in Boston and New York Metro anchor hospital procurement for Bcl-2 inhibitor regimens, with pharmacy benefit managers intermediating outpatient oral therapy distribution. FDA breakthrough therapy designation rewards biomarker-integrated development platforms, compressing Phase II-to-approval timelines for venetoclax combinations. The Greater Boston research cluster concentrates translational biology talent for caspase activator programs.
Germany
University hospitals in Bavaria and North Rhine-Westphalia negotiate enterprise-wide contracts spanning companion diagnostics and therapeutic agents, with payers tightening incremental survival benefit criteria for combination regimens. EMA conditional marketing authorization frameworks align with domestic reimbursement evaluation timelines. The Ludwigshafen-Basel corridor hosts specialized biologics fill-finish capacity for sterile drug substance.
China
Cancer treatment centers in Shanghai and Beijing expand targeted therapy procurement as NMPA breakthrough therapy designation attracts domestic trial investment for next-generation apoptosis modulators. The Yangtze River Delta clinical trial infrastructure accelerates patient enrollment for solid tumor caspase activator studies. Local manufacturing partnerships are emerging to supply intravenous formulations for hospital networks.
Switzerland
Basel anchors European production capacity for complex biologic apoptosis modulators, with specialized facilities adopting single-use bioreactor systems to reduce batch contamination risk. Swissmedic regulatory frameworks align with EMA accelerated pathways for precision oncology candidates. The region's containment-qualified manufacturing sites face supply concentration risk as demand outpaces installed capacity expansion.
United Kingdom
London and Southeast England host clinical trial units testing death receptor agonist mechanisms in early-phase solid tumor studies, with NHS England reimbursement negotiations focusing on biomarker-defined patient subsets. The MHRA operates post-Brexit recognition pathways for FDA and EMA oncology approvals. Research laboratories in the Cambridge cluster source preclinical apoptosis modulators for mechanism-of-action studies.
Oncology Apoptosis Modulators Market Competitive Landscape
The competitive structure tilts toward large-cap pharmaceutical incumbents with established biologics manufacturing infrastructure and companion diagnostic integration capabilities. These players anchor supply chains through specialized facilities in Switzerland and Germany while negotiating enterprise-wide hospital contracts. Three archetypes dominate: Bcl-2 inhibitor specialists leveraging venetoclax manufacturing expertise, checkpoint-apoptosis combination portfolio builders, and caspase activator developers targeting solid tumor white space. Capacity expansion in Basel-region containment facilities and strategic partnerships for biomarker testing platforms represent the dominant competitive moves.
Among North American and European incumbents, AbbVie Inc., Roche Holding AG, and Bristol-Myers Squibb occupy positions across the Bcl-2 inhibitor and combination therapy archetypes. AbbVie exemplifies the manufacturing-specialist model through its venetoclax supply chain concentration. Roche anchors European production geography through Swiss and German biologics infrastructure. Bristol-Myers Squibb sits within the combination-portfolio tier, competing across checkpoint-apoptosis regimens in North American and Asian trial networks. These three companies represent the competitive core around which mid-cap caspase activator developers and regional biotech firms orbit.
| Leading Market Players |
|---|
| AbbVie Inc. |
| AstraZeneca plc |
| Novartis AG |
| Roche Holding AG |
| Merck & Co., Inc. |
| Boehringer Ingelheim |
| Bristol-Myers Squibb |
| Johnson & Johnson |
| Eli Lilly and Company |
| Others |
Value Network & Pricing Analysis
Academic medical center procurement committees in the United States and Germany negotiate enterprise-wide contracts spanning companion diagnostics and therapeutic agents, anchoring a value-based pricing model where biomarker-defined patient subsets command premium positioning against commoditized monotherapy benchmarks.
Pricing Analysis
Margin tightening in oral Bcl-2 inhibitor tiers reflects pharmacy benefit manager intermediation and bundled specialty pharmacy distribution contracts. Three-tier pricing structure across premium biomarker-qualified, standard combination-eligible, and economy access-program tiers separates venetoclax formulations by indication maturity and companion diagnostic requirements. Cost-down pressure on intravenous biologics accelerates because Swiss and German fill-finish capacity constraints limit supply elasticity. Community oncology practices exhibit highest price sensitivity; academic medical centers with integrated delivery networks demonstrate lowest sensitivity due to formulary control and rebate capture mechanisms.
Supply Chain Analysis
Unused single-use bioreactor components and solvent recovery streams from Basel-region facilities feed closed-loop refurbishment programs for specialized containment equipment. Drug substance production concentrates in Switzerland, Germany, and emerging partnerships in China. Active pharmaceutical ingredient synthesis draws from Indian and Chinese intermediate suppliers, with final sterile fill-finish anchored in Swissmedic-qualified Basel facilities. Single-source vulnerability in containment-qualified manufacturing sites creates supply concentration risk as hospital procurement expands. Distribution runs through hospital-centric specialty pharmacy networks and direct-to-treatment-center cold chain logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's pharmaceutical sustainability requirements create a cost-of-compliance moat favoring incumbents with capitalized solvent recovery infrastructure and documented environmental impact filings.
For Market Incumbents: Lock in biomarker-testing platform partnerships to defend against caspase activator developers entering combination therapy white space. Expand Basel-region containment capacity to preempt supply rationing as Chinese hospital procurement accelerates. Deepen backward integration into companion diagnostic manufacturing to capture preferential positioning in precision oncology procurement committees.
For New Entrants and Emerging Players: NMPA breakthrough therapy designation in China opens a window for solid tumor caspase activator developers to establish clinical proof-of-concept before US FDA filing. Target lung cancer resistance-breaking combinations where checkpoint inhibitor progression creates unmet need. Pursue hospital-affiliated cancer treatment center partnerships rather than fragmented community oncology channels.
For Investors and Strategic Acquirers: The window for entry favors mid-cap caspase activator developers with Phase II solid tumor data and integrated biomarker strategies. Long-term viability hinges on controlling diagnostic capabilities alongside therapeutic candidates. Monitor EMA conditional marketing authorization timelines as inflection indicators for European reimbursement traction.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | Biomarker platform control secures preferential positioning in hospital procurement negotiations. |
| Green Manufacturing Transition | EU Green Deal compliance creates barrier-to-entry moat for solvent recovery infrastructure holders. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses development timelines for biomarker-defined subsets. |
| Manufacturing Scale-Up | Basel-region containment capacity expansion addresses supply concentration risk in sterile biologics. |
| Pipeline Diversification | Caspase activator solid tumor programs capture resistance-breaking opportunities beyond Bcl-2 saturation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists informed demand-side assumptions. FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases provided secondary validation. Bottom-up patient population modeling and top-down revenue triangulation converged on segment-level estimates.
Data-stream reconciliation across treatment line, dosage form, administration route, and regional regulatory cluster dimensions structured the analytical framework. CAGRs were derived from patient volume trajectories and pricing elasticity assumptions across the projection horizon. Clinical trial enrollment rates, biomarker prevalence epidemiology, and reimbursement approval timelines served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for caspase activator solid tumor penetration would alter the outlook. Forecasts reflect assumptions about regulatory acceleration pathway utilization and companion diagnostic co-development success rates. Practitioners should monitor NMPA breakthrough therapy designation grants and EMA conditional marketing authorization timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Osteosarcoma Market
Oncology
Peritoneal Cancer Treatment Market
Oncology
Global Metastatic Cancer Treatment Market
Oncology
North America Proton Therapy Market
Oncology
Cancer/Tumor Profiling Market
Oncology
Europe Tumor Ablation Market
Oncology
Small Cell Lung Cancer (SCLC) Treatment Market
Oncology
Head and Neck Cancer Market
Oncology
Epithelial Ovarian Cancer Market
Oncology
Middle East and Africa Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
US Veterinary Oncology Market
Oncology
PD1 Non-Small Cell Lung Cancer Treatment Market
Oncology
Radiation Oncology Market
Oncology
Europe Radiotherapy Market
Oncology
Outpatient Oncology Infusion Market
Oncology
BRCA Mutation-Positive Ovarian Cancer Market