
 Asia-Pacific Ovarian Cancer Diagnostics and Therapeutics Market | 2026-2036
Asia-Pacific Ovarian Cancer Diagnostics and Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ovarian Cancer Diagnostics and Therapeutics Market Outlook
Maintenance contracts for imaging systems and sequencing platforms is expanding as a revenue layer beyond equipment sales. F. Hoffmann-La Roche Ltd anchors its position through integrated diagnostic-therapeutic portfolios spanning oncology biomarkers and companion tests. AstraZeneca competes by leveraging its PARP inhibitor franchise alongside diagnostic partnerships that identify eligible patient populations. Siemens Healthineers AG sustains installed-base loyalty through long-term service agreements that cover calibration, software updates, and remote monitoring capabilities.
Asia-Pacific ovarian cancer diagnostics and therapeutics encompass biomarker assays, imaging modalities, genetic profiling tools, and systemic therapies designed to detect, subtype, and treat epithelial ovarian malignancies, with CA-125 and HE4 protein quantification serving as foundational serum markers alongside BRCA1/2 mutation analysis for risk stratification and treatment selection. The primary commercial purpose centers on enabling stage-appropriate intervention, guiding platinum-based chemotherapy decisions, and identifying candidates for PARP inhibitor maintenance therapy. Biomarker segments lead current revenue generation due to recurring test volumes and established reimbursement pathways, while liquid biopsy applications represent the fastest-expanding category as circulating tumor DNA assays gain clinical validation for treatment monitoring and acquired resistance detection. Next-generation sequencing occupies concentrated margin pools because of high per-test value and complex bioinformatics requirements that limit commoditization.
Japan's PMDA, China's NMPA, and India's CDSCO collectively shape market access through divergent approval timelines, local clinical data requirements, and evolving companion diagnostic frameworks that tie therapy authorization to test availability. Australia's TGA and South Korea's MFDS further influence regional standardization through mutual recognition agreements and harmonized IVD performance standards. Stakeholders must monitor how China's centralized procurement reforms for medical devices reshape pricing dynamics for imaging systems and molecular diagnostic platforms across provincial hospital networks.
Market Dynamics
Companion diagnostic frameworks across Asia-Pacific are collapsing the traditional separation between testing and therapy authorization, forcing diagnostic laboratories and pharmaceutical sponsors into co-development partnerships before product launch.
Growth Catalysts
- NMPA Streamlined Pathways:China's regulator has compressed review timelines for oncology companion diagnostics, enabling simultaneous approval of PARP inhibitors and their paired biomarker assays.
- Platinum Resistance Monitoring:Recurrence tracking protocols in Japanese cancer centers are expanding liquid biopsy utilization for detecting acquired resistance mutations.
- Centralized Cancer Networks:Tier-one hospital procurement consortia in China are consolidating purchasing power for next-generation sequencing platforms across provincial boundaries.
Market Restraints
- Reagent Import Dependency:Specialized polymerases and rare nucleotides for BRCA testing concentrate supply among North American and European specialty chemical manufacturers.
- CDSCO Validation Requirements:India's regulator mandates local clinical performance studies for imported molecular diagnostics, extending time-to-market by eighteen to twenty-four months.
- Imaging System Cost Structure:MRI and PET-CT procurement requires capital allocations exceeding most district hospital annual equipment budgets.
Strategic Opportunities
- Vietnam Diagnostic Infrastructure:Ho Chi Minh City and Hanoi hospital networks lack standardized molecular pathology capacity for HER2 and BRCA testing.
- PMDA Real-World Evidence Framework:Japan's post-market surveillance pathways enable label expansion for PARP inhibitors based on retrospective biomarker cohort analysis.
- Telepathology Integration:Remote slide review platforms are connecting Australian regional centers to centralized gynecologic pathology expertise in Sydney and Melbourne.
Industry Challenges
- Bioinformatics Talent Scarcity:Variant interpretation for complex genomic profiles requires computational biologists with oncology domain expertise that outpaces regional training program output.
- Laboratory Information System Interoperability:Legacy hospital IT architectures in South Korea resist seamless integration with cloud-based sequencing analysis pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ovarian Cancer Diagnostics and Therapeutics Market |
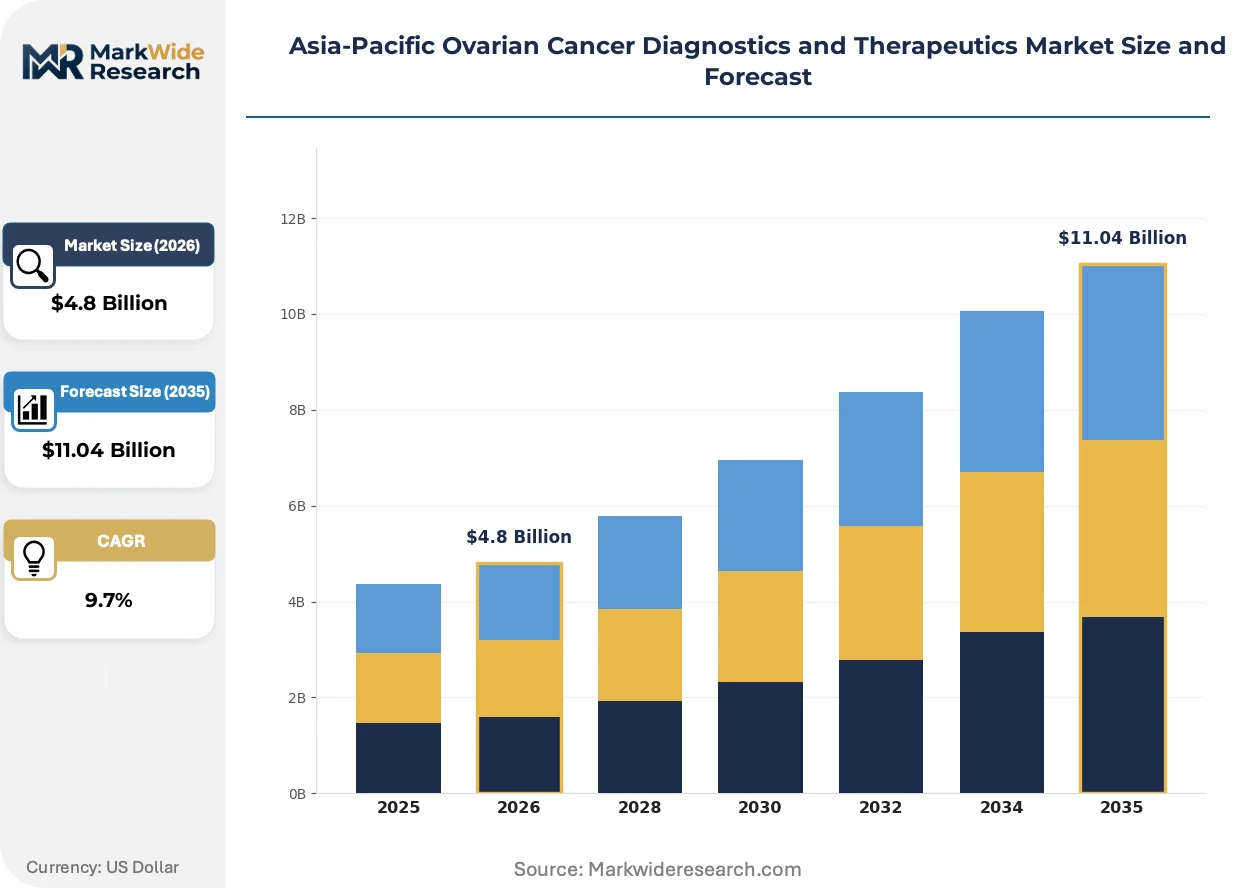
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biomarkers, Imaging Systems, Genetic Testing, Chemotherapy Application: Screening, Diagnosis, Treatment Monitoring, Post-Treatment End User: Hospitals, Diagnostic Laboratories, Research Institutions, Clinics Technology: PCR, Next-Generation Sequencing, Imaging Techniques, Liquid Biopsy |
| Companies Covered | Eli Lilly and Company, Bristol-Myers Squibb Company, F. Hoffmann-La Roche Ltd, AstraZeneca, GlaxoSmithKline Plc, Janssen Pharmaceuticals, Inc., Takeda Pharmaceutical Company, Siemens Healthineers AG, Quest Diagnostics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ovarian Cancer Diagnostics and Therapeutics Market Strategic Shifts
Digital pathology and artificial intelligence classification tools are penetrating histopathology workflows, compressing diagnostic turnaround times while introducing new validation requirements for algorithm-assisted cancer subtyping.
Circulating tumor DNA assays are absorbing monitoring responsibilities previously assigned to serial CA-125 measurements and radiographic surveillance. Major cancer centers in Tokyo and Shanghai have adopted ctDNA panels for post-surgical recurrence detection. The technology is absorbing revenue from conventional serum protein testing while creating parallel demand for specialized collection logistics and cold-chain specimen transport.
PMDA's 2023 guidance on oncology companion diagnostic co-development mandates simultaneous submission of drug and test applications. Japanese pharmaceutical sponsors now embed diagnostic development teams within clinical trial operations. The framework is compressing the historical lag between therapy approval and biomarker test availability from thirty-six months to under twelve.
Hospital procurement committees across China are unbundling imaging system purchases from mandatory multi-year service contracts. Provincial tender documents now separate hardware acquisition from software maintenance and remote monitoring subscriptions. This disaggregation is most visible in Jiangsu and Guangdong provinces, where centralized procurement platforms publish discrete pricing for equipment and service components.
Asia-Pacific Ovarian Cancer Diagnostics and Therapeutics Market Segmentation
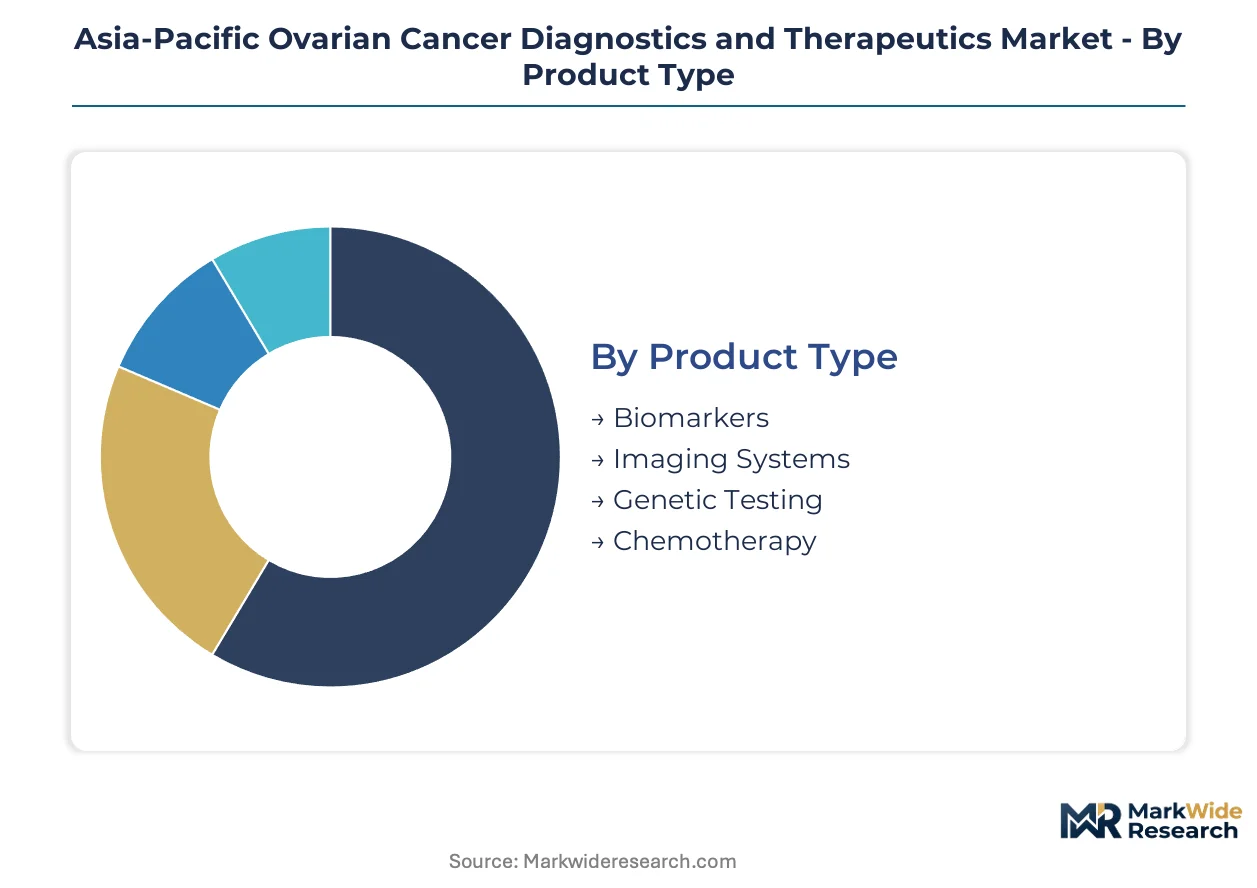
Segmentation in Asia-Pacific ovarian cancer diagnostics and therapeutics reveals divergent margin structures and procurement patterns across testing modalities and care settings. Buyers prioritize recurring revenue predictability in biomarker segments against capital-intensive imaging investments.
Product Type:
Hospital procurement committees weigh upfront capital requirements against per-test economics when allocating budgets across diagnostic platforms.
- Biomarkers:CA-125 and HE4 serum protein quantification assays dominate routine clinical workflows with established reimbursement pathways. China's tier-one cancer centers in Beijing and Shanghai drive recurring test volumes through standardized pre-surgical panels.
- Imaging Systems:MRI and PET-CT platforms require capital allocations exceeding district hospital annual equipment budgets. Japanese university hospitals concentrate procurement for advanced gynecologic oncology staging protocols.
- Genetic Testing:BRCA1/2 germline and somatic mutation analysis guides PARP inhibitor eligibility decisions.
- Chemotherapy:Platinum-based regimens and maintenance therapies constitute the therapeutic backbone.
Volume sits with Biomarkers; growth tilts toward Genetic Testing.
Application:
Clinical utility and regulatory validation status determine reimbursement eligibility across the care continuum.
- Screening:Population-level CA-125 surveillance programs face sensitivity limitations for early-stage detection. Australia's national cervical screening program infrastructure offers template expansion for ovarian risk stratification trials.
- Diagnosis:Histopathologic confirmation combined with biomarker profiling establishes treatment protocols. South Korean gynecologic oncology centers integrate intraoperative frozen section analysis with rapid BRCA testing.
- Treatment Monitoring:Serial CA-125 trending and radiographic assessment track therapeutic response.
- Post-Treatment:Surveillance protocols for recurrence detection rely on multimodal monitoring.
Diagnosis commands the largest addressable population; Post-Treatment applications are climbing the fastest as maintenance therapy durations extend.
End User:
Facility scale and patient throughput dictate technology adoption sequencing and platform sophistication.
- Hospitals:Centralized cancer centers in China's provincial capitals anchor imaging system procurement and multidisciplinary tumor board infrastructure. India's AIIMS network and Tata Memorial facilities concentrate complex surgical and systemic therapy delivery.
- Diagnostic Laboratories:Independent reference labs in Japan's Kanto and Kansai regions specialize in companion diagnostic validation for PMDA submissions.
- Research Institutions:Academic medical centers conduct biomarker discovery and clinical trial enrollment.
- Clinics:Community gynecology practices handle initial symptom evaluation and referral coordination.
Revenue concentrates in Hospitals; Diagnostic Laboratories gain share fastest through outsourcing trends.
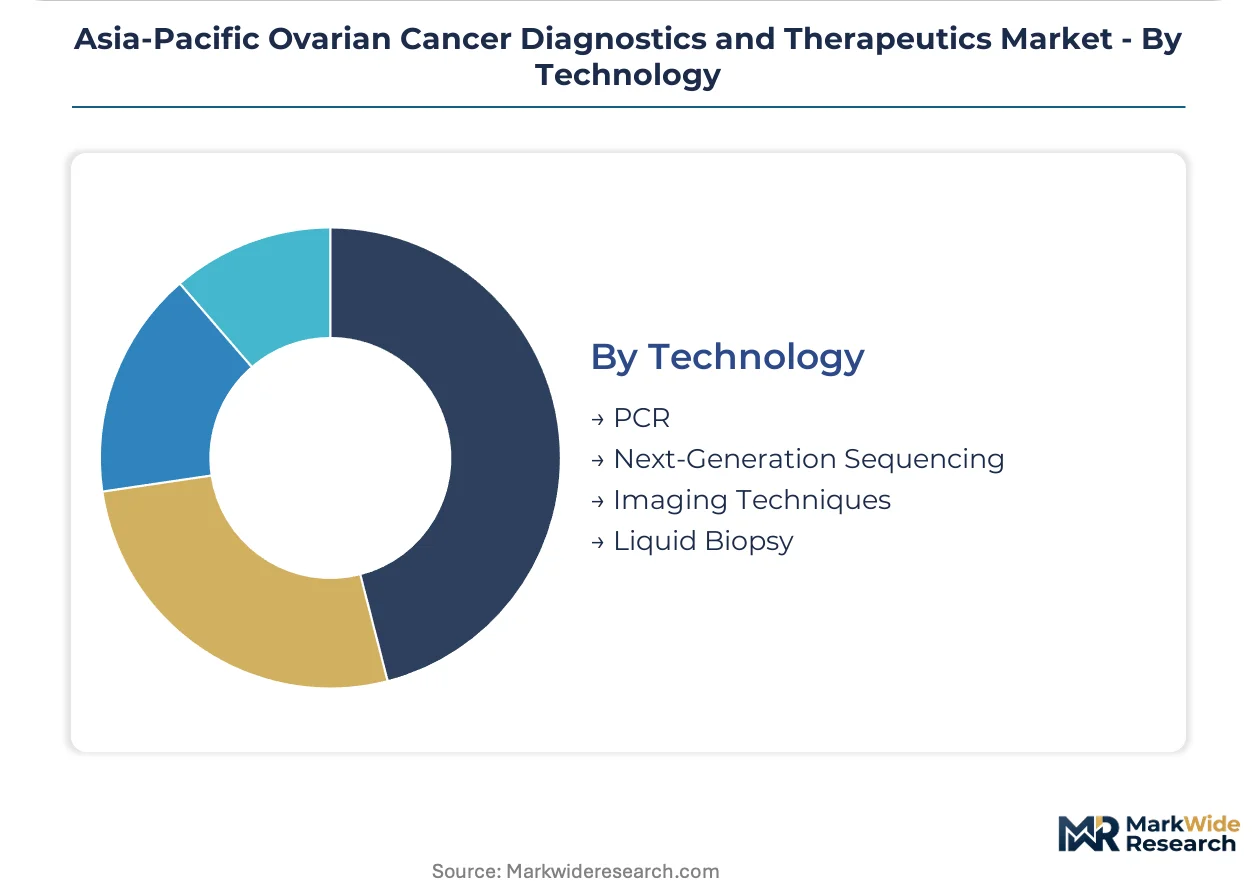
Technology:
Technical complexity and bioinformatics requirements create divergent competitive moats across detection methodologies.
- PCR:Established amplification protocols for BRCA hotspot mutations offer rapid turnaround in resource-constrained settings. Vietnamese hospital networks in Ho Chi Minh City deploy PCR-based testing as an entry point for molecular pathology capacity building.
- Next-Generation Sequencing:Comprehensive genomic profiling commands premium pricing with complex variant interpretation requirements. Singapore's National University Hospital and Japan's National Cancer Center anchor regional sequencing hub development.
- Imaging Techniques:Contrast-enhanced ultrasound and diffusion-weighted MRI advance surgical planning precision.
- Liquid Biopsy:Circulating tumor DNA assays enable non-invasive recurrence monitoring.
PCR maintains installed-base dominance; Liquid Biopsy exhibits the steepest expansion trajectory as ctDNA validation matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates diagnostic equipment production capacity while Japan and Australia absorb premium-priced therapeutics. Consumption patterns diverge sharply across the region's hospital procurement hierarchies.
China
Centralized cancer networks in Beijing and Shanghai drive biomarker adoption through tier-one hospital procurement consortia. NMPA compressed review timelines for oncology companion diagnostics, enabling simultaneous PARP inhibitor and biomarker assay approvals. Jiangsu and Guangdong provinces lead imaging system disaggregation through separate hardware and service contract tenders.
Japan
University hospitals concentrate procurement for advanced gynecologic oncology staging protocols. PMDA's 2023 companion diagnostic guidance mandates simultaneous drug and test submissions, compressing approval lags from thirty-six months to under twelve. Tokyo and Osaka cancer centers anchor regional adoption of circulating tumor DNA monitoring for post-surgical recurrence detection.
India
AIIMS network and Tata Memorial facilities concentrate complex surgical and systemic therapy delivery. CDSCO mandates local clinical performance studies for imported molecular diagnostics, extending time-to-market by eighteen to twenty-four months. Mumbai and Delhi diagnostic laboratories are expanding molecular testing footprints for BRCA analysis.
Australia
TGA influences regional standardization through mutual recognition agreements and harmonized IVD performance standards. National cervical screening program infrastructure offers template expansion for ovarian risk stratification trials. Sydney and Melbourne pathology hubs connect to regional centers through telepathology platforms for remote slide review.
South Korea
Gynecologic oncology centers integrate intraoperative frozen section analysis with rapid BRCA testing. MFDS shapes regional device standards through harmonized approval pathways. Seoul Capital Area hospitals anchor multidisciplinary tumor board infrastructure and next-generation sequencing platform procurement.
Asia-Pacific Ovarian Cancer Diagnostics and Therapeutics Market Competitive Environment
Top-tier vendors anchor integrated diagnostic-therapeutic portfolios, while mid-tier specialists compete through regional service agreements and technology licensing. The vendor base stratifies across three tiers: multinational pharmaceutical-diagnostics conglomerates, regional imaging and laboratory service providers, and emerging liquid biopsy specialists. Two dominant competitive moves are reshaping positioning: long-term maintenance contract expansion beyond equipment sales, and co-development partnerships between diagnostic laboratories and pharmaceutical sponsors prior to product launch.
Within the integrated portfolio tier, F. Hoffmann-La Roche Ltd and AstraZeneca occupy positions spanning oncology biomarkers and companion test development. Siemens Healthineers AG exemplifies the installed-base loyalty archetype through extended service agreements covering calibration and remote monitoring. These three anchors represent divergent strategic pathways: pharmaceutical-led diagnostic integration, diagnostic-led therapeutic pairing, and equipment-led recurring revenue capture.
| Leading Market Players |
|---|
| Eli Lilly and Company |
| Bristol-Myers Squibb Company |
| F. Hoffmann-La Roche Ltd |
| AstraZeneca |
| GlaxoSmithKline Plc |
| Janssen Pharmaceuticals, Inc. |
| Takeda Pharmaceutical Company |
| Siemens Healthineers AG |
| Quest Diagnostics |
| Others |
Value Chain & Pricing Dynamics
Liquid biopsy platform commoditization is compressing per-test margins while concentrating reagent supply among North American and European specialty chemical manufacturers, reshaping both cost economics and procurement risk profiles across Asia-Pacific diagnostic networks.
Pricing Analysis
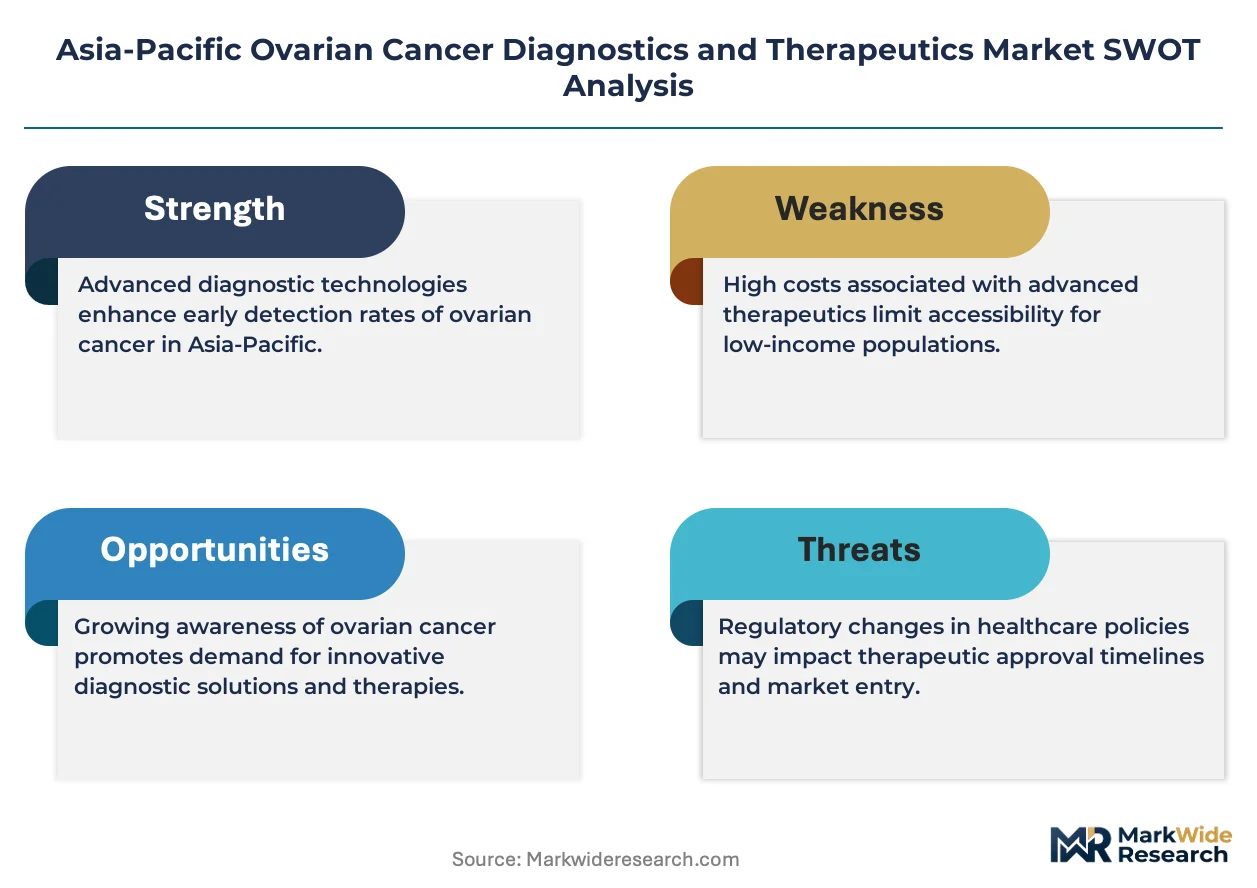
Margin tightening in next-generation sequencing reflects NMPA centralized procurement reforms and unbundled imaging system tenders across Jiangsu and Guangdong provinces. Three-tier pricing structure across premium, standard, and economy levels separates academic medical center contracts from district hospital procurement and reference laboratory outsourcing agreements. Pricing pressure stems from provincial tender platforms publishing discrete hardware and service component pricing. Tier-one cancer centers in Beijing and Shanghai show lowest price sensitivity; district hospitals in Vietnam and Indonesia face acute budget constraints.
Supply Chain Analysis
Freight costs for temperature-controlled specimen transport and cold-chain reagent delivery are absorbing margin across archipelago geographies and inland provincial networks. Specialized polymerases and rare nucleotides concentrate supply in the United States, Germany, and Switzerland. BRCA testing workflows rest on imported amplification enzymes, fluorescent probes, and sequencing consumables. Single-source vulnerability concentrates in European specialty chemical manufacturers for critical reagent components. Distribution runs through tier-one hospital procurement consortia and independent reference laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Companion diagnostic co-development mandates and centralized procurement reforms are forcing sub-scale diagnostic laboratories and equipment distributors into distressed exits, creating consolidation opportunities for integrated portfolio holders.
For Market Incumbents: Acquire liquid biopsy assay development capabilities and ctDNA analysis platforms to anchor post-surgical monitoring revenue streams. Lock in long-term service contracts for imaging systems and sequencing platforms before provincial tender unbundling accelerates. CDSCO validation requirements and eighteen-to-twenty-four month import delays create defensive moats for local manufacturing footprints. For New Entrants and Emerging Players: The mid-tier pricing gap between premium NGS comprehensive genomic profiling and economy PCR-based BRCA hotspot testing offers entry positioning for targeted panel developers. Vietnam's Ho Chi Minh City and Hanoi hospital networks lack standardized molecular pathology capacity. Partner with regional telepathology platforms for remote variant interpretation support. For Investors and Strategic Acquirers: Exit pathways concentrate in pharmaceutical-sponsored diagnostic co-development acquisitions and regional laboratory network rollup transactions. Five-to-ten year viability hinges on biomarker-linked therapy authorization frameworks expanding beyond PARP inhibitors. Watch PMDA real-world evidence guidance adoption rates across Japanese cancer centers as inflection signal for label expansion monetization.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | PMDA simultaneous submission mandates compress therapy-test approval lags from thirty-six months to under twelve. |
| Provincial Procurement Consortium Participation | Jiangsu and Guangdong tender platforms reward integrated hardware-service bundling with preferred vendor status. |
| Liquid Biopsy Assay Validation | Tokyo and Shanghai cancer center adoption of ctDNA panels creates reference site network for regional expansion. |
| Telepathology Platform Integration | Australian regional center connectivity to Sydney and Melbourne expertise addresses bioinformatics talent scarcity. |
| Local Manufacturing Footprint Establishment | CDSCO clinical performance study requirements favor domestic production for eighteen-to-twenty-four month faster market access. |
Study Parameters
Multi-period observation of biomarker test volumes, imaging system procurement cycles, and companion diagnostic approval timelines anchored the trend analysis, supplemented by interviews with oncology biomarker development executives, PMDA regulatory affairs leads, hospital procurement committee members at China's tier-one cancer centers, and reference laboratory operations directors. Secondary validation drew from NMPA approval databases, PMDA guidance documents, CDSCO import registration records, and hospital procurement tender platforms. Bottom-up test volume modeling and top-down therapy market sizing were triangulated against regional regulatory cluster analysis.
Segment-weighting across product type, application, end user, and technology dimensions informed value allocation. Treatment line positioning, biomarker validation status, and regional reimbursement pathway maturity shaped the analytical framework across the projection horizon. CAGRs were derived from installed base expansion rates and per-test economics trajectories. Forecast inputs included platinum resistance monitoring protocol adoption and PARP inhibitor maintenance therapy duration extensions.
Inputs from regulatory filing databases and hospital procurement records were available through the study window; gaps in real-world liquid biopsy utilization data and private laboratory pricing transparency introduce uncertainty bands around ctDNA segment projections. Forecasts reflect documented assumptions regarding biomarker reimbursement stability and companion diagnostic framework harmonization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
US Radiation Oncology Market
Oncology
North America Tumor Ablation Market
Oncology
PD1 Resistant Head and Neck Cancer Market
Oncology
PD1 Non-Small Cell Lung Cancer Treatment Market
Oncology
Liposarcoma Treatment Market
Oncology
Germany Radiotherapy Market
Oncology
Gynecological Cancers Market
Oncology
Internal Radiation Therapy Market
Oncology
AI in Oncology Market
Oncology
Global Particle Therapy Market
Oncology
Glottic Cancer Treatment Market
Oncology
Angiosarcomas Treatment Market
Oncology
Cancer Supportive Care Products Market
Oncology
Global Veterinary Oncology Market
Oncology
Single-Room Proton Therapy Systems Market
Oncology
Global Cancer Treatment Market