
 Quartz Crystal Oscillators Market | 2026-2036
Quartz Crystal Oscillators Market Size, Share, and Industry Trends Forecast 2026-2036
Quartz Crystal Oscillators Market Outlook
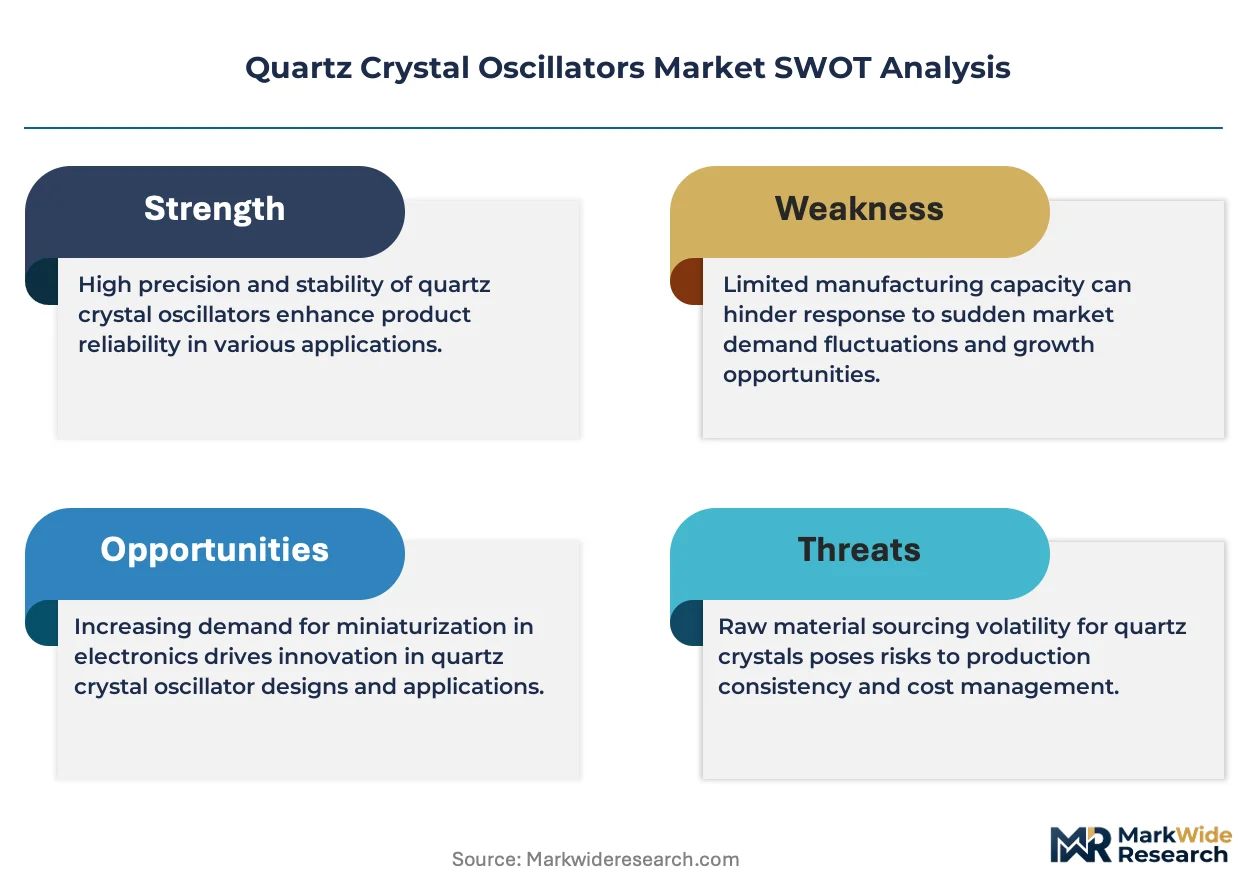
Buyer concentration among telecom equipment vendors is restructuring procurement patterns across the quartz crystal oscillator supply base. Murata Manufacturing Co., Ltd. leverages its ceramic packaging ecosystem to dominate high-frequency AT-cut supplies for base station manufacturers. Seiko Epson Corporation anchors the Japanese supply chain through in-house synthetic quartz cultivation and precision lapping operations. SiTime Corporation differentiates by competing with silicon MEMS alternatives that challenge traditional quartz architectures in temperature-compensated applications.
Quartz crystal oscillators are electromechanical resonators fabricated from synthetic single-crystal silicon dioxide wafers, typically cut along specific crystallographic orientations to achieve target frequency-temperature coefficients and quality factors exceeding ten thousand. AT-cut crystals operating near room-temperature inflection points serve as the primary timing reference in cellular transceivers, GPS receivers, and microcontroller clock domains where parts-per-million stability determines system performance. The application dimension shows automotive timing modules outpacing consumer electronics as ECU counts per vehicle multiply and ADAS sensors require redundant clock sources. Surface mount technology leads unit volume due to pick-and-place compatibility with high-density PCB assemblies, while hybrid technology captures margin pools in aerospace and defense programs requiring radiation-hardened packaging.
Japan's Ministry of Economy, Trade and Industry (METI) classifies high-purity synthetic quartz as a strategically controlled material, restricting export licensing for certain crystal growth equipment and influencing supply security calculations among foreign buyers. The EU F-Gas Regulation and REACH compliance frameworks impose substance restrictions on hermetic sealing materials and electrode metallization processes, elevating qualification costs for European automotive and medical device certifications. Stakeholders must monitor divergence between MEMS timing roadmaps and quartz performance benchmarks to determine capital allocation between legacy crystal fabrication and alternative resonator technologies.
Market Dynamics
Telecom infrastructure buildouts are restructuring procurement patterns across the quartz crystal oscillator supply base, pulling volume from electronics manufacturers toward dedicated network equipment suppliers as 5G base stations demand tighter frequency stability specifications.
Growth Catalysts
- 5G Base Station Miniaturization:Baseband processor manufacturers require AT-cut crystals with sub-ppm stability for massive MIMO arrays, expanding the addressable market for high-frequency timing components.
- Automotive ECU Proliferation:ADAS sensor redundancy mandates and domain controller architectures multiply clock source counts per vehicle, with NHTSA safety regulations accelerating qualification timelines.
- China Domestic Substitution:MIIT industrial policies and SAMR procurement guidelines favor local OEMs in satellite navigation modules and baseband timing circuits.
Market Restraints
- Synthetic Quartz Supply Concentration:Japan's METI export controls on crystal growth equipment create supply security vulnerabilities for foreign fabricators dependent on high-purity feedstock.
- MEMS Timing Substitution:Silicon MEMS oscillators challenge quartz architectures in temperature-compensated applications, pressuring legacy crystal margins in consumer-grade segments.
- REACH Compliance Burden:ECHA substance restrictions on hermetic sealing materials and electrode metallization elevate European automotive and medical device certification costs.
Strategic Opportunities
- Radiation-Hardened Aerospace Demand:Satellite constellation deployments and defense programs require hybrid-packaged oscillators with extended temperature ranges and radiation tolerance.
- India Electronics Manufacturing:PLI scheme incentives for telecom and automotive component production create greenfield fab opportunities for surface-mount crystal assembly.
- EU Green Deal Alignment:F-Gas Regulation phase-downs and CSRD disclosure requirements favor suppliers with low-carbon synthetic quartz cultivation and recyclable packaging.
Industry Challenges
- Precision Lapping Talent Scarcity:The specialized skill set for achieving ten-thousand-plus quality factors in AT-cut crystals faces generational attrition in Japanese and German manufacturing clusters.
- Multi-Standard Certification Overlap:Concurrent FCC, ETSI, and GB standard compliance for telecom timing modules extends product development cycles and testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quartz Crystal Oscillators Market |
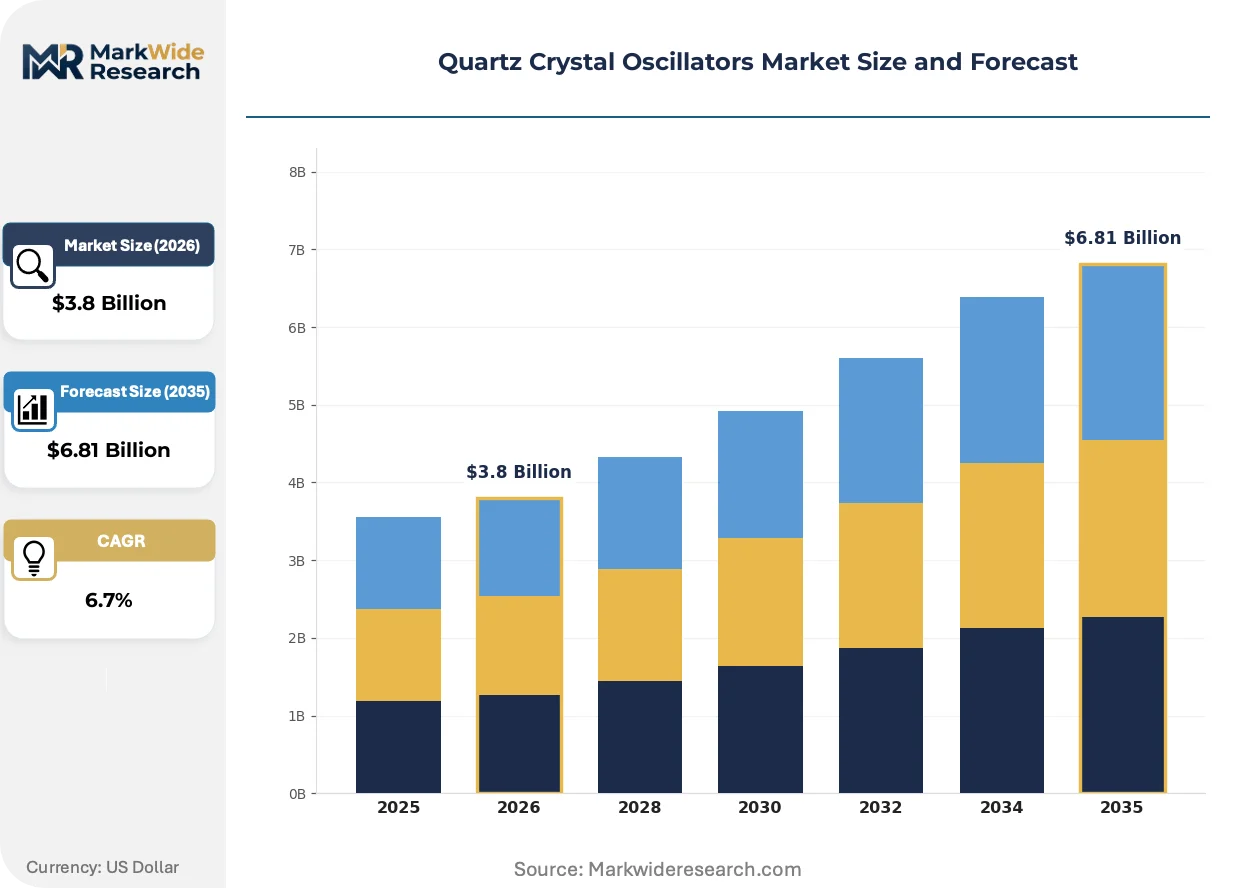
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fundamental Mode, Overtone Mode, AT Cut, BT Cut Application: Communication, Consumer Electronics, Automotive, Medical Devices End User: Telecom Companies, Electronics Manufacturers, Aerospace Firms, Defense Contractors Technology: Surface Mount Technology, Through-Hole Technology, Hybrid Technology, Digital Technology |
| Companies Covered | Murata Manufacturing Co., Ltd., Daishinku Corp., Seiko Epson Corporation, Siward Crystal Technology Co., Ltd., SiTime Corporation, Nihon Dempa Kogyo Co., Ltd., Kyocera Corporation, Abracon LLC, TXC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quartz Crystal Oscillators Market Strategic Shifts
Frequency control architectures are fragmenting across competing resonator technologies while packaging miniaturization and thermal compensation algorithms redefine performance benchmarks.
Photolithographic wafer-level packaging is modularizing oscillator form factors by enabling chip-scale footprints below 1.6mm by 1.2mm. Telecom equipment vendors are adopting these reduced-size units for 5G small cell density requirements. The shift is compressing traditional ceramic package demand and reallocating margin toward semiconductor-compatible assembly flows.
EU F-Gas Regulation restrictions on sulfur hexafluoride and perfluorocarbon hermetic sealing gases are forcing electrode metallization process redesigns. European automotive timing module suppliers face eighteen-month requalification timelines for alternative sealing chemistries. Medical device manufacturers are accelerating ISO 13485-certified oscillator sourcing to preempt MDR substance disclosure deadlines.
Direct contracting between telecom OEMs and crystal cultivators is displacing tiered distribution networks for high-volume 5G infrastructure programs. Japanese and Korean base station manufacturers now specify synthetic quartz purity grades and cutting angles in purchase agreements. China-based network equipment vendors are consolidating supplier panels to three qualified sources per frequency band.
Quartz Crystal Oscillators Market Segmentation
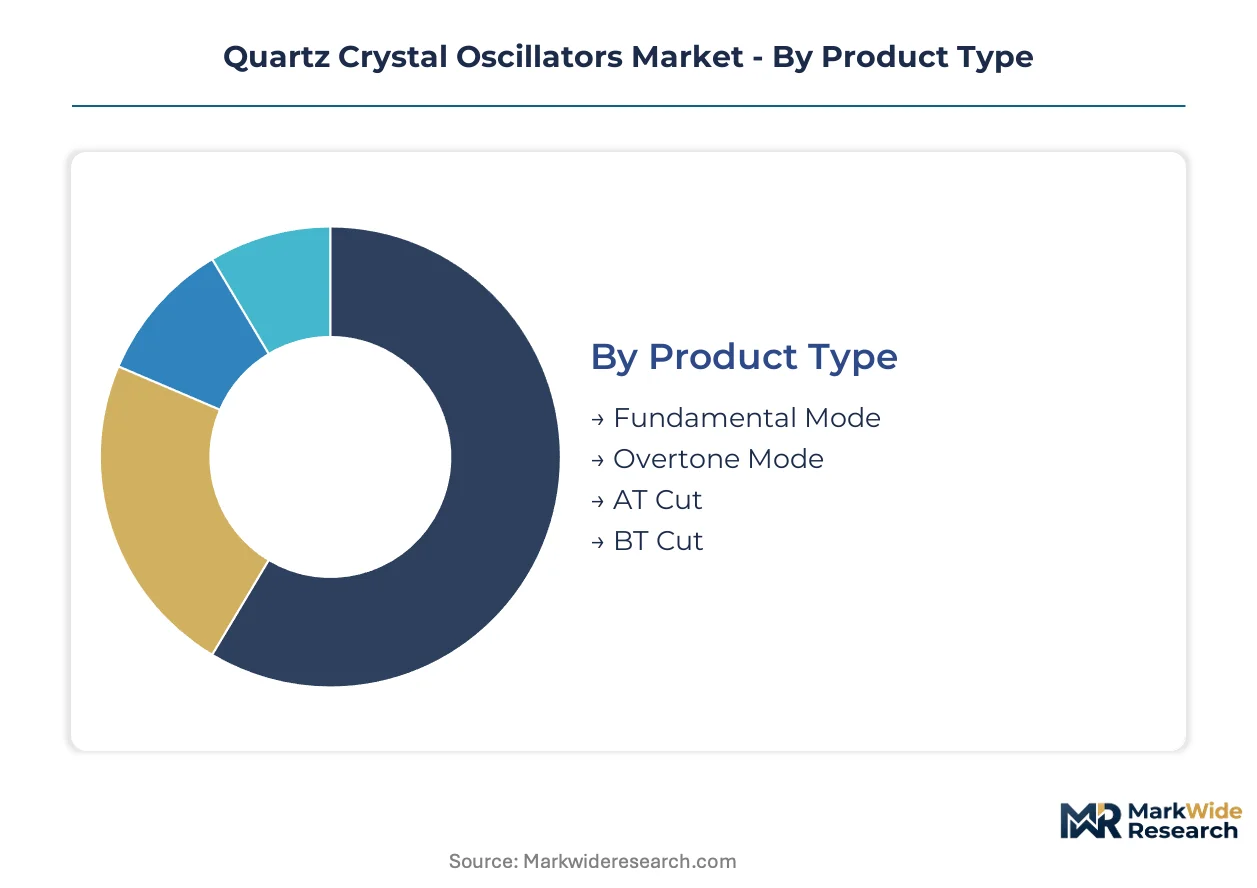
Frequency stability specifications diverge sharply across end-use applications, forcing manufacturers to maintain parallel product architectures. Segmentation clarity enables suppliers to align crystal cutting angles and packaging formats with precise thermal and mechanical stress profiles.
Product Type:
Upgrade cycles in base station infrastructure are shortening as 5G massive MIMO deployments demand tighter frequency tolerances, accelerating displacement of legacy crystal designs.
- AT Cut:Operating near room-temperature inflection points, AT-cut crystals achieve quality factors exceeding ten thousand with minimal frequency drift. Telecom baseband processors in China and Korea specify sub-ppm stability for massive MIMO synchronization, pulling volume from consumer-grade alternatives.
- Fundamental Mode:These crystals oscillate at their natural resonant frequency without harmonic multiplication, offering lowest phase noise for GPS receivers and precision timing modules. Automotive ECU manufacturers favor fundamental mode units for engine control redundancy where jitter tolerance is tightest.
- Overtone Mode:Third and fifth overtone designs extend frequency range without sacrificing stability in high-frequency RF front-ends.
- BT Cut:BT-cut orientations serve specialized applications requiring linear frequency-temperature characteristics across extended ranges.
AT Cut sits at the top of the volume ranking, with Fundamental Mode climbing the fastest as automotive safety systems multiply clock source counts.
Application:
Margin structures across end-use segments reflect certification burden and performance tier rather than raw unit economics.
- Communication:5G infrastructure programs specify hermetically sealed AT-cut crystals with aging rates below three parts per billion per year. NHTSA safety regulations and ETSI electromagnetic compatibility standards extend qualification timelines, compressing supplier margins despite premium pricing.
- Automotive:Domain controller architectures and ADAS sensor fusion require redundant clock sources per vehicle, with each ECU demanding temperature-compensated oscillators. German and Japanese OEMs enforce AEC-Q200 stress test compliance, filtering out consumer-grade suppliers.
- Consumer Electronics:Smartphones and wearables drive unit volume through chip-scale packaging, though MEMS timing alternatives erode quartz share in cost-sensitive tiers.
- Medical Devices:ISO 13485-certified oscillators for implantable and diagnostic equipment face ECHA substance restrictions on electrode metallization.
Communication commands the largest revenue pool, while Automotive expands most quickly as ECU proliferation outpaces vehicle production growth.
End User:
Procurement centralization among equipment vendors is collapsing traditional distribution tiers for high-volume programs.
- Telecom Companies:Direct contracting with synthetic quartz cultivators now specifies purity grades and cutting angles in purchase agreements. Chinese network equipment vendors consolidate supplier panels to three qualified sources per frequency band, displacing tiered distribution networks.
- Electronics Manufacturers:Surface-mount compatibility requirements dominate sourcing criteria for high-density PCB assemblies in consumer and industrial equipment.
- Aerospace Firms:Satellite constellation deployments demand hybrid-packaged oscillators with radiation tolerance and extended temperature ranges.
- Defense Contractors:ITAR and national security classification requirements restrict supplier pools for military timing modules.
Telecom Companies anchor procurement volume, with Aerospace Firms gaining share fastest on satellite deployment schedules.
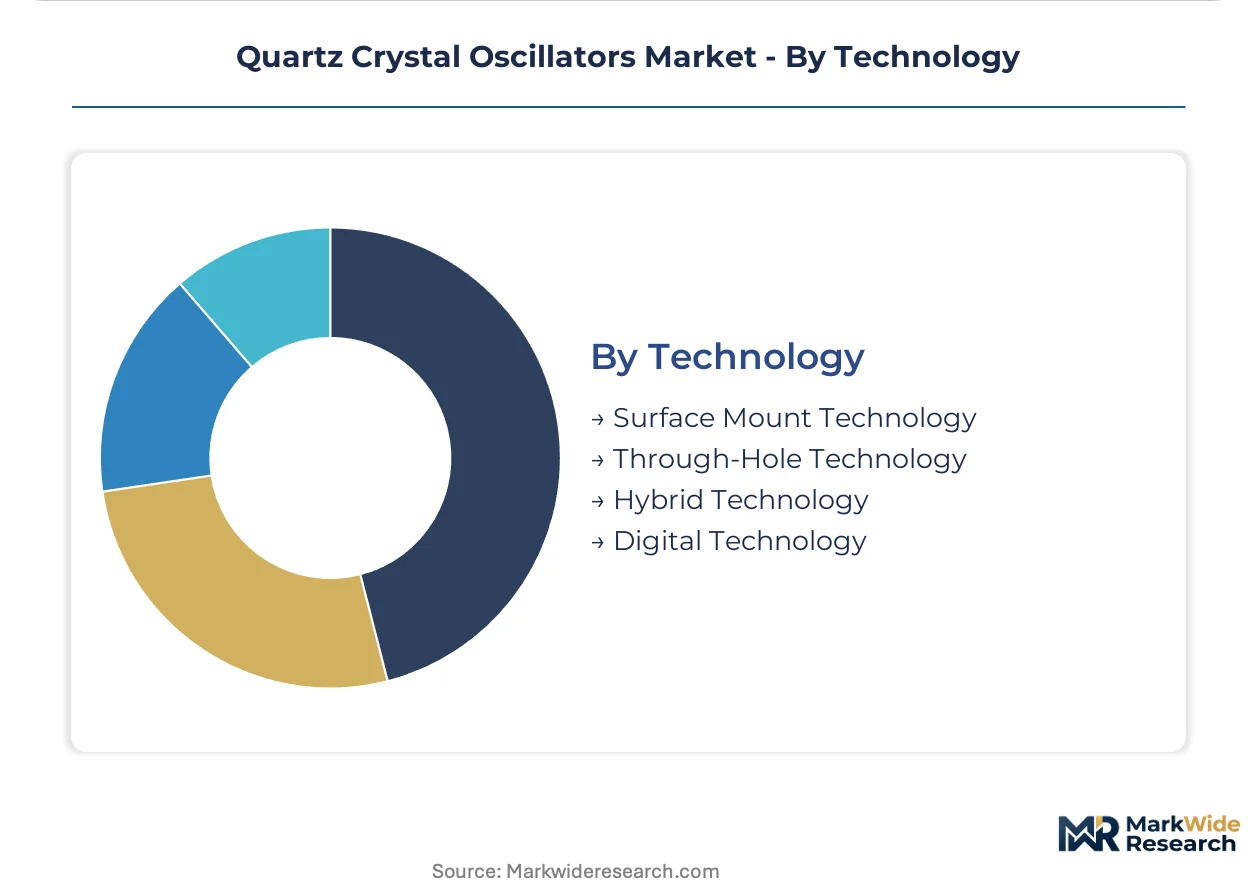
Technology:
Packaging format selection determines assembly compatibility and environmental resilience more than resonator physics alone.
- Surface Mount Technology:Pick-and-place compatibility enables high-density PCB assemblies for smartphones, base stations, and automotive modules. Photolithographic wafer-level packaging now achieves chip-scale footprints below 1.6mm by 1.2mm, compressing traditional ceramic package demand.
- Hybrid Technology:Ceramic-glass composite packages with gold-tin sealing serve aerospace and defense programs requiring radiation hardness and thermal shock resistance. EU F-Gas Regulation restrictions on sulfur hexafluoride hermetic sealing gases force eighteen-month requalification timelines for alternative chemistries.
- Through-Hole Technology:Legacy through-hole formats persist in industrial and replacement markets where mechanical robustness outweighs density requirements.
- Digital Technology:Integrated CMOS compensation circuits enable software-configurable frequency trimming and temperature correction.
Surface Mount Technology leads unit shipments by substantial margin, with Hybrid Technology posting the steepest expansion trajectory on defense and space program ramps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese precision lapping specialists and German ceramic packaging engineers anchor the highest-value manufacturing clusters, while Chinese domestic cultivators scale synthetic quartz output for regional telecom programs.
China
MIIT industrial policies accelerate timing component substitution in baseband processors and BeiDou navigation modules. SAMR procurement guidelines favor domestic OEMs for 5G infrastructure, consolidating supplier panels to three qualified sources per frequency band. Shenzhen and Dongguan host surface-mount assembly clusters serving Huawei and ZTE base station programs.
Japan
METI classifies high-purity synthetic quartz as strategically controlled, restricting export licensing for crystal growth equipment. Domestic fabricators maintain captive cultivation through in-house synthetic quartz operations. The Nagano and Yamanashi prefectures concentrate precision lapping facilities supplying AT-cut crystals for automotive and telecom applications.
Germany
AEC-Q200 stress test compliance filters automotive timing module procurement toward qualified European suppliers. ECHA REACH restrictions on electrode metallization force eighteen-month requalification timelines for hermetic sealing alternatives. Bavaria and Baden-Württemberg anchor automotive ECU manufacturing for BMW and Bosch domain controller architectures.
United States
FCC electromagnetic compatibility standards and NHTSA safety regulations extend qualification timelines for automotive timing modules. Defense programs require ITAR-compliant suppliers for radiation-hardened oscillators in satellite deployments. California and Arizona host aerospace clusters serving SpaceX and government constellation contracts.
South Korea
Base station manufacturers specify synthetic quartz purity grades and cutting angles in direct purchase agreements with cultivators. MFDS and RRA certification requirements govern medical device timing component sourcing. Suwon and Pyeongtaek concentrate Samsung and LG telecom equipment manufacturing pulling volume from traditional distribution tiers.
Quartz Crystal Oscillators Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the quartz crystal oscillator supply base. Japanese and Korean electronics conglomerates leverage backward integration into synthetic quartz cultivation and ceramic packaging. Three archetypes dominate: integrated materials-to-modules conglomerates, precision frequency control specialists, and silicon MEMS challengers. Competitive moves center on direct OEM contracting for 5G infrastructure and qualification acceleration for automotive safety systems.
Among Japanese conglomerates, Murata Manufacturing Co., Ltd. and Seiko Epson Corporation exemplify integrated materials-to-modules positioning through captive synthetic quartz operations. SiTime Corporation occupies the silicon MEMS challenger archetype, competing with temperature-compensated alternatives to traditional quartz architectures. TXC Corporation and Abracon LLC represent focused frequency control specialists serving regional telecom and automotive programs.
| Leading Market Players |
|---|
| Murata Manufacturing Co., Ltd. |
| Daishinku Corp. |
| Seiko Epson Corporation |
| Siward Crystal Technology Co., Ltd. |
| SiTime Corporation |
| Nihon Dempa Kogyo Co., Ltd. |
| Kyocera Corporation |
| Abracon LLC |
| TXC Corporation |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap specialists in Japan's Nagano prefecture anchor the highest-value tier of synthetic quartz cultivation, translating captive feedstock control into pricing discipline that resists commoditization despite MEMS timing encroachment in consumer segments.
Pricing Analysis
Bundled qualification services and unbundled component sales split procurement economics across telecom and automotive verticals. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q200-certified automotive modules from consumer-grade chip-scale units, with certification grade and volume scale as the primary price differentiation drivers. Cost compression in consumer-tier surface-mount crystals is intensifying because MEMS alternatives erode legacy quartz margins. Electronics manufacturers exhibit the highest price sensitivity, while defense contractors and aerospace firms show minimal elasticity due to ITAR compliance requirements.
Supply Chain Analysis
Single-source vulnerability sits with Japan's METI-controlled synthetic quartz feedstock, where export licensing restrictions on crystal growth equipment create supply security gaps for foreign fabricators. Manufacturing concentrates in Japan, China, and South Korea, with precision lapping operations drawing from high-purity synthetic quartz wafers, ceramic packaging substrates, and hermetic sealing gases. Regulatory restriction on sulfur hexafluoride hermetic sealing under EU F-Gas Regulation forces process redesigns with eighteen-month requalification timelines. Distribution runs through direct OEM contracting for high-volume 5G infrastructure programs, displacing traditional tiered distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quartz crystal oscillators function as a stable compounder, with telecom infrastructure refresh cycles and automotive ECU proliferation providing durable demand visibility across economic cycles.
For Market Incumbents: Deepen backward integration into synthetic quartz cultivation to secure feedstock independence from METI export controls. Prioritize AEC-Q200 certification investments for automotive safety system qualification, defending against MEMS timing substitution in temperature-compensated applications through precision lapping capability expansion in Nagano and Yamanashi prefectures.
For New Entrants and Emerging Players: Tier 2 automotive suppliers represent the most penetrable channel partner type for qualification-light timing modules in India's PLI scheme electronics manufacturing corridors. Target surface-mount assembly for telecom and automotive component production in greenfield fab opportunities, leveraging cost positioning against Japanese incumbents while building ISO 13485 capabilities for medical device diversification.
For Investors and Strategic Acquirers: Japanese electronics conglomerates are the most active acquirer in this space, consolidating precision frequency control specialists to anchor 5G infrastructure supply panels. Five-to-ten-year viability favors integrated materials-to-modules players with captive synthetic quartz operations over pure-play assembly houses. Monitor divergence between MEMS timing roadmaps and quartz performance benchmarks as the critical inflection indicator for capital allocation between legacy crystal fabrication and alternative resonator technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Synthetic Quartz Cultivation | METI export controls make in-house feedstock production a supply security imperative for Japanese and Korean fabricators. |
| AEC-Q200 Certification Acceleration | German and Japanese OEM enforcement filters automotive timing module procurement toward qualified European and Asian suppliers. |
| Photolithographic Wafer-Level Packaging | Chip-scale footprints below 1.6mm by 1.2mm enable 5G small cell density requirements for Chinese and Korean base station programs. |
| Hermetic Sealing Chemistry Redesign | ECHA REACH restrictions on sulfur hexafluoride force eighteen-month requalification timelines for European automotive and medical device certifications. |
| Direct OEM Contracting Consolidation | Chinese network equipment vendors now specify synthetic quartz purity grades and cutting angles in purchase agreements with three qualified sources per frequency band. |
Study Parameters
Bottom-up telecom and automotive demand modeling reconciled against top-down synthetic quartz supply tracking forms the analytical core. Primary interviews with baseband processor procurement managers, automotive ECU platform engineers, crystal cultivation technical directors, and hermetic packaging specialists combined with secondary validation from METI trade statistics, ECHA substance restriction databases, FCC electromagnetic compatibility filings, and AEC-Q200 stress test documentation. Triangulation between end-use consumption patterns and feedstock production volumes ensures statistical integrity across the analysis window.
Historical trendline analysis of AT-cut crystal shipment volumes and frequency stability specification evolution informs projection mechanics. Segmentation dimensions span product type, application, end user, and technology, with crystal cutting angle and quality factor thresholds as industry-specific forecast inputs. CAGRs derive from fitted growth curves reconciled against capital expenditure announcements from Japanese and Korean synthetic quartz cultivators.
Revisions become necessary when METI export control enforcement intensifies, MEMS timing performance benchmarks converge with quartz specifications, or EU F-Gas Regulation phase-downs accelerate hermetic sealing chemistry transitions. Forecasts reflect documented assumptions about 5G infrastructure deployment pacing and automotive domain controller architecture proliferation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Micro Thermoelectric Modules Market
Semiconductor Devices
Americas Microcontroller (MCU) Market
Semiconductor Devices
Global Through Silicon via (TSV) Technology Market
Semiconductor Devices
Reachers Market
Semiconductor Devices
Hybrid Microcircuits Market
Semiconductor Devices
United Arab Emirates (UAE) CEP Market
Semiconductor Devices
Plastic Transistors Market
Semiconductor Devices
Thin Film Transistors (TFT) Market
Semiconductor Devices
FPGA Market
Semiconductor Devices
Asia-Pacific Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Mobile Phone Semiconductor Market
Semiconductor Devices
Gan Transistor Market
Semiconductor Devices
Power Supply in Package (Psip) and Power Supply on Chip (Pwrsoc) Market
Semiconductor Devices
Flip Chip Technology Market
Semiconductor Devices
Power Transistor Market
Semiconductor Devices
Global Power MOSFET Market