
 Reachers Market | 2026-2036
Reachers Market Size, Share, and Industry Trends Forecast 2026-2036
Reachers Market Analytics
ISO 13485 certification for medical device quality management is bifurcating the competitive landscape between qualified and unqualified suppliers. Drive Medical leverages its vertical integration across aluminum sourcing and finished goods assembly to sustain cost advantages in medical reacher production. Medline Industries anchors North American hospital supply contracts through its extensive distribution network, while Cardinal Health competes on channel control with direct-to-facility logistics that bypass traditional distributor markups.
Reachers are mechanical assistive devices with telescoping or fixed-length shafts, typically constructed from aluminum tubing with polymer grip mechanisms and serrated jaw tips, designed to extend human grasping range for retrieval tasks in constrained or overhead spaces. Medical reachers command premium positioning due to biocompatibility requirements and sterilization compatibility, while aluminum material grades dominate volume production for their strength-to-weight ratio and corrosion resistance. Garden reachers occupy a mature segment with price-sensitive home consumers, whereas carbon fiber variants represent a nascent high-margin tier targeting industrial applications requiring extended reach with minimal deflection.
FDA 510(k) clearance pathways govern medical reacher market access in the United States, while EU MDR technical documentation requirements are elevating compliance costs for European market entry. Japan's METI enforces JIS standards for industrial ergonomics that directly specify reacher tool specifications in warehouse safety audits. Stakeholders must monitor evolving material sustainability mandates from ECHA REACH restrictions on certain polymer additives that could force reformulation of grip components across multiple product lines.
Market Dynamics
ISO 13485 certification requirements are concentrating procurement authority among qualified medical device suppliers while displacing uncertified manufacturers from institutional channels. This quality management bifurcation is reshaping competitive positioning across ergonomic assistive device categories.
Growth Catalysts
- EU MDR Compliance:Medical facilities in Germany are expanding procurement of ergonomic reacher tools under expanded technical documentation requirements, creating institutional demand pull for certified manufacturers.
- Japan METI Directives:Workplace safety audits specifying reacher tool ergonomics are accelerating institutional purchases of assistive reaching devices in warehousing and healthcare settings.
- Aluminum Tubing Advances:Improved extrusion processes for medical-grade aluminum shafts are enabling lighter-weight designs without sacrificing load-bearing capacity for overhead retrieval tasks.
Market Restraints
- Polymer Additive Restrictions:ECHA REACH restrictions on certain plasticizers used in grip components are forcing reformulation cycles that extend product development timelines.
- Carbon Fiber Supply Concentration:Industrial-grade carbon fiber sourcing concentrates among Asian precursor manufacturers, exposing high-performance reacher producers to input cost volatility.
- FDA 510(k) Pathway Friction:Substantial equivalence documentation requirements for novel jaw mechanism designs create regulatory bottlenecks that delay US market entry for innovative products.
Strategic Opportunities
- Industrial Warehouse Automation:Integration of reacher tools with collaborative robot workstations represents an emerging application segment requiring extended human grasping range in semi-automated environments.
- India PLI Scheme:Production-linked incentives for medical device manufacturing are creating localized supply capacity that could serve price-sensitive institutional buyers across South Asia.
- Biocompatibility-Grade Polymers:Convergence of sterilization-compatible grip materials with antimicrobial surface treatments opens premium positioning in infection-control-sensitive healthcare environments.
Industry Challenges
- ISO 13485 Auditor Scarcity:Limited availability of qualified certification bodies is extending quality management system implementation timelines for mid-tier manufacturers seeking medical device qualification.
- Legacy Sterilization Compatibility:Autoclave-resistant polymer selection remains constrained, forcing trade-offs between grip ergonomics and repeated sterilization durability in hospital procurement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reachers Market |
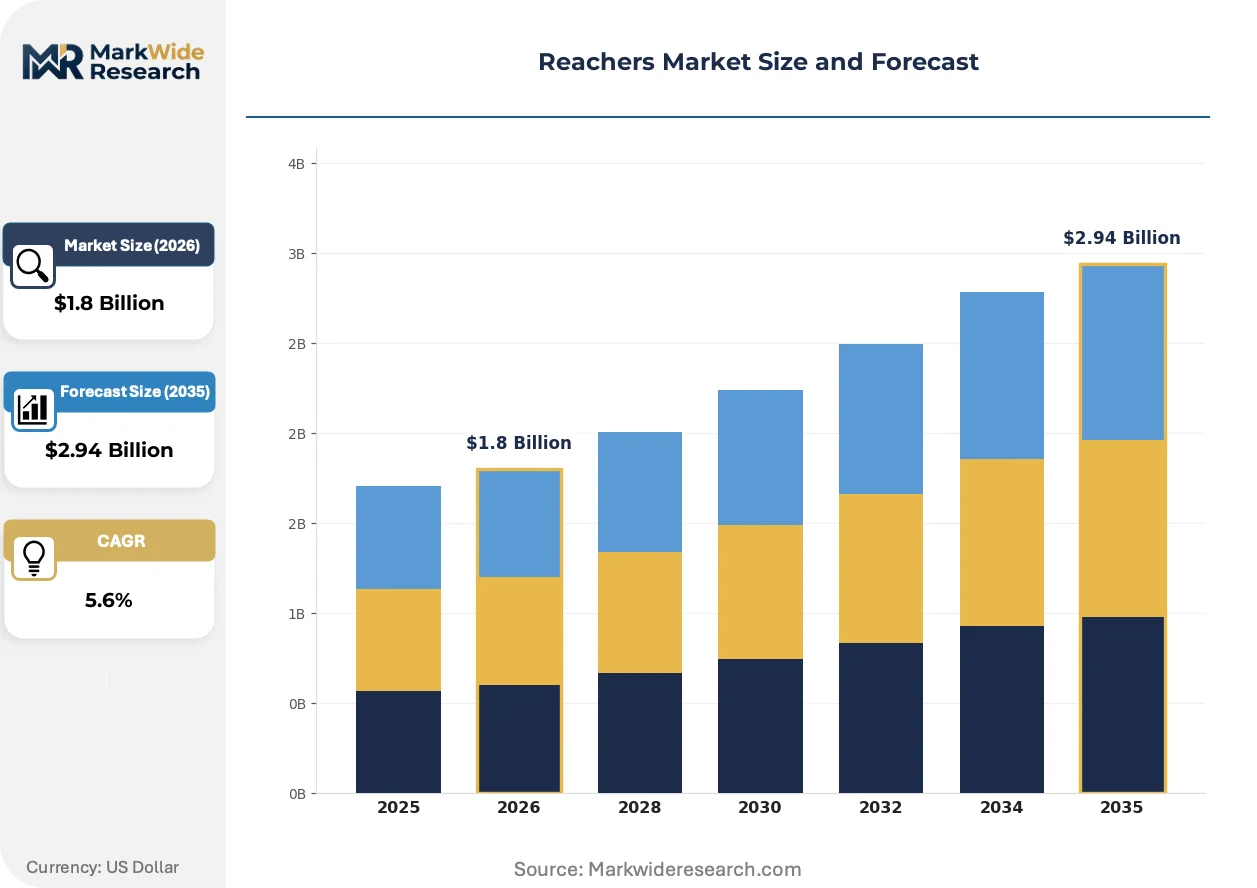
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Garden Reachers, Industrial Reachers, Medical Reachers, Telescopic Reachers Material: Aluminum, Plastic, Steel, Carbon Fiber Application: Home Use, Warehouse Operations, Medical Facilities, Manufacturing Size: Standard, Extended, Compact, Adjustable |
| Companies Covered | Drive Medical, Mabis Healthcare, Vivid Medical, Premier Healthcare, Cardinal Health, Medline Industries, McKesson, Bird & Cronin, Performance Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reachers Market Evolving Landscape
Material science advances and regulatory quality mandates are actively segmenting the competitive landscape between medical-certified and consumer-grade supply tiers. This bifurcation is compressing margins for undifferentiated producers while rewarding specialized compliance investments.
Carbon fiber composite shafts are bifurcating the industrial reacher segment from aluminum-dominated medical and consumer categories. Aerospace and automotive suppliers are adopting carbon fiber variants for extended-reach applications requiring minimal deflection under load. This material transition is compressing addressable market share for traditional aluminum extruders in high-performance industrial channels.
EU MDR technical documentation requirements are elevating compliance costs for European market entry while creating preference stickiness among certified suppliers. German notified bodies are extending review timelines for novel mechanical assistive devices, forcing smaller manufacturers to consolidate certification resources. Medical reacher producers with existing MDR certificates are capturing expanded hospital supply contract renewals.
Direct-to-facility logistics models are displacing traditional distributor networks in North American hospital procurement. Cardinal Health and similar channel controllers are bypassing distributor markups through captive delivery infrastructure, compressing margins for independent medical supply distributors. This channel consolidation is most visible in metropolitan healthcare systems with centralized materials management functions.
Reachers Market Segmentation
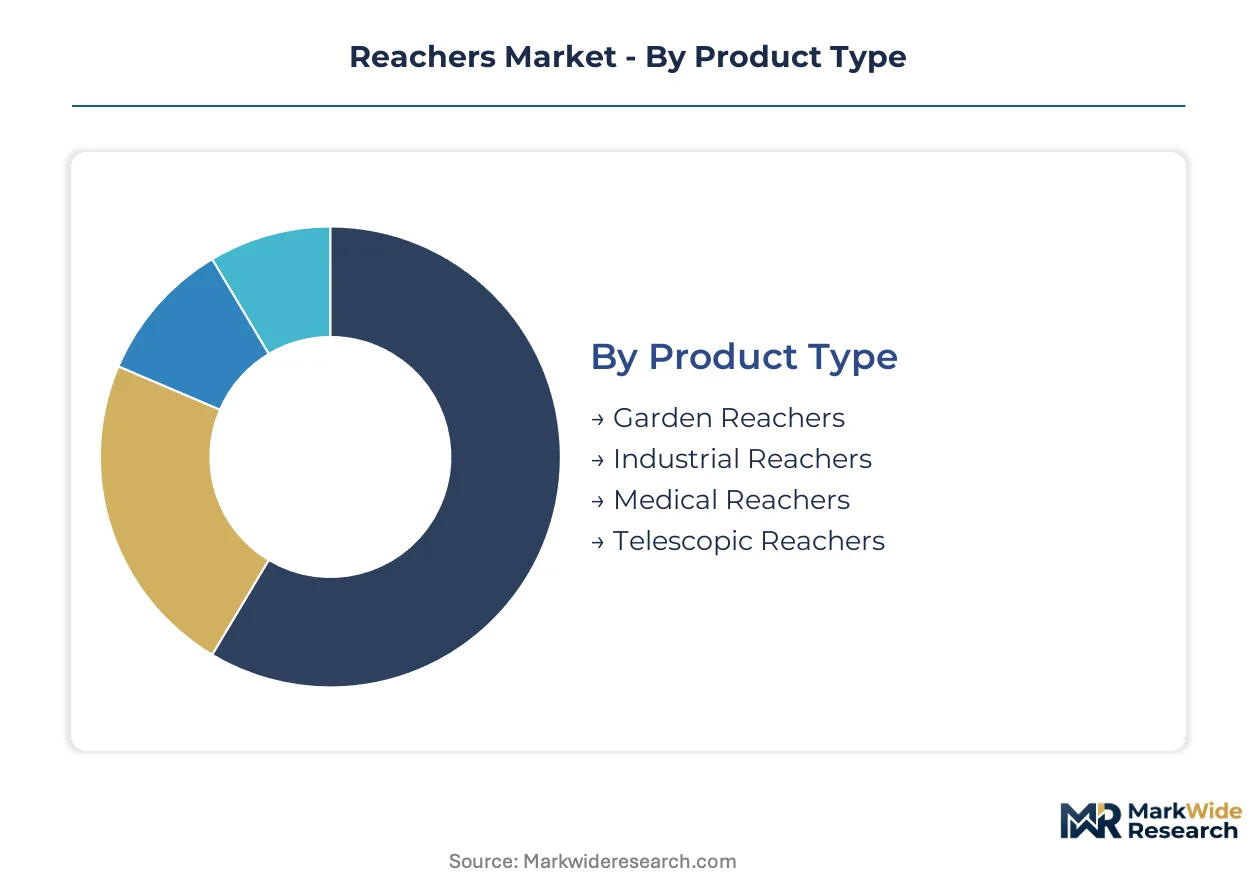
Segmentation in the Reachers Market reveals how regulatory requirements and performance specifications divide procurement channels. Medical-grade certification creates distinct supply tiers that command premium positioning against commoditized alternatives.
Product Type:
EU MDR technical documentation and FDA 510(k) pathways bifurcate the competitive landscape between certified medical devices and unregulated consumer tools.
- Medical Reachers:Aluminum shafts with biocompatible polymer grips and sterilization-compatible jaw mechanisms meet ISO 13485 quality management requirements. German hospital systems are expanding procurement of these certified devices under expanded MDR technical documentation mandates.
- Industrial Reachers:Carbon fiber composite shafts deliver minimal deflection under load for aerospace and automotive assembly applications. METI workplace safety audits in Japan specify ergonomic reacher tool requirements that accelerate institutional purchases in warehousing environments.
- Garden Reachers:Price-sensitive home consumers drive volume through aluminum and plastic variants with basic serrated jaw tips for yard debris collection.
- Telescopic Reachers:Adjustable-length mechanisms serve multi-purpose retrieval tasks across home and light commercial settings where storage constraints matter.
Established volume favors Garden Reachers; emerging adoption favors Medical Reachers.
Material:
Cost tiers separate performance-optimized industrial specifications from price-driven consumer alternatives.
- Aluminum:Medical-grade extrusions dominate institutional procurement for their strength-to-weight ratio and corrosion resistance in sterilization cycles. Drive Medical leverages vertical integration across aluminum sourcing and finished goods assembly to sustain cost advantages in medical reacher production.
- Carbon Fiber:Industrial-grade precursors concentrate among Asian manufacturers, exposing high-performance reacher producers to input cost volatility for extended-reach applications requiring minimal deflection.
- Plastic:Polymer shafts serve budget-conscious home use segments where load-bearing requirements remain modest.
- Steel:Heavy-duty construction targets manufacturing floor applications prioritizing durability over weight considerations.
Aluminum captures the largest production volume; carbon fiber climbs the fastest on industrial automation demand.
Application:
Customer type determines whether procurement flows through institutional supply contracts or retail consumer channels.
- Medical Facilities:Hospital systems with centralized materials management functions source through direct-to-facility logistics that bypass traditional distributor markups. Cardinal Health competes on channel control with captive delivery infrastructure across metropolitan healthcare networks.
- Warehouse Operations:METI ergonomic safety directives in Japan specify reacher tool integration in semi-automated collaborative robot workstations.
- Home Use:Retail distribution serves aging demographics with basic assistive devices for overhead and constrained-space retrieval tasks.
- Manufacturing:Assembly line integration requires extended human grasping range in environments where worker reach limitations create productivity constraints.
Medical Facilities concentrate procurement authority; Warehouse Operations gain share fastest on automation integration.
Size:
Application environment dictates dimensional requirements from compact storage to extended overhead reach.
- Standard:Fixed-length designs serve general-purpose retrieval across home and light commercial settings with predictable reach requirements.
- Extended:Length-optimized shafts target warehouse and industrial applications where overhead shelving and deep racking demand maximum grasping range.
- Compact:Collapsible mechanisms address storage constraints in residential and travel contexts where portability outweighs reach extension.
- Adjustable:Telescoping designs span multiple use cases through variable length configurations that adapt to task-specific requirements.
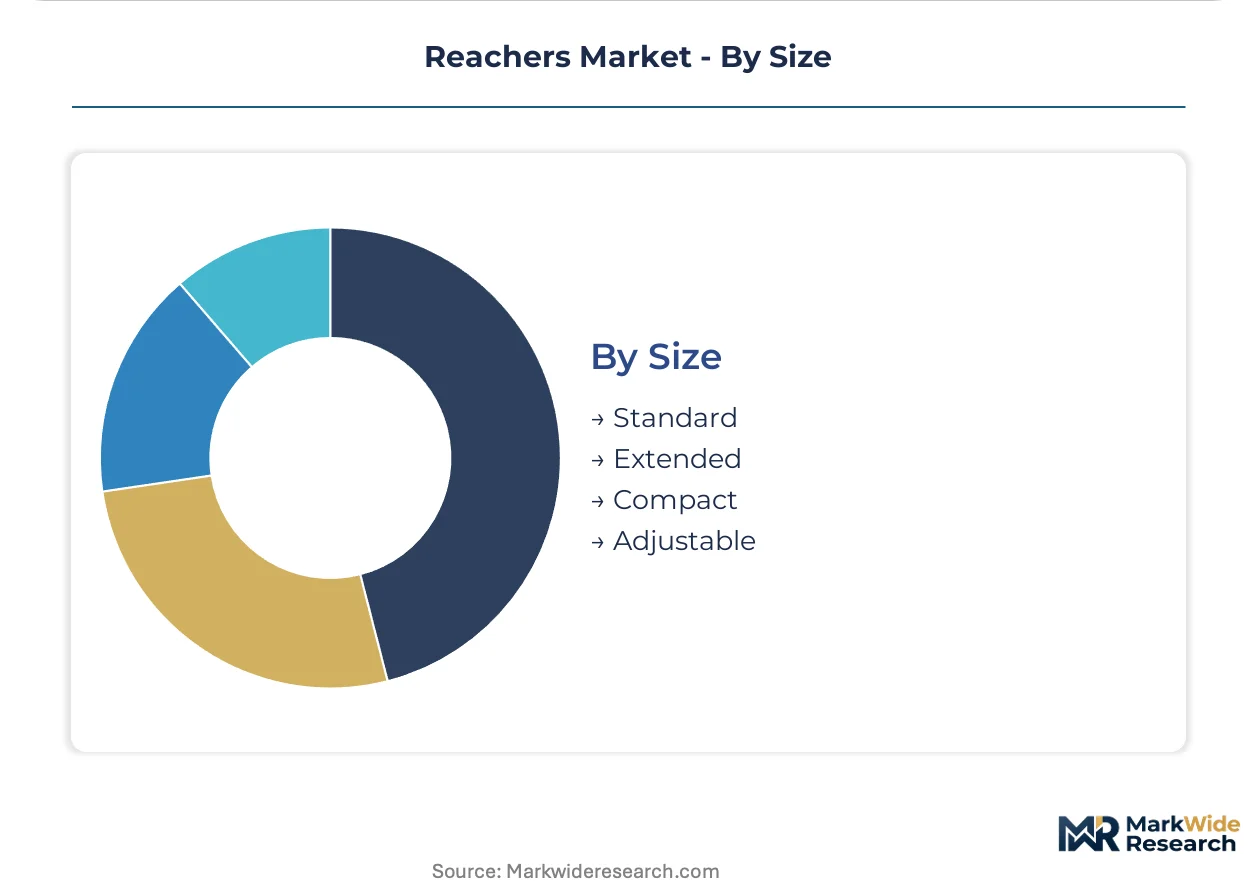
Standard sizes dominate current procurement volume; Adjustable variants expand most quickly on multi-purpose utility demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government procurement incentives and workplace safety mandates are steering institutional demand across major economies. National regulators enforce divergent compliance pathways that segment production and distribution strategies by geography.
United States
Hospital systems with centralized materials management functions are consolidating supplier relationships around direct-to-facility logistics models. FDA 510(k) clearance pathways govern medical reacher market access, creating documentation bottlenecks for novel jaw mechanism designs. Cardinal Health leverages captive delivery infrastructure across metropolitan healthcare networks to bypass traditional distributor markups.
Germany
Medical facilities are expanding procurement of ergonomic reacher tools under expanded EU MDR technical documentation requirements. German notified bodies are extending review timelines for novel mechanical assistive devices, forcing smaller manufacturers to consolidate certification resources. Hospital supply contract renewals are concentrating among producers with existing MDR certificates.
Japan
Aging demographics and warehouse automation investments are accelerating institutional purchases of assistive reaching devices. METI workplace safety audits specify reacher tool ergonomics in warehousing and healthcare settings. Industrial clusters in the Kanto region around Tokyo are integrating reacher tools with collaborative robot workstations in semi-automated environments.
China
Carbon fiber precursor manufacturing concentrates among domestic suppliers, exposing high-performance reacher producers to input cost volatility. NMPA medical device regulations govern import and domestic production standards for hospital-grade assistive devices. Yangtze River Delta manufacturing hubs are scaling aluminum extrusion capacity for medical-grade shaft production.
India
Production-linked incentives for medical device manufacturing are creating localized supply capacity for price-sensitive institutional buyers. CDSCO quality standards align with ISO 13485 frameworks for hospital procurement qualification. Maharashtra and Gujarat industrial corridors are attracting contract manufacturers seeking to serve South Asian healthcare systems.
Reachers Market Competitive Landscape
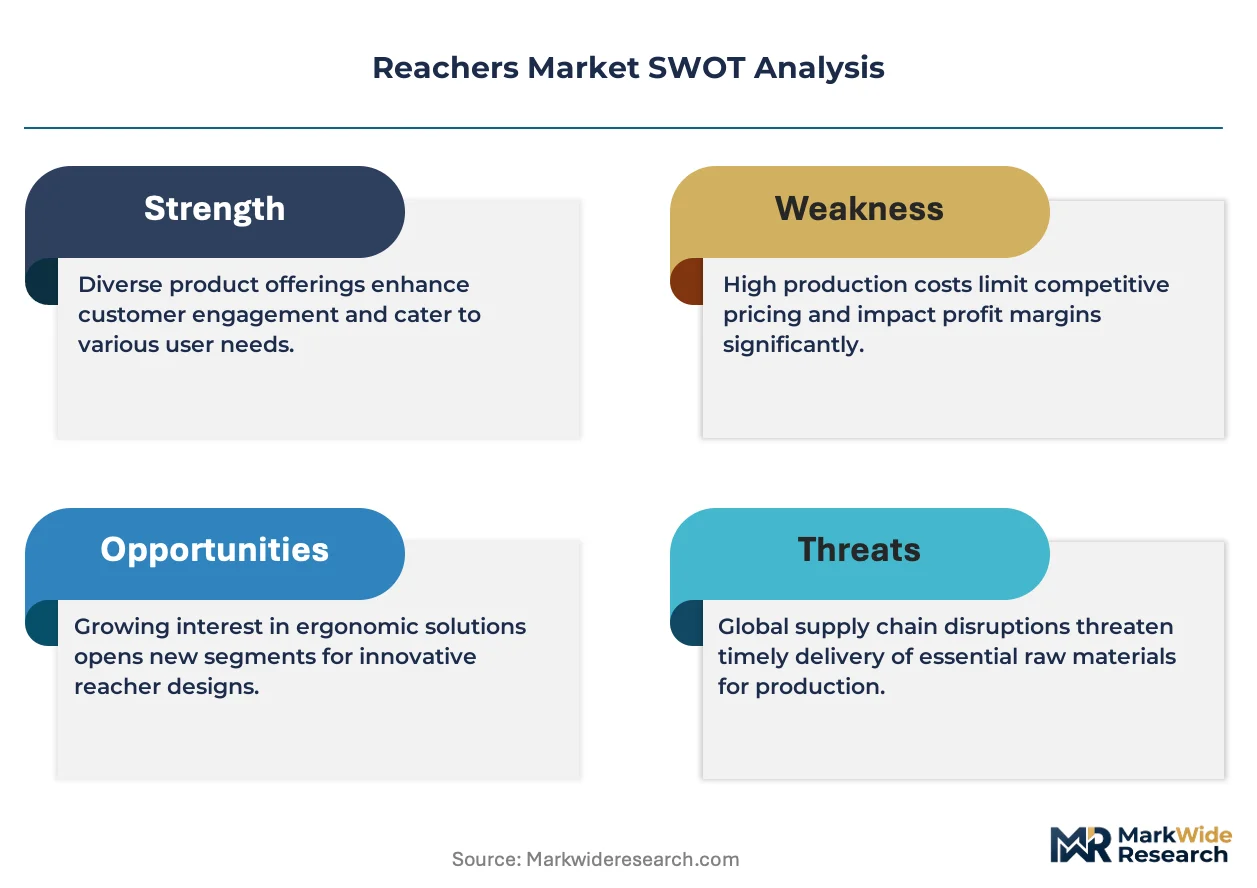
Player mix skews toward diversified medical supply conglomerates with captive distribution infrastructure. The competitive structure concentrates procurement authority among ISO 13485-certified suppliers while displacing uncertified manufacturers from institutional channels. Three archetypes dominate: vertically integrated aluminum processors, channel-controlling logistics operators, and specialized ergonomic device engineers. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms seek MDR certification coverage and direct hospital contracting relationships.
Within the medical supply conglomerate tier, Drive Medical and Cardinal Health exemplify divergent sourcing strategies. Drive Medical leverages backward integration across aluminum sourcing and finished goods assembly to sustain cost advantages in medical reacher production. Cardinal Health competes on channel control with direct-to-facility logistics that bypass traditional distributor markups. Medline Industries anchors North American hospital supply contracts through its extensive distribution network, representing the logistics-scale archetype that competes on coverage breadth rather than manufacturing integration.
| Leading Market Players |
|---|
| Drive Medical |
| Mabis Healthcare |
| Vivid Medical |
| Premier Healthcare |
| Cardinal Health |
| Medline Industries |
| McKesson |
| Bird & Cronin |
| Performance Health |
| Others |
Value Network & Pricing Analysis
Carbon fiber substitution for aluminum in industrial-grade shafts simultaneously relocates supply geography toward Asian precursor manufacturers and compresses pricing power among legacy aluminum extruders serving medical and consumer tiers.
Pricing Analysis
Cost-plus contracts with London Metal Exchange aluminum indexation dominate medical-grade reacher procurement, though carbon fiber variants trade on spot precursor markets with volatile margin exposure. Price differentiation hinges on ISO 13485 certification tier and sterilization-cycle durability ratings, with uncertified garden variants facing acute pressure from Chinese contract manufacturers. Hospital systems exhibit lowest price sensitivity due to bundled GPO contracting, while home-use consumers drive aggressive commoditization.
Supply Chain Analysis
Yangtze River Delta port congestion creates chokepoint risk for carbon fiber precursor shipments feeding industrial reacher assembly. Raw material sourcing draws from Chinese aluminum smelters, Japanese carbon fiber producers, and German polymer compounders, with tariff exposure on medical-grade polymer additives threatening margin stability. Distribution runs through Cardinal Health's captive direct-to-facility networks in metropolitan US healthcare systems alongside traditional Medline distributor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 13485 auditor scarcity constrains certification velocity, creating a bottleneck where qualified manufacturers capture disproportionate institutional contract renewals while aspirants face extended quality system implementation timelines.
For Market Incumbents: Compound certification advantages by accelerating MDR technical documentation for novel jaw mechanisms before German notified body review timelines extend further. Secure backward integration into aluminum extrusion capacity in Yangtze River Delta hubs to offset carbon fiber cost volatility threatening industrial segment margins.
For New Entrants and Emerging Players: Anchor in India's PLI scheme corridors around Maharashtra and Gujarat to serve price-sensitive South Asian hospital systems with CDSCO-aligned quality frameworks. Target warehouse automation integrators in Japan's Kanto region where METI ergonomic mandates create specification-captive demand for collaborative robot workstation accessories.
For Investors and Strategic Acquirers: The market sits at a compliance-concentration phase that favors vertically integrated manufacturers with captive ISO 13485 certification and direct hospital contracting relationships. Long-term viability favors acquirers of mid-tier German notified body clients facing consolidation pressure from extended MDR review cycles. Monitor ECHA REACH polymer additive restriction timelines as inflection signal for grip component reformulation investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Acceleration | Qualifies manufacturers for EU MDR hospital supply contracts in Germany and institutional procurement across Europe. |
| Carbon Fiber Precursor Supply Agreement | Locks input pricing for industrial reacher production serving Japanese warehouse automation integrators. |
| Direct-to-Facility Logistics Expansion | Bypasses distributor markups in US metropolitan healthcare systems with centralized materials management. |
| Biocompatibility-Grade Polymer R&D | Opens premium positioning in infection-control-sensitive hospital environments requiring autoclave-resistant grips. |
| India PLI Scheme Manufacturing Footprint | Creates localized supply capacity for price-sensitive institutional buyers across South Asian healthcare systems. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation databases, and METI workplace safety audit records across aluminum extrusion, carbon fiber precursor, and medical device supply chains. Interviews with hospital procurement managers, biomedical engineers, GPO contracts administrators, and warehouse automation integrators were triangulated with customs trade data and SEC filings from diversified medical supply conglomerates. Bottom-up unit economics were cross-validated against top-down market sizing from national health expenditure databases.
Segmentation dimensions modeled include product type tier, material grade, application environment, and size configuration across the analysis window. CAGRs were derived from regression analysis of historical procurement volumes against demographic and regulatory drivers, with aluminum pricing volatility and carbon fiber supply concentration treated as scenario variables. Forecast inputs incorporated EU MDR implementation timelines and Japan METI ergonomic audit penetration rates.
Decision-makers should treat outputs as directional under assumptions of sustained EU MDR compliance cost elevation and continued METI workplace safety directive enforcement; material deviation in regulatory timelines or carbon fiber precursor supply geography would warrant model refresh. Practitioners should keep alternative scenarios live as ECHA REACH polymer additive restrictions and India PLI scheme capacity buildouts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Asia-Pacific Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Underfill Market
Semiconductor Devices
Global Inp Wafer Market
Semiconductor Devices
Data Processing Unit Market
Semiconductor Devices
Quartz Crystal Oscillators Market
Semiconductor Devices
Micro and Nano PLC Market
Semiconductor Devices
Photosensitive Semiconductor Device Market
Semiconductor Devices
Semiconductor in Phones Market
Semiconductor Devices
Global Small Signal Transistor Market
Semiconductor Devices
Nano-Magnetic Devices Market
Semiconductor Devices
Silicon Carbide Mosfets Market
Semiconductor Devices
Semiconductor Memory IP Market
Semiconductor Devices
Gallium Nitride (Gan) Semiconductor Devices Market
Semiconductor Devices
China MCU Market
Semiconductor Devices
India MLCC Market
Semiconductor Devices
Global Gan on Diamond Semiconductor Substrates Market