
 Global Power MOSFET Market | 2026-2036
Global Power MOSFET Market Size, Share, and Industry Trends Forecast 2026-2036
Global Power MOSFET Market Foresight
The EU Green Deal and its embedded efficiency mandates is consolidating procurement priorities across European industrial automation and automotive tiers. Infineon Technologies leverages its SiC and GaN co-development pipelines to sustain technology leadership in high-voltage switching applications. Toshiba Corporation anchors discrete power device supply across Japanese automotive and industrial OEM channels. STMicroelectronics competes through integrated MOSFET-IGBT module portfolios serving renewable energy inverter manufacturers.
Power MOSFETs are voltage-controlled semiconductor switches fabricated on silicon or silicon-carbide substrates with gate oxide insulation, engineered to handle drain-source voltages from 12V to over 900V at switching frequencies exceeding 100kHz. Their primary purpose is efficient power conversion across motor drives, DC-DC converters, and AC-DC rectification systems. Trench MOSFET technology dominates medium-voltage industrial applications where conduction losses determine system efficiency. Super Junction architectures occupy premium price tiers in consumer power supplies demanding compact thermal profiles. Double Diffused MOSFET designs retain cost advantages in mature automotive body electronics segments.
EPA fuel economy standards and the EU F-Gas Regulation shape MOSFET efficiency benchmarks by mandating reduced energy losses in motor control and thermal management systems. China's MIIT dual carbon goals and Japan's METI semiconductor strategy channel domestic foundry capacity toward automotive-grade wide-bandgap device production. ISO 26262 functional safety requirements and IEC 60747-8 standards gate market access for suppliers serving electric drivetrain and medical device OEMs. Stakeholders must monitor foundry allocation shifts between silicon and silicon-carbide process nodes as customer qualification timelines extend.
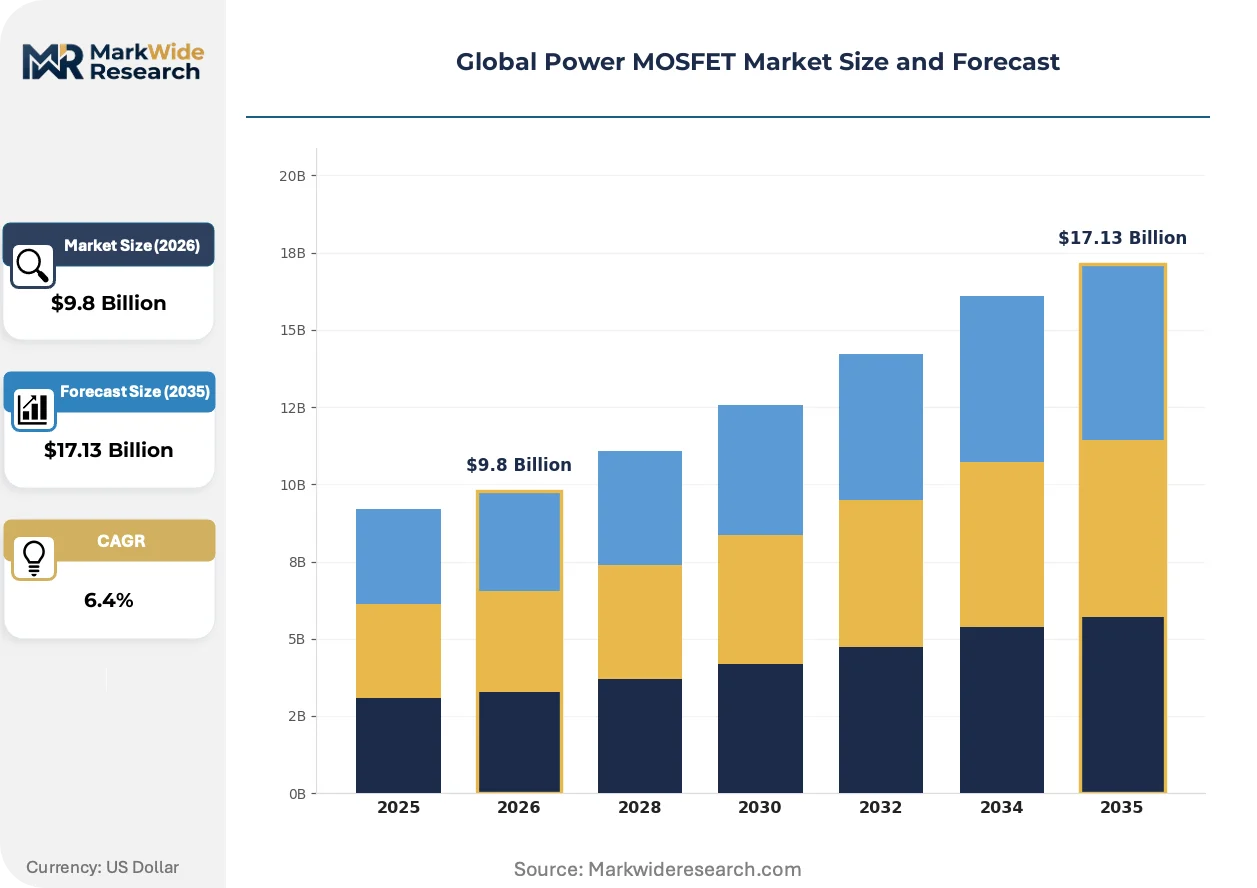
Market Dynamics
Automotive electrification is compressing qualification timelines while fragmenting procurement across silicon and silicon-carbide process nodes. Tier-1 suppliers now dual-source MOSFETs from discrete and integrated module portfolios to hedge against foundry allocation shifts.
Growth Catalysts
- EPA Fuel Economy Standards:Mandates for reduced energy losses in motor control systems are forcing DC-DC converter redesigns across US automotive OEM supply chains.
- Trench MOSFET maturation:Industrial motor drive manufacturers in China are replacing planar designs with trench architectures to cut conduction losses in 400V-600V applications.
- EV powertrain proliferation:Battery electric vehicle traction inverters require 2-4x more MOSFET content per vehicle than internal combustion engine alternatives.
Market Restraints
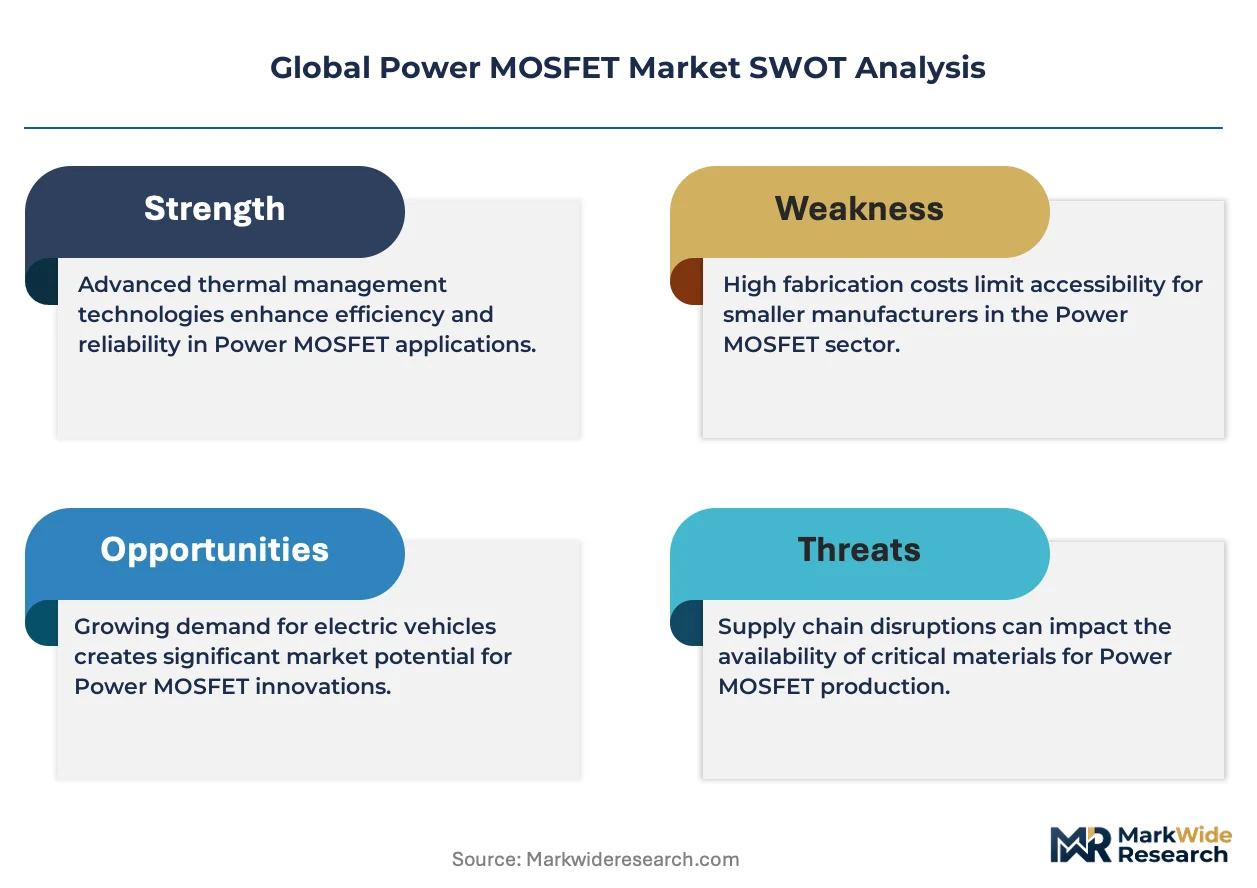
- Silicon-carbide substrate scarcity:Wolfspeed and II-VI capacity constraints limit SiC MOSFET output to premium automotive and aerospace segments.
- ISO 26262 certification burden:Functional safety documentation requirements extend automotive qualification cycles by 18-24 months for new entrants.
- Super Junction cost premium:Epitaxial wafer processing adds 30-40% die cost versus planar MOSFETs, restricting adoption in price-sensitive consumer power supplies.
Strategic Opportunities
- India automotive localization:PLI scheme incentives for power electronics manufacturing are attracting MOSFET packaging investments to serve Maruti Suzuki and Tata Motors.
- GaN-on-Si convergence:650V gallium nitride devices are penetrating sub-10kW solar inverter applications previously reserved for silicon super junction MOSFETs.
- EU F-Gas Regulation:Phase-down of fluorinated greenhouse gases in HVAC systems is accelerating demand for efficient compressor motor drives using advanced MOSFET modules.
Industry Challenges
- Wide-bandgap talent scarcity:Device physics expertise for SiC and GaN process development concentrates at a handful of US and European universities.
- Legacy IGBT qualification inertia:Industrial OEMs with decade-long field-proven inverter designs resist MOSFET migration despite efficiency advantages.
- Dual carbon compliance documentation:China's MIIT carbon accounting requirements add reporting overhead for foundry emissions in MOSFET supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Power MOSFET Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: N-Channel, P-Channel, Depletion Mode, Enhancement Mode Technology: Planar MOSFET, Trench MOSFET, Super Junction, Double Diffused MOSFET, FinFET Application: Consumer Electronics, Renewable Energy Systems, Electric Drives, Power Supplies, Telecommunications End User Industry: Industrial Automation, Aerospace Equipment, Defense Systems, Data Centers, Medical Devices |
| Companies Covered | Toshiba Corporation, Texas Instruments, Infineon Technologies, Renesas Electronics, NXP Semiconductors, STMicroelectronics, ON Semiconductor, Mitsubishi Electric, Vishay Intertechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Power MOSFET Market Shifts & Advancements
Silicon-carbide MOSFET technology is decentralizing power converter architectures across transportation and renewable energy systems. Device manufacturers are racing to match planar silicon cost structures while automotive buyers fragment procurement across multiple substrate technologies.
Silicon-carbide trench MOSFET designs are decentralizing inverter topologies previously dominated by silicon IGBT modules. Electric bus manufacturers in Shenzhen and Daimler's truck divisions are adopting 1200V SiC devices for 800V architectures. This migration compresses thermal management system size by 40% while enabling faster switching frequencies that reduce passive component count.
The EU F-Gas Regulation is mandating refrigerant phase-downs that cascade into compressor motor efficiency requirements. HVAC OEMs must redesign variable-speed drives to meet 2025 leakage thresholds. Japanese and Korean air conditioning manufacturers are responding with integrated intelligent power modules combining super junction MOSFETs with gate drivers.
Direct procurement from foundries is displacing traditional distributor channels for automotive-grade MOSFETs. Tier-1 suppliers like Bosch and Denso are negotiating wafer-start agreements with GlobalFoundries and TSMC. This pattern is most visible in Germany and Japan where just-in-time manufacturing requirements override inventory buffer preferences.
Global Power MOSFET Market Segmentation
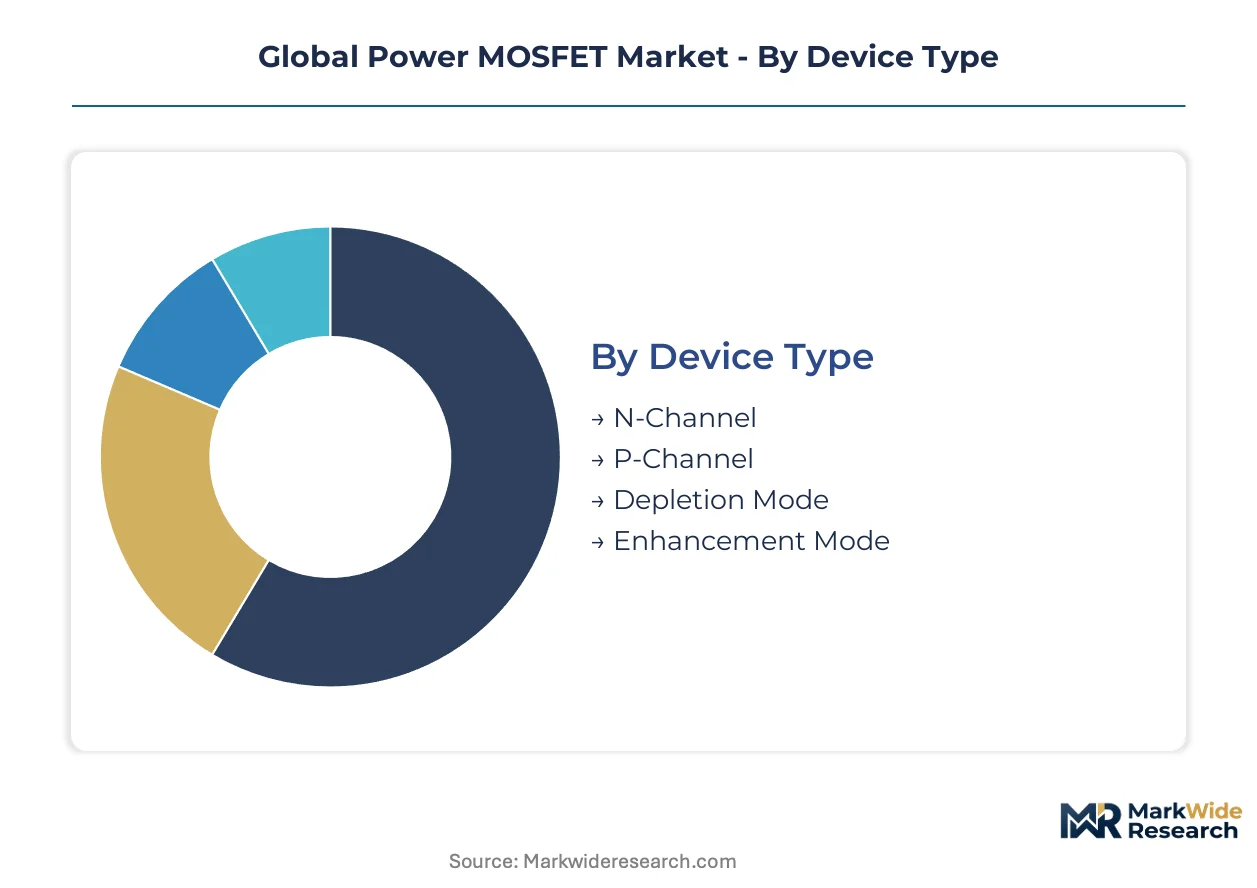
Power MOSFET procurement patterns diverge sharply across device physics, manufacturing geometry, and end-use reliability requirements. Each segmentation axis reveals distinct margin structures and qualification barriers that reshape supplier priorities.
Device Type:
Standardization dominates at the commodity end while depletion-mode variants command premium engineering margins.
- N-Channel:Majority carrier electron conduction delivers lower on-resistance per die area than P-channel alternatives. EV traction inverters in Germany and China specify N-channel devices for 400V-800V battery management systems where conduction losses directly impact range certification.
- P-Channel:Hole-based conduction simplifies high-side switching configurations in automotive body electronics. Japanese tier-1 suppliers specify P-channel MOSFETs for 12V load switching where gate drive complexity reduction outweighs efficiency penalties.
- Depletion Mode:Normally-on operation serves specific fail-safe circuit protection roles in aerospace power distribution.
- Enhancement Mode:Standard normally-off behavior dominates commercial and industrial volume applications.
Most installed capacity flows through N-Channel designs. Expansion is steepest in Depletion Mode for mission-critical redundancy systems.
Technology:
Cost tiers separate mature planar processes from advanced multi-dimensional architectures requiring specialized epitaxial equipment.
- Planar MOSFET:Lateral current flow geometry limits cell density but retains cost advantages in mature process nodes. Chinese foundries supply planar devices for appliance motor drives where 600V blocking ratings suffice and price sensitivity dominates OEM procurement.
- Trench Mrench MOSFET:Vertical channel architecture eliminates JFET resistance component, enabling 50% lower specific on-resistance than planar equivalents. Industrial automation OEMs in Germany and the United States specify trench devices for servo motor drives where thermal management system size constraints drive BOM decisions.
- Super Junction:Charge-compensated pillar structures enable 900V+ ratings in compact die footprints for server power supplies.
- Double Diffused MOSFET:Self-aligned source-body diffusion reduces masking steps for cost-sensitive automotive body electronics.
- FinFET:Three-dimensional gate control addresses short-channel effects in sub-30V logic-compatible power switching.
Foundry utilization peaks in Trench MOSFET capacity. Super Junction commands the steepest expansion trajectory as data center power density requirements intensify.
Application:
Volume concentration versus specification stringency creates divergent qualification timelines across end-use categories.
- Consumer Electronics:Smartphone and laptop adapter demand prioritizes compact thermal profiles over absolute efficiency. Chinese ODMs specify super junction MOSFETs in 65W-100W GaN companion designs where charger miniaturization drives consumer purchasing decisions.
- Renewable Energy Systems:Solar string inverters and wind turbine converters require 20-year operational lifetimes with minimal degradation. European inverter manufacturers qualify silicon-carbide MOSFETs for 1500V DC bus architectures where switching loss reduction improves levelized cost of energy calculations.
- Electric Drives:Industrial motor control and EV traction applications demand automotive-grade reliability documentation.
- Power Supplies:Server and telecom rectifier specifications emphasize efficiency at partial load conditions.
- Telecommunications:Base station power amplifiers require wide-bandgap devices for envelope tracking efficiency.
Production volume concentrates in Consumer Electronics. Renewable Energy Systems show the fastest qualification momentum for wide-bandgap migration.
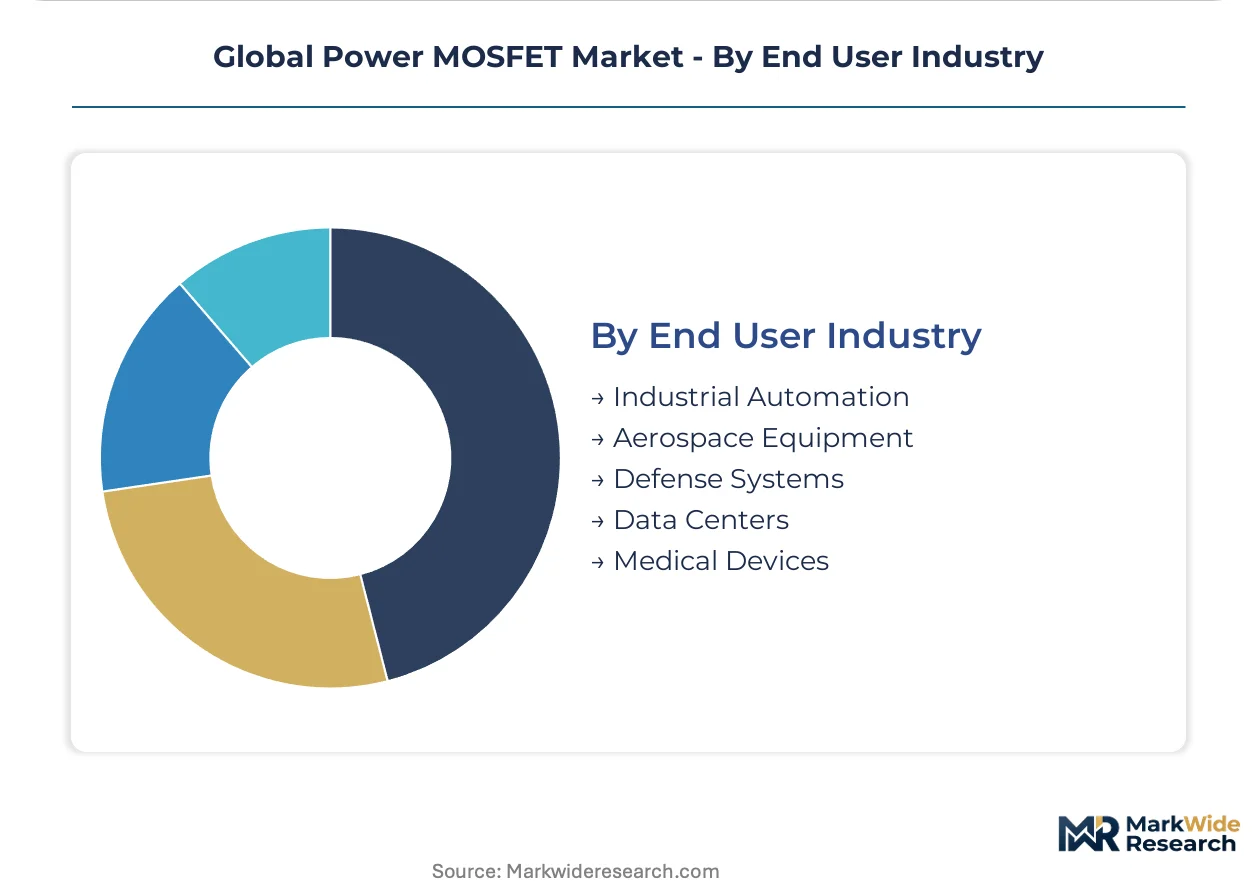
End User Industry:
Customer concentration patterns range from fragmented industrial distribution to captive aerospace supply chains.
- Industrial Automation:Servo drives, robotics, and CNC machine tools require 10-15 year product lifecycle guarantees. German and Japanese machinery OEMs dual-source MOSFETs from discrete and module portfolios to hedge against foundry allocation volatility in power semiconductor capacity.
- Data Centers:Hyperscale operators specify 97%+ efficiency targets for server power supplies that cascade into MOSFET selection criteria. Microsoft and Google procurement teams negotiate directly with device manufacturers for 48V direct conversion architectures that eliminate intermediate bus stages.
- Aerospace Equipment:DO-160 environmental testing and DER certification requirements extend qualification cycles.
- Defense Systems:ITAR and trusted foundry constraints limit supplier pools for radiation-hardened devices.
- Medical Devices:IEC 60601-1 isolation requirements and ISO 13485 quality systems gate market access.
Revenue concentration sits with Industrial Automation. Data Centers are gaining share fastest as AI training load expansion drives power infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power MOSFET manufacturing traces its industrial lineage to Bell Labs' silicon transistor breakthroughs in the United States, with subsequent scaling concentrated in Japanese and German automotive-electronics corridors during the 1980s and 1990s.
China
MIIT dual carbon goals are channeling foundry capacity toward automotive-grade wide-bandgap device production. Domestic OEMs like BYD and NIO are qualifying 800V SiC MOSFETs for traction inverters. The Yangtze River Delta cluster around Shanghai anchors silicon-carbide epitaxial wafer investments serving local EV supply chains.
Germany
KBA emissions protocols and EU Green Deal mandates are compressing procurement timelines across automotive tier-1 suppliers. Industrial automation OEMs in Baden-Württemberg specify trench MOSFETs for servo motor drives where thermal constraints dominate BOM decisions. Bavaria's semiconductor corridor hosts qualification labs for ISO 26262 functional safety certification.
United States
EPA fuel economy standards are forcing DC-DC converter redesigns across Detroit automotive supply chains. FERC grid interconnection rules are accelerating silicon-carbide adoption in utility-scale solar inverters. Texas and Arizona foundry investments are expanding 300mm silicon capacity for power discrete manufacturing.
Japan
METI semiconductor strategy directs domestic capacity toward automotive-grade MOSFET production. Toyota and Honda procurement teams specify P-channel devices for 12V body electronics where gate drive simplification outweighs efficiency trade-offs. The Kyushu silicon island hosts legacy planar MOSFET lines serving appliance motor drive exporters.
India
PLI scheme incentives for power electronics manufacturing are attracting MOSFET packaging investments. Maruti Suzuki and Tata Motors are localizing sourcing for 48V mild-hybrid systems. Gujarat and Tamil Nadu industrial corridors are emerging as backend assembly hubs for discrete power devices.
Global Power MOSFET Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures in power semiconductor supply chains. Integrated device manufacturers retain captive foundry advantages in automotive qualification timelines. Fabless specialists concentrate on application-specific gate driver integration. The competitive arena splits across three archetypes: silicon-carbide substrate owners, trench MOSFET process licensors, and module integration specialists. Capacity expansion and strategic foundry partnerships constitute the dominant competitive moves as allocation volatility reshapes procurement security.
Among diversified semiconductor conglomerates, Toshiba Corporation and Infineon Technologies exemplify integrated manufacturing archetypes with captive silicon and silicon-carbide process development. STMicroelectronics occupies a position bridging discrete MOSFET portfolios with intelligent power module integration for renewable energy inverter manufacturers. These three entities represent distinct competitive postures across substrate technology, automotive qualification depth, and end-use application concentration.
| Leading Market Players |
|---|
| Toshiba Corporation |
| Texas Instruments |
| Infineon Technologies |
| Renesas Electronics |
| NXP Semiconductors |
| STMicroelectronics |
| ON Semiconductor |
| Mitsubishi Electric |
| Vishay Intertechnology |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation refrigerant phase-down mandates gate qualified supply access for compressor motor drive MOSFETs while stratifying pricing tiers across HVAC OEM procurement pools. Tier-1 automotive suppliers now absorb ISO 26262 certification premiums that filter out non-compliant foundries from premium-tier bidding.
Pricing Analysis
Three-tier pricing structure across automotive-grade, industrial-qualified, and consumer-commodity levels segments the MOSFET market by certification burden and thermal performance specifications. Price differentiation hinges on ISO 26262 functional safety documentation depth and foundry traceability for automotive buyers, while consumer electronics procurement prioritizes die shrink cost curves over absolute efficiency metrics. Cost compression in planar silicon tiers intensifies as Chinese foundries expand 600V capacity for appliance motor drives. Industrial automation OEMs in Germany exhibit the lowest price sensitivity, accepting 30-40% die cost premiums for super junction architectures that reduce thermal management system size.
Supply Chain Analysis
Single-source vulnerability sits with silicon-carbide substrate supply concentrated at Wolfspeed and II-VI facilities in the United States. Raw material dependencies draw from high-purity silicon wafers, silicon-carbide boules, and specialized epitaxial equipment anchored in Japan, Germany, and the United States. Tariff exposure on semiconductor manufacturing equipment imports threatens capacity expansion timelines for European and Asian foundries. Distribution runs through direct wafer-start agreements between automotive Tier-1 suppliers and foundries like GlobalFoundries and TSMC, displacing traditional distributor inventory buffers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EV powertrain electrification shifts procurement specifications toward automotive-grade reliability documentation and wide-bandgap thermal performance.
For Market Incumbents: Anticipate GaN-on-Si convergence in sub-10kW solar inverter applications by accelerating 650V device qualification pipelines before silicon super junction MOSFETs lose cost parity. Defend foundry allocation security through captive silicon-carbide substrate agreements that lock epitaxial wafer supply ahead of capacity constraints. Prioritize ISO 26262 certification maintenance as Chinese entrants extend automotive qualification cycles. For New Entrants and Emerging Players: Enter via India automotive localization incentives under the PLI scheme, targeting 48V mild-hybrid MOSFET packaging for Maruti Suzuki and Tata Motors supply chains. White-space concentration sits with depletion-mode device production for aerospace power distribution redundancy systems where mission-critical specifications limit incumbent competition. Pursue joint qualification programs with German industrial automation OEMs seeking dual-source hedges against foundry allocation volatility. For Investors and Strategic Acquirers: Roll-up economics work for trench MOSFET process licensors because automotive electrification is fragmenting procurement across silicon and silicon-carbide nodes while extending customer qualification timelines. Target acquisition archetypes include fabless gate driver integration specialists with existing automotive Tier-1 relationships. Watch for inflection signals in silicon-carbide trench MOSFET adoption rates across 800V EV architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Carbide Capacity Expansion | Wolfspeed and II-VI substrate investments determine automotive-grade MOSFET output availability. |
| Automotive Qualification Acceleration | ISO 26262 documentation depth gates Tier-1 supplier procurement decisions across German OEM channels. |
| Wide-Bandgap Talent Acquisition | Device physics expertise concentration at US and European universities constrains process development velocity. |
| Direct Foundry Partnership | Bosch and Denso wafer-start agreements with TSMC displace distributor inventory buffers. |
| GaN-on-Si Process Migration | 650V gallium nitride penetration into solar inverters threatens silicon super junction MOSFET margins. |
Research Methodology
Direct dialogue with automotive Tier-1 procurement directors, foundry operations managers, industrial automation OEM engineers, and wide-bandgap device physicists grounded this analysis in operational reality. Secondary validation drew from EPA fuel economy filings, EU F-Gas Regulation implementation reports, MIIT dual carbon policy documents, SEC semiconductor capex disclosures, and IHS Markit vehicle production databases. Bottom-up die shipment estimates and top-down inverter content modeling were triangulated against foundry utilization disclosures.
Bottom-up segment modeling tracked MOSFET content per vehicle across battery electric and mild-hybrid architectures, while top-down analysis calibrated against power semiconductor revenue disclosures across the projection horizon. Segmentation dimensions included device physics type, manufacturing geometry, voltage rating tier, end-use reliability specification, and regional regulatory cluster. CAGRs were derived from foundry capacity expansion schedules and OEM platform electrification roadmaps. Key inputs encompassed silicon-carbide substrate supply forecasts and ISO 26262 certification pipeline visibility.
Inputs from foundry utilization reports and automotive platform launch schedules were available through the study window; gaps in silicon-carbide epitaxial wafer yield data introduce uncertainty bands around wide-bandgap adoption trajectories. Forecasts reflect assumptions regarding EV penetration rates, regulatory enforcement timelines, and foundry allocation decisions that could revise materially with policy shifts or substrate supply disruptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global Current Sense Amplifier Market
Semiconductor Devices
Home Appliance MCU Market
Semiconductor Devices
3D TSV Device Market
Semiconductor Devices
High Resistivity Silicon Wafers Market
Semiconductor Devices
Mosfet Power Transistors Market
Semiconductor Devices
Advanced HDI PCB Market
Semiconductor Devices
VCSEL Market
Semiconductor Devices
Global Transistor Market
Semiconductor Devices
Japan CEP Market
Semiconductor Devices
South Korea MLCC Market
Semiconductor Devices
Chip Equalizers Market
Semiconductor Devices
Semiconductor Memory Market
Semiconductor Devices
Middle East and Africa Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Hairpin Stator Market
Semiconductor Devices
Americas Microcontroller (MCU) Market
Semiconductor Devices
Europe Room Cell Module Market