
 Crystal Oscillators Market | 2026-2036
Crystal Oscillators Market Size, Share, and Industry Trends Forecast 2026-2036
Crystal Oscillators Market Intelligence
MEMS-based timing is rewriting the competitive architecture of frequency control, displacing legacy quartz architectures in portable and automotive systems. SiTime Corporation leverages silicon wafer-scale packaging to reduce footprint and power draw across consumer wearables. Seiko Epson Corporation anchors high-volume AT-cut production for precision instruments and industrial automation. KYOCERA Corporation dominates ceramic-packaged oscillators for harsh-environment automotive modules, sustaining qualification pipelines with Tier-1 suppliers.
Crystal oscillators are electromechanical resonators that exploit the piezoelectric properties of synthetic quartz to generate stable clock signals, typically operating from kilohertz to several hundred megahertz with temperature coefficients measured in parts per million. Their primary purpose is to provide reference timing for microprocessors, communication transceivers, and navigation equipment where phase noise and frequency stability determine system performance. AT-cut crystals occupy the mature volume tier in consumer electronics and computing, while SC-cut variants command premium positioning in satellite and military applications where thermal hysteresis must be minimized. The high-frequency segment is expanding fastest as 5G mmWave and automotive radar push reference clocks beyond 100 MHz, concentrating margin pools with vendors qualified for AEC-Q200 stress testing.
The FCC in the United States enforces electromagnetic compatibility standards that shape oscillator phase-noise specifications for wireless infrastructure deployed domestically. ETSI in Europe and Japan's MIC impose additional spurious-emission limits that filter non-compliant suppliers from base-station procurement lists. REACH and RoHS constrain the metallization and sealing materials permissible in hermetic packages, raising qualification costs for new entrants. Stakeholders must monitor the divergence between MEMS and quartz reliability databases as automotive OEMs recalibrate sourcing strategies for software-defined vehicle platforms.
Market Dynamics
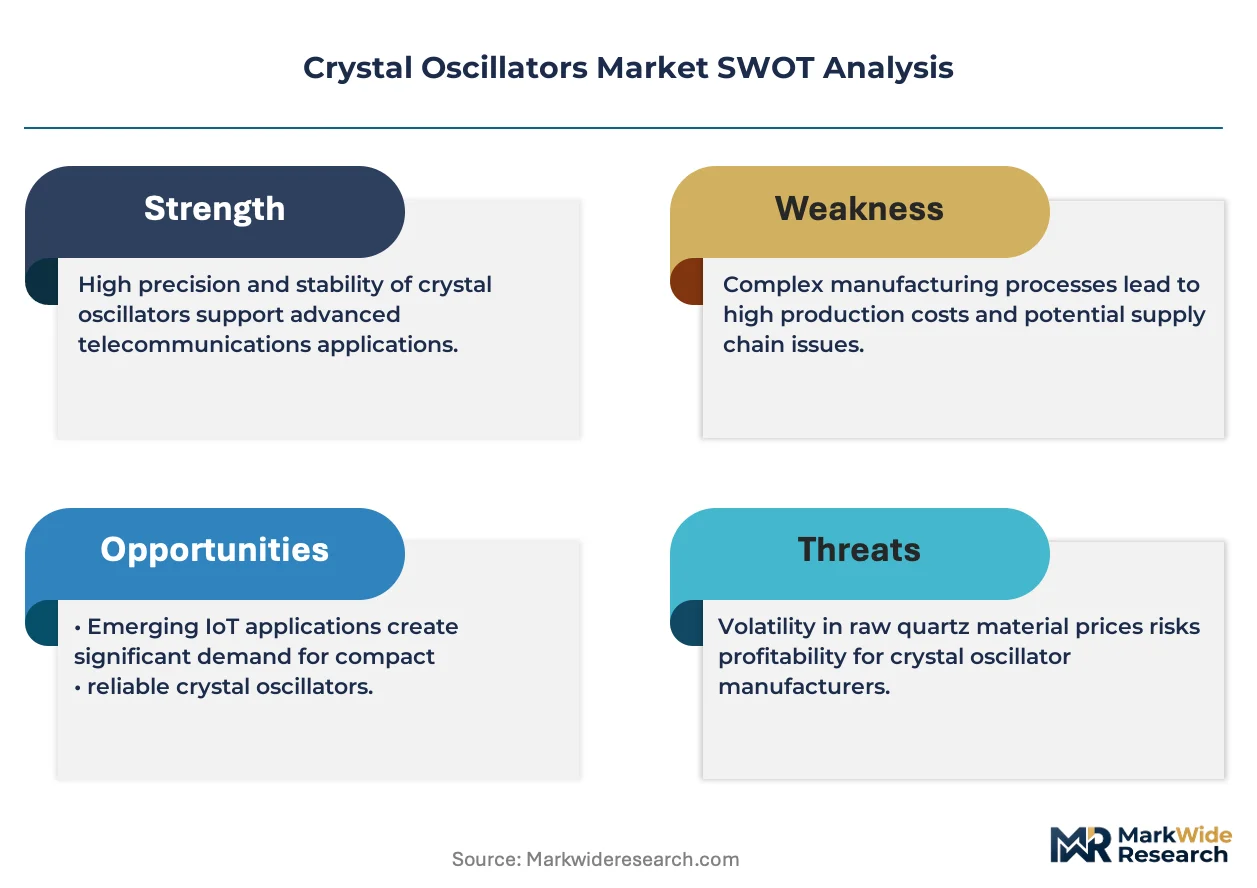
MEMS silicon resonators are compressing the addressable market for legacy quartz architectures, forcing incumbent suppliers to defend frequency stability benchmarks while automotive OEMs recalibrate qualification pipelines for software-defined vehicle platforms.
Growth Catalysts
- 5G mmWave Infrastructure:Base station deployments across China, the United States, and Germany are pulling high-frequency oscillator volume through the supply chain, with carriers specifying phase-noise performance below 100 femtoseconds for beamforming synchronization.
- RoHS Material Exemptions:The European Union's restricted substance framework is accelerating lead-free solder adoption in hermetic ceramic packages, qualifying new metallization chemistries for automotive AEC-Q200 certification.
- Automotive Radar Integration:Tier-1 module suppliers in Japan and South Korea are specifying temperature-compensated oscillators above 100 MHz for 77-81 GHz frequency-modulated continuous-wave systems in advanced driver-assistance platforms.
Market Restraints
- Synthetic Quartz Supply Concentration:High-purity cultured quartz crucible production concentrates in Chinese and Russian feedstock operations, exposing oscillator blank fabricators to geopolitical supply interruptions and purity specification drift.
- MEMS Frequency Stability Ceiling:Silicon-based resonators exhibit temperature coefficients an order of magnitude higher than SC-cut quartz, disqualifying them from satellite payload and precision navigation applications requiring sub-ppm thermal hysteresis.
- REACH Compliance Escalation:ECHA's candidate list expansion for Substances of Very High Concern is forcing reformulation of gold-tin preform alloys used in seam-sealed metal packages, extending qualification cycles for European automotive contracts.
Strategic Opportunities
- India Electronics Manufacturing:The country's production-linked incentive scheme for semiconductor packaging is attracting frequency control component assembly for domestic smartphone and telecom equipment consumption.
- Optical Timing Distribution:Convergence of photonic integrated circuits with low-jitter oscillators is enabling picosecond-synchronized data centers, with hyperscale operators in the United States piloting chip-scale atomic clock integration.
- Space-Qualified Component Shortage:Radiation-hardened oscillator procurement lists from ESA and NASA are undersupplied, creating qualification pathways for vendors with MIL-PRF-55310 heritage manufacturing.
Industry Challenges
- Frequency Synthesizer Integration:System-on-chip designers are embedding digitally controlled oscillators into RF transceivers, compressing discrete component attach rates and forcing quartz suppliers to demonstrate additive phase-noise value.
- Cleanroom Capacity Constraints:Class 100 wafer-level packaging for MEMS timing devices requires capital-intensive fab conversions, straining mid-tier suppliers attempting backward integration into resonator fabrication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crystal Oscillators Market |
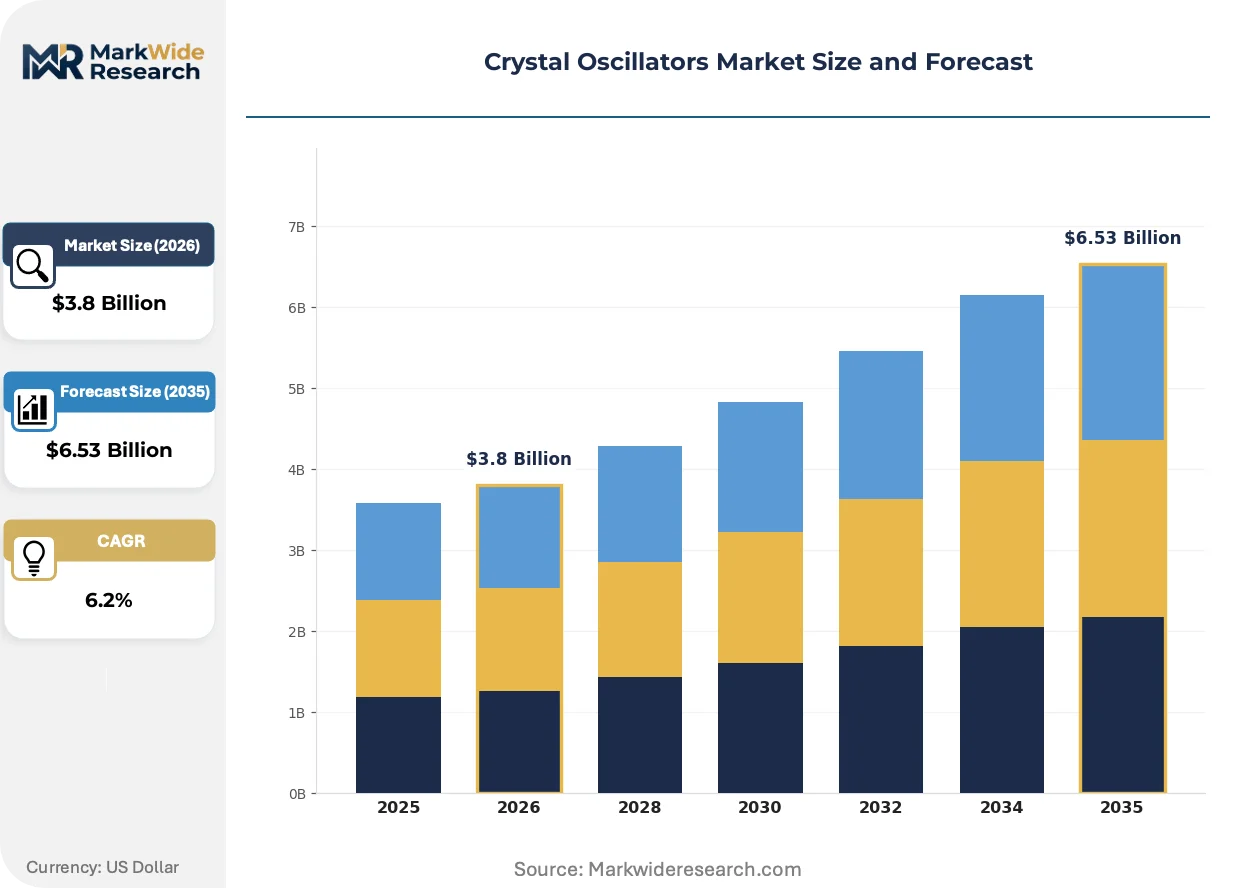
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AT Cut, BT Cut, SC Cut, OC Cut Application: Consumer Electronics, Telecommunication, Automotive, Industrial Machinery End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Research Institutions Frequency Range: Low Frequency, High Frequency, Ultra High Frequency, Others |
| Companies Covered | Murata Manufacturing Co. Ltd., SiTime Corporation, Seiko Epson Corporation, SIWARD Crystal Technology Co. Ltd., Microchip Technology Inc., Nihon Dempa Kogyo Co. Ltd., KYOCERA Corporation, Rakon Limited, TXC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crystal Oscillators Market Strategic Shifts & Innovations
Frequency control is experiencing architectural bifurcation between silicon-scale integration and precision quartz heritage, with packaging innovation and regulatory chemistry constraints determining competitive survival.
Silicon photonics clock distribution is virtualizing the physical layer of timing networks, replacing copper trace jitter accumulation with optical pulse propagation. Hyperscale data center operators in the United States are piloting co-packaged optics with integrated laser-locked oscillators. This convergence is virtualizing traditional PCB-level clock tree design, collapsing discrete buffer and oscillator counts per rack.
REACH authorization requirements are tightening supply chains for hermetic seal materials across European automotive and industrial markets. ECHA's 2024 update to the candidate list added several bisphenol derivatives used in ceramic package epoxy formulations. German and French module suppliers are accelerating qualification of alternative resin systems to maintain CE marking compliance for frequency control components.
Automotive OEMs are compressing oscillator qualification cycles from 24 months to 14 months as software-defined vehicle platforms iterate faster than hardware refresh timelines. Tier-1 suppliers in Japan and South Korea are responding with accelerated temperature cycling protocols that simulate 15-year vehicle life in 6 months. This behavioral shift favors oscillator vendors with existing AEC-Q200 databases over entrants facing de novo reliability accumulation.
Crystal Oscillators Market Segmentation
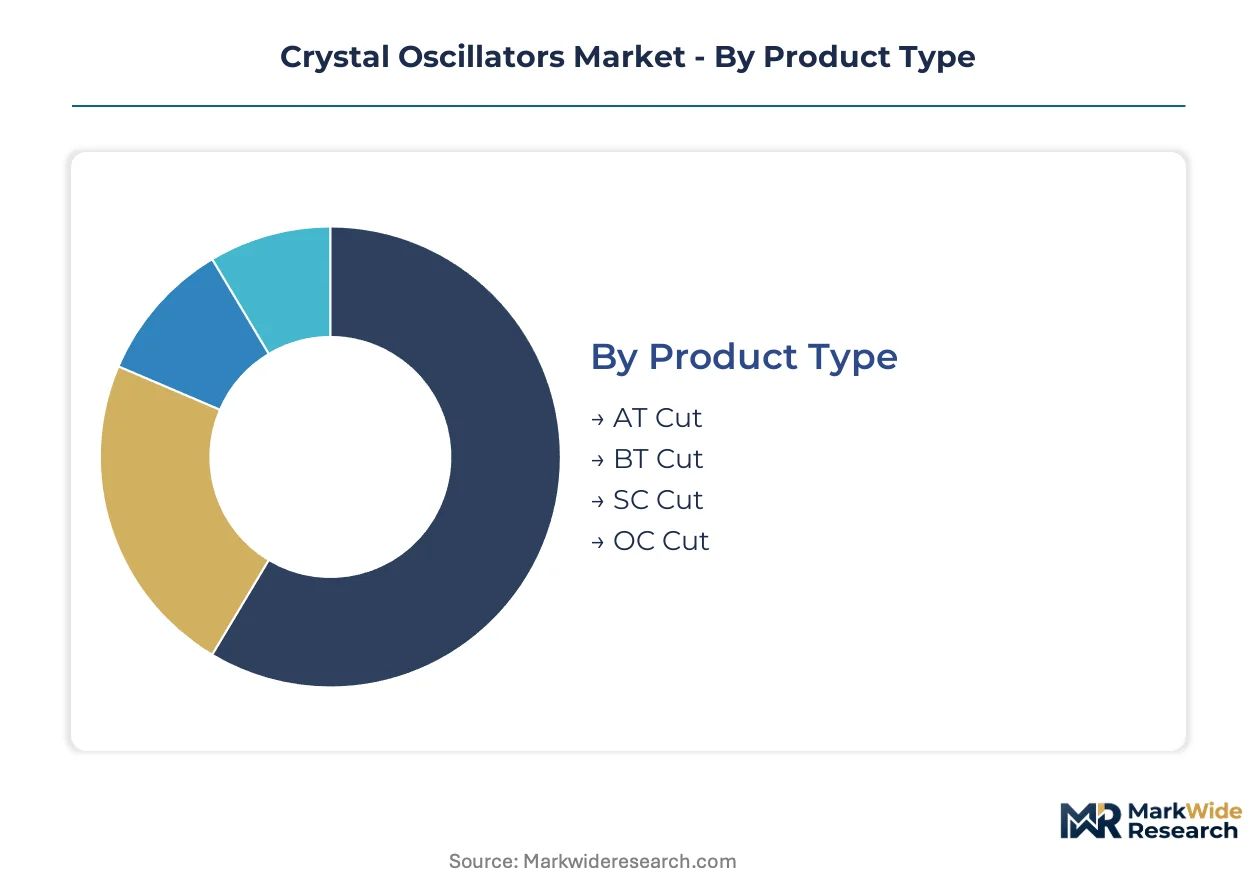
Crystal oscillator procurement patterns diverge sharply across frequency bands and thermal stability requirements, with each segment demanding distinct qualification protocols and service support models. Component selection in precision timing applications hinges on cut geometry, package hermeticity, and temperature coefficient specifications that vary by end-use criticality.
Product Type:
After-sales calibration and aging compensation services concentrate heavily around temperature-stable cuts, with field service intensity scaling directly with precision tier.
- AT Cut:The dominant volume cut operates at 35°15′ orientation with moderate temperature coefficient, serving consumer electronics and computing where cost efficiency outweighs thermal hysteresis concerns. Demand concentrates in Shenzhen and Dongguan contract manufacturing clusters for smartphone and tablet reference clocks, though margin compression from MEMS alternatives is accelerating.
- SC Cut:Stress-compensated geometry eliminates first-order temperature coefficient near turnover point, commanding premium positioning in satellite payloads and precision navigation. European space agencies and military procurement lists specify SC-cut oscillators for orbital applications where thermal cycling extremes demand sub-ppm stability.
- BT Cut:Higher frequency fundamental mode operation suits specific filter applications with reduced temperature range requirements. Japanese industrial automation vendors specify BT-cut resonators for factory timing networks.
- OC Cut:Oven-controlled variants integrate heating elements for parts-per-billion stability, serving telecommunications infrastructure and scientific instrumentation. German base station OEMs maintain qualification pipelines for OC-cut references in 5G synchronization.
AT Cut holds the largest share; momentum sits with SC Cut.
Application:
Cost tier stratification separates commodity consumer references from automotive-qualified units bearing AEC-Q200 certification premiums.
- Telecommunication:Base station and optical transport equipment specify phase-noise performance below 100 femtoseconds for beamforming synchronization. Chinese carriers drive volume through state-backed 5G infrastructure programs, while German operators impose ETSI spurious emission limits that filter supplier lists.
- Automotive:ADAS radar modules and domain controller clocks require temperature-compensated oscillators above 100 MHz with 15-year reliability databases. Tier-1 suppliers in Japan and South Korea specify AEC-Q200 qualification for 77-81 GHz frequency-modulated continuous-wave systems.
- Consumer Electronics:Wearables and smartphones prioritize footprint and power draw over absolute stability, exposing this tier to MEMS displacement. Assembly concentrates in Vietnam and India under production-linked incentive schemes.
- Industrial Machinery:Factory automation networks demand vibration-resistant hermetic packages for programmable logic controller timing. German and Italian machine builders specify ceramic-packaged units for harsh environments.
Telecommunication represents the highest-value tier; automotive climbs fastest on radar integration.
End User:
Volume concentration varies dramatically across the procurement chain, with qualification burden and technical support intensity inversely correlated with purchase scale.
- Tier-1 Suppliers:Module integrators in automotive and telecom consolidate oscillator specifications across multi-year platform contracts, driving qualification standardization. Japanese and South Korean Tier-1s compress validation cycles to 14 months for software-defined vehicle platforms.
- OEMs:Original equipment manufacturers in networking and aerospace maintain approved vendor lists with MIL-PRF-55310 heritage requirements. US defense contractors specify radiation-hardened oscillators for satellite payloads.
- Aftermarket Providers:Replacement timing components for industrial equipment and legacy telecom infrastructure require backward compatibility documentation. European maintenance networks demand REACH-compliant packaging for field swaps.
- Research Institutions:Scientific instrumentation and experimental physics applications specify custom frequency and stability parameters. National laboratories in the United States and Germany procure ultra-stable references for atomic clock comparisons.
Tier-1 Suppliers command the greatest volume leverage; aftermarket Providers face margin pressure from module integration trends.
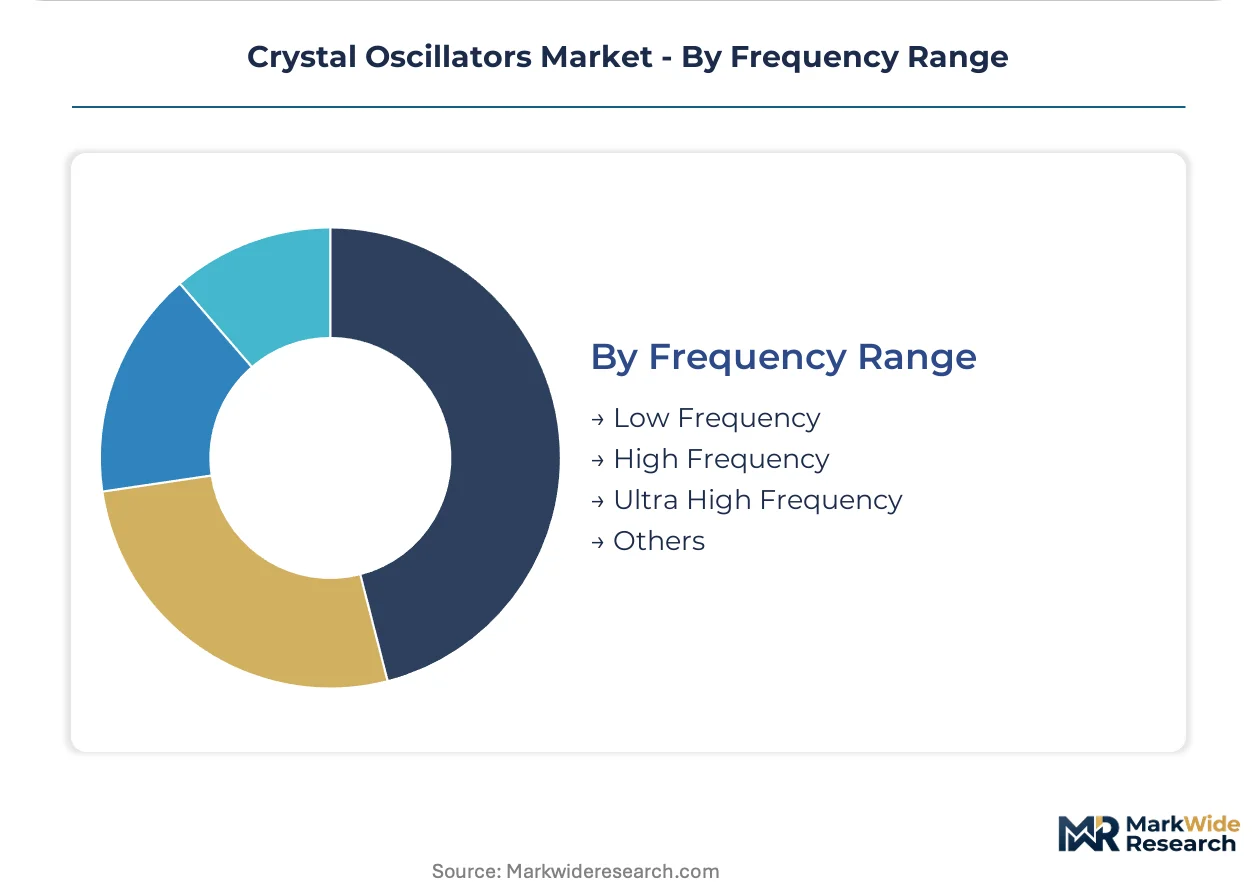
Frequency Range:
Supply chain configuration shifts with frequency tier, with ultra-high-frequency units demanding specialized photolithography and wafer thinning processes.
- High Frequency:100-500 MHz references serve 5G mmWave and automotive radar with fundamental or third-overtone crystal operation. Chinese base station deployments and Korean automotive radar programs concentrate demand.
- Ultra High Frequency:Above-500 MHz signals require inverted mesa or surface-mount MEMS architectures for phase-locked loop references. US hyperscale data centers pilot optical timing distribution at these frequencies.
- Low Frequency:32.768 kHz tuning-fork crystals dominate real-time clock applications in battery-powered devices. Taiwan and China blank fabricators supply watch and IoT module manufacturers.
- Others:Specialized frequency standards including atomic clock disciplined oscillators and chip-scale atomic clock integration serve precision timing networks. US government laboratories and European metrology institutes specify these tiers.
High Frequency dominates current revenue; Ultra High Frequency expands most quickly on photonic integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in frequency control components tilt toward net imports in Western markets while East Asian economies maintain substantial quartz blank and packaged oscillator surpluses. Currency-adjusted procurement costs and qualification timelines shape regional sourcing strategies.
China
Domestic 5G base station deployments by China Mobile, China Telecom, and China Unicom absorb substantial high-frequency oscillator volume. MIIT mandates phase-noise specifications for mmWave infrastructure that filter supplier qualification lists. Dongguan and Shenzhen clusters concentrate contract manufacturing for consumer electronics reference clocks, though REACH-compliant export packaging adds cost overhead for European-bound shipments.
United States
FCC electromagnetic compatibility enforcement shapes oscillator phase-noise benchmarks for domestic wireless infrastructure procurement. Hyperscale data center operators in Northern Virginia and Oregon pilot optical timing distribution with integrated laser-locked oscillators. Defense contractors specify MIL-PRF-55310 heritage manufacturing for satellite payloads, creating qualification barriers for non-domestic suppliers.
Germany
ETSI spurious-emission limits filter base-station supplier lists for Deutsche Telekom and Vodafone procurement. ECHA REACH candidate list expansions force reformulation of ceramic package epoxy formulations used in industrial automation timing modules. Bavarian machine builders specify vibration-resistant hermetic packages for programmable logic controller networks in automotive and chemical process industries.
Japan
METI industrial standards govern frequency stability specifications for precision instrumentation and telecommunications equipment. Tier-1 automotive module suppliers in Aichi Prefecture compress oscillator qualification cycles to 14 months for software-defined vehicle platforms. Kyushu-based fabricators maintain AT-cut production lines for consumer electronics while shifting SC-cut capacity toward satellite and defense applications.
South Korea
Automotive radar integration for 77-81 GHz frequency-modulated continuous-wave systems drives temperature-compensated oscillator specifications above 100 MHz. MFDS regulatory frameworks for electromagnetic compatibility align with ETSI standards for European export qualification. Gyeonggi-do clusters concentrate assembly operations for smartphone and wearable reference clocks under production-linked incentive schemes.
Crystal Oscillators Market Key Industry Players
On the supply side, the industry is bifurcated between silicon-scale MEMS integration and precision quartz heritage manufacturing, with packaging innovation and regulatory chemistry constraints determining competitive survival. Strategic archetypes include wafer-scale silicon resonator specialists, high-volume AT-cut fabricators, and ceramic-packaged harsh-environment suppliers. Dominant competitive moves center on accelerated automotive qualification pipelines and backward integration into resonator fabrication.
Within the MEMS timing tier, SiTime Corporation exemplifies silicon wafer-scale packaging approaches that reduce footprint and power draw. Seiko Epson Corporation anchors high-volume AT-cut production for precision instruments. KYOCERA Corporation occupies a position within ceramic-packaged oscillators for harsh-environment automotive modules, sustaining qualification relationships with Tier-1 suppliers.
| Leading Market Players |
|---|
| Murata Manufacturing Co. Ltd. |
| SiTime Corporation |
| Seiko Epson Corporation |
| SIWARD Crystal Technology Co. Ltd. |
| Microchip Technology Inc. |
| Nihon Dempa Kogyo Co. Ltd. |
| KYOCERA Corporation |
| Rakon Limited |
| TXC Corporation |
| Others |
Cost & Logistics Intelligence
Chinese and Russian high-purity cultured quartz feedstock operations concentrate upstream blank fabrication, tethering margin pools to vendors with captive crucible supply or long-term offtake arrangements. This upstream chokepoint amplifies pricing power for qualified SC-cut suppliers serving satellite and military procurement lists.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on AEC-Q200 certification grade and volume scale, with automotive-qualified units commanding substantial premiums over consumer-grade references. Pricing pressure stems from MEMS displacement in wearables and smartphones, compressing AT-cut margins. Contract manufacturers in Vietnam and India exhibit highest price sensitivity, while European space agencies demonstrate lowest sensitivity for radiation-hardened specifications.
Supply Chain Analysis
Export-control restrictions on high-purity quartz synthesis technology limit feedstock expansion outside China and Russia, constraining supply diversification. Raw material dependencies center on synthetic quartz crucibles, gold-tin preform alloys, and ceramic package epoxy formulations. Single-source vulnerability concentrates in Chinese blank fabrication clusters. Distribution runs through Tier-1 module suppliers in Japan and South Korea for automotive qualification, with direct OEM procurement dominating aerospace and defense tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized fabrication capabilities for SC-cut geometry and space-qualified packaging constitute scarce assets that concentrate competitive advantage among heritage manufacturers. This capability gap widens as automotive OEMs compress qualification timelines faster than new entrants can accumulate reliability databases.
For Market Incumbents: Entrench AEC-Q200 qualification pipelines through accelerated temperature cycling protocols that simulate 15-year vehicle life in compressed windows. Deepen backward integration into resonator fabrication to secure quartz blank supply against Chinese feedstock concentration. Prioritize ceramic package chemistry reformulation to maintain CE marking compliance under REACH candidate list expansions.
For New Entrants and Emerging Players: India's production-linked incentive scheme for semiconductor packaging offers underpenetrated assembly capacity for domestic smartphone and telecom equipment consumption. Target optical timing distribution pilots at US hyperscale data centers as the most penetrable white-space segment. Pursue chip-scale atomic clock integration partnerships with photonic integrated circuit developers as the primary go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across MEMS wafer-scale packaging as Class 100 cleanroom conversions strain mid-tier suppliers. Long-term viability favors vendors with dual quartz-MEMS capability portfolios spanning consumer displacement and precision heritage markets. Acquisition target archetype: ceramic-packaged harsh-environment specialists with existing Tier-1 automotive relationships. Monitor divergence between MEMS and quartz reliability databases as the critical inflection signal for automotive sourcing recalibration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resonator Fabrication | Captive quartz blank supply insulates margin from Chinese feedstock concentration. |
| Accelerated Automotive Qualification Protocols | 14-month validation cycles align oscillator suppliers with software-defined vehicle platform iterations. |
| REACH-Compliant Package Chemistry Reformulation | Alternative resin systems preserve CE marking access for European automotive contracts. |
| Optical Timing Distribution Partnerships | Co-packaged optics with laser-locked oscillators capture hyperscale data center pilot demand. |
| Space-Qualified Heritage Manufacturing Investment | MIL-PRF-55310 certification opens undersupplied ESA and NASA procurement pathways. |
Research Approach
Cross-validation between primary fieldwork with oscillator procurement managers and secondary trade data anchors the qualitative findings. Interviews with Tier-1 supplier sourcing directors, AEC-Q200 qualification engineers, space agency component specialists, and foundry operations heads informed supply-side dynamics. Secondary sources include FCC electromagnetic compatibility filings, ECHA REACH candidate list updates, MIIT base station specifications, and customs records for quartz blank trade flows. Bottom-up segment sizing triangulates against top-down industry revenue estimates.
Calibration against historical shipment data and announced capacity expansions shapes the projection framework. Segmentation dimensions span cut geometry, package hermeticity, frequency tier, and end-use criticality across the analysis window. CAGRs derive from elasticity-adjusted demand curves for 5G infrastructure and automotive radar integration. Industry-specific inputs include announced base station deployment schedules and automotive platform clock content specifications.
The forecast holds incumbent behavior within observed patterns; aggressive moves by MEMS specialists into precision navigation tiers would shift outcomes. Material shifts in Chinese export restrictions on high-purity quartz synthesis technology would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
GPIO Expanders Market
Electronic Components
Lead Zirconate Titanate (PZT) Market
Electronic Components
Robotic Flat Cable Market
Electronic Components
Ceramic Capacitors Market
Electronic Components
High Precision Mechanical Machine Components Market
Electronic Components
Europe Radiation-Hardened Electronics Market
Electronic Components
Speaker Membranes Market
Electronic Components
Efuse Market
Electronic Components
Gigabit Interface Converter Market
Electronic Components
5G Base Station BAW Filters Market
Electronic Components
High-Voltage Interlock Loop Wiring Components Market
Electronic Components
Touchless Tubes Market
Electronic Components
Camera Battery Charger Market
Electronic Components
High-Voltage Capacitor Market
Electronic Components
Braking Resistors Market
Electronic Components
Gas Discharge Tube Market