
 United Arab Emirates (UAE) CEP Market | 2026-2036
United Arab Emirates (UAE) CEP Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates (UAE) CEP Market Analytics
The UAE is tilting toward integrated logistics capacity with dedicated e-commerce fulfillment zones in Dubai South and KIZAD. Aramex leverages its regional courier density to anchor Gulf last-mile networks. DHL Express competes through bonded warehouse infrastructure at Dubai International Airport. Emirates Post Group sustains universal service obligations while digitizing parcel tracking across the seven emirates.
Courier, Express, and Parcel (CEP) services encompass time-definite shipment of documents and packages through integrated pickup, sortation, line-haul, and delivery networks operating on service level agreements measured in hours or days. The sector relies on automated hub-and-spoke sortation achieving throughput above parcel-per-second rates, real-time track-and-trace via GPS-telemetry, and temperature-controlled vehicles for pharmaceutical and perishable cargo. Healthcare product type segments command premium pricing due to MOHAP-validated cold-chain protocols, while IoT Solutions technology layers are penetrating fastest as fleet operators deploy telematics for predictive routing and fuel optimization. RFID Systems maintain steady adoption in high-value asset tracking for automotive and industrial verticals.
MOHAP governs pharmaceutical distribution standards, while the UAE Central Bank supervises cash-in-transit CEP operations through licensing frameworks. CE marking alignment for cross-border EU parcel flows and local TRAI-equivalent telecommunications coordination for IoT fleet connectivity both shape compliance costs. Stakeholders must weigh capital allocation between autonomous delivery pilots and warehouse automation as labor availability tightens in Dubai and Abu Dhabi.
Market Dynamics
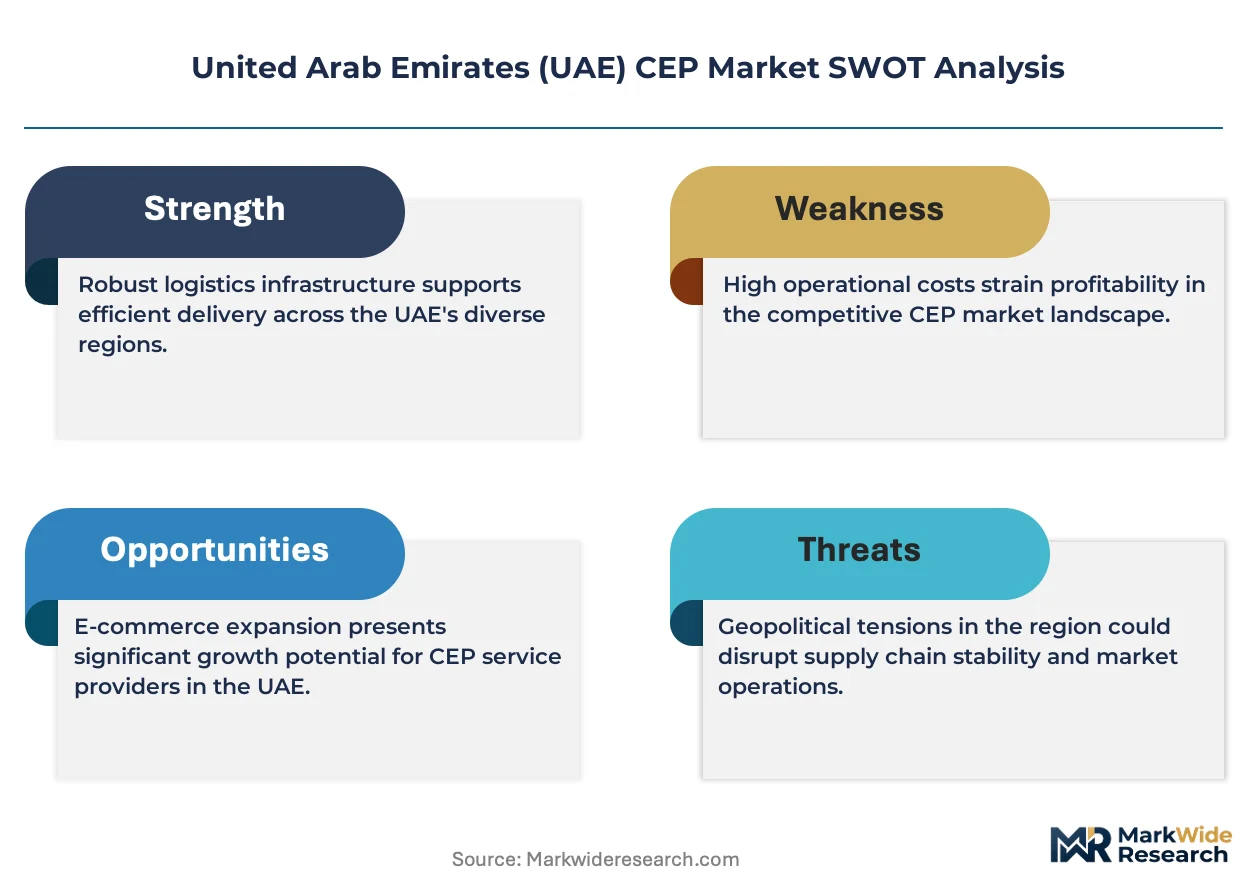
MOHAP pharmaceutical distribution standards are compressing cold-chain compliance timelines while Dubai South e-commerce fulfillment zones absorb capital flows from traditional warehousing. Labor availability constraints in Dubai and Abu Dhabi are forcing automation trade-offs against last-mile density investments.
Growth Catalysts
- Dubai South Fulfillment Zones:Dedicated e-commerce logistics parks are consolidating parcel sortation capacity within bonded free trade corridors. Retailers are relocating inventory closer to consumer clusters in Al Maktoum International Airport catchment areas.
- MOHAP Cold-Chain Mandates:Pharmaceutical distribution regulations now require validated temperature protocols for vaccine and biologic shipments. CEP operators are retrofitting vehicle fleets with IoT-enabled telemetry to maintain compliance documentation.
- RFID Asset Tracking:Automotive and industrial verticals are deploying radio-frequency identification systems for high-value cargo visibility. Real-time inventory positioning is reducing loss rates in cross-emirate line-haul operations.
Market Restraints
- Labor Pool Constraints:Visa sponsorship costs and accommodation requirements are inflating per-delivery economics in Dubai and Abu Dhabi. Fleet operators face recruitment bottlenecks for licensed commercial drivers.
- Real Estate Concentration:Warehouse and sortation facility availability clusters around Jebel Ali and KIZAD industrial zones. Secondary emirates lack comparable logistics infrastructure, limiting network reach.
- Cross-Border Documentation:CE marking alignment for EU-bound parcel flows adds customs processing layers. Gulf Cooperation Council customs harmonization remains incomplete, creating friction in Saudi and Oman corridors.
Strategic Opportunities
- Autonomous Delivery Pilots:Dubai Roads and Transport Authority permitting frameworks are opening controlled zones for drone and robotic last-mile testing. E-commerce platforms are partnering with technology providers for corridor-specific deployment.
- Abu Dhabi Industrial Free Zones:KIZAD and Khalifa Port are attracting pharmaceutical manufacturers requiring integrated CEP services. Temperature-controlled warehousing demand is outpacing regional supply.
- IoT-Telematics Convergence:Fleet operators are layering predictive routing algorithms over GPS-telemetry infrastructure. Fuel optimization and dynamic capacity allocation are emerging as service differentiators.
Industry Challenges
- Legacy System Integration:Emirates Post Group and established courier networks operate on fragmented track-and-trace platforms. Unified parcel visibility across seven emirates requires substantial middleware investment.
- Certification Timeline Compression:MOHAP validation protocols for cold-chain vehicles and warehouses are extending equipment procurement cycles. Operators face working capital pressure during compliance qualification periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates (UAE) CEP Market |
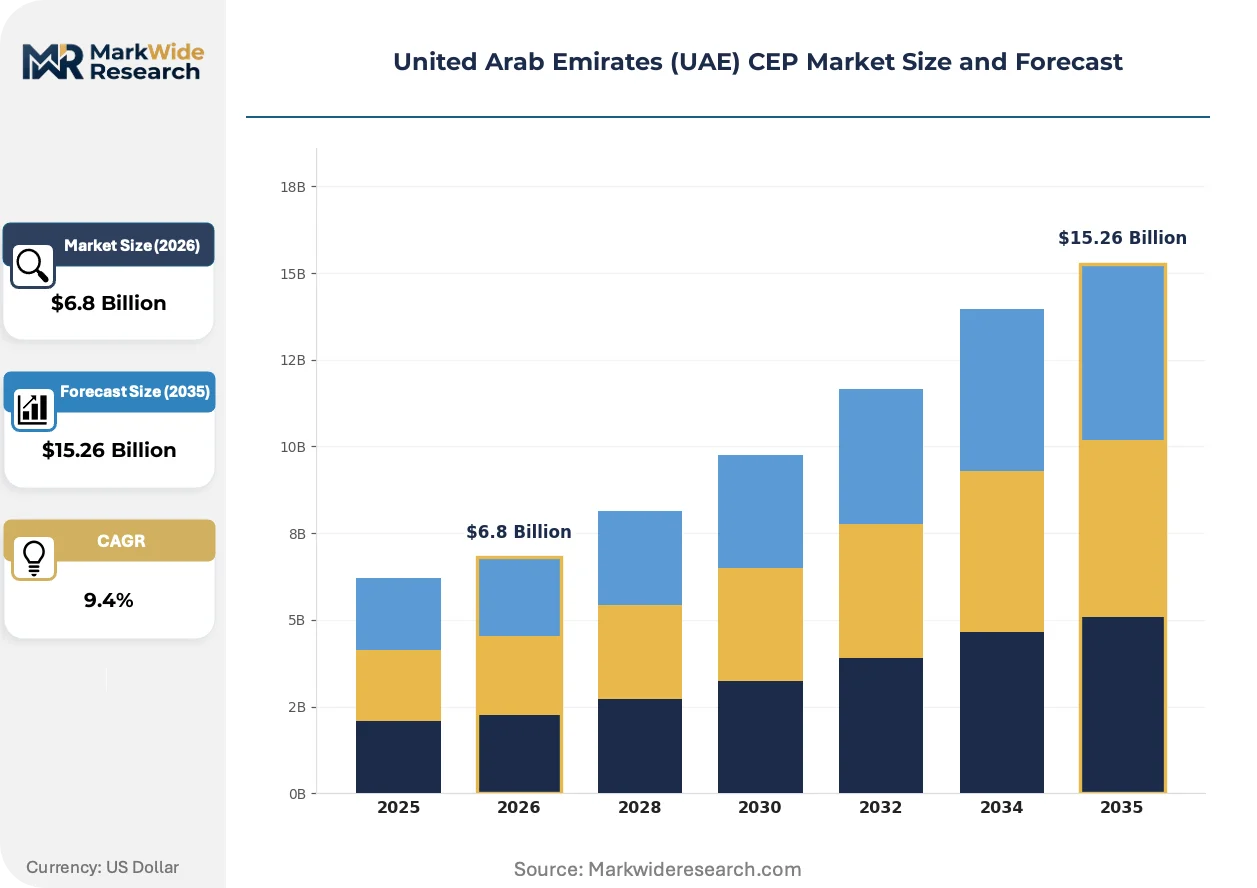
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Healthcare, Automotive, Industrial, Telecommunications Application: Fuel Management, Supply Chain, Energy Efficiency, Asset Tracking End User: Government, Retailers, Logistics, Manufacturing Technology: IoT Solutions, Cloud Computing, RFID Systems, AI Analytics |
| Companies Covered | FedEx, Amazon Logistics, Aramex, DB Schenker, TNT Express, DHL Express, UPS, Geodis, Emirates Post Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates (UAE) CEP Market Evolving Landscape
Digitization of parcel documentation and fleet telemetry is restructuring competitive advantage around data velocity rather than physical network scale alone.
Digital twin platforms are virtualizing warehouse layout optimization and delivery route simulation before physical deployment. Third-party logistics providers in Dubai South are adopting these systems to compress fulfillment center commissioning timelines. The technology is virtualizing capital allocation decisions between automation and labor-intensive operations.
MOHAP pharmaceutical distribution standards are tightening documentation requirements for temperature excursion reporting. Cold-chain CEP operators must now maintain continuous data logging with audit-ready retrieval protocols. Healthcare product segments are absorbing compliance costs through premium service tier pricing.
Subscription-based e-commerce procurement models are displacing transactional parcel volumes with predictable recurring delivery patterns. Fashion and beauty retailers in Dubai are shifting from marketplace dependency to direct-to-consumer channels. This behavioral pivot concentrates volume with integrated fulfillment operators capable of same-day or next-day service level agreements.
United Arab Emirates (UAE) CEP Market Segmentation
CEP operators in the UAE configure service portfolios around cargo sensitivity, regulatory exposure, and telemetry requirements rather than simple weight or distance metrics. Segment boundaries blur where pharmaceutical cold-chain protocols overlap with industrial asset tracking or where government contracts demand multi-technology integration.
Product Type:
Use-case spectrum spans life-critical temperature validation through high-value industrial machinery, with each vertical imposing distinct equipment and certification burdens on fleet operators.
- Healthcare:MOHAP-mandated cold-chain protocols govern vaccine, biologic, and temperature-sensitive pharmaceutical movements. Demand concentrates in Abu Dhabi's KIZAD pharmaceutical cluster and Dubai's healthcare free zones, where manufacturers require validated documentation for every temperature excursion.
- Automotive:High-value spare parts and finished vehicle logistics demand RFID-enabled asset tracking with real-time location verification. Dubai South's bonded corridors absorb the bulk of premium express volumes for just-in-time assembly line replenishment.
- Industrial:Heavy machinery components and project cargo movements utilize specialized flatbed and crane-equipped vehicles within CEP networks.
- Telecommunications:Sensitive electronics shipments require anti-static packaging and rapid customs clearance through Dubai International Airport's bonded facilities.
Established volume favors Healthcare; emerging adoption favors Automotive.
Application:
Cost tier differentiation separates basic shipment monitoring from predictive intervention systems that command premium service fees.
- Supply Chain:End-to-end visibility platforms integrate pickup, line-haul, and last-mile telemetry into unified dashboards for enterprise shippers. Dubai-based retailers and third-party logistics providers deploy these systems to compress inventory carrying costs across the seven emirates.
- Asset Tracking:RFID and GPS convergence enables real-time positioning of high-value cargo containers and vehicle fleets. Industrial manufacturers in Abu Dhabi's industrial zones utilize these capabilities to secure capital equipment movements.
- Fuel Management:Telematics-driven route optimization reduces per-delivery fuel consumption for fleet operators facing margin pressure.
- Energy Efficiency:Electric vehicle integration and warehouse solarization programs align with UAE federal sustainability targets.
Current revenue concentration sits with Supply Chain; steepest expansion trajectory belongs to Asset Tracking.
End User:
Customer type determines contract structure, with government tenders demanding universal service obligations and retail relationships prioritizing speed guarantees.
- Logistics:Third-party logistics providers and freight forwarders represent the core intermediary demand layer, purchasing CEP capacity for resale to shipper clients. Dubai South fulfillment zone operators aggregate multi-retailer volumes for consolidated last-mile injection.
- Retailers:E-commerce platforms and omnichannel merchants drive same-day and next-day service tier adoption. Fashion and beauty direct-to-consumer channels in Dubai are displacing transactional parcel patterns with subscription-based recurring deliveries.
- Government:Emirates Post Group maintains universal service obligations across all seven emirates, with digitization mandates modernizing legacy track-and-trace infrastructure.
- Manufacturing:Industrial producers in KIZAD and Jebel Ali require integrated inbound component and outbound finished goods logistics.
Contract stability favors Logistics; volume growth velocity favors Retailers.
Technology:
Maturity gradients separate proven tracking infrastructure from experimental automation layers still seeking regulatory clearance.
- IoT Solutions:Fleet telematics platforms overlay GPS positioning with predictive routing algorithms and fuel optimization engines. Dubai Roads and Transport Authority permitting frameworks are enabling corridor-specific deployment for autonomous delivery pilots layered on this infrastructure.
- RFID Systems:Radio-frequency identification maintains steady adoption for high-value automotive and industrial cargo tracking, with real-time inventory positioning reducing loss rates in cross-emirate line-haul operations.
- Cloud Computing:Centralized data architectures support multi-emirate parcel visibility and customer-facing tracking portals.
- AI Analytics:Machine learning applications for demand forecasting and dynamic capacity allocation remain in pilot phases among leading operators.
Deployment scale favors IoT Solutions; capability advancement favors AI Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MOHAP pharmaceutical distribution standards anchor the UAE's regulatory framework for cold-chain logistics. Dubai South and Abu Dhabi's KIZAD industrial zones concentrate fulfillment infrastructure. The seven emirates present distinct logistics corridors shaped by free zone positioning and last-mile density.
Dubai
E-commerce fulfillment zones in Dubai South absorb capital flows from traditional warehousing. Dubai Roads and Transport Authority permits autonomous delivery pilots in controlled corridors. Al Maktoum International Airport catchment areas consolidate parcel sortation capacity for retail inventory positioning.
Abu Dhabi
Pharmaceutical manufacturers in KIZAD require integrated temperature-controlled CEP services. Khalifa Port attracts industrial producers needing validated cold-chain documentation. Industrial free zones face temperature-controlled warehousing supply gaps against accelerating demand.
Sharjah
Secondary logistics corridors connect Dubai congestion to northern emirate distribution. Lower real estate costs attract mid-tier fulfillment operators serving price-sensitive retail segments. Sharjah's industrial zones lack comparable bonded infrastructure to Jebel Ali or KIZAD.
Northern Emirates
Ras Al Khaimah and Fujairah present underdeveloped last-mile networks with sparse sortation facility coverage. Universal service obligations from Emirates Post Group extend digitized parcel tracking to these corridors. Infrastructure investment lags behind Dubai-Abu Dhabi concentration.
United Arab Emirates (UAE) CEP Market Competitive Landscape
Capability concentration sits with integrated global networks; scale advantage sits with regional density specialists. The vendor base stratifies across three tiers: multinational express operators with bonded warehouse infrastructure, regional courier networks with Gulf last-mile penetration, and national postal services maintaining universal coverage obligations. Dominant competitive moves include automation capital allocation against labor constraints and strategic positioning within Dubai South fulfillment zones.
Among multinational express operators, FedEx and DHL Express exemplify infrastructure-heavy market entry through airport-adjacent bonded facilities. Aramex occupies a position as the regional density anchor with established Gulf corridor networks. Emirates Post Group represents the universal service tier balancing digitization mandates across all seven emirates.
| Leading Market Players |
|---|
| FedEx |
| Amazon Logistics |
| Aramex |
| DB Schenker |
| TNT Express |
| DHL Express |
| UPS |
| Geodis |
| Emirates Post Group |
| Others |
Value Network & Pricing Analysis
Dubai South bonded corridors concentrate fulfillment infrastructure and compress delivery cost spreads between premium cold-chain services and standard parcel tiers. Supply concentration in Jebel Ali and KIZAD free zones feeds pricing power upstream to warehouse operators while downstream e-commerce platforms absorb margin pressure through volume commitments.
Pricing Analysis
Geographic price spreads widen significantly between Dubai-Abu Dhabi corridors and northern emirate routes. Three-tier pricing structure across premium, standard, and economy levels dominates, with MOHAP certification grade and last-mile density serving as primary differentiation drivers. Cost compression in economy tiers is intensifying because labor sponsorship expenses inflate per-delivery economics. Third-party logistics intermediaries exhibit highest price sensitivity; pharmaceutical manufacturers with cold-chain mandates show lowest.
Supply Chain Analysis
UAE export-control alignment with EU dual-use technology regulations restricts certain IoT telemetry hardware flows from select jurisdictions. Fleet equipment and sortation automation draw from Germany, China, and South Korea; temperature-controlled vehicle chassis feed from European OEMs; RFID hardware sources from East Asian semiconductor fabricators. Single-source vulnerability concentrates in telematics module supply. Distribution runs through bonded free zone clusters before last-mile injection into residential and industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated e-commerce platforms aggregating multi-retailer volumes for negotiated rate structures. Platform consolidation among Dubai-based fashion and beauty direct-to-consumer channels reduces fragmentation in procurement.
For Market Incumbents: Pre-empt autonomous delivery corridor capture through early Dubai Roads and Transport Authority permit accumulation before regulatory windows narrow. Retrofit cold-chain fleets with IoT-enabled telemetry to defend against MOHAP compliance timeline compression. Channel control over Dubai South fulfillment zone positioning represents the critical defensive lever against emerging regional courier networks. For New Entrants and Emerging Players: Northern emirate last-mile corridors with sparse sortation facility coverage represent the most penetrable entry point for mid-tier fulfillment operators. KIZAD-adjacent temperature-controlled warehousing supply gaps offer second-mover advantage in pharmaceutical verticals. Go-to-market positioning should emphasize subscription-based recurring delivery contracts with industrial manufacturers seeking inventory carrying cost reduction. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational express operators divesting non-core Gulf corridor assets amid global network reconfiguration. Long-term viability hinges on automation capital allocation discipline against labor availability constraints. Watch Dubai South fulfillment zone occupancy rates as inflection indicator for infrastructure overbuild risk.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Delivery Pilot Expansion | Dubai Roads and Transport Authority permits enable corridor-specific robotic and drone deployment before regulatory saturation. |
| Cold-Chain Fleet Retrofit | MOHAP-mandated IoT telemetry installation defends service tier eligibility in pharmaceutical verticals. |
| Dubai South Fulfillment Zone Positioning | Bonded warehouse proximity to Al Maktoum International Airport compresses customs clearance timelines for e-commerce platforms. |
| RFID Asset Tracking Integration | Automotive and industrial verticals demand real-time inventory positioning for high-value cargo loss reduction. |
| IoT-Telematics Platform Convergence | Predictive routing algorithms layered over GPS infrastructure differentiate fleet operators on fuel optimization. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade databases, MOHAP regulatory filings, and free zone occupancy reports. Logistics procurement directors at third-party providers, fleet operations managers, and pharmaceutical supply chain executives provided operational perspective. Dubai South development authority disclosures and Emirates Post Group digitization mandates supplied institutional context. Bottom-up parcel volume modeling triangulated against top-down CEP market sizing.
Forecast inputs span product type segmentation by regulatory exposure, application tiers by telemetry sophistication, and end-user contract structures by volume predictability. Modeled dimensions include healthcare cold-chain certification requirements, automotive RFID adoption intensity, and retail subscription penetration patterns. CAGRs derived from trajectory analysis across the projection horizon. Labor availability constraints and autonomous delivery regulatory clearance timelines entered as scenario variables.
Practitioners should monitor MOHAP protocol amendments and Dubai Roads and Transport Authority permit issuance velocity for early signals. Forecasts reflect assumptions about e-commerce volume concentration and automation capital deployment pacing. Material shifts in Gulf Cooperation Council customs harmonization progress or UAE visa sponsorship cost structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Europe Silicon Carbide Wafers Market
Semiconductor Devices
Automotive Grade Emmc Market
Semiconductor Devices
Digital Transistor Market
Semiconductor Devices
APAC Semiconductor Device in Aerospace and Defense Market
Semiconductor Devices
Laneth-16 Market
Semiconductor Devices
Nano-Magnetic Devices Market
Semiconductor Devices
Thin Wafer Market
Semiconductor Devices
Japan Semiconductor Device Market
Semiconductor Devices
Chip on Flex Market
Semiconductor Devices
Single Electron Transistor Market
Semiconductor Devices
5G Automotive Grade Product Market
Semiconductor Devices
Dual Voltage Comparator Market
Semiconductor Devices
Fin Field Effect Transistor (Finfet) Market
Semiconductor Devices
Solar Cell Paste Market
Semiconductor Devices
Europe Semiconductor Device Market
Semiconductor Devices
Semiconductor Memory IP Market