
 Plastic Transistors Market | 2026-2036
Plastic Transistors Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Transistors Market Analytics
The EU Green Deal is expanding the addressable market for substrate-recyclable transistors across European consumer electronics supply chains. Pragmatic Semiconductor leverages roll-to-roll manufacturing to sustain cost leadership in flexible logic devices. Merck KGaA anchors specialty polymer semiconductor supply through captive material science capabilities. Solvay SA differentiates via high-purity dielectric polymers that enable low-voltage organic transistor operation.
Plastic transistors are electronic switching devices fabricated on flexible polymer substrates using organic or solution-processed semiconductors, typically operating below 5V with mechanical bend radii under 10mm for conformal integration. Their primary purpose is enabling large-area, lightweight circuitry for disposable or wearable applications incompatible with rigid silicon. Organic thin-film transistors dominate current production volumes due to decade-long process maturity, while solution-processed transistors represent the fastest-expanding technology segment as inkjet and slot-die coating slash capital intensity. Flexible electronics commands the largest product-type margin pool because medical and automotive buyers pay premiums for conformal integration.
The European Chemicals Agency REACH framework governs organic semiconductor monomer registration, while the EU F-Gas Regulation indirectly steers substrate choices by restricting fluorinated processing gases in competing thin-film technologies. The US EPA oversees solvent emission thresholds at printed electronics foundries serving North American medical device clients. ISO 10993 biocompatibility standards gate plastic transistor adoption in wearable medical applications across all regulated jurisdictions. Stakeholders must weigh polymer semiconductor recyclability certifications against performance benchmarks when qualifying for next-generation automotive interior and point-of-care diagnostic contracts.
Market Dynamics
Roll-to-roll manufacturing is compressing unit economics for flexible polymer circuitry while REACH-mandated monomer registration concentrates qualified supplier pools among German and Belgian material science firms.
Growth Catalysts
- EU Green Deal substrate mandates:Restrictions on silicon wafer disposal are redirecting consumer electronics supply chains toward recyclable polymer alternatives. Wearable health monitor manufacturers now specify organic thin-film transistors in procurement tenders.
- Inkjet patterning throughput gains:Slot-die and inkjet coating systems have slashed capital intensity for printed logic device fabrication. Dresden-based process equipment clusters attract contract manufacturing investment from automotive interior suppliers.
- Germany:Printed electronics clusters in Munich and Dresden concentrate process engineering talent and pilot-line capacity. Medical device OEMs source conformal circuitry from these hubs for point-of-care diagnostic contracts.
Market Restraints
- Monomer supply concentration:ECHA REACH registration requirements limit qualified organic semiconductor precursor suppliers to a handful of European chemical conglomerates. Specialty polymer lead times extend when capacity reallocates to pharmaceutical applications.
- Performance ceiling:Organic thin-film transistors exhibit carrier mobility below solution-processed alternatives, constraining switching speeds in high-frequency applications. Radio-frequency identification tags and near-field communication modules remain silicon-dominant.
- Fluorinated gas restrictions:EU F-Gas Regulation limits plasma etching chemistries used in competing thin-film technologies, indirectly pressuring substrate choices but also complicating process migration paths for established foundries.
Strategic Opportunities
- Automotive interior conformal surfaces:Dashboard and seat-integrated sensor arrays require bend radii under 10mm incompatible with rigid substrates. Tier-1 suppliers in Stuttgart and Wolfsburg pilot printed heater and capacitive touch circuits.
- ISO 10993 biocompatibility certification:Wearable medical applications demand polymer semiconductor formulations passing cytotoxicity and sensitization testing. Contract manufacturers qualifying early capture diagnostic device OEM procurement.
- Solution-processed transistor convergence:Hybrid ink systems combining organic semiconductors with carbon nanotube networks bridge mobility gaps. Printed electronics foundries in Eindhoven and Cambridge scale these formulations for flexible display backplanes.
Industry Challenges
- Process engineering talent scarcity:Roll-to-roll coating and solution-phase patterning require distinct skill sets from silicon wafer processing. Training pipelines lag demand in printed electronics clusters.
- Multi-jurisdiction certification timelines:ISO 10993 biocompatibility testing plus ECHA REACH dossier preparation extends product qualification to 18-24 months. Medical device contracts specify locked semiconductor formulations years ahead of production.
- Legacy equipment integration:Organic transistor fabrication lines must interface with existing pick-and-place and test systems designed for rigid substrates. Retrofit costs concentrate in high-mix, low-volume contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Transistors Market |
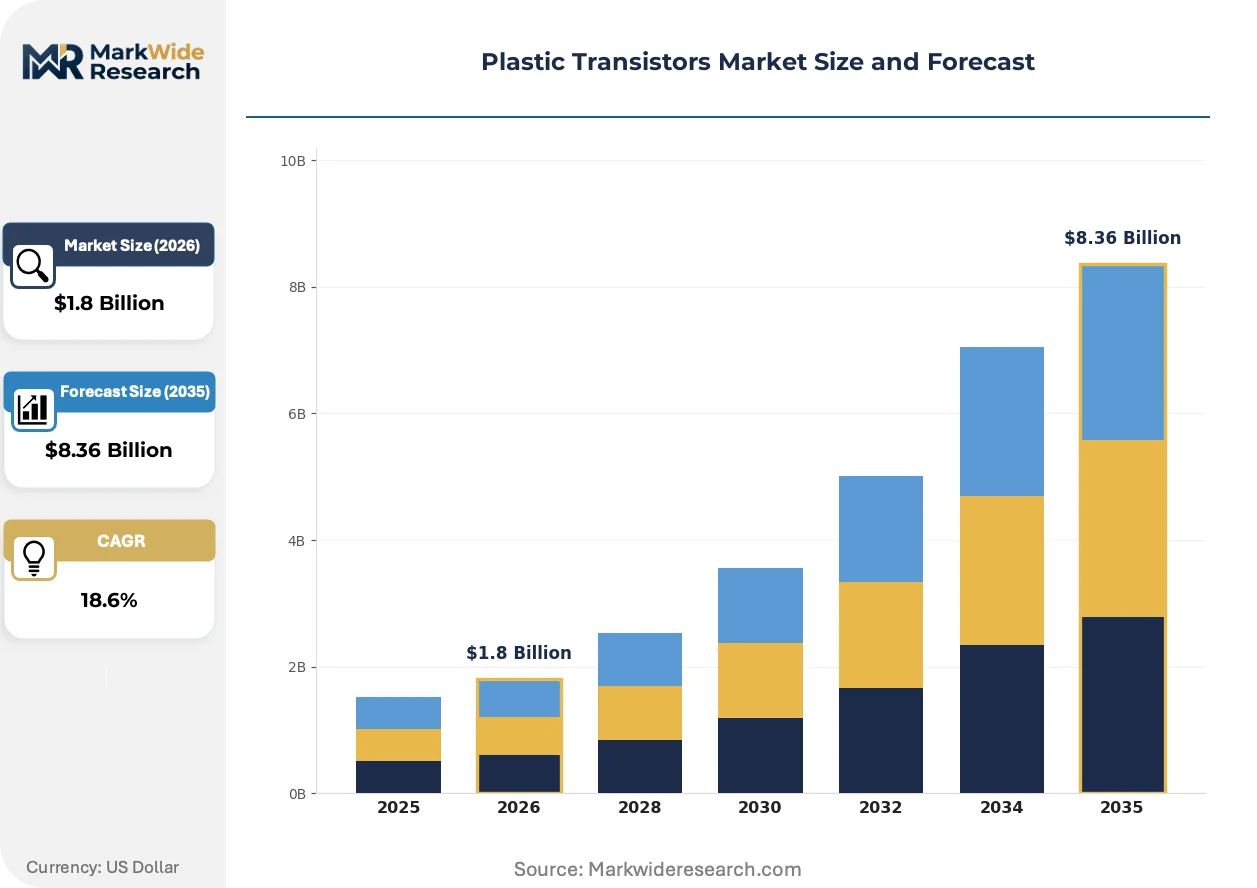
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Electronics, Sensors, OLED Displays, RF IDs Technology: Organic Thin-Film Transistors, Solution-Processed Transistors, Printed Electronics, Phototransistors End User: Consumer Electronics, Automotive Components, Medical Devices, Industrial Automation Distribution Channel: Direct Sales, Online Retail, Distributors, Value-Added Resellers |
| Companies Covered | Pragmatic Semiconductor, Plastic Logic GmbH, Polyera Corporation, E Ink Holdings Inc., AU Optronics Corp., Thin Film Electronics ASA, FlexEnable Limited, Merck KGaA, Solvay SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Transistors Market Evolving Landscape
Solution-processed semiconductor formulations are displacing vapor-deposited organic layers as capital efficiency becomes the decisive competitive variable in flexible logic device manufacturing.
Carbon nanotube-polymer composite inks are expanding into radio-frequency identification and near-field communication applications previously closed to organic electronics. Logistics and retail packaging buyers in the Netherlands and Belgium pilot these tags for item-level inventory tracking. The technology is expanding into supply chain visibility contracts that silicon-based alternatives cannot serve due to substrate cost and mechanical rigidity constraints.
EU F-Gas Regulation restrictions on fluorinated processing gases are steering substrate selection toward polymer alternatives compatible with ambient-pressure coating. Thin-film transistor foundries serving medical device clients face process chemistry recertification. German automotive interior suppliers accelerate organic transistor qualification to avoid supply disruption from plasma etching gas allocation quotas.
Medical device OEMs now bundle semiconductor formulation specifications into long-term diagnostic platform contracts rather than sourcing transistors as commodity components. Procurement teams lock polymer semiconductor grades three to five years ahead of production ramp. This pattern concentrates volume with qualified European material suppliers and excludes Asian foundries lacking REACH-registered monomer supply chains.
Plastic Transistors Market Segmentation
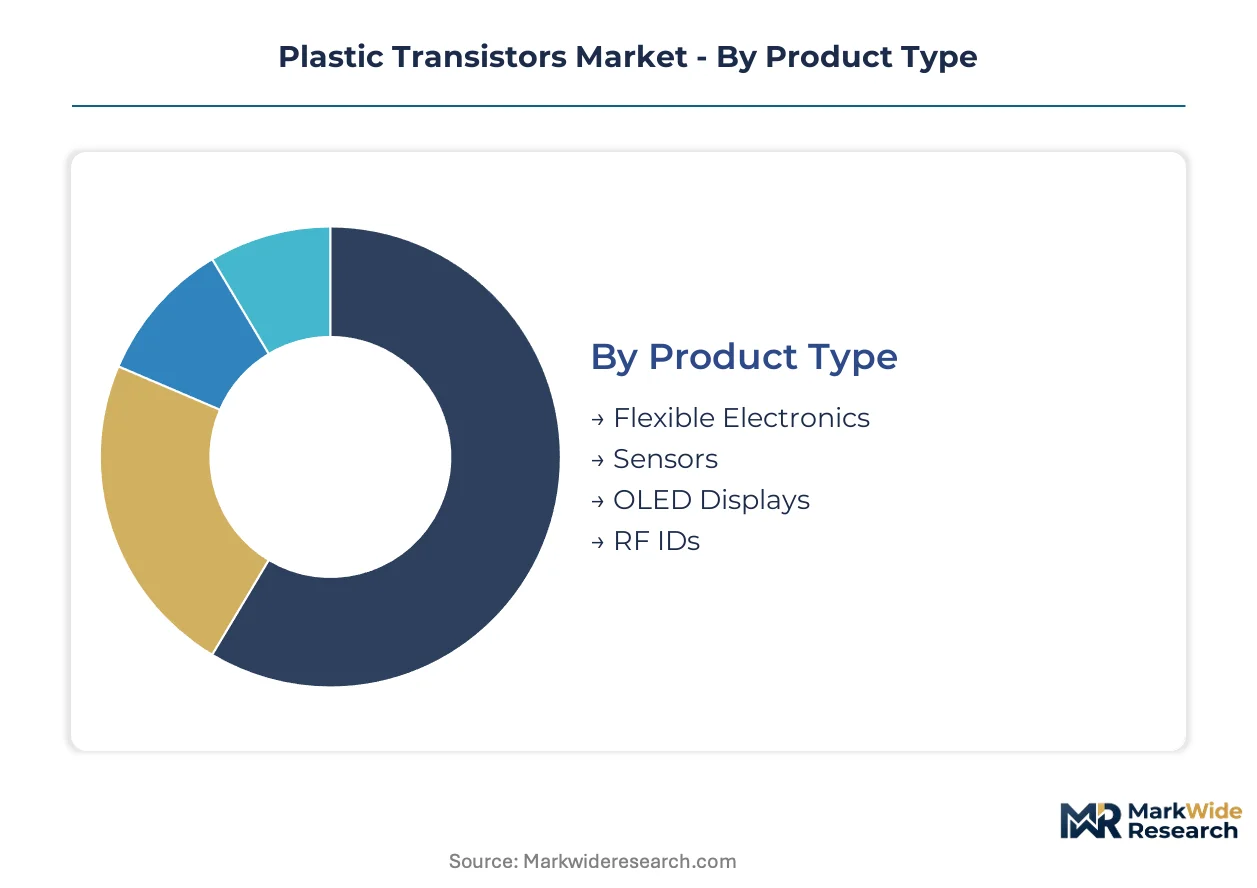
Plastic transistor procurement patterns diverge sharply across application contexts, with medical device contracts demanding ISO 10993 biocompatibility certification while automotive programs prioritize bend-radius specifications under 10mm. Segmentation reveals how formulation requirements and qualification timelines reshape supplier selection and margin capture across end-use verticals.
Product Type:
ISO 10993 biocompatibility certification requirements concentrate in wearable medical segments, while automotive interior applications prioritize mechanical bend-radius validation under standardized test protocols.
- Flexible Electronics:Conformal circuitry fabricated on polymer substrates enables integration with curved automotive dashboards and wearable health monitors. Medical device OEMs in Germany specify these components for point-of-care diagnostic platforms requiring mechanical compliance. Demand clusters in Stuttgart and Wolfsburg where Tier-1 suppliers pilot printed heater and capacitive touch circuits.
- Sensors:Pressure and temperature sensing arrays leverage low-voltage organic transistor operation for battery-powered deployment. Industrial automation buyers in Belgium source these for predictive maintenance systems requiring large-area coverage. REACH-registered polymer semiconductor formulations from Merck KGaA and Solvay SA dominate qualified supply.
- OLED Displays:Flexible backplane transistors enable bendable screen architectures for premium consumer devices.
- RF IDs:Item-level inventory tracking tags exploit substrate cost advantages over silicon alternatives in logistics applications.
Leading the category by volume: Flexible Electronics. Growing fastest: Sensors.
Technology:
Capital intensity separates established vapor-deposition methods from emerging solution-phase approaches, with inkjet and slot-die coating systems slashing equipment investment thresholds for new market entrants.
- Organic Thin-Film Transistors:Vapor-deposited small-molecule semiconductors deliver decade-long process maturity and reliable manufacturing yields. Dresden-based printed electronics clusters concentrate pilot-line capacity for these devices. EU F-Gas Regulation restrictions on fluorinated processing gases indirectly steer substrate selection toward polymer alternatives compatible with this technology.
- Solution-Processed Transistors:Inkjet and slot-die coating of polymer semiconductor inks enables roll-to-roll manufacturing at dramatically reduced capital intensity. Pragmatic Semiconductor leverages this approach for cost leadership in flexible logic devices. Eindhoven and Cambridge foundries scale hybrid ink systems combining organic semiconductors with carbon nanotube networks.
- Printed Electronics:Additive patterning of conductive and semiconductive layers on flexible substrates supports large-area applications.
- Phototransistors:Light-sensitive organic variants enable optical sensing and imaging array applications.
Dominant by installed capacity: Organic Thin-Film Transistors. Expanding most quickly: Solution-Processed Transistors.
End User:
Qualification timelines stretch from 6 months for consumer electronics to 24 months for medical devices, with locked semiconductor formulations specified years ahead of production ramp in diagnostic platform contracts.
- Consumer Electronics:Wearable health monitors and foldable device programs drive procurement of conformal transistor arrays. EU Green Deal restrictions on silicon wafer disposal redirect supply chains toward recyclable polymer alternatives. Procurement tenders now specify organic thin-film transistors for next-generation product generations.
- Automotive Components:Dashboard-integrated sensor arrays and seat-embedded heating circuits demand bend radii incompatible with rigid substrates. German automotive interior suppliers accelerate organic transistor qualification to avoid supply disruption from plasma etching gas allocation quotas under F-Gas Regulation.
- Medical Devices:Point-of-care diagnostic platforms require polymer semiconductor formulations passing cytotoxicity and sensitization testing under ISO 10993.
- Industrial Automation:Predictive maintenance systems leverage large-area sensor coverage for equipment monitoring.
Highest volume uptake: Consumer Electronics. Steepest expansion trajectory: Automotive Components.
Distribution Channel:
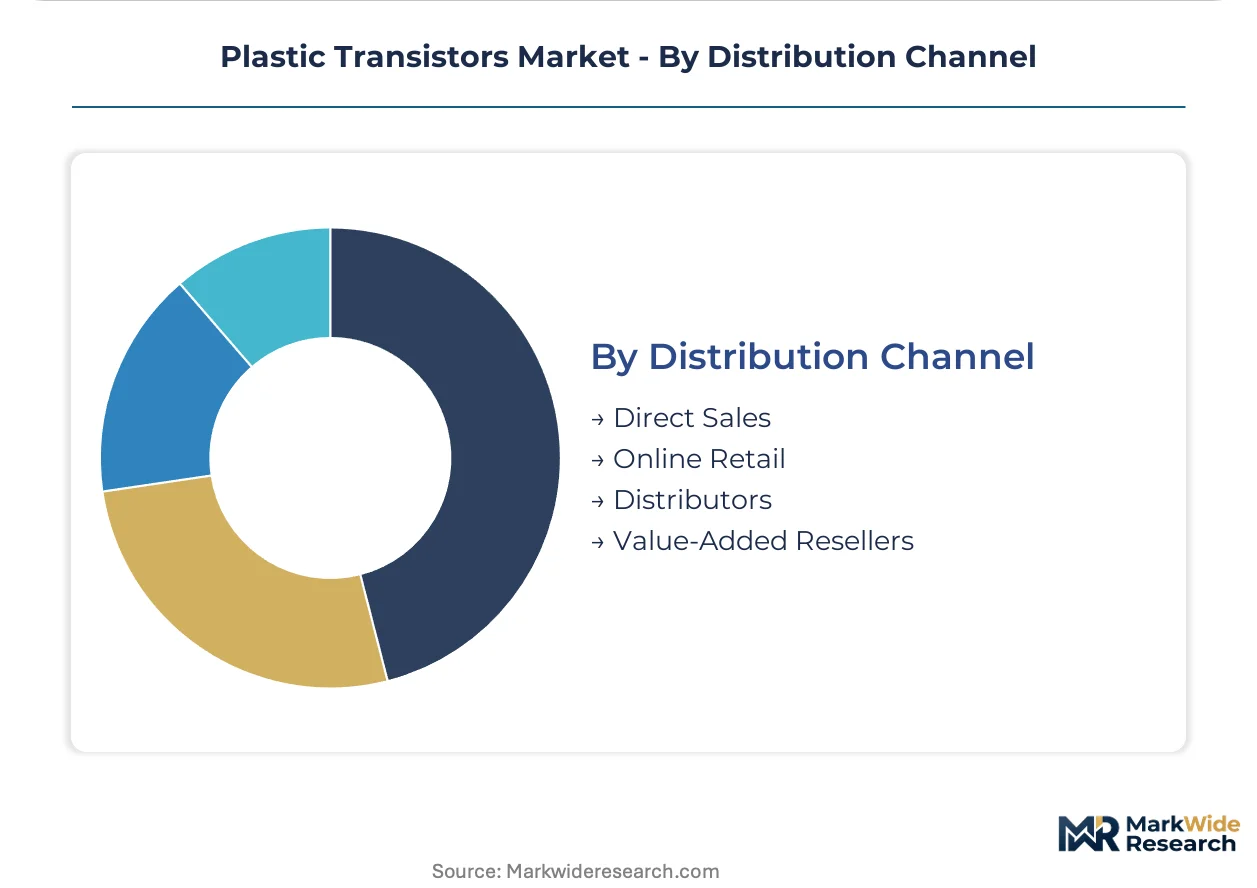
Contract value and technical support requirements determine channel selection, with direct engagement dominating medical and automotive programs while standardized products flow through distributor networks.
- Direct Sales:Medical device and automotive OEMs engage polymer semiconductor suppliers directly for formulation-locked multi-year contracts. ECHA REACH dossier preparation and ISO 10993 testing coordination require dedicated account engineering. Volume concentrates with qualified European material suppliers.
- Distributors:Broad-line electronics distributors serve high-mix, low-volume contract manufacturers requiring rapid material access.
- Online Retail:Standardized development kits and evaluation modules reach research institutions and prototype shops.
- Value-Added Resistors:Specialized resellers provide design-in support for printed electronics integration.
Primary volume pathway: Direct Sales. Gaining share fastest: Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in European chemical and printed electronics clusters, while consumption spreads across automotive, medical, and consumer electronics hubs in Germany, the United States, and East Asia. This geographic split creates supply chain dependencies on REACH-registered monomer suppliers and roll-to-roll manufacturing infrastructure.
Germany
Automotive interior suppliers in Stuttgart and Wolfsburg pilot conformal sensor arrays for dashboard integration. The EU F-Gas Regulation restricts fluorinated processing gases, accelerating organic transistor qualification to avoid plasma etching supply disruptions. Dresden and Munich clusters concentrate printed electronics pilot-line capacity and process engineering talent.
United States
Wearable health monitor OEMs drive procurement of flexible logic devices for next-generation diagnostic platforms. The EPA oversees solvent emission thresholds at printed electronics foundries serving medical device clients. Boston-area contract manufacturers coordinate ISO 10993 biocompatibility testing for polymer semiconductor formulations.
China
Consumer electronics assembly lines absorb flexible display backplane transistors for foldable device programs. The country's national electronics standards regulator governs organic semiconductor import specifications. Yangtze River Delta manufacturing hubs integrate printed logic devices with existing pick-and-place infrastructure.
Japan
Industrial automation buyers source large-area sensor arrays for predictive maintenance systems requiring battery-powered deployment. METI coordinates national research programs on solution-processed semiconductor manufacturing. Kansai region chemical conglomerates supply high-purity dielectric polymers to regional foundries.
United Kingdom
Cambridge-based printed electronics foundries scale hybrid ink systems combining organic semiconductors with carbon nanotube networks. The country's national chemicals regulator enforces REACH-aligned monomer registration requirements. Southeast England research clusters attract contract manufacturing investment from logistics and retail packaging buyers.
Plastic Transistors Market Competitive Landscape
The competitive structure tilts toward material science conglomerates with captive polymer semiconductor capabilities. Roll-to-roll manufacturing specialists and vapor-deposition equipment providers occupy distinct tier positions. Three archetypes dominate: REACH-registered chemical suppliers, flexible foundry operators, and display-integrated backplane fabricators. Capacity expansion and strategic technology licensing represent the primary competitive moves as qualification timelines extend.
Among European material science anchors, Merck KGaA and Solvay SA exemplify the chemical conglomerate archetype with in-house polymer semiconductor and dielectric formulations. Pragmatic Semiconductor occupies a position within the flexible foundry tier, representing roll-to-roll manufacturing scale. These three entities collectively illustrate how supply-side concentration around REACH-registered monomers and process equipment clusters reshapes competitive positioning.
| Leading Market Players |
|---|
| Pragmatic Semiconductor |
| Plastic Logic GmbH |
| Polyera Corporation |
| E Ink Holdings Inc. |
| AU Optronics Corp. |
| Thin Film Electronics ASA |
| FlexEnable Limited |
| Merck KGaA |
| Solvay SA |
| Others |
Value Network & Pricing Analysis
Medical device OEM procurement concentration in Germany and the United States anchors contract-based long-term offtake pricing for REACH-registered polymer semiconductor formulations. Tier-1 automotive suppliers in Stuttgart negotiate volume-scale discounts that compress margins for non-integrated material providers.
Pricing Analysis
Cost-down pressure on flexible logic device tiers accelerates because inkjet and slot-die coating systems slash capital barriers for new entrants. Three-tier pricing structure across ISO 10993-certified premium, automotive-qualified standard, and economy development-kit levels separates medical contract manufacturers from prototype shops. Price differentiation hinges on ECHA REACH dossier completeness and biocompatibility certification status. Consumer electronics buyers exhibit highest price sensitivity; medical device OEMs locked into multi-year diagnostic platform contracts show lowest.
Supply Chain Analysis
Specialty polymer semiconductor supply rests on German and Belgian chemical conglomerates with captive material science capabilities. REACH-registered organic monomers, high-purity dielectric polymers, and hybrid carbon nanotube-ink formulations constitute critical input dependencies. Single-source vulnerability concentrates around ECHA-registered precursor suppliers when capacity reallocates to pharmaceutical applications. Distribution runs through direct sales for formulation-locked medical and automotive contracts, with broad-line electronics distributors serving high-mix contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended qualification timelines and REACH-mandated monomer registration are forcing consolidation among non-integrated foundry operators lacking captive polymer semiconductor supply.
For Market Incumbents: Deepen backward integration into REACH-registered monomer production to defend margin position against solution-processed transistor entrants from Asian foundries. Add roll-to-roll coating capacity in Dresden and Cambridge clusters to capture automotive interior sensor array contracts. Lock medical device OEMs into five-year formulation specifications before competitor qualification cycles complete. For New Entrants and Emerging Players: E-commerce distribution channels for standardized development kits offer the lowest barrier entry point for research institutions and prototype shops lacking direct supplier relationships. Target industrial automation sensor arrays in Belgium and the Netherlands where biocompatibility certification requirements remain absent. Partner with Cambridge and Eindhoven printed electronics foundries for toll manufacturing of hybrid ink formulations. For Investors and Strategic Acquirers: Distressed-cycle entries favor flexible foundry operators with existing ISO 10993 certification pathways in Germany and the United Kingdom. Five-to-ten-year viability hinges on automotive interior program wins and medical device contract renewals. Watch for ECHA REACH registration deadline extensions as the inflection signal for material supplier consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Completion | ECHA dossier approval unlocks multi-year medical device OEM procurement contracts. |
| Roll-to-Roll Capacity Expansion | Dresden cluster additions capture automotive dashboard sensor array pilot programs. |
| Hybrid Ink System Licensing | Carbon nanotube-polymer composite formulations bridge mobility gaps for RFID applications. |
| ISO 10993 Certification Investment | Cytotoxicity testing completion qualifies polymer semiconductors for wearable diagnostic platforms. |
| Automotive Tier-1 Partnership | Stuttgart supplier integration secures conformal heater and touch circuit volume commitments. |
Research Methodology
Independent corroboration across printed electronics foundry managers, polymer semiconductor procurement leads at medical device OEMs, ECHA regulatory affairs specialists, and automotive Tier-1 supplier engineers underwrites the qualitative findings. Secondary validation draws from ECHA REACH registration databases, EU F-Gas Regulation implementation reports, ISO 10993 biocompatibility testing records, and SEC filings of publicly traded material science conglomerates. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Comparable-period anchoring to organic thin-film transistor production histories and solution-processed transistor pilot-line ramp patterns structures the projection horizon. Segmentation dimensions span product type, technology, end user, and distribution channel, with regional regulatory cluster as an additional modeling layer. CAGRs derive from installed capacity expansion schedules and locked contract volume disclosures. Forecast inputs incorporate REACH registration timelines and automotive interior qualification milestones.
The model holds under stable ECHA regulatory enforcement and continued EU F-Gas allocation quotas; deviation in monomer supply disruption or automotive program cancellations would shift trajectory. A small set of triggers—REACH deadline extensions, biocompatibility testing backlogs, and plasma etching gas allocation changes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Micro Thermoelectric Modules Market
Semiconductor Devices
APAC Semiconductor Device in Aerospace and Defense Market
Semiconductor Devices
Die Spacer Market
Semiconductor Devices
Spintronic Logic Devices Market
Semiconductor Devices
Global Switched Capacitor Filter Market
Semiconductor Devices
South Korea MLCC Market
Semiconductor Devices
Large-Size PV Silicon Wafer Market
Semiconductor Devices
Temperature-Controlled Semiconductor Market
Semiconductor Devices
Automotive Grade Emmc Market
Semiconductor Devices
Nanowires Market
Semiconductor Devices
Asia-Pacific Silicon Carbide Wafers Market
Semiconductor Devices
LTCC and HTCC Market
Semiconductor Devices
MBE Components Market
Semiconductor Devices
Japan CEP Market
Semiconductor Devices
Europe Room Cell Module Market
Semiconductor Devices
Gallium Nitride (Gan) Semiconductor Devices Market