
 Global Through Silicon via (TSV) Technology Market | 2026-2036
Global Through Silicon via (TSV) Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Global Through Silicon via (TSV) Technology Market Foresight
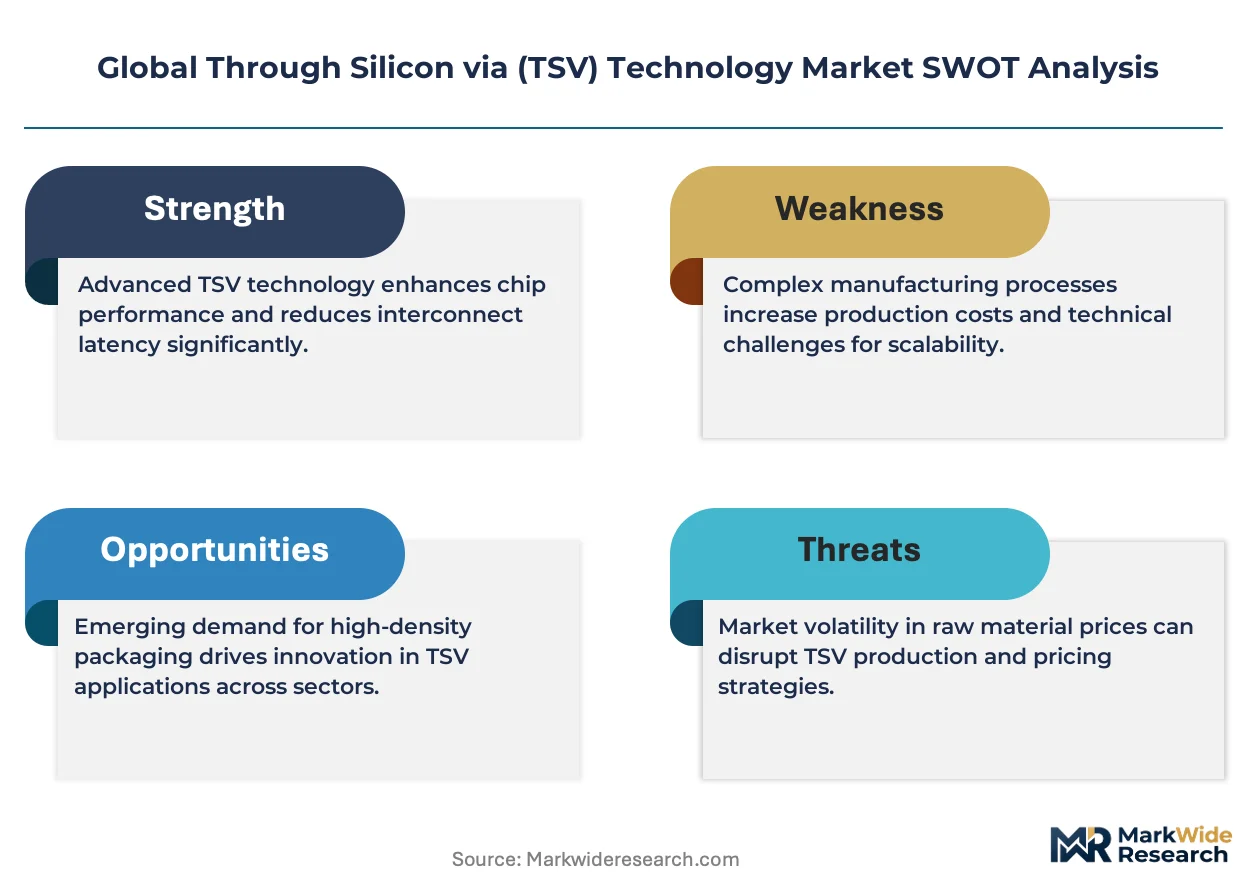
Aftermarket service revenue for TSV metrology and repair tooling is reshaping margin distribution across the semiconductor packaging value chain. Taiwan Semiconductor Manufacturing Company Limited leverages its captive foundry-scale TSV production to dominate advanced interposer supply. Samsung Electronics anchors its position through backward integration into wafer bonding equipment and process IP. Applied Materials, Inc. specializes in via formation hardware, sustaining pricing power in high-aspect-ratio etch systems.
Through Silicon via technology creates vertical electrical interconnects drilled through silicon wafers, typically achieving aspect ratios exceeding 10:1 with copper fill to enable three-dimensional stacking of integrated circuits. Its primary purpose is to shorten signal paths and boost bandwidth density in advanced memory and logic packages. Active TSV configurations lead current volume shipments for high-bandwidth memory stacks, while hybrid TSV architectures are capturing the fastest growth as heterogeneous integration demands rise. Memory Devices applications concentrate the largest revenue pool today, though Computing applications are pulling ahead in wafer starts as AI accelerator packaging scales.
The US CHIPS and Science Act and South Korea's K-Semiconductor Belt strategy are channeling public capital into domestic TSV fabrication lines, tightening equipment procurement cycles. REACH compliance in Europe and evolving EPA hazardous substance rules in the US are elevating material purity standards for copper plating chemistries and dielectric films. Stakeholders must track how export control expansions affect via formation equipment flows and whether China's GB standards for advanced packaging create divergent certification paths for multinational suppliers.
Market Dynamics
Memory bandwidth bottlenecks in AI training clusters are forcing packaging architectures toward denser vertical interconnects, compressing equipment procurement cycles and rewiring foundry-capital-equipment relationships across the semiconductor value chain.
Growth Catalysts
- High-Bandwidth Memory Stacks:AI accelerator demand from hyperscale datacenters is pulling wafer starts toward active TSV configurations for HBM3E and subsequent generations.
- K-Semiconductor Belt:South Korea's domestic subsidy framework is channeling public capital into captive TSV fabrication lines near Pyeongtaek.
- Copper Plating Chemistry Advances:Electroplating process refinements are extending aspect-ratio capabilities beyond 15:1 while maintaining fill uniformity.
Market Restraints
- Wafer Bonding Equipment Concentration:Tooling supply concentrates among Japanese and German precision equipment builders, creating procurement queue risks.
- REACH Compliance Costs:ECHA substance restrictions on dielectric precursors are elevating material qualification timelines and purity certification expenses.
- Hybrid Bonding Substitution:Die-to-wafer direct bonding at sub-10µm pitch threatens mid-range TSV applications in mobile processors.
Strategic Opportunities
- India Semiconductor Mission:PLI scheme incentives for advanced packaging are attracting TSV metrology and repair service investments into Gujarat and Karnataka.
- Automotive Sensor Fusion:LiDAR and camera module integration is opening heterogeneous TSV demand for edge AI inference in autonomous systems.
- EU Chips Act:Subsidy flows toward domestic interposer capacity are creating equipment localization requirements distinct from Asian supply chains.
Industry Challenges
- Process Integration Talent:Scarce expertise in via formation-to-bonding sequence optimization is constraining yield ramp rates at new fabrication lines.
- Multi-Physics Simulation Complexity:Thermo-mechanical stress modeling across stacked die requires cross-functional teams bridging packaging and chip design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Through Silicon via (TSV) Technology Market |
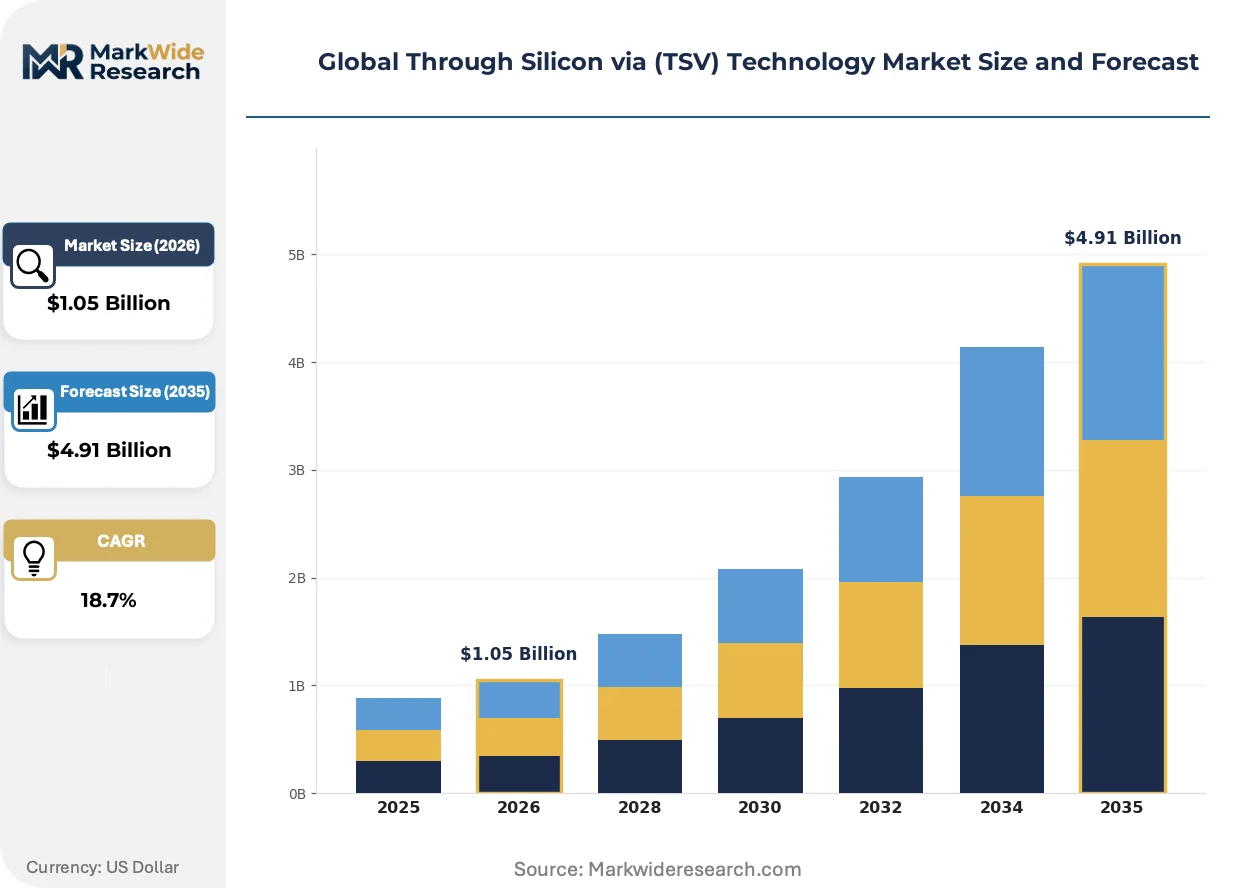
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $4.91 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active TSV, Passive TSV, Hybrid TSV, 3D IC End User: Consumer Electronics, Automotive, Telecommunications, Healthcare Application: Memory Devices, Image Sensors, RF Devices, Computing Technology: Via Formation, Wafer Bonding, Chip Stacking, Interconnects |
| Companies Covered | Taiwan Semiconductor Manufacturing Company Limited, Applied Materials, Inc., Samsung Electronics, Intel Corporation, SK Hynix, ASE Group, Micron Technology, STMicroelectronics, Broadcom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Through Silicon via (TSV) Technology Market Shifts & Advancements
Equipment architectures and process chemistries are converging around extreme aspect-ratio etching and atomic-scale deposition control, compressing the gap between R&D and high-volume manufacturing timelines.
Deep reactive-ion etching hardware is collapsing the tradeoff between via density and mechanical reliability. Memory foundries are adopting multi-frequency bias power systems to achieve 20:1 aspect ratios at 5µm pitch. This capability compression is enabling single-reticle interposers for AI accelerators that previously required chiplet disaggregation.
EPA hazardous substance rules are tightening copper plating bath monitoring requirements. Facilities in the US must now implement real-time effluent tracking for additives and brighteners. California and Texas fabs are responding by qualifying closed-loop regeneration systems that extend chemistry lifecycles while maintaining deposition uniformity.
Aftermarket service unbundling is separating metrology tool ownership from operator training and calibration contracts. Memory manufacturers in South Korea are moving toward per-wafer inspection pricing rather than capital purchases. This consumption shift concentrates vendor relationships around Taiwan and Singapore-based service hubs with rapid field-engineer deployment.
Global Through Silicon via (TSV) Technology Market Segmentation
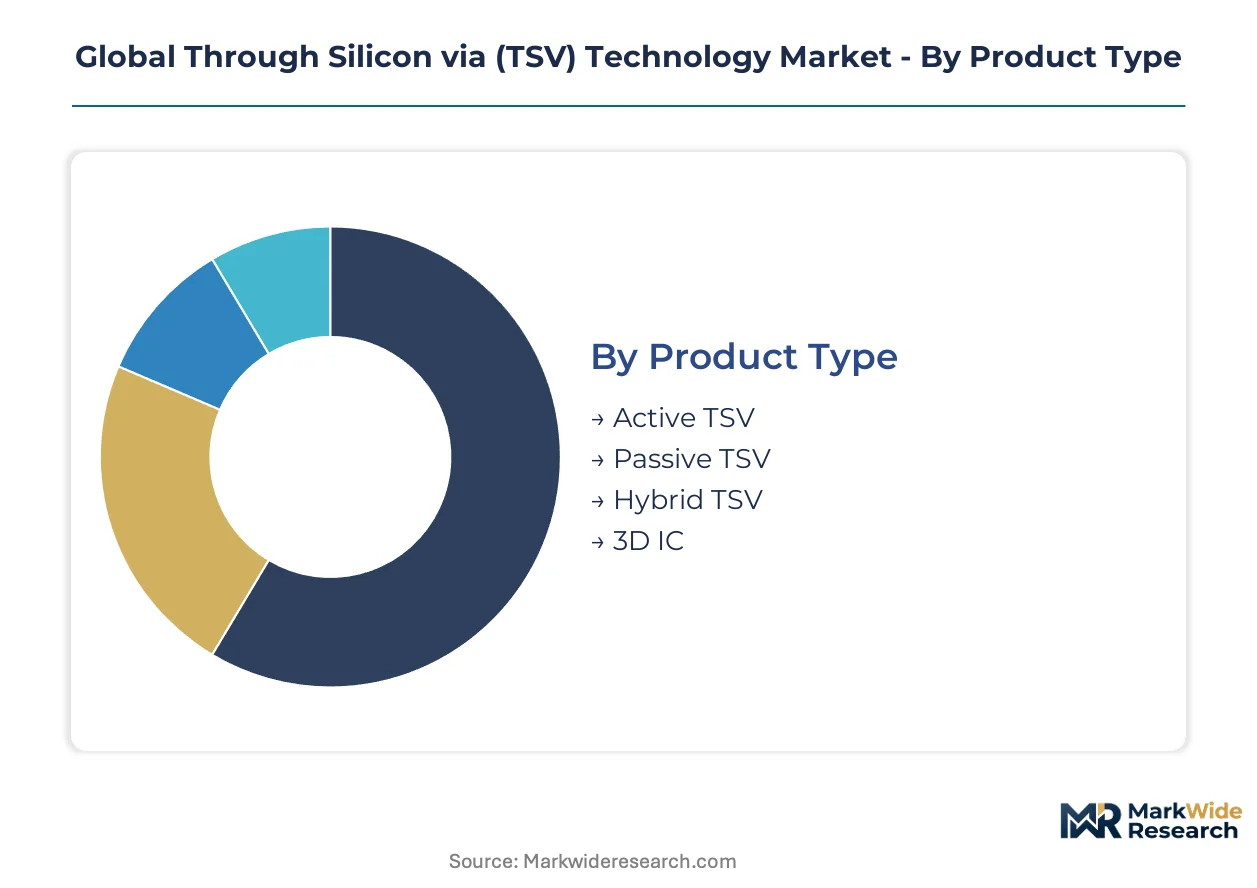
TSV market segmentation reveals how equipment procurement cycles and aftermarket service intensity vary across product architectures, end-use verticals, and process technologies. Understanding these divisions exposes where capital concentrates versus where margins fragment across the value chain.
Product Type:
Aftermarket service intensity diverges sharply across TSV configurations, with active and hybrid variants demanding sustained metrology support while passive interposers require minimal ongoing calibration.
- Active TSV:These configurations integrate active transistors within the via structure itself, enabling signal conditioning and power management functions directly in the interconnect layer. Demand concentrates in South Korea's HBM foundries where Samsung Electronics and SK Hynix operate captive lines for AI accelerator supply to hyperscale datacenters in California and Virginia. Copper fill uniformity requirements drive recurring metrology service contracts.
- Hybrid TSV:Architectures combine active and passive elements to support heterogeneous integration of logic and memory die. Taiwan's Hsinchu Science Park houses the densest installed base, with TSMC deploying hybrid configurations for advanced interposer production bound for NVIDIA and AMD AI training clusters. The fastest expansion trajectory in this category stems from automotive LiDAR module integration.
- Passive TSV:Simple electrical conduits without active components, primarily serving as mechanical and thermal stress relief structures in high-density packages.
- 3D IC:Full three-dimensional stacking implementations where TSVs enable complete vertical integration of multiple functional layers.
By volume, active TSV leads. By growth pace, hybrid TSV is climbing the fastest.
End User:
Customer procurement sophistication separates consumer electronics buyers—focused on unit cost—from automotive and healthcare purchasers who prioritize traceability and failure-mode documentation.
- Consumer Electronics:Smartphone and tablet manufacturers drive the largest wafer start volumes for mid-range TSV implementations. Apple and Qualcomm sourcing patterns from Taiwanese OSATs create cyclical equipment demand spikes aligned with flagship product launches.
- Automotive:Autonomous vehicle sensor fusion requirements are pulling heterogeneous TSV adoption for edge AI inference modules. German OEMs through Bosch and Continental are qualifying TSV-based LiDAR controllers under ISO 26262 functional safety mandates.
- Telecommunications:5G baseband and mmWave beamforming modules utilize TSV interposers for RF performance optimization.
- Healthcare:Medical imaging and implantable device applications impose stringent biocompatibility and reliability standards on TSV metallization.
Consumer electronics commands current volume leadership. Automotive applications are expanding most quickly.
Application:
Application-specific processing requirements determine whether TSV implementations prioritize bandwidth density, thermal dissipation, or signal integrity optimization.
- Memory Devices:HBM3E and subsequent generations anchor the dominant revenue pool, with active TSV configurations enabling the bandwidth density required for AI training workloads. South Korea's Pyeongtaek cluster concentrates the world's densest memory TSV fabrication capacity.
- Computing:AI accelerator packaging is pulling ahead in wafer starts as chiplet disaggregation strategies proliferate. AMD's MI300 and NVIDIA's H100 architectures rely on TSV-enabled interposers for die-to-die communication.
- Image Sensors:Backside-illuminated CMOS sensors utilize TSVs for pixel-to-processor interconnect in smartphone camera modules.
- RF Devices:5G mmWave and satellite communication modules employ TSVs for reduced parasitic capacitance in high-frequency signal paths.
Memory devices retain volume dominance. Computing applications show the steepest expansion trajectory.
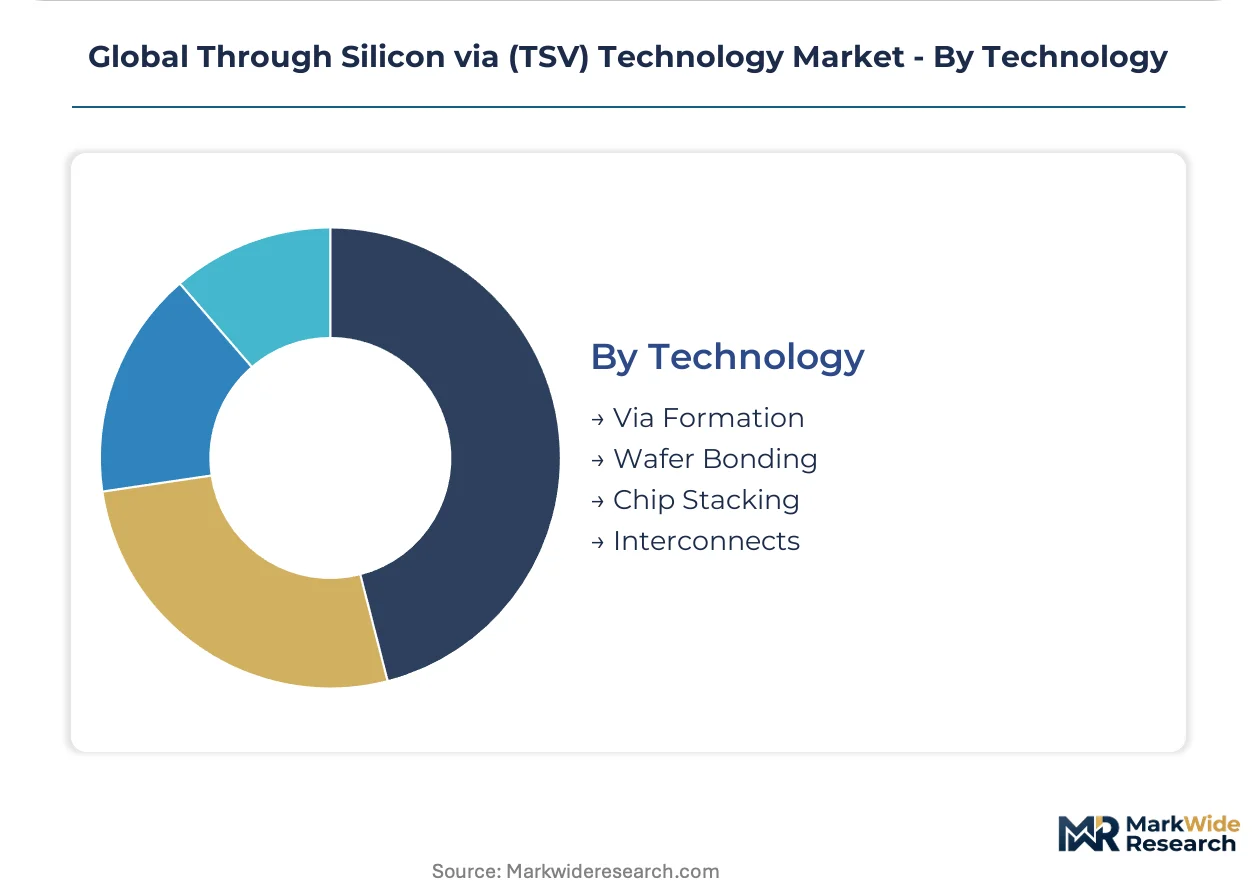
Technology:
Process technology segmentation exposes where equipment vendor relationships concentrate and where chemistry suppliers capture recurring revenue streams.
- Via Formation:Deep reactive-ion etching and laser drilling systems achieve aspect ratios exceeding 15:1 for high-density interconnects. Applied Materials and TEL equipment dominates high-volume memory foundries, with EPA hazardous substance rules tightening effluent monitoring requirements for US-based installations.
- Wafer Bonding:Precision alignment and annealing systems enable permanent die attachment with sub-micron accuracy. Japanese equipment builders including EV Group and SUSS MicroTec control critical tooling supply, creating procurement queue risks during capacity expansion cycles.
- Chip Stacking:Die placement and reflow processes complete the vertical integration sequence.
- Interconnects:Redistribution layer and bump formation technologies complete the electrical pathway from TSV to package substrate.
Via formation leads by installed equipment base. Wafer bonding is gaining share fastest amid hybrid bonding substitution threats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in South Korea and Taiwan show the lowest price elasticity, absorbing premium equipment costs for captive HBM production, while Chinese purchasers face capital constraints under export control pressures.
South Korea
AI accelerator demand from NVIDIA and hyperscale datacenters drives wafer start volumes for HBM3E at Samsung Electronics and SK Hynix. The K-Semiconductor Belt channels public capital into domestic TSV fabrication lines. Pyeongtaek's semiconductor cluster houses the world's densest memory TSV capacity, with equipment procurement cycles compressing to 12-18 months.
Taiwan
TSMC's advanced interposer production for AMD and NVIDIA AI training clusters anchors hybrid TSV adoption. The island's national development fund prioritizes advanced packaging infrastructure under the "Six Core Strategic Industries" framework. Hsinchu Science Park concentrates the densest installed base of hybrid TSV equipment, with metrology service hubs expanding in Taichung.
United States
Domestic AI chip designers are pulling TSV-enabled packaging demand toward Arizona and Texas fabs. The CHIPS and Science Act directs EPA-monitored subsidies into advanced interposer capacity, with hazardous substance rules tightening copper plating bath monitoring. Greater Phoenix emerges as the primary cluster for Intel and TSMC co-located TSV fabrication.
China
Import substitution pressures accelerate domestic equipment qualification for mid-range TSV applications in smartphone and consumer electronics. MIIT's GB standards for advanced packaging create divergent certification paths from Western supply chains. Yangtze River Delta fabs in Shanghai and Wuxi concentrate indigenous via formation tooling trials.
Germany
Automotive sensor fusion requirements from Bosch and Continental pull heterogeneous TSV demand for LiDAR edge AI modules. ECHA REACH compliance elevates material purity standards for copper plating chemistries. Dresden's Silicon Saxony cluster hosts European advanced packaging pilot lines qualifying under EU Chips Act localization mandates.
Global Through Silicon via (TSV) Technology Market Competitive Landscape
Captive foundry operators and precision equipment builders split the market into vertically integrated and specialist supplier camps. Memory foundries with in-house TSV lines capture margin concentration at the top, while Japanese and German tooling vendors control critical wafer bonding equipment supply. Two dominant competitive moves are reshaping positioning: foundries are deepening backward integration into process IP, and equipment vendors are unbundling metrology services into consumption-based pricing models.
Among the captive foundry tier, Taiwan Semiconductor Manufacturing Company Limited and Samsung Electronics exemplify scale-driven integration strategies, each leveraging captive production to dominate interposer supply and equipment procurement relationships. Applied Materials, Inc. occupies a position among precision equipment specialists, sustaining pricing power in high-aspect-ratio etch systems through hardware specialization rather than foundry-scale integration.
| Leading Market Players |
|---|
| Taiwan Semiconductor Manufacturing Company Limited |
| Applied Materials, Inc. |
| Samsung Electronics |
| Intel Corporation |
| SK Hynix |
| ASE Group |
| Micron Technology |
| STMicroelectronics |
| Broadcom Inc. |
| Others |
Supply & Pricing Matrix
Incheon-to-Shenzhen air freight corridors carry copper plating chemistries and dielectric precursors whose volatility shapes margin distribution across TSV equipment tiers. South Korean memory foundries absorb premium tooling costs through captive production models, while Chinese OSATs face capital constraints that compress service contract pricing.
Pricing Analysis
Aftermarket service revenue tiers—spanning calibration contracts, per-wafer inspection pricing, and field-engineer deployment—drive lifetime value concentration for equipment vendors. Three-tier pricing structure across premium, standard, and economy levels separates TSMC-scale foundries from mid-tier OSATs and emerging India-based packaging houses. Cost compression in standard-tier metrology tooling is intensifying because Japanese equipment builders are unbundling ownership from operator training. Chinese purchasers show highest price sensitivity; South Korean captive foundries show lowest.
Supply Chain Analysis
Supplier-financing facilities extended by Japanese precision equipment builders are easing procurement queues for wafer bonding systems amid capacity expansion cycles. Critical tooling supply draws from Japan, Germany, and the United States, with high-aspect-ratio etch systems and alignment platforms anchoring lead dependencies. Single-source vulnerability concentrates in EV Group and SUSS MicroTec bonding equipment. Distribution runs through Taiwan and Singapore-based service hubs with rapid field-engineer deployment to Pyeongtaek and Hsinchu clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid bonding substitution at sub-10µm pitch threatens mid-range TSV applications, forcing incumbents to defend interposer relevance through performance differentiation and captive integration depth.
For Market Incumbents: Insulate HBM3E and subsequent generation supply relationships through backward integration into copper plating process IP. Deepen captive via formation capabilities in Pyeongtaek and Hsinchu to offset hybrid bonding displacement in mobile processor segments. Priority investment targets extreme aspect-ratio etch uniformity to sustain pricing power against direct bonding alternatives.
For New Entrants and Emerging Players: Establish a beachhead in automotive LiDAR module integration where heterogeneous TSV demand outpaces established supply. Target German automotive OEM qualification pipelines through Dresden pilot line partnerships. Go-to-market angle centers on ISO 26262 functional safety documentation and failure-mode traceability that incumbent memory foundries underinvest in.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational equipment vendors' stranded metrology service divisions as consumption-based pricing models reshape ownership structures. Long-term viability hinges on TSV's role in AI accelerator packaging against hybrid bonding substitution timelines. Watch for ECHA REACH compliance cost escalation as inflection signal for chemistry supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Process IP | Samsung Electronics and TSMC deepen captive control over copper fill uniformity specifications. |
| Consumption-Based Service Unbundling | Applied Materials shifts metrology tool ownership toward per-wafer inspection pricing for South Korean memory foundries. |
| Automotive Safety Qualification | Bosch and Continental mandate ISO 26262 documentation for LiDAR edge AI TSV modules. |
| EU Chips Act Localization | Dresden pilot lines qualify under distinct European equipment procurement requirements separate from Asian supply chains. |
| Closed-Loop Chemistry Regeneration | California and Texas fabs adopt EPA-compliant copper plating bath systems to extend additive lifecycles. |
Research Methodology
Operator-level perspectives from wafer bonding equipment engineers, copper plating chemists, OSAT procurement directors, and field service technicians anchored the qualitative base. Primary interview data combined with secondary validation from SEC equipment vendor filings, ECHA substance restriction databases, and MIIT GB standard documentation. Bottom-up wafer start estimates from Pyeongtaek, Hsinchu, and Arizona clusters triangulated against top-down advanced packaging capex disclosures from hyperscale datacenter supply chains.
Scenario-bracketing framed optimistic and conservative demand trajectories across the projection horizon. Segmentation dimensions modeled include TSV configuration type, end-use vertical, process technology tier, and regional regulatory cluster. CAGRs derived from equipment procurement cycle compression rates and memory foundry capacity expansion timelines. Forecast inputs incorporated AI accelerator packaging wafer start elasticity and hybrid bonding substitution threat velocity.
Stress conditions across export control expansion, REACH compliance cost escalation, and hybrid bonding pitch reduction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding subsidy flow continuity and equipment vendor pricing power retention. Macroeconomic contraction, regulatory divergence, or technological substitution acceleration would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Europe Microcontroller Market
Semiconductor Devices
Thick Film Devices Market
Semiconductor Devices
Digital Transistor Market
Semiconductor Devices
Ultra Low Power Microcontroller Market
Semiconductor Devices
Global Thermoelectric Modules Market
Semiconductor Devices
Coated Silicon Wafer Market
Semiconductor Devices
Asia-Pacific Silicon Carbide Wafers Market
Semiconductor Devices
North America Silicon Carbide Wafers Market
Semiconductor Devices
Dual Voltage Comparator Market
Semiconductor Devices
IGCT Market
Semiconductor Devices
Analog to Digital Converter Market
Semiconductor Devices
Multi-Chip Module (MCM) Market
Semiconductor Devices
Semiconductor Memory IP Market
Semiconductor Devices
CZ Silicon Wafer Market
Semiconductor Devices
Flip Chip Technology Market
Semiconductor Devices
Americas Semiconductor Device Market