
 Global Optocoupler Market | 2026-2036
Global Optocoupler Market Size, Share, and Industry Trends Forecast 2026-2036
Global Optocoupler Market Outlook
Asset-light foundry partnerships and fabless manufacturing arrangements is reconfiguring capital barriers for new entrants in the optocoupler sector. ON Semiconductor leverages vertical integration across gallium arsenide LED fabrication to control input costs. Renesas Electronics anchors its position through dedicated isolation IC portfolios serving automotive microcontroller ecosystems. Vishay Intertechnology competes on high-reliability hermetic packaging for aerospace and defense channels.
An optocoupler transmits electrical signals between isolated circuits using a light-emitting diode paired with a photosensitive semiconductor detector, typically achieving isolation voltages from 2.5 kV to 8 kV depending on package construction. The device eliminates ground loop interference and protects sensitive logic from high-voltage transients in industrial motor drives and medical equipment. Phototransistor variants dominate unit shipments due to cost efficiency in consumer appliance feedback circuits, while photodiode architectures capture premium margin pools in high-speed data acquisition and telecommunications infrastructure. Isolated technology segments benefit from IEC 60747-5-5 certification requirements that disqualify non-compliant suppliers from automotive and industrial tenders.
FDA electromagnetic compatibility standards for patient-connected medical devices mandate reinforced isolation in diagnostic equipment, expanding qualified optocoupler procurement lists. ECHA REACH restrictions on lead-based solder materials are accelerating transition to halogen-free molding compounds across European supply chains. China's GB 4943.1 safety standards for information technology equipment impose creepage and clearance specifications that favor domestic certified manufacturers. Stakeholders must monitor evolving wide-bandgap semiconductor gate driver architectures that may displace traditional optocoupler isolation in next-generation power conversion systems.
Market Dynamics
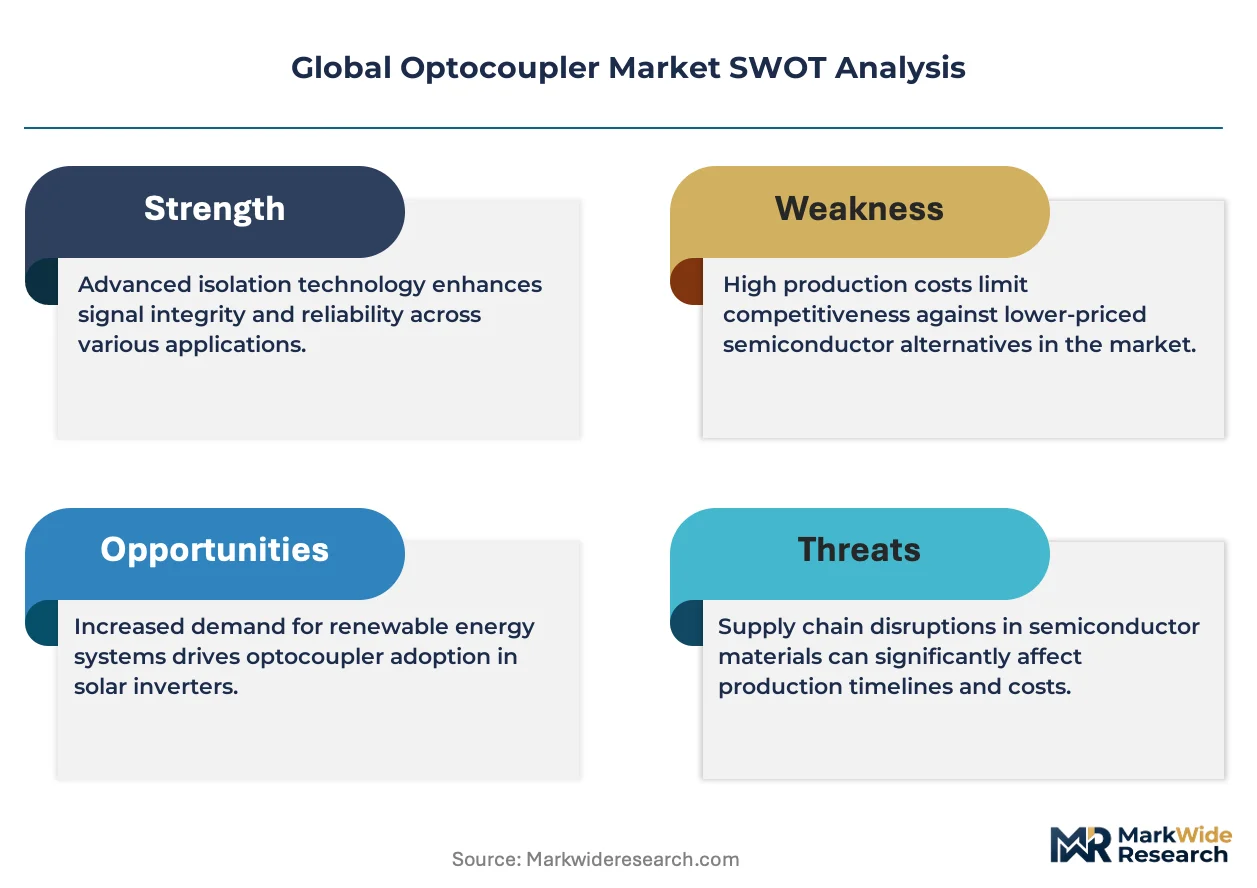
Silicon carbide gate driver integration is virtualizing isolation requirements across power electronics, compressing procurement specifications for legacy phototransistor architectures while expanding qualified supplier pools for high-speed photodiode alternatives.
Growth Catalysts
- Automotive powertrain electrification:Electric vehicle battery management systems in Germany, China, and Japan mandate reinforced isolation per IEC 60747-5-5, expanding component procurement volumes.
- REACH halogen-free mandates:ECHA restrictions on lead-based solder materials accelerate molding compound transitions across European supply chains, qualifying new compound suppliers.
- Wide-bandgap semiconductor proliferation:Silicon carbide power modules in industrial motor drives require faster switching isolation, pulling photodiode architectures into premium applications.
Market Restraints
- GaAs LED input cost volatility:Gallium arsenide wafer pricing fluctuates with rare earth supply concentration in Chinese processing facilities, squeezing margin stability for packaged device manufacturers.
- Capacitive isolator substitution:Digital isolator ICs from Texas Instruments and Analog Devices displace optocouplers in sub-5 kV applications, compressing addressable market for phototransistor variants.
- Taiwan-South Korea fab concentration:Foundry capacity for automotive-grade isolation ICs clusters in Hsinchu and Pyeongtaek corridors, creating single-point failure exposure for fabless designers.
Strategic Opportunities
- India PLI scheme localization:Production-linked incentives for semiconductor packaging attract optocoupler module assembly to Gujarat and Karnataka, reducing import dependency for industrial automation OEMs.
- Medical device isolation unbundling:FDA electromagnetic compatibility standards for patient-connected diagnostic equipment create certified component lists separate from system integrator procurement, opening direct sales channels.
- Photodiode-ASIC convergence:Integration of high-speed optical detectors with custom signal conditioning silicon enables single-package solutions for telecommunications infrastructure.
Industry Challenges
- IEC 60747-5-5 certification timeline:Reinforced isolation qualification for automotive tenders requires 18-24 month validation cycles, locking working capital in pre-revenue inventory.
- Legacy system integration friction:Phototransistor-to-photodiode upgrades in installed industrial motor drives demand controller firmware modifications, slowing replacement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Optocoupler Market |
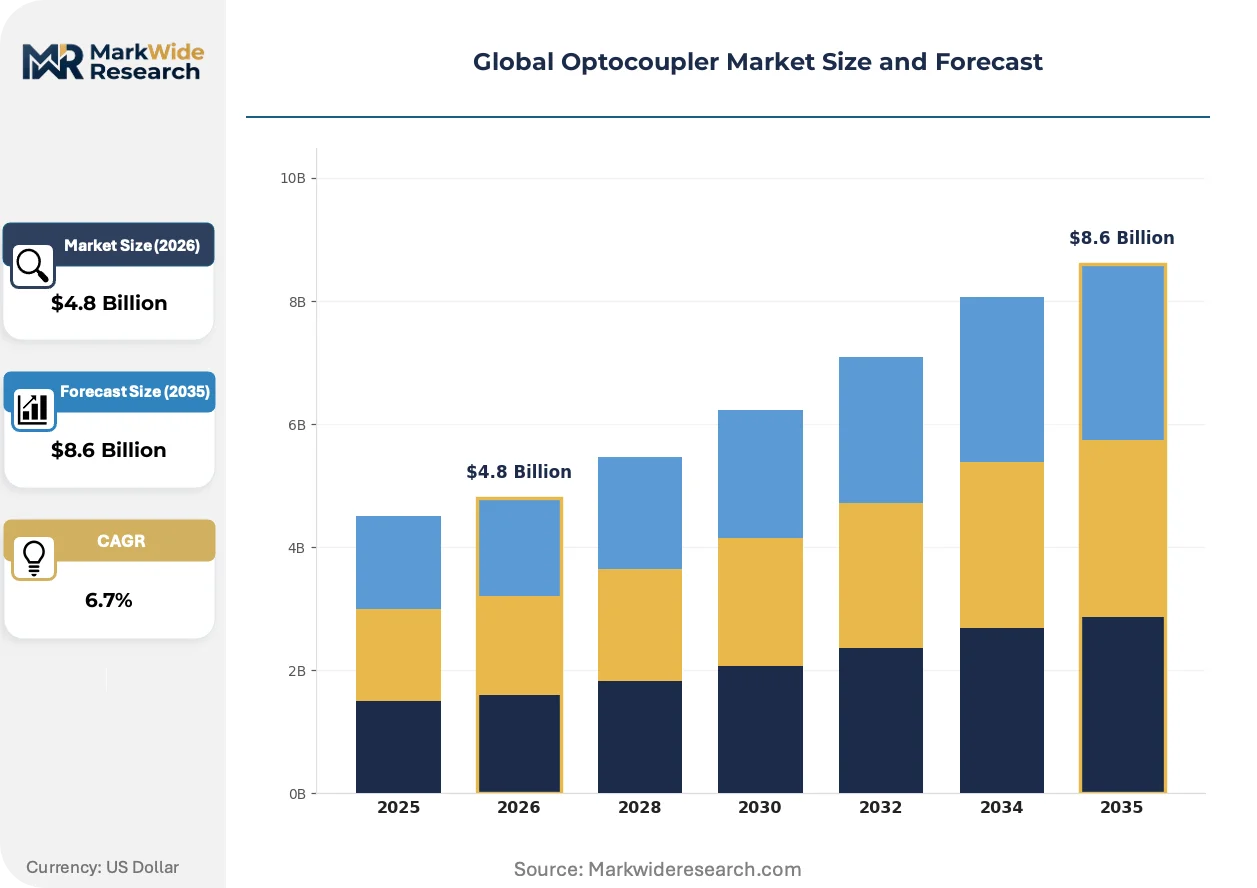
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phototransistor, Photodiode, Photometric, Photomultiplier Technology: Non-Isolated, Isolated, High-Speed, Low-Voltage Application: Industrial Automation, Consumer Electronics, Telecommunication, Automotive End User: Manufacturers, OEMs, Research Institutions, Distributors |
| Companies Covered | ON Semiconductor Corporation, Renesas Electronics Corporation, Vishay Intertechnology Inc., Everlight Electronics, Lite-On Technology Corporation, Broadcom Inc., Toshiba Electronic Devices & Storage Corporation, Sharp Corporation, Infineon Technologies AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Optocoupler Market Strategic Shifts
Isolation technology is bifurcating between cost-optimized phototransistor platforms and performance-driven photodiode architectures, with regulatory certification becoming the primary sorting mechanism for supplier qualification.
Photodiode-based optocouplers with integrated transimpedance amplifiers are virtualizing signal conditioning functions previously implemented in discrete analog front-ends. Telecommunications infrastructure operators in South Korea and Japan adopt these devices for 100 Gbps optical transceiver modules, collapsing board space requirements while maintaining IEC 60747-5-5 isolation ratings. The technology is virtualizing the boundary between optical isolation and high-speed data acquisition subsystems.
ECHA REACH restrictions on halogenated flame retardants in molding compounds redirect supplier qualification criteria across European automotive and industrial channels. Compound reformulation to phosphorus-based alternatives extends material validation timelines by 8-12 months for hermetic packaging specialists. German tier-one automotive suppliers now require full material disclosure documentation upstream to GB 4943.1-equivalent standards, compressing qualified vendor lists to vertically integrated compounders.
Certification-driven procurement consolidation concentrates component selection authority at automotive OEM system architects rather than distributed purchasing departments. Tier-two module suppliers in Japan and Taiwan report compressed quotation cycles as OEMs pre-qualify isolation devices against combined IEC 60747 and AEC-Q101 stress tests. This pattern is most visible in battery management system sourcing for Chinese electric vehicle platforms, where domestic GB standards increasingly determine international supplier access.
Global Optocoupler Market Segmentation
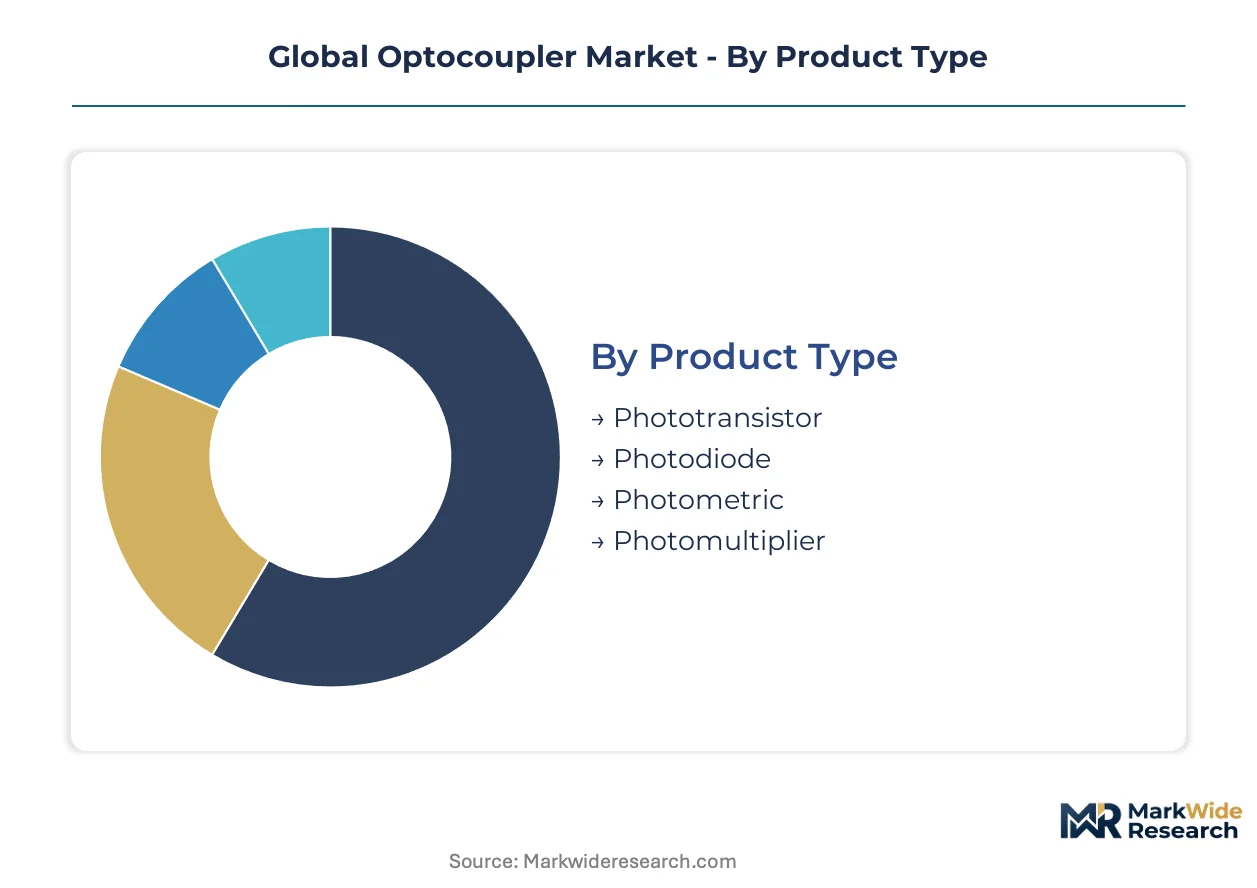
Optocoupler procurement patterns diverge sharply across isolation voltage ratings and switching speed requirements. Component selection authority concentrates at automotive OEM system architects and telecommunications infrastructure operators rather than distributed purchasing departments.
Product Type:
After-sales service intensity varies dramatically across detector architectures, with photodiode variants demanding specialized calibration support while phototransistor platforms minimize field intervention.
- Phototransistor:These devices pair a GaAs LED with a bipolar phototransistor detector, achieving switching speeds up to 250 kHz with isolation ratings from 2.5 kV to 5 kV. Demand concentrates in German and Japanese automotive battery management systems where IEC 60747-5-5 certification gates supplier qualification.
- Photodiode:PIN photodiode architectures with integrated transimpedance amplifiers deliver bandwidth exceeding 50 MHz for 100 Gbps optical transceiver modules in South Korean telecommunications infrastructure. FDA electromagnetic compatibility requirements for patient-connected diagnostic equipment pull these devices into medical device supply chains with reinforced isolation mandates.
- Photometric:Specialized detectors for precision light measurement applications in scientific instrumentation and color calibration systems.
- Photomultiplier:Ultra-sensitive vacuum tube devices for photon counting in medical imaging and high-energy physics research installations.
By volume, phototransistor variants lead. By growth pace, photodiode architectures are gaining share fastest in wide-bandgap gate driver applications.
Technology:
Cost tier stratification separates basic isolation functions from performance-critical signal integrity applications, with certification requirements determining margin capture.
- Isolated:Reinforced insulation systems achieving 5 kV to 8 kV dielectric withstand per IEC 60747-5-5, mandatory for electric vehicle powertrains in China and Germany. ECHA REACH halogen-free mandates extend material validation timelines by 8-12 months for European automotive qualification.
- High-Speed:Photodiode-based architectures with sub-nanosecond propagation delay for silicon carbide gate driver integration in industrial motor drives. Taiwan and South Korea foundry concentration creates single-point failure exposure for fabless designers serving this segment.
- Non-Isolated:Level-shifting optocouplers without galvanic isolation for logic interface applications in consumer appliances.
- Low-Voltage:Sub-3.3 V operating devices for portable electronics and battery-powered instrumentation.
By revenue concentration, isolated technology leads. By expansion trajectory, high-speed variants are climbing the fastest alongside wide-bandgap semiconductor proliferation.
Application:
Customer type determines procurement specification authority, with automotive OEMs pre-qualifying devices against combined IEC 60747 and AEC-Q101 stress tests.
- Automotive:Battery management systems and onboard chargers in electric vehicles manufactured across Germany, China, and Japan mandate reinforced isolation. China's GB 4943.1 safety standards increasingly determine international supplier access to domestic OEM platforms.
- Industrial Automation:Motor drives and programmable logic controllers in European manufacturing facilities face ECHA restrictions on lead-based solder materials, accelerating molding compound transitions.
- Telecommunication:Optical transceiver modules for 5G infrastructure and data center interconnects in South Korea and Japan.
- Consumer Electronics:Feedback circuits in home appliances and power adapters with minimal isolation requirements.
By shipment volume, consumer electronics leads. By value capture, automotive applications are expanding most quickly.
End User:
Supply concentration shapes procurement leverage, with tier-two module suppliers reporting compressed quotation cycles as qualification authority centralizes.
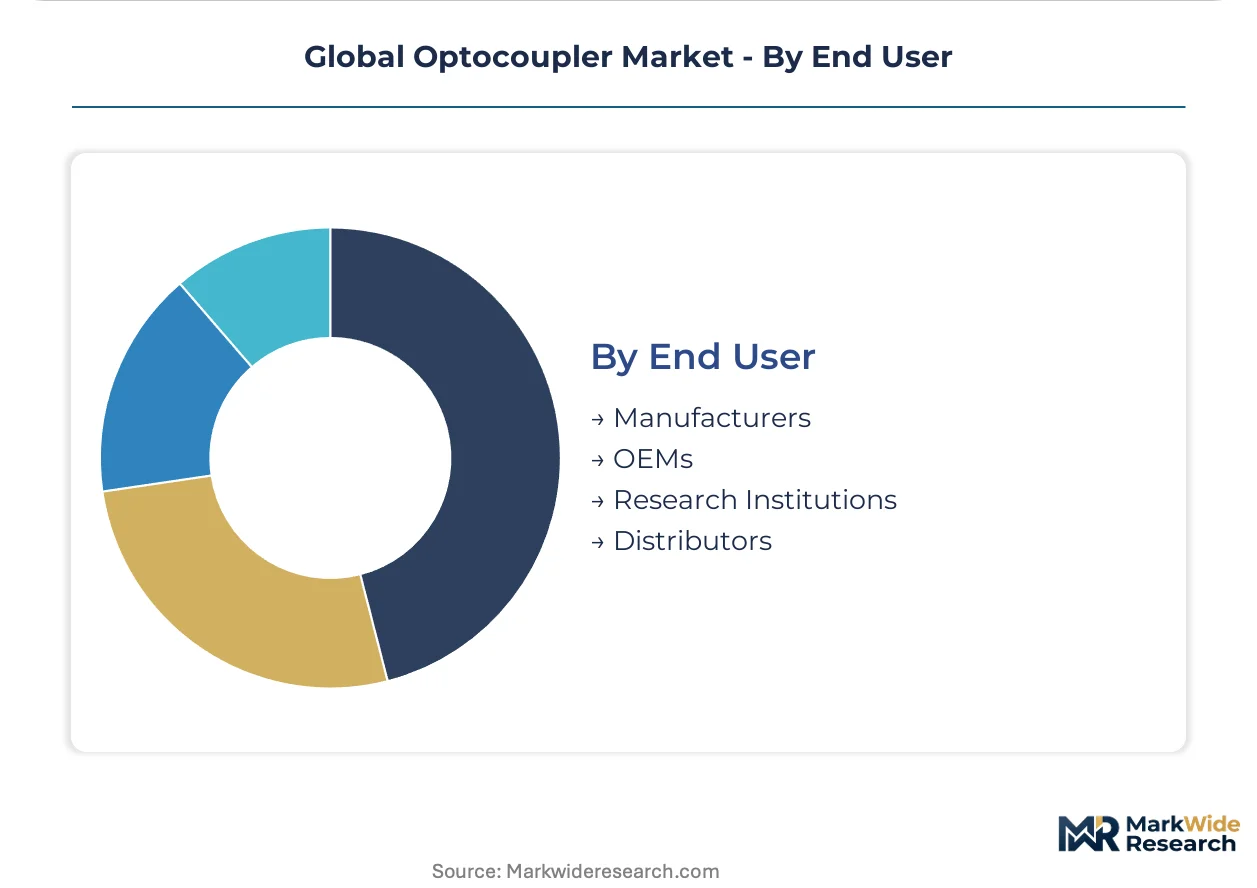
- OEMs:Automotive and telecommunications original equipment manufacturers in Japan and Taiwan drive certification-driven consolidation of component selection authority. System architects now determine isolation device qualification against combined stress tests before purchasing engagement.
- Manufacturers:Contract electronics manufacturers in India's Gujarat and Karnataka corridors assemble optocoupler modules under PLI scheme incentives, reducing import dependency for industrial automation OEMs.
- Distributors:Authorized channel partners serving mid-volume industrial and medical device producers with technical application support.
- Research Institutions:National laboratories and university physics departments sourcing specialized photomultiplier tubes for experimental apparatus.
By procurement volume, manufacturers lead. By specification influence, OEMs command the steepest expansion in direct component authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentive schemes and automotive electrification mandates are redrawing procurement corridors across major manufacturing economies. Component qualification timelines now hinge on regional certification regimes rather than cost arbitrage alone.
China
Electric vehicle battery management systems from BYD and CATL consume reinforced isolation components at scale. GB 4943.1 safety standards for information technology equipment impose creepage specifications that favor domestic certified manufacturers. The Yangtze River Delta corridor around Shanghai hosts concentrated optocoupler packaging operations serving both automotive OEMs and industrial automation exporters.
Germany
Volkswagen and BMW powertrain electrification programs mandate IEC 60747-5-5 certified isolation for onboard chargers. ECHA REACH restrictions on halogenated flame retardants extend material validation timelines by 8-12 months for compound suppliers. Bavaria's automotive electronics cluster around Munich anchors qualification testing for Tier-1 module suppliers.
Japan
Hybrid vehicle production at Toyota and Honda sustains demand for phototransistor architectures in motor control feedback circuits. METI carbon neutrality roadmaps accelerate silicon carbide power module adoption, pulling high-speed photodiode variants into industrial applications. The Chubu region around Nagoya concentrates discrete semiconductor packaging capacity for automotive channels.
South Korea
5G optical transceiver manufacturing for Samsung and SK Hynix drives photodiode procurement with sub-nanosecond propagation delay requirements. MFDS medical device regulations create parallel certification tracks for patient-connected diagnostic equipment. The Pyeongtaek semiconductor corridor houses foundry capacity for automotive-grade isolation ICs.
India
PLI scheme incentives for semiconductor packaging attract optocoupler module assembly to Gujarat and Karnataka, reducing import dependency for industrial automation OEMs. BIS certification requirements for electronic components are tightening entry criteria for non-domestic suppliers. The Delhi-Mumbai Industrial Corridor hosts emerging electronics manufacturing clusters targeting automotive substitution.
Global Optocoupler Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented tiering. Japanese and German automotive electronics suppliers anchor premium certification tiers through vertical integration into compound formulation. Taiwanese and Korean foundry partnerships enable fabless competitors to contest mid-range industrial segments. Consolidation pressure concentrates in phototransistor platforms where digital isolators erode addressable market share. Strategic moves center on IEC 60747-5-5 pre-qualification investments and halogen-free molding compound transitions.
Among vertically integrated compounders, ON Semiconductor Corporation exemplifies backward integration into gallium arsenide LED fabrication to control input cost volatility. Renesas Electronics Corporation occupies a position within the automotive microcontroller ecosystem anchoring strategy. Vishay Intertechnology Inc. represents the high-reliability hermetic packaging archetype serving aerospace and defense procurement channels with extended qualification timelines.
| Leading Market Players |
|---|
| ON Semiconductor Corporation |
| Renesas Electronics Corporation |
| Vishay Intertechnology Inc. |
| Everlight Electronics |
| Lite-On Technology Corporation |
| Broadcom Inc. |
| Toshiba Electronic Devices & Storage Corporation |
| Sharp Corporation |
| Infineon Technologies AG |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in automotive-grade isolation IC foundries across Taiwan and South Korea is compressing quotation cycles and tilting pricing power toward compounders with captive gallium arsenide LED fabrication. Utilization rates above 85 percent at Hsinchu packaging facilities are forcing fabless designers into longer-term offtake commitments to secure die supply.
Pricing Analysis
Certification level creates the primary spread across IEC 60747-5-5 automotive-grade, industrial-standard, and consumer-tier devices. Three-tier pricing structure across premium, standard, and economy levels reflects material disclosure requirements and validation timeline differentials. Cost compression in phototransistor segments is intensifying because Texas Instruments and Analog Devices digital isolators erode addressable share below 5 kV. Industrial automation OEMs exhibit highest price sensitivity, while German tier-one automotive suppliers prioritize qualification speed over unit cost.
Supply Chain Analysis
TSMC and Samsung Foundry hold dominant capacity for automotive-grade isolation IC wafer fabrication, with ASE and Amkor controlling downstream packaging. Taiwan, South Korea, and China concentrate supply for GaAs LED epitaxy, hermetic ceramic packages, and halogen-free molding compounds. The chain draws from rare earth processing facilities in Chinese Inner Mongolia for gallium feedstock, creating single-source vulnerability. Distribution runs through authorized channel partners serving mid-volume industrial and medical device producers with technical application support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified compound formulation capabilities are scarce assets that determine supplier access to European automotive and medical device channels. The 18-24 month IEC 60747-5-5 validation timeline locks working capital and creates defensive moats for incumbents with pre-certified portfolios.
For Market Incumbents: Harden qualification pipelines by securing backward integration into phosphorus-based halogen-free molding compounds before ECHA REACH deadlines. Expand die bank inventory at Hsinchu and Pyeongtaek facilities to buffer Taiwan-South Korea fab concentration risk. Prioritize AEC-Q101 stress test pre-qualification for photodiode architectures targeting silicon carbide gate driver sockets. For New Entrants and Emerging Players: India's Gujarat and Karnataka PLI scheme corridors represent the most penetrable entry point for optocoupler module assembly serving industrial automation OEMs. Medical device isolation unbundling under FDA electromagnetic compatibility standards opens direct sales channels outside system integrator procurement. Pursue compound supplier partnerships with German tier-one automotive suppliers demanding GB 4943.1-equivalent material disclosure documentation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated compounders with captive GaAs LED fabrication and hermetic packaging capabilities. Long-term viability hinges on positioning for wide-bandgap semiconductor proliferation rather than legacy phototransistor replacement cycles. Monitor silicon carbide power module adoption rates at Toyota and Honda as inflection indicator for photodiode architecture demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 60747-5-5 Pre-Qualification Investment | 18-24 month validation cycles lock out non-compliant suppliers from German and Chinese automotive tenders. |
| Halogen-Free Molding Compound Transition | ECHA REACH restrictions extend material validation timelines and compress qualified vendor lists to integrated compounders. |
| Photodiode-ASIC Convergence | Integration of optical detectors with custom signal conditioning silicon collapses board space for 100 Gbps transceivers. |
| India PLI Scheme Localization | Gujarat and Karnataka packaging incentives reduce import dependency for industrial automation OEMs. |
| GaAs LED Backward Integration | Captive epitaxy capacity buffers rare earth supply concentration and stabilizes input cost volatility. |
Study Parameters
The analysis maps phototransistor, photodiode, photometric, and photomultiplier detector architectures, each validated through semiconductor procurement managers, automotive platform engineers, medical device regulatory affairs leads, and telecommunications infrastructure operators. Primary fieldwork combined with secondary validation from IEC certification databases, ECHA REACH substance registrations, SEC 10-K filings, and customs/trade data enabled bottom-up and top-down triangulation across the value chain.
Assumptions held fixed include ECHA REACH enforcement timelines, IEC 60747-5-5 certification requirements, and silicon carbide power module adoption curves, while GaAs wafer pricing volatility and digital isolator substitution rates were varied across sensitivity scenarios. Segmentation dimensions modeled encompass detector architecture, isolation voltage tier, switching speed requirement, end-use industry, and regional regulatory cluster. CAGRs were derived from installed base growth and content-per-unit expansion in electric vehicle powertrains and telecommunications infrastructure.
Practitioners should monitor wide-bandgap semiconductor gate driver architecture shifts and ECHA substance restriction amendments for early signals of optocoupler displacement or compound reformulation requirements. Quarterly review of Taiwan-South Korea foundry utilization rates and Chinese rare earth export quotas is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Optical Emission Spectroscopy Market
Optoelectronics
Gaas Photodiode Market
Optoelectronics
Electro-Optical/Infrared (EO/IR) Systems Market
Optoelectronics
Laser Projector Market
Optoelectronics
Optoelectronic Development Tools Market
Optoelectronics
2-Ethyl-3,4-Ethylenedioxythiophene Market
Optoelectronics
Laser Diode Market
Optoelectronics
Europe Optoelectronics Market
Optoelectronics
Gaas Wafer and Epiwafer Market
Optoelectronics
Quantum Cascade Lasers Market
Optoelectronics
Cadmium Telluride Photovoltaic Market
Optoelectronics
Optoelectronic Transducers Market
Optoelectronics
Opto-Electronics Device Market
Optoelectronics
Algainp Epitaxial Wafers Market
Optoelectronics
United States Optoelectronics Market
Optoelectronics
Laser Projection Market