
 Photoluminescent Film Market | 2026-2036
Photoluminescent Film Market Size, Share, and Industry Trends Forecast 2026-2036
Photoluminescent Film Market Outlook
Specialized polymer chemist availability is unwinding across Asia-Pacific manufacturing hubs, tightening formulation capacity for strontium aluminate-based photoluminescent coatings. The 3M Company leverages its multi-layer adhesive platform to dominate self-adhesive installation formats across North American infrastructure retrofits. SKC anchors regional supply through captive PET film extrusion in South Korea, sustaining cost positions against imported substrates. IMOTO CO., LTD. specializes in ultra-thin glow-in-the-dark laminates for precision electronics labeling, occupying a defensible niche against commodity safety signage competitors.
Photoluminescent film comprises a substrate layer coated with phosphorescent pigments—typically europium-doped strontium aluminate—engineered to absorb ambient light and emit visible luminescence for durations exceeding ten hours after excitation ceases. These films serve critical visibility functions in unpowered emergency egress systems, marine safety equipment, and low-light industrial environments where electrical backup failure poses catastrophic risk. Glow-in-the-dark product types command mature volume positions across mass-market craft and toy applications, while emergency exit markings concentrate margin pools through certified compliance premiums in commercial construction. Safety applications within the application dimension are displacing decorative films as the fastest-expanding demand vector, driven by regulatory mandates rather than discretionary spending.
OSHA low-level exit signage requirements and NFPA 101 Life Safety Code provisions in the United States compel photoluminescent material adoption in commercial buildings exceeding seventy-five feet in height. ECHA REACH substance restrictions on legacy zinc sulfide phosphors are accelerating European transitions to strontium aluminate formulations with superior afterglow persistence. Japan's METI energy conservation directives incentivize zero-power safety systems in public facilities, reinforcing domestic demand for Luminescent Materials Corporation and Tsujiden Co. outputs. Stakeholders must monitor evolving harmonized standards between ISO 17398 safety sign durability classifications and national building codes to anticipate certification barriers that will reshape competitive access across priority export corridors.
Market Dynamics
Facility managers across commercial real estate are retrofitting aging structures with zero-power egress systems as electrical backup failures expose liability gaps in legacy infrastructure.
Growth Catalysts
- NFPA 101 Life Safety Code:United States commercial buildings exceeding seventy-five feet in height must install low-level exit signage, compelling material upgrades from electrically powered to photoluminescent solutions.
- Strontium aluminate phosphors:Europium-doped formulations deliver afterglow persistence exceeding ten hours, eliminating battery maintenance costs and enabling adoption in marine safety equipment and unpowered industrial environments.
- Japan's METI directives:Energy conservation mandates in public facilities incentivize zero-power safety systems, reinforcing domestic manufacturing output for precision electronics labeling applications.
Market Restraints
- Specialized polymer chemist scarcity:Asia-Pacific manufacturing hubs face tightening formulation capacity for high-performance phosphorescent coatings, constraining substrate quality consistency.
- ECHA REACH substance restrictions:Legacy zinc sulfide phosphor phase-outs force immediate formulation transitions, compressing margin recovery timelines for European distributors.
- High-performance adhesive input costs:Multi-layer acrylic platforms required for durable self-adhesive installation formats experience petrochemical price volatility, pressuring retrofit project economics.
Strategic Opportunities
- ISO 17398 harmonization:Convergence between international safety sign durability classifications and national building codes creates certification arbitrage for compliant manufacturers entering priority export corridors.
- Ultra-thin glow-in-the-dark laminates:Precision electronics labeling represents an underpenetrated niche with premium pricing power distinct from commodity safety signage segments.
- German commercial building stock:Aging infrastructure combined with stringent occupational safety enforcement generates concentrated demand for code-compliant egress marking retrofits.
Industry Challenges
- Phosphorescent pigment integration complexity:Substrate layer uniformity requirements demand specialized coating equipment, elevating capital intensity for new market entrants.
- Certification timeline compression:Evolving harmonized standards between ISO classifications and national building codes extend product validation cycles, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photoluminescent Film Market |
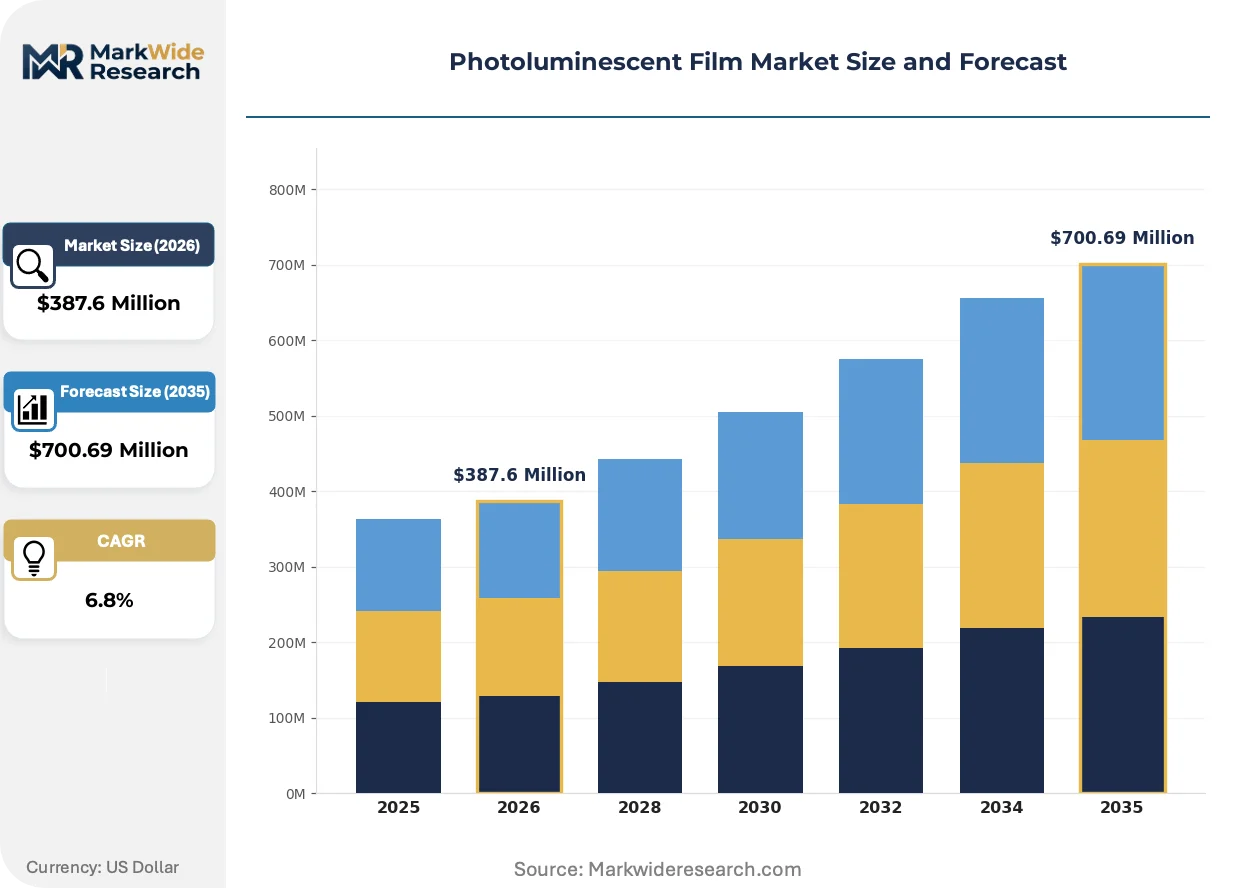
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glow-in-the-Dark, Safety Signs, Decorative Films, Emergency Exit Markings Application: Emergency Lighting, Safety Applications, Interior Design, Art Projects End User: Manufacturing, Construction, Retail, Hospitality Installation: Self-Adhesive, Non-Adhesive, Laminated, In-Mold |
| Companies Covered | The 3M Company, SKC, IMOTO CO., LTD., Avery Dennison, LINTEC Corporation, Tsujiden Co., Luminescent Materials Corporation, Radiant Color Technologies, Glow Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photoluminescent Film Market Strategic Shifts
Formulation chemistry and installation format preferences are converging to redefine competitive advantage, with substrate performance and adhesive durability separating premium suppliers from commodity producers.
Strontium aluminate-based photoluminescent coatings are displacing zinc sulfide legacy formulations across certified safety applications. Commercial construction procurement teams specify europium-doped substrates for egress systems in facilities governed by NFPA 101 provisions. The technology is displacing electrically powered exit signage in height-restricted buildings where backup power failure poses catastrophic liability exposure.
REACH substance restrictions on zinc sulfide phosphors are accelerating European transitions to superior afterglow persistence formulations. Industrial consequence includes immediate raw material sourcing reconfiguration for coating manufacturers serving EU export markets. Commercial construction segments in Germany and France are responding by pre-qualifying strontium aluminate suppliers ahead of mandatory compliance deadlines.
Retrofit-first procurement patterns are compressing new-build specification cycles for emergency egress systems. Facility management service providers are consolidating vendor relationships around full-service substrate-adhesive-installation packages, displacing component-only purchasing. This concentration is most visible in United States commercial real estate portfolios where centralized safety compliance oversight reduces supplier fragmentation.
Photoluminescent Film Market Segmentation
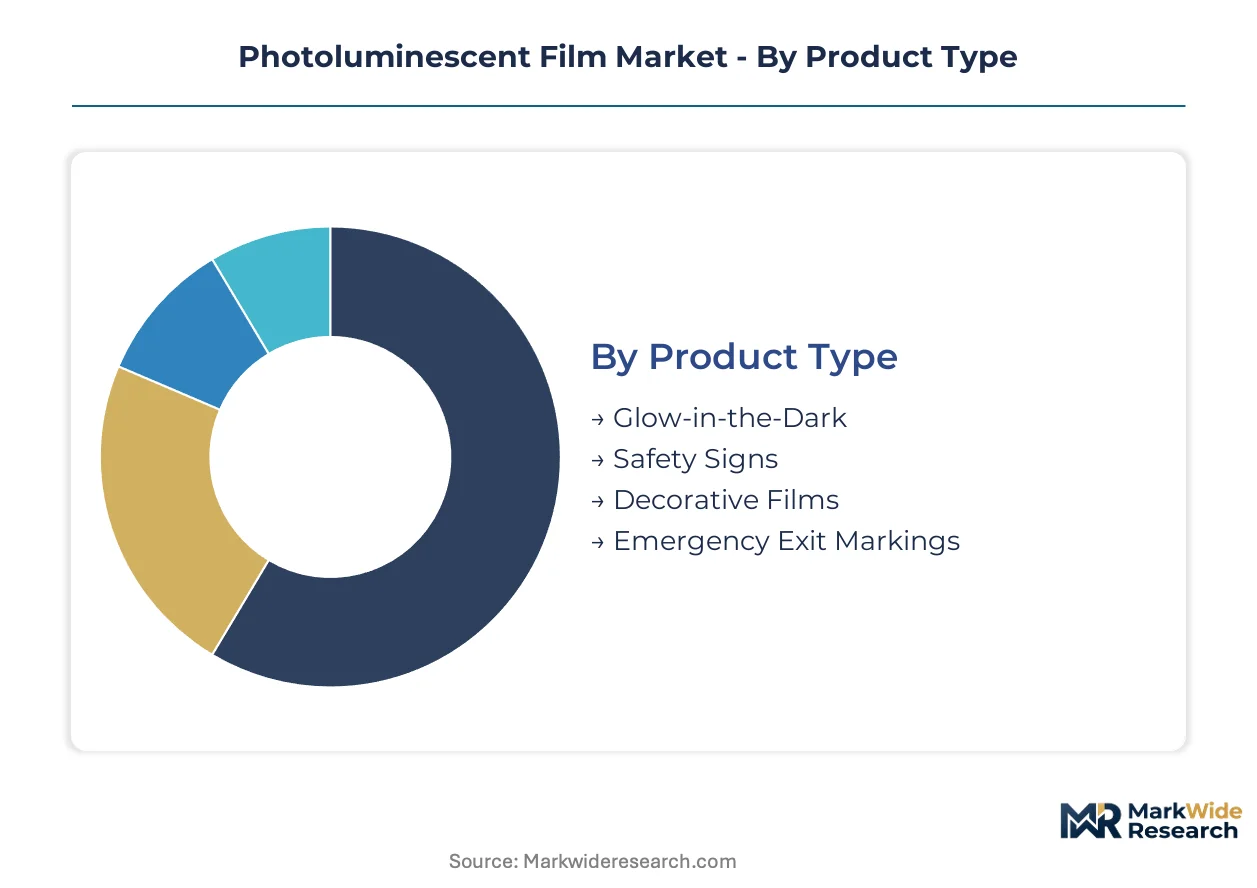
Segmentation in photoluminescent film markets reveals how regulatory mandates and installation economics reshape competitive positioning across substitute-threatened categories. Product formulation durability and adhesive platform performance now determine vendor selection more than luminescence intensity alone.
Product Type:
Substitution pressure from electrically powered alternatives is most acute in decorative applications, where battery-operated LED strips compete on color range and programmability.
- Safety Signs:Certified egress markings employ europium-doped strontium aluminate substrates engineered for ISO 17398 durability classifications. Demand concentrates in United States commercial real estate portfolios subject to NFPA 101 height restrictions, where facility managers eliminate electrical backup liability through zero-power installation.
- Emergency Exit Markings:Low-location luminous strips and floor-mounted directional indicators serve unpowered evacuation pathways in marine vessels and industrial facilities. German commercial building retrofits drive specification intensity as REACH-mandated phosphor transitions accelerate material upgrade cycles.
- Glow-in-the-Dark:Mass-market craft and toy applications face margin compression from Asian commodity producers.
- Decorative Films:Architectural accent and entertainment venue applications compete directly with active illumination technologies.
Safety Signs retains volume leadership; Emergency Exit Markings holds the steepest expansion curve.
Application:
Cost tier differentiation separates certified safety systems from discretionary interior design specifications, with procurement authority residing in entirely different organizational functions.
- Safety Applications:Industrial environments and transportation infrastructure deploy photoluminescent films where electrical failure poses catastrophic risk. Japan's METI energy conservation directives reinforce public facility adoption, sustaining domestic manufacturing output for precision labeling requirements.
- Emergency Lighting:Unpowered egress illumination displaces battery-backed fixtures in height-restricted buildings and marine safety equipment. United States OSHA enforcement patterns compel retrofit investment across aging commercial building stock exceeding seventy-five feet.
- Interior Design:Hospitality and corporate environment accents command premium pricing through custom color matching.
- Art Projects:Limited-edition installations and museum exhibitions specify archival-grade substrate formulations.
Safety Applications dominates procurement volume; Emergency Lighting is climbing the fastest as code compliance deadlines compress.
End User:
Customer type determines specification complexity, with construction and manufacturing procurement teams demanding certified compliance documentation that retail buyers rarely require.
- Construction:Commercial building contractors integrate photoluminescent egress systems into new-build and retrofit safety packages. German facility managers specify strontium aluminate formulations ahead of mandatory zinc sulfide phase-outs, pre-qualifying suppliers for multi-year maintenance contracts.
- Manufacturing:Industrial facility operators deploy glow-in-the-dark floor markings and equipment labeling in low-light production environments. United States automotive and aerospace plants specify durable adhesive platforms resistant to chemical exposure and foot traffic abrasion.
- Retail:Point-of-sale displays and seasonal merchandise drive cyclical demand for lower-durability formulations.
- Hospitality:Hotel and entertainment venue designers specify decorative luminescent accents for experiential differentiation.
Construction anchors procurement scale; Manufacturing is gaining share fastest through industrial safety mandates.
Installation:
Supply concentration in multi-layer adhesive platforms creates tiered performance segmentation, with self-adhesive formats commanding premium positioning against mechanically fastened alternatives.
- Self-Adhesive:Pressure-sensitive acrylic platforms enable rapid retrofit installation across concrete, metal, and painted drywall substrates. North American infrastructure projects specify 3M adhesive technologies for durability warranties spanning decade-long service intervals.
- Laminated:Protective overlaminate films extend substrate lifespan in high-abrasion environments such as marine decks and factory floors. SKC captive PET extrusion in South Korea sustains regional cost positions against imported substrate alternatives.
- Non-Adhesive:Mechanically fastened or magnetic mounting serves temporary and reusable applications.
- In-Mold:Integration during injection molding enables durable labeling of plastic safety equipment and electronic housings.
Self-Adhesive retains specification dominance; Laminated is expanding most quickly through industrial durability requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA enforcement patterns in the United States establish the regulatory baseline that other jurisdictions reference for photoluminescent egress compliance. Facility managers across commercial real estate portfolios respond to height-based mandates by eliminating electrical backup systems entirely.
United States
Commercial buildings exceeding seventy-five feet face NFPA 101 Life Safety Code requirements for low-level exit signage. Facility managers in Chicago, New York, and Los Angeles retrofit aging stock with zero-power systems to close liability gaps from generator failure. OSHA inspection intensity in coastal metro corridors accelerates procurement timelines for strontium aluminate formulations.
Germany
Aging commercial building stock in Frankfurt, Munich, and Hamburg generates concentrated demand for code-compliant egress marking. ECHA REACH substance restrictions on zinc sulfide phosphors compel immediate formulation transitions to europium-doped alternatives. Industrial facility operators in the Ruhr Valley pre-qualify suppliers ahead of mandatory compliance deadlines.
Japan
METI energy conservation directives incentivize zero-power safety systems across public facilities in Tokyo, Osaka, and Nagoya. Precision electronics labeling applications sustain domestic manufacturing output for ultra-thin glow-in-the-dark laminates. Tsujiden Co. and Luminescent Materials Corporation anchor regional supply through captive production networks.
South Korea
SKC operates captive PET film extrusion facilities serving regional cost positions against imported substrate alternatives. Industrial safety mandates in Busan-Ulsan manufacturing corridors drive specification intensity for durable adhesive platforms. Seoul Capital Area commercial real estate retrofits concentrate demand for self-adhesive installation formats.
United Kingdom
London commercial property managers respond to Building Regulations Approved Document B provisions for emergency lighting alternatives. Manchester and Birmingham industrial estates deploy photoluminescent floor markings in low-light production environments. British Standards Institution certification timelines extend product validation cycles for continental suppliers.
Photoluminescent Film Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with adhesive platform control and phosphorescent formulation expertise defining competitive separation. The 3M Company leverages multi-layer acrylic technologies to dominate North American retrofit infrastructure. SKC sustains regional cost positions through captive substrate extrusion. Three strategic archetypes prevail: integrated materials-science conglomerates, regional substrate specialists, and precision electronics labeling niche players. Competitive moves concentrate on vertical integration into phosphorescent pigment sourcing and certification pre-qualification ahead of harmonized standard implementation.
Among Japanese precision manufacturers, IMOTO CO., LTD. exemplifies the ultra-thin laminate specialist archetype. The 3M Company and SKC represent divergent scale strategies—adhesive platform dominance versus captive substrate control. Tsujiden Co. and Luminescent Materials Corporation occupy positions within the domestic Japanese supply base serving METI-directed public facility procurement. Avery Dennison and LINTEC Corporation sit within the diversified label-and-film conglomerate tier competing across multiple luminescent application segments.
| Leading Market Players |
|---|
| The 3M Company |
| SKC |
| IMOTO CO., LTD. |
| Avery Dennison |
| LINTEC Corporation |
| Tsujiden Co. |
| Luminescent Materials Corporation |
| Radiant Color Technologies |
| Glow Technologies Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive PET film extrusion capacity in South Korea and Japan anchors substrate cost positions, concentrating supply-side scale economies among integrated producers while compressing margin floors for distributors dependent on imported materials. This geographic concentration of formulation expertise and substrate manufacturing shapes pricing power across certified safety applications, where NFPA 101 and REACH compliance premiums separate defensible margin tiers from commodity glow-in-the-dark segments.
Pricing Analysis
Price spreads between German industrial procurement and Asian mass-market channels exceed threefold, reflecting certification-grade stratification. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17398-certified egress systems from uncertified decorative films. Cost compression in economy-tier craft applications is intensifying because Asian commodity producers flood mass-market channels with zinc sulfide legacy formulations. Construction procurement teams exhibit lowest price sensitivity due to liability-driven specification mandates, while retail buyers drive aggressive commoditization.
Supply Chain Analysis
Strait of Malacca transit routes underpin raw material flows for europium-doped strontium aluminate phosphors, creating logistics vulnerability for European and North American coating manufacturers. Supply concentrates in China, South Korea, and Japan for phosphorescent pigment synthesis and PET substrate extrusion. Formulation chemistry draws from rare earth oxide feedstocks, multi-layer acrylic adhesives, and precision coating equipment. Single-source vulnerability in specialized polymer chemist availability constrains quality consistency. Distribution runs through construction supply houses, industrial safety distributors, and direct OEM contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through facility management service provider consolidation, with centralized procurement teams displacing fragmented component purchasing across commercial real estate portfolios.
For Market Incumbents: Secure backward integration into phosphorescent pigment sourcing to defend margin positions against raw material volatility. Prioritize ISO 17398 certification pre-qualification ahead of harmonized standard implementation to lock out emerging competitors. The threat of REACH-mandated formulation transitions compresses timeline advantages for prepared suppliers. For New Entrants and Emerging Players: Certification fast-track through British Standards Institution or UL pathways opens access to UK and North American retrofit corridors. Precision electronics labeling represents the most penetrable white-space target, with premium pricing power distinct from commodity safety signage. A go-to-market angle anchored in ultra-thin laminate technology for automotive and aerospace applications bypasses incumbent construction supply channel control. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors adhesive platform specialists with captive substrate relationships over pure-play phosphorescent coating operations. Long-term viability rests on regulatory compliance durability rather than luminescence performance alone. The acquisition target archetype combines multi-layer acrylic expertise with pre-qualified certification status. Watch for ECHA substance restriction expansion signals as inflection indicators for formulation transition urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphorescent Pigments | Captive supply of europium-doped strontium aluminate insulates margin from rare earth price volatility. |
| ISO 17398 Certification Pre-Qualification | Early compliance with harmonized durability classifications locks preferred supplier status with construction procurement teams. |
| Ultra-Thin Laminate Capacity Expansion | Precision electronics labeling commands premium pricing distinct from commodity safety signage segments. |
| Multi-Layer Adhesive Platform Investment | Decade-long durability warranties differentiate retrofit offerings in North American infrastructure markets. |
| Regional Substrate Extrusion Joint Venture | Local PET film production in Busan-Ulsan corridor reduces logistics exposure for Korean industrial safety demand. |
Study Parameters
The analysis maps safety signage, emergency exit markings, glow-in-the-dark products, and decorative films, each validated through facility managers, construction procurement leads, industrial safety officers, and coating formulation chemists. Primary interviews with these stakeholders combined with secondary validation from NFPA code documentation, ECHA REACH substance databases, METI directive filings, and customs trade data. Bottom-up segment sizing triangulates against top-down market aggregation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models product type, application, end user, and installation format dimensions. CAGRs derive from segment-level growth trajectory analysis incorporating regulatory mandate timelines, commercial building stock age profiles, and phosphorescent formulation transition curves. Industry-specific inputs include OSHA enforcement intensity patterns and ECHA substance restriction phase-out schedules.
Underlying assumptions cover regulatory compliance deadline adherence, rare earth oxide supply continuity, and construction retrofit spending persistence, with deviation risk concentrated in REACH restriction expansion scope and polymer chemist labor market tightness. Practitioners should keep alternative scenarios live as harmonized standard implementation timelines and energy conservation directive revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Optoelectronic Transducers Market
Optoelectronics
Gaas Photodiode Market
Optoelectronics
EPON ONU Market
Optoelectronics
Light Projector Market
Optoelectronics
Laser Projection Market
Optoelectronics
Gallium Arsenide Gaas Wafer Market
Optoelectronics
Optoelectronics Market
Optoelectronics
Europe Optoelectronics Market
Optoelectronics
United States Optoelectronics Market
Optoelectronics
Thermophotovoltaics Market
Optoelectronics
Laser Projector Market
Optoelectronics
Automotive Optoelectronics Market
Optoelectronics
Gallium Arsenide Market
Optoelectronics
Americas Optoelectronics Market
Optoelectronics
Integrated Circuit Optocouplers Market
Optoelectronics
Asia-Pacific Optoelectronics Market