
 Gaas Epiwafer Market | 2026-2036
Gaas Epiwafer Market Size, Share, and Industry Trends Forecast 2026-2036
Gaas Epiwafer Market Insights
Compound semiconductor process engineering talent scarcity is redrawing competitive boundaries across the GaAs epiwafer supply base. IQE leverages its epitaxy foundry model to sustain high-mix production across RF and photonics applications. Freiberger Compound Materials anchors European supply security through captive crystal growth and polishing capabilities. WIN Semiconductors dominates pure-play GaAs foundry services, competing on yield rates and cycle-time compression for handset power amplifiers.
GaAs epiwafers consist of thin crystalline layers grown atop gallium arsenide substrates via metal-organic chemical vapor deposition or hydride vapor phase epitaxy, engineered for direct bandgap properties that enable efficient electron mobility at microwave frequencies. These wafers serve as the foundational material for high-frequency RF power amplifiers, infrared laser diodes, and high-brightness LEDs where silicon substrates underperform. Multi-layer epiwafers command premium positioning as handset OEMs stack heterostructures for enhanced power-added efficiency. RF device applications absorb the dominant share of merchant epiwafer output, while laser diode segments for LiDAR and optical communications represent the fastest-expanding demand pool. MOCVD technology leads production volume, though HVPE gains traction for thick-layer structures in photovoltaics and specialty lasers.
FDA oversight of medical laser systems and FCC spectrum allocation rules directly shape GaAs epiwafer demand through device certification requirements and frequency band assignments. EPA hazardous waste protocols and OSHA semiconductor fabrication standards govern chemical handling in MOCVD reactors, raising compliance costs for domestic manufacturers. REACH substance restrictions in Europe and RoHS material limits constrain dopant selection and post-etch cleaning chemistries across export-bound supply chains. Stakeholders must monitor emerging export controls on compound semiconductor equipment and precursor chemicals as geopolitical fragmentation of epitaxial tool sourcing intensifies.
Market Dynamics
5G base station deployment intensity is compressing RF power amplifier procurement cycles, forcing epiwafer suppliers to synchronize MOCVD reactor scheduling with telecommunications infrastructure rollout timetables in East Asian fabrication clusters.
Growth Catalysts
- Dual carbon mandates:China's MEE efficiency standards are accelerating substrate energy-consumption benchmarks, pushing foundries toward thicker epi-layers that reduce thermal losses in high-frequency operation.
- LiDAR integration:Automotive OEMs are specifying 905nm and 1550nm laser diodes for advanced driver-assistance systems, creating fresh demand pools for HVPE-grown thick-layer structures.
- Spectrum allocation:FCC mid-band assignments for 5G-Advanced are expanding addressable frequency ranges for handset power amplifiers, extending GaAs heterostructure relevance against silicon alternatives.
Market Restraints
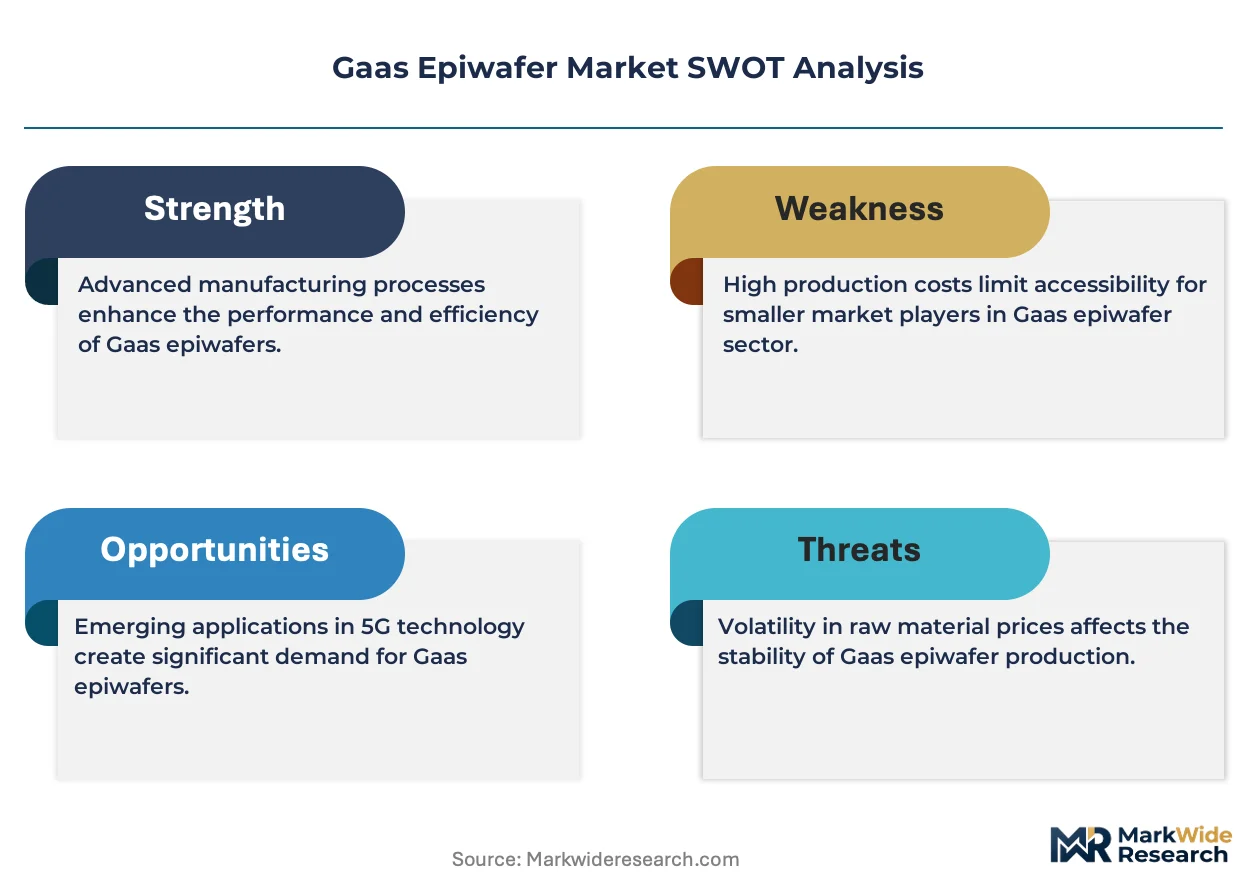
- Precursor chemical concentration:Trimethylgallium and arsine supply chains cluster in Japanese and Chinese specialty chemical producers, exposing MOCVD operators to geopolitical disruption risk.
- Capital intensity barriers:Multi-wafer MOCVD reactors require $15-25 million per installation with 18-month qualification timelines, freezing out mid-scale entrants.
- Silicon germanium substitution:SiGe BiCMOS processes are capturing sub-6GHz RF applications where linearity requirements permit, narrowing GaAs addressable markets in cost-sensitive handset segments.
Strategic Opportunities
- Photovoltaic concentrator cells:Triple-junction GaAs structures for space and terrestrial concentrator systems represent underexploited demand, with satellite constellation operators specifying radiation-hardened epi-designs.
- Optical communications expansion:Data center interconnects at 400G and 800G are driving VCSEL and edge-emitting laser demand for short-reach fiber links, favoring 6-inch epiwafer formats.
- European supply security:REACH substance restrictions and strategic autonomy frameworks are incentivizing captive crystal growth and polishing investments outside East Asian supply nodes.
Industry Challenges
- Epitaxy engineer scarcity:Compound semiconductor process engineering talent pools concentrate in Taiwan and South Korea, constraining reactor utilization rates at newer fabrication facilities.
- Multi-layer qualification protocols:Handset OEMs require 12-18 month heterostructure validation cycles for each new power amplifier design, compressing effective product lifecycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gaas Epiwafer Market |
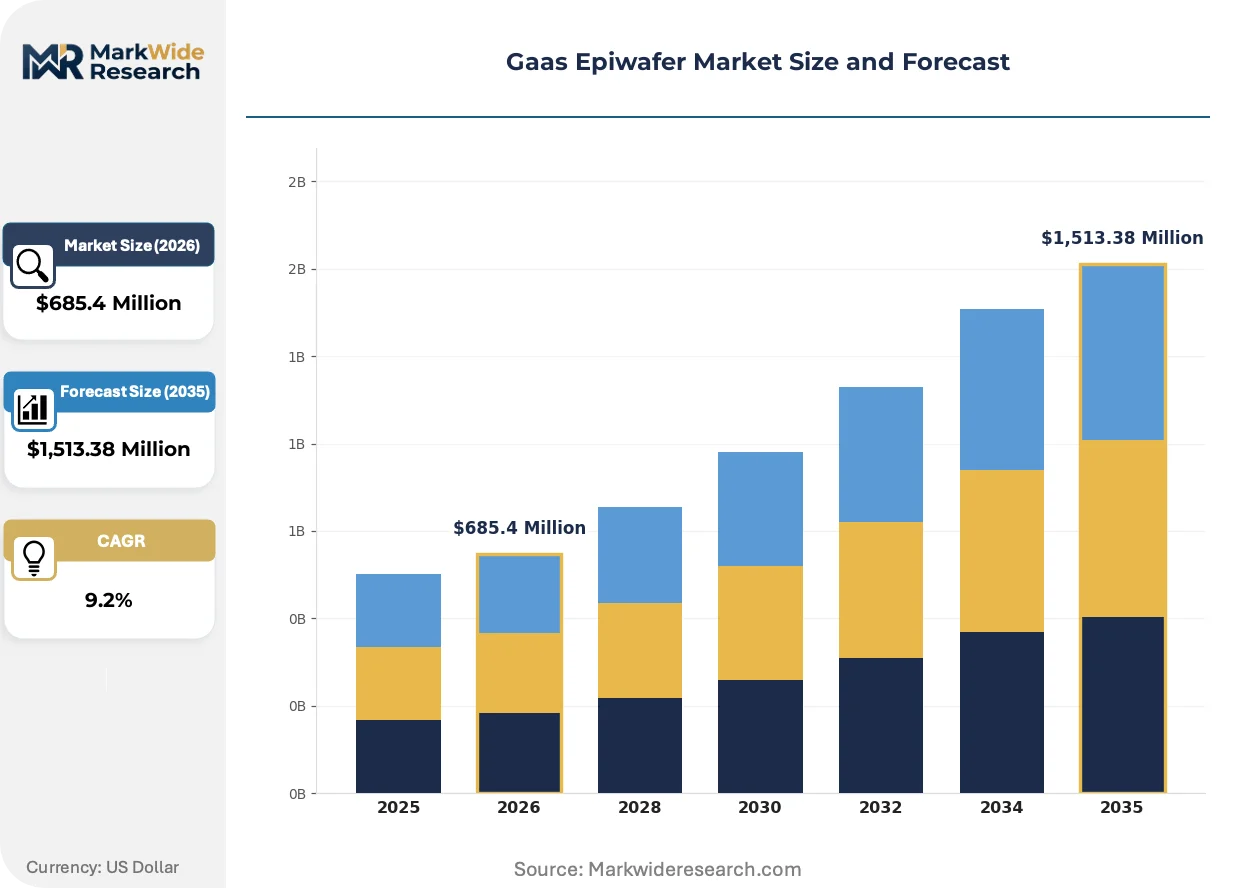
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,513.38 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Layer Epiwafers, Multi-Layer Epiwafers, Pinned Epiwafers, Epitaxial Wafer Structures End User: Telecommunications, Consumer Electronics, Automotive, Aerospace Technology: MOCVD, LPE, CVD, HVPE Application: LEDs, Laser Diodes, RF Devices, Photovoltaics |
| Companies Covered | Sumitomo Electric Industries, Freiberger Compound Materials, AXT, Xiamen Powerway Advanced Material, DOWA Electronics Materials, IQE, Vital Materials, China Crystal Technologies, WIN Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gaas Epiwafer Market Trends and Innovations
Process engineering advances and regulatory recalibrations are redefining competitive differentiation in epitaxial wafer supply, with equipment architecture and precursor chemistry emerging as decisive capability anchors.
Monolithic integration of power amplifiers with RF switches and filters is miniaturizing front-end module footprints for 5G millimeter-wave handsets. Smartphone OEMs in South Korea and Taiwan are specifying 150mm epiwafers with 15-plus heterostructure layers to achieve target power-added efficiency. This density requirement is compressing cycle times at merchant foundries and favoring equipment architectures with faster temperature ramp rates.
REACH substance restrictions in Europe are constraining dopant selection and post-etch cleaning chemistries across export-bound supply chains. ECHA candidate list updates are forcing reformulation of selenium and tellurium precursor alternatives in MOCVD processes. Photonics applications with European medical device exposure are accelerating qualification of compliant epi-processes ahead of sunset dates.
Consolidation among RF device OEMs is concentrating procurement leverage and demanding vendor-managed inventory arrangements from epiwafer suppliers. Tier-one handset power amplifier designers in Taiwan are negotiating take-or-pay contracts with foundries to secure reactor capacity. This contractual evolution is most visible in East Asian semiconductor fabrication clusters where multi-year supply agreements now precede technology node transitions.
Gaas Epiwafer Market Segmentation
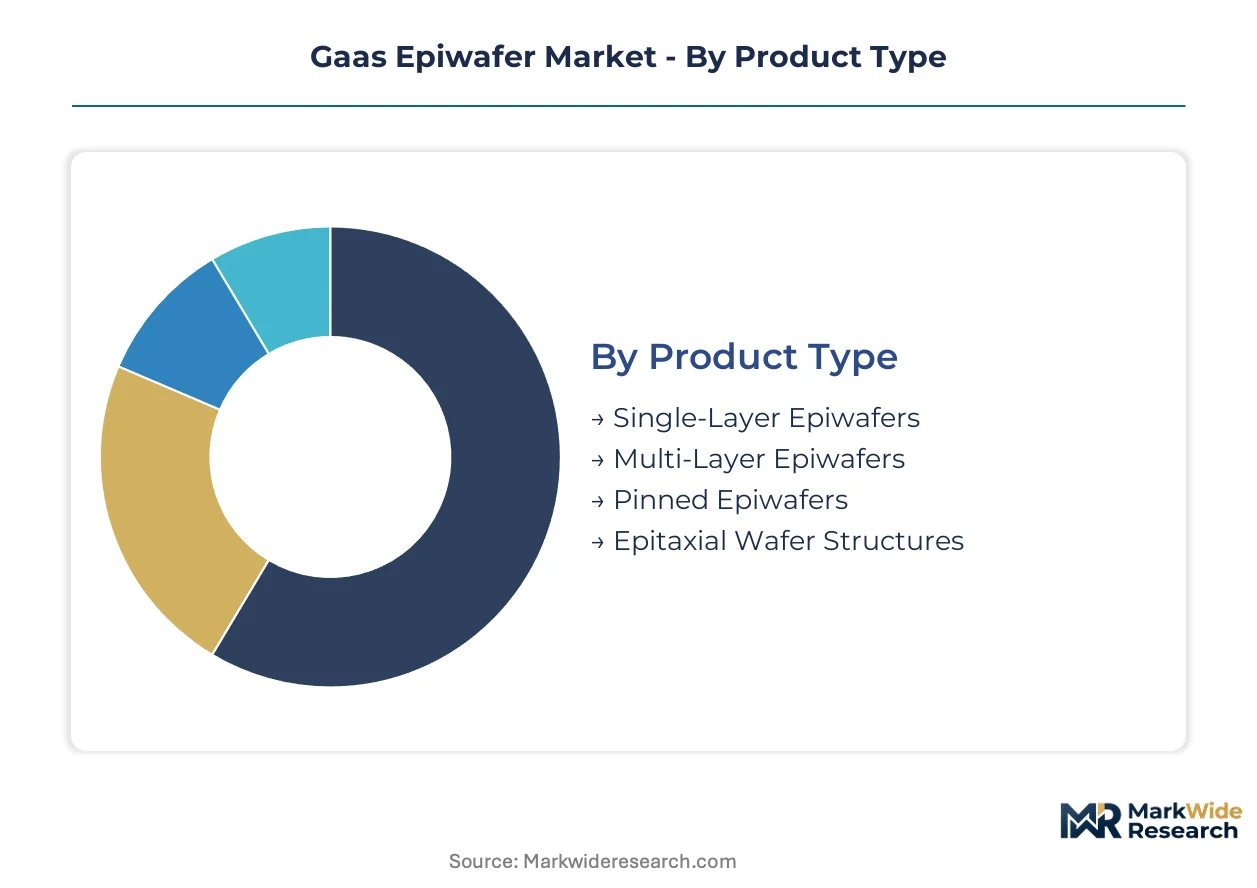
GaAs epiwafer procurement patterns diverge sharply across product architectures and deposition technologies, with heterostructure complexity and substrate diameter driving foundry capacity allocation decisions. Equipment qualification timelines and end-use certification requirements fragment addressable volumes across divergent specification bands.
Product Type:
Multi-layer heterostructures face intensifying substitution pressure from silicon germanium BiCMOS in sub-6GHz handset segments, while single-layer formats confront commoditization as Chinese substrate producers expand merchant epi capacity.
- Multi-Layer Epiwafers:These structures stack 15-plus heterolayers via precise MOCVD temperature cycling to achieve target power-added efficiency in millimeter-wave power amplifiers. Handset OEMs in Taiwan and South Korea specify these wafers for 5G-Advanced front-end modules, though 18-month qualification cycles compress effective revenue windows.
- Single-Layer Epiwafers:Simpler epitaxial structures grown for infrared LEDs and basic photodetector applications carry thinner margins but faster production turns. Chinese merchant foundries are expanding 150mm single-layer capacity to serve domestic LED packaging clusters, pressuring pricing in commodity tiers.
- Pinned Epiwafers:Specialized structures with buried doping profiles for high-frequency RF switching applications, manufactured primarily for defense-qualified suppliers.
- Epitaxial Wafer Structures:Custom-engineered layer stacks for research institutions and prototype foundry services, commanding premium pricing at low volumes.
Multi-Layer Epiwafers retain volume leadership; Pinned Epiwafers hold the steepest expansion curve.
End User:
Automotive qualification protocols impose the most demanding reliability screening, with AEC-Q101 stress testing extending procurement lead times beyond telecommunications or consumer electronics benchmarks.
- Telecommunications:Base station OEMs and handset power amplifier designers absorb the dominant share of merchant epiwafer output, with 5G-Advanced deployments in Taiwan and South Korea compressing MOCVD reactor scheduling. FCC mid-band spectrum assignments are expanding addressable frequency ranges for GaAs heterostructures.
- Automotive:LiDAR module integrators specify 905nm and 1550nm laser diode epiwafers for advanced driver-assistance systems, with European OEMs accelerating REACH-compliant process qualifications ahead of ECHA sunset dates.
- Consumer Electronics:Wireless earbud and wearable device manufacturers drive VCSEL demand for short-range optical sensing, favoring 6-inch wafer formats.
- Aerospace:Satellite constellation operators specify radiation-hardened triple-junction structures for space photovoltaic concentrator cells, with captive epitaxy requirements limiting merchant market penetration.
Telecommunications dominates current procurement volumes; Automotive climbs the fastest as LiDAR penetration deepens.
Technology:
Capital intensity stratifies deposition technology adoption, with multi-wafer MOCVD reactor installations requiring $15-25 million per unit and freezing out mid-scale entrants.
- MOCVD:Metal-organic chemical vapor deposition dominates production volume through precise control of aluminum gallium arsenide composition gradients. East Asian foundries in Taiwan and South Korea operate the largest installed reactor fleets, though trimethylgallium precursor supply chains cluster in Japanese and Chinese specialty chemical producers.
- HVPE:Hydride vapor phase epitaxy gains traction for thick-layer structures exceeding 10 micrometers in photovoltaics and specialty lasers, with slower growth rates but superior material quality for space applications.
- LPE:Liquid phase epitaxy persists for legacy infrared LED production and research-scale device fabrication.
- CVD:Chemical vapor deposition variants serve niche silicon-germanium co-integration processes and compound semiconductor research applications.
MOCVD retains volume leadership; HVPE holds the steepest expansion trajectory.
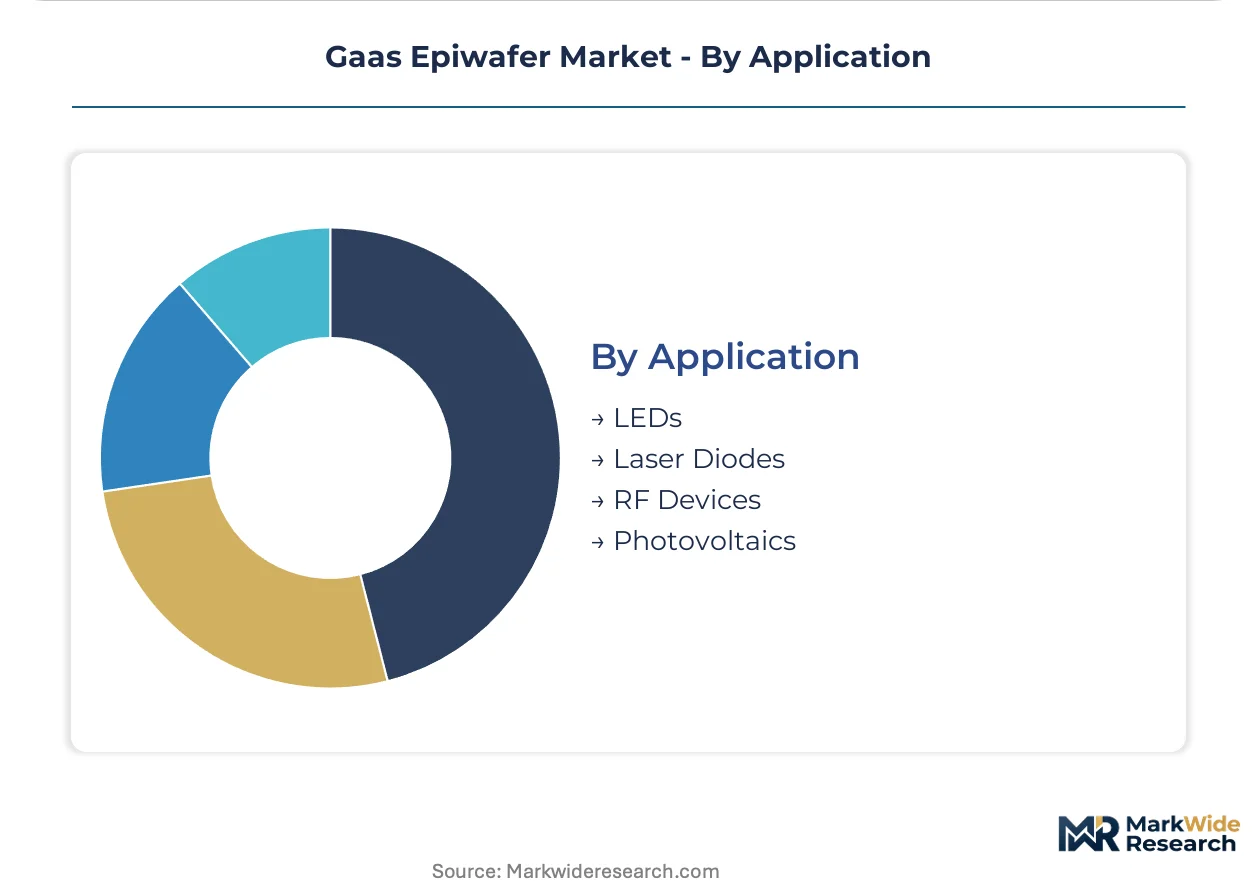
Application:
RF power amplifier specifications are tightening faster than LED or photovoltaic efficiency benchmarks, concentrating R&D investment in heterostructure bandgap engineering.
- RF Devices:Power amplifiers and low-noise amplifiers for cellular infrastructure and handsets command premium epiwafer pricing, with 5G base station deployment intensity in East Asian fabrication clusters synchronizing foundry output schedules.
- Laser Diodes:Edge-emitting and vertical-cavity surface-emitting lasers for data center interconnects and automotive LiDAR represent the fastest-expanding demand pool, with 400G and 800G optical links favoring 6-inch formats.
- LEDs:Infrared emitters for sensing and night-vision applications sustain steady demand, though visible LED migration to silicon substrates constrains GaAs volume growth.
- Photovoltaics:Triple-junction concentrator cells for space and terrestrial systems require specialized radiation-hardened epi-designs, with satellite constellation operators driving qualification of European supply alternatives.
RF Devices retain volume leadership; Laser Diodes gain share fastest as optical communications and LiDAR specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT substrate efficiency mandates and MEE dual carbon standards concentrate procurement leverage in Chinese fabrication clusters. Taiwan and South Korean foundries synchronize MOCVD reactor scheduling with telecommunications infrastructure rollouts.
China
Domestic LED packaging clusters in Xiamen and Shenzhen absorb expanding single-layer epiwafer capacity from merchant foundries. MEE efficiency benchmarks push substrate producers toward thicker epi-layers that cut thermal losses in high-frequency RF operation. Yangtze River Delta fabrication nodes in Shanghai and Suzhou coordinate trimethylgallium precursor logistics with Japanese specialty chemical suppliers.
Taiwan
Handset power amplifier designers compress 18-month heterostructure qualification cycles to match 5G-Advanced front-end module roadmaps. National Communications Commission spectrum assignments align with FCC mid-band allocations, extending addressable frequency ranges for GaAs heterostructures. Hsinchu Science Park anchors pure-play foundry services competing on yield rates and cycle-time compression.
South Korea
Samsung and LG smartphone OEMs specify 150mm epiwafers with 15-plus heterostructure layers for millimeter-wave power-added efficiency targets. Ministry of Trade, Industry and Energy strategic technology programs fund compound semiconductor process engineering talent development. Pangyo and Giheung semiconductor clusters concentrate MOCVD reactor fleets serving RF device exports.
United States
FCC spectrum allocation rules for 5G-Advanced directly shape epiwafer demand through frequency band assignments and device certification timelines. FDA oversight of medical laser systems constrains dopant selection in photonics-bound supply chains. Defense-qualified suppliers in Arizona and Texas manufacture pinned epiwafers with buried doping profiles for high-frequency RF switching applications.
Germany
REACH substance restrictions and ECHA candidate list updates force reformulation of selenium and tellurium precursor alternatives in MOCVD processes bound for European medical device markets. Freiburg anchors captive crystal growth and polishing capabilities securing continental supply security. Bavarian research institutions prototype custom-engineered layer stacks for satellite photovoltaic concentrator qualification.
Gaas Epiwafer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in GaAs epiwafer supply. Merchant epitaxy foundries with captive MOCVD reactor fleets compete against substrate producers with backward integration into crystal growth. Three archetypes dominate: pure-play epitaxy foundries, integrated substrate-to-epi manufacturers, and compound semiconductor device fabricators with captive epi capacity. Capacity expansion and strategic partnerships constitute the primary competitive moves, with foundries locking in take-or-pay contracts and substrate producers securing precursor chemical supply agreements.
Among integrated European suppliers, Freiberger Compound Materials occupies a position exemplifying captive crystal growth and polishing capabilities. Within the merchant foundry tier, IQE and WIN Semiconductors represent distinct archetypes—IQE anchoring high-mix production across RF and photonics applications, while WIN Semiconductors exemplifies pure-play GaAs foundry services competing on yield optimization. Sumitomo Electric Industries and DOWA Electronics Materials sit within the materials-integrated tier, leveraging precursor chemical and substrate supply chain proximity.
| Leading Market Players |
|---|
| Sumitomo Electric Industries |
| Freiberger Compound Materials |
| AXT |
| Xiamen Powerway Advanced Material |
| DOWA Electronics Materials |
| IQE |
| Vital Materials |
| China Crystal Technologies |
| WIN Semiconductors |
| Others |
Pricing and Supply Chain Analysis
SiGe BiCMOS substitution in sub-6GHz handset power amplifiers is simultaneously redrawing supply geography toward silicon foundry clusters in Taiwan and compressing pricing economics for commodity-grade single-layer GaAs epiwafers as Chinese merchant foundries expand 150mm capacity.
Pricing Analysis
Geographic price spreads between East Asian fabrication clusters and European supply nodes reflect divergent regulatory compliance burdens, with REACH-mandated precursor reformulations adding cost premiums to German-manufactured epiwafers. Three-tier pricing structure across AEC-Q101 automotive-qualified, defense-specification, and commercial-grade tiers separates premium multi-layer heterostructures from commoditized single-layer formats. Cost compression in commercial-grade tiers is intensifying because Chinese substrate producers are backward-integrating into merchant epitaxy capacity. Handset power amplifier designers in South Korea and Taiwan exhibit the lowest price sensitivity due to take-or-pay contract structures, while domestic LED packaging clusters in China drive the most aggressive procurement negotiations.
Supply Chain Analysis
Container availability constraints on transpacific trade lanes from Japanese specialty chemical ports to Yangtze River Delta fabrication nodes are elevating inbound logistics costs for trimethylgallium and arsine precursors. MOCVD reactor manufacturing concentrates in Japan, Germany, and the United States, while merchant epitaxy production clusters in Taiwan, South Korea, and China. Raw material dependencies rest on high-purity gallium metal from Chinese smelters, arsine gas from Japanese chemical producers, and aluminum alkyl precursors from German specialty chemical suppliers. Single-source vulnerability in Japanese trimethylgallium supply exposes East Asian foundries to geopolitical disruption risk. Distribution runs through direct vendor-managed inventory arrangements with Tier-1 RF device OEMs, supplemented by spot procurement for research-scale volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
5G-Advanced spectrum allocations and automotive LiDAR integration are accelerating this market through a technology inflection that rewards reactor utilization rates and heterostructure qualification speed.
For Market Incumbents: Consolidate reactor capacity through multi-year take-or-pay contracts with handset power amplifier designers in Taiwan and South Korea, locking in utilization before SiGe BiCMOS captures additional sub-6GHz share. Deepen backward integration into captive crystal growth and polishing capabilities to secure supply continuity against precursor chemical export control risks. Prioritize MOCVD equipment architectures with faster temperature ramp rates to compress cycle times for 15-plus layer heterostructures. For New Entrants and Emerging Players: Differentiate on REACH-compliant process qualifications for European medical laser and automotive LiDAR markets where incumbent supply chains face ECHA-mandated reformulation timelines. Target satellite constellation operators specifying radiation-hardened triple-junction photovoltaic structures, a segment with captive epitaxy requirements that limit merchant competition. Pursue qualification partnerships with Bavarian research institutions prototyping custom layer stacks for space applications. For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors pure-play epitaxy foundries with installed MOCVD reactor fleets and established handset OEM relationships. Long-term viability across the projection horizon rests on securing compound semiconductor process engineering talent pools concentrated in Taiwan and South Korea. Monitor FCC mid-band spectrum assignment timelines as the critical inflection indicator for GaAs heterostructure demand against silicon alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Multi-wafer MOCVD reactor installations in Taiwan and South Korea secure reactor utilization for 5G-Advanced handset power amplifier procurement cycles. |
| Backward Integration | Captive crystal growth and polishing capabilities in Germany reduce dependence on East Asian substrate supply nodes under REACH substance restrictions. |
| Long-term Supply Agreement | Take-or-pay contracts with Japanese trimethylgallium producers lock in precursor chemical access against export control escalation risks. |
| Joint Venture | Partnerships between European epiwafer suppliers and satellite constellation operators accelerate radiation-hardened triple-junction qualification timelines. |
| Geographic Expansion | Merchant foundry capacity additions in China serve domestic LED packaging clusters while pressuring pricing in commodity single-layer tiers. |
Research Methodology
Desk research of SEC filings from compound semiconductor equipment manufacturers, customs data on trimethylgallium trade flows, and FCC spectrum allocation dockets preceded structured interviews with epitaxy process engineers, RF device procurement managers, MOCVD equipment sales directors, and automotive LiDAR module integrators. Primary fieldwork with stakeholders in Taiwan, South Korea, Germany, and the United States combined with secondary validation against MIIT efficiency standard disclosures and ECHA candidate list updates. Bottom-up epiwafer volume estimates by deposition technology and top-down RF device market sizing were triangulated to derive segment-level projections.
Variance decomposition across product type, end user, deposition technology, and application dimensions anchored the analytical framework over the projection horizon. Modeled segmentation captured heterostructure complexity tiers, substrate diameter formats, geographic fabrication clusters, and certification grade requirements. CAGRs were computed from annual volume trajectories incorporating 5G base station deployment schedules, automotive LiDAR penetration curves, and satellite constellation launch manifests as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained telecommunications infrastructure investment and stable precursor chemical trade flows; material deviation in FCC spectrum timing or Japanese export controls would warrant model refresh. Practitioners should keep alternative scenarios live as geopolitical fragmentation of epitaxial tool sourcing and REACH substance restriction timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
China Optical Detector Market
Optoelectronics
Gallium Arsenide Gaas Wafer Market
Optoelectronics
Optocoupler IC Market
Optoelectronics
Optoelectronics Market
Optoelectronics
3D Projector Market
Optoelectronics
Integrated Circuit Optocouplers Market
Optoelectronics
Thermophotovoltaics Market
Optoelectronics
Japan Optoelectronics Market
Optoelectronics
Asia-Pacific Optoelectronics Market
Optoelectronics
China Optoelectronics Market
Optoelectronics
Infrared Emitter and Receiver Market
Optoelectronics
Quantum Dot Solar Cell Market
Optoelectronics
Electro-Optical/Infrared (EO/IR) Systems Market
Optoelectronics
Laser Projector Market
Optoelectronics
Optical Pulse Sensor Market
Optoelectronics
Global Shortwave Infrared (SWIR) Market