
 Opto-Electronics Device Market | 2026-2036
Opto-Electronics Device Market Size, Share, and Industry Trends Forecast 2026-2036
Opto-Electronics Device Market Insights
Buyer concentration among telecommunications OEMs is repositioning procurement leverage across the opto-electronics supply chain. Samsung Electronics leverages vertical integration across LED and laser diode fabrication to control cost structures. Sony Corporation anchors premium image sensor supply for automotive and medical imaging customers. Hamamatsu Photonics specializes in photodetector architectures for scientific instrumentation, competing on precision rather than volume scale.
Opto-electronics devices convert electrical signals to light and vice versa through semiconductor junctions, typically operating across ultraviolet to infrared wavelengths with response times measured in nanoseconds, serving as the functional backbone of data transmission, sensing, and display systems. Silicon photonics is displacing legacy fiber optic assemblies in data center interconnects due to co-packaging advantages with CMOS electronics. Photodetectors and optical sensors are capturing margin pools in medical device and automotive safety applications where certification barriers limit supplier entry.
FCC equipment authorization rules govern opto-electronic transmitter deployment in US telecommunications infrastructure, while ECHA REACH restrictions on cadmium and lead content reshape phosphor and quantum dot formulations across European supply chains. Japan's METI energy efficiency standards for displays redirect LED manufacturer R&D toward lower-power architectures. Stakeholders must monitor divergence between regional material compliance regimes and silicon photonics packaging roadmaps to avoid stranded component investments.
Market Dynamics
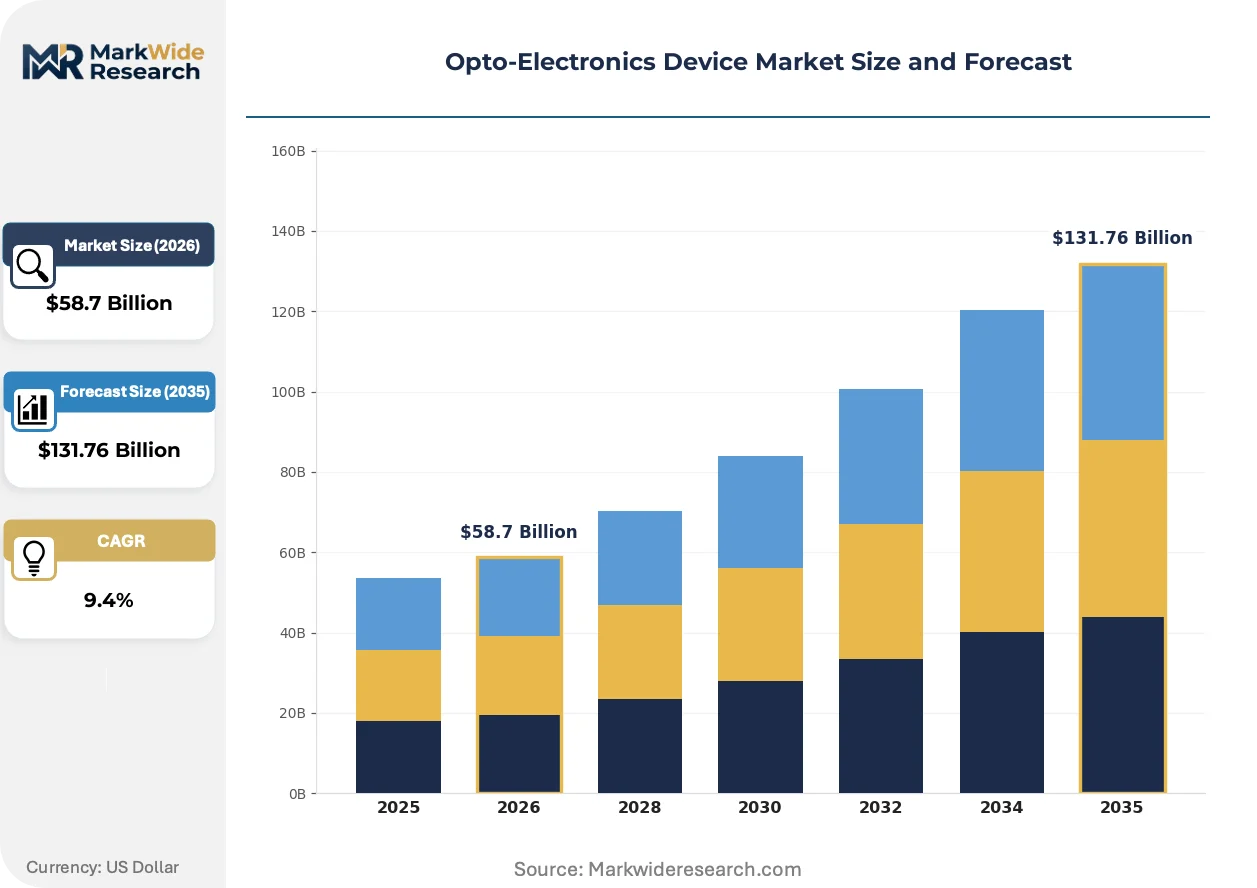
Silicon photonics integration with CMOS electronics is restructuring component procurement across telecommunications and data center supply chains, compressing legacy fiber optic assembly margins while concentrating fabrication capacity among semiconductor foundries with advanced packaging capabilities.
Growth Catalysts
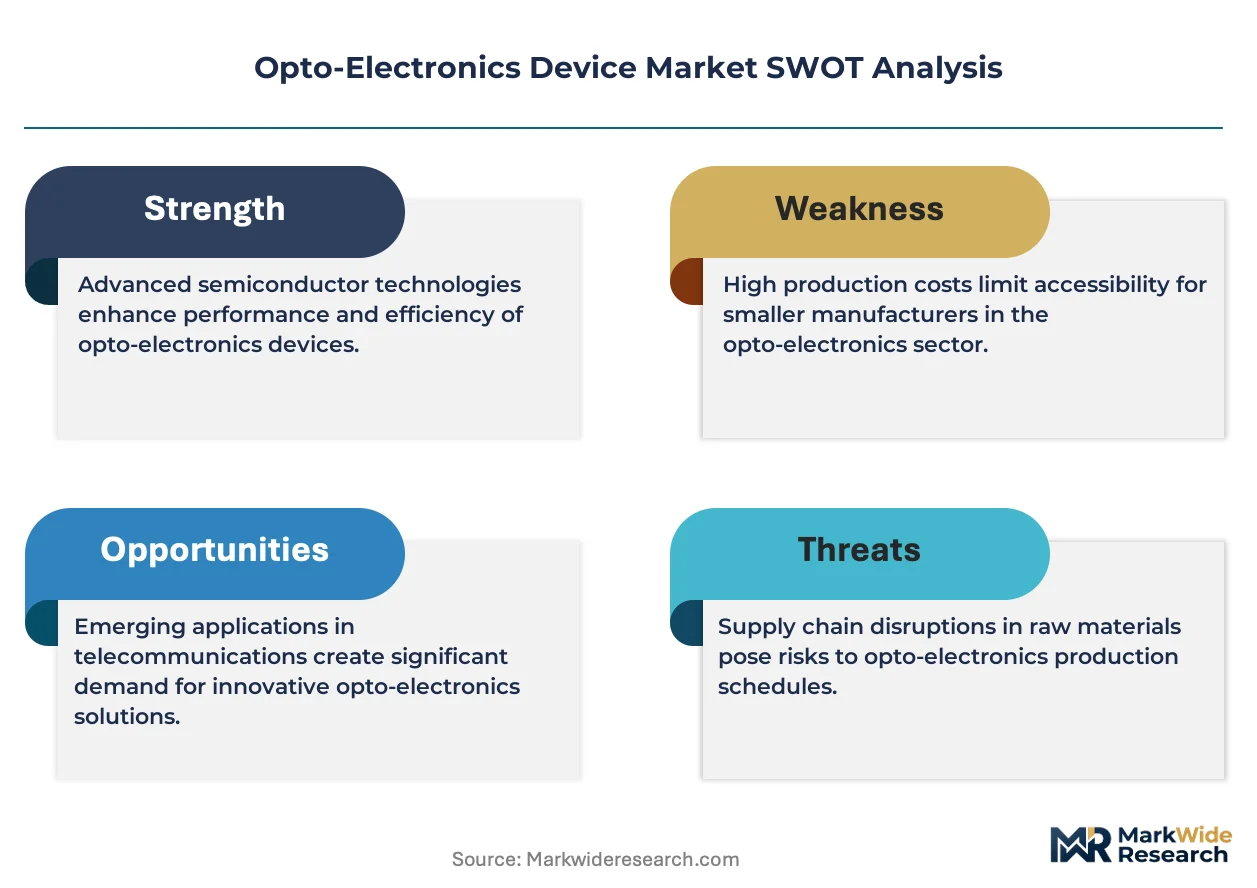
- ECHA REACH substance restrictions:RoHS and REACH compliance mandates in Europe are accelerating phosphor reformulation R&D, opening substitution opportunities for quantum dot and perovskite emitters in display applications.
- Data center interconnect buildouts:Hyperscale cloud operators are expanding co-packaged photonic-electronic module deployment, pulling demand for high-speed lasers and photodetectors at 800G and 1.6T speeds.
- Automotive LiDAR sensor proliferation:Safety mandates for advanced driver-assistance systems in China, Japan, and Germany are scaling VCSEL and SPAD array orders from tier-one automotive suppliers.
Market Restraints
- Indium phosphide substrate scarcity:Limited wafer supply from specialized foundries constrains laser diode output for telecom and sensing applications, amplifying price volatility for 1550nm sources.
- Compound semiconductor equipment costs:MOCVD reactor capex and cleanroom requirements create barriers for new entrants in LED and laser fabrication, entrenching incumbent capacity control.
- Silicon photonics yield challenges:Hybrid integration of III-V materials onto silicon platforms suffers from thermal expansion mismatch defects, limiting volume economics for mainstream adoption.
Strategic Opportunities
- India PLI scheme for electronics:Production-linked incentives for semiconductor and display manufacturing are attracting LED packaging and module assembly investments to offset China concentration.
- Medical imaging photodetector demand:PET-MRI fusion systems and fluorescence-guided surgery equipment require low-noise avalanche photodiodes, creating premium margin pools outside commodity telecom markets.
- Co-packaged optics standardization:OIF and IEEE interoperability frameworks are enabling multi-sourcing of chiplets and optical engines, reducing single-supplier dependency for cloud operators.
Industry Challenges
- Photonics packaging engineer scarcity:Specialized expertise in fiber attach, lens alignment, and hermetic sealing exceeds current vocational pipeline output, inflating labor costs for precision assembly operations.
- Telecom equipment authorization timelines:FCC Part 15 and Part 68 certification procedures for optical transmitters impose six-to-nine month delays, compressing product launch windows against competitive pressure.
- Legacy SONET/SDH system integration:Incumbent telecom operators require backward-compatible opto-electronic interfaces, forcing dual-mode product architectures that dilute R&D efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Opto-Electronics Device Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $131.76 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LEDs, Laser Diodes, Photodetectors, Optical Sensors Technology: Fiber Optics, Quantum Dots, Organic Electronics, Silicon Photonics Application: Telecommunications, Consumer Electronics, Medical Devices, Automotive Lighting End User: OEMs, Research Institutes, Healthcare Providers, Industrial Manufacturers |
| Companies Covered | Samsung Electronics, Sony Corporation, Osram, Vishay Intertechnology, Panasonic Corporation, Mitsubishi Electric, Hamamatsu Photonics, OmniVision Technologies, ROHM Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Opto-Electronics Device Market Trends and Innovations
Three intersecting developments are restructuring how opto-electronic components are designed, validated, and procured: materials science breakthroughs, regulatory substance bans, and buyer consolidation in downstream equipment markets.
Thin-film lithium niobate modulators are electrifying high-speed optical communication by enabling voltage-efficient electro-optic conversion at 100 GHz bandwidth. Cloud data center operators are qualifying these devices for 1.6 Tbps coherent transceivers ahead of 2025 deployment timelines. The technology is electrifying competitive positioning by rewarding foundries with specialized thin-film processing capabilities over legacy indium phosphide suppliers.
ECHA REACH Annex XVII restrictions on cadmium and lead content are forcing reformulation of quantum dot phosphors for display backlighting and color conversion applications. European display manufacturers are accelerating perovskite and indium phosphide alternative development to maintain CE marking eligibility. Medical imaging and professional monitor segments face the steepest compliance cost curves due to stringent color gamut requirements that cadmium-based materials previously satisfied.
Hyperscale cloud buyers are consolidating optical transceiver procurement through direct foundry relationships, bypassing traditional module vendors. Amazon Web Services, Microsoft Azure, and Google Cloud are issuing joint specifications for co-packaged optical engines, compressing supplier margins through volume concentration. This pattern is most visible in North American and East Asian data center clusters where single-site deployments exceed 100,000 ports annually.
Opto-Electronics Device Market Segmentation
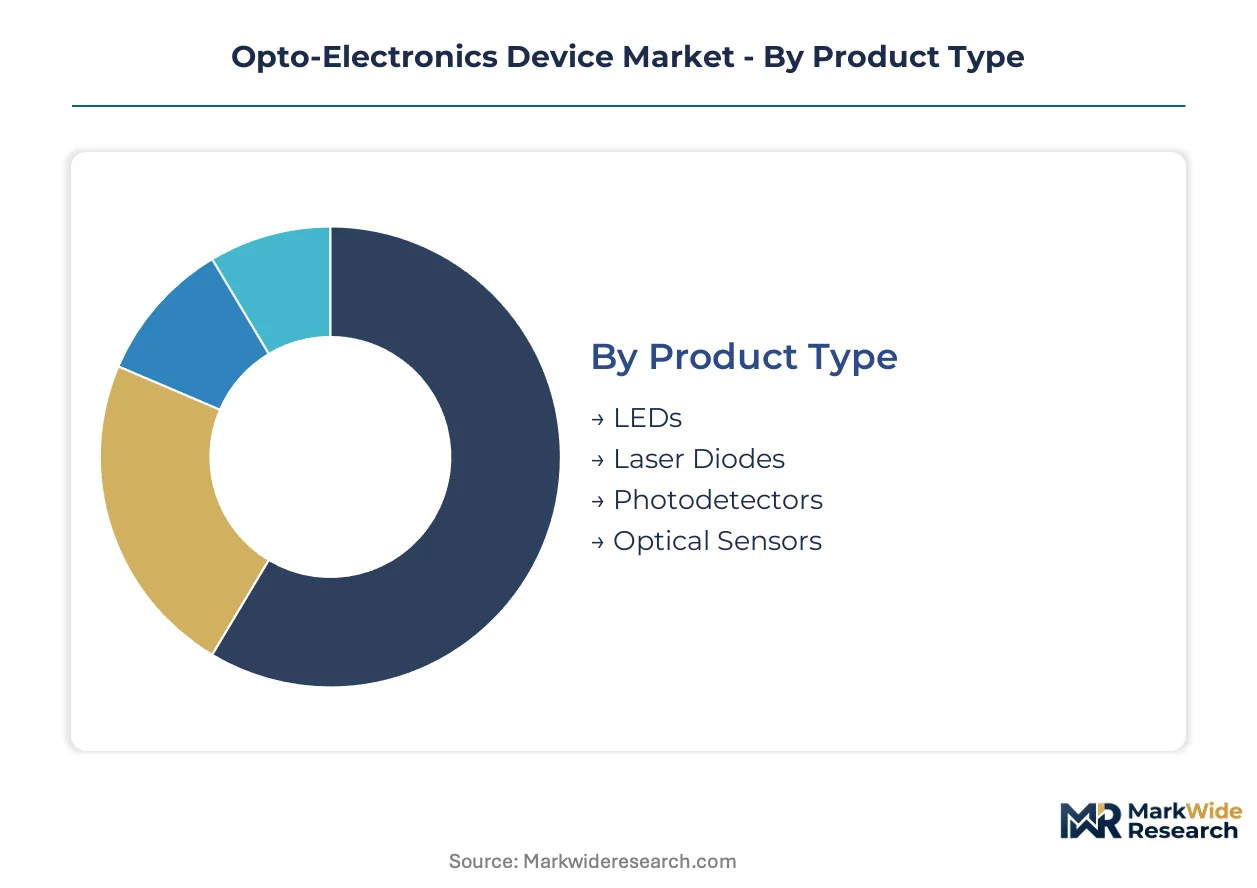
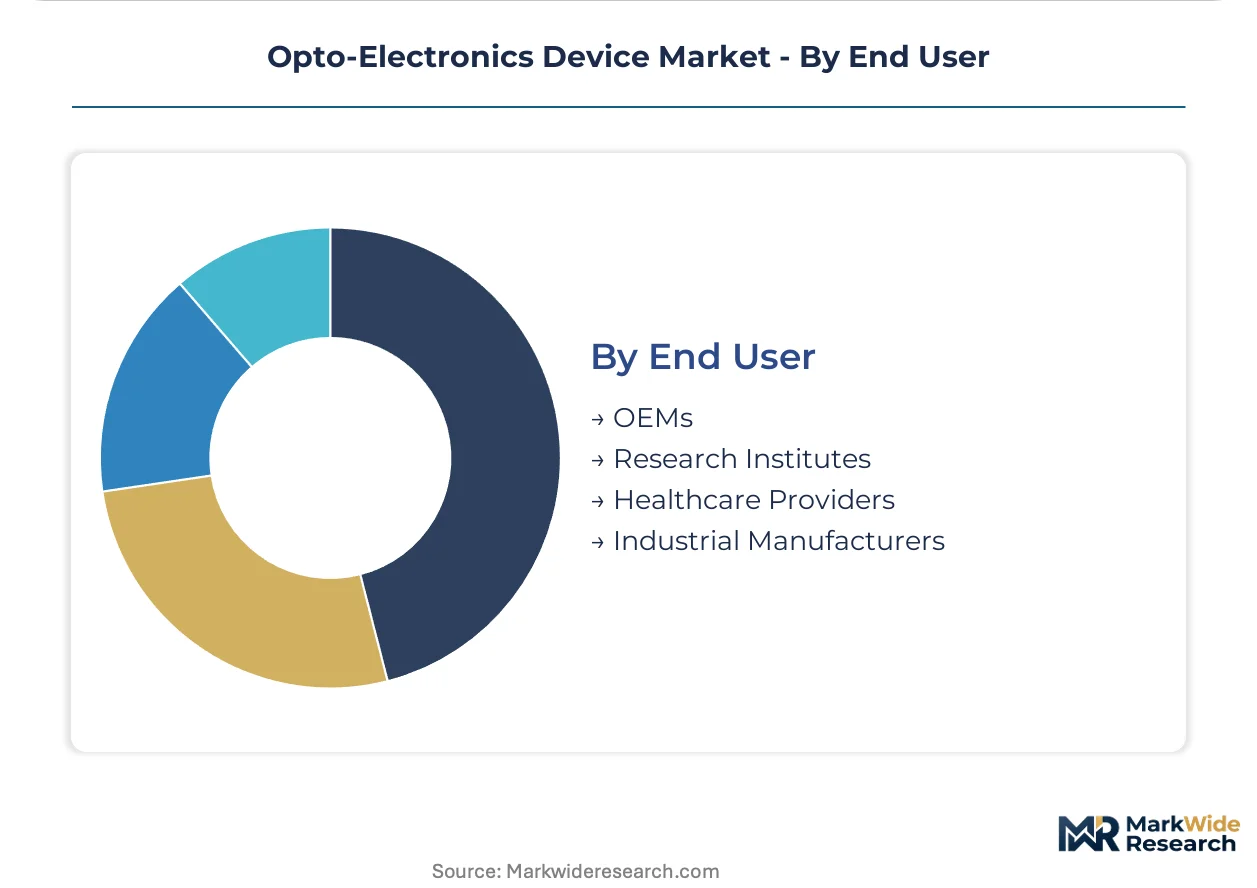
Opto-electronics procurement patterns diverge sharply across product architectures and buyer types. Upgrade cycles in telecommunications infrastructure and automotive sensing platforms reshape component demand trajectories differently for each segment cluster.
Product Type:
Replacement timelines in display backlighting and data center interconnects drive divergent volume patterns across component categories.
- LEDs:Solid-state emitters constructed from gallium nitride or indium gallium nitride epitaxial layers on sapphire or silicon carbide substrates. Display manufacturers in China and South Korea dominate procurement for backlighting and direct-view applications, with automotive interior lighting pulling premium high-brightness variants.
- Laser Diodes:Stimulated emission devices operating at 850nm, 1310nm, or 1550nm wavelengths for optical communication and sensing. Telecommunications OEMs concentrate orders for distributed feedback and vertical-cavity surface-emitting architectures, constrained by indium phosphide wafer availability.
- Photodetectors:Semiconductor junction devices converting photons to electrical signals through photovoltaic or photoconductive mechanisms.
- Optical Sensors:Integrated detection modules combining photodiodes with signal conditioning electronics for proximity, ambient light, and gesture recognition functions.
LEDs sit at the top of the volume ranking, with laser diodes climbing the fastest.
Technology:
Cost tiers separate legacy fiber assemblies from emerging integrated photonic platforms.
- Fiber Optics:Glass or plastic waveguides transmitting modulated light across telecommunications and sensing networks. Incumbent telecom operators in Germany and Japan maintain installed bases of single-mode and multimode cabling, though silicon photonics erodes transceiver attachment demand.
- Silicon Photonics:CMOS-compatible optical components fabricated on silicon-on-insulator wafers enabling co-packaged electronic-photonic integration. Hyperscale cloud operators in the United States and China qualify these devices for 800G and 1.6T data center interconnects, displacing discrete optical assemblies.
- Quantum Dots:Nanoscale semiconductor crystals exhibiting size-tunable emission spectra for display color conversion.
- Organic Electronics:Carbon-based opto-electronic materials including OLED emitters and organic photodetectors.
Fiber optics commands the largest installed base, while silicon photonics gains share fastest.
Application:
Margin structures diverge between regulated medical certification and volume consumer electronics.
- Telecommunications:Optical transmission and reception equipment for long-haul, metro, and access networks. Equipment vendors in Japan and Finland concentrate procurement of coherent transceivers and passive optical network components, driven by 5G fronthaul and fiber-to-the-home deployment.
- Medical Devices:Diagnostic and therapeutic equipment incorporating optical coherence tomography, fluorescence imaging, and laser surgery systems. Healthcare providers in Switzerland and the United States demand avalanche photodiodes and superluminescent diodes meeting FDA and Swissmedic biocompatibility requirements.
- Consumer Electronics:Smartphones, tablets, and wearables integrating ambient light sensors, proximity detectors, and camera modules.
- Automotive Lighting:Exterior illumination and interior ambiance systems utilizing LED and laser sources.
Telecommunications generates the highest component volume, with medical devices expanding most quickly.
End User:
Customer type dictates procurement sophistication and contract structures.
- OEMs:Original equipment manufacturers integrating opto-electronic subsystems into finished products. Samsung Electronics and Sony Corporation negotiate multi-year supply agreements for image sensors and display backlights, leveraging forecast visibility against price volatility.
- Industrial Manufacturers:Factory automation and process control system builders. Machine vision integrators in Germany and the United States source structured light projectors and line scan cameras for quality inspection lines.
- Research Institutes:Academic and government laboratories requiring custom photodetector arrays and laser sources.
- Healthcare Providers:Hospital systems and diagnostic imaging centers purchasing endoscopic and surgical visualization equipment.
OEMs dominate procurement volume, with healthcare providers showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the dominant manufacturing footprint for opto-electronics components, while Japan maintains premium positioning in specialized photodetector architectures. Germany anchors European demand through automotive LiDAR and industrial automation procurement. South Korea and the United States split leadership in display technology and data center interconnects respectively.
China
Telecommunications infrastructure buildouts and display panel manufacturing concentrate component demand in Shenzhen and Suzhou industrial clusters. MIIT broadband expansion targets and dual carbon goals redirect LED manufacturer R&D toward energy-efficient architectures. Yangtze River Delta fabs scale silicon photonics packaging for hyperscale cloud operators.
Japan
Automotive safety mandates and medical imaging equipment drive photodetector and laser diode procurement from Nagoya and Osaka manufacturing centers. METI energy efficiency standards for displays force lower-power LED development trajectories. Hamamatsu anchors precision photodetector supply for scientific instrumentation customers.
Germany
Industrial automation and automotive LiDAR sensor demand pull VCSEL and SPAD array orders through Munich and Stuttgart supplier networks. ECHA REACH substance restrictions on cadmium and lead reshape quantum dot phosphor formulations for display applications. Bavarian machine vision integrators source structured light projectors for quality inspection lines.
South Korea
Samsung Electronics leverages captive LED and laser diode fabrication across Gyeonggi-do and Chungcheongnam-do complexes to control cost structures. Display manufacturing clusters in Suwon and Asan concentrate backlighting component procurement. Government semiconductor support programs attract co-packaged optics packaging investments.
United States
Hyperscale cloud operators in Northern Virginia and Oregon data center clusters qualify silicon photonics devices for 800G and 1.6T interconnect speeds. FCC equipment authorization rules govern optical transmitter deployment timelines. Greater Boston and Bay Area photonics startups target thin-film lithium niobate modulator commercialization.
Opto-Electronics Device Market Competitive Landscape
East Asian producers anchor the volume tier through integrated fabrication complexes; European and North American specialists hold premium positioning in precision instrumentation and custom photodetector architectures. Market structure concentrates among semiconductor conglomerates with compound semiconductor foundry capabilities, mid-scale photonics module assemblers, and niche scientific instrument suppliers. Dominant competitive moves include foundry partnerships for silicon photonics packaging capacity and backward integration into III-V epitaxial wafer supply.
Among the diversified electronics conglomerates, Samsung Electronics and Sony Corporation occupy positions spanning LED fabrication through image sensor supply, while Hamamatsu Photonics exemplifies the precision-tier archetype focused on scientific and medical instrumentation applications. These three entities represent contrasting strategic postures: captive vertical manufacturing, premium sensor specialization, and precision photodetector engineering respectively.
| Leading Market Players |
|---|
| Samsung Electronics |
| Sony Corporation |
| Osram |
| Vishay Intertechnology |
| Panasonic Corporation |
| Mitsubishi Electric |
| Hamamatsu Photonics |
| OmniVision Technologies |
| ROHM Semiconductor |
| Others |
Pricing and Supply Chain Analysis
Performance divergence between telecom-grade laser diodes and commodity LED backlights manifests in both pricing stratification and supply chain configurations, with indium phosphide wafer scarcity anchoring premium tier premiums while gallium nitride epitaxy oversupply compresses display component margins across Chinese manufacturing clusters.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard LED packages even as indium phosphide substrate scarcity elevates 1550nm laser diode premiums. Three-tier pricing structure across precision photodetectors, industrial-grade sensors, and commodity emitters separates certification-grade medical components from automotive and consumer variants. Pricing pressure stems from hyperscale cloud buyers consolidating optical transceiver procurement through direct foundry relationships. Telecommunications OEMs exhibit lowest price sensitivity due to network reliability requirements, while display manufacturers negotiate aggressively on volume backlighting contracts.
Supply Chain Analysis
Photonics packaging engineer scarcity in Japan and Germany constrains precision assembly capacity despite equipment availability. Manufacturing concentrates in China, Japan, and South Korea, with compound semiconductor fabrication drawing from indium phosphide substrates, gallium nitride epitaxial wafers, and specialized MOCVD equipment. Single-source vulnerability characterizes indium phosphide wafer supply from specialized foundries. Distribution runs through tier-one module assemblers serving telecommunications OEMs and hyperscale cloud operators directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between European REACH compliance costs and Asian manufacturing scale, with ECHA substance restrictions creating 15-20% cost differentials on quantum dot phosphors that repositionable suppliers can exploit through reformulation investments in China or South Korea.
For Market Incumbents: Cement silicon photonics packaging capabilities through foundry partnerships in Taiwan and the United States before hyperscale cloud buyers consolidate procurement further. Defend against thin-film lithium niobate modulator substitution by accelerating coherent transceiver integration roadmaps. Prioritize backward integration into III-V epitaxial wafer supply to secure indium phosphide substrate access against foundry allocation constraints. For New Entrants and Emerging Players: Capture medical imaging photodetector segments where FDA and Swissmedic certification barriers limit incumbent expansion and premium margins exceed commodity telecom markets by substantial multiples. Target India's PLI scheme for LED packaging investments to offset China concentration risk. Pursue co-packaged optics standardization through OIF framework participation as a qualification shortcut for cloud operator supply lists. For Investors and Strategic Acquirers: Consolidation pressure builds where silicon photonics yield challenges strand mid-scale module assemblers without advanced packaging partnerships. Frame long-term viability around captive III-V material supply or specialized thin-film processing capabilities that hyperscale buyers cannot internalize. Target acquisition candidates with photonics packaging engineering depth in Japan or Germany. Monitor hyperscale cloud operator direct foundry relationship announcements as inflection indicators for traditional module vendor margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Foundry Partnership | Secures co-packaged optics capacity for 800G and 1.6T transceiver qualification at hyperscale cloud operators. |
| Perovskite Phosphor Reformulation | Maintains CE marking eligibility under ECHA REACH cadmium restrictions for European display manufacturers. |
| III-V Epitaxial Wafer Backward Integration | Reduces indium phosphide substrate dependency amid specialized foundry allocation constraints. |
| Medical Device Certification Investment | Opens premium avalanche photodiode margins in PET-MRI and fluorescence-guided surgery equipment. |
| India PLI Scheme Manufacturing Entry | Diversifies LED packaging footprint away from China concentration through production-linked incentives. |
Research Methodology
Bottom-up telecommunications and data center interconnect modeling reconciled against top-down compound semiconductor foundry output tracking forms the analytical core of this study. Primary interviews with optical transceiver procurement managers at hyperscale cloud operators, photonics packaging engineers at tier-one assemblers, and regulatory affairs specialists at display manufacturers combined with secondary validation from SEC filings, MIIT broadband deployment disclosures, and ECHA substance restriction updates. Triangulation against customs data for indium phosphide substrate imports and LED export volumes from Chinese manufacturing clusters reinforced volume estimates.
Input-output matrices map laser diode, photodetector, and LED unit volumes to downstream application demand across telecommunications infrastructure, automotive LiDAR, medical imaging, and consumer electronics segments. Modeled dimensions include product architecture, technology platform, application vertical, and end-user procurement sophistication. CAGRs derive from segment-level demand elasticity analysis and supply-side capacity expansion schedules. Forecast inputs incorporate MIIT dual carbon targets, METI display efficiency standards, and hyperscale cloud operator capex disclosure patterns across the projection horizon.
Underlying measurement precision varies by segment; silicon photonics and medical imaging photodetectors carry tighter precision than commodity LED backlighting due to concentrated buyer disclosure. Forecasts reflect assumptions about indium phosphide wafer supply continuity, ECHA REACH enforcement timelines, and hyperscale cloud operator co-packaged optics adoption curves. Practitioners should monitor FCC equipment authorization backlog durations and thin-film lithium niobate modulator qualification announcements at major cloud operators for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Laser Projector Market
Optoelectronics
Optical Pulse Sensor Market
Optoelectronics
Gunn Diode Market
Optoelectronics
Optoelectronic Development Tools Market
Optoelectronics
Global Indium Phosphide (Inp) Wafers Market
Optoelectronics
Laser Diode Market
Optoelectronics
Global Shortwave Infrared (SWIR) Market
Optoelectronics
Infrared Emitter and Receiver Market
Optoelectronics
Quantum Cascade Lasers Market
Optoelectronics
Electro-Optical/Infrared (EO/IR) Systems Market
Optoelectronics
Optical Emission Spectroscopy Market
Optoelectronics
Americas Optoelectronics Market
Optoelectronics
Quantum Dot Lasers Market
Optoelectronics
China Optoelectronics Market
Optoelectronics
Photoluminescent Film Market
Optoelectronics
Japan Optoelectronics Market