
 Mid-Infrared Laser Market | 2026-2036
Mid-Infrared Laser Market Size, Share, and Industry Trends Forecast 2026-2036
Mid-Infrared Laser Market Analysis
Asset-light leasing models for high-power laser systems is rewriting capital deployment across the competitive landscape. IPG Photonics Corporation leverages captive chip fabrication to sustain margin control over fiber laser cores. Hamamatsu Photonics K.K. anchors its position through vertical integration of crystal growth and optical coating capabilities. Thorlabs competes by specializing in compact, turnkey mid-infrared sources for research laboratories.
Mid-infrared lasers emit electromagnetic radiation in the 2–20 μm wavelength band, typically generated through quantum cascade, solid-state, or fiber-based gain media, and serve primarily to enable molecular fingerprinting for chemical sensing and precision material ablation. Fiber lasers command the largest installed base due to superior thermal management and beam quality in industrial cutting environments, while quantum cascade semiconductor lasers represent the fastest-expanding category as spectroscopy applications multiply in environmental monitoring. Solid-state systems retain premium pricing in medical applications where pulse stability governs tissue interaction outcomes.
FDA laser product performance standards and the EU Medical Device Regulation shape certification pathways for surgical and diagnostic equipment, directly influencing product development timelines and market access costs. Japan's METI enforces JIS standards for industrial laser safety that constrain system design parameters for manufacturing exports. Stakeholders must monitor evolving REACH restrictions on rare-earth dopants and gallium arsenide substrates that could disrupt supply continuity for critical gain media.
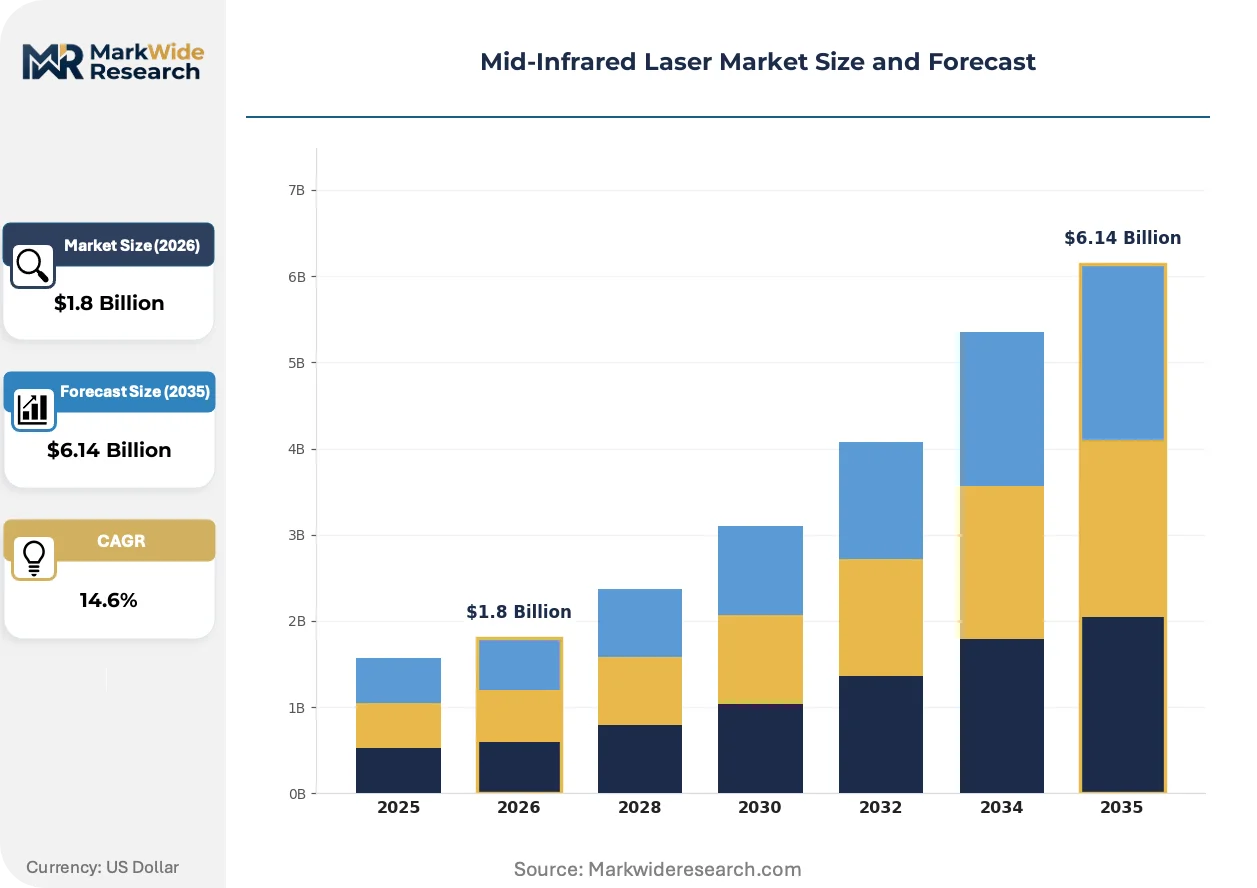
Market Dynamics
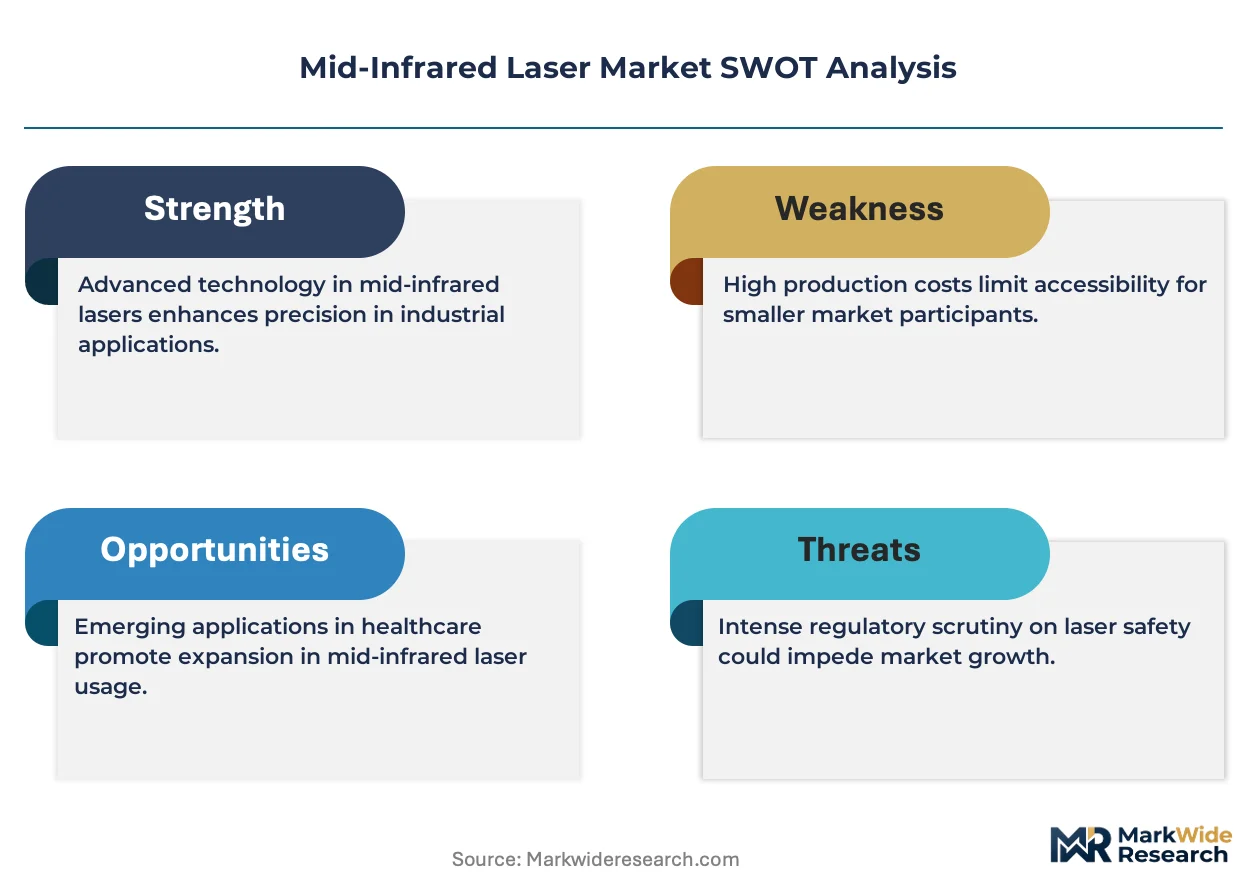
The mid-infrared laser market is being fundamentally restructured by the convergence of tightened surgical safety classifications and the shift toward solid-state architectures in medical device manufacturing. This dual pressure is compressing product development cycles while elevating capital requirements for certification compliance.
Growth Catalysts
- FDA laser safety reclassifications:Tightened performance standards for surgical equipment are accelerating investments in pulse-stabilized solid-state systems that meet tissue interaction protocols.
- METI-backed photonics clusters:Japan's Ministry of Economy, Trade and Industry is channeling public-private funding into fiber laser adoption for sub-micron precision manufacturing in automotive and electronics sectors.
- Quantum cascade semiconductor advances:Spectroscopy applications for environmental methane detection are expanding deployment of compact, tunable sources in remote sensing networks.
Market Restraints
- Rare-earth dopant supply concentration:Erbium and thulium sourcing depends on concentrated refining capacity in China, exposing fiber laser manufacturers to export restriction risk under evolving trade frameworks.
- Gallium arsenide substrate limitations:REACH restrictions on arsenic compounds are constraining quantum cascade laser fabrication, forcing substrate redesigns that extend qualification timelines.
- Medical certification cost structure:EU Medical Device Regulation conformity assessment expenses for surgical laser systems now exceed development budgets for mid-tier manufacturers.
Strategic Opportunities
- Minimally invasive surgical tool integration:German medical device manufacturers are scaling procurement of solid-state mid-infrared sources for next-generation laparoscopic and robotic platforms.
- Environmental monitoring mandates:EPA methane emissions regulations are creating installed base expansion for portable spectroscopy systems in oil and gas infrastructure inspection.
- Asset-light leasing models:High-power system financing through equipment-as-a-service contracts is unlocking capital-constrained research laboratories and small-batch manufacturers.
Industry Challenges
- Specialized optical engineering talent scarcity:Crystal growth, coating, and beam delivery design expertise is concentrated among legacy specialists, constraining workforce expansion for scaling manufacturers.
- Multi-jurisdiction certification complexity:Simultaneous FDA, CE marking, and PMDA submissions for surgical equipment require redundant testing protocols that fragment R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mid-Infrared Laser Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid-State Lasers, Fiber Lasers, Semiconductor Lasers, Gas Lasers Application: Material Processing, Medical Applications, Environmental Monitoring, Spectroscopy End User: Healthcare, Manufacturing, Research Institutions, Aerospace Technology: Continuous Wave, Pulsed Technology, Mode-Locked Lasers, Q-Switched Lasers |
| Companies Covered | Leonardo DRS, Inc., IPG Photonics Corporation, TRUMPF SE + Co. KG, Coherent, Inc., Thermo Fisher Scientific, Inc., Hamamatsu Photonics K.K., Thorlabs, MKS Instruments, Lumentum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mid-Infrared Laser Market Emerging Trajectories
Technology migration and regulatory recalibration are actively compressing traditional competitive moats in mid-infrared laser supply. Manufacturers must now synchronize hardware roadmaps with evolving safety frameworks across multiple jurisdictions.
Quantum cascade laser technology is migrating from benchtop laboratory configurations toward field-deployable environmental sensing platforms. Water utilities and pipeline operators are adopting portable methane detection systems at accelerating pace. This migration is collapsing the historical boundary between research-grade and industrial-grade source specifications, forcing component suppliers to dual-qualify product lines.
EU Medical Device Regulation enforcement is extending pre-market clinical evidence requirements to diagnostic laser equipment previously exempt under legacy directives. Surgical and dermatological device manufacturers now face biocompatibility testing expansions that add twelve to eighteen months to registration timelines. German and Swiss precision engineering clusters are responding by consolidating regulatory affairs functions across portfolio companies.
Research laboratory procurement is fragmenting from bundled system sales toward modular source-and-optics configurations. Universities and national laboratories are unbundling beam delivery and detection components, sourcing discrete mid-infrared emitters through specialized distributors. This pattern is most pronounced in Japan and Germany, where institutional buyers prioritize interoperability over turnkey integration.
Mid-Infrared Laser Market Segmentation
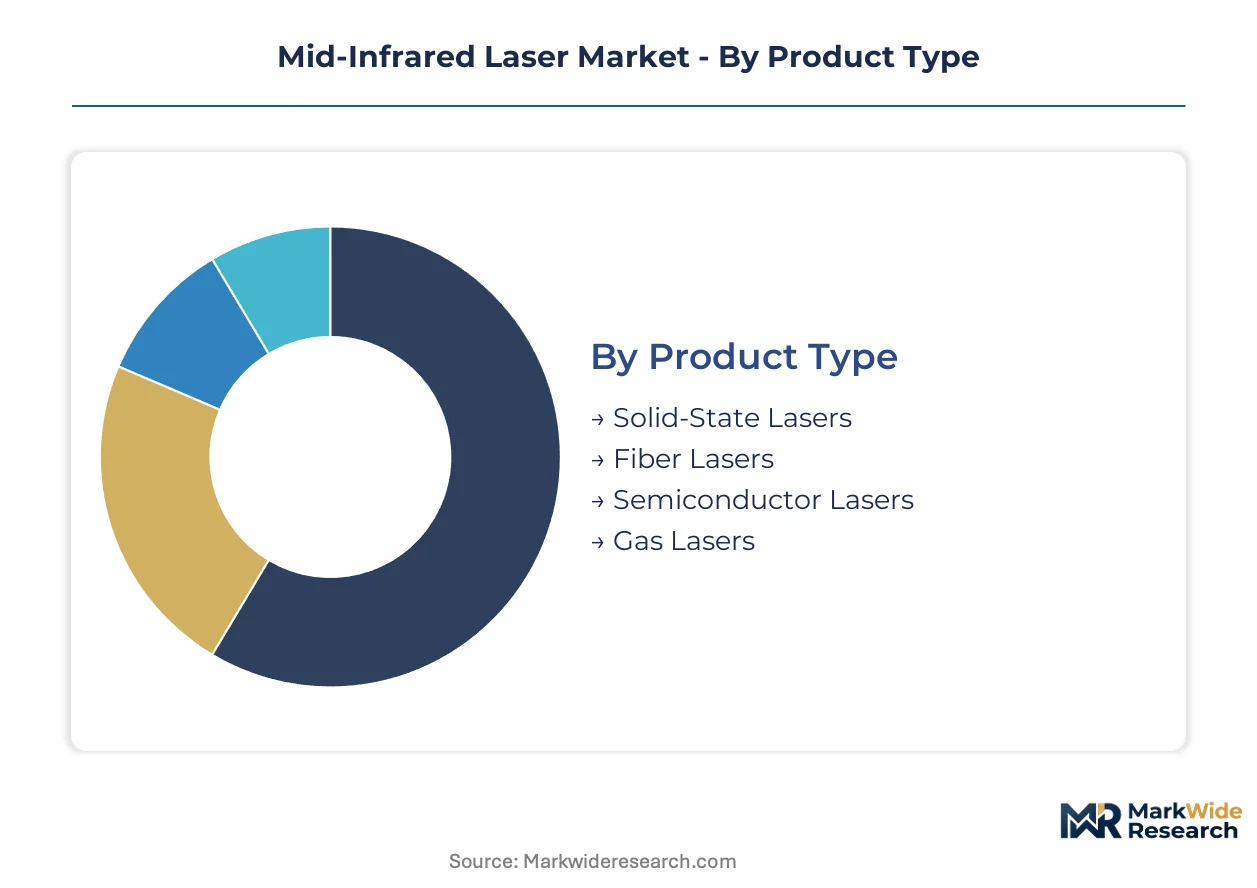
Mid-infrared laser procurement patterns diverge sharply across product architectures and end-use requirements. Understanding these fault lines clarifies where capital concentrates and which specifications command pricing premiums.
Product Type:
Replacement cycles stretch from under three years for semiconductor modules to over seven years for solid-state installations, compressing or extending revenue recognition timelines accordingly.
- Fiber Lasers:These systems leverage erbium or thulium dopants in silica fiber gain media to deliver superior thermal management and beam quality for industrial cutting environments. German automotive suppliers and Japanese electronics manufacturers deploy fiber architectures for sub-micron precision manufacturing, though rare-earth supply concentration in China introduces procurement risk under evolving export frameworks.
- Solid-State Lasers:Crystal-based gain media—typically doped with transition metal ions—generate high pulse stability essential for tissue interaction control in surgical platforms. German medical device manufacturers are scaling procurement of these systems for next-generation laparoscopic tools as FDA safety classifications tighten.
- Semiconductor Lasers:Quantum cascade architectures enable compact, tunable emission across the 3-12 μm band for spectroscopy applications.
- Gas Lasers:Carbon monoxide and carbon dioxide configurations persist in legacy material processing installations requiring high continuous-wave output.
Fiber lasers anchor the volume base while solid-state systems gain share at the steepest rate in medical certification pipelines.
Application:
Customer investment horizons vary from capital-intensive production line integration to discrete research procurement, reshaping vendor sales motion requirements.
- Material Processing:Industrial cutting, welding, and surface treatment operations demand kilowatt-class output with sustained duty cycles. Japanese METI-backed photonics clusters are channeling deployment into automotive and electronics manufacturing, where fiber laser thermal efficiency reduces operating cost structures.
- Medical Applications:Surgical and dermatological platforms require pulse-stabilized sources meeting biocompatibility protocols under EU Medical Device Regulation and FDA performance standards. German precision engineering clusters are consolidating regulatory affairs functions across portfolio companies to manage extended pre-market clinical evidence timelines.
- Environmental Monitoring:Portable methane detection systems for oil and gas infrastructure inspection leverage quantum cascade tunability.
- Spectroscopy:Research laboratories and national measurement institutes drive demand for narrow-linewidth sources.
Material processing commands the largest installed base while medical applications expand most quickly under tightened safety mandates.
End User:
Procurement sophistication ranges from institutional tender processes to integrated supply chain partnerships, fragmenting vendor go-to-market approaches.
- Manufacturing:Automotive, electronics, and precision component producers prioritize uptime guarantees and predictive maintenance integration. Japanese industrial buyers are unbundling beam delivery components to source discrete emitters through specialized distributors prioritizing interoperability.
- Healthcare:Hospital systems and outpatient surgical centers demand turnkey integration with existing robotic platforms. FDA and PMDA submission requirements for surgical equipment now exceed development budgets for mid-tier manufacturers, consolidating procurement among vertically integrated suppliers.
- Research Institutions:Universities and national laboratories favor modular configurations over bundled system sales.
- Aerospace:Satellite-based sensing and directed energy applications impose radiation-hardening and reliability specifications.
Manufacturing absorbs the highest absolute unit volume while healthcare generates the steepest margin expansion.
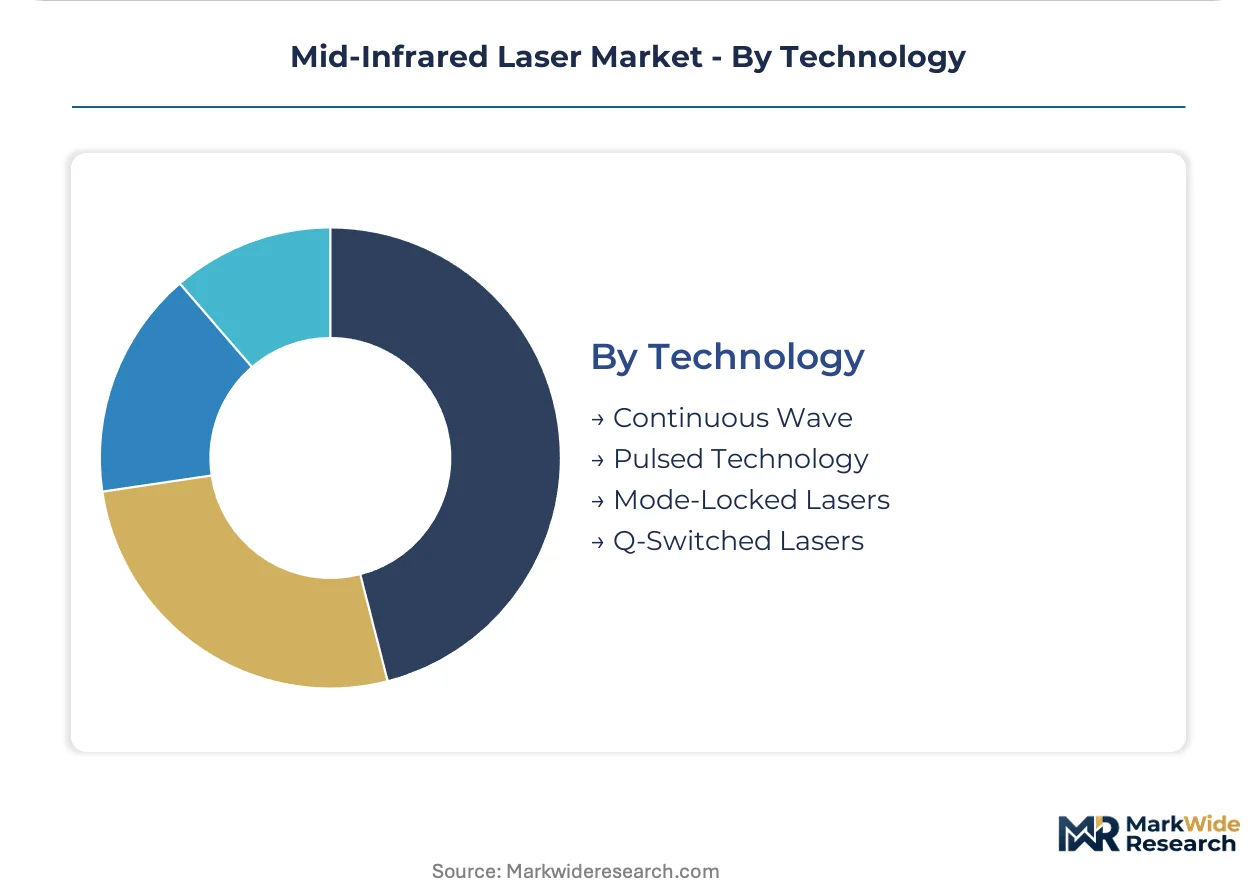
Technology:
Output modality selection governs thermal load management and material interaction physics, constraining retrofit compatibility.
- Continuous Wave:Sustained emission enables high-throughput industrial processing where thermal accumulation aids material removal. German and Swiss precision engineering clusters favor CW architectures for automotive component manufacturing requiring consistent cut edge quality.
- Pulsed Technology:Peak power concentration permits cold ablation of heat-sensitive substrates in medical and microelectronics applications. Solid-state pulse-stabilized systems are displacing legacy configurations in German surgical tool procurement as tissue interaction protocols tighten.
- Q-Switched Lasers:Nanosecond pulse generation serves marking and micromachining applications.
- Mode-Locked Lasers:Ultrafast pulse trains enable time-resolved spectroscopy and nonlinear optical research.
Continuous wave technology retains the broadest installed footprint while pulsed configurations climb fastest in medical and precision electronics segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German medical device manufacturers and Japanese precision engineering clusters currently concentrate procurement of solid-state and fiber laser systems. Buyer sophistication varies sharply between institutional healthcare tenders in Europe and unbundled component sourcing in Asian manufacturing hubs.
United States
EPA methane emissions regulations are accelerating deployment of portable spectroscopy systems for oil and gas infrastructure inspection. FDA laser safety reclassifications for surgical equipment are extending certification timelines for domestic medical device manufacturers. Boston and San Diego biotech corridors are consolidating procurement of pulse-stabilized sources for next-generation surgical platforms.
Germany
Automotive suppliers in Baden-Württemberg are scaling fiber laser integration for sub-micron precision manufacturing of electric vehicle components. EU Medical Device Regulation conformity assessment requirements are compressing development cycles for surgical laser systems. Munich and Stuttgart precision engineering clusters are pooling regulatory affairs functions across portfolio companies to manage extended pre-market clinical evidence timelines.
Japan
METI-backed photonics clusters are channeling public-private funding into fiber laser adoption for automotive and electronics manufacturing. PMDA submission requirements for surgical equipment now exceed development budgets for mid-tier domestic manufacturers. Nagoya and Osaka industrial corridors are unbundling beam delivery components to source discrete emitters through specialized distributors prioritizing interoperability.
China
Rare-earth refining concentration for erbium and thulium dopants is exposing fiber laser manufacturers to export restriction risk under evolving trade frameworks. MIIT industrial standards for laser safety are constraining system design parameters for manufacturing exports. Yangtze River Delta precision manufacturing hubs are accelerating backward integration into crystal growth capabilities to reduce import dependency.
Switzerland
Swissmedic enforcement of medical device quality management standards is elevating barrier thresholds for surgical laser market entry. Precision engineering clusters in Zurich and Basel are consolidating photonics supply chains through captive optical coating capabilities. Watchmaking and medical technology manufacturers are co-developing compact solid-state sources for micro-machining applications.
Mid-Infrared Laser Market Vendor Landscape
Channel-controlling players compete with product-specialist players across distinct procurement pathways. The vendor base separates into consolidated premium-tier suppliers with captive fabrication capabilities and fragmented specialists serving modular research laboratory demand. Three strategic archetypes dominate: vertically integrated chip fabricators, crystal growth specialists with optical coating control, and compact turnkey system providers. Capacity expansion in rare-earth dopant refining and strategic partnerships for regulatory compliance certification represent the dominant competitive moves reshaping positioning.
Among North American-based diversified technology conglomerates, IPG Photonics Corporation and Coherent, Inc. occupy positions anchoring the fiber and solid-state architecture segments. Hamamatsu Photonics K.K. exemplifies the Japanese specialist archetype integrating upstream crystal growth with downstream optical component fabrication. These three entities represent distinct geographic and structural approaches to margin defense through supply chain control.
| Leading Market Players |
|---|
| Leonardo DRS, Inc. |
| IPG Photonics Corporation |
| TRUMPF SE + Co. KG |
| Coherent, Inc. |
| Thermo Fisher Scientific, Inc. |
| Hamamatsu Photonics K.K. |
| Thorlabs |
| MKS Instruments |
| Lumentum |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese rare-earth refining capacity is compressing erbium and thulium dopant spot pricing while elevating strategic stockpiling behavior among Japanese and German fiber laser manufacturers facing export restriction risk.
Pricing Analysis
Certification level (FDA-grade versus industrial-grade) creates the primary spread between solid-state surgical sources and standard material processing systems. Three-tier pricing structure across premium, standard, and economy levels tracks pulse stability specifications and biocompatibility testing depth. Cost compression in mid-tier fiber architectures is intensifying because Chinese rare-earth export licensing delays are forcing spot market premiums. Research laboratories exhibit highest price sensitivity through unbundled component sourcing, while hospital systems absorb premium pricing for turnkey robotic integration.
Supply Chain Analysis
Upstream feedstock concentration for erbium and thulium draws from Chinese rare-earth refining complexes, gallium arsenide substrates rest on German and Japanese wafer fabrication, and optical coatings hinge on Swiss and US specialty chemical deposition. Single-source vulnerability in Chinese dopant supply exposes fiber laser manufacturers to MIIT export licensing unpredictability. Distribution runs through captive direct sales for medical OEMs and specialized photonics distributors serving research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capital equipment procurement cycles in precision manufacturing are recovering from trough conditions as METI-backed photonics clusters accelerate fiber laser deployment for automotive electrification.
For Market Incumbents: Entrench market position through backward integration into crystal growth capabilities and captive optical coating facilities. IPG Photonics-style chip fabrication control defends margin structure against rare-earth price volatility. Consolidating regulatory affairs functions across portfolio companies addresses EU Medical Device Regulation complexity threatening mid-tier competitors.
For New Entrants and Emerging Players: Modular source-and-optics configurations for research laboratories in Japan and Germany represent the most penetrable entry point given institutional buyer preference for interoperability over turnkey integration. Portable environmental monitoring systems for EPA-mandated methane detection offer second white-space target. Equipment-as-a-service financing models unlock capital-constrained academic buyers without competing on upfront system pricing.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among captive chip fabricators with installed base expansion through replacement cycles and service contracts. Five-to-ten year viability favors vertically integrated specialists controlling upstream dopant refining or downstream regulatory certification pipelines. Monitoring REACH enforcement intensity on arsenic compounds provides early signal for quantum cascade laser substrate redesign timelines and qualification cost inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crystal Growth | Captive supply of doped gain media insulates margin from Chinese export licensing volatility. |
| FDA-Grade Certification Investment | Pulse-stabilized solid-state architectures command surgical equipment premiums under tightened safety classifications. |
| Equipment-as-a-Service Launch | Asset-light leasing unlocks research laboratory procurement constrained by capital expenditure limits. |
| Regulatory Affairs Consolidation | Pooled CE marking and PMDA submission resources compress pre-market clinical evidence timelines. |
| Environmental Sensing Platform Integration | Quantum cascade tunability aligns with EPA methane detection mandates in oil and gas infrastructure. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, METI photonics cluster disbursement records, and REACH restriction dockets. Primary interviews engaged laser system design engineers, hospital biomedical equipment procurement managers, and precision manufacturing plant managers across German automotive and Japanese electronics corridors. Secondary validation drew from customs trade data for rare-earth dopant flows, SEC equipment manufacturer filings, and JIS standard revision archives. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing across product architectures.
Forecast inputs span technology migration curves for quantum cascade semiconductor advances, regulatory timeline assumptions for EU Medical Device Regulation enforcement, and substitution elasticity between fiber and solid-state architectures. Segmentation modeling covers product type, application vertical, end-user procurement sophistication, and output modality. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in comparable precision equipment categories. Rare-earth supply concentration scenarios and certification cost trajectories inform scenario-weighted projections.
Practitioners should monitor MIIT export licensing intensity, REACH arsenic compound restriction evolution, and FDA surgical laser reclassification pace for early signals of forecast revision. Cross-checking against equipment manufacturer order backlog disclosures and photonics cluster funding allocation trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Silicon Photonics Wafer Market
Optical Components
Optical Encoder Market
Optical Components
Optical Sensor Market
Optical Components
Photomask Pellicle Market
Optical Components
Optical Interconnect Market
Optical Components
Picosecond and Femtosecond Fiber Lasers Market
Optical Components
Mobile Optical Pluggable Market
Optical Components
Acousto Optic Devices Market
Optical Components
Liquid Lenses Market
Optical Components
Optical Film Market
Optical Components
Pancake Optical Module Market
Optical Components
Polarizer Film Market
Optical Components
Erbium-Doped Fiber Amplifier Market
Optical Components
High Power Double-Clad Fiber Bragg Grating Market
Optical Components
Electro Optical System Market
Optical Components
Optical Waveguide Market