
 Global Shortwave Infrared (SWIR) Market | 2026-2036
Global Shortwave Infrared (SWIR) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Shortwave Infrared (SWIR) Market Outlook
Indium gallium arsenide sensor-grade performance is unwinding legacy cost barriers across industrial vision systems. Teledyne FLIR leverages captive InGaAs foundry capacity to sustain pricing power in defense-qualified imagers. Allied Vision Technologies GmbH competes through modular camera architectures that accommodate multiple sensor formats. DOWA Electronics Materials Co., Ltd. anchors the supply chain through epitaxial wafer production that feeds both captive and merchant sensor fabricators.
Shortwave infrared denotes electromagnetic radiation spanning approximately 1,000 to 2,500 nanometers, a spectral window where InGaAs photodiodes achieve peak quantum efficiency and where atmospheric moisture absorption creates distinct reflectance signatures for material identification. SWIR cameras penetrate silicon wafers to reveal subsurface defects during semiconductor fabrication, while SWIR sensors in spectroscopy instruments discriminate chemical compositions for pharmaceutical quality control. InGaAs technology leads product shipments due to established foundry infrastructure, though quantum dots represent the fastest-expanding technology category as colloidal synthesis methods mature. Aerospace and defense applications concentrate margin pools because ITAR and EAR compliance requirements limit supplier competition.
FDA 21 CFR Part 11 shapes healthcare deployment by mandating electronic record integrity for SWIR-based diagnostic devices, while EU RoHS and REACH restrict hazardous substances in InGaAs sensor manufacturing processes. The FCC regulates SWIR laser emissions for telecommunications applications, and Japan's METI promotes domestic compound semiconductor supply chains through strategic technology roadmaps. Stakeholders must monitor export control list revisions affecting InGaAs focal plane arrays, as reclassification would reshape competitive access across allied defense markets.
Market Dynamics
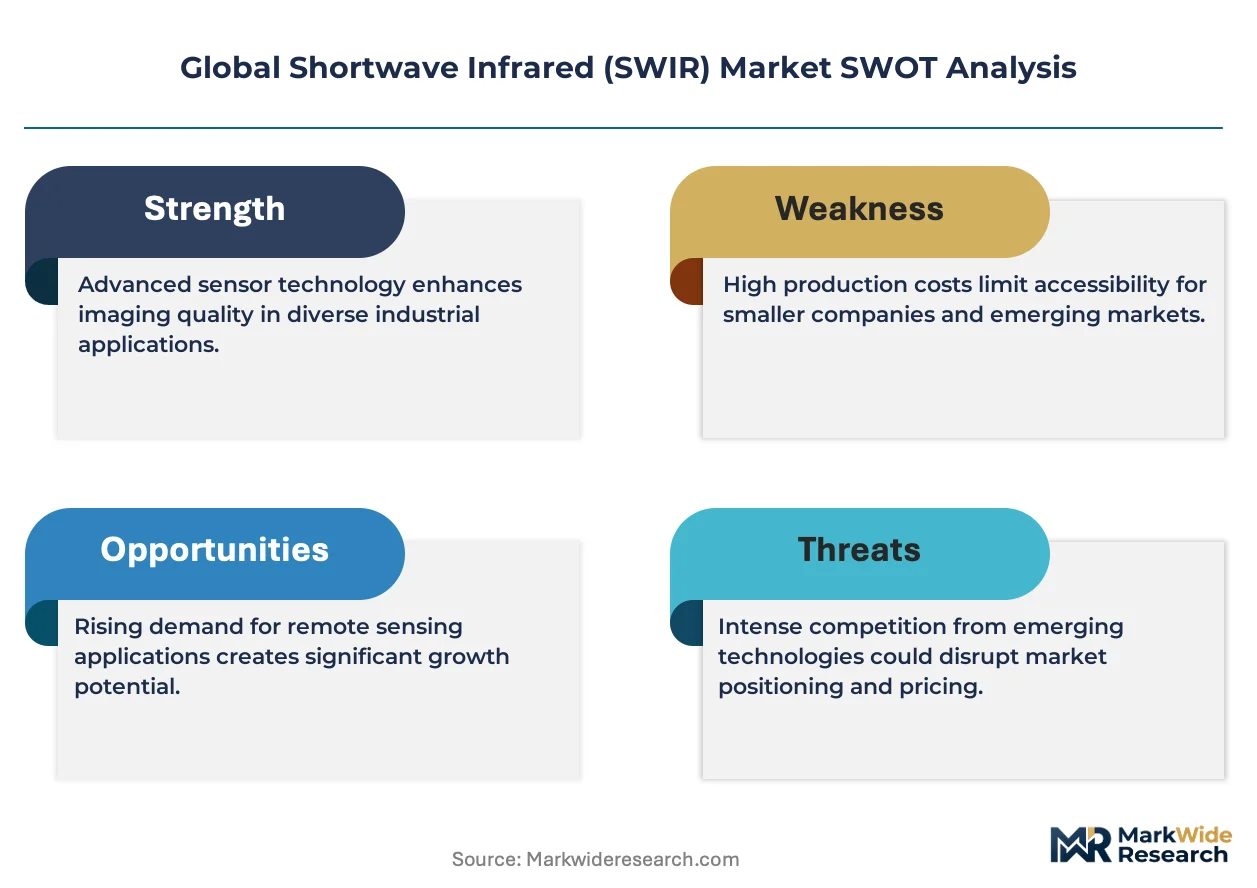
InGaAs sensor cost curves are flattening faster than alternative technologies can scale, concentrating competitive advantage among foundry-integrated suppliers while quantum dot architectures chase performance parity from a trailing position.
Growth Catalysts
- Sub-micron defect detection:Semiconductor fabs in Taiwan and South Korea now mandate subsurface wafer inspection at 7nm nodes and below, pulling SWIR cameras into every lithography bay.
- FDA 21 CFR Part 11:Electronic record integrity requirements for diagnostic devices are certifying SWIR-based imaging systems for pharmaceutical quality control workflows.
- Indium phosphide substrates:Expanding merchant epitaxial capacity is reducing InGaAs focal plane array feedstock costs by double-digit percentages annually.
Market Restraints
- Indium supply concentration:Over 80% of global indium refining occurs in Chinese smelters, exposing sensor fabricators to export quota volatility and price spikes.
- ITAR/EAR compliance costs:US State Department export controls on focal plane arrays force dual-track product development, inflating R&D overhead for defense-qualified suppliers.
- Silicon-based NIR extension:Extended silicon photodiodes approaching 1100nm are capturing cost-sensitive machine vision applications below 1200nm, compressing SWIR entry-level pricing.
Strategic Opportunities
- Quantum dot SWIR:Colloidal synthesis advances are enabling solution-processed imagers on glass substrates, opening automotive LiDAR and consumer electronics volumes previously inaccessible to InGaAs.
- EU Green Deal compliance:REACH substance restrictions are accelerating replacement of legacy lead-selenide detectors with RoHS-compliant InGaAs alternatives in European process industries.
- Telecom channel expansion:Hyperscale data center operators in Virginia and Frankfurt are specifying SWIR optical channel monitors for 800G coherent transceivers, creating a high-volume merchant market.
Industry Challenges
- Compound semiconductor process engineering:Foundry technicians skilled in MOCVD epitaxy and III-V device physics command premium wages, constraining capacity expansion timelines.
- Defense qualification cycles:MIL-STD-810 environmental testing and MIL-PRF-38534 QML certification extend product development by 18-24 months, freezing out capital-constrained entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Shortwave Infrared (SWIR) Market |
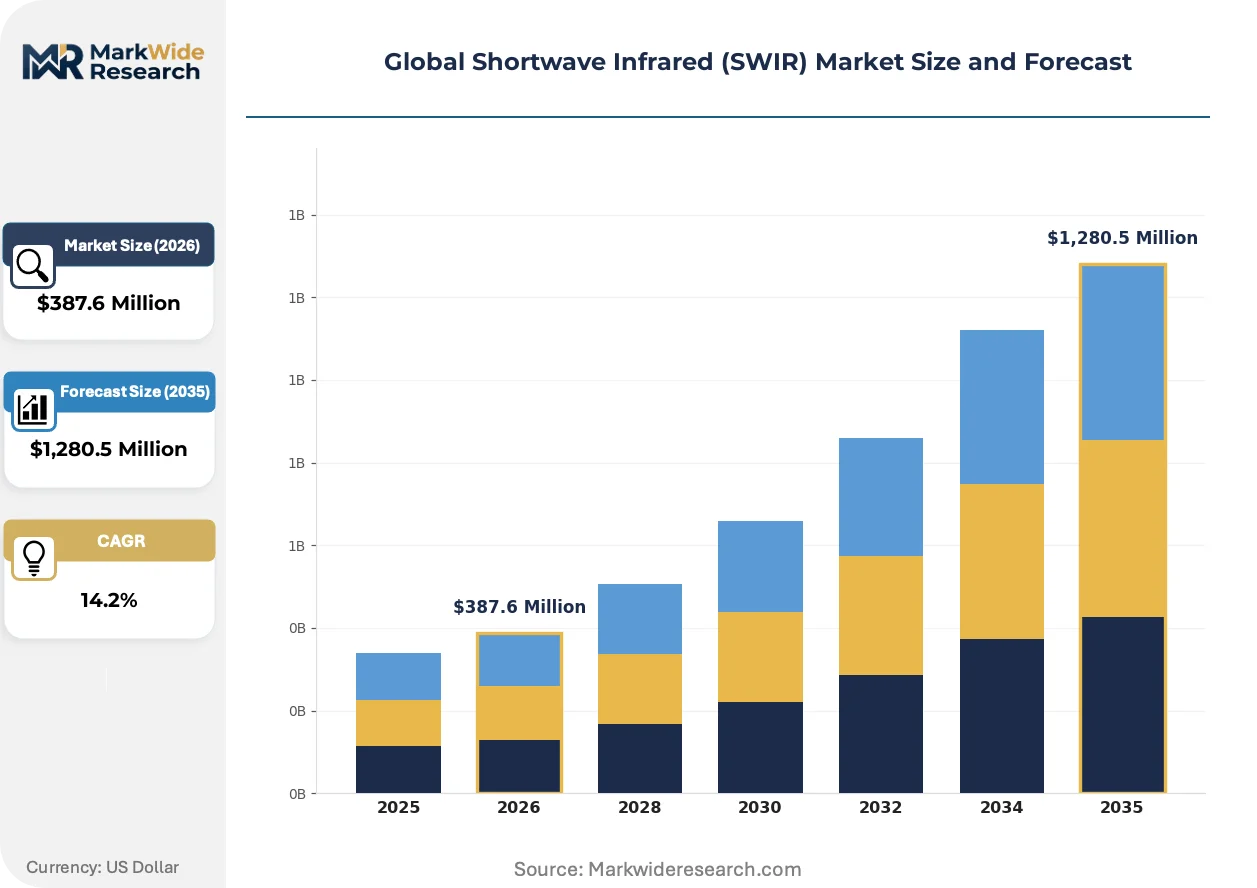
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SWIR Cameras, SWIR Light Sources, SWIR Sensors, SWIR Lasers Technology: CCDs, InGaAs, HgCdTe, Quantum Dots Application: Aerospace, Defense, Spectroscopy, Industrial Inspection End User: Healthcare, Manufacturing, Agriculture, Research |
| Companies Covered | Ushio OPTO Semiconductors Inc., DOWA Electronics Materials Co., Ltd., Lite-On Inc., Everlight Electronics Co Ltd, EPILEDS, Teledyne FLIR LLC, Allied Vision Technologies GmbH, Collins Aerospace, Leonardo DRS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Shortwave Infrared (SWIR) Market Strategic Shifts
Sensor technology trajectories are diverging between established InGaAs performance tiers and emerging quantum dot architectures, while regulatory frameworks and procurement behaviors recalibrate competitive access across end-use verticals.
Quantum dot SWIR technology is bifurcating the cost-performance frontier for shortwave infrared detection. Colloidal lead sulfide and indium arsenide quantum dots deposited by inkjet or spin-coating achieve 70-80% quantum efficiency across 1000-1700nm without indium phosphide substrates. Automotive Tier 1s in Germany and Japan are sampling these sensors for thermal-agnostic cabin monitoring and LiDAR receiver arrays. The technology is bifurcating the market into premium InGaAs defense/aerospace tiers and mass-market quantum dot tiers for consumer and automotive volumes.
EU REACH Annex XVII restrictions on cadmium and lead compounds are forcing reformulation of quantum dot compositions and accelerating InGaAs substitution in industrial spectroscopy. ECHA substance evaluations now cover indium compounds, prompting sensor fabricators to secure supply chain documentation for SVHC compliance. European pharmaceutical and food safety inspection OEMs are responding by dual-qualifying InGaAs and emerging perovskite-SWIR alternatives to hedge regulatory exposure.
Hyperscale cloud infrastructure operators are consolidating optical component procurement around vertically integrated transceiver suppliers who specify SWIR channel monitors as standard subassemblies. This buyer concentration is displacing merchant camera vendors who previously sold discrete SWIR instruments to telecom equipment manufacturers. The shift is most visible in Ashburn, Virginia and Dublin data center clusters, where Microsoft, Amazon, and Google procurement teams now mandate SWIR-based optical performance monitoring at the transceiver level rather than the system level.
Global Shortwave Infrared (SWIR) Market Segmentation
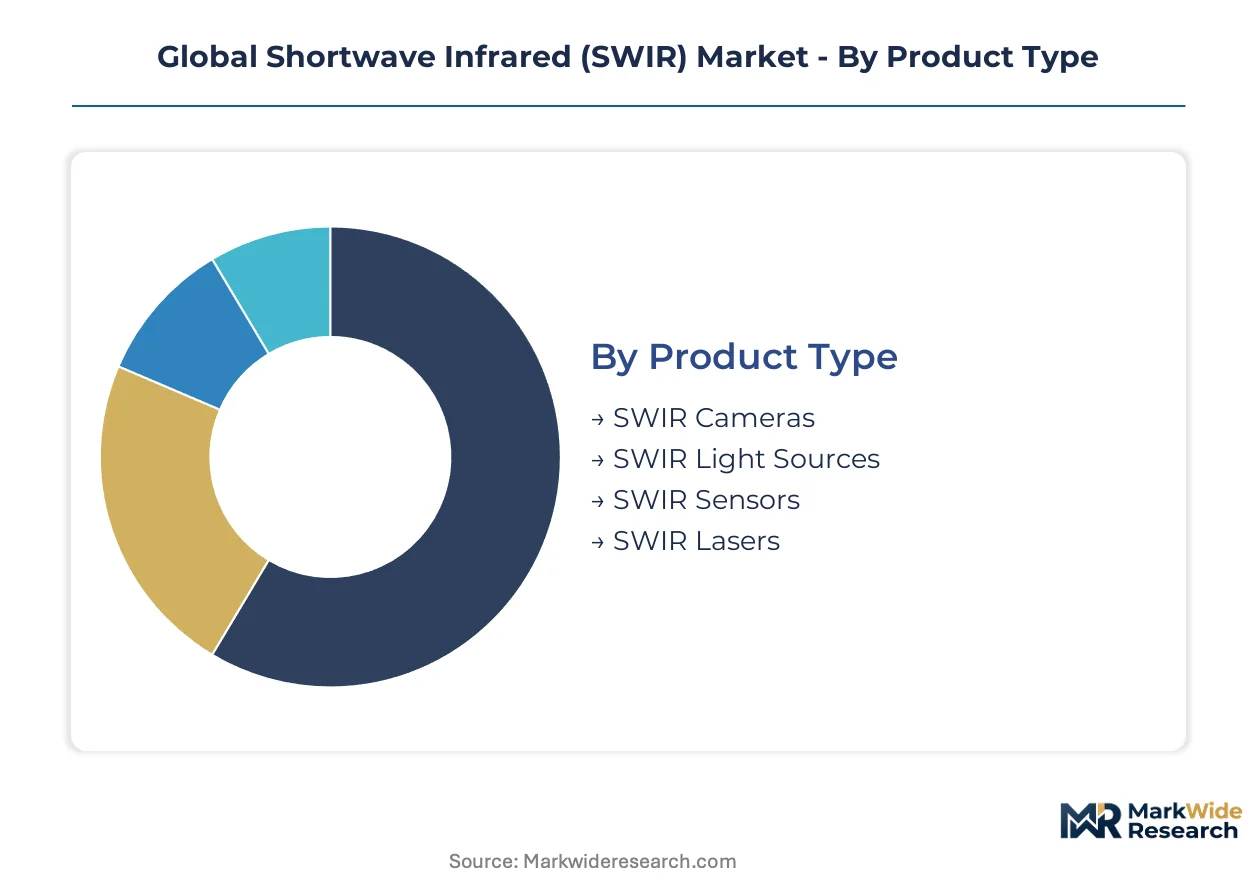
SWIR market segmentation reveals divergent substitution pressures across hardware categories and competing sensor architectures. Product and technology boundaries are blurring as quantum dot deposition methods challenge InGaAs cost structures in volume applications.
Product Type:
SWIR cameras face intensifying substitution pressure from integrated sensor modules in telecom and consumer electronics, while discrete light sources and sensors retain protected positions in defense and scientific instrumentation.
- SWIR Cameras:Focal plane array assemblies with integrated readout electronics dominate semiconductor wafer inspection bays in Taiwan and South Korea. Sub-micron defect detection at advanced nodes pulls cooled InGaAs imagers into every lithography cluster despite silicon NIR extension below 1100nm.
- SWIR Sensors:Discrete photodiode arrays and linear sensors feed OEM spectroscopy platforms for pharmaceutical quality control. FDA 21 CFR Part 11 record-integrity requirements are certifying these components for diagnostic device integration in US and European healthcare workflows.
- SWIR Light Sources:Broadband lamps and tunable lasers illuminate inspection targets in machine vision and materials characterization systems.
- SWIR Lasers:Single-mode and pulsed sources enable LiDAR transmitters and optical communications channel monitoring.
SWIR cameras retain volume leadership; SWIR sensors hold the steepest expansion curve as modular integration accelerates across industrial OEM supply chains.
Technology:
Cost tier stratification separates mature foundry-produced formats from emerging solution-processed alternatives chasing performance parity.
- InGaAs:Lattice-matched indium gallium arsenide on indium phosphide substrates delivers 70-90% quantum efficiency across 900-1700nm with established epitaxial foundry infrastructure. Merchant wafer supply from Japanese and German sources is reducing feedstock costs for defense-qualified and industrial-grade imagers.
- Quantum Dots:Colloidal lead sulfide and indium arsenide nanocrystals deposited by inkjet or spin-coating achieve broadband SWIR response without III-V substrates. Automotive Tier 1s in Germany and Japan are sampling these sensors for thermal-agnostic cabin monitoring and LiDAR receiver arrays.
- CCDs:Silicon-based charge-coupled devices with extended red response serve cost-sensitive applications below 1100nm where SWIR penetration is marginal.
- HgCdTe:Mercury cadmium telluride extends into MWIR and LWIR bands for cooled high-performance defense systems requiring extended spectral reach beyond 2500nm.
InGaAs maintains revenue concentration; quantum dots are climbing the fastest as colloidal synthesis methods mature for automotive and consumer volumes.
Application:
Margin concentration correlates with qualification barriers and export control exposure across end-use verticals.
- Defense:ITAR and EAR compliance requirements on focal plane arrays limit supplier competition and sustain pricing power for US-qualified imagers. MIL-STD-810 environmental testing extends development cycles, freezing out capital-constrained entrants.
- Industrial Inspection:Semiconductor fabs in Taiwan and South Korea now mandate subsurface wafer inspection at 7nm nodes and below, pulling SWIR cameras into every lithography bay.
- Aerospace:Satellite remote sensing and aerial surveillance platforms demand radiation-hardened sensors with proven space heritage.
- Spectroscopy:Pharmaceutical quality control and food safety inspection OEMs are dual-qualifying InGaAs and emerging perovskite alternatives to hedge EU REACH regulatory exposure.
Defense commands the highest margins; industrial inspection is gaining share fastest as semiconductor capital equipment cycles accelerate.
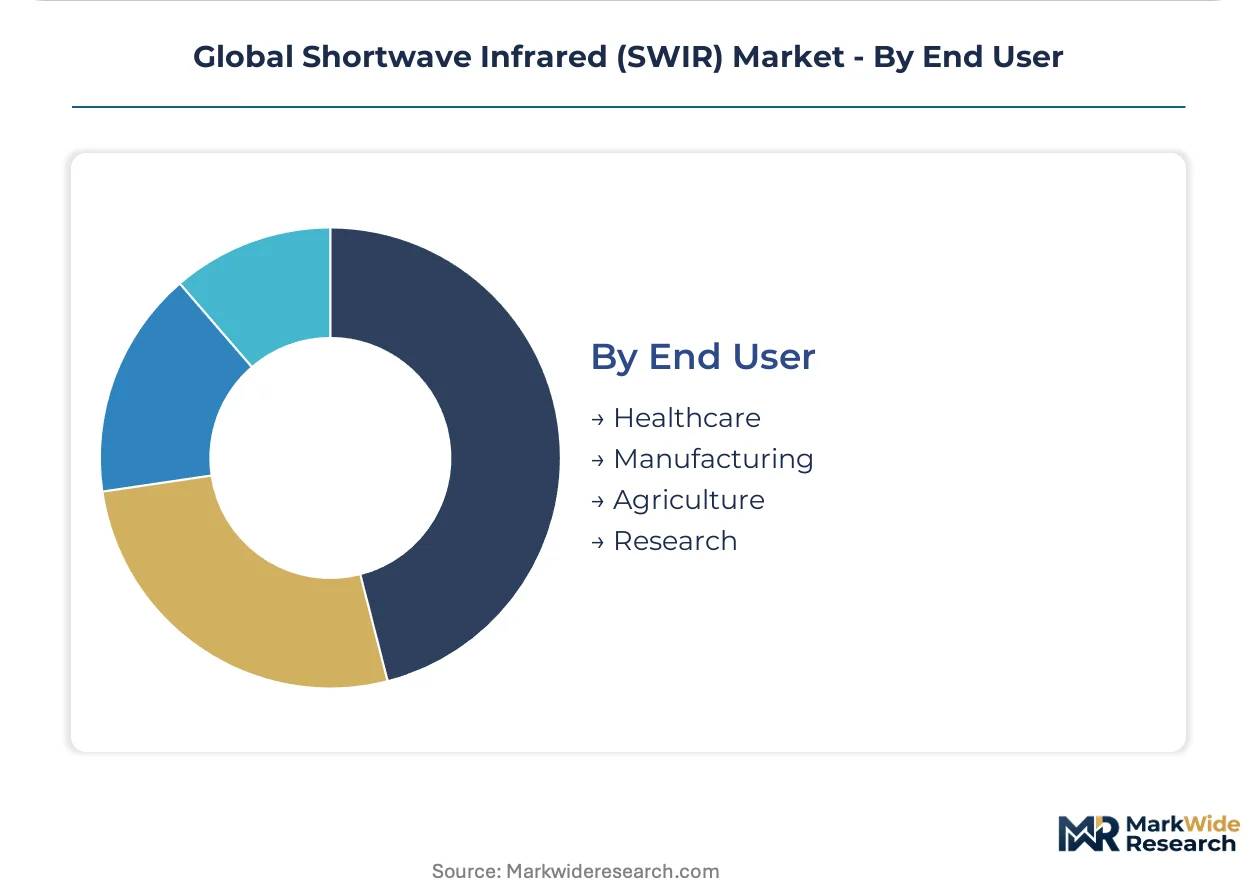
End User:
Customer type determines procurement sophistication and integration depth across value chain positions.
- Manufacturing:Precision fabrication and electronics assembly lines deploy SWIR vision systems for defect detection and process monitoring. Hyperscale data center operators in Virginia and Frankfurt are specifying SWIR optical channel monitors for 800G coherent transceivers.
- Healthcare:Diagnostic device manufacturers integrate SWIR imaging for pharmaceutical quality control and surgical guidance applications.
- Research:Academic and government laboratories drive early adoption of emerging quantum dot and perovskite sensor architectures.
- Agriculture:Crop monitoring and food sorting applications leverage SWIR reflectance signatures for moisture content and defect identification.
Manufacturing leads procurement volume; healthcare is expanding most quickly as FDA certification pathways mature for SWIR-based diagnostic platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indium refining capacity clusters heavily in Chinese smelters, while precision manufacturing demand concentrates in Taiwan, South Korea, and Germany. Defense procurement anchors adoption in the United States and Japan. Regulatory frameworks in the European Union and United States shape compliance requirements for export-controlled focal plane arrays.
United States
Defense procurement from Raytheon and Lockheed Martin sustains demand for ITAR-qualified InGaAs imagers. The State Department's EAR controls on focal plane arrays limit foreign supplier access. Ashburn, Virginia hosts hyperscale data center clusters where Microsoft and Amazon specify SWIR optical channel monitors for 800G coherent transceivers.
Germany
Automotive Tier 1 suppliers in Stuttgart and Munich sample quantum dot sensors for LiDAR receiver arrays and thermal-agnostic cabin monitoring. The KBA and EU REACH Annex XVII restrictions on cadmium compounds force reformulation of quantum dot compositions. The Eindhoven-Frankfurt corridor anchors merchant epitaxial wafer distribution for InGaAs feedstock.
Japan
METI promotes domestic compound semiconductor supply chains through strategic technology roadmaps targeting InGaAs sensor independence. Sony and Hamamatsu Photonics anchor precision manufacturing demand for semiconductor wafer inspection systems. The Kyushu region concentrates epitaxial foundry capacity feeding both captive and merchant sensor fabricators.
Taiwan
TSMC and United Microelectronics mandate subsurface wafer inspection at 3nm and 5nm nodes, pulling cooled InGaAs imagers into every lithography bay. The Hsinchu Science Park concentrates SWIR camera deployment across semiconductor capital equipment cycles. Export control compliance shapes procurement from US-qualified suppliers.
South Korea
Samsung Electronics and SK Hynix drive sub-micron defect detection requirements at advanced memory nodes. The MFDS regulates SWIR-based diagnostic devices for pharmaceutical quality control applications. The Yongin-Giheung corridor anchors industrial inspection system integration for electronics manufacturing.
Global Shortwave Infrared (SWIR) Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the SWIR market. Foundry-integrated suppliers with captive InGaAs epitaxial capacity command premium pricing in defense-qualified segments, while modular camera specialists compete on flexibility and lead time. Three archetypes dominate: vertically integrated compound semiconductor houses, modular industrial vision specialists, and merchant epitaxial wafer suppliers. Competitive dynamics center on dual-track product development for ITAR compliance and capacity expansion for merchant wafer supply.
Among Japanese and German fabricators, DOWA Electronics Materials Co., Ltd., Allied Vision Technologies GmbH, and Teledyne FLIR LLC occupy distinct positions in the value chain. DOWA anchors merchant epitaxial supply feeding both captive and merchant sensor producers. Allied Vision exemplifies modular camera architecture specialists accommodating multiple sensor formats. Teledyne FLIR represents foundry-integrated defense suppliers leveraging captive InGaAs capacity. These three illustrate how geographic origin and corporate structure map onto divergent competitive strategies across the technology-cost frontier.
| Leading Market Players |
|---|
| Ushio OPTO Semiconductors Inc. |
| DOWA Electronics Materials Co., Ltd. |
| Lite-On Inc. |
| Everlight Electronics Co Ltd |
| EPILEDS |
| Teledyne FLIR LLC |
| Allied Vision Technologies GmbH |
| Collins Aerospace |
| Leonardo DRS |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four month defense qualification cycles compress inventory turnover for InGaAs focal plane arrays, concentrating pricing power among foundry-integrated suppliers with captive epitaxial capacity while forcing merchant fabricators into strategic stockpiling of indium phosphide substrates.
Pricing Analysis
ITAR and EAR export controls dictate the pricing tier structure across the SWIR market. Three-tier pricing stratifies across ITAR-qualified defense imagers, industrial-grade inspection cameras, and emerging quantum dot alternatives for automotive volumes. Price differentiation hinges on MIL-PRF-38534 QML certification grade and foundry integration depth. Cost compression in entry-level machine vision reflects silicon NIR extension below 1100nm. Automotive Tier 1s exhibit highest price sensitivity; defense primes accept premium positioning for qualified supply security.
Supply Chain Analysis
Strategic stockpiling of indium phosphide substrates dominates inventory strategy among Japanese and German sensor fabricators seeking buffer against Chinese export quota volatility. Merchant epitaxial supply concentrates in Japan, Germany, and Taiwan. Raw material dependencies center on refined indium, gallium metal, and high-purity phosphine gas. Single-source vulnerability runs through Chinese indium refining exceeding 80% of global capacity. Distribution runs through vertically integrated defense contractors and modular camera OEMs serving industrial automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as quantum dot architectures bifurcate demand between premium defense tiers and mass-market automotive volumes, creating distinct competitive arenas with divergent capability requirements.
For Market Incumbents: Consolidate captive epitaxial capacity in Japan and Germany to defend margin position against quantum dot substitution in sub-1700nm applications. Lock in long-term indium supply agreements before ECHA substance evaluations tighten. Prioritize MIL-STD-810 qualification pipeline investment to maintain ITAR-compliant supplier lists. For New Entrants and Emerging Players: Modular integration services for pharmaceutical OEMs represent the most penetrable white-space target, as FDA 21 CFR Part 11 compliance burdens slow incumbent response times. Quantum dot sensor packaging for automotive LiDAR receivers offers second entry path. Pursue partnership-first go-to-market with German Tier 1s seeking REACH-compliant alternatives to lead-selenide detectors. For Investors and Strategic Acquirers: Long-term, this sits as a compound semiconductor consolidation play because defense qualification barriers and foundry capital intensity favor scaled operators over fragmented merchant suppliers. Target acquisition archetype: merchant epitaxial wafer suppliers with established MOCVD capacity and Japanese or European regulatory documentation. Watch indium price volatility and ECHA SVHC list revisions as inflection signals for supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Merchant Epitaxial Capacity Expansion | DOWA and Japanese suppliers reduce InGaAs feedstock costs for defense and industrial imagers. |
| Quantum Dot Formulation Pivot | Lead-free colloidal synthesis addresses EU REACH cadmium restrictions for automotive cabin monitoring. |
| ITAR-Compliant Product Line Duplication | Dual-track development preserves US defense market access against export control tightening. |
| Telecom Channel Integration | Hyperscale data center procurement consolidation favors transceiver-level SWIR monitor suppliers. |
| Indium Supply Contracting | Long-term offtake agreements hedge Chinese smelter quota volatility for sensor fabricators. |
Study Parameters
Two parallel data streams informed the analysis: primary engagement with compound semiconductor executives, defense procurement officers, and pharmaceutical device engineers; and secondary validation through SEC filings, ECHA substance registry entries, and customs trade records. Bottom-up triangulation across sensor unit economics and top-down validation against capital equipment spending patterns anchored volume estimates.
Across the analysis window, forecasts model technology substitution between InGaAs and quantum dot architectures, application segmentation by qualification barrier height, and regional regulatory cluster effects on supplier access. CAGRs derive from wafer inspection capital equipment cycles, defense appropriation trajectories, and automotive LiDAR adoption curves. Hyperscale data center optical transceiver specifications and FDA certification pathway timelines constitute key industry-specific inputs.
Forecasts assume regulatory continuity in US export control regimes and EU REACH substance restrictions; material policy shifts affecting InGaAs focal plane array classification or cadmium compound exemptions would require re-modeling. Revision becomes warranted when indium price volatility or ECHA SVHC list expansion crosses thresholds that alter feedstock cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Optical Emission Spectroscopy Market
Optoelectronics
Gunn Diode Market
Optoelectronics
Electro-Optical/Infrared (EO/IR) Systems Market
Optoelectronics
China Optoelectronics Market
Optoelectronics
Laser Projector Market
Optoelectronics
Gaas Wafer and Epiwafer Market
Optoelectronics
Global Opto-Isolator Market
Optoelectronics
Quantum Dot Solar Cell Market
Optoelectronics
Gaas Photodiode Market
Optoelectronics
Opto-Electronics Device Market
Optoelectronics
Europe Wigig Market
Optoelectronics
Quantum Cascade Lasers Market
Optoelectronics
Quantum Dots Market
Optoelectronics
Smart Compact Projectors Market
Optoelectronics
Global Infrared Optoelectronics Market
Optoelectronics
Laser Diode Market