
 Integrated Circuit Optocouplers Market | 2026-2036
Integrated Circuit Optocouplers Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated Circuit Optocouplers Market Foresight
Aftermarket service revenue for isolation component refurbishment is tilting toward original manufacturers with captive technical knowledge. Toshiba Electronic Devices & Storage Corporation leverages its vertically integrated semiconductor fabrication to control replacement part availability. Vishay Intertechnology anchors its aftermarket position through broad distributor networks spanning industrial repair channels. Broadcom Inc. differentiates by specializing in high-reliability refurbishment protocols for telecommunications infrastructure.
Integrated circuit optocouplers are solid-state devices combining an LED emitter and photodetector in a single package, achieving galvanic isolation ratings typically from 2.5 kV to 5 kV while transmitting signals across an electrically insulated barrier. These components prevent ground loop interference and protect sensitive control circuitry in high-voltage industrial environments. High-speed optocouplers now lead product type margins as data rates exceed 50 Mbps in telecommunications backhaul. Surface-mount technology dominates installation methods due to automated assembly compatibility in consumer electronics and automotive electronics. Signal isolation applications sustain the largest volume share, though motor control segments in industrial automation are expanding fastest.
ISO 9001 and IEC 60747-5-5 standards govern optocoupler safety certifications, with China's GB standards adding regional electromagnetic compatibility requirements through MIIT enforcement. The EU's RoHS and REACH frameworks restrict hazardous substances in semiconductor packaging materials, reshaping supplier qualification processes. Stakeholders must monitor evolving isolation voltage requirements in electric vehicle powertrain standards and decide whether to certify products against emerging automotive-grade specifications before competitor lock-in solidifies.
Market Dynamics
China's MIIT enforcement of tightened GB electromagnetic compatibility standards is forcing industrial equipment manufacturers to upgrade isolation architectures, compressing supplier qualification timelines and tilting procurement toward certified component vendors.
Growth Catalysts
- Industrial automation motor control:Factory electrification in Germany and Japan is expanding procurement of galvanic isolation components for variable frequency drives and servo systems.
- REACH and RoHS substance restrictions:The EU's hazardous substance frameworks are reshaping semiconductor packaging material specifications, favoring suppliers with compliant supply chains.
- Telecommunications backhaul expansion:High-speed optocouplers exceeding 50 Mbps data rates are capturing margin premiums in 5G infrastructure deployments across East Asian manufacturing clusters.
Market Restraints
- Silicon photodiode input cost volatility:Wafer pricing fluctuations and foundry capacity constraints are compressing margins for standard-grade optocoupler production.
- Supply concentration in East Asian packaging:Backend assembly and testing capacity clusters around Shenzhen and Seoul, creating geographic vulnerability to regional logistics disruptions.
- Capacitive and magnetic isolator substitution:Silicon-based isolation technologies are displacing optocouplers in sub-5 kV applications where higher integration density is prioritized.
Strategic Opportunities
- Electric vehicle powertrain certification:Emerging automotive-grade isolation voltage specifications present first-mover advantages for suppliers certifying before competitor lock-in solidifies.
- Surface-mount technology channel expansion:Automated assembly compatibility in consumer electronics is opening distributor partnerships beyond traditional industrial repair channels.
- Aftermarket refurbishment services:Captive technical knowledge at original manufacturers creates service revenue potential in isolation component replacement and recertification.
Industry Challenges
- IEC 60747-5-5 certification timeline compression:Accelerated safety approval requirements are straining testing laboratory capacity and extending product launch schedules.
- Legacy system integration complexity:Retrofitting galvanic isolation into existing industrial control architectures demands custom engineering support and fragments volume economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated Circuit Optocouplers Market |
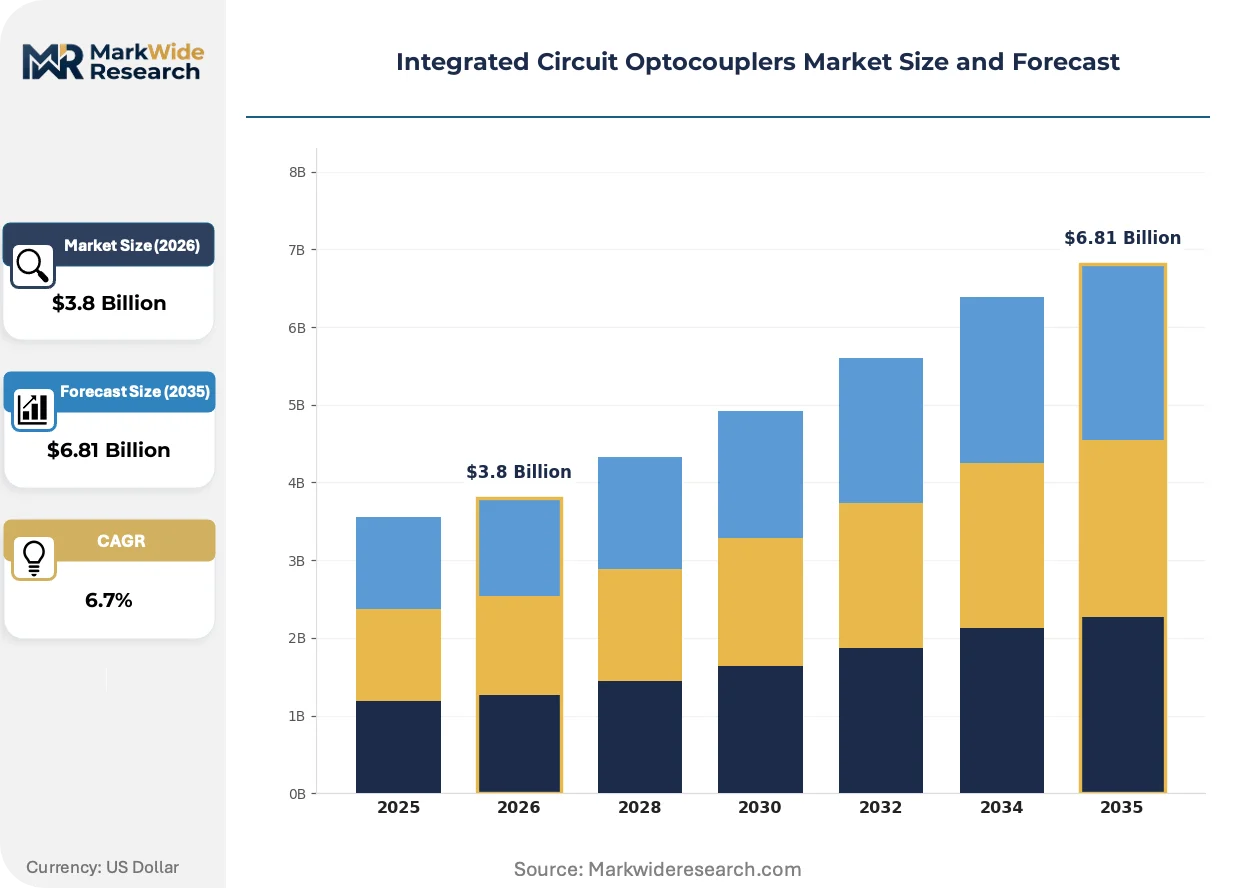
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC Optocouplers, DC Optocouplers, RF Optocouplers, High-Speed Optocouplers End User: Consumer Electronics, Automotive Electronics, Industrial Automation, Telecommunications Installation: Surface-Mount Technology, Through-Hole Technology, Modular Installation, Integrated Installation Application: Signal Isolation, Power Management, Data Communication, Motor Control |
| Companies Covered | Toshiba Electronic Devices & Storage Corporation, Infineon Technologies, Broadcom Inc., Lite-On Technology Corporation, Texas Instruments Incorporated, Vishay Intertechnology, ON Semiconductor Corporation, Everlight Electronics, Renesas Electronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated Circuit Optocouplers Market Shifts & Advancements
Optocoupler architecture is hybridizing with complementary isolation technologies as data rate requirements diverge across end-use verticals. Three developments are restructuring competitive positioning.
Silicon dioxide-based digital isolators is hybridizing with traditional LED-photodiode architectures in mixed-signal designs. Automotive tier-one suppliers are adopting these hybrid configurations for battery management systems where 5 kV isolation must coexist with SPI communication at 100 Mbps. The convergence is compressing addressable market share for pure optocoupler solutions in high-reliability segments.
REACH substance restrictions are tightening enforcement on semiconductor molding compounds and leadframe plating materials. The ECHA authorization process is disqualifying legacy halogenated flame retardants from new designs, forcing reformulation of package materials. Industrial automation OEMs in Germany are accelerating supplier audits to verify compliance before 2025 material deadline phases.
Consolidation of procurement authority at contract manufacturers is displacing traditional distributor relationships in consumer electronics. Foxconn and Pegatron are centralizing component selection for smartphone and tablet power adapters, compressing vendor lists to three qualified sources per specification. This concentration is most visible in Shenzhen manufacturing clusters where surface-mount optocoupler volumes concentrate.
Integrated Circuit Optocouplers Market Segmentation
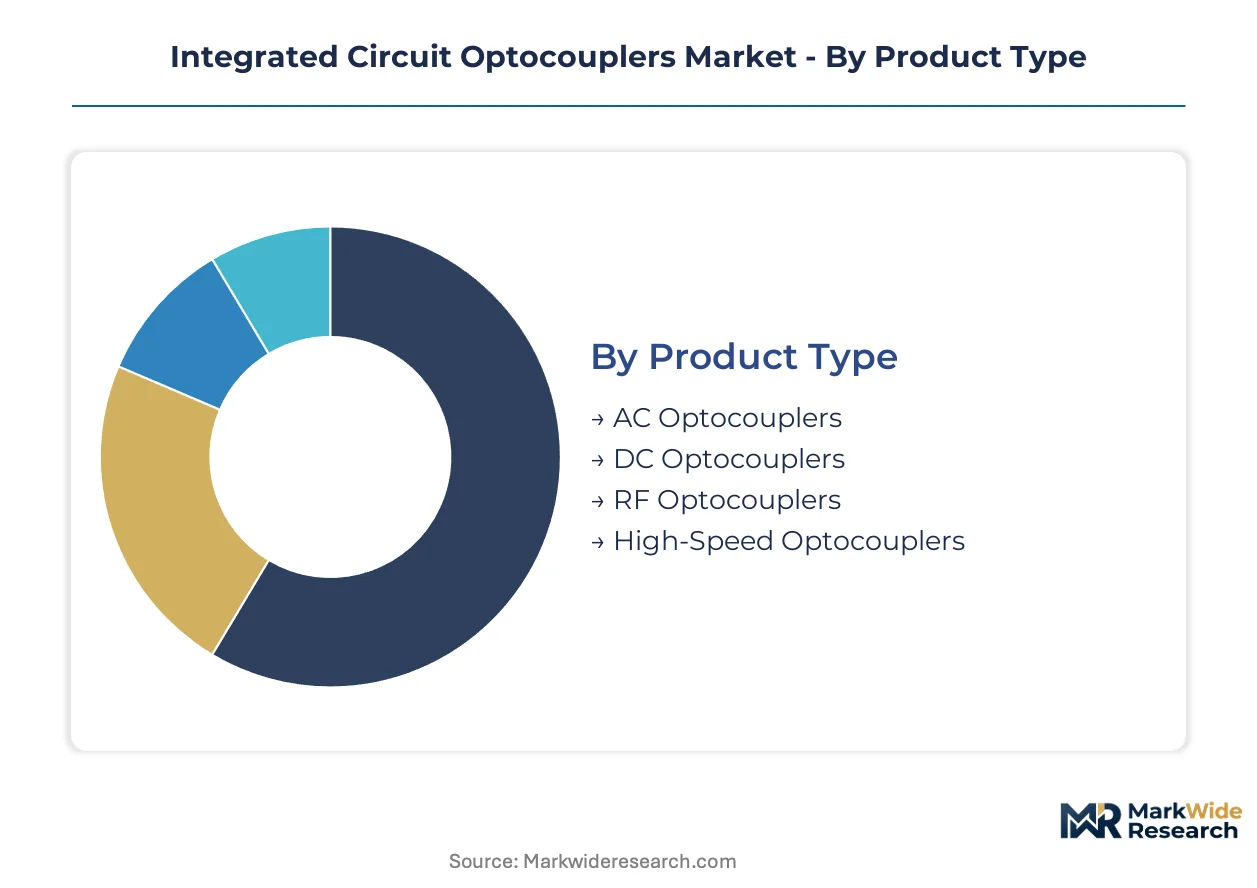
Optocoupler segmentation reflects diverging technical requirements across isolation voltage ratings, switching speeds, and form factor constraints. Manufacturers configure product portfolios around these axes to capture margin premiums in high-reliability verticals while maintaining volume positions in cost-sensitive consumer applications.
Product Type:
Use-case spectrum spans from line-frequency AC mains isolation to gigahertz-range RF signal coupling, with data rate requirements determining architecture selection.
- High-Speed Optocouplers:These devices achieve switching speeds exceeding 50 Mbps through optimized LED-photodiode pair geometries and reduced parasitic capacitance. Telecommunications backhaul deployments in Seoul and Shenzhen manufacturing clusters are absorbing volumes as 5G infrastructure scales, with MIIT certification requirements compressing supplier qualification timelines for Chinese network equipment vendors.
- DC Optocouplers:Standard DC-coupled architectures dominate industrial control applications where galvanic isolation must coexist with slow-speed logic-level translation. Factory electrification initiatives across Germany and Japan are expanding procurement for variable frequency drive interfaces, though capacitive isolator substitution is eroding share in sub-5 kV applications.
- AC Optocouplers:Bidirectional LED configurations enable zero-cross detection and phase control in mains-connected equipment.
- RF Optocouplers:Specialized packages maintain signal integrity across isolation barriers at frequencies above 100 MHz for radar and communication systems.
The dominant share belongs to DC Optocouplers, while High-Speed Optocouplers is closing the gap fastest.
End User:
Customer concentration varies sharply by certification burden, with automotive-grade specifications creating the steepest barriers to entry.
- Industrial Automation:Motor control and programmable logic controller applications demand isolation ratings from 2.5 kV to 5 kV with extended temperature ranges. German machinery OEMs are accelerating supplier audits to verify REACH compliance on molding compounds before ECHA authorization deadlines phase out halogenated flame retardants.
- Automotive Electronics:Battery management systems and onboard chargers require AEC-Q100 qualification plus emerging isolation voltage specifications for electric vehicle powertrains. Tier-one suppliers in Japan are adopting hybrid optocoupler-digital isolator configurations to satisfy SPI communication at 100 Mbps alongside 5 kV isolation.
- Telecommunications:Base station power supplies and optical line terminal equipment consume high-speed variants for signal integrity.
- Consumer Electronics:Smartphone and tablet power adapters drive surface-mount volumes through consolidated procurement at contract manufacturers.
Industrial Automation commands the largest revenue base, though Automotive Electronics is expanding most quickly as electrification mandates tighten.
Installation:
Assembly method selection tracks automation density and repair accessibility requirements across end-use verticals.
- Surface-Mount Technology:Tape-and-reel packaging enables high-speed pick-and-place assembly in consumer electronics and automotive electronics. Foxconn and Pegatron procurement centralization in Shenzhen is compressing vendor lists to three qualified sources per specification, concentrating volume among suppliers with proven high-volume delivery.
- Through-Hole Technology:Pin-through-board mounting persists in industrial equipment where field repairability and mechanical robustness outweigh assembly automation benefits. Japanese factory automation OEMs specify these packages for servo drive replacement schedules spanning 15-20 year equipment lifecycles.
- Modular Installation:Pluggable optocoupler modules facilitate rapid replacement in process control systems without soldering.
- Integrated Installation:Chip-on-board and co-packaged configurations reduce footprint in space-constrained medical and aerospace applications.
Surface-Mount Technology holds the volume majority, while Modular Installation is gaining traction fastest in maintenance-critical process industries.
Application:
Functional segmentation isolates signal integrity requirements from power handling demands, with motor control emerging as the most technically demanding intersection.
- Motor Control:Variable frequency drives and servo systems require isolation between high-voltage power stages and low-voltage control logic, with common-mode transient immunity specifications exceeding 25 kV/μs. German industrial automation expansion is driving specification upgrades as IE4 and IE5 efficiency mandates proliferate across European manufacturing.
- Signal Isolation:Logic-level translation and ground loop elimination sustain the highest unit volumes across consumer, industrial, and telecommunications equipment. Standard-grade devices face margin compression from silicon photodiode input cost volatility and foundry capacity constraints.
- Power Management:Feedback isolation in switched-mode power supplies demands tight voltage reference accuracy across temperature.
- Data Communication:High-speed serial links in telecommunications and computing equipment prioritize propagation delay and pulse width distortion specifications.
Signal Isolation maintains the broadest installed base, while Motor Control is climbing the fastest as factory electrification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity and backend packaging operations concentrate in East Asian manufacturing corridors, with German and Japanese industrial automation OEMs driving specification upgrades across European and Northeast Asian demand centers. Regulatory enforcement of electromagnetic compatibility standards in China and substance restrictions in the EU are compressing supplier qualification timelines. Industrial clusters in Shenzhen, Seoul, and Nagoya anchor component procurement authority.
China
MIIT enforcement of tightened GB electromagnetic compatibility standards is forcing industrial equipment manufacturers to upgrade isolation architectures and compress supplier qualification timelines. The regulator's certification requirements now cover network equipment vendors deploying 5G infrastructure at scale. Shenzhen manufacturing clusters concentrate surface-mount optocoupler volumes as Foxconn and Pegatron centralize procurement authority for consumer electronics power adapters.
Germany
Factory electrification initiatives are expanding procurement of galvanic isolation components for variable frequency drives and servo systems across industrial automation OEMs. ECHA authorization deadlines phasing out halogenated flame retardants are accelerating supplier audits on molding compound compliance. Bavarian machinery manufacturers are specifying REACH-compliant packages ahead of 2025 material transition phases.
Japan
Tier-one automotive suppliers are adopting hybrid optocoupler-digital isolator configurations to satisfy SPI communication at 100 Mbps alongside 5 kV isolation for battery management systems. METI efficiency mandates for industrial equipment are tightening electromagnetic compatibility requirements. Nagoya-area factory automation OEMs specify through-hole packages for servo drive replacement schedules spanning 15-20 year equipment lifecycles.
South Korea
Telecommunications backhaul deployments are absorbing high-speed optocoupler volumes as 5G infrastructure scales in Seoul manufacturing clusters. The country's national telecommunications regulator enforces certification alignment with international IEC standards for network equipment. Samsung and LG supply chain procurement is concentrating demand for surface-mount components in consumer electronics and automotive electronics applications.
United States
FCC electromagnetic interference standards govern optocoupler integration into telecommunications and industrial control equipment, with NHTSA emerging automotive-grade specifications for electric vehicle powertrains creating certification pathways. Texas and California industrial automation installations are retrofitting galvanic isolation into existing control architectures. West Coast contract manufacturers are qualifying suppliers for high-reliability refurbishment protocols in data center power infrastructure.
Integrated Circuit Optocouplers Market Competitive Landscape
Vertically integrated semiconductor fabricators and broad-line component distributors split the market along certification depth and channel reach vectors. The vendor base organizes into three strategic archetypes: captive fabrication specialists controlling replacement part availability, distributor-anchored suppliers spanning industrial repair channels, and high-reliability certification leaders targeting telecommunications infrastructure. Competitive moves center on automotive-grade specification pre-qualification and aftermarket refurbishment service expansion.
Among captive fabrication specialists, Toshiba Electronic Devices & Storage Corporation represents the vertically integrated archetype with in-house semiconductor production. Vishay Intertechnology exemplifies distributor-anchored positioning through broad industrial repair channel networks. Broadcom Inc. occupies the high-reliability tier, with specialization in telecommunications infrastructure refurbishment protocols. These three companies illustrate the competitive segmentation between fabrication control, distribution breadth, and certification depth.
| Leading Market Players |
|---|
| Toshiba Electronic Devices & Storage Corporation |
| Infineon Technologies |
| Broadcom Inc. |
| Lite-On Technology Corporation |
| Texas Instruments Incorporated |
| Vishay Intertechnology |
| ON Semiconductor Corporation |
| Everlight Electronics |
| Renesas Electronics Corporation |
| Others |
Supply & Pricing Matrix
Wafer fabrication capacity in Taiwan and South Korea concentrates upstream cost control, positioning foundry pricing as the fulcrum where margin pools shift between standard-grade commodity producers and automotive-certified specialists downstream.
Pricing Analysis
REACH and RoHS substance restrictions dictate the pricing tier structure across the Integrated Circuit Optocouplers Market, separating REACH-compliant automotive-grade packages from standard industrial variants. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden, with AEC-Q100 qualification commanding substantial premiums over IEC 60747-5-5 baseline products. Cost compression in standard-grade segments is intensifying because silicon photodiode input volatility and foundry capacity constraints squeeze margins. Consumer electronics contract manufacturers exhibit the highest price sensitivity, while German industrial automation OEMs prioritize certification compliance over unit economics.
Supply Chain Analysis
Backend assembly concentration in Shenzhen and Seoul creates geographic vulnerability to regional logistics disruptions across the Integrated Circuit Optocouplers Market supply network. Taiwan and South Korea dominate frontend wafer fabrication, while China, Japan, and Malaysia anchor backend packaging and testing operations. Raw material dependencies center on gallium arsenide substrates, gold wire bonding materials, and halogen-free molding compounds. Distribution runs through consolidated contract manufacturer procurement at Foxconn and Pegatron, displacing traditional broad-line distributor relationships in consumer electronics volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Integrated Circuit Optocouplers Market requires substitution defense against silicon dioxide-based digital isolators, which are hybridizing with traditional architectures and eroding share in high-reliability battery management applications.
For Market Incumbents: Build certification moats around emerging automotive-grade isolation voltage specifications before competitor lock-in solidifies. Deepen backward integration into gallium arsenide substrate supply to buffer wafer pricing volatility. Capture aftermarket refurbishment revenue through captive technical knowledge in isolation component replacement protocols.
For New Entrants and Emerging Players: Establish a beachhead in modular installation formats for process control systems, where maintenance-critical industries seek rapid replacement capabilities without soldering. Target through-hole technology segments serving Japanese factory automation OEMs with 15-20 year equipment lifecycles. Lead with REACH-compliant package formulations to preempt ECHA authorization deadline disqualifications.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated fabricators with in-house semiconductor production and proven high-volume delivery track records. Monitor MIIT enforcement patterns on GB electromagnetic compatibility standards as the inflection indicator for Chinese network equipment vendor qualification timelines. Long-term viability hinges on positioning ahead of hybrid optocoupler-digital isolator convergence in automotive powertrain applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Automotive-Grade Certification Investment | AEC-Q100 qualification unlocks electric vehicle powertrain procurement at tier-one Japanese and German suppliers. |
| REACH-Compliant Material Transition | ECHA authorization deadlines phase out halogenated flame retardants, forcing reformulation of package molding compounds. |
| Aftermarket Refurbishment Service Expansion | Captive technical knowledge at original manufacturers creates recurring revenue in isolation component recertification. |
| High-Speed Product Portfolio Development | Devices exceeding 50 Mbps capture margin premiums in 5G telecommunications backhaul deployments across Seoul clusters. |
| Contract Manufacturer Direct Qualification | Foxconn and Pegatron procurement centralization in Shenzhen compresses vendor lists to three qualified sources per specification. |
Research Methodology
The analysis maps high-speed, DC, AC, and RF optocoupler sub-sectors, each validated through semiconductor fabrication executives, industrial automation procurement leads, automotive tier-one supplier engineers, and telecommunications equipment designers. Primary interview intelligence triangulates against secondary sources including MIIT GB standard filings, ECHA authorization documentation, IEC certification registries, and SEC semiconductor segment disclosures. Bottom-up volume builds from contract manufacturer procurement data and foundry capacity announcements reconcile with top-down market sizing across the projection horizon.
Forecast assumptions hold fixed the current regulatory enforcement trajectory for electromagnetic compatibility standards and substance restrictions, while varying adoption rates of hybrid isolation architectures and electric vehicle powertrain electrification mandates. Segmentation dimensions modeled include product type, end-user vertical, installation technology, and application function across the analysis window. CAGRs derive from installed base replacement cycles, content-per-vehicle expansion in automotive electronics, and factory electrification capital expenditure patterns in German and Japanese industrial automation.
Stress conditions across wafer pricing volatility, foundry capacity allocation shifts, and logistics disruption scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions on MIIT enforcement continuity, ECHA authorization timeline adherence, and hybrid isolator substitution velocity in sub-5 kV applications. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Laser Projection Market
Optoelectronics
Quantum Cascade Lasers Market
Optoelectronics
Quantum Dot Solar Cell Market
Optoelectronics
Gaas Epiwafer Market
Optoelectronics
Europe Optoelectronics Market
Optoelectronics
Europe Wigig Market
Optoelectronics
Green Laser Diode Market
Optoelectronics
Heterojunction Solar Cell Market
Optoelectronics
Global Optoelectronic Components Market
Optoelectronics
Gallium Arsenide Gaas Wafer Market
Optoelectronics
Global Infrared Optoelectronics Market
Optoelectronics
China Optoelectronics Market
Optoelectronics
Algainp Epitaxial Wafers Market
Optoelectronics
Electro-Optical/Infrared (EO/IR) Systems Market
Optoelectronics
Japan Optoelectronics Market
Optoelectronics
2-Ethyl-3,4-Ethylenedioxythiophene Market