
 Genetic Analyzer Systems Market | 2026-2036
Genetic Analyzer Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Genetic Analyzer Systems Market Analytics
Instrument leasing and reagent rental agreements are tilting competitive dynamics toward vendors with captive consumables ecosystems. Thermo Fisher Scientific leverages its ion semiconductor sequencing platform to anchor long-term contracts with clinical laboratories. Illumina sustains pricing power through proprietary flow cell chemistry that locks in recurring revenue streams. QIAGEN competes by bunding sample-to-insight workflows that reduce per-run operational complexity for mid-sized research facilities.
Genetic analyzer systems are instruments that detect and record nucleic acid sequences or fragment sizes through optical, electrochemical, or fluorescent signal detection, typically resolving base pairs with accuracy thresholds exceeding 99.9% for clinical-grade platforms. These systems serve diagnostic, research, and forensic applications where nucleic acid identity determines therapeutic selection, hereditary risk profiling, or evidentiary matching. Next-generation sequencers command the largest installed base among product types, while real-time PCR systems retain dominant share in infectious disease diagnostics where turnaround time governs purchasing decisions. Sequencing by synthesis technology leads capital deployment in oncology and rare disease research, whereas capillary electrophoresis maintains utility in forensic STR analysis and confirmatory Sanger sequencing workflows where read length precision outweighs throughput scale.
The FDA's Class II special controls for NGS-based oncology panels and the EMA's In Vitro Diagnostic Regulation framework in Europe are elevating validation burdens and consolidating purchasing authority among laboratories with dedicated regulatory affairs functions. ISO 15189 accreditation requirements and CLIA certification standards in the United States further filter vendor eligibility by mandating traceable quality management systems. Stakeholders must monitor how evolving premarket review pathways for artificial intelligence-augmented variant interpretation reshape instrument software upgrade cycles and service contract structures.
Market Dynamics
The Genetic Analyzer Systems Market is experiencing structural compression as instrument vendors pivot from capital sales toward reagent rental models that lock laboratories into multi-year consumables commitments. This shift is redistributing profitability upstream and raising barriers for mid-tier competitors lacking vertically integrated chemistry portfolios.
Growth Catalysts
- Companion diagnostic mandates:FDA approvals for NGS-based oncology panels now require validated sequencing platforms, driving instrument procurement at academic medical centers pursuing clinical trial enrollment.
- ISO 15189 accreditation expansion:Clinical laboratories in Germany and France pursuing this quality standard must upgrade to traceable genetic analyzer systems with documented calibration protocols.
- Forensic database expansion:National law enforcement agencies in Brazil and India are modernizing STR analysis infrastructure to support criminal DNA registries.
Market Restraints
- Flow cell supply concentration:Proprietary consumables for high-throughput sequencers are manufactured at single-source facilities in California and Massachusetts, creating geographic vulnerability.
- Reagent cold chain requirements:Enzyme-based sequencing chemistries degrade outside controlled temperature ranges, elevating logistics costs for laboratories in tropical climates.
- EMA MDR transition friction:The In Vitro Diagnostic Regulation's stricter conformity assessment procedures are delaying market entry for new platform introductions.
Strategic Opportunities
- Point-of-care infectious disease testing:Portable real-time PCR systems are penetrating rural clinics in Indonesia and Vietnam where centralized laboratory infrastructure remains sparse.
- AI-augmented variant interpretation:Machine learning algorithms trained on population-specific allele frequencies are enabling diagnostic laboratories to reduce manual curation time for rare disease cases.
- CE marking mutual recognition:The EU-Switzerland MRA facilitates simultaneous market access across 27 member states plus Swissmedic jurisdictions for validated IVD platforms.
Industry Challenges
- Bioinformatics specialist scarcity:Clinical laboratories report 18-month recruitment cycles for variant scientists capable of interpreting complex structural variants in hereditary cancer panels.
- CLIA certification timelines:High-complexity molecular testing accreditation requires documented proficiency testing that extends instrument deployment schedules by 9-14 months.
- Legacy Sanger integration:Research facilities maintaining capillary electrophoresis workflows face software incompatibility when attempting to merge data formats with next-generation sequencing outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Genetic Analyzer Systems Market |
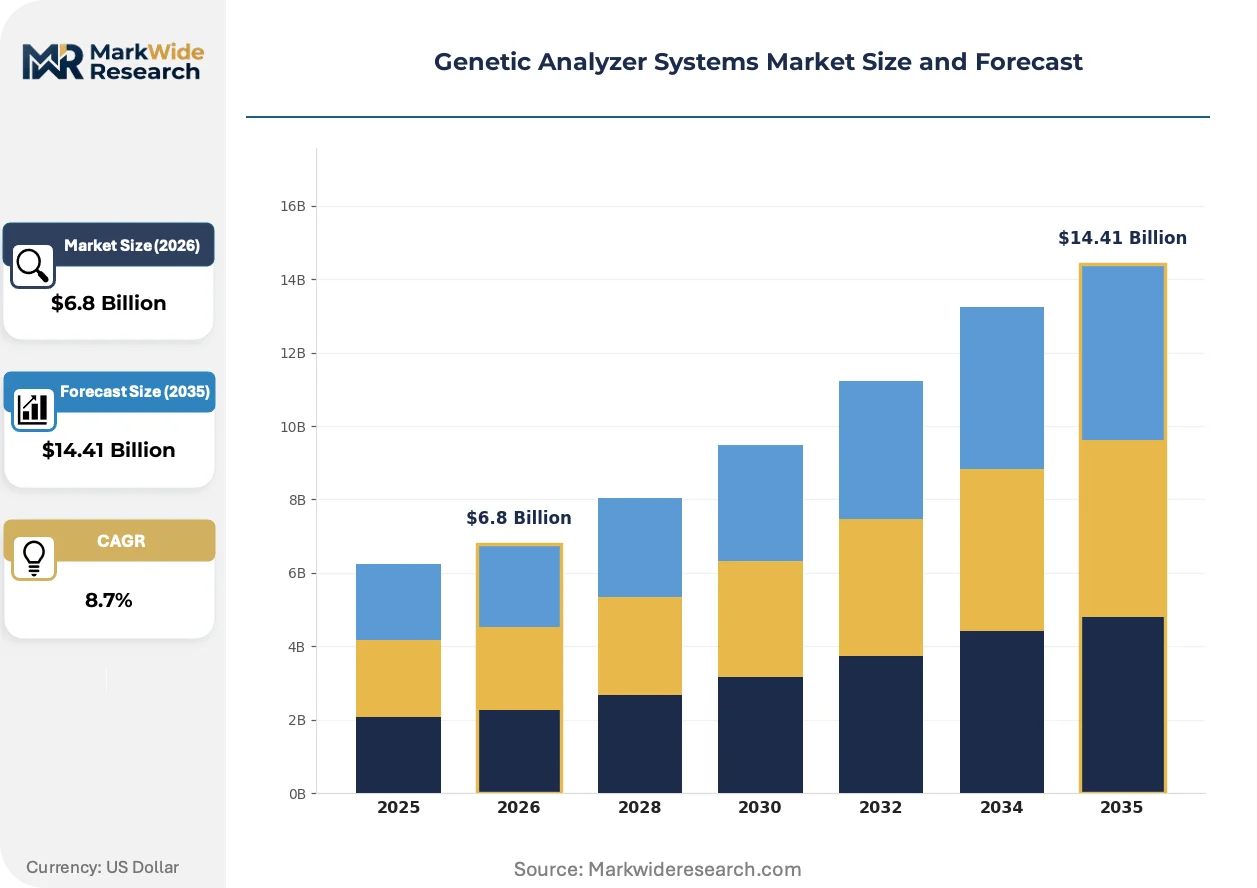
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sanger Sequencers, Next-Generation Sequencers, Real-Time PCR Systems, Fragment Analyzers Technology: Capillary Electrophoresis, Sequencing by Synthesis, Ion Semiconductor Sequencing, Pyrosequencing Application: Clinical Research, Forensic Testing, Agriculture, Diagnostics End User: Academic Institutions, Pharmaceutical Companies, Clinical Laboratories, Biotech Firms |
| Companies Covered | Thermo Fisher Scientific, Illumina, F. Hoffmann-La Roche, Danaher Corporation, Agilent Technologies, Bio-Rad Laboratories, QIAGEN, PerkinElmer, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Genetic Analyzer Systems Market Evolving Landscape
Sequencing technology is fragmenting into specialized modalities optimized for specific clinical decision points rather than universal platforms. This specialization is compressing instrument replacement cycles and fragmenting vendor market power across distinct application verticals.
Long-read sequencing technology is migrating from research-only installations toward clinical validation laboratories pursuing definitive resolution of complex structural variants. Pediatric genetic testing centers in Boston and San Francisco are adopting these platforms to reduce diagnostic odyssey duration for rare disease patients. The structural consequence is a bifurcation in instrument procurement: short-read systems for high-volume screening, long-read systems for definitive diagnosis.
The FDA's classification of artificial intelligence-augmented variant calling software as Class II medical devices is imposing premarket validation requirements on sequencer firmware updates. Diagnostic laboratories must now document algorithm version control in quality management systems. Oncology-focused facilities in the United States are responding by negotiating service contracts that guarantee regulatory-compliant software maintenance.
Instrument leasing arrangements are displacing outright purchase as the dominant procurement mechanism among mid-sized clinical laboratories. Reagent rental agreements bundle consumables, service, and software access into per-run pricing that converts capital expenditure to operational budgets. This pattern is most visible among community hospital laboratories in Texas and Florida seeking to preserve balance sheet capacity for EMR investments.
Genetic Analyzer Systems Market Segmentation
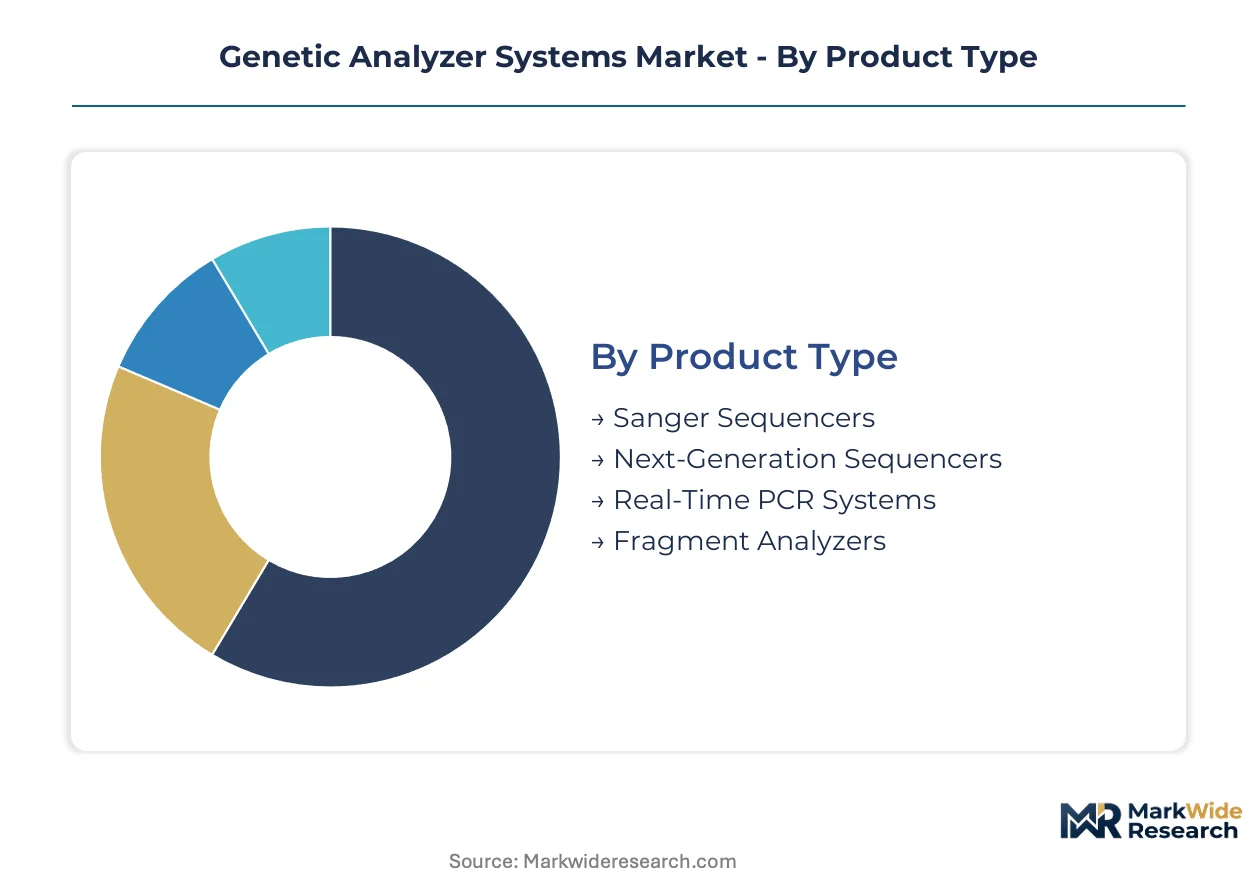
Genetic analyzer procurement patterns diverge sharply across product architectures and end-use settings. Laboratories select platforms based on throughput requirements, regulatory validation status, and consumables lock-in economics rather than capital cost alone.
Product Type:
Cost tier determines accessibility and operational commitment levels across laboratory budgets.
- Next-Generation Sequencers:High-throughput platforms utilizing massively parallel sequencing chemistry to generate terabase-scale outputs per run. Academic medical centers in Boston and San Francisco deploy these systems for oncology companion diagnostic workflows where panel breadth governs clinical trial eligibility.
- Real-Time PCR Systems:Quantitative amplification platforms detecting nucleic acid accumulation through fluorescent probe hydrolysis in each thermal cycle. Infectious disease laboratories in Texas and Florida favor these instruments for respiratory pathogen panels where two-hour turnaround times determine therapeutic decisions.
- Sanger Sequencers:Capillary electrophoresis-based instruments resolving individual nucleotide incorporations through dye terminator chemistry. Confirmatory testing facilities employ these systems for variant verification where read length precision exceeds throughput requirements.
- Fragment Analyzers:Microfluidic separation systems sizing nucleic acid fragments through gel matrix migration. Agricultural biotechnology stations utilize these platforms for marker-assisted breeding programs requiring rapid genotype screening.
Next-Generation Sequencers hold installed capacity. Real-Time PCR Systems is rotating up the share rankings.
Technology:
Application specificity drives technology selection more than universal platform performance.
- Sequencing by Synthesis:Reversible terminator chemistry enabling simultaneous detection of millions of clonal DNA clusters through fluorescent imaging. Oncology-focused laboratories in Germany deploy this technology for tumor mutational burden profiling under EMA IVD Regulation compliance frameworks.
- Ion Semiconductor Sequencing:pH-sensitive detection of hydrogen ion release during nucleotide incorporation without optical components. Mid-sized clinical laboratories in Florida favor this approach for amplicon-based panels where reagent rental agreements reduce per-run cost variability.
- Capillary Electrophoresis:Electric field-driven separation of DNA fragments through polymer matrices with single-base resolution. Forensic laboratories in Brazil maintain this technology for CODIS-compatible STR analysis where allele calling standards mandate established protocols.
- Pyrosequencing:Luciferase-based detection of pyrophosphate release during DNA polymerization. Research facilities employ this method for methylation analysis applications requiring quantitative CpG site interrogation.
Sequencing by Synthesis dominates capital deployment. Ion Semiconductor Sequencing is climbing the fastest among clinical adopters.
Application:
Customer workflow complexity varies dramatically across diagnostic versus research use cases.
- Diagnostics:Regulatory-validated testing workflows generating patient-actionable variant reports with documented analytical performance. CLIA-certified laboratories in California process hereditary cancer panels under FDA Class II special controls for NGS-based assays.
- Clinical Research:Prospective specimen analysis supporting therapeutic development without diagnostic claims. Pharmaceutical sponsors in Massachusetts require sequencing platforms with 21 CFR Part 11 compliant audit trails for regulatory submission packages.
- Forensic Testing:DNA profiling for human identification through STR locus amplification and comparative database searching. National law enforcement agencies in India modernize this infrastructure for criminal registry expansion.
- Agriculture:Genomic selection and trait mapping for crop improvement and livestock breeding programs. Seed companies deploy marker-assisted selection platforms to accelerate varietal development cycles.
Diagnostics commands premium pricing. Clinical Research is expanding most quickly as trial complexity intensifies.
End User:
Procurement authority concentrates differently across institutional budget structures and regulatory sophistication.
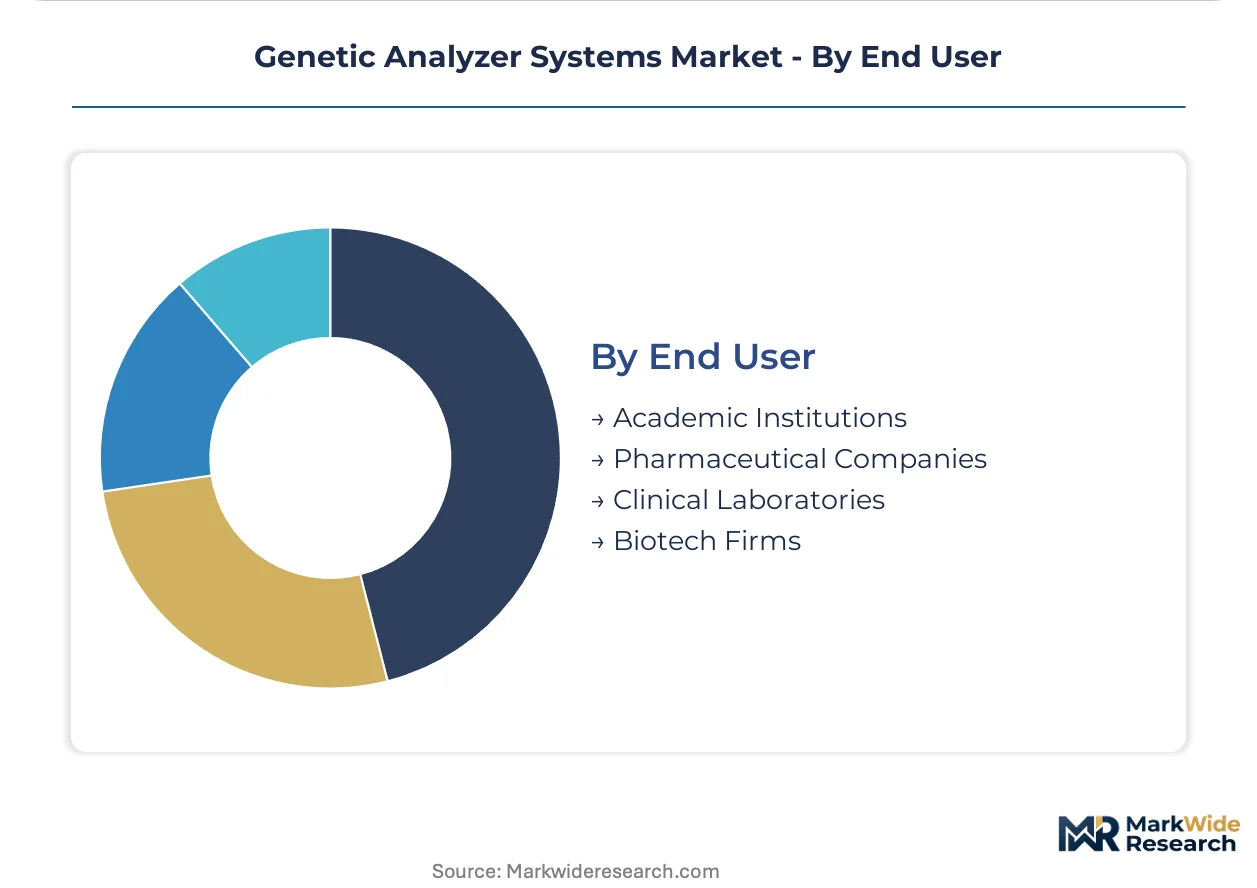
- Clinical Laboratories:Patient-facing diagnostic facilities requiring accredited quality management systems and proficiency testing documentation. Hospital-based laboratories in France pursue ISO 15189 accreditation mandating traceable instrument calibration protocols.
- Academic Institutions:Research universities with diverse funding streams spanning federal grants and institutional support. Genome centers in California maintain mixed instrument fleets serving both basic science and fee-for-service operations.
- Pharmaceutical Companies:Drug developers integrating biomarker strategies into clinical trial design and companion diagnostic co-development. Biotech clusters in Boston anchor sequencing procurement for precision oncology pipelines.
- Biotech Firms:Venture-backed developers of nucleic acid-based therapeutics and diagnostic platforms. Emerging companies in San Francisco leverage reagent rental agreements to preserve capital for platform development.
Clinical Laboratories concentrate purchasing volume. Biotech Firms are gaining share fastest among emerging segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where academic medical centers absorb premium instrument costs, while laboratories in India and Brazil face compressed margins due to import duties and cold chain logistics burdens.
United States
FDA Class II special controls for NGS-based oncology panels mandate validated sequencing platforms at academic medical centers pursuing clinical trial enrollment. CLIA certification requirements for high-complexity molecular testing extend instrument deployment timelines by 9-14 months. The Boston biotech cluster anchors procurement for precision oncology pipelines, while San Francisco Bay Area facilities drive adoption of long-read systems for rare disease diagnosis.
Germany
ISO 15189 accreditation expansion requires clinical laboratories to upgrade to traceable genetic analyzer systems with documented calibration protocols. EMA IVD Regulation frameworks elevate validation burdens for NGS-based tumor mutational burden profiling. The Rhine-Ruhr metropolitan region concentrates instrument procurement among hospital networks modernizing pathology infrastructure under national cancer plan mandates.
China
NMPA medical device registration pathways for gene sequencing instruments are shortening review cycles for domestic manufacturers while maintaining stringent requirements for imported platforms. The country's national pharmaceutical regulator prioritizes local production of high-throughput sequencers under strategic industry development programs. The Yangtze River Delta anchors manufacturing clusters for sequencing consumables serving both domestic demand and export markets.
Brazil
National law enforcement agencies are modernizing STR analysis infrastructure to support criminal DNA registry expansion under federal public security initiatives. ANVISA medical device registration requirements for diagnostic sequencers create compliance barriers for mid-sized clinical laboratories. São Paulo state concentrates procurement among forensic institutes and agricultural biotechnology stations deploying marker-assisted breeding platforms.
India
CDSCO medical device rules for in vitro diagnostics are tightening quality benchmarks for imported sequencing platforms while exempting certain research-grade instruments. The country's national pharmaceutical regulator mandates local clinical validation studies for companion diagnostic approvals. Genome centers in Karnataka and Maharashtra are expanding sequencing capacity to support pharmaceutical contract research operations.
Genetic Analyzer Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in reagent and consumables supply. The vendor base stratifies into three tiers: multinational conglomerates with captive chemistry portfolios, mid-sized specialists bunding sample-to-insight workflows, and regional distributors serving price-sensitive installations. Consolidation pressure intensifies as reagent rental models redistribute profitability toward consumables ecosystems. Dominant competitive moves include backward integration into proprietary flow cell manufacturing and strategic partnerships for AI-augmented variant interpretation software.
Among diversified life sciences conglomerates, Thermo Fisher Scientific and Danaher Corporation exemplify platform integrators leveraging ion semiconductor and capillary electrophoresis architectures respectively. Illumina occupies a position as the archetypal sequencing chemistry incumbent with proprietary flow cell ecosystems. QIAGEN represents the mid-tier specialist model, bunding nucleic acid preparation workflows that reduce operational complexity for research facilities lacking dedicated bioinformatics staff.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Illumina |
| F. Hoffmann-La Roche |
| Danaher Corporation |
| Agilent Technologies |
| Bio-Rad Laboratories |
| QIAGEN |
| PerkinElmer |
| Abbott Laboratories |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese sequencing consumables manufacturing is compressing reagent pricing while simultaneously triggering quality-tier stratification among procurement officers at CLIA-certified laboratories. This utilization imbalance rewards vendors with captive flow cell production in Massachusetts and California while forcing mid-tier competitors toward reagent rental concessions.
Pricing Analysis
The customization-premium spread separates standard per-run pricing from configured-to-order sequencing workflows that bundle bioinformatics interpretation and regulatory documentation. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 15189 accreditation status and FDA Class II validation tier rather than raw instrument throughput. Cost compression in economy-tier reagent rentals is intensifying because Chinese manufacturers are flooding Southeast Asian distribution channels with unbundled sequencing chemistries. Academic medical centers in Boston demonstrate the least price sensitivity due to grant-funded procurement, while community hospital laboratories in Florida face acute budget constraints driving aggressive reagent rental negotiation.
Supply Chain Analysis
Export-control regimes limiting semiconductor-grade optical sensors and precision fluidics components constrain instrument manufacturing scalability for non-US vendors. Proprietary flow cell manufacturing concentrates in California and Massachusetts, while enzyme reagent production clusters in China's Yangtze River Delta. Supply chain vulnerability hinges on single-source cold chain logistics for temperature-sensitive sequencing chemistries, with distribution running through regional clinical laboratory distributors rather than direct vendor relationships. Tariff exposure on Chinese-sourced reagents is elevating landed costs for European and Latin American laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Genetic analyzer systems penetration remains early-cycle in mid-sized clinical laboratories and emerging economy forensic infrastructure, with companion diagnostic mandates and ISO 15189 accreditation expansion providing durable tailwinds through the projection horizon.
For Market Incumbents: Pre-empt reagent rental model disruption by locking multi-year consumables commitments with community hospital laboratories before emerging competitors achieve CLIA certification timelines. Backward integration into proprietary flow cell manufacturing in Massachusetts insulates margin structures against Chinese reagent pricing pressure. Prioritize firmware update service contracts that guarantee FDA-compliant AI-augmented variant interpretation software maintenance. For New Entrants and Emerging Players: Mid-sized clinical laboratories in Texas and Florida pursuing EMR investments represent the most penetrable entry point for reagent rental agreements that convert capital expenditure to operational budgets. Point-of-care infectious disease testing in rural Indonesian and Vietnamese clinics offers white-space expansion where centralized laboratory infrastructure remains sparse. Lead with portable real-time PCR systems bundled with simplified sample-to-insight workflows that reduce per-run operational complexity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across reagent rental-dependent business models as consumables economics displace instrument sales. Five-to-ten-year viability favors platform integrators with captive chemistry portfolios over pure-play hardware vendors exposed to flow cell supply concentration risks. Monitor EMA MDR transition friction as an inflection signal: delayed market entry timelines for new platform introductions will accelerate consolidation toward established regulatory affairs functions.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Rental Agreement Expansion | Converts capital expenditure to operational budgets for mid-sized clinical laboratories in Texas and Florida. |
| Proprietary Flow Cell Manufacturing | Insulates margin structures against Chinese reagent pricing pressure and supply chain vulnerability. |
| AI-Augmented Variant Interpretation Software | Addresses bioinformatics specialist scarcity reducing manual curation time for rare disease cases. |
| Point-of-Care Platform Development | Penetrates rural clinics in Indonesia and Vietnam where centralized laboratory infrastructure remains sparse. |
| ISO 15189 Accreditation Support Services | Captures laboratories in Germany and France pursuing quality standards mandating traceable instrument calibration. |
Research Methodology
Operator-level perspectives from clinical laboratory directors, biomedical engineers, regulatory affairs specialists, and GPO contracts managers anchored the qualitative base for this analysis. Primary interviews with hospital purchasing committees and sequencing platform engineers combined with secondary validation against FDA 510(k) filings, EMA IVD Regulation guidance documents, CLIA certification databases, and ISO 15189 accreditation registries. Bottom-up instrument installation counts and top-down reagent consumption estimates underwent triangulation to resolve segmentation discrepancies.
Scenario-bracketing around regulatory approval timelines and adoption curve steepness informed the analytical framework across the analysis window. Segmentation dimensions modeled include product architecture, technology chemistry, application workflow, and end-user institutional type. CAGRs derived from instrument replacement cycle analysis and consumables attach-rate projections incorporated EMA MDR transition friction and NMPA domestic manufacturing incentives as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in grant funding cycles for academic medical centers or cold chain logistics costs in tropical climates would shift the trajectory. Material shifts in FDA premarket review pathways for artificial intelligence-augmented variant interpretation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Biomaterial Tester Market
Biotechnology Equipment
Cell Proliferation Kit Market
Biotechnology Equipment
Biobanking Equipment Market
Biotechnology Equipment
Upstream Bioprocessing Equipment Market
Biotechnology Equipment
Tissue Microarrayer Market
Biotechnology Equipment
United States Transfection Technologies Market
Biotechnology Equipment
Botanical Extraction Equipment Market
Biotechnology Equipment
Cellular Localization Kits Market
Biotechnology Equipment
Global Automated Biochemical Analyzer Market
Biotechnology Equipment
Global Biotechnology Instruments Market
Biotechnology Equipment
Cryopreservation Equipment Market
Biotechnology Equipment
Global Latex Agglutination Test Kits Market
Biotechnology Equipment
Fermentation Equipment Market
Biotechnology Equipment
Latin America Protein Purification and Isolation Market
Biotechnology Equipment
Global Plant Cell Culture Equipment Market
Biotechnology Equipment
Automated Molecular Diagnostics Testing System Market