
 Biosurgery Equipment Market | 2026-2036
Biosurgery Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Biosurgery Equipment Market Outlook
Ambulatory surgical centers is bifurcating demand away from traditional hospital procurement channels. Johnson & Johnson Services, Inc leverages its broad hemostat portfolio to serve both inpatient and outpatient settings. Baxter anchors its position through synthetic polymer expertise in surgical sealants. Medtronic competes with concentrated R&D investment in bioresorbable adhesion barriers.
Biosurgery equipment encompasses implantable and topical agents engineered to control bleeding, prevent tissue adhesion, or seal surgical wounds, typically formulated from fibrinogen-thrombin combinations, oxidized cellulose, or synthetic polyethylene glycol hydrogels with specified absorption profiles ranging from 24 hours to 30 days. These products serve to reduce operative time, minimize postoperative complications, and eliminate the need for mechanical interventions in open and minimally invasive procedures. Surgical sealants lead technology revenue within biological conjugates due to premium pricing in cardiovascular applications. Hemostats dominate volume throughput in trauma settings where rapid deployment determines clinical outcomes. Adhesion barriers command concentrated margins in gynecologic and abdominal surgery despite narrower procedural penetration.
The FDA enforces 510(k) and PMA pathways for hemostats and sealants, while the EU Medical Device Regulation mandates clinical evidence upgrades under MDR transition timelines that extend compliance burdens for manufacturers. ISO 10993 biocompatibility testing standards govern material safety validation across both jurisdictions, directly influencing product development cycles and market access speed. Stakeholders must monitor reimbursement parity between inpatient and outpatient biosurgery procedures as site-of-care economics reshape purchasing authority.
Market Dynamics
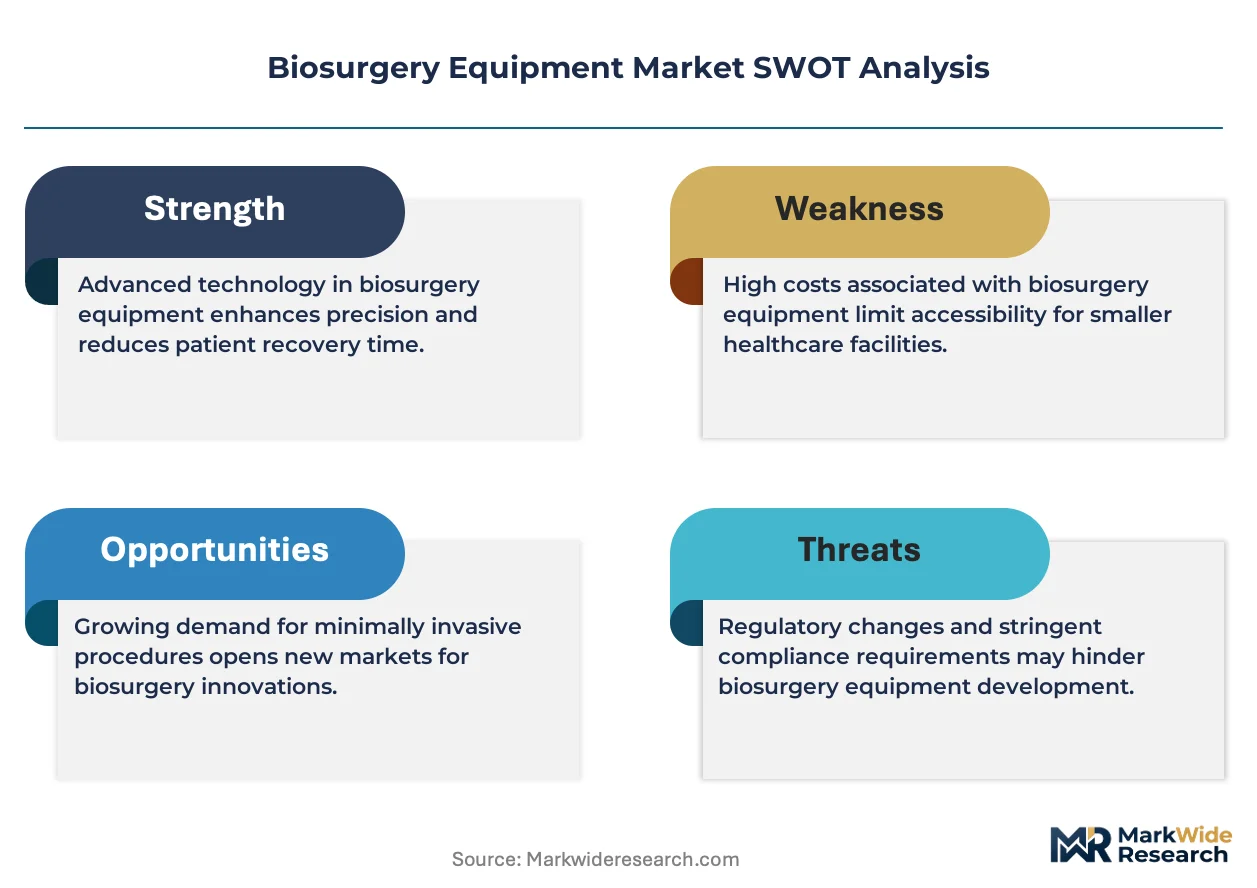
The FDA's tightened hemostat biocompatibility standards are compressing product development timelines while simultaneously elevating barriers to market entry for synthetic polymer formulations. This regulatory pressure is forcing manufacturers to revalidate absorption profiles and thrombin sourcing protocols across entire portfolios.
Growth Catalysts
- Ambulatory Surgical Center Expansion:Outpatient procedure volume in United States integrated delivery networks is accelerating demand for rapid-deployment hemostats that reduce operative time without inpatient monitoring infrastructure.
- EU MDR Clinical Evidence Mandate:The Medical Device Regulation's upgraded clinical evidence requirements for surgical sealants is creating competitive separation between manufacturers with robust trial data and those dependent on predicate devices.
- Fibrinogen-Thrombin Formulation Advances:Concentrated R&D investment in recombinant thrombin sourcing is improving lot-to-lot consistency and reducing immunogenicity risk in cardiovascular applications.
Market Restraints
- Bovine-Derived Material Sourcing:Concentrated reliance on bovine fibrinogen from limited geographies exposes supply chains to transmissible spongiform encephalopathy screening disruptions and export restrictions.
- Synthetic Polymer Cost Structure:Polyethylene glycol hydrogel raw material volatility and specialized manufacturing equipment requirements compress margins for sealant producers outside high-volume cardiovascular segments.
- Mechanical Hemostasis Substitution:Advanced electrocautery devices and ultrasonic scalpels in laparoscopic procedures reduce addressable procedure volume for topical hemostat application.
Strategic Opportunities
- Pediatric and Neonatal Surgery:Underpenetrated demand for low-dose, rapid-absorption hemostats in congenital cardiac repair presents formulation development white space with premium pricing tolerance.
- India Central Government Health Scheme:Ayushman Bharat's expansion of reimbursed surgical procedures in tier-2 and tier-3 cities creates first-mover advantage for manufacturers establishing domestic production.
- Bioresorbable Adhesion Barrier Convergence:Integration of anti-adhesion properties with antimicrobial loading is opening gynecologic and abdominal surgery segments previously resistant to standalone barrier products.
Industry Challenges
- ISO 10993-5 Cytotoxicity Testing Bottlenecks:Backlogs at contracted testing laboratories extend pre-submission timelines by six to nine months for novel material formulations.
- Legacy Hospital Inventory Integration:New sealant delivery systems require compatibility validation with existing OR storage, warming protocols, and nursing workflow patterns, slowing adoption velocity.
- Thrombin Patent Landscape Complexity:Dense overlapping intellectual property around recombinant production methods forces licensing negotiations or costly workarounds for second-generation entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biosurgery Equipment Market |
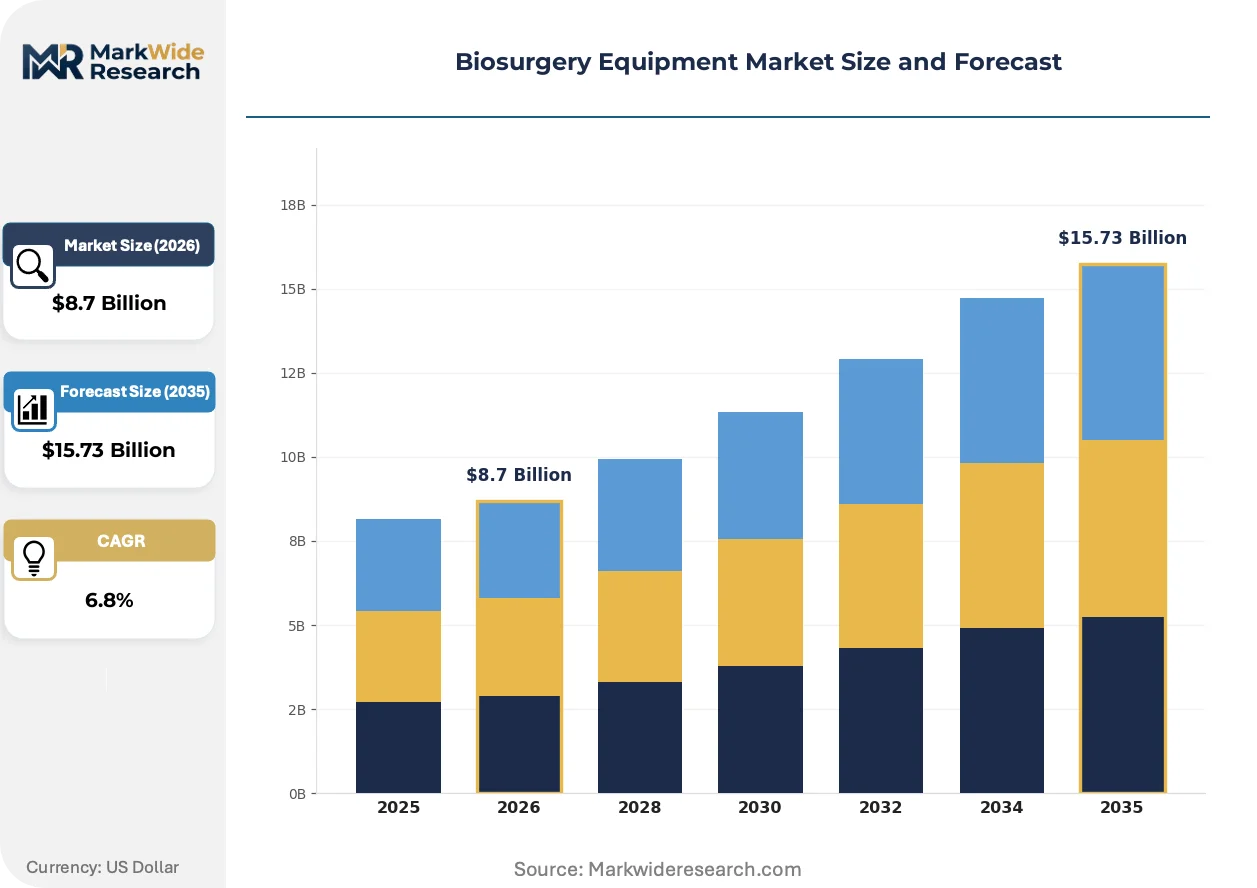
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Sealants, Hemostats, Adhesion Barriers, Sutures Technology: Biological Conjugates, Synthetic Polymers, Natural Polymers, Chemical Agents Application: Wound Care, Orthopedic Surgery, Cardiovascular Surgery, Neurosurgery End User: Hospitals, Ambulatory Surgical Centers, Trauma Centers, Specialty Clinics |
| Companies Covered | Johnson & Johnson Services, Inc, Baxter, Medtronic, BD, INTEGRA LIFESCIENCES, Stryker, B. Braun SE, Sanofi, Pfizer Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biosurgery Equipment Market Strategic Shifts
Bioresorbable material science is actively compressing the performance gap between synthetic and biological sealants while regulatory convergence between FDA and EU MDR pathways is harmonizing evidence requirements. These forces are reshaping competitive positioning around clinical data depth rather than formulation origin alone.
Flowable hemostatic matrices incorporating oxidized cellulose and gelatin sponges are bifurcating the trauma segment from traditional gauze-based mechanical compression. Emergency departments in United States Level I trauma centers are adopting these products for rapid hemorrhage control in penetrating injury cases. This technology is bifurcating procurement decisions between speed-of-application and cost-per-unit metrics that previously favored commodity gauze.
The EU Medical Device Regulation's extended transition timelines for Class III surgical sealants are forcing manufacturers to upgrade post-market surveillance systems and clinical follow-up protocols. Economic operators now face mandatory summary of safety and clinical performance documentation that elevates compliance costs disproportionately for smaller portfolio holders. Cardiovascular sealant categories bear the heaviest documentation burden due to their critical performance classification and extended implantation duration.
Site-of-care economics are consolidating purchasing authority within United States integrated delivery networks that negotiate centralized contracts spanning inpatient and ambulatory settings. Hospital supply chain directors now demand unit-dose packaging and standardized warming protocols that function across OR and ASC environments without workflow modification. This concentration is most visible in cardiovascular service lines where sealant consumption volume justifies direct manufacturer partnerships bypassing traditional distribution intermediaries.
Biosurgery Equipment Market Segmentation
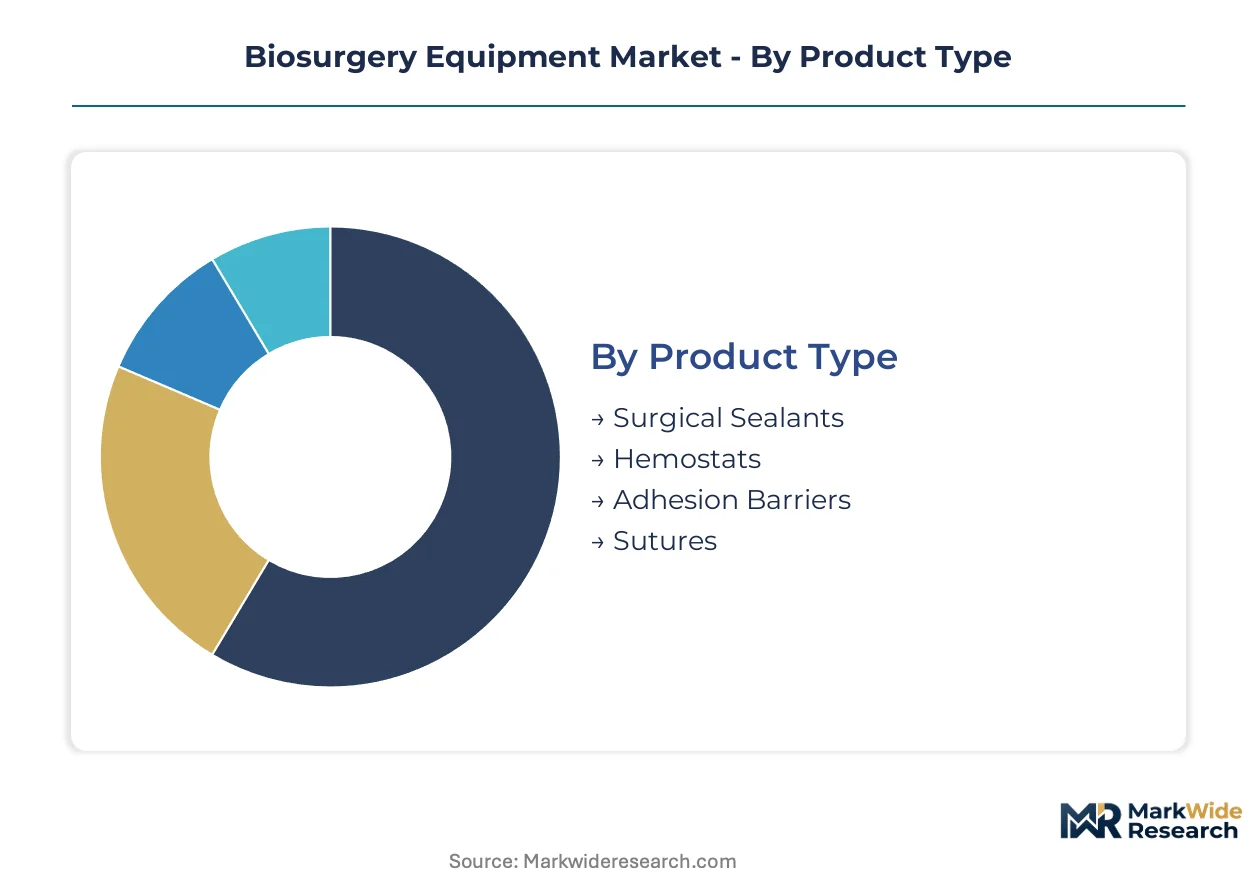
Segmentation in biosurgery equipment reveals how substitute technologies and site-of-care economics reshape procurement priorities across product categories. Manufacturers must align formulation portfolios with the specific performance thresholds and reimbursement pathways governing each segment.
Product Type:
Mechanical hemostasis methods exert substitution pressure unevenly across product categories, with electrocautery and ultrasonic devices displacing topical agents most aggressively in laparoscopic settings.
- Surgical Sealants:Polyethylene glycol hydrogels and fibrinogen-thrombin combinations form mechanical barriers across tissue planes. Demand concentrates in United States cardiovascular service lines where integrated delivery networks negotiate direct manufacturer contracts for high-volume consumption.
- Hemostats:Oxidized cellulose, gelatin sponges, and flowable matrices accelerate coagulation at bleeding sites. Trauma centers in United States Level I facilities drive volume for rapid-deployment formats that compress hemorrhage control time without mechanical compression infrastructure.
- Adhesion Barriers:Bioresorbable films and gels prevent postoperative tissue adherence. Gynecologic and abdominal surgery applications in specialty clinics command premium pricing despite narrower procedural penetration relative to sealants.
- Sutures:Traditional mechanical wound closure retains dominance in superficial tissue approximation. Cost sensitivity in ambulatory settings limits biosurgical substitution for this established category.
Hemostats retain volume leadership across acute care settings; surgical sealants hold the steepest expansion curve as cardiovascular procedure complexity escalates.
Technology:
Cost tier stratification separates premium biological formulations from commodity synthetic alternatives, with reimbursement parity determining competitive viability across hospital and outpatient channels.
- Biological Conjugates:Fibrinogen-thrombin systems derived from human or bovine plasma deliver physiological hemostasis. Cardiovascular surgery in United States academic medical centers demands these formulations despite raw material volatility and immunogenicity screening requirements.
- Synthetic Polymers:Polyethylene glycol and cyanoacrylate platforms offer tunable absorption profiles and reduced infection risk. Cost compression in trauma center procurement favors these alternatives where rapid deployment outweighs biological performance advantages.
- Natural Polymers:Collagen, gelatin, and polysaccharide matrices provide absorbable scaffolding for cellular infiltration. Orthopedic applications in specialty clinics leverage these materials for bone hemostasis and soft tissue repair.
- Chemical Agents:Oxidized cellulose and mineral-based compounds trigger passive hemostasis through physical properties. Sustained demand in wound care settings supports this lowest-cost technology tier.
Synthetic polymers dominate trauma and emergency volume; biological conjugates capture the highest value per procedure in cardiovascular applications.
Application:
Customer type concentration varies sharply by surgical specialty, with cardiovascular and orthopedic service lines representing the most consolidated purchasing authority within integrated delivery networks.
- Wound Care:Topical hemostats and sealants manage external and internal bleeding across trauma and surgical indications. United States emergency departments favor flowable matrix formats that integrate with existing wound management protocols.
- Orthopedic Surgery:Bone wax alternatives and fibrin sealants control bleeding in joint replacement and spinal procedures. Ambulatory surgical centers in United States metropolitan markets drive demand for rapid-absorption formulations that eliminate postoperative monitoring requirements.
- Cardiovascular Surgery:High-performance sealants prevent anastomotic bleeding in coronary bypass and valve replacement. Academic medical centers with concentrated procedural volume negotiate supply contracts directly with manufacturers.
- Neurosurgery:Low-swell, rapid-gelation sealants prevent cerebrospinal fluid leakage and control dural bleeding. Stringent biocompatibility requirements limit eligible suppliers in this highest-regulation application segment.
Cardiovascular surgery commands premium technology adoption; wound care applications expand most quickly across site-of-care migration.
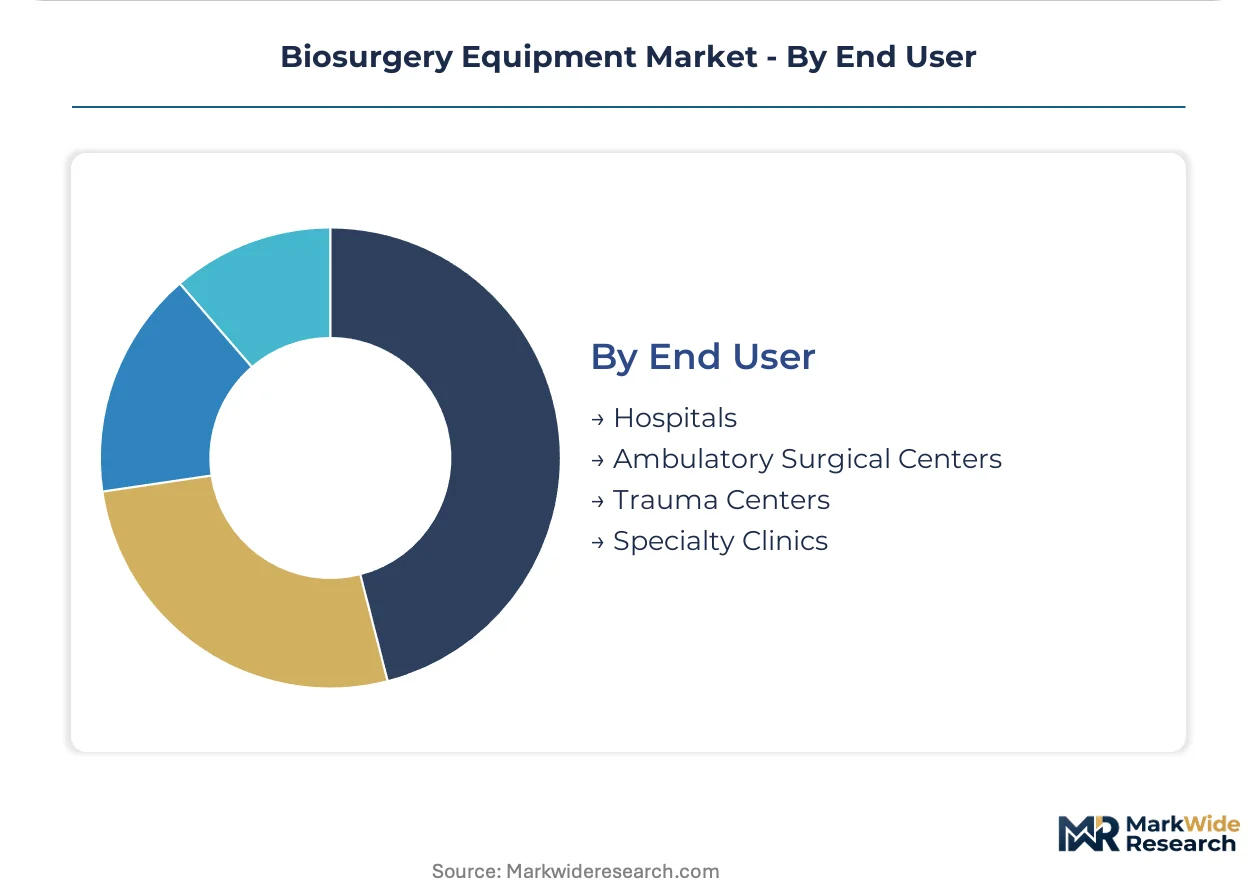
End User:
Geography-based purchasing authority consolidation reshapes distribution requirements, with metropolitan integrated delivery networks exerting disproportionate influence over manufacturer contract terms.
- Hospitals:Inpatient surgical departments maintain diversified biosurgery portfolios across service lines. Legacy inventory systems and nursing workflow patterns slow adoption velocity for novel delivery formats despite clinical evidence advantages.
- Ambulatory Surgical Centers:Outpatient procedure volume accelerates demand for unit-dose packaging and standardized warming protocols. United States ASC networks negotiate centralized procurement contracts that span cardiovascular and orthopedic service lines.
- Trauma Centers:Level I facilities prioritize speed-of-application metrics in hemorrhage control product selection. Emergency department protocols favor flowable hemostatic matrices over traditional mechanical compression for penetrating injury cases.
- Specialty Clinics:Concentrated procedural focus in gynecology, urology, and ophthalmology drives niche formulation demand. Reimbursement parity between inpatient and outpatient settings determines biosurgical substitution economics for these lower-volume purchasers.
Hospitals retain volume leadership across product categories; ambulatory surgical centers climb the fastest as outpatient migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated delivery networks in the United States concentrate purchasing authority for advanced surgical sealants, while ambulatory surgical centers across Germany and Japan reshape procurement patterns through centralized outpatient contracts.
United States
Academic medical centers in Boston and Houston drive demand for high-performance cardiovascular sealants with direct manufacturer contracting. FDA's tightened 510(k) biocompatibility standards force revalidation of thrombin sourcing protocols across entire portfolios. The Cleveland Clinic and Mayo Clinic anchor procurement concentration in the Midwest, negotiating supply agreements that span inpatient and ambulatory service lines.
Germany
University hospitals in Munich and Heidelberg prioritize biological conjugates for complex cardiac procedures despite raw material volatility. EU MDR clinical evidence mandates create competitive separation between manufacturers with robust trial data and predicate-dependent entrants. The Rhine-Ruhr industrial corridor hosts specialized testing laboratories serving ISO 10993 validation requirements for synthetic polymer formulations.
Japan
PMDA's alignment with international biocompatibility standards accelerates market access for recombinant thrombin products in Tokyo and Osaka metropolitan areas. Aging demographics expand orthopedic biosurgery demand in Kansai region ambulatory centers. Nagoya's medical device cluster concentrates R&D investment in bioresorbable adhesion barriers for gynecologic applications.
India
Ayushman Bharat's expansion of reimbursed surgical procedures in tier-2 cities creates first-mover advantage for domestic production investments. CDSCO's streamlined medical device registration under the 2017 rules reduces entry timelines for hemostat manufacturers. Maharashtra and Gujarat host emerging distribution hubs serving private hospital chains in Mumbai and Ahmedabad with rapid-deployment trauma products.
China
NMPA's updated medical device classification rules elevate clinical evidence requirements for Class III surgical sealants in Beijing and Shanghai. Domestic manufacturers in the Yangtze River Delta scale oxidized cellulose production for wound care applications. Shenzhen's precision manufacturing base supplies automated delivery systems for laparoscopic hemostat deployment.
Biosurgery Equipment Market Competitive Environment
Player mix skews toward diversified medical technology conglomerates with broad hemostat portfolios serving multiple surgical specialties. Market structure concentrates around three to five dominant suppliers controlling cardiovascular and trauma segments through integrated delivery network contracts. Strategic archetypes include biological sourcing specialists, synthetic polymer innovators, and full-line surgical solution providers. Competitive moves center on M&A for thrombin patent access and capacity expansion for recombinant production facilities.
Within the diversified conglomerate tier, Johnson & Johnson Services, Inc and Baxter occupy positions defined by breadth of hemostat and sealant offerings across inpatient and outpatient channels. Medtronic exemplifies the R&D-intensive archetype with concentrated investment in bioresorbable adhesion barriers. These three entities anchor competitive dynamics around clinical evidence generation and direct contracting with United States integrated delivery networks, while smaller specialists compete on niche formulation development.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc |
| Baxter |
| Medtronic |
| BD |
| INTEGRA LIFESCIENCES |
| Stryker |
| B. Braun SE |
| Sanofi |
| Pfizer Inc |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day thrombin sourcing lead times from bovine plasma collection to finished hemostat formulation compress pricing power for manufacturers without captive recombinant production capacity. This inventory band concentrates margin pressure on second-tier suppliers dependent on spot-market fibrinogen while integrated delivery networks exploit procurement consolidation to extract volume discounts across cardiovascular sealant portfolios.
Pricing Analysis
Next-generation recombinant thrombin formulations command three-to-four-fold premiums over prior-generation bovine-derived alternatives, while economy-tier oxidized cellulose hemostats face persistent cost compression. Three-tier pricing structure across premium, standard, and economy levels stratifies by biocompatibility certification grade and absorption profile precision. Pricing pressure stems from mechanical hemostasis substitution in laparoscopic settings as electrocautery devices displace topical agents. Ambulatory surgical centers exhibit highest price sensitivity due to reimbursement parity constraints, while academic medical centers tolerate premium biological conjugates for complex cardiovascular applications.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for European manufacturers sourcing bovine fibrinogen from South American collection facilities. Supply concentration centers on United States recombinant thrombin production, Chinese oxidized cellulose manufacturing, and German precision polymer synthesis for sealant hydrogels. Raw material dependencies encompass bovine plasma derivatives, pharmaceutical-grade polyethylene glycol, and gelatin sponges from porcine sources. Single-source vulnerability in recombinant thrombin patent licensing creates supply continuity risk. Distribution runs through integrated delivery network direct contracts bypassing traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through United States integrated delivery network procurement consolidation, fragmenting traditional hospital purchasing autonomy into centralized contract negotiation.
For Market Incumbents: Consolidate thrombin sourcing through backward integration into recombinant production facilities or exclusive plasma collection agreements. Defensive patent licensing around recombinant production methods neutralizes emerging entrant threats. Capacity addition in United States Midwest production corridors secures supply continuity against bovine-derived material export restrictions. Channel control through direct IDN partnerships insulates margin position from distributor disintermediation. For New Entrants and Emerging Players: Pediatric formulation gaps where incumbents under-serve congenital cardiac repair present accessible white-space entry points. India tier-2 city penetration under Ayushman Bharat expansion offers lowest competitive density for rapid-deployment hemostats. Bioresorbable adhesion barrier integration with antimicrobial loading captures gynecologic surgery segments resistant to standalone products. Go-to-market execution through domestic production partnerships accelerates CDSCO registration timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates with under-monetized hemostat divisions lacking IDN direct contracting infrastructure. Long-term viability favors manufacturers with recombinant thrombin capabilities and MDR-compliant clinical evidence packages. Mid-cap specialists with ISO 10993 validation completion and cardiovascular sealant 510(k) clearance represent optimal acquisition archetypes. Signal to monitor: FDA biocompatibility standard tightening velocity and its differential impact on synthetic versus biological formulation portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Thrombin Capacity Expansion | Captive production insulates margin against bovine plasma volatility and TSE screening disruptions. |
| EU MDR Clinical Evidence Upgrade | Robust trial data creates competitive separation from predicate-dependent manufacturers in sealant categories. |
| IDN Direct Contracting Partnership | Bypassing distributor intermediaries captures cardiovascular service line volume concentration. |
| Pediatric Formulation Development | Low-dose rapid-absorption hemostats access premium pricing in underpenetrated congenital cardiac repair. |
| India Domestic Production Investment | Ayushman Bharat tier-2 expansion creates first-mover advantage in reimbursed procedure growth corridors. |
Study Parameters
Cross-validation between primary interviews with hospital purchasing committee members, GPO contracts managers, and biomedical engineers anchors the qualitative findings against secondary validation from FDA 510(k) and PMA filings, EU MDR summary of safety and clinical performance documentation, and hospital procurement database records. Bottom-up triangulation across product-level volume estimates and top-down reconciliation against integrated delivery network contract disclosures ensures convergence. Primary fieldwork encompassed trauma center emergency department protocol assessments and ambulatory surgical center workflow observations.
Sensitivity analysis across recombinant thrombin sourcing scenarios and mechanical hemostasis substitution rates informs the analytical framework. Segmentation dimensions modeled span product type, technology platform, surgical application specialty, and end-user facility category across the projection horizon. CAGRs derive from procedure volume elasticity coefficients and price trajectory assumptions by technology tier. Industry-specific forecast inputs incorporate EU MDR transition timeline uncertainty and IDN procurement consolidation velocity.
Forecasts assume regulatory continuity in FDA 510(k) biocompatibility standards and EU MDR clinical evidence mandates; material policy shifts would require re-modeling. Specific risk factors encompassing bovine-derived material export restrictions, recombinant thrombin patent litigation outcomes, and mechanical hemostasis technology advancement could revise trajectory assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Cell and Tissue Culture Supplies Market
Biotechnology Equipment
Life Science Instrumentation Market
Biotechnology Equipment
Low Endotoxin Gelatin Market
Biotechnology Equipment
Cellular Localization Kits Market
Biotechnology Equipment
Cartridges for RT-PCR Automatic Systems Market
Biotechnology Equipment
Biotherapeutics Virus Removal Filters Market
Biotechnology Equipment
Asia-Pacific Transfection Reagent and Equipment Market
Biotechnology Equipment
Cell Harvesting Systems Market
Biotechnology Equipment
Laboratory Filtration Devices Market
Biotechnology Equipment
SDS Poly Acrylamide Gel Electrophoresis Market
Biotechnology Equipment
Global Life Science Reagents Market
Biotechnology Equipment
Global Transfection Technologies Market
Biotechnology Equipment
Global Biotechnology Reagents Market
Biotechnology Equipment
Biomaterial Tester Market
Biotechnology Equipment
Automated Cell Counting Market
Biotechnology Equipment
Transfection Reagents Market