
 Cancer RNA Expression Market | 2026-2036
Cancer RNA Expression Market Size, Share, and Industry Trends Forecast 2026-2036
Cancer RNA Expression Market Analytics
Bioinformatics talent scarcity is redrawing competitive boundaries across the Cancer RNA Expression Market. Illumina, Inc. leverages its installed base of sequencing systems to sustain recurring consumable revenue across clinical and research accounts. Thermo Fisher Scientific, Inc. anchors its position through end-to-end workflow integration spanning sample preparation through data analysis. QIAGEN competes with modular assay portfolios that address fragmented laboratory infrastructure in mid-tier hospitals.
Cancer RNA expression encompasses the quantitative measurement of messenger RNA, non-coding RNA, and transcriptomic signatures extracted from tumor tissue or liquid biopsy specimens, typically requiring reverse transcription, amplification, and detection sensitivity reaching single-digit copies per reaction. Its primary commercial purpose centers on identifying oncogenic driver alterations, predicting therapeutic response, and stratifying patients into molecularly defined treatment arms. Kits and reagents capture the dominant share of product-type revenue owing to their recurring purchase rhythm and compatibility with multiple instrument platforms. Next-Generation Sequencing commands the fastest expansion within technology segments as multiplexed transcriptome analysis displaces single-gene methods in comprehensive genomic profiling panels. Diagnostics applications are deepening margin pools as laboratories seek CLIA-validated, reimbursement-supported assays rather than research-use-only products.
The FDA oversees premarket approval and breakthrough device designation for RNA-based oncology diagnostics, while the Clinical Laboratory Improvement Amendments govern analytical validity standards in decentralized testing environments. The European Medicines Agency coordinates companion diagnostic qualification with marketing authorization procedures, creating parallel but distinct compliance obligations for multinational assay developers. Stakeholders must monitor evolving reimbursement policies for transcriptomic tests as payors tighten evidentiary requirements for molecular diagnostic coverage.
Market Dynamics
The FDA's accelerated approval pathways for biomarker-driven oncology drugs are compressing development timelines and forcing diagnostic developers to synchronize regulatory submissions with pharmaceutical partners. This structural pressure is reshaping how RNA expression assays move from research-use-only to clinically validated products.
Growth Catalysts
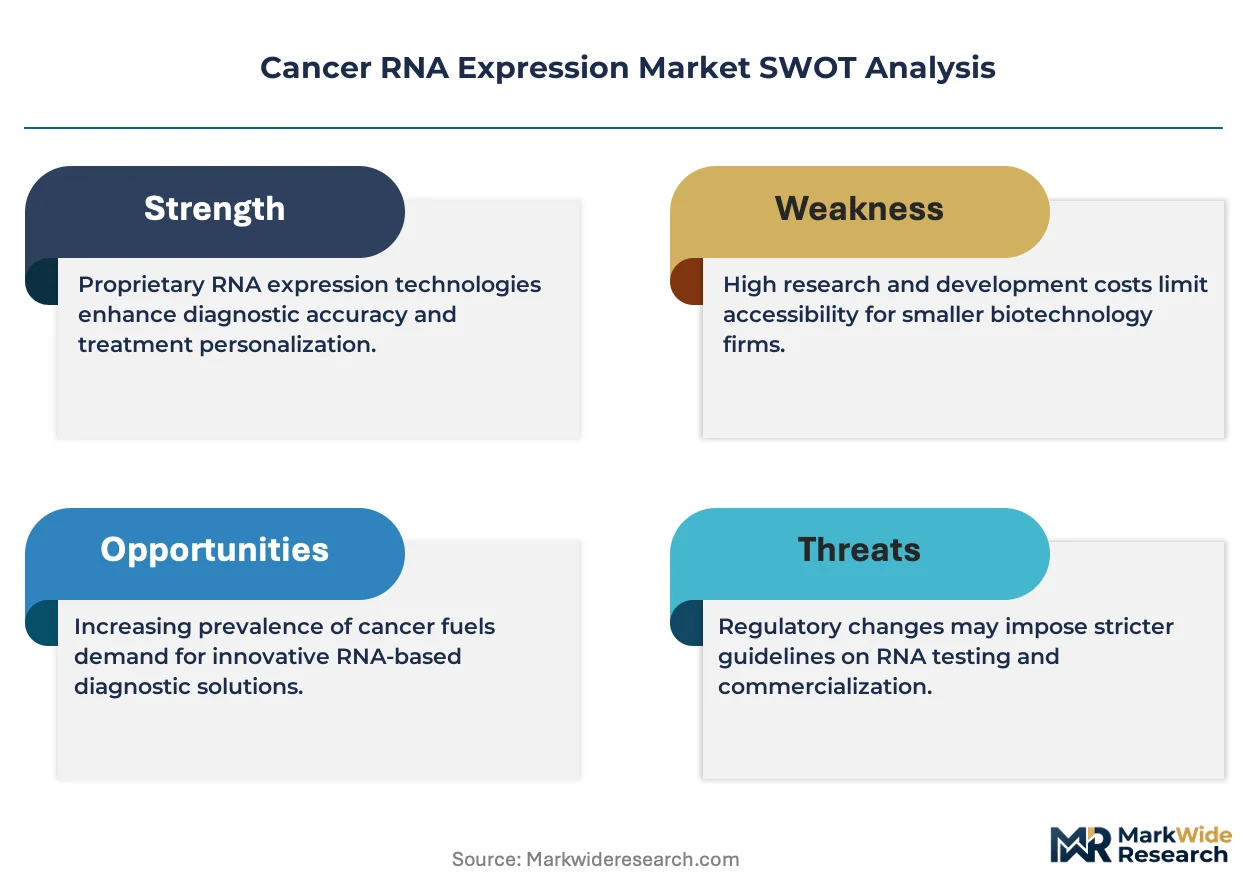
- Companion diagnostic mandates:The FDA now requires co-development of biomarker tests for targeted oncology therapies, creating automatic demand pull for RNA expression profiling in solid tumors and hematologic malignancies.
- Liquid biopsy expansion:Circulating tumor RNA analysis from blood draws is displacing tissue biopsies in monitoring applications, opening addressable patient populations previously excluded from serial testing.
- Academic medical center deployment:Integrated health networks in the United States are standardizing NGS-based expression panels across multiple hospital sites, generating recurring consumable demand at scale.
Market Restraints
- Reimbursement uncertainty:Medicare contractor variability and commercial payor evidentiary requirements create coverage gaps for novel transcriptomic signatures, limiting test adoption in community oncology practices.
- Input cost concentration:Sequencing reagent supply chains concentrate among a handful of enzyme and oligonucleotide manufacturers, exposing assay developers to price volatility and allocation constraints.
- Technical sensitivity limits:Low-abundance fusion transcripts and rare splice variants remain below detection thresholds in standard clinical workflows, restricting clinical utility in certain cancer subtypes.
Strategic Opportunities
- Minimal residual disease monitoring:Personalized RNA signatures for post-treatment surveillance represent an underpenetrated application with recurring testing frequency and premium pricing potential.
- EMA parallel qualification:The European Medicines Agency's streamlined companion diagnostic pathway creates regulatory tailwinds for assay developers seeking simultaneous US-EU market entry.
- AI-assisted variant interpretation:Machine learning integration with transcriptomic data is compressing reporting turnaround times and enabling laboratory service differentiation in competitive reference markets.
Industry Challenges
- Bioinformatics workforce scarcity:Clinical laboratories face acute shortages of computational biologists capable of validating and maintaining variant classification pipelines under CLIA oversight.
- Legacy LIS integration:Electronic health record connectivity and laboratory information system interoperability create deployment friction, particularly in mid-tier hospital networks with heterogeneous IT infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cancer RNA Expression Market |
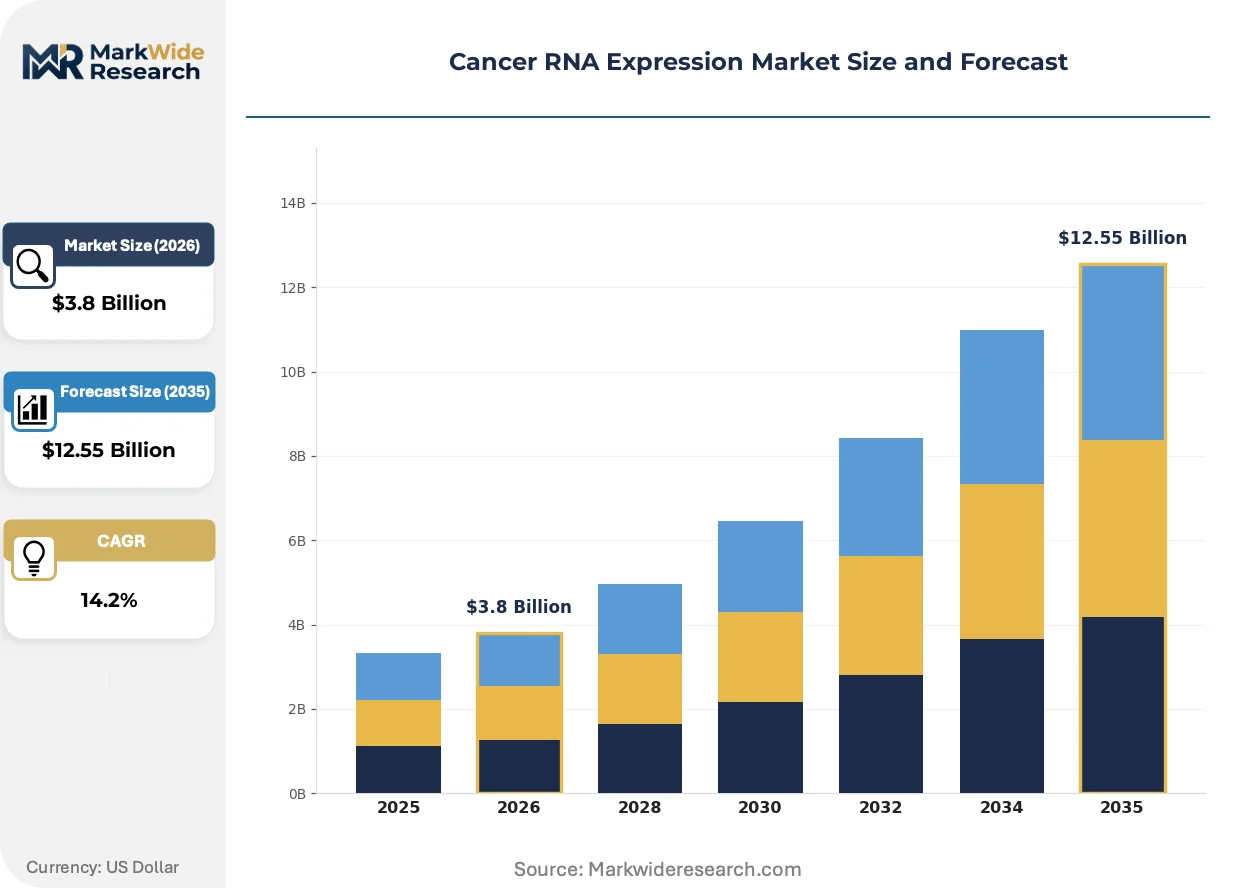
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assays, Kits, Reagents, Instruments Application: Research, Diagnostics, Therapeutics, Drug Development End User: Academic Institutes, Hospitals, Biotechnology Companies, Pharmaceutical Firms Technology: qPCR, Microarrays, Next-Generation Sequencing, Digital PCR |
| Companies Covered | Illumina, Inc., Thermo Fisher Scientific, Inc., QIAGEN, Agilent Technologies, Inc., Bio-Rad Laboratories, Inc., Hoffmann-La Roche Ltd, Merck KGaA, Pacific Biosciences of California, Inc., 10x Genomics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cancer RNA Expression Market Evolving Landscape
RNA expression technologies are fragmenting into specialized modalities optimized for specific clinical questions, with single-cell resolution and spatial transcriptomics emerging alongside bulk sequencing for tissue profiling. This diversification is forcing platform decisions earlier in product development cycles.
Single-cell RNA sequencing is bifurcating the research market from clinical diagnostics, with academic centers adopting 10x Genomics and similar platforms for tumor microenvironment studies while clinical laboratories standardize on targeted panels with faster turnaround. Pharmaceutical translational medicine groups are the primary adopters, embedding these technologies into early-phase trial protocols. The structural consequence is a talent and infrastructure gap between research-grade and clinical-grade transcriptomic capabilities.
The EMA's In Vitro Diagnostic Regulation implementation is forcing assay developers to rebuild technical documentation and quality management systems for European market access. Manufacturers with existing CE-marked products face compressed transition timelines to maintain compliance. Mid-sized reference laboratories in Germany and France are consolidating vendor relationships to reduce regulatory validation burden across their test menus.
Oncology practices are unbundling molecular diagnostic procurement from pathology service contracts, creating direct purchasing relationships with specialized reference laboratories. Hospital systems in Texas and California are piloting this model for complex genomic profiling, bypassing traditional academic center intermediaries. This channel disintermediation is most visible in community cancer centers seeking faster turnaround times for therapy selection decisions.
Cancer RNA Expression Market Segmentation
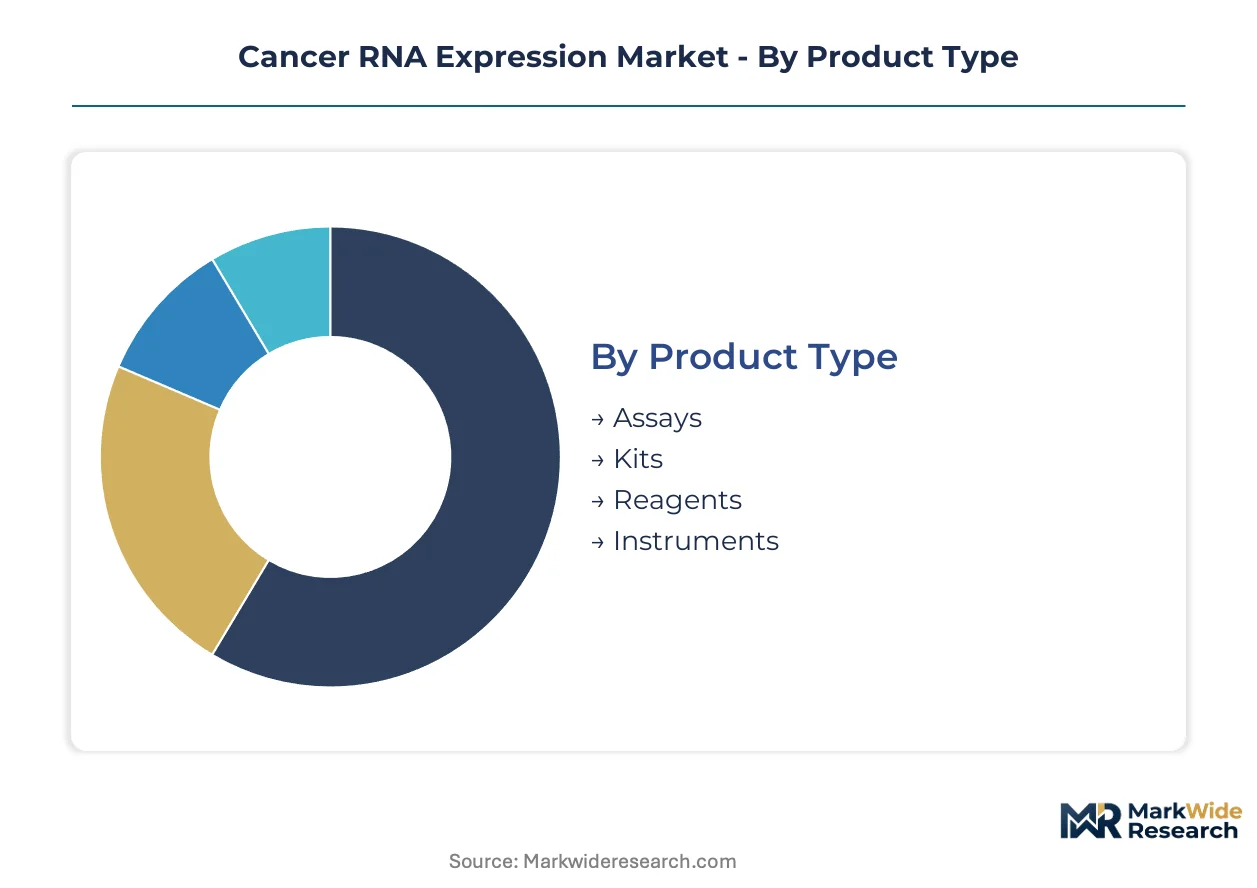
Segmentation in the Cancer RNA Expression Market reveals distinct procurement patterns across research and clinical environments. Product type and technology choices diverge sharply between academic centers pursuing discovery science and hospital laboratories delivering patient care. Understanding these segment boundaries enables suppliers to align pricing, regulatory strategy, and service models with specific buyer requirements.
Product Type:
Kits and reagents flow predominantly through domestic distribution channels anchored to recurring consumable contracts, while instruments concentrate demand among export-led capital equipment procurement cycles.
- Kits:Pre-configured reaction assemblies containing primers, probes, and master mixes standardized for specific cancer gene panels. Academic medical centers in the United States drive volume through CLIA-validated assay menus requiring consistent replenishment cycles.
- Reagents:Enzyme formulations, nucleotides, and buffers enabling laboratory-developed test workflows. Mid-tier hospitals in Germany and France source these through consolidated vendor relationships to reduce EMA IVDR compliance burden across their test menus.
- Assays:Targeted detection systems for specific oncogenic transcripts.
- Instruments:Capital platforms for amplification and detection.
Kits command the established base. The steepest expansion runs through reagents.
Application:
Cost tier separation distinguishes premium-priced diagnostic applications from research-grade products, with reimbursement status determining margin structure across segments.
- Diagnostics:CLIA-validated, reimbursement-supported assays for therapy selection and patient stratification. Integrated health networks in Texas and California deploy these at scale for comprehensive genomic profiling, generating recurring revenue pools.
- Research:Research-use-only products for discovery science and biomarker qualification. Pharmaceutical translational medicine groups embed these into early-phase oncology trial protocols, particularly for single-cell and spatial transcriptomic studies.
- Therapeutics:RNA-based therapeutic monitoring and response assessment.
- Drug Development:Biomarker-driven patient selection for clinical trials.
Diagnostics commands the established base. The steepest expansion runs through drug development.
End User:
Customer type determines purchasing authority, with centralized procurement in pharmaceutical firms contrasting against fragmented decision-making in academic settings.
- Pharmaceutical Firms:Co-development partners for companion diagnostics with synchronized regulatory submissions to FDA. These buyers demand end-to-end workflow integration from sample preparation through data analysis to compress development timelines.
- Academic Institutes:Discovery-oriented purchasers adopting 10x Genomics platforms for tumor microenvironment studies. Research-grade capabilities here create talent and infrastructure gaps versus clinical-grade transcriptomic operations.
- Hospitals:Clinical service delivery requiring CLIA oversight and EHR connectivity.
- Biotechnology Companies:Emerging diagnostic developers seeking modular assay portfolios.
Pharmaceutical firms command the established base. The steepest expansion runs through biotechnology companies.
Technology:
Maturity curves separate established quantitative methods from emerging multiplexed platforms, with adoption velocity constrained by bioinformatics workforce availability.
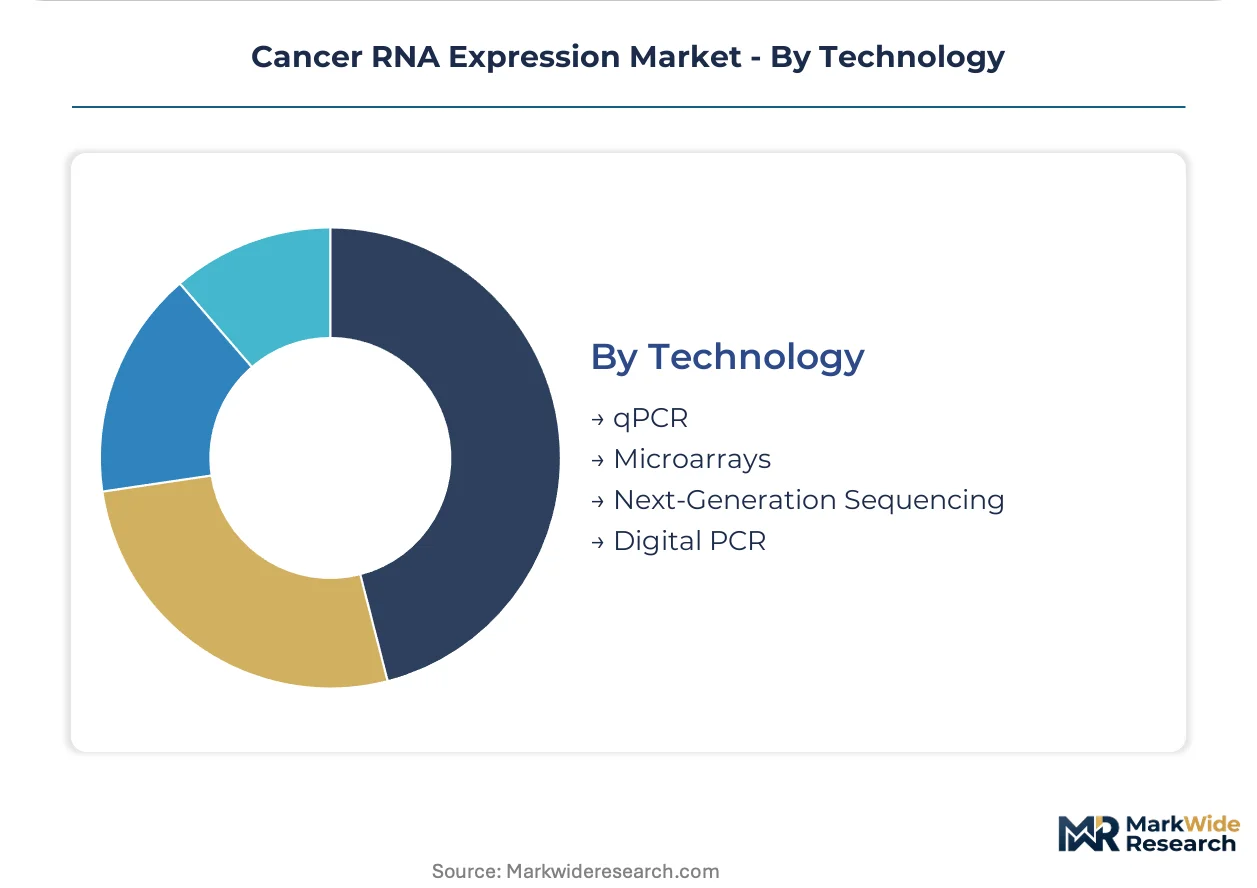
- Next-Generation Sequencing:Multiplexed transcriptome analysis displacing single-gene methods in comprehensive genomic profiling. Academic medical centers in the United States standardize these panels across multiple hospital sites, generating consumable demand at scale.
- qPCR:Quantitative reverse transcription polymerase chain reaction for targeted, rapid-turnaround applications. Community oncology practices rely on these workflows where reimbursement uncertainty limits investment in capital-intensive platforms.
- Microarrays:Hybridization-based expression profiling for established biomarker signatures.
- Digital PCR:Absolute quantification methods for minimal residual disease monitoring.
qPCR commands the established base. The steepest expansion runs through next-generation sequencing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways for biomarker-driven oncology drugs anchor demand concentration in the United States, where integrated health networks deploy NGS-based expression profiling at scale. Academic medical centers and pharmaceutical co-development partnerships generate recurring consumable demand across clinical and research accounts.
United States
Companion diagnostic mandates from the FDA synchronize regulatory submissions with pharmaceutical partners, compressing development timelines for RNA expression assays. The Clinical Laboratory Improvement Amendments govern analytical validity standards in decentralized testing environments across hospital networks. Texas and California hospital systems pilot direct procurement models for complex genomic profiling, bypassing traditional academic center intermediaries.
Germany
Mid-tier reference laboratories consolidate vendor relationships to reduce regulatory validation burden under the EMA's In Vitro Diagnostic Regulation implementation. The German national pharmaceutical regulator coordinates with EMA companion diagnostic qualification procedures, creating parallel compliance obligations for multinational assay developers. The Eindhoven Region and Bavaria industrial clusters concentrate pharmaceutical translational medicine groups embedding RNA technologies into early-phase trial protocols.
United Kingdom
London and Southeast England academic institutes adopt single-cell and spatial transcriptomic platforms for tumor microenvironment studies, creating infrastructure gaps versus clinical-grade operations. The Medicines and Healthcare products Regulatory Agency aligns with EMA pathways for biomarker-driven therapy approval. Greater Manchester and Cambridge biotech clusters attract emerging diagnostic developers seeking modular assay portfolios.
China
Domestic biotechnology companies expand procurement of RNA-based companion diagnostics to guide oncology therapy selection in tier-one cities. The National Medical Products Administration oversees premarket approval for molecular diagnostic platforms under harmonized standards with international reference laboratories. Yangtze River Delta medical centers in Shanghai and Suzhou deploy NGS panels at scale for comprehensive genomic profiling.
Japan
Pharmaceutical firms in Tokyo and Osaka accelerate co-development partnerships for biomarker-driven drugs, generating demand pull for CLIA-validated expression assays. The Pharmaceuticals and Medical Devices Agency streamlines companion diagnostic qualification with marketing authorization procedures. Kansai region hospitals standardize on targeted qPCR workflows where reimbursement frameworks limit capital-intensive platform investment.
Cancer RNA Expression Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Cancer RNA Expression Market. Sequencing platform manufacturers with installed instrument bases capture recurring consumable revenue through locked reagent contracts, while modular assay developers compete on flexibility for fragmented laboratory infrastructure. Three archetypes dominate: integrated workflow providers, platform-agnostic reagent suppliers, and specialized bioinformatics service firms. Competitive moves concentrate on strategic partnerships with pharmaceutical sponsors and portfolio diversification into liquid biopsy applications.
Within the integrated workflow tier, Illumina, Inc. and Thermo Fisher Scientific, Inc. occupy positions anchoring end-to-end solutions from sample preparation through data analysis. QIAGEN exemplifies the modular assay archetype, competing through fragmented infrastructure compatibility rather than platform lock-in. These three companies represent the dominant competitive anchors, with differentiation running through regulatory synchronization capabilities and consumable revenue models rather than instrument hardware alone.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Thermo Fisher Scientific, Inc. |
| QIAGEN |
| Agilent Technologies, Inc. |
| Bio-Rad Laboratories, Inc. |
| Hoffmann-La Roche Ltd |
| Merck KGaA |
| Pacific Biosciences of California, Inc. |
| 10x Genomics |
| Others |
Value Network & Pricing Analysis
Long-term consumable contracts lock in sequencing reagent supply for integrated health networks while anchoring price visibility across multi-year procurement cycles. These arrangements concentrate purchasing power among academic medical centers in the United States and pharmaceutical co-development partners, compressing margin flexibility for modular assay developers competing on fragmented infrastructure compatibility.
Pricing Analysis
Geographic price spreads widen between CLIA-validated diagnostic assays in the United States and research-use-only products in European academic institutes, reflecting reimbursement status differentials. Pricing stratifies across premium, standard, and economy tiers based on regulatory certification level and after-sales bioinformatics support bundling. Cost compression in mid-tier hospital segments intensifies because of Medicare contractor variability and evidentiary requirements tightening. Community oncology practices exhibit highest price sensitivity, while pharmaceutical firms demonstrate lowest sensitivity due to co-development timeline pressures.
Supply Chain Analysis
Strategic stockpiling of enzyme formulations and oligonucleotide master mixes dominates over just-in-time preferences, driven by allocation constraints from concentrated manufacturers. Supply concentrates in the United States, Germany, and China for sequencing platforms and consumable production. Raw material dependencies center on reverse transcriptase enzymes, fluorophore-labeled probes, and synthetic nucleotides. Single-source vulnerability in thermostable polymerase supply creates structural risk exposure. Distribution runs through domestic distribution channels for kits and reagents, with instruments following export-led capital equipment procurement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consumable revenue streams from recurring reagent contracts expand faster than instrument hardware sales, positioning bioinformatics service layers as the critical service-attach opportunity. Laboratories seek CLIA-validated assay menus with embedded data interpretation support, shifting competitive differentiation toward software-enabled workflow integration.
For Market Incumbents: Fortify installed base lock-in through expanded CLIA-validated assay menus and preemptive certification investments under FDA breakthrough device pathways. Sequencing platform manufacturers face substitution pressure from targeted qPCR workflows in reimbursement-constrained environments; defend through consumable contract structures that embed multi-year replenishment commitments and technical support bundling. For New Entrants and Emerging Players: Bioinformatics workforce scarcity in mid-tier hospital networks creates a service-layer gap where incumbents under-serve variant classification pipeline maintenance. Target community cancer centers in Texas and California bypassing traditional academic intermediaries through direct procurement pilots. Penetrate via AI-assisted turnaround compression and EHR connectivity solutions addressing legacy LIS integration friction. For Investors and Strategic Acquirers: Specialized bioinformatics service firms with CLIA-compliant variant classification capabilities represent the priority acquisition archetype. Long-term viability hinges on regulatory synchronization speed with pharmaceutical partners and consumable revenue recurrence rates. Watch FDA companion diagnostic mandate expansion into hematologic malignancies as the inflection signal for assay developer consolidation activity.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Validation Pathway | FDA breakthrough designation compresses development timelines for biomarker-driven oncology diagnostics. |
| Pharmaceutical Co-Development Partnership | Synchronized regulatory submissions align assay validation with drug approval pathways under FDA mandates. |
| Liquid Biopsy Application Expansion | Circulating tumor RNA analysis opens serial testing populations previously excluded from tissue biopsy requirements. |
| AI-Assisted Variant Interpretation | Machine learning integration compresses reporting turnaround and differentiates laboratory services in competitive reference markets. |
| EMA Parallel Qualification Strategy | Streamlined companion diagnostic pathway creates regulatory tailwinds for simultaneous US-EU market entry. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA premarket approval databases, EMA companion diagnostic qualification records, Clinical Laboratory Improvement Amendments enforcement reports, and hospital procurement contract disclosures. Interviews with diagnostic assay developers, CLIA laboratory directors, pharmaceutical regulatory affairs leads, and payer access specialists inform demand-side validation. Bottom-up triangulation across product-type shipment data and top-down reconciliation against health system expenditure records ensure cross-verified outputs.
Segmentation dimensions modeled span product type, technology platform, application purpose, and end-user archetype across the projection horizon. Analytical framework incorporates therapy selection decision workflows, reimbursement coverage determinations, and regulatory approval velocity as industry-specific forecast inputs. CAGRs derive from installed base expansion rates, consumable pull-through coefficients, and assay menu adoption curves.
Forecasts assume regulatory continuity in FDA accelerated approval pathways and EMA In Vitro Diagnostic Regulation implementation; material policy shifts would require re-modeling. Revision becomes warranted when companion diagnostic mandate scope expansion or reimbursement evidentiary requirement tightening crosses thresholds that alter assay developer investment returns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Becker Muscular Dystrophy Market
Medical Biotechnology
Breast Tissue Markers Market
Medical Biotechnology
Human Placental Protein Market
Medical Biotechnology
Global MRSA Testing Market
Medical Biotechnology
Global Mrna Vaccine Market
Medical Biotechnology
Myoglobin Market
Medical Biotechnology
North America Bacteriophages Therapy Market
Medical Biotechnology
Fetal Macrosomia Market
Medical Biotechnology
Alcohol Dehydrogenase Enzymes Market
Medical Biotechnology
X-Linked Hypophosphatemia Market
Medical Biotechnology
Global Premature Rupture of Membranes (PROM) Testing Market
Medical Biotechnology
Clarithromycin Market
Medical Biotechnology
Galectin Inhibitor Therapeutics Market
Medical Biotechnology
Europe Cell Culture Market
Medical Biotechnology
Vanishing Bone Disease Market
Medical Biotechnology
Serum Lactate Testing Market