
 South Korea Insulin Drugs and Delivery Devices Market | 2026-2036
South Korea Insulin Drugs and Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Insulin Drugs and Delivery Devices Market Insights
The gap between premium smart delivery systems and conventional pen devices is broadening in South Korea. Novo Nordisk leverages its biosimilar manufacturing depth to anchor the long-acting insulin segment. Eli Lilly and Company competes through specialized rapid-acting formulations targeted at Type 1 diabetes protocols. Sanofi differentiates via integrated pen-and-cartridge ecosystems that dominate hospital formulary placement.
South Korea insulin drugs and delivery devices encompass recombinant human and analog insulin formulations alongside mechanical and electronic delivery systems, typically administered subcutaneously with U-100 concentration standardization to regulate blood glucose in diabetic patients. The primary purpose centers on maintaining glycemic control across chronic disease management pathways. Long-acting insulin formulations command stable margin pools due to predictable dosing regimens and strong clinician preference. Smart insulin pens represent the fastest-growing technology segment as MFDS digital health integration standards accelerate connected device adoption. Homecare settings emerge as a concentrated demand channel driven by aging-in-place policies and remote monitoring infrastructure expansion.
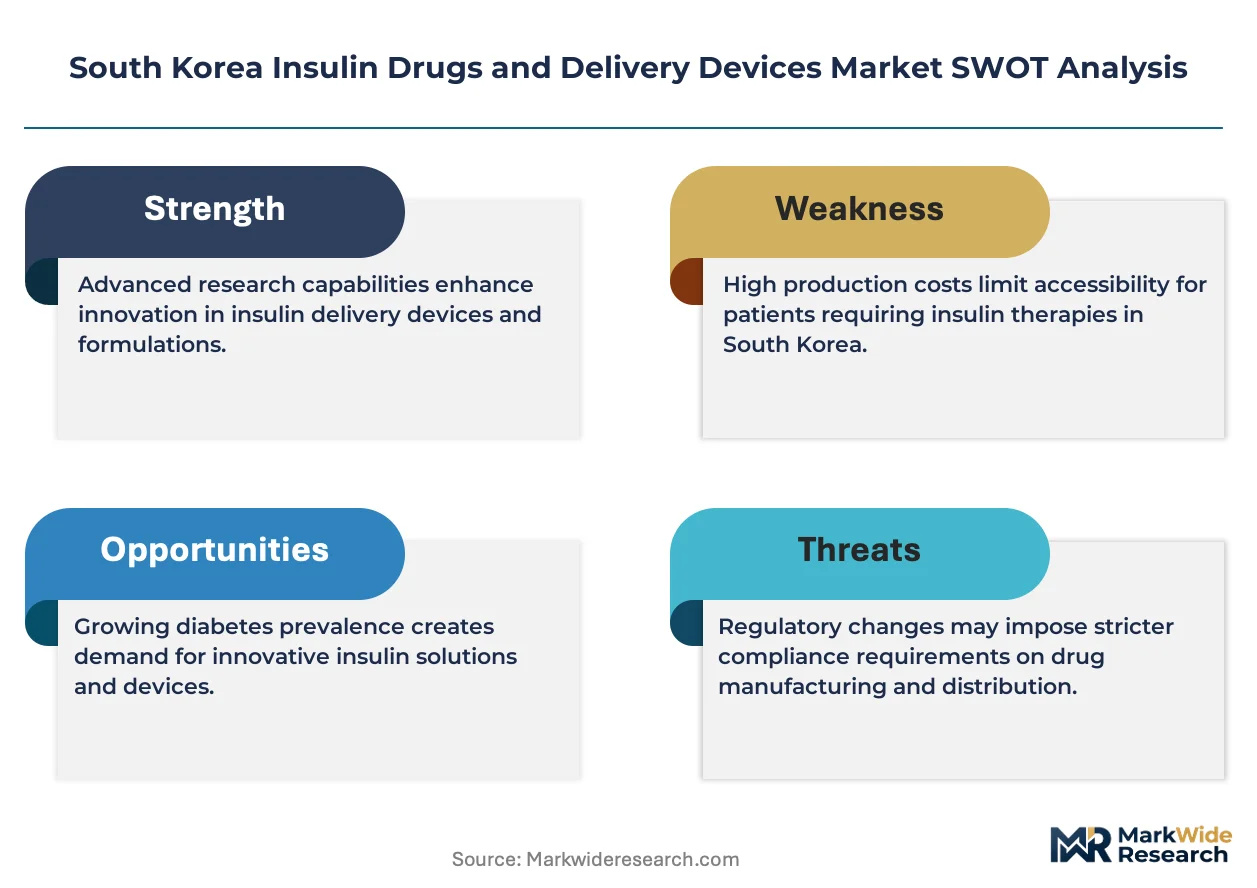
MFSD approval pathways and reimbursement schedules shape product commercialization timelines, while KDCA pharmacovigilance requirements enforce post-market surveillance obligations that elevate compliance costs for device manufacturers. The Ministry of Health and Welfare's chronic disease management framework directly influences prescribing patterns through its national diabetes registry and physician incentive structures. Stakeholders must monitor evolving digital therapeutics classification criteria that could reclassify connected insulin delivery systems under software-as-medical-device regulations.
Market Dynamics
MFDS reimbursement restructuring for digital therapeutics is compressing commercialization timelines while fragmenting prescribing authority across Seoul's tertiary networks and provincial diabetes centers.
Growth Catalysts
- MFDS Digital Health Integration Standards:Connected insulin pen data streams now qualify for remote patient monitoring reimbursement, accelerating hospital formulary adoption across Seoul metropolitan clusters.
- Aging-in-Place Policy Framework:Ministry of Health and Welfare homecare subsidies redirect chronic diabetes management from inpatient to residential settings, expanding pen device demand in Gyeonggi and Busan provinces.
- U-100 Concentration Standardization:Unified dosing protocols simplify clinician training requirements and reduce medication error liability, smoothing product substitution across public health insurance tiers.
Market Restraints
- API Import Concentration:Active pharmaceutical ingredient supply for analog insulin concentrates among three contract manufacturers in Zhejiang province, exposing Korean formulators to cross-border logistics volatility.
- KDCA Post-Market Surveillance Burden:Pharmacovigilance reporting obligations for connected devices require dedicated adverse event infrastructure, elevating compliance overhead for mid-scale device entrants.
- Recombinant Human Insulin Substitution:Price-competitive biosimilar human formulations retain formulary preference in rural health centers, constraining analog insulin margin expansion.
Strategic Opportunities
- Daegu-Gyeongbuk Medical Cluster:Underpenetrated diabetes center networks in Korea's fourth-largest city present first-mover positioning for integrated pen-and-sensor ecosystems.
- Software-as-Medical-Device Reclassification:Pending MFDS guidance on connected pen algorithms creates pathway for subscription-based dose optimization services.
- Pharmacy Channel Digitization:GS Retail and CJ Olive Young e-pharmacy platforms enable direct-to-patient pen cartridge replenishment, bypassing hospital procurement bottlenecks.
Industry Challenges
- Biologics Manufacturing Talent Scarcity:Yeast-based insulin fermentation expertise concentrates among retiring cohorts at Hanmi Pharmaceutical and Celltrion, constraining domestic production scale-up.
- Legacy Device Interoperability:Non-connected pen systems deployed through National Health Insurance Service tenders lack Bluetooth connectivity, complicating hybrid fleet management in multi-site hospital systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Insulin Drugs and Delivery Devices Market |
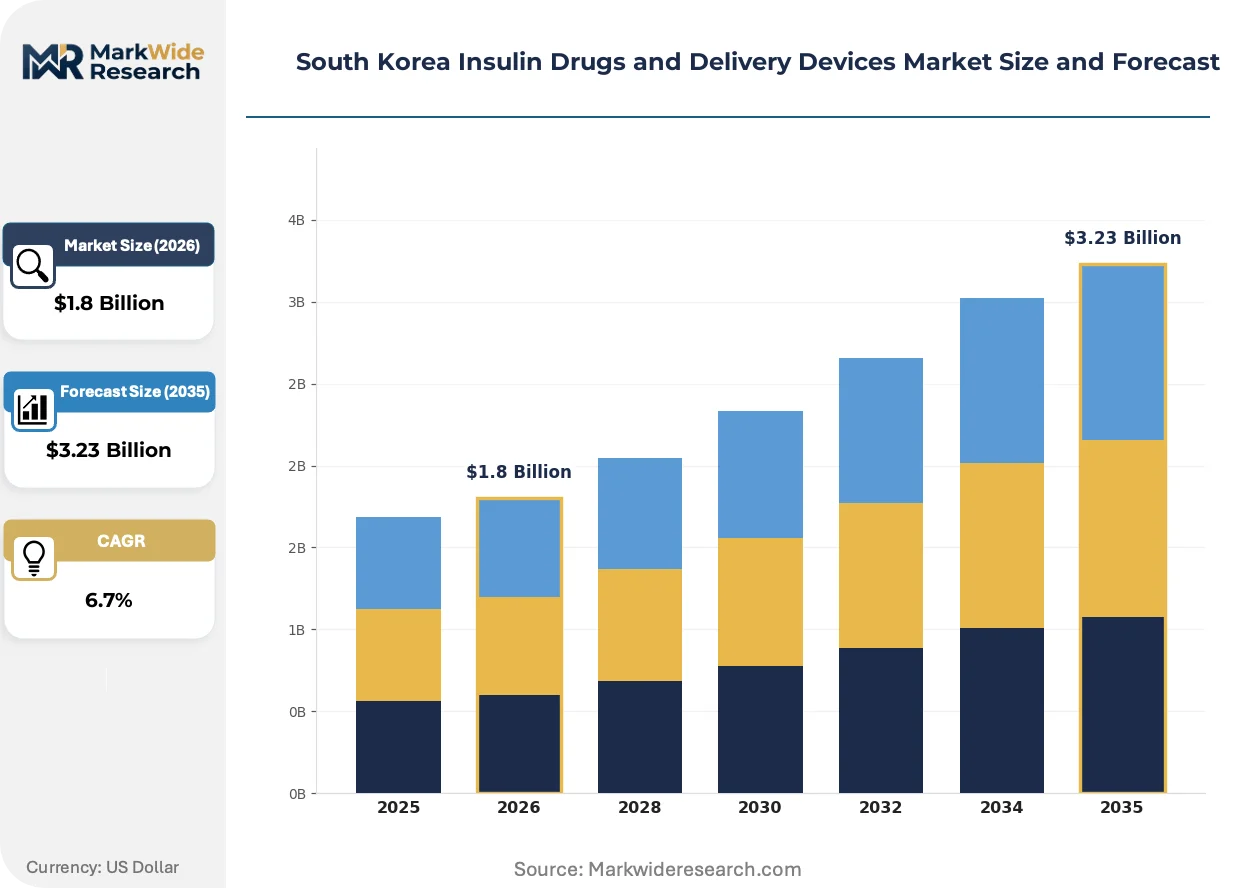
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rapid-Acting Insulin, Long-Acting Insulin, Insulin Pumps, Pen Devices Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Insulin Resistance End User: Hospitals, Clinics, Homecare Settings, Pharmacies Technology: Needle-Injector Systems, Smart Insulin Pens, Continuous Glucose Monitoring, Patch Pumps |
| Companies Covered | Novo Nordisk, Eli Lilly and Company, Sanofi, Medtronic, Becton Dickinson, Roche, Merck & Co., Inc., AstraZeneca, Boehringer Ingelheim, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Insulin Drugs and Delivery Devices Market Trends and Innovations
Connected delivery systems are compressing the data feedback loop between patient dosing behavior and clinician intervention protocols across Korean diabetes management pathways.
Bluetooth-enabled smart insulin pens are consolidating dose logging and glycemic pattern analysis into single-device workflows. Seoul National University Hospital and Samsung Medical Center have deployed these systems across endocrinology wards since MFDS clearance. The technology is consolidating previously separate glucose meter, pen, and mobile app purchasing decisions into unified procurement bundles.
MFDS Software-as-Medical-Device classification guidelines are reshaping connected pen commercialization pathways. Algorithm-driven dose recommendation features now trigger standalone regulatory review parallel to hardware approval. Device manufacturers are responding by segregating basic logging functions from advanced decision-support modules to preserve timeline flexibility.
Hospital formulary committees are unbundling after-sales training from device procurement contracts. Previously bundled technical support and patient education services now undergo separate vendor selection, with Asan Medical Center and Severance Hospital piloting third-party diabetes educator networks. This shift is most visible in Seoul's tertiary care tier, where specialized nursing capacity constraints force outsourcing of pen device onboarding.
South Korea Insulin Drugs and Delivery Devices Market Segmentation
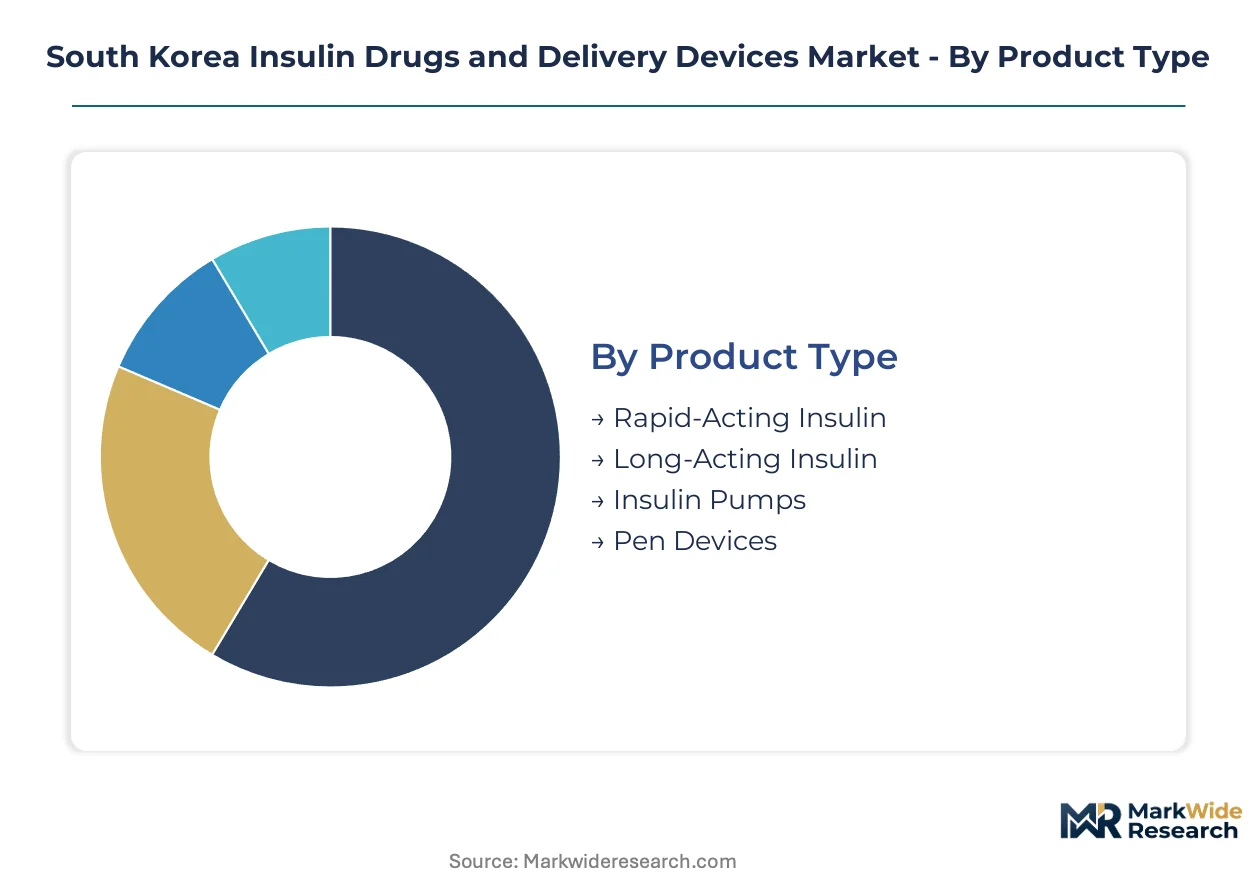
Segmentation in South Korea's insulin market reveals how MFDS reimbursement tiers and digital health integration standards fragment procurement decisions across delivery technologies and care settings. Understanding these divides exposes where margin pools concentrate versus where volume scales through standardized tenders.
Product Type:
The customization-vs-standardization spectrum runs from algorithm-driven pump systems to commodity pen cartridges, with reimbursement intensity inversely tracking hardware sophistication.
- Long-Acting Insulin:Analog formulations with extended glucose-lowering profiles enable once-daily dosing protocols. Demand concentrates in Seoul's tertiary endocrinology wards where clinician preference for predictable basal coverage drives formulary placement.
- Pen Devices:Disposable and reusable mechanical injection systems dominate National Health Insurance Service procurement volumes. Gyeonggi province homecare programs absorb the majority of device shipments under aging-in-place subsidies.
- Rapid-Acting Insulin:Ultra-short onset formulations for prandial glucose control.
- Insulin Pumps:Subcutaneous infusion systems with programmable basal-bolus delivery.
Leading the category by volume: Pen Devices. Growing fastest: Long-Acting Insulin.
Application:
Cost tier stratification separates intensive insulin protocols from adjunctive therapy prescriptions, with reimbursement rates scaling by disease severity and complication risk.
- Type 2 Diabetes:Progressive insulin dependency in later-stage metabolic disease creates the largest addressable population. Busan and Daegu diabetes centers manage high patient volumes through standardized pen-and-cartridge protocols under NHIS chronic disease management pathways.
- Type 1 Diabetes:Absolute insulin deficiency mandates lifelong exogenous replacement with intensive monitoring. Pediatric and young adult cohorts in Seoul metropolitan clusters drive adoption of integrated pump-and-sensor ecosystems despite premium pricing.
- Gestational Diabetes:Temporary insulin requirements during pregnancy with strict glycemic targets.
- Insulin Resistance:Adjunctive insulin therapy in severe metabolic syndrome cases.
Dominant by patient volume: Type 2 Diabetes. Expanding most quickly: Type 1 Diabetes.
End User:
Customer type fragmentation splits between institutional procurement committees and direct-to-patient channels, with divergent price sensitivity and technical support requirements.
- Hospitals:Tertiary care networks with dedicated endocrinology departments anchor high-value pump and smart pen adoption. Samsung Medical Center and Asan Medical Center pilot connected device fleets under MFDS digital therapeutics reimbursement pilots.
- Homecare Settings:Residential diabetes management programs in Gyeonggi and South Gyeongsang provinces absorb subsidized pen device volumes. Ministry of Health and Welfare remote monitoring infrastructure enables clinician oversight without inpatient admission.
- Clinics:Outpatient diabetes centers with limited specialist staffing.
- Pharmacies:Retail and e-pharmacy channels for cartridge replenishment.
Highest value concentration: Hospitals. Fastest channel expansion: Homecare Settings.
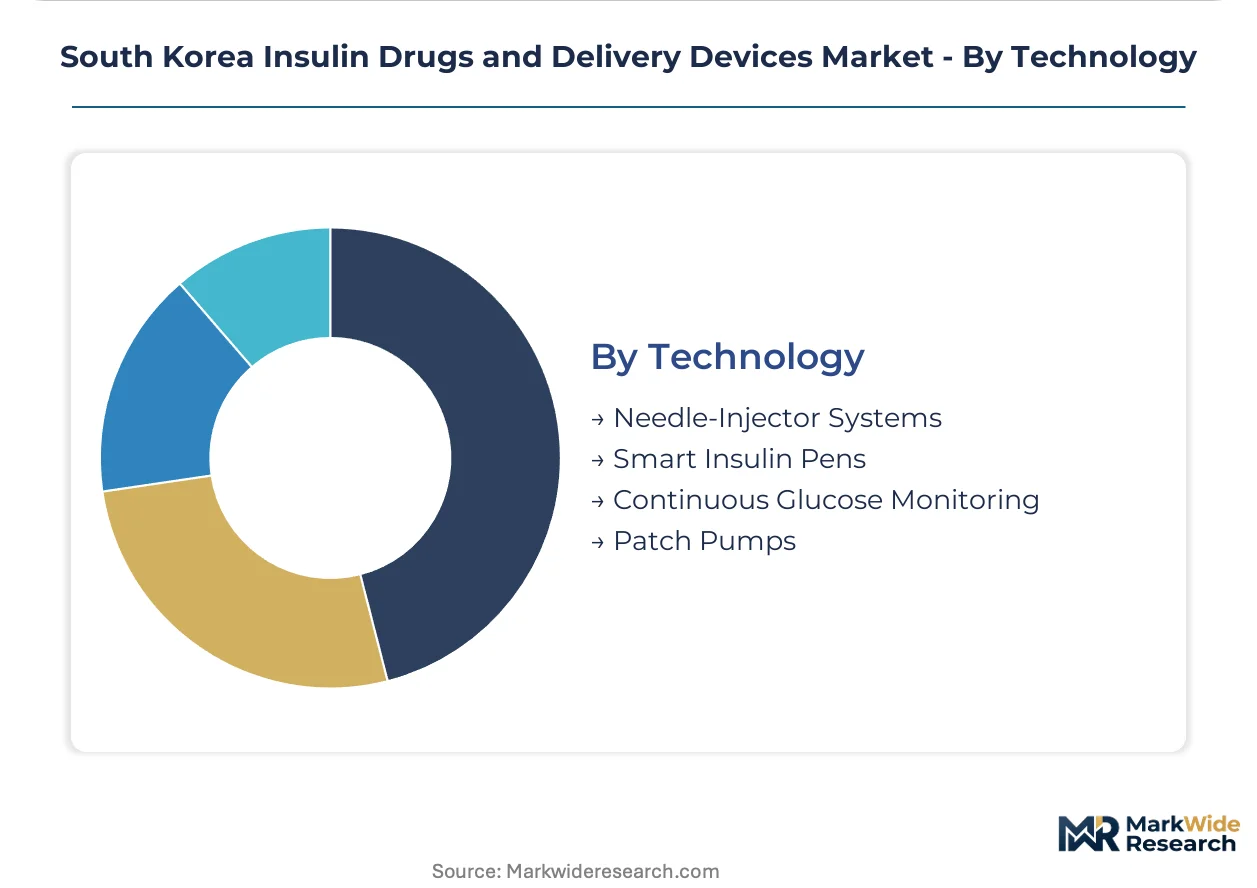
Technology:
Maturity gradients separate legacy mechanical systems from connected platforms awaiting software-as-medical-device regulatory clarity.
- Smart Insulin Pens:Bluetooth-enabled dose logging and glycemic pattern analysis consolidate previously separate device workflows. Seoul National University Hospital deployment validates MFDS clearance pathways for connected delivery systems.
- Continuous Glucose Monitoring:Interstitial glucose sensors with real-time data transmission enable closed-loop insulin dosing. Integration with patch pump systems creates ecosystem lock-in for early adopters in metropolitan diabetes centers.
- Needle-Injector Systems:Conventional syringe and vial administration for cost-sensitive settings.
- Patch Pumps:Adhesive-mounted disposable infusion devices for tube-free delivery.
Widest installed base: Needle-Injector Systems. Steepest adoption curve: Smart Insulin Pens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul Capital Area anchors South Korea's insulin market activity, with tertiary care networks driving smart pen adoption under MFDS digital health pilots. Provincial diabetes centers in Busan-Ulsan and Daegu-Gyeongbuk absorb standardized pen device volumes through National Health Insurance Service tenders.
Seoul Capital Area
Seoul's tertiary endocrinology wards concentrate demand for connected insulin delivery systems. MFDS reimbursement restructuring for remote patient monitoring accelerates smart pen procurement at Samsung Medical Center and Asan Medical Center. The metropolitan cluster validates digital therapeutics integration before national rollout.
Busan-Ulsan
Busan's diabetes centers manage high patient volumes through standardized pen-and-cartridge protocols. Ministry of Health and Welfare chronic disease management pathways subsidize device access for aging populations. Ulsan's industrial base supports medical device component manufacturing for regional formulators.
Daegu-Gyeongbuk
Daegu's underpenetrated diabetes center networks present positioning opportunities for integrated pen-and-sensor ecosystems. KDCA pharmacovigilance requirements enforce post-market surveillance obligations that elevate compliance costs for new entrants. The Gyeongbuk medical cluster attracts device manufacturers seeking lower-cost clinical trial sites.
Daejeon-Sejong
Daejeon's research institutions contribute to biosimilar insulin development through public-private partnerships. The national pharmaceutical regulator maintains headquarters in Sejong, streamlining MFDS approval consultations for domestic manufacturers. Regional hospitals participate in multi-site trials for connected delivery systems.
Gwangju-Honam
Gwangju's homecare programs absorb subsidized pen device volumes under aging-in-place policy frameworks. Rural health centers in the Honam region retain preference for price-competitive recombinant human insulin formulations. Remote monitoring infrastructure expansion lags behind Seoul and Busan metropolitan clusters.
South Korea Insulin Drugs and Delivery Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the digital integration spectrum in South Korea's insulin market. The vendor base consolidates around three strategic tiers: multinational pharmaceutical conglomerates with biosimilar manufacturing depth, diversified medical device manufacturers with pen hardware expertise, and domestic formulators seeking technology licensing partnerships. Dominant competitive moves include strategic partnerships for connected device ecosystems and backward integration into active pharmaceutical ingredient sourcing to mitigate cross-border supply volatility.
Within the multinational pharmaceutical tier, Novo Nordisk, Eli Lilly and Company, and Sanofi occupy positions that exemplify divergent specialization strategies. Novo Nordisk represents the biosimilar manufacturing depth archetype, anchoring long-acting insulin supply through fermentation expertise. Eli Lilly and Company exemplifies rapid-acting formulation specialization targeted at intensive insulin protocols. Sanofi occupies a position emphasizing integrated pen-and-cartridge ecosystem control. These three entities collectively shape hospital formulary placement dynamics and reimbursement negotiation leverage across Seoul's tertiary care networks.
| Leading Market Players |
|---|
| Novo Nordisk |
| Eli Lilly and Company |
| Sanofi |
| Medtronic |
| Becton Dickinson |
| Roche |
| Merck & Co., Inc. |
| AstraZeneca |
| Boehringer Ingelheim |
| Others |
Pricing and Supply Chain Analysis
API feedstock indices for recombinant insulin fermentation cascade through Korean formulator cost structures into three-tier pricing stratification across premium analog, standard biosimilar, and economy human insulin tiers. MFDS reimbursement banding amplifies these cost pass-through effects, concentrating margin capture among manufacturers with captive fermentation capacity.
Pricing Analysis
Value-based pricing anchored to HbA1c outcome guarantees shapes premium analog insulin contracting at Seoul's tertiary networks. Pricing stratifies across premium, standard, and economy tiers based on MFDS biosimilar interchangeability certification and bundled after-sales educator support. Cost compression in the recombinant human segment intensifies as NHIS tenders favor lowest-compliant bidders. Rural health centers exhibit highest price sensitivity; tertiary endocrinology wards prioritize clinical outcome guarantees over unit cost.
Supply Chain Analysis
Regional distribution centers in Incheon and Busan operate hub-and-spoke patterns for pen device logistics, with cold-chain integrity monitoring throughout. Active pharmaceutical ingredient supply draws from contract manufacturers in China, India, and domestic yeast fermentation facilities. Single-source vulnerability concentrates in Zhejiang province API suppliers exposed to cross-border customs volatility. Distribution runs through hospital procurement consortia and pharmacy chain replenishment networks with divergent service-level requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MFDS Software-as-Medical-Device reclassification functions as a cost-of-compliance moat, elevating barrier-to-entry for connected pen entrants lacking dedicated regulatory affairs infrastructure.
For Market Incumbents: To counter API import concentration risk, secure backward integration into fermentation capacity through technology licensing with domestic biologics manufacturers. Prioritize certification investment for algorithm-driven dose recommendation modules ahead of pending MFDS guidance publication. For New Entrants and Emerging Players: Begin with Daegu-Gyeongbuk diabetes center networks as the most penetrable geography, where incumbent smart pen deployment lags Seoul by several adoption cycles. Pursue pharmacy channel digitization partnerships with GS Retail or CJ Olive Young for direct-to-patient cartridge replenishment bypassing hospital procurement committees. For Investors and Strategic Acquirers: Distressed-cycle entries favor domestic formulators with dormant fermentation assets in Daejeon-Sejong research corridors, where public-private partnership infrastructure enables rapid capability reactivation. Monitor MFDS digital therapeutics reimbursement pilot expansion as the inflection signal for connected device ecosystem viability.| Strategic Initiative | Industry Significance |
|---|---|
| MFDS SaMD Classification Pathway | Algorithm-driven dose recommendation modules trigger standalone regulatory review parallel to hardware clearance. |
| Hospital System Partnership | Samsung Medical Center and Asan Medical Center pilot connected device fleets under digital therapeutics reimbursement pilots. |
| Backward Integration into API Supply | Captive fermentation capacity mitigates cross-border logistics volatility from Zhejiang province suppliers. |
| Pharmacy Channel Digitization | GS Retail and CJ Olive Young e-pharmacy platforms enable direct-to-patient pen cartridge replenishment. |
| Software Companion Development | Bluetooth-enabled dose logging consolidates previously separate glucose meter, pen, and mobile app purchasing decisions. |
Research Methodology
Multi-period observation of MFDS approval timelines, NHIS reimbursement schedule revisions, and hospital formulary placement patterns anchored the trend analysis, supplemented by interviews with regulatory affairs leads at multinational pharmaceutical subsidiaries, formulary directors at Seoul tertiary networks, biomedical engineers at connected device manufacturers, and procurement managers at National Health Insurance Service regional offices. Secondary validation drew from MFDS medical device registration databases, NHIS pharmaceutical pricing bulletins, ClinicalTrials.gov entries for Korean diabetes intervention studies, and hospital procurement consortium contract disclosures. Bottom-up patient population modeling and top-down pharmaceutical market sizing were triangulated against manufacturer shipment data.
Segment-weighting approaches applied differential growth assumptions across product type, application, end user, and technology dimensions, with additional stratification by regional regulatory cluster and digital health integration maturity. CAGRs were derived from logarithmic trend fitting across the projection horizon, calibrated against historical analog insulin adoption curves and smart pen penetration rates in comparable East Asian markets. Forecast inputs incorporated MFDS digital therapeutics reimbursement expansion scenarios and Ministry of Health and Welfare aging-in-place subsidy allocation trajectories.
Underlying measurement precision varies by segment; connected insulin pen adoption rates carry tighter precision than gestational diabetes application sizing due to sparse clinical protocol standardization. Forecasts reflect documented assumptions regarding reimbursement pathway timing and regulatory clearance velocity. Decision-makers should treat outputs as directional within the stated assumption set, recognizing that KDCA pharmacovigilance enforcement intensity or API supply disruptions could materially revise trajectory projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Kinase Inhibitors Market
Biopharmaceuticals
Biopharmaceutical Excipients Market
Biopharmaceuticals
Human Chorionic Gonadotropin Market
Biopharmaceuticals
Recombinant Human Serum Albumin Market
Biopharmaceuticals
Russia Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Protein Therapeutics Market
Biopharmaceuticals
Somatropin Market
Biopharmaceuticals
Discovery Bioanalysis Market
Biopharmaceuticals
A - Estradiol Market
Biopharmaceuticals
Biopharmaceuticals Manufacturing Consumables Testing Market
Biopharmaceuticals
Middle East and Africa Insulin Delivery Devices Market
Biopharmaceuticals
Targeted Protein Degradation Market
Biopharmaceuticals
Sezary Syndrome Market
Biopharmaceuticals
Anti-Neprilysin Market
Biopharmaceuticals
HIV Market
Biopharmaceuticals
Global Biopharmaceutical Fermentation Systems Market