
 Micro-Bioreactors Market | 2026-2036
Micro-Bioreactors Market Size, Share, and Industry Trends Forecast 2026-2036
Micro-Bioreactors Market Foresight
EMA's revised Annex 1 guidelines on sterile manufacturing is repositioning capital allocation across upstream processing equipment. Sartorius AG leverages its integrated fluid management portfolio to dominate single-use micro-bioreactor supply to European gene therapy developers. Thermo Fisher Scientific sustains competitive intensity through deep distribution reach into North American academic laboratories. Danaher anchors its position via applied bioscience subsidiaries that specialize in parallel fermentation analytics.
Micro-bioreactors are small-volume culture vessels, typically operating at milliliter to low-liter scales, designed for high-throughput screening of cell culture conditions, strain optimization, and process parameter mapping before scale-up to production bioreactors. Their primary purpose is compressing development timelines by enabling simultaneous evaluation of hundreds of culture variables with minimal media consumption. Lab-scale systems occupy the largest installed base across pharmaceutical companies and contract research organizations, though modular systems are expanding fastest as facilities seek reconfigurable platforms that accommodate diverse cell types. Fed-batch technology retains dominant share in biopharmaceutical applications where titer maximization governs process economics, while continuous flow configurations are gaining traction in specialty chemicals production.
FDA process analytical technology initiatives and EMA quality-by-design frameworks jointly elevate the documentation burden for micro-bioreactor data integrity, particularly where outputs directly inform commercial process submissions. ISO 13485 quality management standards and GMP-adjacent equipment qualification protocols further differentiate suppliers capable of delivering validated systems from instrumentation vendors lacking regulatory infrastructure. Stakeholders must evaluate whether supplier audit trails and software compliance architectures match the evidentiary demands of downstream commercial filing pathways.
Market Dynamics
Cell therapy developers are compressing timelines from candidate selection to IND filing, forcing parallel adoption of micro-bioreactor fleets that can execute hundreds of simultaneous process parameter sweeps. This acceleration imperative is restructuring supplier relationships around data integrity architectures and validation documentation depth.
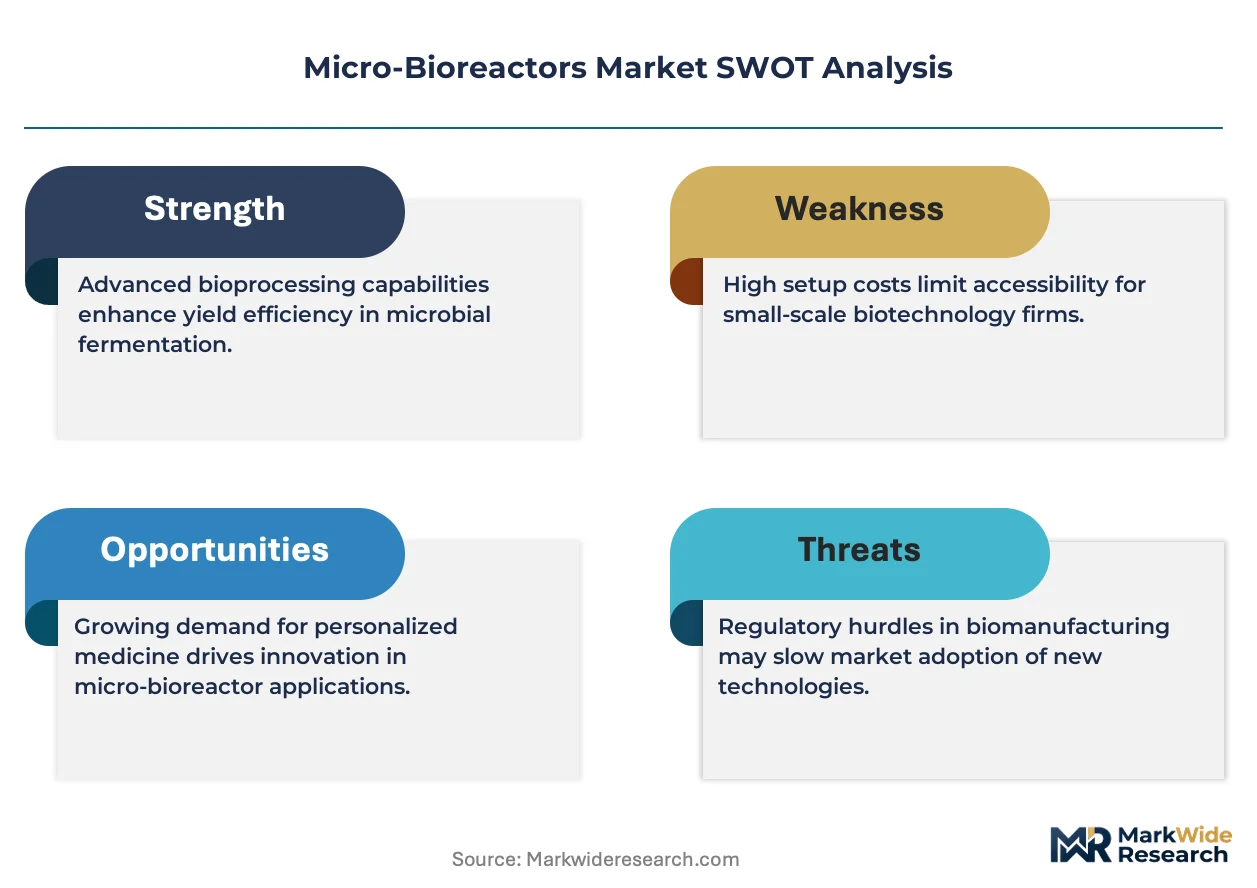
Growth Catalysts
- FDA Process Analytical Technology:The framework mandates real-time quality monitoring, elevating micro-bioreactors with integrated Raman spectroscopy and capacitance probes for cell density tracking.
- Gene therapy manufacturing:Viral vector producers require rapid clone screening to identify high-producing cell lines before expensive scale-up commitments.
- Single-use materials:Film technologies eliminate cleaning validation burdens and cross-contamination risks between campaigns.
Market Restraints
- Perfusion media costs:Chemically defined formulations for sensitive cell types command premium pricing that constrains high-throughput experimental scale.
- Sensor supply concentration:Dissolved oxygen and pH probe manufacturing concentrates in German and Swiss component suppliers, creating single-source vulnerabilities.
- EMA Annex 1 compliance:Revised sterile manufacturing guidelines impose qualification documentation that extends equipment procurement cycles by four to six months.
Strategic Opportunities
- India biologics corridor:CDSCO regulatory harmonization with ICH standards is attracting contract development investment that requires screening infrastructure.
- Microphysiological systems convergence:Organ-on-chip platforms are integrating micro-bioreactor modules for pharmacokinetic modeling.
- Outcome-based service contracts:Equipment vendors are bundling consumables, software licenses, and application support into multi-year performance agreements.
Industry Challenges
- Bioprocess data science talent:Facilities struggle to hire computational biologists capable of extracting actionable insights from high-dimensional cell culture datasets.
- Legacy system integration:Manufacturing execution systems at established biopharmaceutical sites require custom middleware to ingest micro-bioreactor data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro-Bioreactors Market |
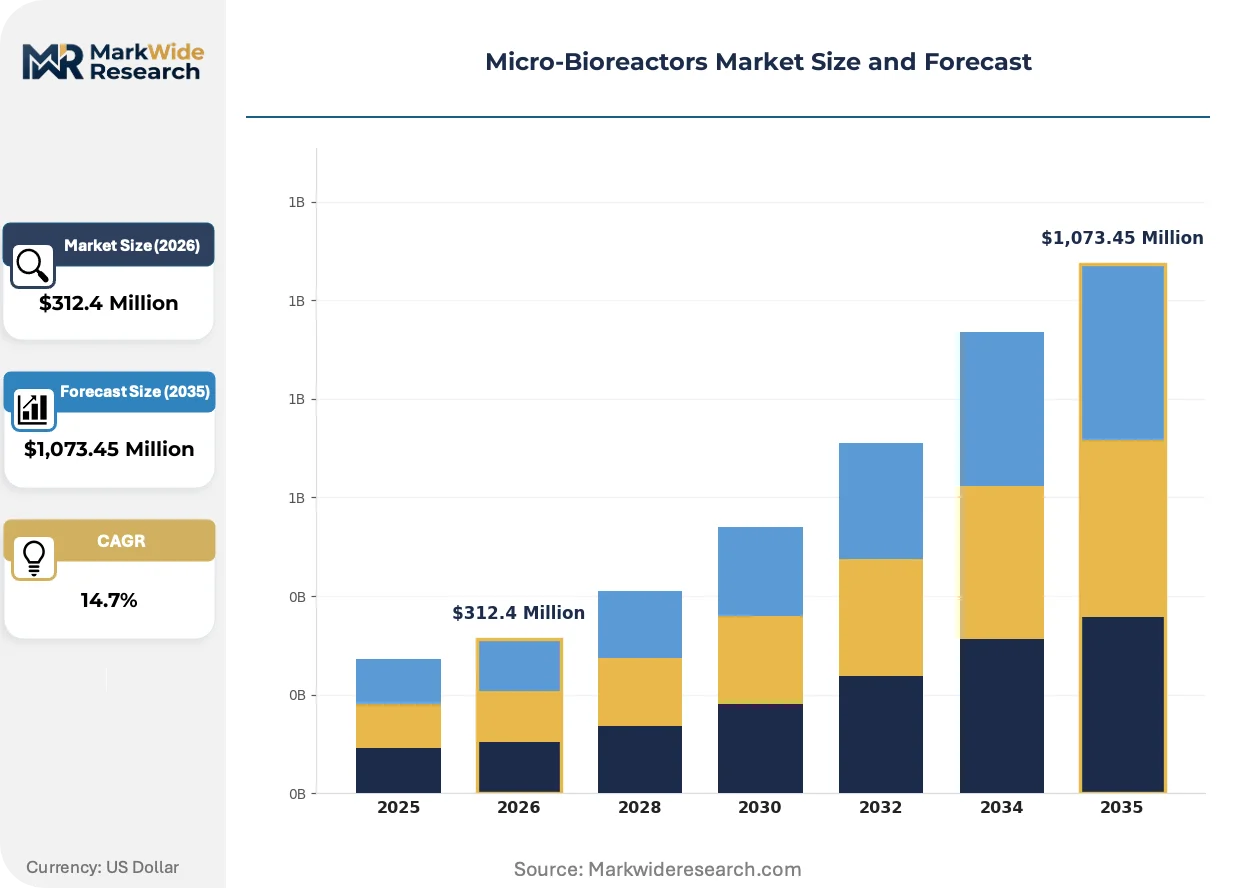
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $1,073.45 Million |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lab-Scale, Pilot-Scale, Commercial-Scale, Multi-Use Technology: Continuous Flow, Batch Processing, Fed-Batch, Modular Systems Application: Biopharmaceuticals, Biofuels, Specialty Chemicals, Food & Beverages End User: Research Institutions, Pharmaceutical Companies, Biotech Firms, Academic Laboratories |
| Companies Covered | Sartorius AG, Thermo Fisher Scientific, Danaher, Eppendorf AG, Merck KGaA, Infors AG, Applikon Biotechnology, m2p-labs GmbH, Lonza Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro-Bioreactors Market Shifts & Advancements
Automation architectures are eliminating manual sampling and offline analytics from upstream process development. Vendors are competing on closed-loop control capabilities that compress design-of-experiment cycles from weeks to days.
Machine learning-driven process control is automating fed-batch parameter optimization across parallel culture vessels. Cell therapy developers in Boston and San Francisco are deploying these systems to execute thousands of media composition permutations. The technology is automating the transition from heuristic process design to model-predictive control that anticipates nutrient depletion before metabolic stress manifests.
EMA's revised Annex 1 guidelines on sterile manufacturing are mandating contamination control strategies that extend to small-scale equipment. This is forcing micro-bioreactor suppliers to implement isolator-compatible designs and closed sampling systems. European gene therapy facilities are responding by consolidating procurement around vendors with pre-validated GMP documentation packages.
Biopharmaceutical procurement teams are unbundling equipment purchases from long-term consumables contracts. Large molecule developers in Massachusetts and North Carolina are negotiating separate agreements for vessels, sensors, and media to optimize total cost of ownership. This behavior is most pronounced among CDMOs managing multiple client programs with divergent cell line requirements.
Micro-Bioreactors Market Segmentation
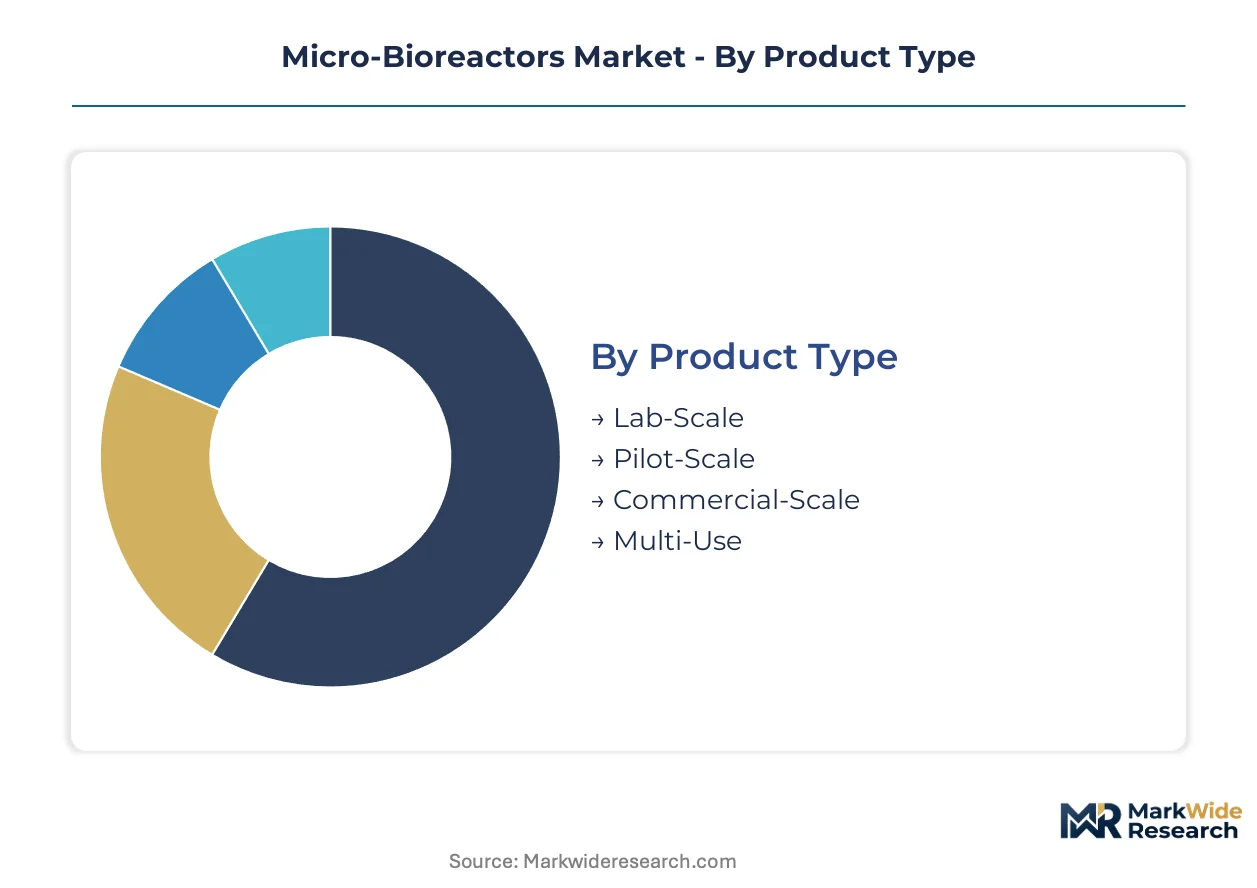
Micro-bioreactor segmentation reflects divergent capital intensity and regulatory exposure across the development-to-manufacturing continuum. Procurement patterns split between standardized platforms for high-throughput screening and validated systems for GMP-adjacent process characterization.
Product Type:
Standardization dominates at screening scales while customization intensifies as vessels approach commercial process qualification thresholds.
- Lab-Scale:Milliliter to low-liter vessels engineered for parallel experimental design with minimal media consumption. Demand concentrates at contract research organizations in Germany and Massachusetts executing cell line development campaigns for viral vector producers. These systems prioritize throughput density over process control precision.
- Pilot-Scale:Intermediate volume platforms bridging design-of-experiment outputs to manufacturing scale validation. Biopharmaceutical companies in North Carolina and California deploy these for engineering run confirmation before technology transfer to production facilities. FDA process analytical technology documentation requirements elevate software compliance specifications.
- Commercial-Scale:Validated systems for GMP process performance qualification studies.
- Multi-Use:Reconfigurable platforms accommodating diverse cell types across sequential programs.
Most installed capacity flows through Lab-Scale. Expansion is steepest in Pilot-Scale.
Technology:
Capital deployment patterns track process economics: batch modes minimize equipment cost while continuous configurations optimize productivity metrics for high-value products.
- Fed-Batch:Dominant configuration for monoclonal antibody and recombinant protein production where titer maximization governs process economics. Pharmaceutical companies in Switzerland and Ireland standardize on these systems for clone screening before scale-up commitments. EMA quality-by-design frameworks mandate extensive parameter mapping that fed-batch platforms execute efficiently.
- Modular Systems:Reconfigurable architectures enabling rapid switchover between microbial, mammalian, and insect cell applications. Contract manufacturers in Singapore and South Korea invest here to serve diverse client portfolios without dedicated asset lock-in. Automation integration reduces campaign changeover validation burden.
- Continuous Flow:Perfusion-based operation for specialty chemicals and select biopharmaceutical applications.
- Batch Processing:Simplest operational mode for early-stage strain characterization.
Revenue concentration sits with Fed-Batch. Modular Systems are gaining share fastest.
Application:
Regulatory stringency and margin structure vary dramatically across end-markets, dictating equipment specification tiers.
- Biopharmaceuticals:Cell and gene therapy manufacturing dominates capital allocation, with viral vector developers requiring rapid clone screening to compress IND timelines. Facilities in Boston and Basel prioritize closed-system designs and pre-validated software packages to satisfy FDA and EMA filing requirements.
- Specialty Chemicals:Enzyme and biocatalyst producers in the Netherlands and Japan leverage micro-bioreactors for metabolic pathway optimization. Lower regulatory documentation burden permits faster experimental iteration compared to pharmaceutical applications.
- Biofuels:Algal and yeast strain development for renewable fuel applications.
- Food & Beverages:Fermentation optimization for cultured proteins and novel ingredients.
Biopharmaceuticals command the highest equipment specification tier. Specialty Chemicals show the steepest volume climb.
End User:
Procurement authority and technical specification depth diverge between research-driven and commercially-focused organizations.
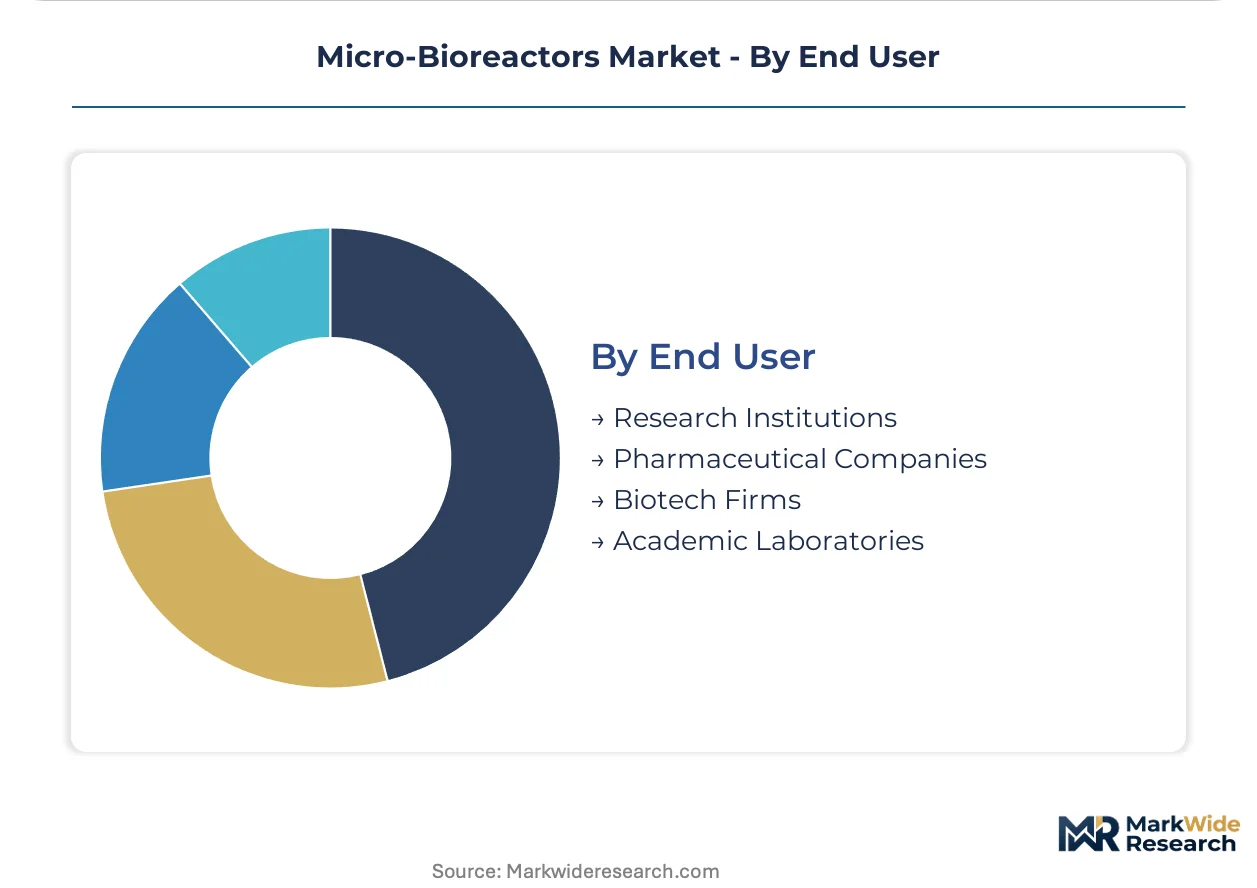
- Pharmaceutical Companies:Integrated biopharmaceutical firms in Germany and Switzerland maintain captive micro-bioreactor fleets for internal pipeline programs. These buyers demand comprehensive validation documentation and long-term service agreements. Capital budgets prioritize regulatory compliance architecture over unit cost minimization.
- Biotech Firms:Venture-backed developers in San Francisco and Cambridge compress timelines through outsourced screening partnerships or leased equipment arrangements. Cash conservation drives preference for consumables-inclusive service contracts over capital purchases.
- Research Institutions:National laboratories and independent research centers.
- Academic Laboratories:University-based groups with limited capital budgets.
Pharmaceutical Companies represent the largest revenue pool. Biotech Firms are expanding procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German process engineers and Swiss instrumentation specialists anchor European bioprocessing talent clusters that service contract manufacturers across the continent.
United States
Venture-backed cell therapy developers in Boston and San Francisco compress IND timelines through outsourced screening partnerships. FDA process analytical technology guidelines mandate real-time quality monitoring that elevates equipment specifications. North Carolina's Research Triangle hosts biopharmaceutical engineering runs that bridge micro-bioreactor outputs to manufacturing scale validation.
Germany
Sartorius AG and Eppendorf AG anchor a dense supplier cluster serving European biologics production networks. EMA quality-by-design frameworks reshape equipment validation requirements for commercial process submissions. Bavaria's instrumentation corridor concentrates dissolved oxygen and pH probe manufacturing, creating component supply vulnerabilities.
Switzerland
Integrated biopharmaceutical firms in Basel maintain captive micro-bioreactor fleets for internal pipeline programs. Swissmedic regulations align with EMA Annex 1 sterile manufacturing guidelines that extend qualification documentation cycles. The country's precision engineering heritage supports sensor probe manufacturing concentration.
India
CDSCO regulatory harmonization with ICH standards attracts contract development investment requiring screening infrastructure. The central government's PLI scheme for pharmaceuticals incentivizes domestic biologics manufacturing capacity. Maharashtra's biotech corridor near Mumbai emerges as a demand center for modular micro-bioreactor platforms.
Singapore
Contract manufacturers invest in reconfigurable micro-bioreactor architectures to serve diverse client portfolios without asset lock-in. The city-state's national pharmaceutical regulator maintains alignment with FDA and EMA standards for technology transfer documentation. Bioprocessing facilities in Tuas Biomedical Park execute rapid campaign changeovers between microbial and mammalian cell applications.
Micro-Bioreactors Market Competitive Landscape
The competitive structure tilts toward diversified life science conglomerates with integrated fluid management portfolios. German and Swiss instrumentation specialists command premium positioning through regulatory documentation depth. Three archetypes dominate: integrated conglomerates with multi-product life science portfolios, specialized bioprocessing equipment pure-plays, and applied bioscience subsidiaries of industrial holding companies. Competitive moves concentrate on strategic partnerships for software compliance architectures and geographic expansion into Asian biologics corridors.
Among German-based precision instrumentation groups, Sartorius AG and Eppendorf AG exemplify the integrated fluid management archetype that dominates European gene therapy supply. Thermo Fisher Scientific represents the diversified conglomerate model with deep distribution reach into North American academic laboratories. Danaher occupies a position within the applied bioscience holding company tier, anchoring competitive intensity through subsidiaries specializing in parallel fermentation analytics.
| Leading Market Players |
|---|
| Sartorius AG |
| Thermo Fisher Scientific |
| Danaher |
| Eppendorf AG |
| Merck KGaA |
| Infors AG |
| Applikon Biotechnology |
| m2p-labs GmbH |
| Lonza Group |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between GMP-validated systems and research-grade platforms manifests in both equipment pricing and supply chain sourcing strategies. Premium-tier vendors command substantial markups through pre-qualified documentation packages that accelerate FDA and EMA filing timelines, while commodity-tier suppliers compete on consumables bundling and academic distribution reach. This divergence reshapes procurement patterns as biopharmaceutical companies prioritize regulatory compliance architecture over unit cost minimization.
Pricing Analysis
Bundled service contracts versus unbundled equipment purchases define the dominant pricing split across buyer archetypes. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by validation depth, software compliance architecture, and after-sales support intensity. Price compression runs through research-grade segments as consumables-inclusive service contracts displace capital purchases among cash-constrained biotech firms. Academic laboratories exhibit highest price sensitivity, while integrated pharmaceutical companies prioritize total cost of ownership calculations that weight regulatory risk mitigation above upfront expenditure.
Supply Chain Analysis
India's PLI scheme for pharmaceuticals and domestic-content preferences in China's biologics corridor are reshaping component sourcing strategies for equipment manufacturers. Precision sensor manufacturing concentrates in Germany and Switzerland, with dissolved oxygen and pH probe fabrication anchored in Bavaria's instrumentation corridor. Plastic film technologies for single-use vessels draw from specialized polymer suppliers in the United States and Japan. Single-source vulnerability in German probe manufacturing creates supply chain risk exposure. Distribution runs through authorized distributor networks serving contract manufacturers and direct sales teams for large pharmaceutical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in GMP-validated system tiers where documentation depth commands pricing power, while single-use consumables bundling captures recurring revenue streams that offset equipment margin pressure.
For Market Incumbents: Hedge against unbundling pressure by deepening software compliance architectures and expanding outcome-based service contracts that lock in multi-year consumables commitments. Incumbent vendors face emerging threat from modular platform specialists offering rapid cell-type reconfiguration. Priority lever rests on backward integration into sensor probe manufacturing to reduce German supply concentration exposure. For New Entrants and Emerging Players: Enter via India's biologics corridor where CDSCO regulatory harmonization attracts contract development investment requiring screening infrastructure. Most penetrable white space sits in modular systems for Asian CDMOs managing diverse client portfolios. Go-to-market angle emphasizes rapid campaign changeover capabilities and isolator-compatible designs that satisfy EMA Annex 1 sterile manufacturing guidelines. For Investors and Strategic Acquirers: Consolidation pressure builds where specialized bioprocessing equipment pure-placks lack regulatory documentation infrastructure to serve commercial-stage biopharmaceutical clients. Long-term viability favors applied bioscience subsidiaries with parallel fermentation analytics capabilities and established FDA filing support track records. Signal to watch: unbundling behavior among Massachusetts and North Carolina CDMOs negotiating separate vessel, sensor, and media agreements.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Documentation Package Investment | Pre-validated software architectures accelerate EMA Annex 1 compliance timelines for gene therapy developers. |
| Single-Use Materials Backward Integration | In-house film manufacturing reduces cross-contamination risks and cleaning validation burdens between campaigns. |
| Machine Learning Control Platform Launch | Automated fed-batch parameter optimization compresses design-of-experiment cycles from weeks to days. |
| India Biologics Corridor Expansion | CDSCO regulatory alignment with ICH standards attracts contract development investment requiring screening infrastructure. |
| Sensor Probe Manufacturing Partnership | Dual-sourcing arrangements with Swiss and German component suppliers mitigate single-source vulnerability exposure. |
Research Methodology
Multiple input streams — primary interviews with bioprocess engineers and regulatory affairs leads, secondary validation through FDA 510(k) filings and EMA submission databases, and trade data from customs records — were reconciled through bottom-up and top-down triangulation. Conversations with contract manufacturing executives, academic laboratory directors, and GMP quality officers informed equipment specification and procurement pattern assessments. Secondary sources included SEC filings from diversified life science conglomerates, ISO 13485 certification registries, and biopharmaceutical facility expansion announcements.
Cross-referencing historical shipment data against expert panel inputs anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product tier, technology configuration, application end-market, and buyer archetype. CAGRs were derived through regression analysis of installed base expansion and replacement cycle timing. Industry-specific forecast inputs incorporated gene therapy pipeline advancement rates and CDMO capacity buildout announcements.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time equipment pricing transparency introduce uncertainty bands around revenue projections. Forecasts reflect assumptions regarding EMA Annex 1 implementation timelines and FDA process analytical technology adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Airlift Bioreactors Market
Biotechnology Equipment
Global Biotechnology Instruments Market
Biotechnology Equipment
Restriction Endonucleases Products (REP) Market
Biotechnology Equipment
Biobanking Equipment Market
Biotechnology Equipment
Global Transfection Reagents and Equipment Market
Biotechnology Equipment
Global Large Molecule Bioanalytical Technologies Market
Biotechnology Equipment
Global Biotechnology Reagents Market
Biotechnology Equipment
Biotechnology Reagent and Kits Market
Biotechnology Equipment
Moving Bed Bioreactor Market
Biotechnology Equipment
Cartridges for RT-PCR Automatic Systems Market
Biotechnology Equipment
Tissue Microarrayer Market
Biotechnology Equipment
Bioprocess Analyzers and Technology Market
Biotechnology Equipment
Automated Molecular Diagnostics Testing System Market
Biotechnology Equipment
Laboratory Shakers Market
Biotechnology Equipment
Global Biological Microscope Objectives Market
Biotechnology Equipment
Fluorescence Immunoassay Analyzers Market