
 Whole Plasmid Sequencing Market | 2026-2036
Whole Plasmid Sequencing Market Size, Share, and Industry Trends Forecast 2026-2036
Whole Plasmid Sequencing Market Insights
Platform licensing revenue is reshaping competitive economics in the Whole Plasmid Sequencing space. Illumina leverages its installed base of sequencing instruments to sustain recurring consumable sales. Pacific Biosciences anchors its position through long-read accuracy for complex plasmid structures. Oxford Nanopore Technologies competes on portable workflow flexibility for distributed validation labs.
Whole plasmid sequencing denotes the determination of complete nucleotide order in circular extrachromosomal DNA molecules, typically spanning 1 kb to 500 kb, using methods that resolve secondary structures and repeat regions without fragmentation. The technique serves primary industrial purpose in verifying vector integrity for gene therapy manufacturing and synthetic biology construction pipelines. Next-generation sequencing occupies the largest installed base for high-throughput plasmid screening, while nanopore sequencing captures the fastest expansion as real-time read lengths exceed prior technical limits. Synthetic biology applications concentrate margin pools where turnkey validation contracts bundle sequencing with functional confirmation.
FDA gene therapy guidance and EMA advanced therapy medicinal product frameworks both mandate plasmid identity verification as a release criterion for clinical-grade material. ISO 17025 accreditation requirements shape demand by restricting contract testing to laboratories with documented chain-of-custody protocols. Stakeholders must monitor how regulatory convergence between FDA and EMA on circular DNA specifications alters equipment qualification standards and service provider eligibility.
Market Dynamics
Long-read nanopore accuracy is displacing short-read methods as the dominant validation approach for circular DNA, compressing turnaround times from weeks to hours and forcing incumbent platforms to defend installed bases through consumable bundling.
Growth Catalysts
- FDA gene therapy guidance:Mandates plasmid identity verification as a release criterion for clinical-grade material, creating non-negotiable demand from contract manufacturers.
- Synthetic biology construction pipelines:Turnkey validation contracts now bundle sequencing with functional confirmation, expanding addressable spend per project.
- ISO 17025 accreditation requirements:Restrict contract testing to laboratories with documented chain-of-custody protocols, filtering out unqualified competitors and concentrating volume with accredited providers.
Market Restraints
- Consumable cost concentration:Flow cell and reagent pricing tied to semiconductor supply chains creates margin volatility for high-throughput operators.
- Reference database gaps:Incomplete circular DNA annotation limits automated variant calling accuracy for novel synthetic constructs.
- Platform lock-in effects:Bioinformatics pipeline investments create switching costs that delay adoption of superior sequencing chemistries.
Strategic Opportunities
- Distributed validation labs:Portable nanopore workflows enable point-of-manufacture testing, reducing sample transit risk for temperature-sensitive materials.
- EMA advanced therapy medicinal product frameworks:Regulatory convergence with FDA specifications creates service standardization opportunities across Atlantic markets.
- CRISPR guide RNA verification:Emerging demand for off-target screening in therapeutic editing workflows extends plasmid sequencing into adjacent quality control steps.
Industry Challenges
- Bioinformatics specialist scarcity:Shortage of personnel trained in circular genome assembly algorithms constrains lab scaling.
- Equipment qualification timelines:FDA 21 CFR Part 11 compliance for electronic records extends validation periods for new instrument installations.
- Cross-platform standardization delays:Absence of universal plasmid reference materials complicates inter-laboratory reproducibility studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Whole Plasmid Sequencing Market |
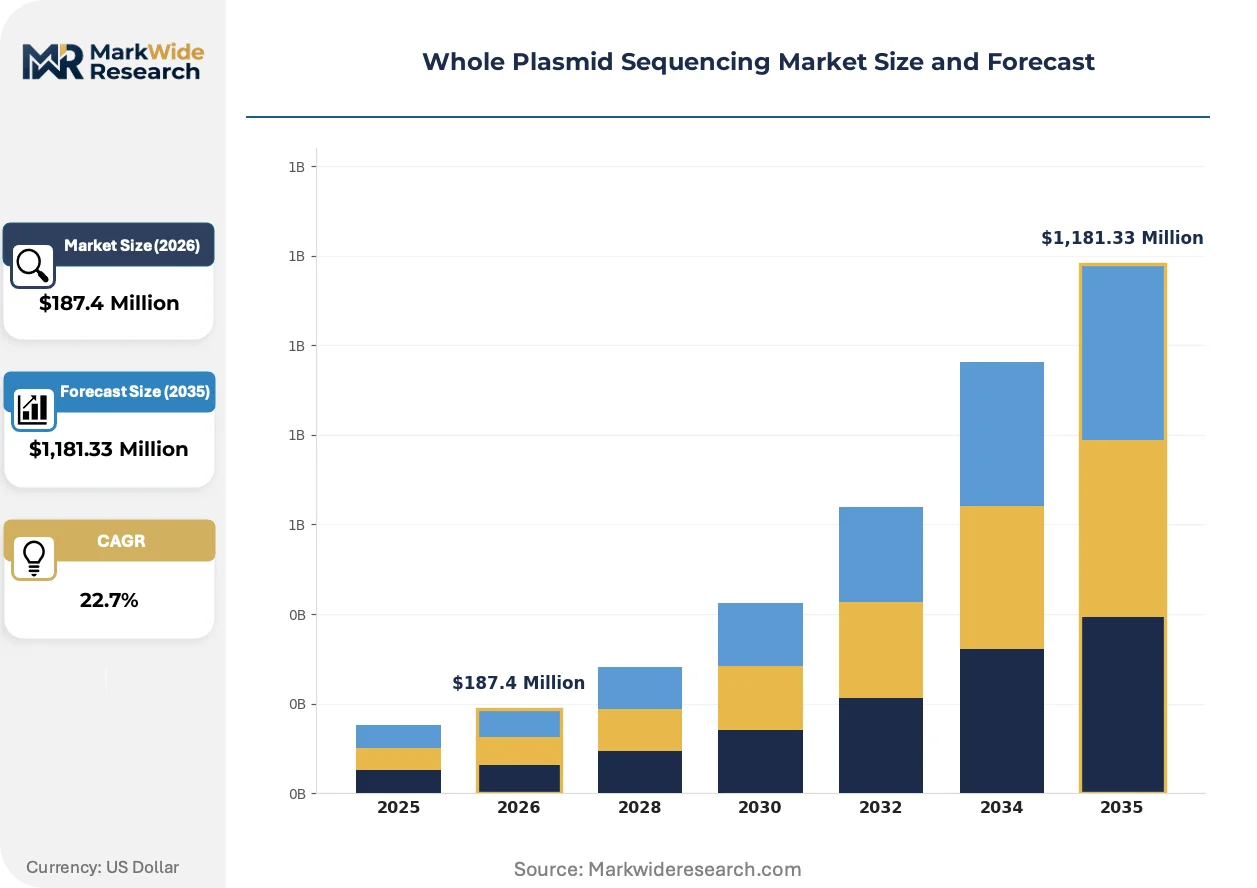
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Next-Generation Sequencing, Sanger Sequencing, Pyrosequencing, Nanopore Sequencing, Single-Molecule Real-Time Technology: Sequencing by Synthesis, Sequencing by Ligation, Ion Semiconductor, Optical Mapping, Array-Based Methods Application: Gene Cloning, Antibiotic Resistance Profiling, Synthetic Biology, Plasmid Validation, Genetic Engineering End User: Biotechnology Firms, Pharmaceutical Developers, Academic Research Centers, Contract Research Organizations |
| Companies Covered | Illumina, Thermo Fisher Scientific, Pacific Biosciences, Oxford Nanopore Technologies, QIAGEN, Eurofins Genomics, Azenta Life Sciences, GenScript Biotech, BGI Genomics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Whole Plasmid Sequencing Market Trends and Innovations
Real-time basecalling and adaptive sampling are compressing the economics of plasmid verification, enabling same-day release decisions that previously required batch sequencing queues.
Nanopore sequencing is virtualizing the physical fragmentation step that historically limited circular DNA resolution. Gene therapy developers are adopting this chemistry for complex vector structures exceeding 50 kb. The technology is virtualizing sample preparation bottlenecks, collapsing the distinction between research-grade screening and GMP-release testing.
EMA advanced therapy medicinal product frameworks are tightening documentation requirements for plasmid master cell banks. Manufacturers must now submit full sequence traceability from starting materials to final product. European contract testing organizations are responding by investing in redundant sequencing platforms to eliminate single-point-of-failure risks during regulatory inspections.
CDMOs are unbundling sequencing services from broader analytical packages, selling verification as standalone line items rather than embedded costs. This transparency is accelerating price discovery and compressing margins for undifferentiated providers. The shift is most visible in United States gene therapy clusters, where sponsor companies now negotiate sequencing rates separately from fill-finish contracts.
Whole Plasmid Sequencing Market Segmentation
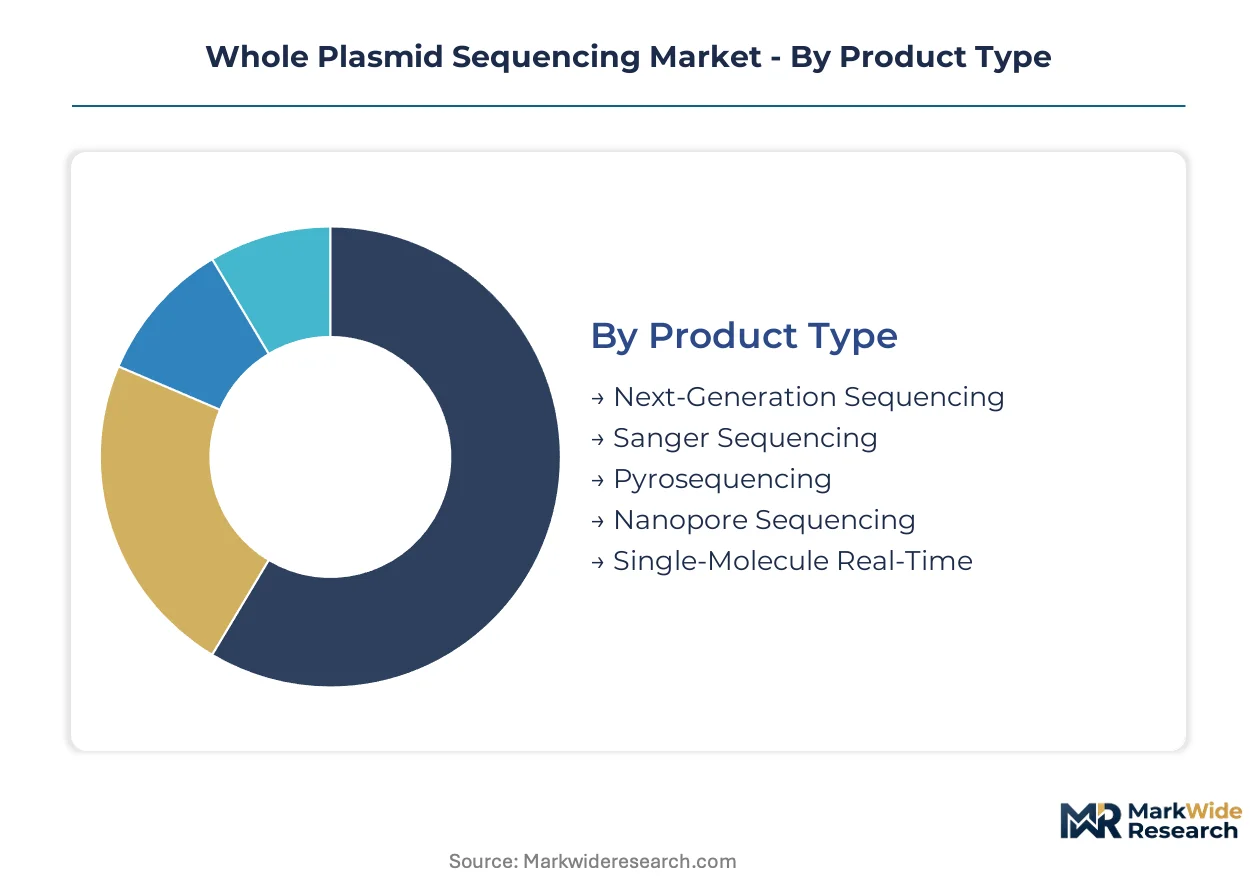
Whole plasmid sequencing segments reflect divergent technical requirements across clinical-grade verification and research-grade screening. Platform selection hinges on read length demands, turnaround constraints, and regulatory documentation burdens specific to gene therapy release workflows.
Product Type:
Mature short-read platforms dominate installed base economics while emerging long-read chemistries capture the fastest expansion in circular DNA resolution.
- Next-Generation Sequencing:Short-read platforms deliver high-throughput parallel processing of 150-300 bp fragments with mature bioinformatics pipelines. United States contract manufacturers deploy these systems for batch screening of standard vector constructs where reference genomes are well-annotated.
- Nanopore Sequencing:Real-time electrical signal detection enables continuous reads exceeding 100 kb without fragmentation, resolving complex secondary structures and repetitive elements. Gene therapy developers in Massachusetts and California clusters adopt this chemistry for vectors exceeding 50 kb with intricate regulatory cassettes.
- Single-Molecule Real-Time:Zero-mode waveguide technology captures polymerase kinetics for epigenetic modification detection alongside primary sequence.
- Sanger Sequencing:Capillary electrophoresis remains the gold standard for targeted verification of cloning junctions and promoter regions.
- Pyrosequencing:Emulsion PCR coupled with luciferase detection suits rapid mutation scanning in antibiotic resistance profiling applications.
Next-Generation Sequencing handles the majority of throughput; Nanopore Sequencing is gaining share fastest as read lengths extend past prior technical limits.
Technology:
Cost tier differentiation separates premium optical systems from semiconductor-based instruments with lower capital barriers.
- Sequencing by Synthesis:Reversible terminator chemistry with fluorescent detection anchors Illumina's installed base, offering lowest per-base cost for high-volume plasmid screening. Biotechnology firms in San Diego and Boston corridors standardize on this modality for GMP-release documentation.
- Sequencing by Ligation:Oligonucleotide ligation with fluorescent readout enables mate-pair library construction for scaffolding large circular constructs. Academic centers deploy this approach for de novo assembly of novel synthetic plasmids lacking reference sequences.
- Ion Semiconductor:pH-based detection of hydrogen ion release during polymerization eliminates optical components, reducing instrument footprint for distributed validation labs.
- Optical Mapping:Single-molecule imaging of restriction enzyme patterns provides long-range structural validation complementary to sequence data.
- Array-Based Methods:Hybridization to tiled oligonucleotide probes enables rapid presence-absence screening of known vector elements.
Sequencing by Synthesis commands the largest revenue pool; Sequencing by Ligation shows steepest expansion trajectory in synthetic biology construction pipelines.
Application:
Volume concentrates in regulatory-mandated verification while margin pools shift toward bundled functional confirmation services.
- Plasmid Validation:Complete sequence verification against designed reference constitutes the primary quality control gate for clinical-grade material release. FDA gene therapy guidance mandates identity confirmation as a non-negotiable criterion, driving sustained demand from contract manufacturers.
- Synthetic Biology:Turnkey contracts now bundle sequencing with functional assays, expanding addressable spend per construction project. European biotechnology clusters in Cambridge UK and Basel pursue integrated validation workflows for cell-free protein synthesis systems.
- Gene Cloning:Insert verification and orientation confirmation remain routine screening steps in molecular biology core facilities.
- Antibiotic Resistance Profiling:Mobile genetic element tracking supports epidemiological surveillance and hospital infection control programs.
- Genetic Engineering:CRISPR guide RNA expression cassette verification extends into off-target screening for therapeutic editing workflows.
Plasmid Validation absorbs the dominant share of sequencing volume; Synthetic Biology is expanding most quickly as bundled service contracts proliferate.
End User:
Customer type determines procurement sophistication, with pharmaceutical developers demanding ISO 17025 accreditation and academic centers prioritizing cost per sample.
- Pharmaceutical Developers:Gene therapy sponsors require full chain-of-custody documentation and validated bioinformatics pipelines for regulatory submission. FDA 21 CFR Part 11 compliance for electronic records extends equipment qualification timelines, concentrating volume with established service providers.
- Contract Research Organizations:Independent verification capacity allows sponsor companies to outsource release testing while maintaining arm's-length quality oversight. United States CROs in Research Triangle Park and Maryland I-270 corridor invest in redundant platforms to eliminate single-point-of-failure risks.
- Biotechnology Firms:Mid-stage companies balance in-house screening capacity against outsourced validation for GMP milestones.
- Academic Research Centers:Core facilities prioritize instrument utilization rates and multi-user accessibility over regulatory documentation depth.
Pharmaceutical Developers generate the largest contract value per engagement; Contract Research Organizations are climbing the fastest as CDMOs unbundle sequencing from broader analytical packages.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sequencing service capacity clusters near gene therapy manufacturing hubs and synthetic biology research corridors. Platform vendors prioritize instrument placement in markets with stringent circular DNA release criteria.
United States
FDA gene therapy guidance mandates plasmid identity verification for clinical-grade material release. Massachusetts and California biotechnology clusters drive concentrated demand for rapid turnaround validation. CDMOs in Research Triangle Park unbundle sequencing from analytical packages to accelerate price discovery.
Germany
EMA advanced therapy medicinal product frameworks tighten documentation requirements for plasmid master cell banks. ISO 17025 accreditation filters contract testing eligibility to laboratories with validated chain-of-custody protocols. Heidelberg and Munich synthetic biology centers invest in redundant sequencing platforms for regulatory inspection readiness.
United Kingdom
Cambridge biotechnology corridor pursues integrated validation workflows for cell-free protein synthesis systems. MHRA convergence with FDA specifications on circular DNA standards shapes equipment qualification timelines. London contract research organizations expand service portfolios around plasmid verification to capture sponsor outsourcing.
China
NMPA tightening of gene therapy manufacturing standards drives domestic sequencing infrastructure investment. Beijing and Shanghai gene therapy developers adopt long-read chemistries for complex vector structures exceeding 50 kb. BGI Genomics anchors national capacity expansion for clinical-grade plasmid release testing.
Switzerland
Swissmedic alignment with EMA frameworks creates service standardization opportunities for Atlantic market access. Basel pharmaceutical developers require full sequence traceability from starting materials to final product. Zurich contract testing laboratories qualify nanopore workflows for distributed point-of-manufacture validation.
Whole Plasmid Sequencing Market Competitive Landscape
Platform-integrated conglomerates and specialized long-read innovators split the market between consumable bundling strategies and chemistry differentiation. Illumina leverages its installed base to sustain recurring reagent sales through validated pipeline lock-in. Pacific Biosciences and Oxford Nanopore Technologies anchor opposing ends of the accuracy-portability spectrum. Competitive moves concentrate on strategic partnerships with CDMOs and geographic expansion into gene therapy manufacturing clusters.
Among platform-integrated conglomerates, Thermo Fisher Scientific exemplifies the consumable-recurring model through broad analytical workflow integration. QIAGEN occupies a position within the sample-to-insight archetype, bundling extraction chemistries with sequencing services. Eurofins Genomics represents the contract-testing scale tier, anchoring European validation capacity expansion. These three entities collectively illustrate how vendor strategies diverge between instrument placement and service provision.
| Leading Market Players |
|---|
| Illumina |
| Thermo Fisher Scientific |
| Pacific Biosciences |
| Oxford Nanopore Technologies |
| QIAGEN |
| Eurofins Genomics |
| Azenta Life Sciences |
| GenScript Biotech |
| BGI Genomics |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in short-read sequencing services across the United States is compressing spot pricing for standard plasmid verification, forcing providers to bundle consumables and bioinformatics support to defend margin pools. This utilization imbalance concentrates pricing power with platform-integrated conglomerates while fragmenting margins for standalone service laboratories.
Pricing Analysis
Consumable-recurring revenue tiers dominate lifetime value capture, with flow cell and reagent contracts anchoring multi-year customer lock-in. Pricing stratifies across GMP-certified, ISO 17025-accredited, and research-grade service levels, with FDA 21 CFR Part 11 compliance commanding substantial premia. Cost compression in research-grade screening intensifies as CDMOs unbundle sequencing from analytical packages. Academic core facilities exhibit highest price sensitivity; gene therapy sponsors demonstrate lowest sensitivity due to regulatory non-negotiability.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for semiconductor-dependent flow cell components. Manufacturing concentration rests on the United States, Germany, and China for instrument assembly, with Singapore and Ireland anchoring reagent formulation. Single-source vulnerability persists for specialized polymerases and modified nucleotides. Distribution runs through direct platform vendor channels for pharmaceutical developers and regional distributor networks for academic customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward gene therapy sponsors as CDMO consolidation concentrates procurement volume with fewer contract manufacturers. This fragmentation among service buyers is accelerating price discovery and squeezing undifferentiated providers.
For Market Incumbents: Pre-empt nanopore displacement by embedding short-read platforms into validated GMP workflows with 21 CFR Part 11 compliance documentation. Anchor capacity expansion in Massachusetts and California clusters where sponsor density sustains premium pricing. Defend against portable workflow entrants by locking CDMOs into consumable-committed multi-year contracts. For New Entrants and Emerging Players: Distributed point-of-manufacture validation in European gene therapy clusters represents the most penetrable entry point, where EMA documentation requirements outpace incumbent service capacity. CRISPR guide RNA verification workflows offer adjacent white-space expansion beyond core plasmid sequencing. Pursue strategic partnerships with mid-stage biotechnology firms lacking in-house GMP infrastructure as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across nanopore sequencing sub-segments as portable instruments reduce facility qualification burdens. Long-term viability favors service providers with ISO 17025 accreditation depth and redundant platform portfolios over pure instrument manufacturers. Target acquisition archetypes include regional contract testing laboratories with validated chain-of-custody protocols. Watch for FDA-EMA regulatory convergence on circular DNA specifications as the key inflection signal for cross-Atlantic service standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Convergence Partnership | EMA-FDA alignment on plasmid specifications enables unified service contracts across Atlantic markets. |
| Nanopore Workflow Qualification | Oxford Nanopore's portable chemistry collapses turnaround times for point-of-manufacture release testing. |
| Consumable Bundling Expansion | Illumina's reagent-committed contracts lock CDMOs into high-margin recurring revenue streams. |
| ISO 17025 Accreditation Investment | Eurofins Genomics anchors European validation capacity with documented chain-of-custody protocols. |
| Synthetic Biology Turnkey Integration | Cambridge UK clusters bundle sequencing with functional assays for cell-free protein synthesis systems. |
Research Methodology
Operator-level perspectives from gene therapy development executives, CDMO quality directors, regulatory affairs specialists, and sequencing platform product managers anchored the qualitative base. Primary interviews combined with secondary validation from FDA guidance documents, EMA advanced therapy frameworks, ISO 17025 accreditation registries, and SEC filings from listed sequencing providers. Bottom-up service provider capacity estimates triangulated against top-down gene therapy pipeline forecasts.
Scenario-bracketing framed analytical outputs across the projection horizon, with base, upside, and downside cases reflecting regulatory approval velocity and platform substitution rates. Segmentation dimensions modeled include sequencing chemistry, read length requirements, regulatory documentation burden, end-user sophistication tier, and geographic manufacturing cluster. CAGRs derived from installed base expansion curves and consumable pull-through assumptions, with gene therapy clinical trial initiation rates and synthetic biology construction pipeline growth as primary forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in biotechnology venture funding availability and gene therapy M&A activity would shift the trajectory. Forecasts reflect assumptions on regulatory timeline stability and platform chemistry transition rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Nutrigenomics Market
Genomics
Plant Genomics Market
Genomics
Omics Lab Services Market
Genomics
Global Immune Repertoire Sequencing Market
Genomics
Pharmacogenomic (Pgx) Testing Market
Genomics
Genetic Material Market
Genomics
Pre-Pregnancy Genetic Testing Market
Genomics
Mrna Sequencing Market
Genomics
North America Microarray Market
Genomics
Global Blockchain in Genomic Data Management Market
Genomics
Europe Genetic Testing Market
Genomics
Antisense Oligonucleotides Market
Genomics
UAE Genetic Testing Market
Genomics
Japan Next Generation Sequencing Market
Genomics
Global NGS Sample Preparation Market
Genomics
NGS-Based RNA-Sequencing Market