
 Global Biological Data Visualization Market | 2026-2036
Global Biological Data Visualization Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biological Data Visualization Market Intelligence
Pharmaceutical companies are pivoting toward integrated multi-omics pipelines, pulling demand for visualization platforms that unify genomics, proteomics, and metabolomics outputs. Thermo Fisher Scientific leverages its instrument-to-software ecosystem to anchor enterprise contracts with top-twenty pharma R&D divisions. Illumina competes through proprietary genome browser integrations that tighten sequencing-to-analysis workflows. Genedata specializes in scalable cloud deployments for academic consortia, occupying a distinct niche between commercial biotech and open-source alternatives.
Biological data visualization encompasses software systems and computational interfaces that render genomic sequences, protein interaction networks, metabolic pathways, and cellular imaging data into interpretable graphical formats, typically processing file sizes from gigabytes to terabytes through optimized rendering engines and GPU acceleration. Its primary commercial purpose is to compress discovery timelines in life-science R&D by enabling bench scientists to detect patterns without writing custom code. Desktop software retains the largest installed base among legacy pharma IT environments, while cloud platforms represent the fastest-expanding segment as hybrid compute policies relax security objections. Network analysis tools command premium pricing due to specialized algorithm requirements and scarce bioinformatics talent, whereas mobile applications remain marginal outside field-based agricultural genomics use cases.
FDA software validation guidelines, EMA's evolving expectations for computational reproducibility in regulatory submissions, and ISO 13485 quality management standards collectively shape product roadmaps and customer procurement checklists across North America and Europe. HIPAA compliance requirements in the United States and GDPR constraints in Europe add data-sovereignty layers that favor regional cloud hosting partnerships over centralized global infrastructure. Stakeholders must monitor how AI Act transparency mandates in Europe and emerging FDA guidance on machine-learning-enabled visualization tools redefine acceptable evidentiary standards for clinical decision-support outputs.
Market Dynamics
Cloud-native visualization architectures are compressing deployment timelines for multi-omics pipelines, forcing incumbent desktop software vendors to reengineer rendering engines for hybrid compute environments or lose enterprise renewals.
Growth Catalysts
- NIH funding concentration:Sustained federal investment in genome sequencing initiatives at the National Institutes of Health drives procurement of network analysis tools and genome browsers across Boston and San Diego biotech clusters.
- FDA software validation standards:Formal guidance on analytical software validation for clinical decision-support tools creates procurement mandates that accelerate platform upgrades in pharmaceutical R&D divisions.
- GPU acceleration maturation:Optimized rendering engines leveraging graphics processing units now process terabyte-scale cellular imaging datasets without custom code, expanding addressable users beyond bioinformatics specialists.
Market Restraints
- Scarce bioinformatics talent:Specialized algorithm requirements for protein interaction network analysis create persistent hiring bottlenecks that inflate implementation costs and extend deployment timelines.
- GDPR data-sovereignty requirements:European Union constraints on cross-border genomic data transfer favor regional cloud hosting partnerships over centralized global infrastructure, fragmenting vendor scale economics.
- Legacy IT lock-in:Desktop software retains entrenched positions in pharmaceutical IT environments with rigid hybrid compute policies that delay cloud migration decisions despite security objections easing.
Strategic Opportunities
- Underpenetrated agricultural genomics:Field-based mobile visualization applications remain marginal outside crop breeding programs, presenting white space for purpose-built interfaces in Brazil and Argentina soybean research stations.
- EU AI Act transparency mandates:Emerging European requirements for explainable machine-learning outputs in clinical decision-support create compliance-driven replacement cycles for black-box visualization tools.
- Metabolomics-proteomics convergence:Unified platforms integrating mass spectrometry outputs with pathway visualization capture budget shifts as pharmaceutical companies consolidate point solutions into enterprise contracts.
Industry Challenges
- ISO 13485 certification timelines:Quality management system audits for visualization software used in regulated clinical settings extend product launch schedules by twelve to eighteen months.
- HIPAA technical safeguard integration:Encryption and access control implementations for United States healthcare deployments create engineering complexity that strains mid-tier vendor development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biological Data Visualization Market |
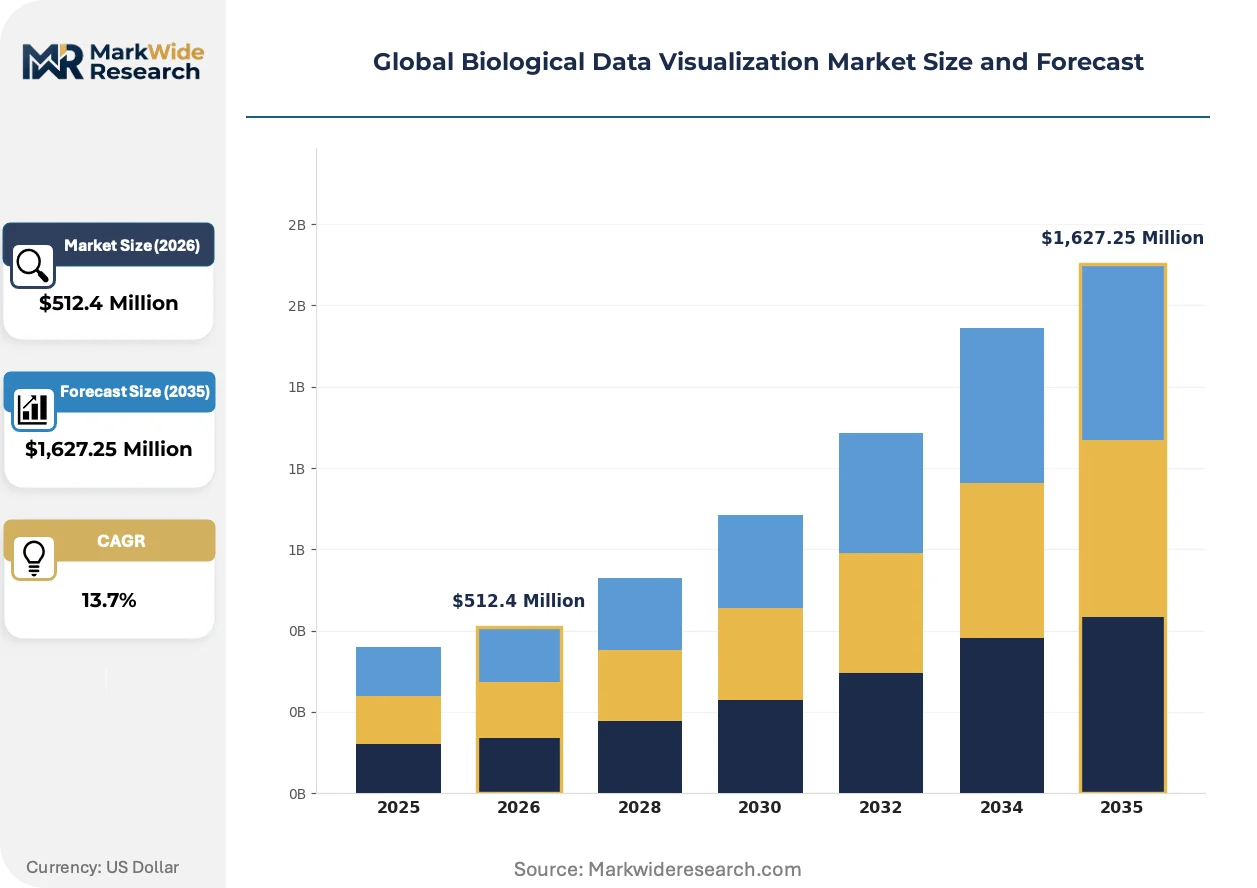
| Market Size in 2026 | $512.4 Million |
| Market Size in 2035 | $1,627.25 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Software, Web-based Tools, Mobile Applications, Cloud Platforms, Embedded Systems Technology: Graph Visualization, Heatmaps, Genome Browsers, Network Analysis, 3D Imaging Application: Genomics, Proteomics, Metabolomics, Systems Biology, Pharmacogenomics End User: Biotechnology Firms, Academic Researchers, Pharmaceutical Companies, Bioinformatics Service Providers, Government Agencies |
| Companies Covered | 10x Genomics, Bio-Rad Laboratories, Illumina, GE HealthCare, QIAGEN, Thermo Fisher Scientific, Agilent Technologies, Genedata, Danaher, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biological Data Visualization Market Strategic Shifts & Innovations
Rendering engines are absorbing artificial intelligence inference layers that automate pattern detection in microscopy images, compressing the interpretive gap between raw data acquisition and hypothesis generation for bench scientists.
WebAssembly-based browser visualization is absorbing compute-intensive alignment algorithms previously restricted to server-side processing, enabling pharmaceutical discovery teams to interact with billion-read genome assemblies without local installation. Thermo Fisher Scientific and Illumina are embedding these modules into instrument control software, tightening sequencing-to-analysis loops. This architecture is absorbing latency constraints that previously forced batch-processing workflows, collapsing feedback cycles from days to minutes.
EMA computational reproducibility expectations for regulatory submissions now require version-controlled visualization pipelines with documented parameter sets, forcing vendors to embed audit trails and deterministic rendering into product roadmaps. European pharmaceutical companies are pre-qualifying platforms against these standards before procurement. Contract research organizations serving EMA submission pathways represent the most affected segment, with quality assurance departments now vetoing tools lacking reproducibility certifications.
Subscription pricing models are displacing perpetual licenses in academic consortia and mid-tier biotechnology companies, unbundling maintenance from upfront capital commitments and accelerating procurement cycles. Cloud platform vendors capture this shift through consumption-based metering that aligns costs with actual compute utilization. This transition is most visible in United States NIH-funded research institutions, where budget volatility favors operational expenditure classification over capital equipment depreciation schedules.
Global Biological Data Visualization Market Segmentation
Segmentation in biological data visualization tracks how regulatory certification burdens, computational architectures, and end-user technical sophistication fragment procurement patterns across the life sciences R&D value chain.
Product Type:
ISO 13485 quality management certification applies selectively: desktop software and embedded systems face mandatory audits for clinical decision-support deployments, while web-based tools and mobile applications navigate lighter conformity assessment paths unless integrated into regulated workflows.
- Desktop Software:Legacy installed-base leader in pharmaceutical IT environments with entrenched validation protocols. Demand concentrates in United States and German pharma headquarters where hybrid compute policies delay cloud migration despite easing security objections.
- Cloud Platforms:Fastest-expanding segment as consumption-based metering aligns with NIH-funded research budget volatility. HIPAA technical safeguards and GDPR data-sovereignty requirements favor regional hosting partnerships over centralized infrastructure.
- Web-based Tools:WebAssembly architectures now absorb compute-intensive alignment algorithms previously server-bound.
- Mobile Applications:Marginal outside Brazilian and Argentinian field-based agricultural genomics use cases.
- Embedded Systems:Tight instrument-to-software integration with thermocycler and sequencer control modules.
Desktop software sits at the top of the volume ranking, with cloud platforms climbing the fastest.
Technology:
Cost tier separation is pronounced: network analysis commands premium pricing due to scarce algorithm talent, while heatmap visualization approaches commoditization in academic licensing.
- Network Analysis:Specialized graph algorithms for protein interaction mapping require dedicated bioinformatics expertise. Procurement concentrates in Boston and San Diego biotech clusters where NIH-funded consortia drive enterprise contract values.
- Genome Browsers:Sequence navigation interfaces with proprietary integrations tightening sequencing-to-analysis loops. United States research institutions represent the dominant demand concentration with budget volatility favoring subscription over perpetual licensing.
- Graph Visualization:Pathway and ontology rendering with standardized layout algorithms.
- Heatmaps:Expression matrix visualization approaching utility-tier pricing in bulk academic deployments.
- 3D Imaging:GPU-accelerated cellular and molecular structure rendering with terabyte-scale dataset requirements.
Network analysis captures the highest margin tier, with 3D imaging expanding most quickly as GPU acceleration matures.
Application:
Application maturity correlates with data standardization: genomics leads with established file formats, while metabolomics-proteomics convergence creates integration complexity that favors unified platform procurement.
- Genomics:Mature segment with standardized FASTA, BAM, and VCF formats enabling interoperable visualization. Demand anchors in United States NIH-funded initiatives and Chinese national genome projects with distinct data-sovereignty requirements.
- Metabolomics:Mass spectrometry output visualization with emerging pathway integration requirements. Pharmaceutical R&D divisions in Switzerland and Germany are consolidating point solutions into enterprise contracts capturing this convergence.
- Proteomics:Mass spectrometry and interaction network visualization with complex quantitative workflows.
- Systems Biology:Multi-omics integration platforms requiring specialized mathematical modeling layers.
- Pharmacogenomics:Clinical decision-support applications with FDA validation guidance creating procurement mandates.
Genomics holds the largest installed base, with metabolomics gaining share fastest as pharmaceutical companies pivot toward integrated multi-omics pipelines.
End User:
Customer type determines pricing architecture: pharmaceutical companies negotiate enterprise site licenses with validation documentation, while academic researchers drive subscription displacement through consumption-based cloud metering.
- Pharmaceutical Companies:Enterprise procurement with ISO 13485 and FDA software validation requirements. Top-twenty R&D divisions in the United States, Switzerland, and Japan anchor contract values through instrument-to-software ecosystem commitments.
- Academic Researchers:NIH-funded United States institutions and European Research Council grantees with budget volatility favoring operational expenditure classification over capital depreciation schedules.
- Biotechnology Firms:Venture-backed startups in Cambridge, Massachusetts and Basel with rapid scaling visualization needs.
- Bioinformatics Service Providers:Contract research organizations with EMA reproducibility certification requirements.
- Government Agencies:National genome initiatives with data-sovereignty and security clearance constraints.
Pharmaceutical companies dominate enterprise value, with academic researchers showing the steepest expansion trajectory in cloud platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston biotech corridor anchors procurement intensity for network analysis tools and genome browsers, with NIH-funded research institutions and pharmaceutical R&D divisions driving enterprise contract values across three continents.
United States
FDA software validation guidance for clinical decision-support tools creates mandatory procurement cycles across top-twenty pharmaceutical R&D divisions. HIPAA technical safeguard requirements favor regional cloud hosting partnerships over centralized infrastructure. The San Diego and Boston clusters concentrate demand for multi-omics visualization platforms among venture-backed biotechnology firms.
Germany
EMA computational reproducibility expectations for regulatory submissions force version-controlled pipeline adoption among contract research organizations. ISO 13485 quality management certification timelines extend product launch schedules for visualization software vendors. The Munich and Heidelberg life-science clusters drive enterprise procurement of pathway visualization tools among mid-cap pharmaceutical companies.
Switzerland
Swissmedic regulatory frameworks align with EMA standards while maintaining distinct data-sovereignty requirements for genomic data processing. Basel anchors pharmaceutical headquarters procurement of instrument-to-software ecosystem contracts. The Zurich academic corridor favors subscription-based cloud metering over perpetual licensing for metabolomics-proteomics convergence platforms.
China
NMPA evolving standards for AI-enabled medical software create compliance preparation cycles among domestic visualization developers. National genome initiatives with data-sovereignty constraints favor regional cloud infrastructure over foreign-hosted platforms. The Beijing-Tianjin and Yangtze River Delta clusters concentrate government-funded research procurement of domestic genome browser alternatives.
United Kingdom
GDPR constraints on cross-border genomic data transfer fragment vendor scale economics for European pharmaceutical deployments. The Cambridge and Oxford research corridors drive academic consortia adoption of WebAssembly-based browser visualization tools. London-based contract research organizations pre-qualify platforms against EMA reproducibility standards before procurement.
Global Biological Data Visualization Market Key Industry Players
Strategic partnerships dominate the current landscape as instrument manufacturers tighten sequencing-to-analysis loops through embedded visualization modules. The vendor base concentrates among three tiers: diversified life-science conglomerates with instrument-to-software ecosystems, specialized bioinformatics software developers with cloud-native architectures, and open-source platform providers with academic consortium traction. M&A activity and technology licensing agreements represent the primary competitive moves, with incumbents acquiring GPU-accelerated rendering capabilities and cloud deployment expertise.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Illumina exemplify instrument-anchored competitive positioning, while Genedata occupies a distinct niche among specialized software developers serving academic consortia and mid-tier biotechnology firms. These three entities represent divergent strategic archetypes: ecosystem lock-in through hardware-software integration, proprietary workflow tightening from sequencing through analysis, and scalable cloud deployments for budget-volatile research institutions.
| Leading Market Players |
|---|
| 10x Genomics |
| Bio-Rad Laboratories |
| Illumina |
| GE HealthCare |
| QIAGEN |
| Thermo Fisher Scientific |
| Agilent Technologies |
| Genedata |
| Danaher |
| Others |
Cost & Logistics Intelligence
GPU-accelerated rendering engine maturation simultaneously compresses per-terabyte processing costs and concentrates supply leverage among cloud infrastructure providers with captive silicon partnerships. Pharmaceutical procurement teams now negotiate enterprise visualization contracts against a backdrop where compute hardware commoditization clashes with specialized bioinformatics talent scarcity.
Pricing Analysis
Input-cost pass-through from GPU and cloud infrastructure pricing dominates vendor margin structures, with subscription-based SaaS tiers displacing perpetual licenses across NIH-funded research institutions. Price differentiation rests on ISO 13485 certification grade and volume-scale enterprise commitments, with validated clinical decision-support modules commanding three-to-five-fold premiums over academic licensing tiers. Pricing pressure stems from WebAssembly-based browser tools collapsing deployment friction for mid-tier alternatives. Academic researchers exhibit highest price sensitivity, favoring consumption-metered operational expenditure over capital depreciation schedules.
Supply Chain Analysis
China's data-sovereignty requirements and India's software services concentration are reshaping sourcing patterns for visualization platform development and regional cloud hosting partnerships. Core dependencies center on NVIDIA GPU supply allocations, hyperscaler data center capacity in Frankfurt and Singapore, and specialized bioinformatics algorithm talent pools anchored in Boston and Basel. Single-source vulnerability concentrates in GPU accelerator supply chains subject to export control restrictions. Distribution runs through direct enterprise sales teams for pharmaceutical accounts and academic consortium procurement channels for research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where FDA validation documentation and EMA reproducibility certifications now separate viable procurement candidates from commodity alternatives. Demand is consolidating toward premium specifications as pharmaceutical R&D divisions pre-qualify platforms against tightening regulatory evidentiary standards.
For Market Incumbents: Hedge against WebAssembly-native entrants by embedding deterministic rendering audit trails into existing genome browser architectures before EMA submission pathways harden requirements. Prioritize backward integration into GPU-optimized cloud infrastructure partnerships to defend margin position against hyperscaler pricing leverage.
For New Entrants and Emerging Players: Launch via mobile-first field interfaces targeting Brazilian and Argentinian agricultural genomics stations, where underpenetrated crop breeding programs lack incumbent software lock-in. Capture metabolomics-proteomics convergence workflows through purpose-built mass spectrometry visualization modules that pharmaceutical R&D divisions are consolidating into enterprise contracts.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized bioinformatics software developers with cloud-native architectures but limited instrument ecosystem integration. Five-to-ten year viability hinges on platform consolidation into multi-omics pipelines. Target acquisition archetypes: GPU-accelerated rendering specialists with FDA pre-submission documentation. The signal to watch is EMA reproducibility certification adoption rates among contract research organizations.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | WebAssembly architectures collapse deployment timelines for NIH-funded consortia seeking consumption-based metering. |
| FDA Validation Documentation Investment | Pre-submission pathways for clinical decision-support tools create procurement mandates across top-twenty pharmaceutical R&D divisions. |
| GPU Rendering Engine Acquisition | Terabyte-scale cellular imaging processing capabilities differentiate premium network analysis tool pricing tiers. |
| Regional Cloud Hosting Partnership | GDPR and HIPAA technical safeguard compliance favors Frankfurt and Singapore data center deployments over centralized infrastructure. |
| Academic Consortium Subscription Conversion | Operational expenditure classification aligns with NIH budget volatility and displaces perpetual license revenue models. |
Research Approach
Coverage spans the United States, Germany, Switzerland, China, and the United Kingdom, with primary inputs from each market's distinct regulatory and procurement environments. The approach combines structured interviews with bioinformatics platform directors, pharmaceutical R&D procurement leads, regulatory affairs specialists at contract research organizations, and academic consortium IT directors with secondary validation against FDA guidance documents, EMA submission databases, NIH funding allocation records, and ISO certification registries. Bottom-up segment sizing triangulates against top-down market envelope checks.
Rate-of-change decomposition separates volume expansion in cloud platform deployments from value capture in premium network analysis and 3D imaging segments across the projection horizon. The analytical framework models deployment model, organization size tier, vertical application concentration, and regional regulatory cluster as primary segmentation dimensions. CAGRs derive from fitted growth curves adjusted for NIH funding trajectory assumptions and pharmaceutical R&D budget elasticity estimates. Industry-specific inputs include genome sequencing throughput projections and mass spectrometry instrument installation base growth.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated FDA guidance finalization or abrupt GPU supply chain disruptions. Forecasts reflect documented assumptions regarding hybrid compute policy relaxation timelines and EMA reproducibility standard enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioinformatics
Microrna (Mirna) Market
Bioinformatics
Bioinformatics in IVD Testing Market
Bioinformatics
Bioinformatics Software Market
Bioinformatics
Bioinformatics Market
Bioinformatics
South Korea Computational Biology Market
Bioinformatics
Global Computational Biology Market
Bioinformatics
Europe AI in Life Science Analytics Market
Bioinformatics
US Computational Biology Market
Bioinformatics
Germany Computational Biology Market
Bioinformatics
Germany Computer-Aided Drug Discovery Market
Bioinformatics
In Silico Protein Design Market
Bioinformatics
Global Chemoinformatics Market
Bioinformatics
LAMEA Computer-Aided Drug Discovery Market
Bioinformatics
China Computational Biology Market
Bioinformatics
North America Computational Biology Market
Bioinformatics
AI in Life Science Analytics Market