
 OEM Coatings Market | 2026-2036
OEM Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
OEM Coatings Market Outlook
Direct supply agreements between coating formulators and automotive original equipment manufacturers is tilting toward integrated service contracts that bundle application technology with material supply. PPG Industries Inc. leverages its global refinish network to anchor long-term OEM partnerships across multiple vehicle platforms. Axalta Coating Systems Ltd specializes in mobility-focused color and performance systems that differentiate its position in electric vehicle programs. Kansai Paint Co. Ltd competes aggressively in Asian assembly plant proximity, sustaining cost advantages through regional manufacturing density.
OEM coatings constitute formulated protective and decorative films applied to original manufactured goods prior to sale, typically comprising binders, pigments, solvents or water carriers, and functional additives engineered for adhesion, durability, and appearance. These systems cure through thermal, radiation, or chemical crosslinking mechanisms to achieve specified gloss, hardness, and corrosion resistance thresholds on metal, plastic, or composite substrates. Waterborne coatings now lead technology transitions as environmental compliance tightens, while solvent-borne systems retain margin pools in heavy industrial equipment where performance specifications remain most demanding. Powder coatings represent the fastest-growing product category, driven by zero-VOC profiles and overspray recovery economics that appeal to sustainability-minded automotive and electronics manufacturers.
EPA regulations in the United States restrict hazardous air pollutant emissions from coating operations, compelling facility-level technology upgrades and material substitutions. REACH and the EU Green Deal in Europe mandate chemical substance registration and carbon footprint disclosure that reshape formulation choices and supply chain documentation requirements. Stakeholders must monitor how evolving multi-jurisdictional chemical frameworks interact with customer sustainability scorecards to determine which technology investments will secure future OEM qualification status.
Market Dynamics
Automotive electrification is compressing bake-cycle requirements and substrate portfolios, forcing formulators to rebuild thermal cure profiles around battery enclosure materials and lightweight composites that solvent-borne systems struggle to wet properly.
Growth Catalysts
- EU Green Deal carbon border adjustments:European automakers now specify coating carbon footprints in supplier scorecards, accelerating waterborne and powder system qualifications.
- China domestic vehicle production scaling:Local assembly plant density around Shanghai and Guangzhou creates captive demand for regional formulation capacity.
- UV-curable primer technology maturation:Reduced energy consumption and line-speed flexibility attract premium electric vehicle manufacturers seeking process efficiency.
Market Restraints
- Titanium dioxide supply concentration:Pigment sourcing from limited sulfate-process suppliers exposes formulators to input cost volatility.
- REACH substance authorization timelines:ECHA's evolving restricted substance list forces premature reformulation investments before revenue certainty.
- Heavy industrial equipment performance thresholds:Solvent-borne corrosion protection retains specification lock-in where salt-spray requirements exceed waterborne capabilities.
Strategic Opportunities
- India PLI scheme automotive incentives:Domestic manufacturing subsidies attract coating technical centers to serve emerging local OEM assembly.
- Electronics powder coating penetration:Zero-VOC profiles and overspray recovery economics open appliance and consumer electronics applications.
- Self-healing clearcoat chemistry convergence:Microcapsule and polymer network technologies merge to enable scratch-recovery differentiation in premium vehicle programs.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in hybrid waterborne-UV systems remains concentrated among retiring technical specialists.
- Multi-jurisdictional certification timelines:Simultaneous EPA, REACH, and China MEE registration creates regulatory lag for new product introductions.
- Legacy paint shop retrofit capex:Converting thermal ovens for lower-temperature cure profiles demands capital allocation competing with battery plant investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | OEM Coatings Market |
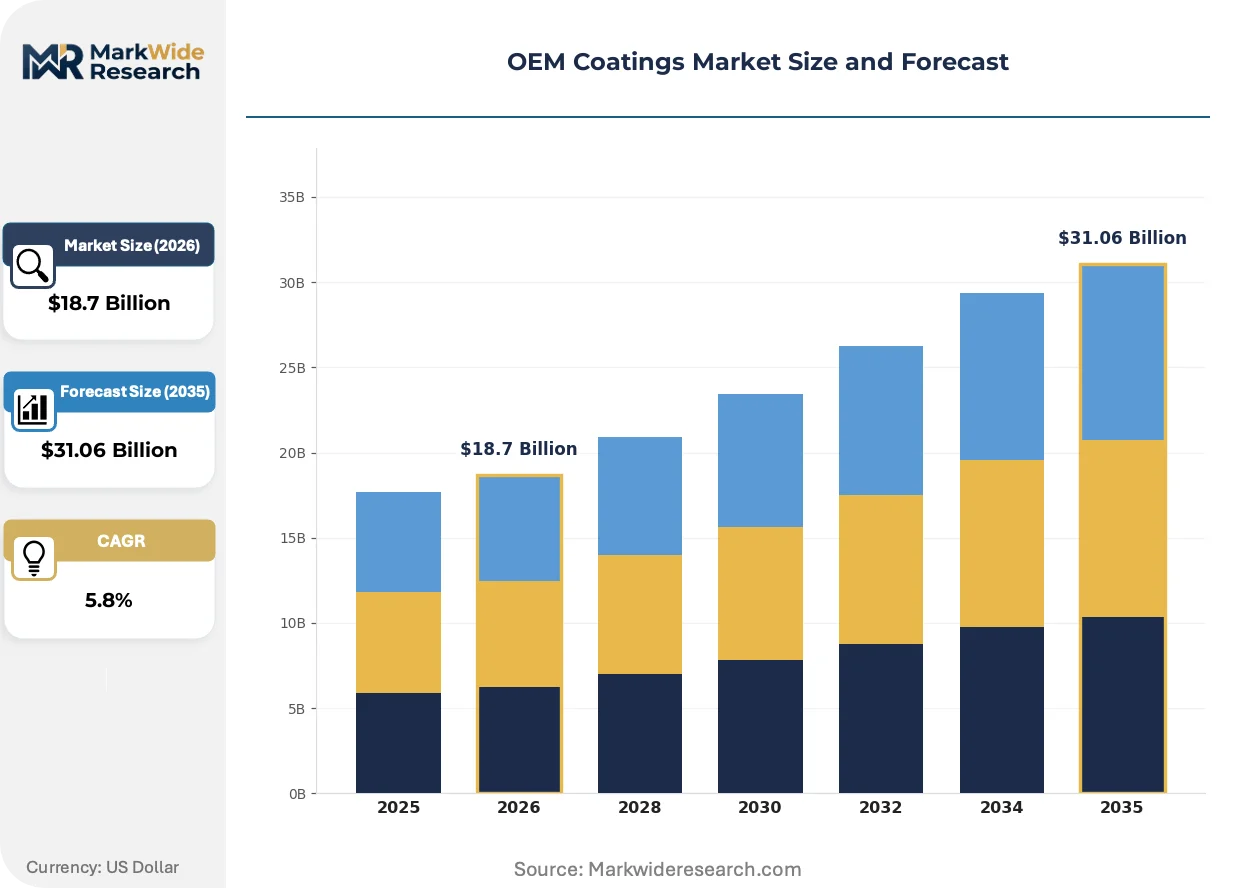
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solvent-borne Coatings, Waterborne Coatings, Powder Coatings, UV-cured Coatings End User: Automotive Manufacturers, Aerospace Companies, Consumer Electronics, Industrial Equipment Manufacturers Technology: Electrostatic Spraying, Conventional Spray Painting, Roller Coating, Dip Coating Application: Exterior Coatings, Interior Coatings, Specialty Coatings, Protective Coatings |
| Companies Covered | Axalta Coating Systems Ltd, The Sherwin-Williams Company, BASF SE, KCC Corporation, Kansai Paint Co. Ltd, PPG Industries Inc., Nippon Paint Holdings Co. Ltd, Berger Paints India Ltd, Akzo Nobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
OEM Coatings Market Strategic Shifts
Coating functionality is expanding beyond protection and aesthetics into thermal management and electromagnetic shielding as vehicle architectures electrify. Formulators now compete on integrated material-performance systems rather than commodity resin supply.
Self-healing clearcoat chemistry is migrating from concept validation to production qualification. Tier 1 suppliers in Germany and Japan are piloting microencapsulated polymer systems that release repair agents upon scratch initiation. This technology is migrating from luxury exterior panels toward high-touch interior surfaces where durability expectations are intensifying.
REACH authorization requirements are tightening substance documentation burdens across European supply chains. ECHA's expanded SCIP database mandates article-level chemical disclosure that forces coating manufacturers to map raw material provenance deeper into additive and catalyst tiers. Automotive OEMs with integrated European assembly are restructuring supplier qualification protocols to preempt registration gaps.
Automotive buyers are consolidating coating procurement through platform-level master service agreements rather than plant-specific spot contracts. German and Korean OEMs now bundle application equipment, technical service, and material supply into multi-year performance contracts. This restructuring concentrates volume with integrated suppliers capable of deploying on-site technical teams across multiple assembly locations.
OEM Coatings Market Segmentation
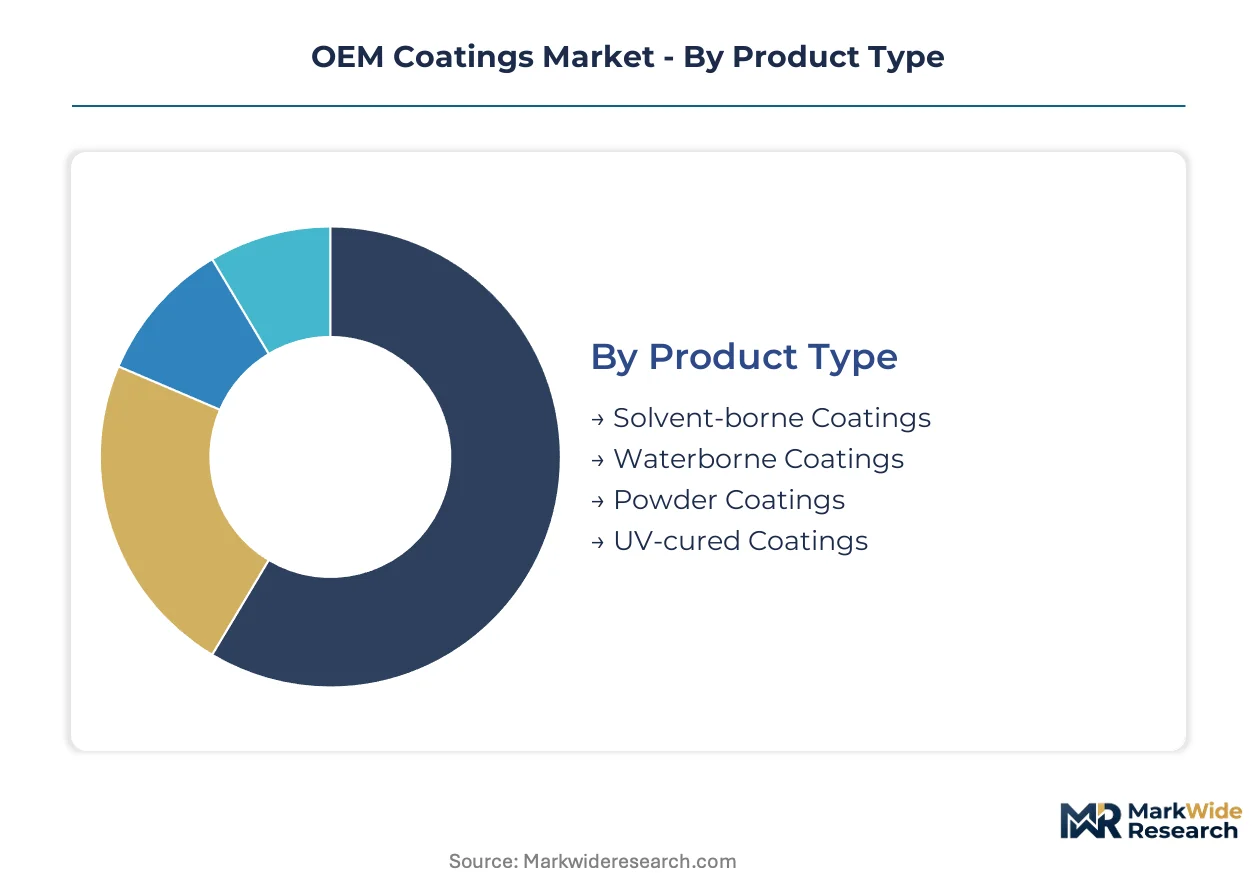
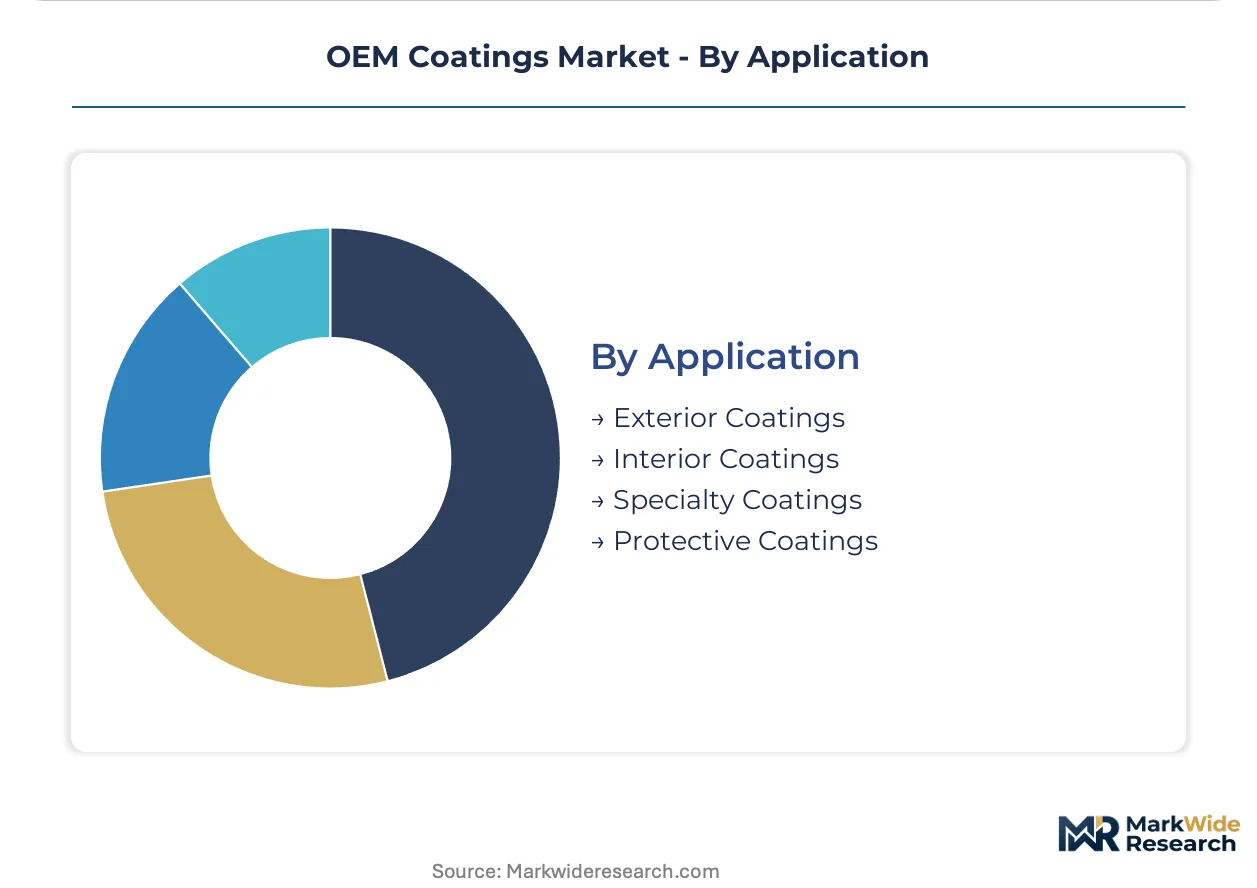
OEM coatings segment along four intersecting dimensions that determine formulation requirements, application protocols, and service intensity. Each category shapes procurement patterns differently across automotive, aerospace, and industrial verticals. Understanding these splits clarifies where technical differentiation commands premium positioning versus where cost efficiency dominates supplier selection.
Product Type:
After-sales service intensity varies sharply across product categories, with waterborne and powder systems demanding sustained technical support for line conversions and cure optimization while solvent-borne coatings rely on established maintenance protocols.
- Waterborne Coatings:These systems employ water as the primary carrier medium with acrylic, polyurethane, or epoxy resin dispersions engineered for low-VOC compliance. Automotive assembly plants in Germany and China now specify waterborne basecoats and clearcoats for new vehicle platforms as EPA and MEE emissions enforcement tightens. Formulators must embed on-site technical teams to manage humidity-controlled spray booth parameters and flash-off timing.
- Powder Coatings:Thermoset or thermoplastic resin powders applied through electrostatic charging achieve zero-VOC profiles with near-complete overspray recovery. Appliance and electronics manufacturers in Japan and South Korea are converting metal enclosure lines to powder systems to satisfy customer sustainability scorecards. Application equipment suppliers bundle powder reclamation systems with material supply contracts to lock in multi-year service relationships.
- Solvent-borne Coatings:Traditional solvent-carried systems retain specification in heavy industrial equipment where salt-spray resistance exceeds waterborne capabilities.
- UV-cured Coatings:Photoinitiator-activated systems cure within seconds under ultraviolet exposure, enabling line-speed flexibility for premium electric vehicle manufacturers.
By volume, solvent-borne coatings lead. By growth pace, powder coatings are ahead.
End User:
Cost tier stratification separates end-user segments, with aerospace and premium automotive programs absorbing formulation premiums while industrial equipment buyers prioritize standard-grade corrosion protection.
- Automotive Manufacturers:Light vehicle and commercial truck producers specify coating systems across exterior body-in-white, interior trim, and underhood applications with exacting gloss and durability protocols. Battery electric vehicle programs in China and Germany are compressing bake cycles and expanding plastic substrate portfolios that challenge conventional solvent-borne wetting. OEMs now bundle application equipment, technical service, and material supply into platform-level master service agreements.
- Aerospace Companies:Commercial aviation and defense contractors demand chromate-free corrosion inhibition and lightning strike conductivity in structural coatings subject to FAA and EASA airworthiness directives. MRO facility proximity drives regional formulation capacity decisions, with technical centers clustering around Toulouse, Hamburg, and Seattle assembly corridors.
- Consumer Electronics:Smartphone, laptop, and appliance manufacturers specify thin-film decorative and protective coatings for metal and plastic enclosures.
- Industrial Equipment Manufacturers:Agricultural, construction, and mining equipment producers prioritize salt-spray resistance and abrasion tolerance over appearance metrics.
Automotive manufacturers command the largest absolute volume. Aerospace companies sustain the highest margin per liter applied.
Technology:
Application technology selection tracks substrate geometry and production volume, with high-complexity automotive bodies favoring electrostatic precision while flat-goods manufacturing gravitates toward roller efficiency.
- Electrostatic Spraying:Charged particle attraction achieves transfer efficiency exceeding 85% on conductive metal substrates, minimizing material waste in high-volume automotive operations. German and Korean OEMs mandate electrostatic application for exterior basecoat and clearcoat layers to meet carbon footprint targets in supplier scorecards. Equipment suppliers differentiate through robotic integration and real-time film thickness monitoring.
- Conventional Spray Painting:Air-atomized application retains relevance for repair operations, prototype builds, and low-volume specialty vehicles where capital-intensive electrostatic installation cannot be amortized.
- Roller Coating:Continuous web application dominates flat metal coil and wood panel processing for appliance and furniture OEMs.
- Dip Coating:Immersion application ensures complete coverage of complex geometries in small parts and fastener manufacturing.
Electrostatic spraying dominates automotive exterior volume. Roller coating achieves the lowest per-square-meter applied cost.
Application:
Maturity gradients separate application segments, with exterior automotive coatings representing a contested, innovation-intensive battleground while protective industrial coatings follow slower specification cycles.
- Exterior Coatings:Visible automotive body panels demand integrated color, gloss, and chip-resistance performance with self-healing clearcoat technologies now entering production qualification. Tier 1 suppliers in Germany and Japan are piloting microencapsulated repair systems that release polymer agents upon scratch initiation. OEM color styling studios now collaborate directly with formulator R&D centers to compress development timelines.
- Specialty Coatings:Thermal management and electromagnetic shielding functionalities are expanding coating value propositions as vehicle architectures electrify. Battery enclosure manufacturers specify ceramic-filled coatings for flame retardancy and dielectric isolation.
- Interior Coatings:Dashboard, door panel, and seating frame applications prioritize scratch resistance and volatile organic compound emissions control for cabin air quality.
- Protective Coatings:Underbody, chassis, and structural applications emphasize corrosion inhibition through cathodic protection compatibility and stone-chip resistance.
Exterior coatings generate the highest revenue per vehicle. Specialty coatings are climbing the fastest as electrification expands functional requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU carbon border adjustments and China's domestic production subsidies are redrawing regional supply maps, forcing formulators to co-locate technical centers with qualifying assembly corridors.
China
Domestic vehicle production scaling around Shanghai and Guangzhou sustains captive demand for regional formulation capacity. MEE emissions enforcement tightens waterborne system specifications for new vehicle platforms. Local suppliers deepen hybrid waterborne-UV capabilities to serve battery electric vehicle programs concentrated in the Yangtze River Delta.
Germany
Automotive OEMs now specify coating carbon footprints in supplier scorecards under EU Green Deal compliance timelines. ECHA's REACH substance authorization forces premature reformulation investments before revenue certainty. Technical centers cluster around Stuttgart and Munich to support platform-level master service agreements with integrated application equipment bundling.
United States
EPA hazardous air pollutant restrictions compel facility-level technology upgrades across automotive assembly plants. IRA clean manufacturing incentives accelerate powder system conversions in appliance and electronics sectors. Coating procurement concentrates in Michigan and Ohio corridor plants serving Detroit Three platform consolidation.
Japan
METI energy efficiency standards compress bake-cycle requirements for electric vehicle coating lines. JIS certification protocols maintain specification lock-in for premium automotive exterior programs. Formulators in Nagoya and Osaka prefectures pilot self-healing clearcoat microencapsulation for high-touch interior surfaces.
India
PLI scheme automotive manufacturing subsidies attract coating technical centers to serve emerging local OEM assembly. BIS voluntary standards for VOC emissions anticipate future mandatory alignment with EU benchmarks. Tamil Nadu and Maharashtra assembly plant density creates regional formulation demand around Chennai and Pune industrial corridors.
OEM Coatings Market Competitive Environment
On the supply side, the industry is consolidating around integrated service providers capable of bundling application technology with material supply. Three strategic archetypes dominate: global diversified chemical conglomerates with captive resin production, specialized coating formulators with mobility-focused color systems, and regional Asian suppliers leveraging assembly plant proximity for cost positioning. Competitive moves concentrate on M&A for technology access and geographic expansion into qualifying manufacturing corridors.
Among North American and European diversified suppliers, PPG Industries Inc., Axalta Coating Systems Ltd, and The Sherwin-Williams Company exemplify the integrated service archetype, anchoring positions through multi-year performance contracts that bundle technical deployment across multiple assembly locations. These entities represent the scale-driven tier where global refinish networks support OEM partnership continuity.
| Leading Market Players |
|---|
| Axalta Coating Systems Ltd |
| The Sherwin-Williams Company |
| BASF SE |
| KCC Corporation |
| Kansai Paint Co. Ltd |
| PPG Industries Inc. |
| Nippon Paint Holdings Co. Ltd |
| Berger Paints India Ltd |
| Akzo Nobel N.V. |
| Others |
Value Chain & Pricing Dynamics
Titanium dioxide sulfate-process suppliers in China and Ukraine anchor pigment cost volatility, concentrating margin pools with formulators who locked long-term offtake before raw material spikes. Waterborne system premiums now capture value from stranded solvent-borne capacity as EPA and MEE enforcement tightens.
Pricing Analysis
Volume-discount tiering separates platform-level master service agreements from plant-specific spot contracts, with German and Korean OEMs bundling application equipment and technical service into multi-year performance commitments. Price differentiation hinges on carbon footprint certification tier and on-site technical deployment density. Cost compression in standard-grade industrial coatings is intensifying because regional Asian suppliers are flooding commodity corrosion protection segments. Industrial equipment manufacturers exhibit highest price sensitivity; premium automotive and aerospace programs absorb formulation premiums with minimal elasticity.
Supply Chain Analysis
Export-control scrutiny on advanced photoinitiator chemistries limits UV-curable precursor flows from select European suppliers, forcing formulators to diversify photoinitiator sourcing. Geographic supply concentration centers on China for titanium dioxide and resin intermediates, Germany for specialty additives, and Japan for automotive-grade polymer dispersions. Raw material portfolios draw from petroleum-derived solvents, bio-based acrylic dispersions, and ceramic-filled functional pigments. Single-source vulnerability in sulfate-process TiO2 exposes margins to input shocks. Distribution feeds from integrated formulator technical centers directly into OEM assembly plant paint shops, bypassing traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as electrification fragments substrate portfolios and bake-cycle requirements, creating niches for specialists who rebuild thermal cure profiles around battery enclosures and lightweight composites.
For Market Incumbents: Pre-empt qualification lockout by embedding on-site technical teams across multiple assembly locations before platform-level master service agreements consolidate volume. Anchor backward integration into captive resin production to defend margin position against regional Asian cost pressure. Secure REACH pre-registration for substitute chemistries before ECHA substance authorization timelines force premature reformulation.
For New Entrants and Emerging Players: India's Tamil Nadu and Maharashtra industrial corridors offer underpenetrated coating technical center potential as PLI scheme subsidies attract domestic OEM assembly. Target powder coating penetration in consumer electronics and appliance manufacturing where zero-VOC profiles and overspray recovery economics open specification windows. Lead with sustainability scorecard compliance as the go-to-market wedge against legacy solvent-borne incumbents.
For Investors and Strategic Acquirers: Capital is best deployed toward hybrid waterborne-UV formulation specialists with demonstrated electric vehicle platform qualifications and retiring technical specialist knowledge capture. Long-term viability hinges on regulatory chemistry pivot capabilities across EPA, REACH, and China MEE frameworks. Watch for self-healing clearcoat production qualification announcements as the inflection signal for premium vehicle program capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive acrylic and polyurethane dispersion supply secures margin control against petrochemical volatility. |
| Platform-Level Master Service Agreement | Bundled application equipment and technical service locks multi-year volume with German and Korean OEMs. |
| REACH Pre-Registration Investment | Early substitute chemistry registration preempts ECHA authorization gaps that disqualify competitors. |
| Powder System Line Conversion | Zero-VOC profiles with overspray recovery satisfy appliance and electronics manufacturer sustainability scorecards. |
| Self-Healing Clearcoat Production Qualification | Microencapsulated repair technology differentiation captures premium exterior and high-touch interior vehicle programs. |
Study Parameters
A standing panel of automotive OEM platform engineers, Tier 1 supplier procurement directors, coating formulator R&D leads, and paint shop operations managers provided ongoing calibration across primary interview rounds. Secondary validation drew from SEC 10-K filings of listed coating suppliers, customs and trade data on titanium dioxide and resin intermediate flows, ACC and Cefic industry reports, and EPA enforcement action databases. Bottom-up volume estimates from assembly plant coating consumption rates triangulated against top-down market sizing from chemical production and trade statistics.
Scenario-bracketing framed demand trajectories across conservative, baseline, and accelerated electrification adoption paths throughout the forecast period. Segmentation modeling tracked product type, end-user industry, application technology, and regional production hub dimensions. CAGRs were derived from regression analysis of historical volume trends against projected vehicle production and industrial equipment output, with explicit modeling of waterborne penetration rates and powder coating conversion curves as industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-backed suppliers or accelerated EU carbon border adjustment implementation would shift outcomes. Material shifts in REACH substance authorization timelines or breakthrough self-healing chemistry commercialization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Global Inorganic Antimicrobial Coatings Market
Coatings
Global UV-Cured Coatings Market
Coatings
Marine Anti Fouling Coatings Market
Coatings
Marine Nanocoating Market
Coatings
BPA-Free Coatings Market
Coatings
Zero Friction Coatings Market
Coatings
Anti-Adhesion Coatings Market
Coatings
Tablet Coatings Market
Coatings
Europe Metal Finishing Market
Coatings
Emulsion Coatings Market
Coatings
Hydrophilic Coatings Market
Coatings
Urethane Surface Coatings Market
Coatings
Asia-Pacific Anti-Friction Coatings Market
Coatings
Energy Efficient Powder Coatings Market
Coatings
Canada Protective Coatings Market
Coatings
Global Surface Protection Films Market