
 Global Wood Protection Coating Market | 2026-2036
Global Wood Protection Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wood Protection Coating Market Outlook
European alkyd resin production is shifting toward high-solids and water-reducible platforms to meet tightening VOC ceilings. PPG Industries sustains technology leadership through controlled distribution of proprietary direct-to-wood systems across North American retail channels. Akzo Nobel dominates decorative wood care in Western Europe with concentrated brand equity among professional applicators. Asian Paints extends its position in tropical climate formulations through specialized anti-fungal chemistries for Southeast Asian humidity exposure.
Wood protection coatings are film-forming liquid systems containing biocides, UV absorbers, and binders that cure to create moisture barriers on cellulose substrates, typically specified to 40-150 microns dry film thickness depending on exposure class. Their primary purpose is to extend service life of exterior joinery, decking, and cladding by blocking photodegradation and biological attack. Water-based acrylic systems now lead volume in residential DIY channels across temperate markets due to low odor and soap-water cleanup, while oil-based alkyds retain preference among professional floor refinishers for penetration depth and repairability. Bio-based technology segments are expanding fastest in Nordic and German markets where building certification schemes reward renewable content, though solvent-based systems still anchor industrial throughput in tropical zones where humidity demands maximum moisture exclusion.
REACH registration requirements and the EU Green Deal framework are forcing reformulation of preservative actives across coatings sold in the European Economic Area, with ECHA evaluations on boron compounds and creosote alternatives directly constraining supplier portfolios. EPA registration under FIFRA governs biocide claims in the United States, creating divergence in permissible active ingredients between Atlantic markets. China's MEE enforcement of GB standards on architectural coating VOC content is tightening import conditions for solvent-heavy systems. Stakeholders must monitor regulatory divergence on preservative actives and VOC thresholds as formulation decisions made for one geography increasingly fail to transfer across others.
Market Dynamics
Formulation chemistry divergence between Atlantic regulatory regimes is fragmenting product portfolios and forcing parallel R&D tracks. REACH biocide restrictions and EPA FIFRA registration requirements now demand incompatible preservative systems, compressing economies of scale for multinational suppliers.
Growth Catalysts
- EU Green Deal framework:Mandatory embodied carbon disclosure in construction procurement is accelerating certified low-emission coating specification across German and Nordic residential markets.
- Timber architecture codes:German building regulations mandating exposed wood structural elements in public construction are expanding professional-grade coating volumes for facade and decking applications.
- Water-reducible alkyd platforms:High-solids resin technology is capturing share from conventional solvent systems in Western European professional channels as VOC ceilings tighten.
Market Restraints
- Boron compound phase-out:ECHA evaluations restricting creosote alternatives are eliminating proven preservative actives from European formulations without cost-comparable replacements.
- Titanium dioxide volatility:Pigment input costs fluctuate with Chinese export quotas, destabilizing water-based acrylic production economics for mid-tier suppliers.
- Tropical solvent dependence:Humidity-driven moisture exclusion requirements in Southeast Asia lock industrial volume into high-VOC systems that face tightening import barriers in temperate markets.
Strategic Opportunities
- GB standard compliance:China's MEE enforcement of architectural coating VOC limits creates first-mover advantage for low-emission technology holders in a historically solvent-heavy market.
- Bio-based resin convergence:Renewable binder chemistry combined with UV-curable platforms opens premium positioning in Nordic green building certification schemes.
- Direct-to-wood retail systems:Proprietary single-coat technologies distributed through home improvement channels capture DIY volume from traditional two-coat professional specifications.
Industry Challenges
- Biocide registration timelines:EPA FIFRA and ECHA parallel review processes extend new active ingredient commercialization to 4-7 years, freezing formulation innovation pipelines.
- Applicator skill stratification:Water-based system spray techniques diverge fundamentally from oil-based brush application, fragmenting contractor training and warranty claim exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wood Protection Coating Market |
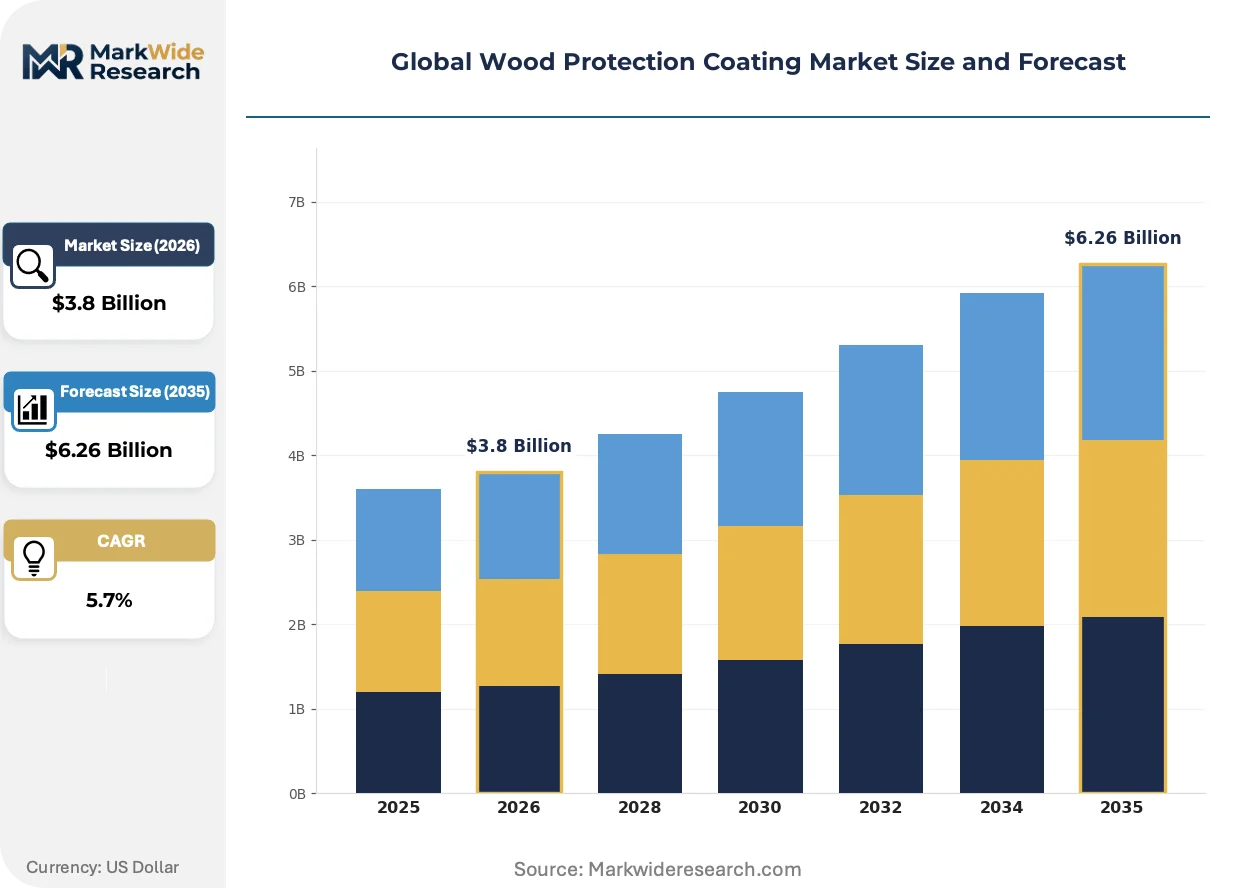
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Oil-Based, Solvent-Based, UV-Resistant Application: Furniture, Flooring, Outdoor Structures, Decks End User: Household, Commercial, Industrial, DIY Technology: Nanotechnology, Conventional Coatings, Bio-Based, Acrylic |
| Companies Covered | The Sherwin-Williams Company, PPG Industries, Inc., Akzo Nobel N.V., BASF SE, Nippon Paint Holdings Co., Ltd., RPM International Inc., Axalta Coating Systems, Arkema, Asian Paints, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wood Protection Coating Market Strategic Shifts
Coating functionality is migrating from passive moisture barriers toward active substrate preservation systems integrating biocide delivery, UV stabilization, and vapor-permeable film formation in single-platform chemistries.
Water-reducible high-solids alkyd technology is overtaking conventional solvent-borne systems in European professional refinishing channels. German and Austrian floor contractors now specify these platforms for penetration depth comparable to oil-based predecessors without VOC exposure liability. The shift is compressing solvent-based alkyd margins while rewarding resin suppliers with proprietary water-compatible modification patents.
REACH authorization requirements for preservative actives are forcing dual-track formulation portfolios across Atlantic markets. ECHA restrictions on boron compounds and creosote alternatives directly eliminate actives permitted under EPA FIFRA, compelling suppliers to maintain incompatible biocide inventories. Industrial coating specifications in Germany and France now exclude actives legal in US exterior applications, fragmenting global product architectures.
Certification-driven procurement is displacing price-first specification in German and Nordic residential construction. Passive house and Nordic Swan ecolabel compliance now gate coating selection for timber facade and decking contracts, unbundling material cost from lifecycle performance evaluation. Professional applicators in Hamburg and Copenhagen report certified system premiums of 15-25 percent over conventional alternatives without volume loss.
Global Wood Protection Coating Market Segmentation
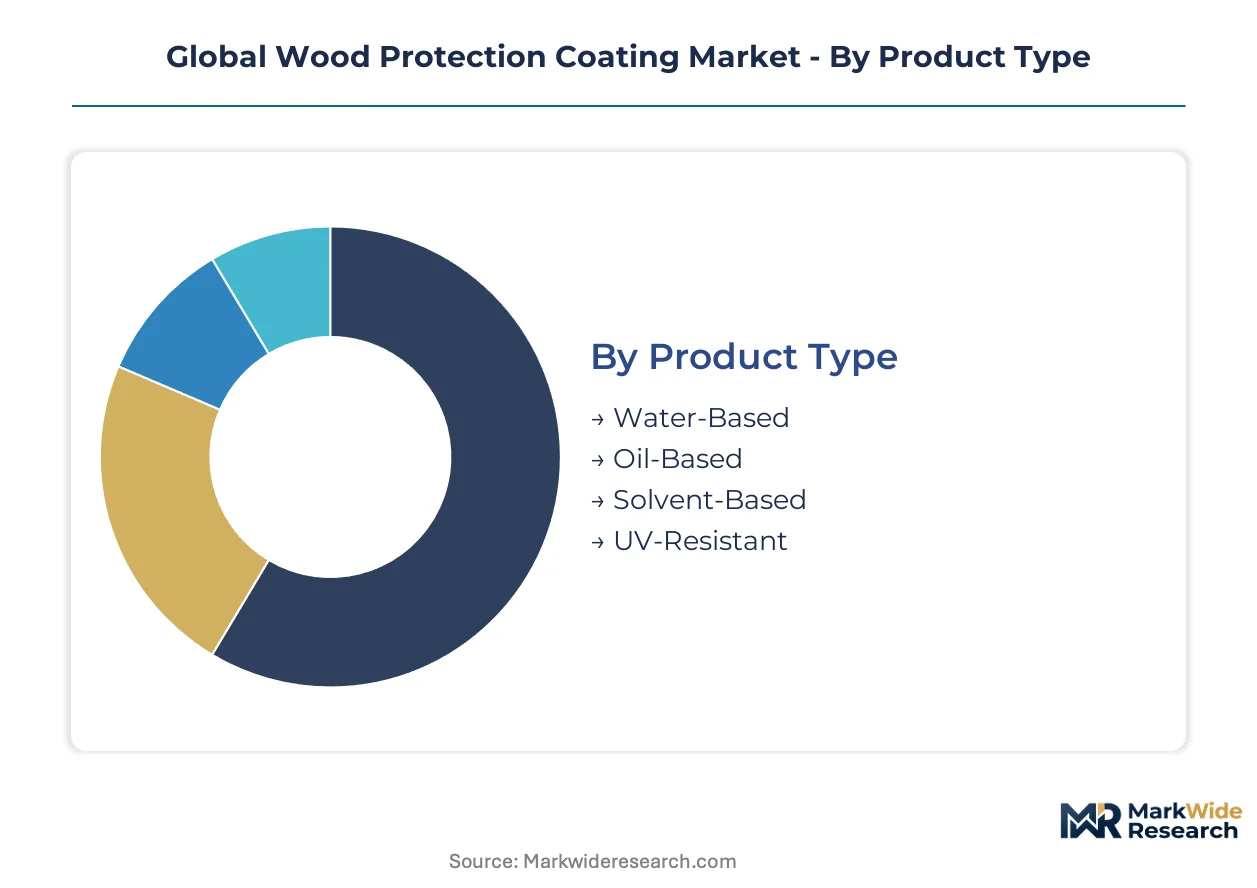
Wood protection coating procurement diverges sharply across formulation chemistry, end-use exposure class, and applicator skill level. Specification decisions cascade from regulatory VOC ceilings through to substrate preparation requirements and warranty terms.
Product Type:
Formulation chemistry determines emission profiles, penetration depth, and repairability across temperate and tropical deployment zones.
- Water-Based:Acrylic and polyurethane dispersions cure through evaporation coalescence, achieving 40-80 microns dry film thickness. German and Nordic residential construction channels specify these systems for interior joinery and low-exposure exterior applications where ECHA VOC restrictions apply. REACH compliance costs are lowest here.
- Oil-Based:Natural and modified drying oils penetrate cellular structure rather than film-forming, enabling spot repair without full stripping. Professional floor refinishers in Hamburg and Copenhagen specify these for heritage timber where reversibility matters. ECHA biocide restrictions on creosote alternatives are compressing traditional preservative oil formulations.
- Solvent-Based:Alkyd and polyurethane systems deliver maximum moisture exclusion through 100-150 micron builds. Southeast Asian industrial procurement relies on these for tropical humidity exposure where GB standard VOC enforcement remains uneven.
- UV-Resistant:Benzotriazole and hindered amine stabilizer packages extend service life in direct solar exposure. Decking specifications in Arizona and Queensland specify these for horizontal surfaces.
Mature deployment sits with oil-based penetration systems. Newer deployment is concentrated in water-based platforms.
Application:
Exposure class dictates film thickness, biocide loading, and re-coating intervals.
- Decks:Horizontal surfaces accumulate moisture and UV dose simultaneously, demanding 100-150 micron builds with integrated anti-fungal packages. German timber architecture codes are expanding professional coating volumes for public construction decking.
- Outdoor Structures:Cladding and pergola applications prioritize vapor permeability over absolute moisture exclusion. Nordic Swan ecolabel procurement gates specification for these exposures in Denmark and Sweden.
- Flooring:Interior wear resistance and repairability dominate specification. Austrian and German contractors specify water-reducible high-solids alkyds for residential refinishing where odor and VOC exposure liability constrain solvent alternatives.
- Furniture:Aesthetic clarity and tactile finish quality drive selection. DIY channels in US home improvement retail favor single-coat direct-to-wood systems for these applications.
Volume concentrates in deck and outdoor structure applications. Margin expansion is steepest in flooring refinishing.
End User:
Procurement authority and application skill stratify warranty terms and product form.
- Commercial:Facility managers specify certified systems with documented lifecycle performance. German public construction mandates are accelerating professional-grade coating procurement for exposed timber elements.
- DIY:Home improvement retail channels demand soap-water cleanup and low-odor application. PPG Industries distributes proprietary direct-to-wood systems through these channels in North America.
- Industrial:Prefabrication and mass timber manufacturing specify factory-applied coatings with controlled cure conditions. Southeast Asian humidity demands maximum moisture exclusion from solvent-heavy systems.
- Household:Small-volume maintenance purchases concentrate in weather-triggered seasonal patterns. Water-based acrylics lead volume in temperate market DIY channels.
Specification authority sits with commercial procurement. Volume expansion is fastest in DIY retail conversion.
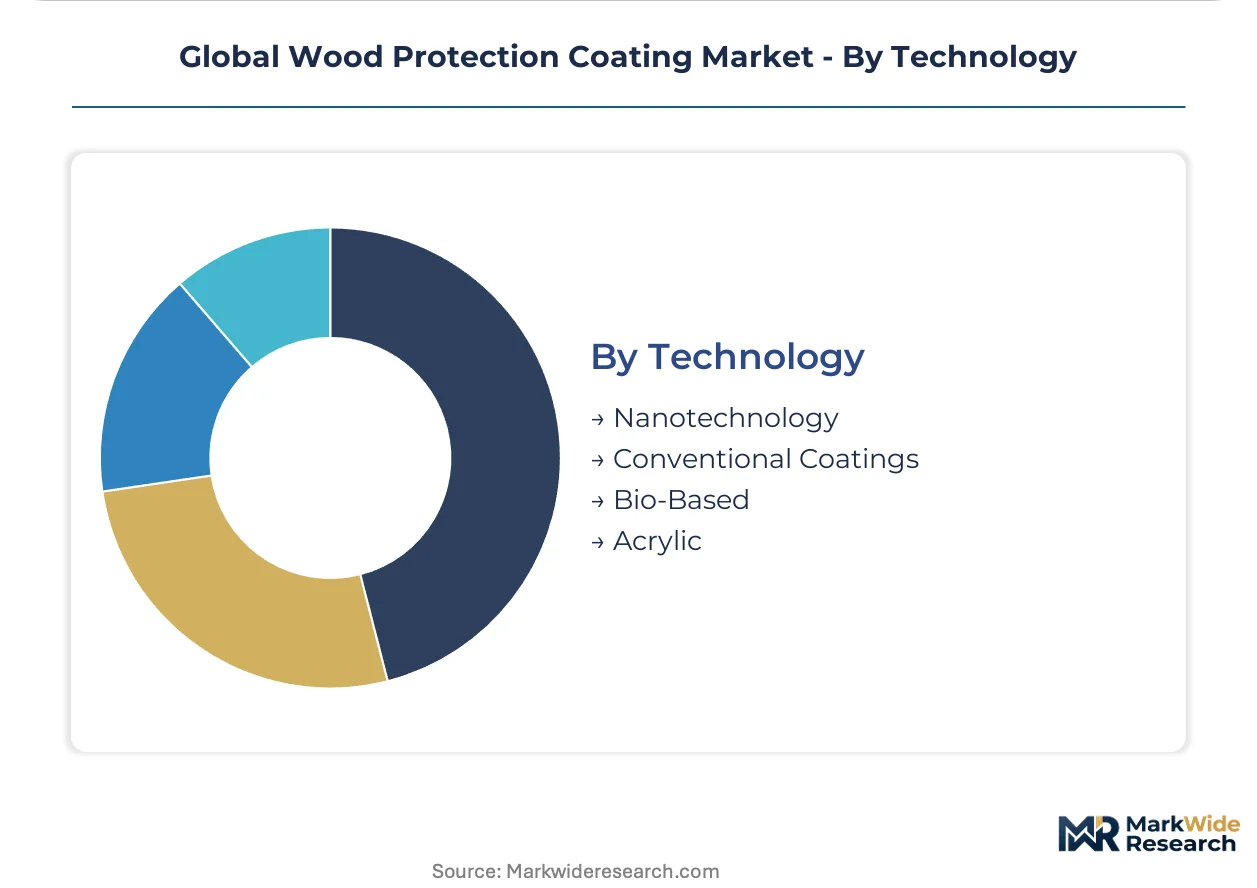
Technology:
Resin chemistry and cure mechanism determine renewable content, regulatory compliance, and capital equipment requirements.
- Bio-Based:Renewable binder content from tall oil fatty acids and lignin derivatives qualifies for Nordic Swan and German green building certification credits. Premium positioning of 15-25 percent over conventional alternatives is sustaining despite raw material cost volatility.
- Acrylic:Water-borne emulsion polymers dominate residential DIY volume through low odor and ambient cure. Titanium dioxide pigment cost fluctuations from Chinese export quotas are destabilizing mid-tier supplier economics.
- Nanotechnology:Colloidal silica and metal oxide nanoparticles enhance scratch resistance and UV stability without film thickness penalties. Patent-protected formulations command premium positioning in professional channels.
- Conventional Coatings:Unmodified alkyd and polyurethane systems anchor industrial throughput in markets where VOC enforcement remains permissive. Import barriers are tightening in China under MEE GB standard enforcement.
Installed base concentrates in conventional solvent platforms. Technology migration is accelerating in bio-based and acrylic segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tall oil fatty acid feedstocks from Nordic forests anchor bio-based resin supply chains serving German and Scandinavian coating formulators. REACH authorization requirements and EPA FIFRA registration divergence now force parallel preservative inventories across Atlantic markets. Timber architecture mandates in Hamburg and Copenhagen concentrate specification authority among certified professional applicators.
United States
Outdoor decking renovation cycles and residential construction velocity drive formulation demand across temperate climate zones. EPA FIFRA registration governs biocide claims, constraining preservative actives to inventories incompatible with European REACH restrictions. The Southeast industrial corridor from Georgia to North Carolina hosts prefabricated mass timber manufacturing facilities specifying factory-applied moisture barriers.
Germany
Public construction codes mandating exposed timber structural elements expand professional-grade coating procurement for facades and decking. EU Green Deal embodied carbon disclosure requirements accelerate certified low-emission system specification in Hamburg and Berlin procurement offices. The Bavarian timber processing cluster around Munich integrates coating selection into passive house certification workflows.
China
Architectural coating production for tropical climate export markets concentrates solvent-heavy system capacity despite domestic regulatory pressure. MEE enforcement of GB standards on VOC content tightens import conditions for high-emission formulations while creating first-mover advantage for compliant technology holders. The Yangtze River Delta manufacturing belt around Shanghai and Suzhou dominates water-borne acrylic emulsion polymer output.
Japan
Heritage timber preservation standards and humid subtropical exposure conditions sustain demand for penetrating oil systems in traditional architecture maintenance. METI industrial standards and JIS certification requirements govern coating performance claims for exterior joinery applications. The Kansai region around Osaka anchors specialty resin formulation for repairable heritage coating systems.
Sweden
Nordic Swan ecolabel procurement gates coating selection for residential timber construction across Denmark and Swedish markets. Bio-based resin advances from tall oil derivatives qualify for green building certification credits, commanding 15-25 percent premiums over conventional alternatives. The Stockholm-Uppsala corridor concentrates R&D activity for renewable binder chemistry integrated with UV-curable platforms.
Global Wood Protection Coating Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue bio-based certification positioning and regional regulatory compliance specialization. The vendor base stratifies across multinational integrated coatings groups, regional resin specialists, and private-label distributors serving home improvement retail. Three archetypes dominate: technology-integrated multinationals with proprietary direct-to-wood systems, bio-based resin specialists capturing Nordic certification premiums, and industrial solvent-heavy suppliers serving tropical humidity markets. Competitive moves concentrate on portfolio diversification to manage Atlantic regulatory divergence and strategic partnerships for bio-based feedstock security.
Within the multinational integrated tier, The Sherwin-Williams Company and PPG Industries exemplify technology-anchored positioning through controlled distribution architectures. Akzo Nobel occupies a position representing European decorative wood care concentration among professional applicator networks. Asian Paints anchors the tropical climate specialization vector with humidity-driven formulation expertise. These three names illustrate how competitive positioning fragments across regulatory regimes, climate exposure requirements, and applicator skill stratification rather than converging on uniform global product architectures.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| PPG Industries, Inc. |
| Akzo Nobel N.V. |
| BASF SE |
| Nippon Paint Holdings Co., Ltd. |
| RPM International Inc. |
| Axalta Coating Systems |
| Arkema |
| Asian Paints |
| Others |
Value Chain & Pricing Dynamics
Titanium dioxide pigment costs from Chinese export quotas cascade through water-based acrylic production economics, compressing mid-tier supplier margins while concentrating pricing power among resin producers with captive mineral processing. This input volatility stratifies the market across certified premium systems, professional-grade formulations, and commodity DIY alternatives.
Pricing Analysis
Warranty bundling separates professional-grade coating procurement from unbundled DIY retail transactions, with certified applicators in Hamburg and Copenhagen commanding 15-25 percent premiums for documented lifecycle performance. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with Nordic Swan ecolabel compliance gating access to premium tiers. Pricing pressure stems from REACH authorization costs for preservative actives, forcing dual-track formulation portfolios that erode economies of scale. DIY retail channels exhibit highest price sensitivity, while commercial procurement in German public construction prioritizes lifecycle value over unit cost.
Supply Chain Analysis
Skilled resin chemist availability in the Yangtze River Delta, Bavarian timber processing cluster, and Stockholm-Uppsala corridor anchors formulation capacity for water-reducible alkyd and bio-based platforms. Supply draws from tall oil fatty acid feedstocks in Nordic forests, titanium dioxide pigment from Chinese processing facilities, and specialty biocide actives subject to ECHA and EPA registration divergence. Single-source vulnerability concentrates in REACH-authorized preservative suppliers, where 4-7 year registration timelines freeze alternative sourcing. Distribution runs through home improvement retail chains for DIY volume and certified professional applicator networks for commercial specification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where REACH authorization requirements for preservative actives erect barrier-to-entry moats favoring incumbents with parallel ECHA and EPA registration capabilities.
For Market Incumbents: Anticipate biocide registration timeline compression by maintaining dual-track preservative inventories across Atlantic markets, while consolidating water-reducible alkyd resin capacity in the Bavarian cluster to capture German timber architecture code expansion. ECHA boron compound phase-out represents the primary substitution threat requiring proactive reformulation investment. For New Entrants and Emerging Players: Enter via GB standard compliance specialization in China's architectural coating sector, where MEE enforcement creates first-mover advantage for low-emission technology holders. The penetrable white-space sits in tropical climate formulations for Southeast Asian humidity exposure, leveraging direct-to-wood retail distribution through regional home improvement chains. For Investors and Strategic Acquirers: ECHA authorization grant announcements for novel preservative actives are the leading indicator that formulation innovation pipelines are unlocking value-capture opportunities. The 5-10 year viability window favors acquisition of bio-based resin specialists with Nordic Swan certification positioning and captive tall oil feedstock arrangements. Watch for EPA FIFRA registration acceleration as signal of Atlantic regulatory convergence enabling portfolio simplification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Tall oil fatty acid captive supply secures Nordic Swan certification premiums in German residential construction. |
| REACH-Compliant Preservative Registration | ECHA authorization for novel actives unlocks European formulation portfolios currently constrained by boron restrictions. |
| Water-Reducible Alkyd Capacity Expansion | Bavarian cluster investment captures professional refinishing demand from Hamburg and Copenhagen contractors. |
| GB Standard Compliance Certification | MEE enforcement in Yangtze River Delta creates import advantage for low-VOC technology holders. |
| Direct-to-Wood Retail Distribution | Single-coat proprietary systems through home improvement channels displace traditional two-coat professional specifications. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with coating formulators, professional applicators in Hamburg and Copenhagen, timber procurement officers at German public construction authorities, and resin R&D directors. ECHA biocide authorization databases, EPA FIFRA registration records, China MEE GB standard enforcement disclosures, and Nordic Swan ecolabel certification registries provided regulatory validation. Bottom-up volume modeling triangulated against top-down construction expenditure analysis.
Segmentation granularity operated at formulation chemistry, exposure class application, and end-user procurement authority levels across the projection horizon. CAGRs derived from regression analysis of historical coating consumption against timber construction permits and renovation cycle data. Bio-based resin penetration rates, REACH authorization timelines for preservative actives, and VOC ceiling enforcement trajectories in EU and Chinese markets served as industry-specific forecast inputs.
Revisions become necessary when ECHA authorization decisions accelerate or delay novel biocide commercialization, when China MEE enforcement intensity shifts GB standard compliance economics, or when German timber architecture code adoption extends beyond Hamburg and Berlin procurement offices. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Sol Gel Nanocoating Market
Coatings
Coating Auxiliaries Market
Coatings
Italy Automotive OEM Coatings Market
Coatings
Global Fluorinated Ethylene Propylene (FEP) Coatings Market
Coatings
Japan Automotive OEM Coatings Market
Coatings
Middle-East and Africa Thermal Spray Market
Coatings
Powder Coating Booth Market
Coatings
Topcoat Market
Coatings
Global Polytetrafluoroethylene (PTFE) Coatings Market
Coatings
Coating Equipment Market
Coatings
Solvent Borne Coatings Market
Coatings
Spain Automotive OEM Coatings Market
Coatings
China Marine Coatings Market
Coatings
Global Intumescent Coatings Market
Coatings
Germany Automotive OEM Coatings Market
Coatings
South Africa Automotive OEM Coatings Market