
 Global Nanocoatings Market | 2026-2036
Global Nanocoatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nanocoatings Market Foresight
Aftermarket service revenue for protective coating reapplication and performance monitoring is reconfiguring how nanocoating suppliers capture lifetime customer value. BASF leverages its polymer science infrastructure to integrate nano-ceramic dispersions with conventional automotive clearcoats. PPG Industries anchors North American aerospace demand through specialized anti-icing and erosion-resistant formulations for turbine components. Tesla NanoCoatings competes in corrosion protection for energy infrastructure, particularly offshore wind towers and pipeline systems.
Nanocoatings are ultra-thin functional films, typically 1–100 nanometers in thickness, engineered through sol-gel processing, chemical vapor deposition, or layer-by-layer assembly to impart properties such as superhydrophobicity, antimicrobial activity, or electrical conductivity. Their primary industrial purpose is to modify surface behavior without altering bulk substrate characteristics, enabling performance gains in durability, energy efficiency, and hygiene control. Hydrophobic and oleophobic types dominate current volume due to mature application protocols in automotive and consumer electronics, while conductive nanocoatings represent the fastest-expanding margin pool as flexible electronics and transparent electrode demand intensifies. Ceramic material formulations sustain premium pricing in aerospace and medical device end uses where thermal stability and biocompatibility requirements exclude polymer alternatives.
The EPA regulates volatile organic compound emissions from coating operations under 40 CFR Part 59, pushing manufacturers toward waterborne nano-dispersion technologies, while REACH registration requirements in Europe mandate comprehensive toxicity dossiers for nano-scale substances, elevating compliance costs for new market entrants. China's SAMR enforces GB standards for nano-product labeling and occupational exposure limits, creating divergent certification pathways for multinational suppliers. Stakeholders must monitor regulatory fragmentation between jurisdictions while positioning formulation capabilities to serve medical device and clean energy segments where standards continue tightening.
Market Dynamics
Automotive OEMs and electronics manufacturers are consolidating specification power around nano-ceramic and conductive formulations, compressing supplier margins while elevating performance thresholds for corrosion resistance and optical clarity.
Growth Catalysts
- EPA 40 CFR Part 59 VOC thresholds:US coating operations face tightening emission limits, accelerating waterborne nano-dispersion adoption across industrial finishing lines.
- Flexible transparent electrodes:Conductive nanocoatings for foldable displays and photovoltaic substrates are pulling volume from sputtered indium tin oxide alternatives.
- German automotive supplier clusters:Stuttgart and Wolfsburg area OEMs are specifying nano-ceramic clearcoats for chassis corrosion protection at scale.
Market Restraints
- REACH registration costs:ECHA toxicity dossier requirements for nano-scale substances impose six-figure compliance burdens on new European entrants.
- Specialized deposition equipment:Chemical vapor deposition systems for aerospace-grade ceramic coatings require capital commitments that exclude mid-scale applicators.
- Plasma-enhanced alternatives:Thick-film plasma spray coatings compete for turbine blade thermal barrier applications where nanocoating durability remains unproven.
Strategic Opportunities
- India medical device manufacturing:CDSCO regulatory harmonization with EU MDR is opening import-substitution pathways for antimicrobial nano-surface coatings on surgical instruments.
- Layer-by-layer assembly convergence:Integration with inkjet printing enables functional film deposition on temperature-sensitive polymer substrates for wearable electronics.
- China dual carbon policy:MEE enforcement of industrial emission intensity targets is mandating nano-catalytic coatings for process equipment energy efficiency.
Industry Challenges
- Sol-gel process engineering talent:Formulation chemists with hybrid organic-inorganic synthesis expertise command premium compensation and limited availability.
- Multi-jurisdiction certification timelines:Concurrent EPA, REACH, and SAMR substance registrations extend product commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nanocoatings Market |
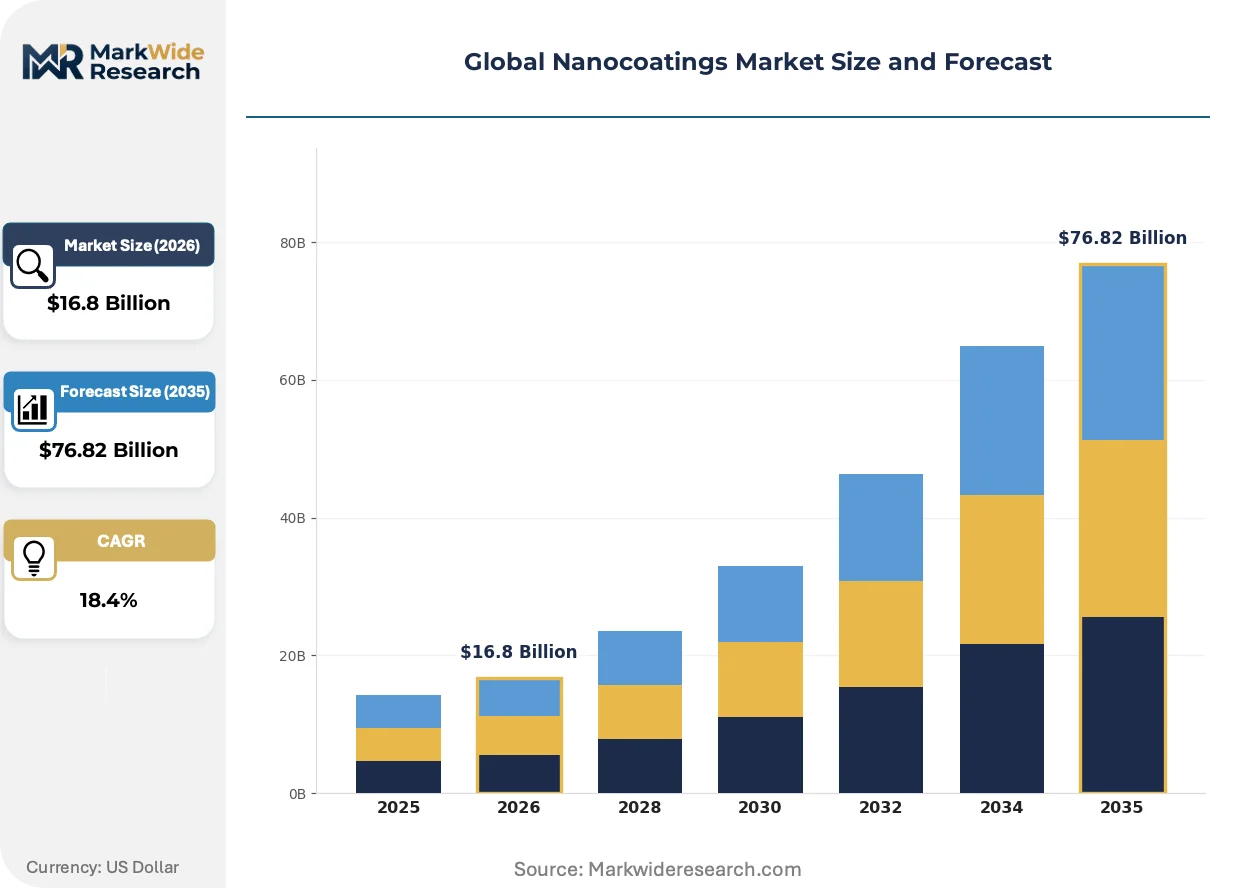
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $76.82 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Automotive, Aerospace, Electronics, Healthcare Type: Hydrophobic, Oleophobic, Anti-Reflective, Conductive Material: Metallic, Polymer, Ceramic, Composite End User: Industrial, Consumer Goods, Medical Devices, Energy |
| Companies Covered | Tesla NanoCoatings, PPG Industries, P2i Ltd., Nanovere Technologies, Nanophase Technologies Corporation, Nanofilm, BASF, Henkel AG and Co. KGaA, Akzo Nobel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nanocoatings Market Shifts & Advancements
Formulation science and application hardware are converging to enable functional films on substrates previously excluded by temperature or geometry constraints, reshaping competitive capability requirements.
Self-healing polymer nanocoatings incorporating microencapsulated repair agents are migrating from laboratory demonstration to automotive clearcoat trials. German and Japanese OEMs are validating scratch-recovery performance in outdoor exposure programs. This migration from concept to qualified specification is compressing traditional warranty cost structures for luxury vehicle finishes.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of hydrophobic nanocoatings across European consumer electronics and textile applications. Manufacturers are substituting fluorine-free silane chemistries at performance trade-offs in contact angle durability. Medical device coatings face the most acute reformulation pressure given biocompatibility requalification requirements.
Aftermarket service unbundling is fragmenting traditional coating supply relationships. Industrial asset operators in energy infrastructure are separating initial application from performance monitoring and reapplication scheduling, creating discrete contract opportunities for specialized inspection and maintenance providers. This pattern is most developed in North Sea offshore wind installations where access logistics dominate lifetime cost structures.
Global Nanocoatings Market Segmentation
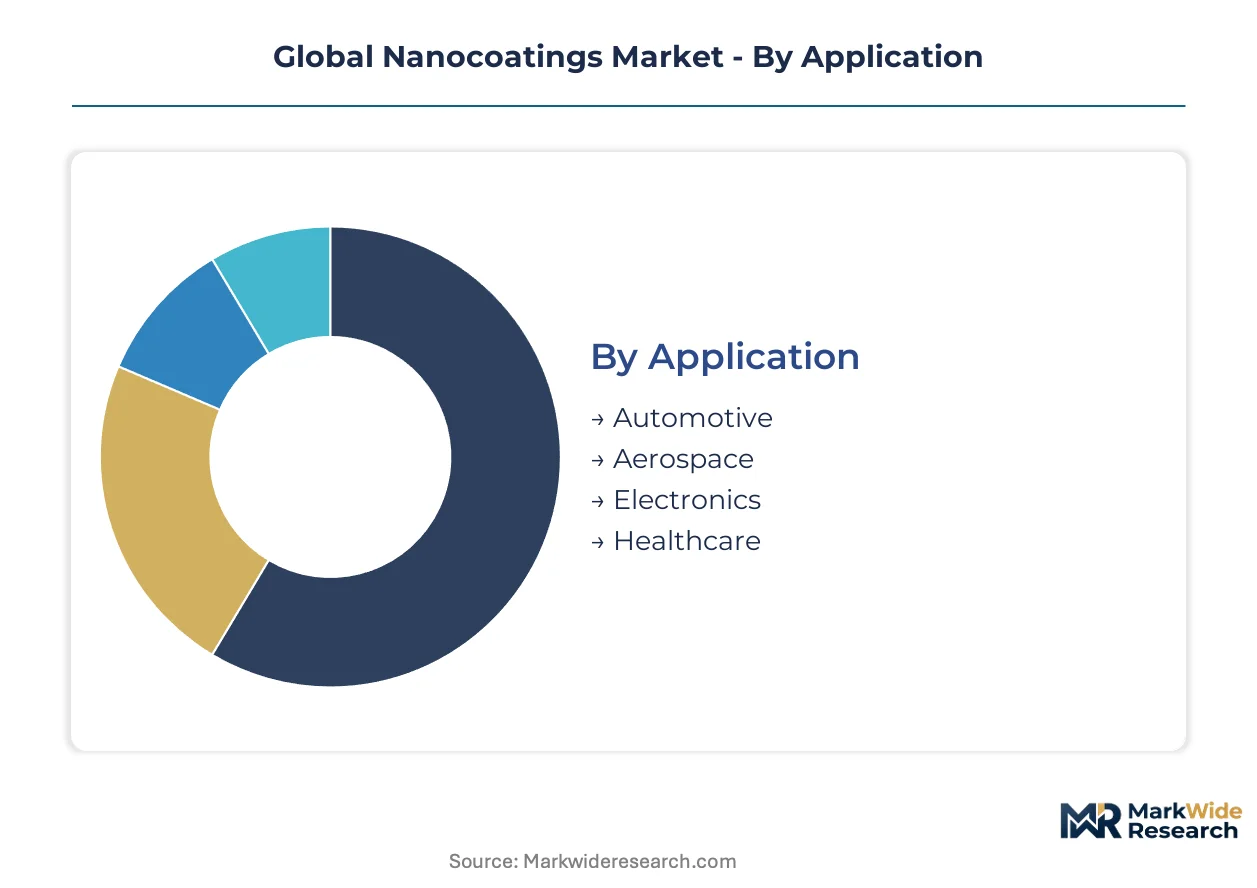
Nanocoating suppliers configure formulation portfolios around distinct performance envelopes demanded by end-use environments. Application-specific requirements for thermal stability, optical clarity, or biocompatibility drive material selection and deposition method choices across supplier R&D programs.
Application:
Use-case spectrum spans corrosion protection in heavy machinery to antimicrobial surfaces in surgical settings, with each vertical imposing unique specification hierarchies on coating performance.
- Automotive:Nano-ceramic dispersions integrate with conventional clearcoats to deliver scratch resistance and UV degradation protection for exterior body panels. Stuttgart and Wolfsburg area OEMs specify these formulations for chassis corrosion protection at volume scale.
- Electronics:Conductive nanocoatings for flexible displays and transparent electrodes displace sputtered indium tin oxide alternatives in foldable smartphone and photovoltaic substrate applications. Chinese manufacturers drive volume uptake for touch panel and display stack integration.
- Aerospace:Erosion-resistant and anti-icing formulations protect turbine components from particulate damage and atmospheric ice accumulation during flight operations.
- Healthcare:Antimicrobial nano-surface coatings on surgical instruments address CDSCO regulatory requirements in India's expanding medical device manufacturing sector.
The dominant share belongs to Automotive, while Electronics is closing the gap fastest.
Type:
Functional chemistry selection determines surface energy modification, electrical conductivity, or optical interference properties achievable on target substrates.
- Conductive:Transparent electrode formulations enable flexible electronics architectures previously excluded by rigid metal oxide alternatives. Demand concentrates in foldable display manufacturing lines across Chinese and South Korean electronics suppliers.
- Hydrophobic:Silane-based chemistries replace fluorinated alternatives under REACH Annex XVII restrictions, trading contact angle durability for regulatory compliance in European consumer electronics applications.
- Oleophobic:Oil-repellent surfaces reduce fingerprint visibility and cleaning frequency on touchscreen interfaces and optical lenses.
- Anti-Reflective:Gradient refractive index layers suppress glare and improve light transmission efficiency in photovoltaic modules and display systems.
Hydrophobic coatings retain volume leadership, though Conductive formulations command steepest expansion trajectory.
Material:
Substrate compatibility and environmental exposure severity dictate inorganic versus organic phase selection in formulation design.
- Ceramic:Alumina, titania, and silica-based coatings sustain premium positioning in aerospace thermal barrier and medical device biocompatibility applications where polymer alternatives fail temperature or sterilization requirements.
- Polymer:Self-healing microencapsulated systems migrate from laboratory demonstration to automotive clearcoat trials with German and Japanese OEM validation programs.
- Metallic:Silver and copper nanoparticle dispersions impart antimicrobial and conductive functionality in healthcare and electronics end uses.
- Composite:Hybrid organic-inorganic matrices balance processability with performance durability across industrial finishing operations.
Ceramic formulations anchor premium pricing tiers, while Composite materials gain formulation flexibility advantages.
End User:
Procurement sophistication and lifetime cost calculation methods diverge sharply between asset-intensive infrastructure operators and consumer product manufacturers.
- Industrial:Energy infrastructure operators in North Sea offshore wind unbundle initial coating application from performance monitoring and reapplication scheduling, creating discrete contract opportunities for specialized service providers.
- Medical Devices:Biocompatibility requalification requirements impose acute reformulation pressure on hydrophobic coating suppliers serving European surgical instrument manufacturers.
- Energy:China's MEE enforcement of industrial emission intensity targets mandates nano-catalytic coatings for process equipment energy efficiency improvements.
- Consumer Goods:Electronics and textile manufacturers face REACH-driven substitution timelines for fluorine-free hydrophobic formulations.
Industrial end users generate highest lifetime service revenue attachment, while Medical Devices imposes steepest regulatory compliance barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China and Germany demonstrate lowest price elasticity as automotive and electronics OEMs prioritize performance specifications over unit cost, while industrial operators in India and the United States exhibit higher sensitivity to lifetime cost calculations in infrastructure applications.
China
Electronics manufacturers in Shenzhen and Dongguan drive conductive nanocoating volume for foldable displays and touch panel stacks. SAMR enforces GB standards for nano-product labeling and occupational exposure limits, creating certification complexity for multinational entrants. The Yangtze River Delta concentration of photovoltaic substrate producers is specifying anti-reflective nano-layers to improve module efficiency.
Germany
Automotive OEMs in Stuttgart and Wolfsburg specify nano-ceramic clearcoats for chassis corrosion protection at volume scale. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force reformulation timelines for hydrophobic coatings serving consumer electronics and textile applications. The Baden-Württemberg supplier cluster is validating self-healing polymer nanocoatings in outdoor exposure programs for luxury vehicle finishes.
United States
Aerospace demand concentrates in anti-icing and erosion-resistant formulations for turbine components. EPA 40 CFR Part 59 VOC thresholds accelerate waterborne nano-dispersion adoption across industrial finishing lines. PPG Industries anchors North American aerospace supply relationships through specialized deposition protocols.
India
Medical device manufacturing expansion in Maharashtra and Gujarat creates import-substitution pathways for antimicrobial nano-surface coatings on surgical instruments. CDSCO regulatory harmonization with EU MDR elevates biocompatibility documentation requirements. The Karnataka electronics manufacturing corridor is evaluating conductive nanocoatings for domestic smartphone assembly integration.
Japan
Automotive OEMs in Toyota City and Yokohama trial self-healing clearcoat technologies for premium vehicle segments. METI industrial technology roadmaps prioritize nano-ceramic thermal barrier development for next-generation powertrain efficiency. The Osaka-Kobe chemical industry concentration supplies hybrid organic-inorganic sol-gel precursors to regional coating formulators.
Global Nanocoatings Market Competitive Landscape
Integrated chemical conglomerates and specialized nano-material suppliers split the market along capability depth versus application focus. The vendor base concentrates around formulation science leaders with captive polymer infrastructure and deposition equipment partnerships. Three archetypes dominate: diversified chemical majors leveraging scale economies, nano-technology pure-plays with intellectual property positions, and regional application service providers bundling installation with performance monitoring. Competitive moves center on waterborne formulation R&D partnerships and geographic expansion into medical device manufacturing clusters.
Among diversified chemical majors, BASF and Henkel AG and Co. KGaA represent the integrated-formulation archetype with polymer science infrastructure extending into nano-ceramic dispersions. PPG Industries occupies a position exemplifying aerospace-specialist positioning through turbine component coating relationships. Tesla NanoCoatings anchors the infrastructure-focused tier with energy sector concentration. These three illustrate how competitive positioning stratifies across end-use specialization rather than geographic coverage alone.
| Leading Market Players |
|---|
| Tesla NanoCoatings |
| PPG Industries |
| P2i Ltd. |
| Nanovere Technologies |
| Nanophase Technologies Corporation |
| Nanofilm |
| BASF |
| Henkel AG and Co. KGaA |
| Akzo Nobel |
| Others |
Supply & Pricing Matrix
REACH Annex XVII fluorochemical restrictions function as a regulatory chokepoint that compresses margin structures for hydrophobic formulation tiers while simultaneously fragmenting European supply chains toward silane-based precursor networks. This regulatory pressure widens pricing spreads between compliant and legacy formulations while forcing supplier geographic repositioning.
Pricing Analysis
Aftermarket service revenue from performance monitoring and scheduled reapplication drives lifetime value capture in industrial nanocoating deployments. Three-tier pricing structure across premium ceramic, standard polymer, and economy composite formulations reflects certification grade and volume scale differentiation. Cost compression in mid-tier waterborne dispersions intensifies as EPA 40 CFR Part 59 compliance becomes baseline. Industrial energy infrastructure operators exhibit lowest price elasticity due to access logistics dominance in lifetime cost calculations, while consumer electronics manufacturers show highest sensitivity to unit coating costs.
Supply Chain Analysis
Export-control restrictions on plasma-enhanced deposition equipment limit technology transfer to Chinese and Indian coating applicators, constraining regional capability buildout. Sol-gel precursor manufacturing concentrates in Germany, Japan, and the United States, drawing from specialty silane and metal alkoxide feedstocks. Single-source vulnerability persists for aerospace-grade ceramic nanopowders sourced from limited qualified suppliers. Distribution runs through authorized applicator networks bundling installation with SAMR, EPA, and REACH compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Nanocoatings Market operates as a defensive-moat industry where regulatory entrenchment creates substantial switching costs for qualified suppliers across multi-jurisdiction certification requirements.
For Market Incumbents: Build certification moats by accelerating concurrent EPA, REACH, and SAMR substance registrations ahead of competitor timelines. Secure backward integration into sol-gel precursor manufacturing to isolate formulation cost volatility from specialty chemical supply markets. Counter emerging waterborne nano-dispersion specialists by embedding performance monitoring telemetry into coating system warranties.
For New Entrants and Emerging Players: Establish a beachhead in India's antimicrobial surgical instrument coating segment where CDSCO-EU MDR harmonization creates import-substitution demand without incumbent lock-in. Target layer-by-layer assembly convergence with inkjet printing equipment partnerships for wearable electronics temperature-sensitive substrates. Lead with application service bundling rather than formulation-only supply to bypass capital-intensive deposition equipment barriers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors formulation-science specialists with captive polymer infrastructure and qualified regulatory dossiers. Long-term viability hinges on waterborne technology transition completion and medical device biocompatibility certification depth. Watch for inflection signals in German automotive OEM self-healing clearcoat qualification announcements as indicator of premium tier demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Formulation R&D Partnership | EPA 40 CFR Part 59 compliance accelerates industrial finishing line conversion away from solvent-based systems. |
| Backward Integration into Sol-Gel Precursors | Captive supply of silane and metal alkoxide feedstocks isolates margin pressure from specialty chemical markets. |
| Multi-Jurisdiction Certification Investment | Concurrent EPA, REACH, and SAMR registrations extend competitive moats through 18-24 month approval timelines. |
| Aftermarket Service Unbundling | Performance monitoring and reapplication scheduling contracts capture lifetime value in North Sea offshore wind installations. |
| Layer-by-Layer Assembly Convergence | Inkjet printing integration enables functional film deposition on temperature-sensitive polymer substrates for wearable electronics. |
Research Methodology
A standing panel of coating formulation chemists, automotive OEM specification engineers, medical device regulatory affairs leads, and industrial asset maintenance directors provided ongoing calibration throughout the study period. Primary interview intelligence combined with secondary validation from EPA enforcement records, ECHA registration dossiers, SAMR GB standard publications, and SEC 10-K filings from diversified chemical majors. Bottom-up volume modeling across application segments triangulated against top-down macroeconomic drivers.
Scenario bracketing around regulatory implementation timelines and technology substitution curves anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include functional type, material chemistry, deposition method, end-use vertical, and regional regulatory cluster. CAGRs derived from slope analysis of historical adoption curves adjusted for technology readiness level transitions. Forecast inputs incorporated OEM specification release schedules and medical device biocompatibility requalification timelines.
Stress conditions across REACH Annex XVII expansion scope, EPA VOC threshold tightening velocity, and Chinese dual carbon policy enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding sol-gel process engineering talent availability and multi-jurisdiction certification timeline stability. Material shifts in fluorine-free hydrophobic formulation performance parity or plasma-enhanced deposition equipment export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Coating Binders Market
Coatings
Spain Automotive OEM Coatings Market
Coatings
Polysiloxane Coatings Market
Coatings
Electrical Appliance Coatings Market
Coatings
Textile Coatings Market
Coatings
Cold Gas Spray Coating Market
Coatings
Middle-East and Africa Coil Coatings Market
Coatings
Canada Floor Coatings Market
Coatings
PACVD-Based Coatings Market
Coatings
Global PET Film Coated Steel Coil Market
Coatings
Intumescent Fire Retardant Coating Market
Coatings
Hull Coatings Market
Coatings
Morocco Automotive OEM Coatings Market
Coatings
Global Intumescent Coatings Market
Coatings
Coating Thickness Gauge Market
Coatings
Carbon Fiber Coatings Market