
 Dispersion Coating Market | 2026-2036
Dispersion Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Dispersion Coating Market Analysis
Specialized polymer chemists and formulation engineers are reorganizing how dispersion coating producers scale capacity, as talent scarcity in emulsion polymerization constrains batch consistency at volume. BASF SE leverages its Ludwigshafen integrated site to captive-produce acrylic monomers for coating resins. Evonik Industries anchors its position through high-purity specialty additives that control particle size distribution. Dow Inc. competes on water-based polyurethane dispersions for automotive clearcoats.
Dispersion coatings are aqueous polymer systems where resin particles 0.05–5 microns in diameter remain stably suspended in water, then coalesce into continuous films upon evaporation; they serve primarily to protect substrates from corrosion, weathering, and chemical attack while reducing volatile organic compound emissions versus solvent-borne alternatives. Water-based formulations lead volume due to regulatory tailwinds but command thinner margins, whereas polyurethane dispersions represent the fastest-expanding chemistry as automotive OEMs demand soft-touch interiors with abrasion resistance. Spray coating technology dominates application-method share in aerospace maintenance facilities, while dip coating occupies the marine sector where uniform hull protection requires full immersion coverage.
EPA VOC regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-borne coating formulations in US manufacturing facilities, while REACH registration requirements in Europe mandate toxicity documentation for imported resin components. OEM procurement teams must monitor how California Air Resources Board amendments and impending EU Green Deal taxonomy rules will redefine qualifying criteria for low-emission coating systems.
Market Dynamics
Water-based polyurethane dispersions are fragmenting the automotive interior coatings segment as OEMs abandon solvent-borne soft-touch formulations under tightening VOC mandates. This chemistry shift is compressing incumbent resin margins while opening formulation partnerships between polymer suppliers and Tier-1 component manufacturers.
Growth Catalysts
- EU Green Deal taxonomy:The EU Green Deal's low-emission manufacturing criteria are accelerating solvent-to-water transitions across German automotive finishing lines. BMW and Mercedes-Benz procurement teams now mandate aqueous coating portfolios from supplier networks.
- Marine hull protection:Dip coating technology occupies expanding share in shipyard maintenance operations where full-immersion coverage requirements favor aqueous dispersion systems over spray alternatives.
- Aerospace MRO expansion:Spray coating technology dominates application-method share in maintenance facilities as fleet operators extend aircraft service intervals and increase repaint frequency.
Market Restraints
- Acrylic monomer supply concentration:Captive production of coating-grade acrylics concentrates at Ludwigshafen-scale integrated sites, constraining independent formulator access to cost-competitive resin inputs.
- Particle size control limitations:Batch-to-batch consistency in emulsion polymerization suffers from talent scarcity among specialized polymer chemists, degrading film formation reliability at commercial volumes.
- REACH registration friction:Toxicity documentation mandates for imported resin components create compliance delays and documentation costs for non-European suppliers seeking European market access.
Strategic Opportunities
- India industrial corridor penetration:Underpenetrated demand in Gujarat and Maharashtra manufacturing clusters offers first-mover positioning as domestic automotive production scales aqueous coating adoption.
- Soft-touch interior convergence:Polyurethane dispersion chemistry combined with abrasion-resistant additive packages is opening specification wins in premium vehicle cabin components previously served by solvent systems.
- California Air Resources Board amendments:Pending CARB rule revisions will redefine qualifying criteria for low-emission coating systems, creating certification-first advantages for pre-compliant formulation portfolios.
Industry Challenges
- Emulsion polymerization talent scarcity:Specialized formulation engineers command premium compensation as batch consistency expertise concentrates among mid-career technical specialists with decade-plus experience.
- Application equipment reconfiguration:Water-based viscosity and drying characteristics require spray gun and dip tank modifications that extend capital deployment timelines for coating line conversions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dispersion Coating Market |
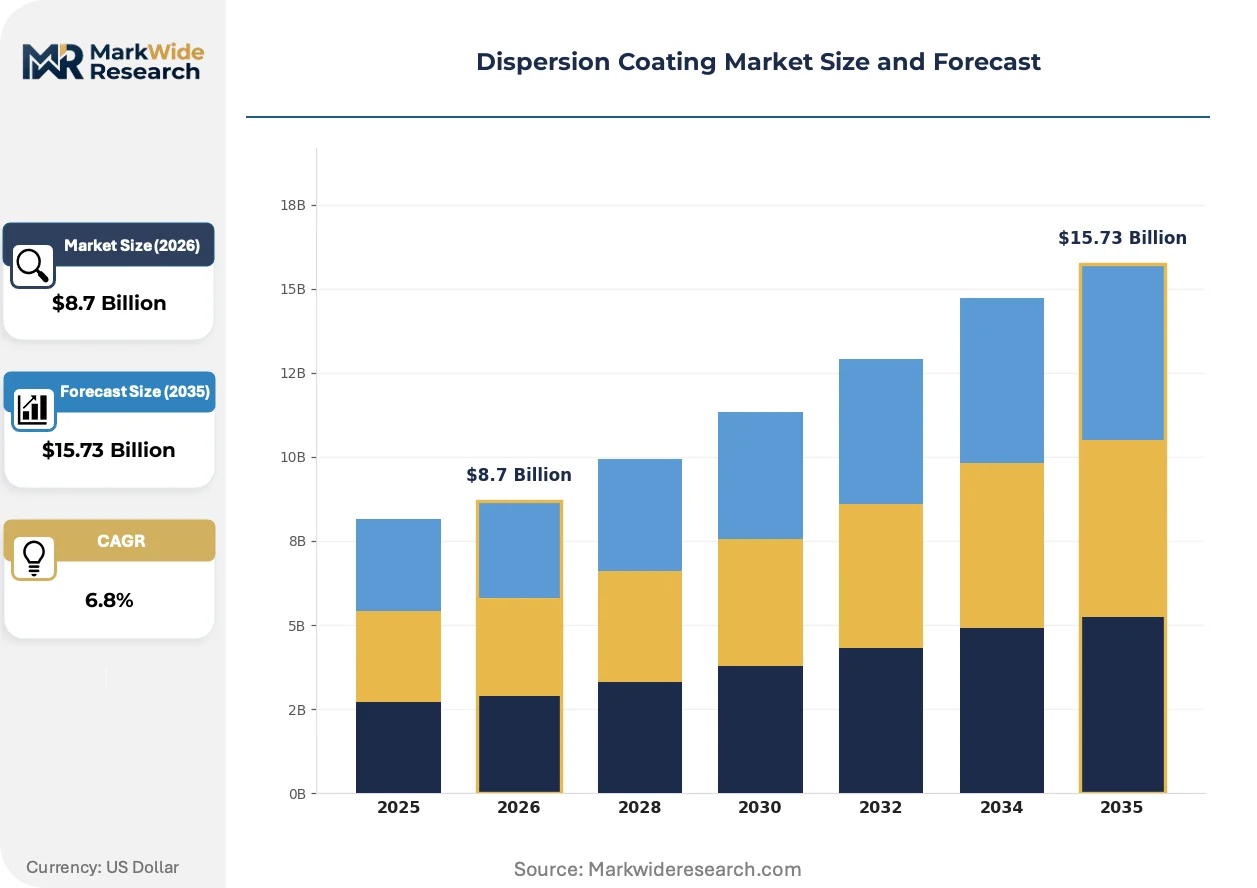
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Epoxy, Polyurethane, Water-Based Application: Aerospace, Automotive, Marine, Electronics End User: Manufacturers, Contractors, OEMs, Distributors Technology: Spray Coating, Brush Coating, Dip Coating, Roll Coating |
| Companies Covered | Lubrizol Corporation, Evonik Industries, BASF SE, Dow Inc., Arkema Group, BYK Additives, Solvay SA, Akzo Nobel N.V., Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dispersion Coating Market Emerging Trajectories
Polymer chemistry convergence with precision additive control is reshaping how dispersion coatings achieve performance parity with legacy solvent systems. Formulators now compete on particle engineering rather than resin substitution alone.
Hybrid acrylic-polyurethane dispersion technology is fragmenting the clearcoat segment as automotive OEMs seek single-layer solutions combining gloss retention with soft-touch aesthetics. Tier-1 interior component suppliers in Germany are piloting these systems for instrument panel and door trim applications. The technology is fragmenting established supply relationships by enabling direct polymer supplier-to-OEM technical partnerships that bypass traditional coating compounders.
REACH authorization requirements under ECHA oversight are forcing reformulation of legacy dispersant chemistries used in coating stabilizers. Industrial consequence includes accelerated substitution of alkylphenol ethoxylate surfactants with bio-based alternatives. Water-based architectural coatings in Southern Europe show fastest response as Italian and Spanish formulators face downstream pressure from export-oriented furniture manufacturers.
Automotive procurement teams are consolidating approved supplier lists around coating systems pre-qualified for multi-OEM use. Tier-1 component manufacturers face compressed switching cycles as platform commonality across BMW, Mercedes-Benz, and Volkswagen reduces formulation tolerance. This concentration is most visible in Bavaria's supplier corridor where dual-qualification requirements now dominate contract negotiations.
Dispersion Coating Market Segmentation
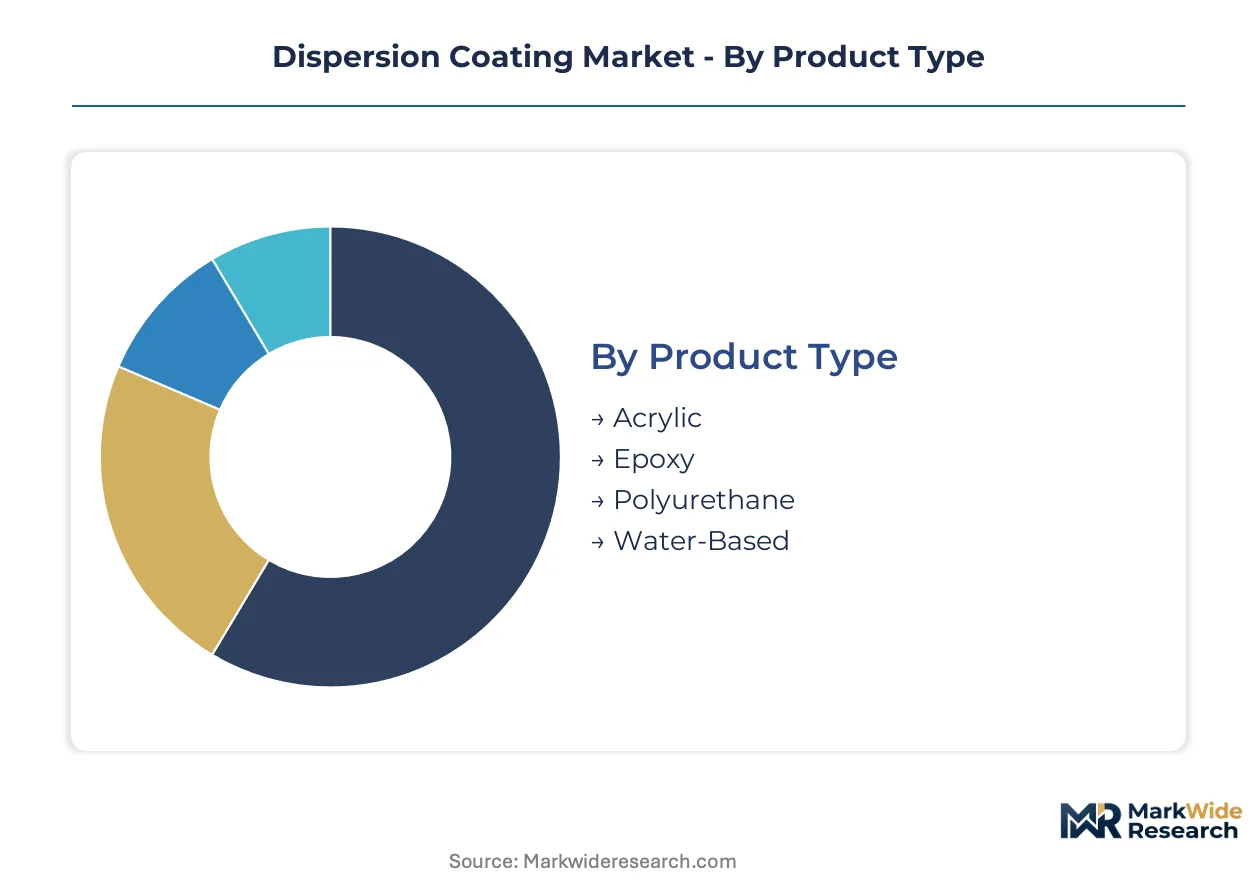
Dispersion coating procurement patterns diverge sharply across product chemistries and application methods, with regulatory pressure fragmenting legacy supply relationships while creating specification windows for reformulated systems. Understanding these segment boundaries reveals where margin compression concentrates and where formulation partnerships unlock premium positioning.
Product Type:
Domestic production of acrylic and water-based systems dominates European and North American supply, whereas polyurethane dispersions rely more heavily on imported specialty monomers subject to REACH documentation requirements.
- Acrylic:Thermoplastic resin systems formed through emulsion polymerization of acrylate monomers deliver cost-efficient film formation with moderate chemical resistance. German automotive OEM finishing lines in Bavaria's supplier corridor represent the densest demand concentration, with BMW and Mercedes-Benz procurement teams now mandating aqueous acrylic portfolios from Tier-1 networks under EU Green Deal taxonomy pressure.
- Polyurethane:Two-component or water-borne polyurethane dispersions achieve superior abrasion resistance and soft-touch aesthetics through segmented polymer architecture. This chemistry is displacing solvent-borne alternatives fastest in premium vehicle cabin components, where instrument panel and door trim specifications now favor water-based polyurethane clearcoats with gloss retention matching legacy systems.
- Epoxy:Cross-linked thermoset systems provide exceptional chemical and corrosion resistance for industrial maintenance applications.
- Water-Based:Broad formulation category encompassing aqueous suspensions of multiple resin chemistries, defined primarily by low-VOC compliance rather than single-polymer identity.
Acrylic commands the established base. The steepest expansion runs through polyurethane.
Application:
Cost-tier stratification separates aerospace specification-grade systems from high-volume automotive production lines, with marine applications occupying a mid-tier position defined by immersion-performance requirements rather than aesthetic tolerance.
- Automotive:OEM finishing lines and Tier-1 component manufacturing consume the largest formulation volumes, with interior soft-touch coatings and exterior clearcoats representing distinct specification tracks. California Air Resources Board amendments are accelerating solvent-to-water transitions across US-based production facilities, compressing incumbent resin margins while opening formulation partnerships between polymer suppliers and component manufacturers.
- Aerospace:Maintenance, repair and overhaul facilities dominate demand as fleet operators extend aircraft service intervals and increase repaint frequency. Spray coating technology prevails in this segment, with specification requirements focusing on weight minimization and fuel-efficiency contributions rather than unit cost.
- Marine:Shipyard maintenance operations favor dip coating technology where full-immersion coverage requirements protect hull substrates from biofouling and corrosion.
- Electronics:Conformal coating applications for printed circuit boards and consumer device housings demand precision film thickness control.
Automotive absorbs the highest absolute volumes. Aerospace generates the most pronounced specification premium.
End User:
Volume concentration tilts toward direct OEM procurement teams, with distributor and contractor channels serving fragmented maintenance and repair demand where batch sizes preclude direct polymer supplier relationships.
- OEMs:Original equipment manufacturers in automotive, aerospace, and marine sectors maintain approved supplier lists with pre-qualified coating systems, consolidating procurement around multi-platform compatibility requirements. BMW, Mercedes-Benz, and Volkswagen platform commonality across German production networks reduces formulation tolerance and compresses switching cycles for Tier-1 component manufacturers.
- Manufacturers:Industrial facilities applying dispersion coatings to their own production output, including furniture, appliance, and metal fabrication operations.
- Contractors:Third-party applicators serving maintenance, repair, and construction markets where project-based demand and specification variability favor distributor-supplied products.
- Distributors:Intermediary stocking points bridging formulation producers with fragmented end-use demand, capturing value through technical service and just-in-time delivery rather than manufacturing margin.
OEMs anchor volume concentration. Contractors present the most pronounced channel fragmentation.
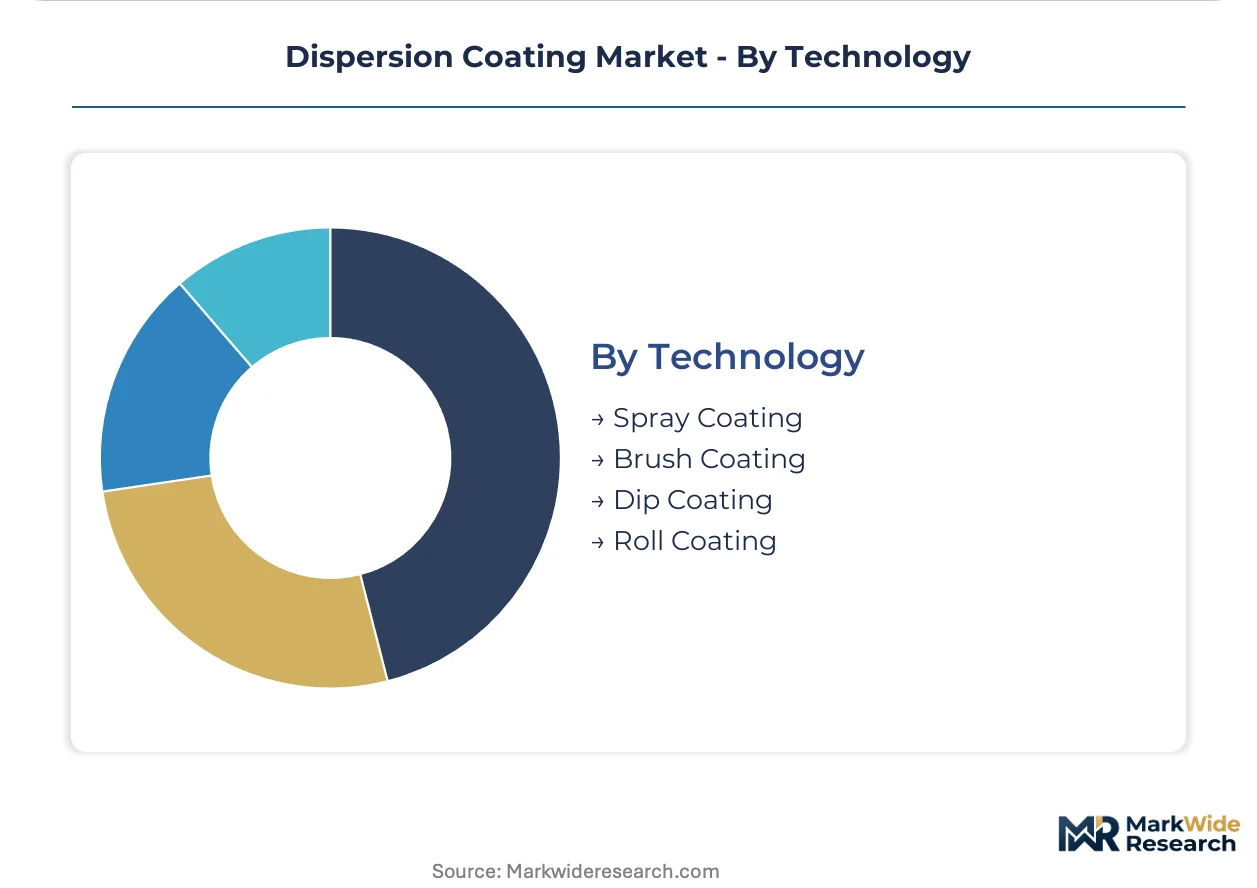
Technology:
Application equipment capital requirements and viscosity compatibility with water-based formulations create divergent adoption curves, with spray systems leading aerospace and automotive while dip coating dominates marine immersion applications.
- Spray Coating:Atomized application through pneumatic or electrostatic equipment delivers uniform film thickness on complex geometries. Aerospace MRO facilities in Germany and the United States represent the most intensive users, with maintenance intervals driving repaint frequency and specification continuity requirements.
- Dip Coating:Full-immersion application ensures complete substrate coverage for uniform hull protection in marine maintenance operations, with aqueous dispersion systems displacing solvent alternatives as shipyards reconfigure tank infrastructure.
- Brush Coating:Manual application for touch-up, repair, and small-batch industrial maintenance where equipment investment is uneconomical.
- Roll Coating:Continuous application for flat substrates in metal coil and wood panel processing, demanding precise viscosity control for uniform film build.
Spray coating holds the technology leadership position. Dip coating is climbing the fastest as marine infrastructure conversions accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH and EU Green Deal mandates anchor European regulatory gravity, while EPA VOC rules and California Air Resources Board amendments shape North American compliance architecture. Dispersion coating demand clusters around automotive finishing corridors and marine maintenance hubs where aqueous formulation transitions concentrate investment.
Germany
BMW and Mercedes-Benz procurement teams mandate aqueous coating portfolios from Tier-1 supplier networks. EU Green Deal taxonomy criteria accelerate solvent-to-water transitions across Bavaria's automotive finishing lines. Ludwigshafen-scale integrated sites captive-produce acrylic monomers for coating resins, constraining independent formulator access to cost-competitive inputs.
United States
EPA National Emission Standards for Hazardous Air Pollutants constrain solvent-borne formulations in manufacturing facilities. California Air Resources Board amendments redefine qualifying criteria for low-emission coating systems, creating certification-first advantages for pre-compliant portfolios. Aerospace MRO facilities in the Southeast and Pacific Northwest drive spray coating technology demand as fleet operators extend aircraft service intervals.
China
Domestic automotive production scales aqueous coating adoption across Yangtze River Delta manufacturing clusters. The country's national environmental regulator enforces tightening VOC limits in industrial coating applications. Shanghai and Jiangsu province shipyards favor dip coating technology for hull protection as marine infrastructure conversions accelerate.
India
Gujarat and Maharashtra manufacturing clusters present underpenetrated demand as domestic automotive production expands. The Bureau of Indian Standards develops coating performance benchmarks aligned with export market requirements. Pune and Ahmedabad industrial corridors attract first-mover positioning from polymer suppliers establishing local formulation capacity.
Japan
Automotive OEMs in the Nagoya and Tokyo regions specify water-based polyurethane dispersions for interior soft-touch components. METI industrial standards encourage low-emission manufacturing processes across coating application facilities. Osaka-based Tier-1 suppliers reformulate portfolios to meet multi-OEM qualification requirements for platform commonality.
Dispersion Coating Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated chemical conglomerates commanding resin supply chains while specialty additive specialists capture formulation value. The market structure tilts toward consolidation at the polymer input level and fragmentation among regional coating compounders. Three archetypes dominate: captive-integrated resin producers, high-purity specialty additive suppliers, and water-based polyurethane dispersion specialists. Competitive moves concentrate on strategic partnerships between polymer suppliers and Tier-1 manufacturers, plus application equipment reconfiguration for aqueous viscosity compatibility.
Within the integrated chemical tier, BASF SE anchors polymer supply through its Ludwigshafen site architecture, while Evonik Industries exemplifies specialty additive positioning through particle size distribution control. Dow Inc. occupies the water-based polyurethane dispersion vector for automotive clearcoat applications. These three represent distinct competitive archetypes rather than overlapping strategic positions.
| Leading Market Players |
|---|
| Lubrizol Corporation |
| Evonik Industries |
| BASF SE |
| Dow Inc. |
| Arkema Group |
| BYK Additives |
| Solvay SA |
| Akzo Nobel N.V. |
| Clariant AG |
| Others |
Supply Flow & Price Mechanics
EU Green Deal taxonomy criteria gate both supplier qualification and price differentiation simultaneously, as OEM procurement teams mandate aqueous coating portfolios that command certification premiums while excluding uncertified competitors from Tier-1 networks. This regulatory architecture compresses margins for solvent-borne incumbents while rewarding pre-compliant formulators with pricing power in automotive finishing corridors.
Pricing Analysis
German automotive OEMs pay 15-25% premiums over North American counterparts for REACH-compliant polyurethane dispersions, reflecting documentation costs and captive supply constraints. Three-tier pricing structure across premium, standard, and economy levels separates multi-OEM qualified systems from single-platform approvals and commodity acrylics. Price erosion runs through standard-grade acrylics as Ludwigshafen-scale producers expand captive capacity. Tier-1 component manufacturers show highest price sensitivity due to platform commonality compressing formulation tolerance, while aerospace MRO operators prioritize specification continuity over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites acrylic monomer flows to Asian formulation hubs, exposing dispersion coating supply chains to maritime logistics volatility. Production gravity centers on Germany, China, and the United States, with specialty polyurethane monomers drawing from South Korean and Japanese chemical complexes. Raw material dependencies include coating-grade acrylics, aliphatic isocyanates, and bio-based surfactants substituting for REACH-restricted dispersants. Single-source vulnerability concentrates at Ludwigshafen-scale integrated sites controlling acrylic monomer supply. Distribution runs through direct OEM procurement channels for automotive volumes, with regional distributors serving fragmented marine maintenance demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where REACH documentation requirements and OEM qualification cycles create switching costs that protect incumbent positions for 5-7 year windows.
For Market Incumbents: Shield formulation portfolios by accelerating backward integration into acrylic monomer production, mirroring BASF's Ludwigshafen captive supply model. Deepen technical partnerships with BMW and Mercedes-Benz procurement teams to secure multi-platform qualification ahead of EU Green Deal taxonomy enforcement. Prioritize particle size distribution control capabilities as batch consistency expertise concentrates among scarce polymer chemists. For New Entrants and Emerging Players: California Air Resources Board pre-certification fast-tracks offer lowest-friction entry into automotive supply chains before amended rules take effect. Target India's Gujarat and Maharashtra manufacturing clusters where domestic automotive production expansion outpaces local formulation capacity. Pursue white-label partnerships with established additive suppliers to bypass REACH registration delays for imported resin components. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core coating resin divisions amid portfolio rationalization. Mid-cap polyurethane dispersion specialists with automotive interior qualifications present attractive 5-10 year holds as soft-touch specifications displace solvent alternatives. Watch for inflection when Tier-1 suppliers in Bavaria's corridor announce dual-qualification requirements across BMW-Mercedes-Benz-Volkswagen platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomers | Ludwigshafen-scale captive production insulates margin from supply concentration risks. |
| REACH Pre-Registration Investment | Documentation completion before authorization deadlines secures European market access. |
| Hybrid Acrylic-Polyurethane R&D Partnership | Single-layer clearcoat development fragments established compounding relationships. |
| Marine Dip Coating Infrastructure Conversion | Shipyard tank reconfiguration accelerates aqueous displacement of solvent systems. |
| India Local Formulation Capacity Buildout | Pune and Ahmedabad corridors attract first-mover positioning as automotive scales. |
Methodological Framework
Cross-validation between primary interviews with polymer chemists, Tier-1 procurement managers, and marine coating applicators anchors the qualitative findings against secondary sources including ECHA registration databases, customs trade flows for acrylic monomers, and SEC filings from integrated chemical producers. Bottom-up volume estimates from application-method segments triangulate with top-down resin consumption figures from Cefic and ACC industry reports.
Sensitivity analysis across crude oil price scenarios and REACH enforcement timelines tests forecast robustness throughout the projection horizon. Segmentation modeling incorporates chemistry type, application technology, end-user procurement channel, and regional regulatory cluster dimensions. CAGRs derive from installed base growth in automotive finishing lines, fleet expansion in aerospace MRO, and shipyard conversion rates to aqueous dip coating systems.
Decision-makers should treat outputs as directional under stable regulatory enforcement assumptions; material deviation in EU Green Deal implementation pace or California Air Resources Board amendment timing would warrant model refresh. Practitioners should keep alternative scenarios live as emulsion polymerization talent scarcity and acrylic monomer supply concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Nigeria Protective Coatings Market
Coatings
Shipping Container Coatings Market
Coatings
Plastic-Coated Wires Market
Coatings
Non-Stick Coatings Market
Coatings
Global Anti-Smudge Coatings Market
Coatings
BRIC Performance Coatings Market
Coatings
Wood Preservative Coatings Market
Coatings
Sol Gel Nanocoating Market
Coatings
Global Waterborne Coatings Market
Coatings
Vacuum Coating Machine Market
Coatings
Transportation Coating Market
Coatings
Functional Coil Coating Market
Coatings
Marine Coatings Market
Coatings
North America Powder Coatings Market
Coatings
Egypt Automotive OEM Coatings Market
Coatings
Coating Pigments Market