
 Global Decorative Coatings Market | 2026-2036
Global Decorative Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Decorative Coatings Market Foresight
ISO 14001 environmental management certification is rotating competitive eligibility among suppliers seeking specification on large commercial projects. PPG Industries leverages its automotive color-matching heritage to anchor premium positioning in architectural segments. Akzo Nobel N.V. sustains European regulatory compliance leadership through controlled substance substitution programs. Asian Paints Limited dominates South Asian distribution through an owned-retail network that extends into rural pin codes.
Decorative coatings encompass pigmented liquid or powder systems applied to interior and exterior substrates primarily for aesthetic enhancement alongside corrosion and moisture protection, typically formulated with binders such as acrylic, alkyd, or polyurethane resins at solids contents ranging from 30% to 60%. Water-based emulsion paints now occupy the largest volume share as solvent-based alternatives face formulation constraints under tightening emissions rules. Wall coatings applications generate the deepest margin pools in residential end-use segments, while powder coatings are displacing liquid alternatives in metal protection for commercial complexes due to zero-VOC profiles and overspray recovery economics.
EPA rules in the United States limit hazardous air pollutant content in architectural coatings, compelling reformulation of alkyd-based products. REACH and the EU Green Deal in Europe are accelerating substitution of titanium dioxide and conventional biocides with bio-based alternatives. India's BIS mandates certification for lead and chromium content in decorative paints, tightening import and domestic manufacturing standards. Stakeholders must monitor regulatory divergence across these jurisdictions to anticipate raw material qualification costs and regional product registration timelines.
Market Dynamics
Water-based emulsion chemistry is decomposing the solvent-borne incumbency across residential and commercial specification channels, compressing alkyd demand and reallocating R&D budgets toward low-VOC polymer architectures.
Growth Catalysts
- REACH Phase-Out Schedules:ECHA restrictions on conventional titanium dioxide and biocide classifications are redirecting formulation investment toward bio-based binders and mineral alternatives.
- Tier-Two Urbanization:Housing stock expansion in Indian cities such as Jaipur and Lucknow is generating specification demand for premium interior emulsions with antimicrobial claims.
- Powder Coating Recovery Economics:Zero-VOC profiles and near-total overspray reclaimability are displacing liquid metal protection in commercial facade applications.
Market Restraints
- Titanium Dioxide Supply Concentration:Pigment production clusters in China create input cost volatility and qualification delays for alternative opacifiers.
- Alkyd Reformulation Friction:EPA hazardous air pollutant limits on architectural coatings compel solvent-borne producers to absorb margin compression or exit decorative segments.
- Cure-Temperature Limitations:Powder systems require substrate thermal tolerance that excludes wood and temperature-sensitive composites from conversion.
Strategic Opportunities
- Bio-Based Binder Convergence:Plant-derived polyurethane and alkyd hybrids are opening specification pathways in EU Green Deal-aligned public procurement.
- Rural Distribution Infrastructure:Owned-retail network extension into Indian rural pin codes captures underpenetrated repainting cycles.
- ISO 14001 Certification Arbitrage:Environmental management credentialing creates eligibility differentiation for large commercial project bidding.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in water-borne polymer stabilization and biocide-free preservation systems remains concentrated among legacy specialists.
- Multi-Jurisdiction Registration Timelines:Divergent BIS, EPA, and REACH substance qualification requirements extend product launch cycles and inflate compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Decorative Coatings Market |
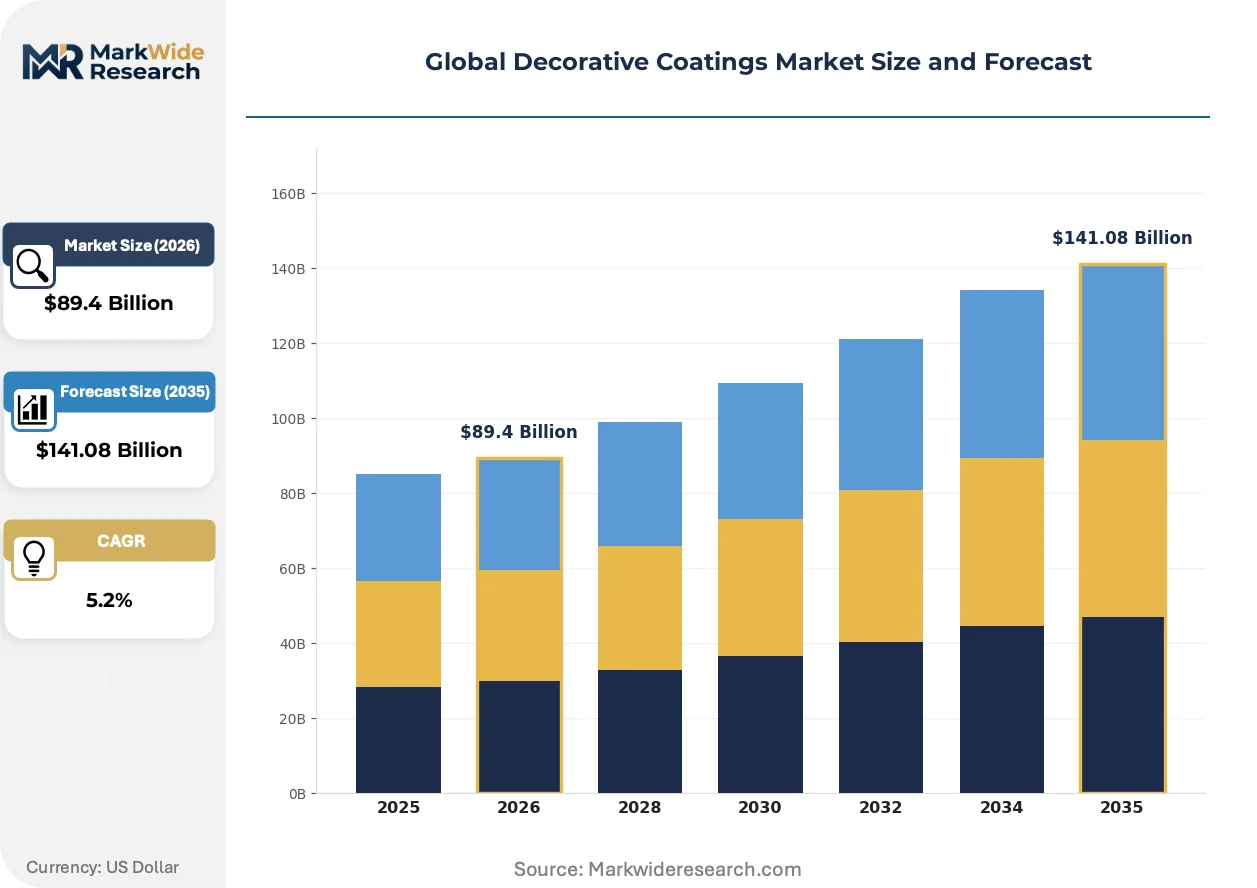
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $141.08 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsion Paints, Solvent-Based Paints, Powder Coatings, Water-Based Coatings, Textured Coatings Application: Wall Coatings, Wood Finishing, Metal Protection, Ceiling Coatings, Furniture Refinishing, Decorative Art End User: Residential Properties, Commercial Complexes, Hospitality Venues, Educational Institutes, Government Buildings Distribution Channel: Direct Sales, Retail Stores, E-Commerce Platforms, Distributors, Dealers |
| Companies Covered | Sherwin-Williams Company, PPG Industries, Inc., Akzo Nobel N.V., Nippon Paint Holdings Co., Ltd., Asian Paints Limited, BASF SE, RPM International Inc., Kansai Paint Co., Ltd., Jotun Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Decorative Coatings Market Shifts & Advancements
Digital color-matching hardware and predictive maintenance coatings are restructuring how architectural specifications are developed and how performance warranties are underwritten across project types.
Self-healing polymer networks embedded in exterior emulsions are decomposing the traditional repaint cycle economics for commercial facades. Building operators in North American and Northern European climates are specifying these systems on 15-year maintenance contracts. The technology is compressing aftermarket coating demand while shifting margin capture toward upfront material premiums.
REACH authorization requirements for chromium-based corrosion inhibitors are forcing substitution toward silica-based and rare-earth alternatives in metal primers. Formulators serving marine and industrial-adjacent decorative segments face reformulation timelines compressed by sunset dates. German and Dutch coating producers are advancing hybrid organic-inorganic sol-gel systems to maintain performance parity.
Specification influence is migrating from general contractors to facilities management platforms with embedded coating lifecycle databases. Large commercial property portfolios in the United States are consolidating vendor panels around predictive performance analytics rather than unit-cost bidding. This shift concentrates procurement authority among buyers with capital planning horizons exceeding traditional project timelines.
Global Decorative Coatings Market Segmentation
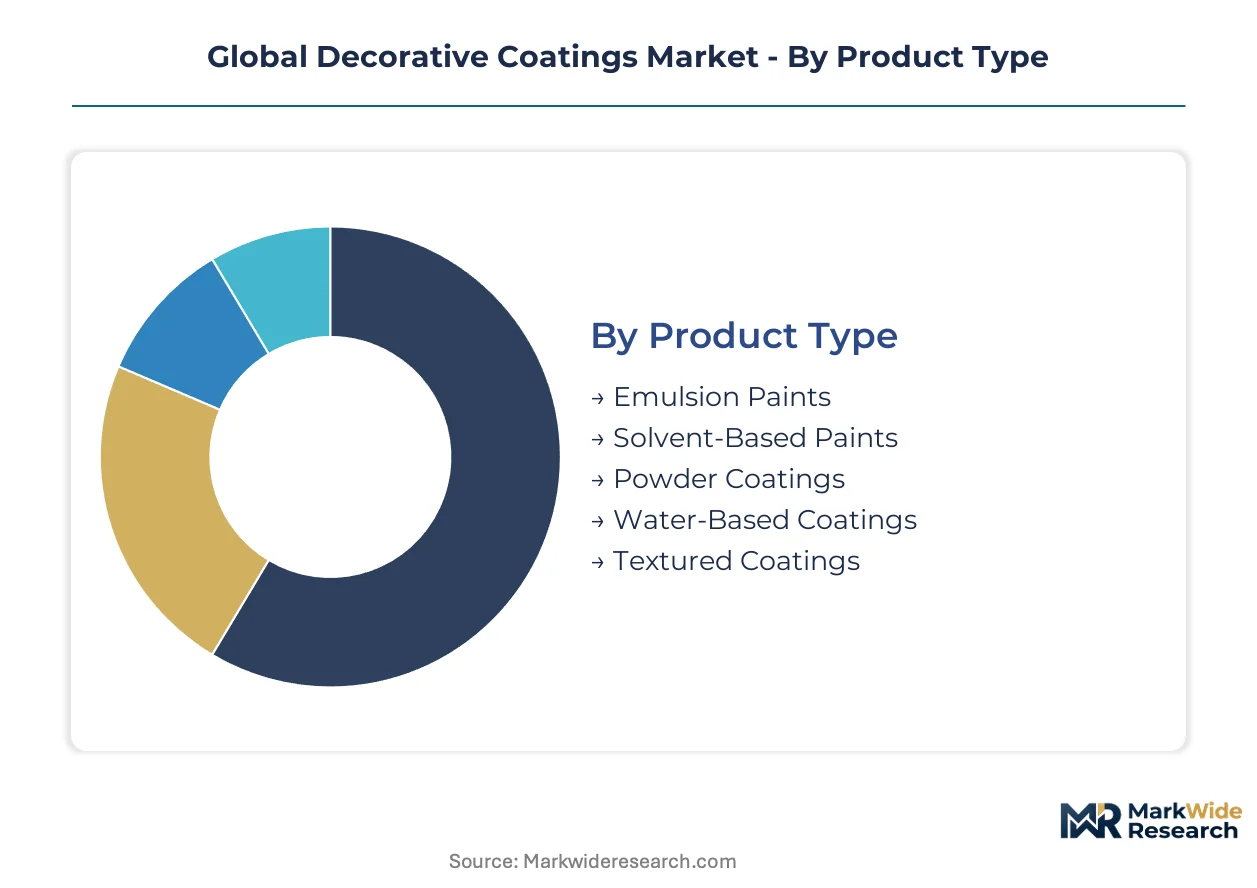
Segmentation in decorative coatings reveals how formulation chemistry, substrate requirements, and procurement channels allocate margin capture differently across the value chain. Understanding these divides exposes where specification authority concentrates and where supply-side positioning creates defensible revenue streams.
Product Type:
Margin pools in this category concentrate in water-based emulsions and powder systems where regulatory compliance creates qualification barriers.
- Emulsion Paints:Acrylic and vinyl-acrylic latex dispersions in water-based matrices dominate residential interior specification. Demand clusters in Indian tier-two cities and suburban North American renovation markets where low-odor application drives premium positioning.
- Powder Coatings:Thermosetting resin systems applied electrostatically to metal substrates deliver zero-VOC profiles with near-complete overspray recovery. Commercial facade projects in Germany and the Netherlands specify these systems for 15-year maintenance contracts.
- Solvent-Based Paints:Alkyd and polyurethane resin solutions in organic solvent carriers face EPA hazardous air pollutant limits in the United States.
- Water-Based Coatings:Broader category spanning emulsions, water-dispersible alkyds, and hybrid systems subject to REACH VOC restrictions.
- Textured Coatings:Aggregate-filled systems applied in thick films for aesthetic surface effects on exterior masonry.
Emulsion Paints holds installed capacity. Powder Coatings is rotating up the share rankings.
Application:
Volume concentration in this category tracks housing stock turnover and commercial construction cycles across distinct climate zones.
- Wall Coatings:Interior and exterior emulsion systems applied to plaster, drywall, and masonry substrates generate the deepest margin pools in residential end-use segments. Self-healing polymer networks are compressing repaint cycles in North American commercial maintenance contracts.
- Metal Protection:Primers and topcoats for architectural steel and aluminum face REACH authorization pressure on chromium-based corrosion inhibitors. German formulators advance silica-based and rare-earth alternatives to maintain specification eligibility.
- Wood Finishing:Clear and pigmented systems for interior trim, cabinetry, and exterior joinery.
- Ceiling Coatings:Specialized flat emulsions with high hide and acoustic properties for commercial interiors.
- Furniture Refinishing:Decorative lacquers and conversion varnishes for residential and contract furniture.
- Decorative Art:Artist-grade pigments and specialty effect coatings for murals and architectural features.
Wall Coatings commands specification volume. Metal Protection is gaining share fastest on zero-VOC powder conversion.
End User:
Procurement authority in this category fragments between individual homeowners, facilities management platforms, and public procurement offices with divergent performance horizons.
- Residential Properties:Single-family and multi-family housing drives specification of premium interior emulsions with antimicrobial and stain-resistant claims. Repainting cycles in Indian owned-retail networks extend into rural pin codes.
- Commercial Complexes:Office, retail, and mixed-use developments consolidate vendor panels around predictive performance analytics rather than unit-cost bidding.
- Hospitality Venues:Hotels and restaurants demand rapid-cure, high-durability systems with color-matching precision.
- Educational Institutes:Schools and universities specify low-VOC systems under LEED and BREEAM certification pathways.
- Government Buildings:Public procurement in the European Union aligns with EU Green Deal bio-based binder mandates.
Residential Properties holds installed demand. Commercial Complexes is climbing the fastest on facilities management platform consolidation.
Distribution Channel:
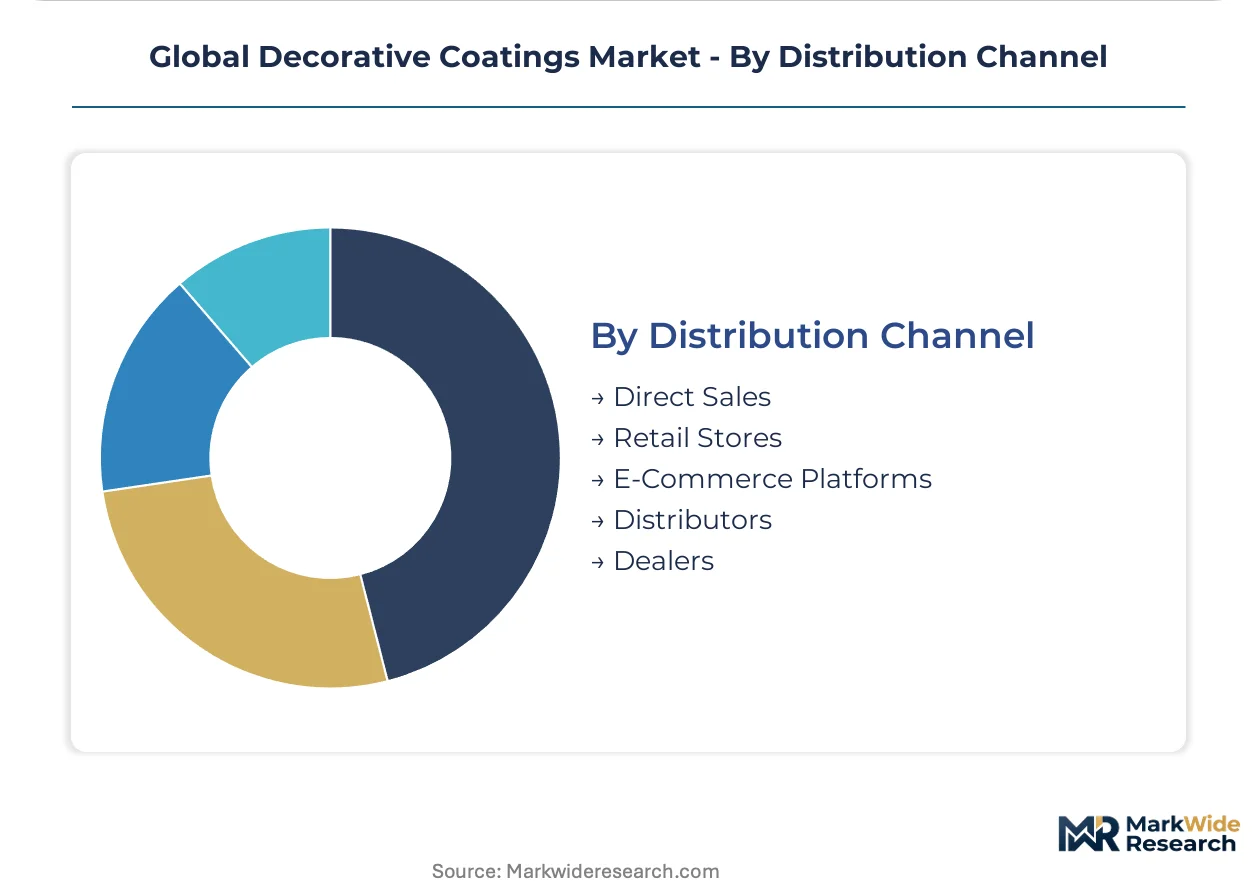
Channel economics in this category diverge between owned-retail control in South Asia and specification-influencer models in developed markets.
- Retail Stores:Company-owned and franchised outlets in India extend into rural pin codes with color-matching hardware and technical consultation. Asian Paints Limited's network demonstrates how captive distribution captures repainting cycles.
- Distributors:Regional stockists serving professional painting contractors and small retailers concentrate inventory risk.
- Direct Sales:Manufacturer-to-contractor relationships for large commercial projects with embedded lifecycle databases.
- E-Commerce Platforms:Online marketplaces gaining traction in urban consumer segments for standard emulsion products.
- Dealers:Independent retailers serving local construction markets with limited technical support.
Retail Stores holds installed infrastructure. Direct Sales is rotating up the share rankings on commercial project consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers concentrate in suburban renovation corridors, tier-two Indian cities, and German commercial facade markets where specification authority fragments between facilities management platforms and owned-retail networks.
United States
Suburban housing stock turnover in Sun Belt metros drives premium interior emulsion specification. EPA hazardous air pollutant limits compel alkyd reformulation across architectural coating lines. Dallas-Fort Worth and Phoenix construction clusters absorb water-based polymer capacity expansions from Gulf Coast resin producers.
Germany
Commercial facade maintenance contracts specify 15-year performance warranties with self-healing polymer networks. REACH authorization timelines for chromium-based corrosion inhibitors accelerate silica-based primer development. The Rhine-Ruhr industrial corridor hosts powder coating application facilities serving Dutch and Belgian cross-border projects.
India
Tier-two cities including Jaipur and Lucknow generate housing stock expansion for antimicrobial interior emulsions. BIS certification mandates for lead and chromium content tighten import qualification windows. Asian Paints Limited's owned-retail network extends color-matching infrastructure into rural pin codes across Maharashtra and Gujarat.
China
Titanium dioxide production concentration in eastern provinces creates input cost volatility for decorative coating formulators. The country's national environmental regulator enforces dual carbon goals that redirect capacity toward water-based emulsion systems. Yangtze River Delta chemical clusters supply acrylic latex dispersions to Southeast Asian export markets.
Netherlands
EU Green Deal procurement mandates drive bio-based binder specification in public building renovations. ECHA restrictions on conventional biocides redirect preservation system R&D toward mineral alternatives. Rotterdam port logistics clusters handle powder coating resin imports for German and Belgian metal protection applications.
Global Decorative Coatings Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive resin supply and regional specialists with owned-retail density. Three archetypes dominate: multinational coating formulators with automotive heritage extending into architectural color-matching, Asian family-controlled enterprises with rural distribution infrastructure, and European regulatory compliance leaders with substitution program expertise. Competitive moves concentrate on backward integration into titanium dioxide and acrylic latex supply, plus ISO 14001 certification acquisition for commercial project eligibility.
Within the multinational tier, PPG Industries and Sherwin-Williams Company exemplify scale-driven positions anchored in North American specification channels. Akzo Nobel N.V. occupies a compliance-leadership position shaped by REACH-era reformulation capabilities. Asian Paints Limited represents the distribution-integrated archetype with captive retail networks spanning South Asian pin codes.
| Leading Market Players |
|---|
| Sherwin-Williams Company |
| PPG Industries, Inc. |
| Akzo Nobel N.V. |
| Nippon Paint Holdings Co., Ltd. |
| Asian Paints Limited |
| BASF SE |
| RPM International Inc. |
| Kansai Paint Co., Ltd. |
| Jotun Group |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements with titanium dioxide suppliers in eastern China lock in both feedstock access and price visibility for decorative coating formulators navigating volatile pigment markets. These contracts typically index to regional chemical benchmarks while embedding minimum volume commitments that shape working capital requirements across the value chain.
Pricing Analysis
Cost-plus contracts with titanium dioxide indexation dominate raw material procurement for water-based emulsion producers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 14001-certified systems from commodity emulsions and import-dependent solvent-borne alternatives. Pricing pressure stems from REACH-driven biocide substitution costs that compress margins in European specification channels. Residential renovation buyers in suburban North America exhibit highest price sensitivity, while facilities management platforms prioritize lifecycle cost over unit pricing.
Supply Chain Analysis
Inventory cycles for titanium dioxide extend to twelve-to-eighteen weeks due to ocean freight scheduling from Chinese production clusters in Shandong and Jiangsu provinces. Acrylic latex dispersion capacity concentrates in China, Germany, and the United States, with formulators drawing from Yangtze River Delta chemical parks for Southeast Asian export supply. Single-source vulnerability in rare-earth corrosion inhibitor alternatives creates qualification bottlenecks for metal primer producers. Distribution runs through owned-retail networks in South Asia and specification-influencer channels in developed markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory jurisdictions creates niche opportunities for specialists mastering multi-jurisdiction registration workflows. Tier-two urbanization in India and facilities management platform consolidation in North America generate divergent demand profiles that resist standardization.
For Market Incumbents: Shield specification position in European commercial projects by accelerating ISO 14001 certification acquisition ahead of Green Deal procurement mandates. Prioritize backward integration into acrylic latex supply through Gulf Coast capacity partnerships that reduce exposure to Yangtze River Delta logistics disruptions. Defend against Asian Paints Limited's rural network extension by embedding color-matching hardware in contractor-facing distributor locations.
For New Entrants and Emerging Players: Lead with bio-based binder formulations targeting EU public procurement channels where substitution program expertise remains scarce among mid-tier formulators. Penetrate Indian tier-two cities through technical consultation services that Asian Paints Limited's owned-retail network underserves for commercial project specification. Deploy direct sales teams with embedded lifecycle databases to capture facilities management platform consolidation in North American Sun Belt metros.
For Investors and Strategic Acquirers: Regional specialists with REACH-era reformulation capabilities and captive distribution in South Asian pin codes represent priority acquisition targets. Long-term viability hinges on water-borne polymer stabilization expertise concentration among legacy specialists that integrated chemical conglomerates cannot replicate through internal development. Monitor ECHA authorization timelines for remaining conventional biocides as inflection indicator for mineral alternative qualification premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Latex | Gulf Coast resin capacity captures water-based emulsion demand from Dallas-Fort Worth construction clusters. |
| ISO 14001 Certification Acquisition | Environmental management credentials unlock EU Green Deal-aligned public procurement eligibility. |
| Rural Retail Network Extension | Owned outlets in Maharashtra and Gujarat pin codes capture underpenetrated Indian repainting cycles. |
| Bio-Based Binder Development | Plant-derived polyurethane hybrids open specification pathways in REACH-restricted European markets. |
| Powder Coating Application Capacity | Zero-VOC metal protection systems serve German and Dutch commercial facade maintenance contracts. |
Research Methodology
A standing panel of plant managers at titanium dioxide production facilities, procurement leads at downstream coating formulators, distribution channel partners in Indian tier-two cities, and technical R&D directors at acrylic latex producers provided ongoing calibration across primary interview cycles. Secondary validation drew from customs and trade data, American Chemistry Council and Cefic industry reports, SEC 10-K filings of listed coating manufacturers, and EPA hazardous air pollutant enforcement disclosures. Bottom-up volume modeling triangulated against top-down value estimates derived from regional construction activity indices.
Consistency checks validated volume and value outputs against external benchmarks including regional housing stock turnover data and commercial construction permit databases. Segmentation modeling spanned formulation chemistry, substrate application, end-user procurement authority, and distribution channel structure across the analysis window. CAGRs were derived from regression analysis of historical volume trends projected against regulatory phase-out schedules and urbanization patterns. Industry-specific inputs included REACH authorization timelines, BIS certification mandates, and powder coating cure-temperature constraints.
Forecasts assume regulatory continuity in EPA hazardous air pollutant limits, REACH substance restrictions, and BIS lead content mandates; material policy shifts would require re-modeling of alkyd reformulation economics and import qualification windows. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Interior Architectural Coatings Market
Paints & Coatings
Small Paint Pail Market
Paints & Coatings
Fluorescent Paint Market
Paints & Coatings
Global Texture Paint Market
Paints & Coatings
North America Paints and Coatings Market
Paints & Coatings
Paint Defoamers Market
Paints & Coatings
Asia-Pacific Paint Thinner Market
Paints & Coatings
Metal Paint Tray Market
Paints & Coatings
Resins in Paints and Coatings Market
Paints & Coatings
Hybrid Paint Cans Market
Paints & Coatings
Bituminous Paints Market
Paints & Coatings
Anti-Fungal and Anti-Bacterial Paints Market
Paints & Coatings
India Architectural Coatings Market
Paints & Coatings
Middle East and Africa Paints and Coatings Market
Paints & Coatings
Faux Paints and Coatings Market
Paints & Coatings
Asia-Pacific Paints and Coatings Additives Market