
 Sol Gel Nanocoating Market | 2026-2036
Sol Gel Nanocoating Market Size, Share, and Industry Trends Forecast 2026-2036
Sol Gel Nanocoating Market Analytics
The gap between laboratory sol-gel formulations and industrial throughput is narrowing as roll-to-roll coating lines integrate in-situ gelation modules. Solvay leverages its fluoropolymer heritage to anchor hybrid sol-gel supply chains for aerospace clients. 3M competes through proprietary silane-crosslinking platforms that dominate electronics moisture-barrier applications. Nanovations Pty Ltd specializes in ambient-cure titania coatings for building facades, occupying a distinct geographic niche across Australian and Southeast Asian infrastructure projects.
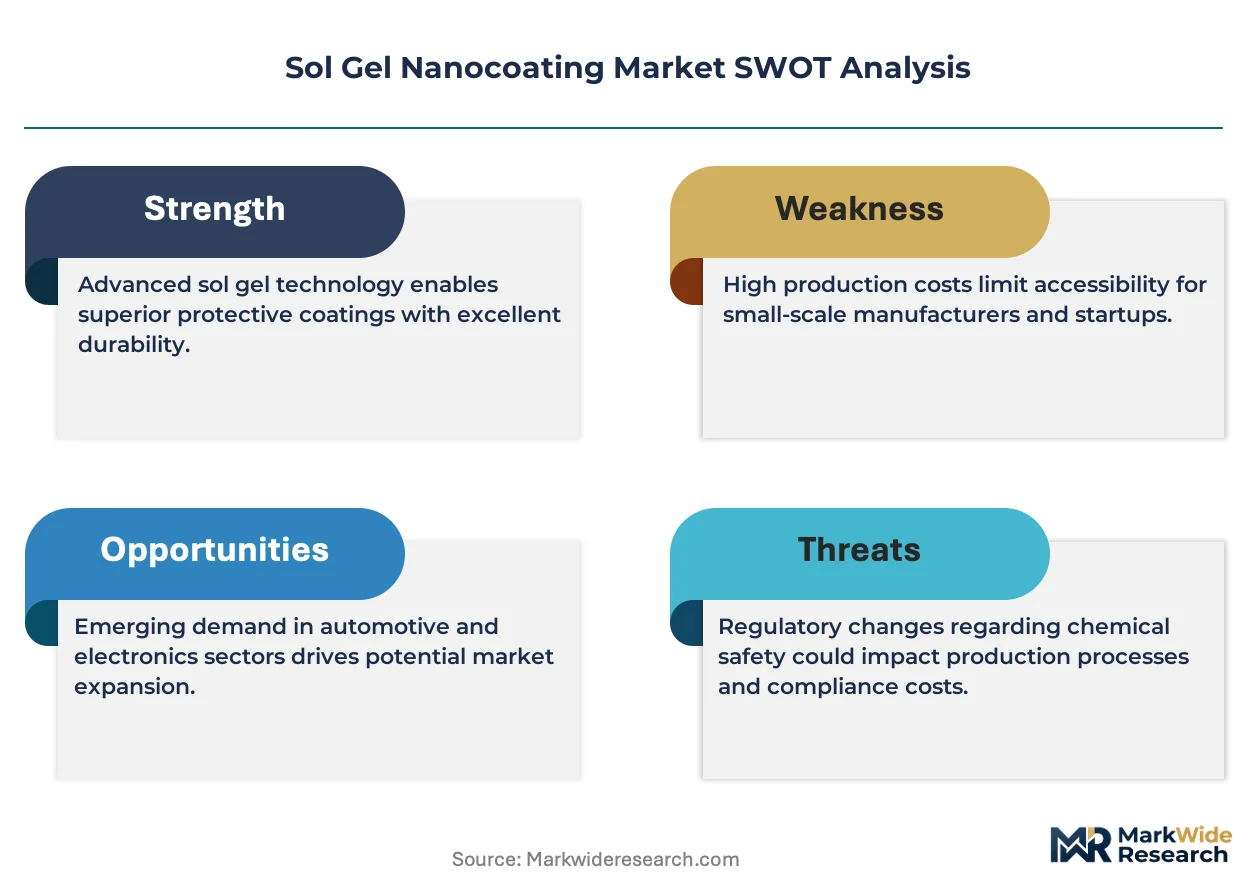
Sol gel nanocoatings constitute thin inorganic or hybrid organic-inorganic films formed through hydrolysis and condensation of metal alkoxides, typically 50–500 nm thick, engineered for abrasion resistance, optical clarity, or chemical protection. The material dimension reveals silica formulations leading volume due to mature precursor availability and broad substrate compatibility, while zirconia coatings command premium positioning in high-temperature aerospace segments. Application-level demand structures around automotive and electronics clusters, with medical device coatings representing the fastest-expanding margin pool as sterilization-resistant barrier requirements intensify.
REACH registration obligations through ECHA govern precursor chemical authorization across European manufacturing nodes, while EPA VOC emission limits under the Clean Air Act constrain solvent-based formulation deployment in US production facilities. FDA device coating biocompatibility standards further shape medical end-user procurement specifications. Stakeholders must monitor evolving fluorinated substance restrictions across multiple jurisdictions, as precursor chemistry substitutions will determine which formulation platforms retain commercial viability.
Market Dynamics
Roll-to-roll coating lines with in-situ gelation modules are compressing the gap between laboratory sol-gel formulations and industrial throughput, fundamentally restructuring how manufacturers scale nanocoating deployment.
Growth Catalysts
- REACH compliance obligations:ECHA precursor registration requirements across European manufacturing nodes are pushing formulators toward water-based sol-gel systems. Automotive suppliers in Germany now specify these coatings for lightweight aluminum body panels.
- Electronics moisture-barrier demand:Silane-crosslinking platforms are capturing specification wins in semiconductor packaging applications. Device manufacturers prioritize optical clarity combined with chemical protection for sensitive components.
- Aerospace corrosion specification tightening:OEM turbine blade coating requirements are expanding sol-gel adoption for high-temperature oxidation resistance. Zirconia formulations command premium positioning in this segment.
Market Restraints
- Metal alkoxide precursor volatility:Supply concentration for specialized titanium and zirconium alkoxides creates input cost instability. German and Japanese chemical suppliers dominate precursor manufacturing.
- Fluorinated substance restriction trajectory:Multiple jurisdictions are tightening controls on perfluorinated precursors. Formulation platforms dependent on these chemistries face substitution pressure.
- Curing energy intensity:Thermal gelation requirements for certain hybrid formulations limit deployment on temperature-sensitive substrates. Ambient-cure alternatives remain narrower in performance scope.
Strategic Opportunities
- Medical device sterilization barriers:FDA biocompatibility standards for implantable devices are creating specification windows for sterilization-resistant nanocoatings. This application vertical shows the fastest margin expansion.
- Australian infrastructure facade protection:Ambient-cure titania coatings for building exteriors remain underpenetrated across Southeast Asian construction markets. Climate resilience specifications drive specification interest.
- Photovoltaic anti-reflective convergence:Sol-gel silica formulations are integrating with cell manufacturing lines. Solar module producers seek optical clarity improvements without vacuum deposition costs.
Industry Challenges
- Formulation-to-line integration complexity:Customizing gelation kinetics for existing coating equipment requires specialized process engineering talent. Manufacturers report 12-18 month qualification timelines for new production integrations.
- ISO 10993 certification pathway duration:Medical device coating approvals face extended biocompatibility testing protocols. Early-stage coating developers struggle to fund parallel regulatory tracks across multiple jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sol Gel Nanocoating Market |
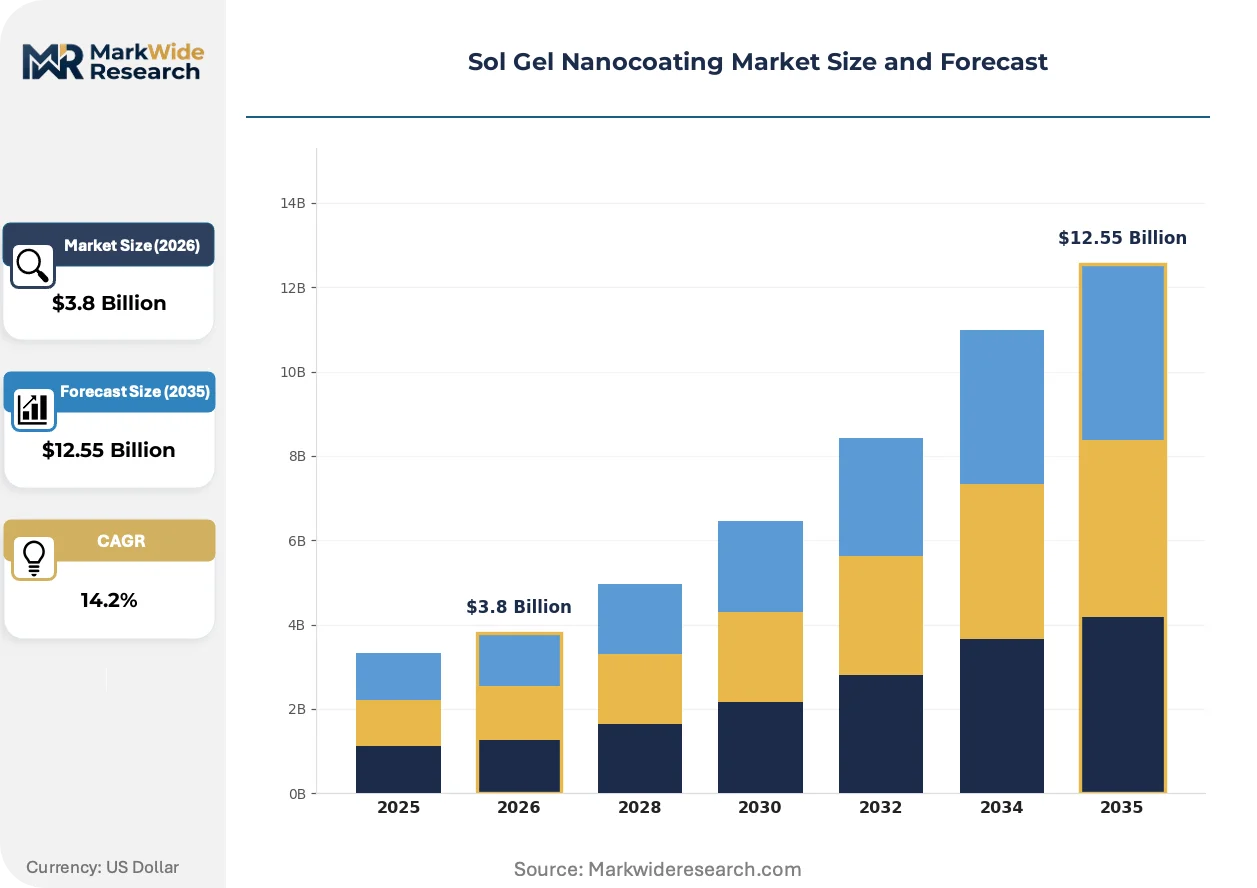
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Aerospace, Automotive, Electronics, Medical Material: Silica, Zirconia, Alumina, Titania Formulation: Sol, Gel, Hybrid, Powder End User: Manufacturers, Contractors, Researchers, Consumers |
| Companies Covered | Solvay, ACTnano, 3M, Nanovations Pty Ltd, CHEMAT TECHNOLOGY INC., PPG Industries, Nanoslic, CMR Coatings, SCHOTT AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sol Gel Nanocoating Market Evolving Landscape
Active gelation control technologies are compressing curing cycles and expanding substrate compatibility, while regulatory chemistry restrictions are forcing precursor substitutions across formulation portfolios.
Photocatalytic titania-silica hybrid coatings with tuned bandgap structures are rendering obsolete conventional organic UV stabilizers in exterior architectural applications. German automotive suppliers now specify these systems for self-cleaning body panel finishes. The technology is compressing maintenance cycle frequencies and redefining warranty terms for coating performance.
EPA VOC emission limits under the Clean Air Act are constraining solvent-based formulation deployment across US production facilities. Coating manufacturers are reconfiguring precursor supply chains toward aqueous hydrolysis routes. Electronics moisture-barrier applications in North American facilities show the most rapid formulation platform migration.
Specification consolidation among tier-one automotive OEMs is compressing supplier qualification cycles and raising performance verification requirements. Coating vendors must now demonstrate 10-year durability data before platform adoption. This pattern is most visible in German and Japanese automotive supply chains, where procurement teams centralize coating decisions at the OEM level rather than tier-two discretion.
Sol Gel Nanocoating Market Segmentation
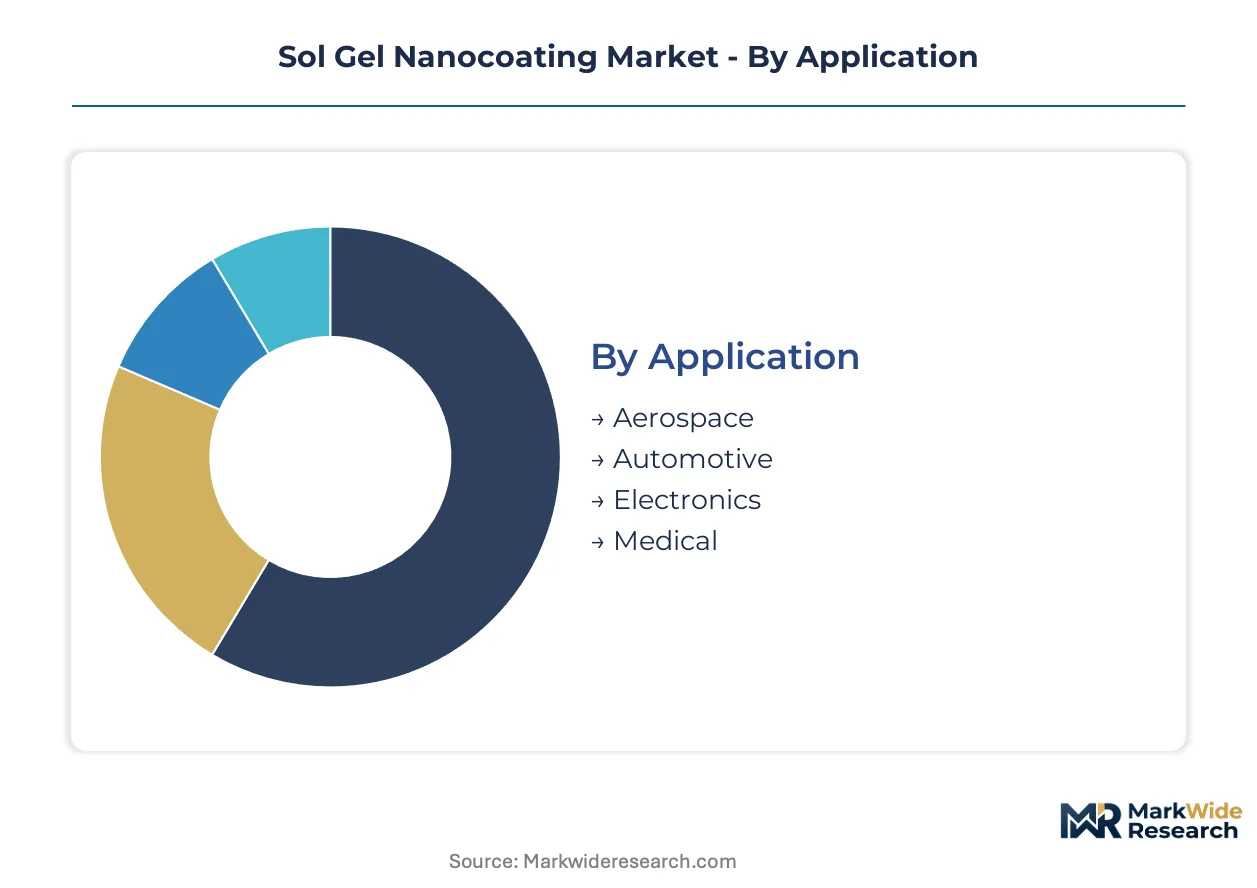
Segmentation in sol-gel nanocoatings reveals how precursor chemistry, curing protocols, and end-use specifications fragment demand across incompatible performance tiers. Formulators must match gelation kinetics to substrate constraints while navigating divergent regulatory thresholds across application verticals.
Application:
Mature industrial coatings dominate volume, while emerging medical applications reshape margin structures through sterilization-resistant barrier specifications.
- Aerospace:Zirconia formulations deliver high-temperature oxidation resistance for turbine blade coatings. OEM specification tightening in Germany and Japan drives qualification cycles for corrosion-resistant platforms.
- Automotive:German suppliers integrate silica-based systems into lightweight aluminum body panels for abrasion resistance and optical clarity. REACH compliance obligations accelerate water-based formulation adoption across European manufacturing nodes.
- Electronics:Silane-crosslinking platforms capture moisture-barrier specifications in semiconductor packaging applications.
- Medical:Sterilization-resistant barrier coatings for implantable devices face extended FDA biocompatibility testing protocols.
Automotive retains volume leadership; medical holds the steepest expansion curve.
Material:
Cost tiers separate commodity precursors from premium ceramic formulations, with supply concentration determining formulation accessibility.
- Silica:Mature precursor availability and broad substrate compatibility anchor volume production. Electronics manufacturers in North American facilities specify silica formulations for optical clarity combined with chemical protection.
- Zirconia:Premium positioning in high-temperature aerospace segments commands elevated pricing. Japanese and German chemical suppliers dominate specialized zirconium alkoxide manufacturing.
- Alumina:Hardness specifications suit wear-resistant industrial coating applications.
- Titania:Photocatalytic hybrid coatings with tuned bandgap structures displace organic UV stabilizers in Australian and Southeast Asian building facade projects.
Silica dominates by tonnage; titania climbs the fastest through photocatalytic specification expansion.
Formulation:
Customer type determines curing infrastructure requirements, separating integrated manufacturers from specification-driven contractors.
- Sol:Liquid precursor systems enable dip-coating and spin-coating integration for electronics manufacturers. EPA VOC emission limits under the Clean Air Act constrain solvent-based deployment in US production facilities.
- Gel:Pre-condensed networks suit roll-to-roll coating lines with in-situ gelation modules. Automotive OEMs in Germany centralize procurement decisions at the platform level.
- Hybrid:Organic-inorganic matrices balance flexibility with chemical resistance for medical device applications.
- Powder:Solid-state delivery formats reduce shipping constraints for remote infrastructure projects.
Gel formulations retain volume leadership; hybrid platforms gain share fastest through medical sterilization barrier specifications.
End User:
Supply concentration fragments across research-to-production transitions, with qualification timelines separating pilot-scale researchers from validated manufacturers.
- Manufacturers:Integrated production lines demand 10-year durability verification before platform adoption. Tier-one automotive OEMs compress supplier qualification cycles through centralized procurement.
- Contractors:Ambient-cure titania coatings for building facades serve Australian and Southeast Asian infrastructure markets. Climate resilience specifications drive specification interest across underpenetrated construction verticals.
- Researchers:Laboratory-scale formulation development faces 12-18 month qualification timelines for production line integration.
- Consumers:Limited direct access due to specialized application equipment requirements.
Manufacturers retain volume leadership; contractors hold the steepest expansion curve through infrastructure climate adaptation spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement teams in Germany, aerospace specification engineers in the United States, and electronics manufacturers across East Asia drive differentiated demand patterns for sol-gel nanocoating platforms. Each geography imposes distinct regulatory thresholds that reshape formulation chemistry and curing infrastructure requirements.
United States
EPA VOC emission limits under the Clean Air Act constrain solvent-based formulation deployment across domestic production facilities. Electronics moisture-barrier manufacturers in California and Texas accelerate migration toward aqueous hydrolysis routes. Aerospace OEMs in the Pacific Northwest specify zirconia formulations for high-temperature turbine blade applications.
Germany
REACH registration obligations through ECHA govern precursor chemical authorization across European manufacturing nodes. Automotive suppliers in Bavaria and Baden-Württemberg integrate silica-based systems into lightweight aluminum body panels. Procurement centralization at tier-one OEMs compresses supplier qualification cycles to 12-month windows.
Japan
METI industrial standards and JIS certification requirements shape coating performance verification protocols. Electronics packaging manufacturers in the Kanto region specify silane-crosslinking platforms for semiconductor moisture barriers. Specialized zirconium alkoxide supply concentrates among domestic chemical suppliers serving aerospace sub-tier producers.
Australia
Climate resilience specifications for infrastructure facades drive specification interest across New South Wales and Victoria. Ambient-cure titania coatings from Nanovations Pty Ltd occupy building exterior protection markets. TGA medical device standards create parallel certification pathways for sterilization-resistant barrier coatings.
China
MIIT industrial policy and GB standards govern coating performance benchmarks for domestic manufacturing. Solar module producers in Jiangsu and Zhejiang integrate sol-gel silica formulations for anti-reflective cell surface treatments. Dual carbon goals accelerate water-based formulation adoption across state-owned industrial coating facilities.
Sol Gel Nanocoating Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation platforms that diverge by curing infrastructure and substrate compatibility. The vendor base organizes around three strategic archetypes: diversified chemical conglomerates with fluoropolymer heritage, silane-crosslinking technology specialists, and ambient-cure regional niche players. Consolidation pressure intensifies as tier-one automotive OEMs centralize procurement decisions and compress qualification timelines. Competitive moves concentrate on backward integration into precursor supply and technology licensing partnerships for roll-to-roll coating line integration.
Among diversified chemical conglomerates, Solvay anchors hybrid sol-gel supply chains for aerospace clients through its fluoropolymer heritage. 3M occupies the silane-crosslinking technology vector that dominates electronics moisture-barrier specifications. Nanovations Pty Ltd exemplifies the regional specialist archetype, concentrating ambient-cure titania coatings across Australian and Southeast Asian infrastructure markets where climate resilience specifications drive procurement.
| Leading Market Players |
|---|
| Solvay |
| ACTnano |
| 3M |
| Nanovations Pty Ltd |
| CHEMAT TECHNOLOGY INC. |
| PPG Industries |
| Nanoslic |
| CMR Coatings |
| SCHOTT AG |
| Others |
Value Network & Pricing Analysis
German and Japanese chemical suppliers dominate specialized titanium and zirconium alkoxide manufacturing, anchoring margin capture upstream while coating formulators downstream face compressed pricing power on commodity silica formulations. This concentration pattern splits profitability between precursor suppliers and integrated coating platforms.
Pricing Analysis
Cost-plus contracts with metal alkoxide indexation govern long-term supply agreements between precursor manufacturers and coating formulators. Three-tier pricing structure across premium, standard, and economy levels separates zirconia aerospace specifications from silica automotive volumes and titania infrastructure grades. Pricing pressure stems from REACH compliance-driven formulation requalification costs. Automotive OEMs exhibit highest price sensitivity through centralized procurement, while medical device manufacturers accept premium positioning for sterilization-resistant barriers.
Supply Chain Analysis
Contract manufacturing concentrates among German automotive coating integrators, Japanese electronics packaging specialists, and Australian infrastructure applicators. Precursor supply draws from German and Japanese chemical producers, with Chinese solar module manufacturers emerging as volume consumers. Single-source vulnerability runs through specialized zirconium alkoxide channels. Distribution runs through direct OEM supply agreements for automotive and aerospace, with contractor networks serving building facade applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tier-one automotive OEMs have centralized procurement decisions, shifting buyer power toward consolidated specification authorities and compressing supplier margins across coating tiers.
For Market Incumbents: Entrench fluoropolymer heritage positions through backward integration into precursor supply and accelerated certification investment for medical device barriers. Silane-crosslinking platforms face substitution pressure from aqueous hydrolysis alternatives; defend through IP licensing partnerships for roll-to-roll coating line integration. For New Entrants and Emerging Players: Establish a beachhead in Australian and Southeast Asian infrastructure facade protection, where ambient-cure titania coatings remain underpenetrated and climate resilience specifications drive procurement. Target contractor networks with powder formulation delivery formats that reduce shipping constraints for remote projects. For Investors and Strategic Acquirers: Capital is best deployed toward hybrid formulation specialists with FDA biocompatibility certification pathways already initiated, as medical sterilization barriers represent the steepest margin expansion curve across the analysis window. Watch for inflection signals in photovoltaic anti-reflective coating adoption rates among solar module producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Solvay anchors hybrid sol-gel supply chains through captive alkoxide sourcing. |
| Medical Device Certification Investment | FDA biocompatibility pathways unlock sterilization-resistant barrier premium positioning. |
| Roll-to-Roll Coating Line Partnership | 3M licenses silane-crosslinking platforms for semiconductor packaging moisture barriers. |
| Water-Based Formulation Migration | EPA VOC limits force aqueous hydrolysis adoption across North American electronics facilities. |
| Ambient-Cure Technology Licensing | Nanovations Pty Ltd expands titania coating reach through Southeast Asian contractor networks. |
Research Methodology
A spread of perspectives from coating formulators, automotive procurement leads, aerospace specification engineers, and medical device regulatory affairs directors converged on the working assumptions. Primary interviews combined with secondary validation from ECHA REACH registration databases, EPA Clean Air Act enforcement records, FDA 510(k) filing repositories, and customs trade data for metal alkoxide imports. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material chemistry tier, curing protocol infrastructure, end-use vertical, and regional regulatory cluster. CAGRs derived from weighted average growth trajectories across these segments. Industry-specific forecast inputs incorporated solar module production capacity expansion and automotive lightweighting aluminum adoption curves.
Stress conditions across metal alkoxide price volatility, fluorinated substance restriction timing, and medical device approval duration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about gelation kinetics scalability and qualification timeline compression. Quarterly review of OEM procurement centralization indicators and photovoltaic coating specification adoption is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Europe Super Hydrophobic Coatings Market
Coatings
Superhydrophobic Coatings Market
Coatings
Global Industrial Floor Coatings Market
Coatings
Global Flat Glass Coatings Market
Coatings
2K Protective Coatings Market
Coatings
United Kingdom Protective Coatings Market
Coatings
Global Automotive Specialty Coatings Market
Coatings
Flexible Waterproof Coating Market
Coatings
Sol-Gel Coatings Market
Coatings
Wood Sealer Market
Coatings
Industrial Coatings Market
Coatings
Global Fireproofing Coatings for Wood Market
Coatings
Camouflage Coatings Market
Coatings
Wire Enamels Market
Coatings
Polyvinylidene Chloride (PVDC) Coated Films Market
Coatings
Global Low Friction Coatings Market