
 Sustained Release Coatings Market | 2026-2036
Sustained Release Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Sustained Release Coatings Market Intelligence
Pharmaceutical-grade polymer coatings with precise dissolution profiles is rotating the market toward higher-value applications. Global chemical giant BASF SE leverages its extensive polymer science portfolio to serve both pharmaceutical and agricultural clients. Evonik specializes in advanced methacrylic acid copolymers for enteric and sustained-release functionalities. Colorcon dominates the on-dosage finishing space with its integrated film coating systems and technical support.
Sustained release coatings are functional films, typically polymer-based, applied to active ingredients like pharmaceutical pellets or fertilizer granules. These materials control the release rate by managing diffusion or erosion characteristics based on their molecular structure. Their main purpose is to maintain consistent therapeutic drug levels or prolong the active life of agricultural chemicals. Polymer-based coatings lead the market in volume, while the pharmaceutical application segment commands the highest margins due to stringent performance standards.
Regulatory bodies like the US FDA and the EMA in Europe enforce strict criteria for dissolution profiles and excipient safety in drug products. These demanding requirements directly influence polymer selection and manufacturing process validation for suppliers. Formulators must navigate the complex and sometimes diverging material safety standards between pharmaceutical, agrochemical, and food-contact applications.
Market Dynamics
The market's central dynamic is the technical and regulatory demand for precision in release profiles. Stringent criteria from pharmaceutical regulators like the US FDA and EMA are forcing innovation away from generic films toward highly engineered polymer systems.
Growth Catalysts
- Pharmaceutical Regulations:Strict mandates from the US FDA and Europe's EMA for precise dissolution profiles and excipient safety in oral solid dosage forms compel drug makers to adopt advanced, validated coating technologies.
- Agrochemical Demand:Modernization in the agricultural sectors of Brazil and India drives the need for controlled-release fertilizers and pesticides, which improve crop yields and reduce environmental runoff, boosting polymer coating consumption.
- Biodegradable Polymers:Development of polylactic acid (PLA) and polycaprolactone (PCL) based coatings addresses environmental concerns, opening new applications in both agriculture and pharmaceuticals where sustainability is a key purchasing criterion.
Market Restraints
- Raw Material Volatility:The price and availability of key polymer precursors, such as methacrylic acid and ethyl acrylate, are subject to fluctuations in the petrochemical market, impacting production costs and margin stability for coating manufacturers.
- Process Consistency:Achieving uniform coating thickness and porosity at commercial scale is technically challenging and capital-intensive, creating a high barrier to entry and restraining rapid supply expansion for high-performance applications.
- Divergent Standards:Navigating conflicting material safety and purity requirements between pharmaceutical (EMA, FDA), agrochemical (EPA, EFSA), and food-contact applications complicates formulation and limits the interchangeability of polymer grades.
Strategic Opportunities
- Nutraceutical Applications:The growing market for vitamins, probiotics, and dietary supplements offers a less regulated but high-volume opportunity for coatings that can protect sensitive ingredients and manage release in the digestive tract.
- Smart Responsive Coatings:Formulating polymers that release active ingredients in response to specific triggers like pH, enzymes, or temperature can create next-generation drug delivery systems for targeted therapies, commanding premium prices.
- Southeast Asian Expansion:Establishing formulation support and production facilities in emerging pharmaceutical manufacturing hubs like Vietnam and Indonesia provides a first-mover advantage to serve local and regional drug producers.
Industry Challenges
- Regulatory Validation Timelines:The extensive time and cost required to validate a new polymer excipient through the US FDA or EMA regulatory pathways can delay product launches by several years, creating significant operational hurdles.
- Scale-Up Complexity:Transferring a coating process from a laboratory fluid bed coater to a large-scale production unit without altering the drug release profile is a major technical challenge for formulators and contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustained Release Coatings Market |
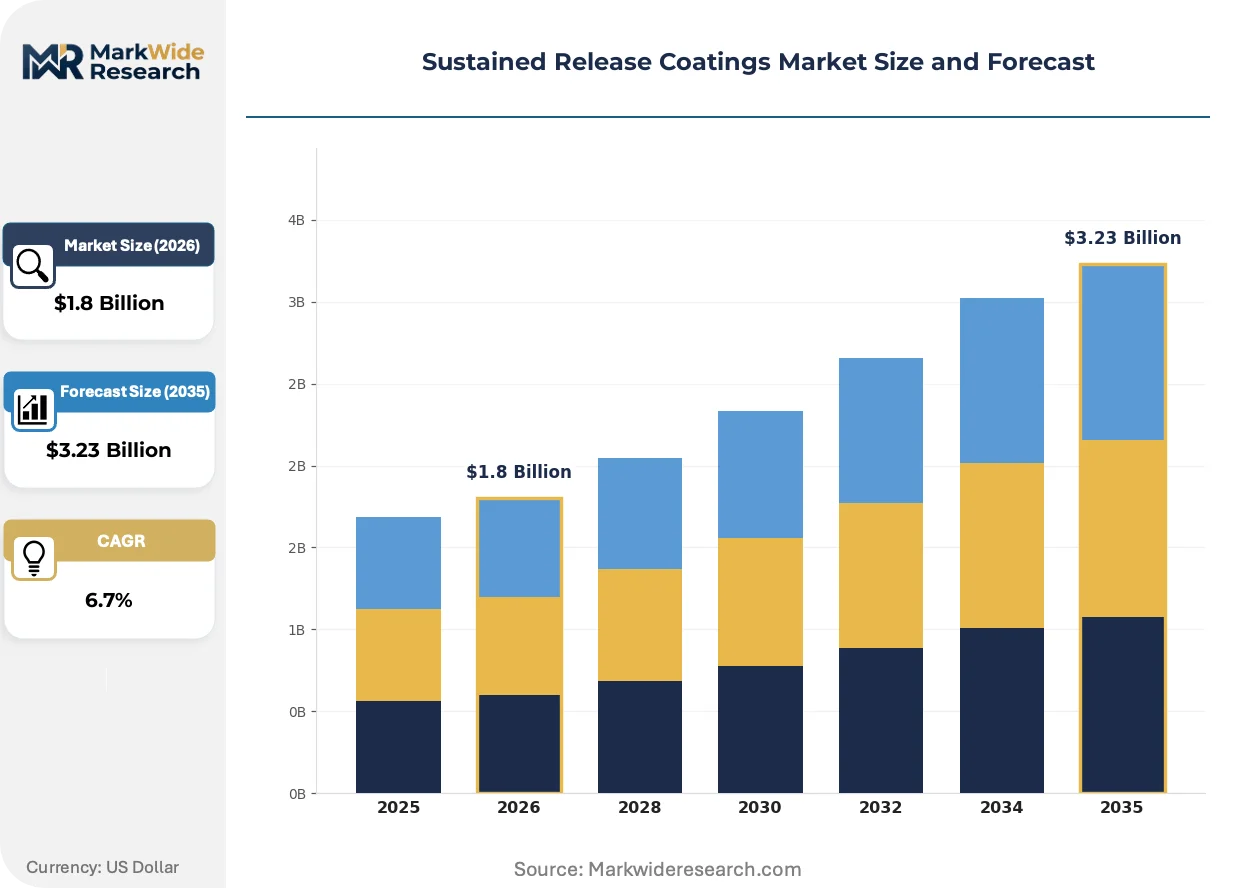
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer-Based, Lipid-Based, Inorganic-Based, Hybrid Coatings Application: Pharmaceutical, Agricultural Chemicals, Food Packaging, Industrial Equipment Technology: Microencapsulation, Layer-by-Layer Assembly, Sol-Gel Method, Spray Drying End User: Drug Manufacturers, Agrochemical Producers, Food Processing Firms, Equipment Fabricators |
| Companies Covered | BASF SE, Evonik, Colorcon, Coating Place, Inc., Ashland Inc., JRS PHARMA, Eastman Chemical Co., Spraycel Coatings, Panchsheel Organics Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustained Release Coatings Market Strategic Shifts & Innovations
Innovation is centered on developing functional coatings that offer more than simple release delay. The market is shifting toward materials that provide targeted delivery, enhanced stability, and improved patient compliance, driven by advances in polymer science and drug development.
Multi-layered coating systems, which combine soluble, insoluble, and enteric polymers, are gaining traction. Pharmaceutical developers are adopting these complex films to achieve sophisticated pulsatile or zero-order release kinetics for chronic disease medications. This technology is fragmenting the market from monolithic solutions into highly specialized niches based on specific therapeutic release profiles.
The European Union's Medical Device Regulation (MDR) is tightening the requirements for drug-device combination products. This directly impacts items like drug-eluting stents and coated catheters, forcing manufacturers to provide more extensive data on the safety and performance of the sustained-release coating itself. The cardiovascular and orthopedic segments are most affected, now requiring deeper collaboration with polymer suppliers.
A notable behavioral shift is the move from buying raw polymers to sourcing complete, pre-formulated film coating systems. This trend disrupts the traditional component-based supply chain, favoring suppliers who offer an integrated package of materials, colorants, and technical support. This model is most prominent among small to mid-sized pharmaceutical companies in North America that lack deep in-house formulation expertise.
Sustained Release Coatings Market Segmentation
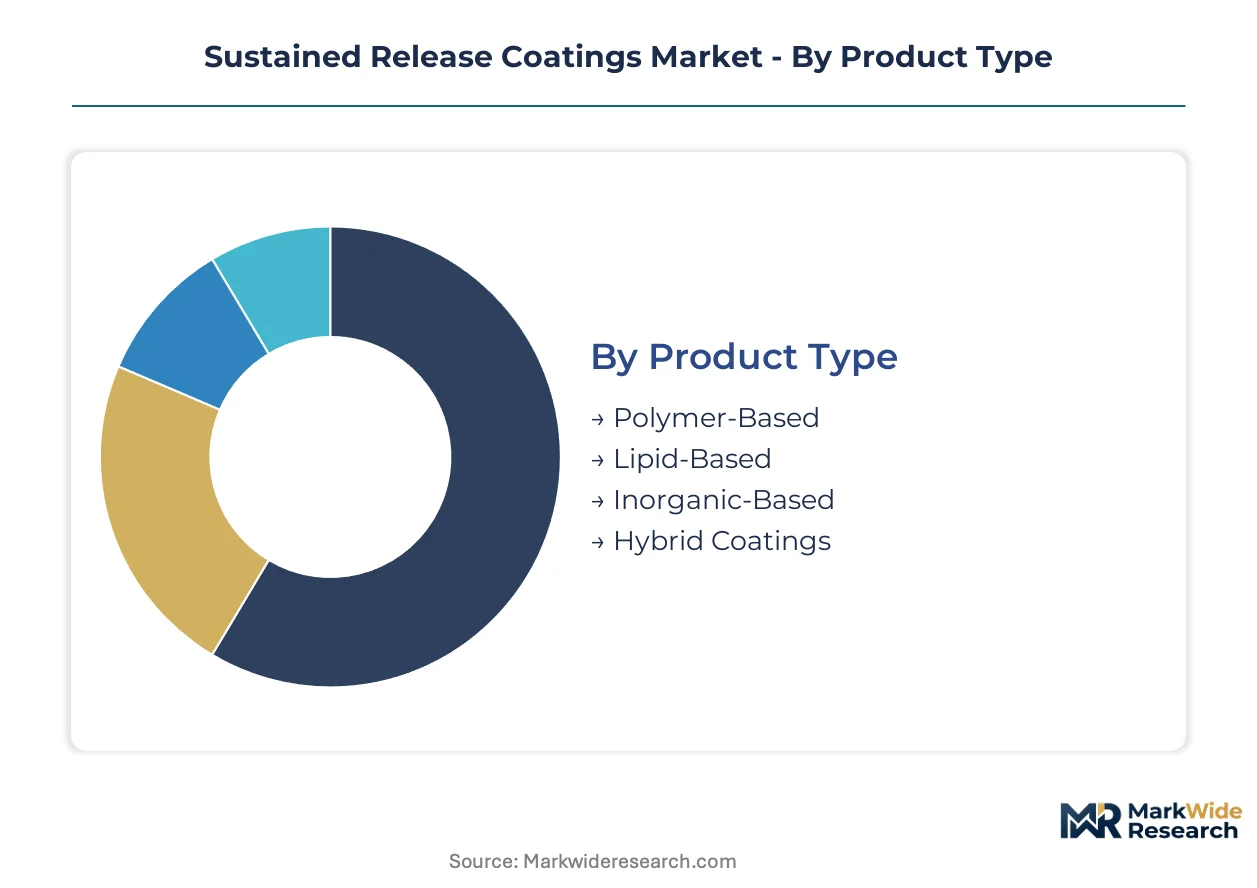
The sustained release coatings market segments across diverse product types, applications, and technologies, each driven by distinct performance requirements. Understanding these segments is crucial for identifying where innovation is concentrating and where market value is being created. Precision in drug delivery and agricultural efficiency underpins the demand across these varied categories.
Product Type:
The product type segmentation reveals how different material compositions serve both established domestic markets and emerging export opportunities in specialized applications.
- Polymer-Based:These coatings, often based on cellulose derivatives or acrylics, control release through diffusion or erosion mechanisms. They dominate the market in volume due to their versatility and cost-effectiveness in both pharmaceutical oral solid dosage forms in the US and controlled-release fertilizers in India.
- Hybrid Coatings:Combining organic and inorganic components, these advanced materials offer enhanced barrier properties and tunable release kinetics. Demand for hybrid systems is concentrating in European pharmaceutical markets for complex drug-device combinations, requiring superior mechanical strength and biocompatibility.
- Lipid-Based:Utilizing waxes, fatty acids, or glycerides, these coatings provide pH-dependent or temperature-sensitive release, primarily for nutraceuticals.
- Inorganic-Based:Coatings using silica or calcium phosphate offer high thermal stability and mechanical strength for specific industrial applications.
Polymer-Based commands the established base. The steepest expansion runs through Hybrid Coatings.
Application:
Application segments are differentiated by their regulatory burden and the resulting margin structures, influencing material selection and process validation costs across various end-use industries.
- Pharmaceutical:Coatings for oral solid dosage forms manage drug dissolution profiles, ensuring precise therapeutic levels for patients. This segment commands the highest margins due to stringent US FDA and European EMA regulatory requirements for excipient safety and dissolution consistency.
- Agricultural Chemicals:Controlled-release coatings on fertilizers and pesticides enhance nutrient uptake and reduce environmental runoff. Brazilian and Indian agricultural sectors are driving demand for these coated products, aiming to improve crop yields and resource efficiency.
- Food Packaging:These coatings extend shelf life and protect sensitive ingredients from moisture or oxygen degradation in various food products.
- Industrial Equipment:Coatings provide corrosion resistance, wear protection, or lubrication for components operating in harsh industrial environments.
The Pharmaceutical segment holds the largest share of value. Agricultural Chemicals are gaining share fastest.
Technology:
Technological approaches to sustained release coatings vary in their maturity and the concentration of specialized expertise required, impacting their adoption rates across different industries.
- Microencapsulation:This technique involves enclosing active ingredients within a small capsule, typically polymers, to control release. It is widely applied in pharmaceutical formulations for taste masking and extended release, with significant adoption by drug manufacturers in North America.
- Spray Drying:A cost-effective and scalable method, spray drying creates fine particles with a coating layer by atomizing a liquid formulation into a hot drying medium. This technology is increasingly used by agrochemical producers in Southeast Asia for large-volume fertilizer coating.
- Layer-by-Layer Assembly:This precise method builds thin, multi-layered films through sequential adsorption of charged polymers, enabling highly customized release profiles.
- Sol-Gel Method:Utilizing a chemical solution that transforms into an inorganic network, this technique creates porous coatings for specialized medical device applications.
Microencapsulation represents a mature technology base. Spray Drying is expanding most quickly due to its scalability.
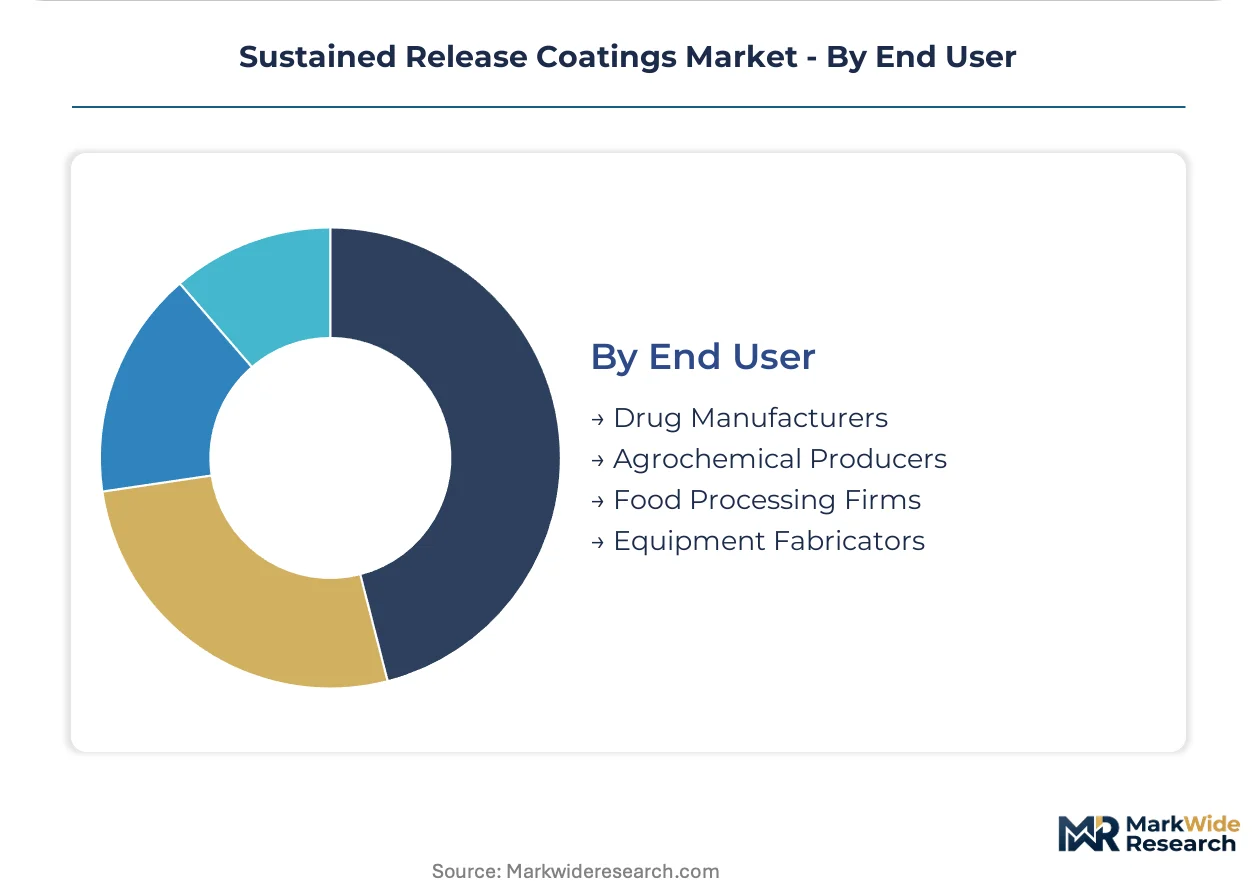
End User:
End-user segments are defined by their specific product development cycles and volume requirements, dictating the types of coating solutions and technical support they demand from suppliers.
- Drug Manufacturers:These companies require highly validated coating systems for pharmaceutical excipients, adhering to strict regulatory guidelines from bodies like the US FDA. Their demand focuses on precise dissolution profiles for chronic disease medications and advanced drug-device combinations.
- Agrochemical Producers:Manufacturers of fertilizers and pesticides utilize coatings to improve product efficacy, reduce application frequency, and minimize environmental impact. Companies in Brazil and India are significant consumers, seeking cost-effective, high-volume coating solutions.
- Food Processing Firms:These firms use coatings for ingredient protection, moisture barrier, and flavor encapsulation in various food and beverage products.
- Equipment Fabricators:Manufacturers of industrial machinery apply coatings for enhanced durability, corrosion resistance, and specific surface functionalities.
Drug Manufacturers drive high-value, low-volume demand. Agrochemical Producers are experiencing significant growth in volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The supply-side concentration for sustained release coatings is evident in regions with advanced pharmaceutical manufacturing and robust agricultural sectors. These areas drive both innovation in polymer science and high-volume demand for controlled-release applications. Regulatory frameworks also heavily influence regional market dynamics.
United States
Drug manufacturers in the United States demand sophisticated polymer coatings for advanced oral solid dosage forms. The US FDA mandates rigorous dissolution profiles and excipient safety, compelling innovation in coating technologies. Pharmaceutical clusters in New Jersey and Massachusetts focus on developing and validating these high-performance materials for new drug formulations.
Germany
Germany's chemical industry provides a strong foundation for sustained release coating development, particularly for pharmaceutical and specialty agrochemical applications. The EMA's stringent excipient safety and dissolution requirements shape product development for European markets. Chemical parks around Ludwigshafen and Leverkusen house research and production facilities for advanced polymer systems.
India
India's agricultural sector requires significant volumes of controlled-release fertilizers and pesticides to improve crop yields. The country's national agricultural policies encourage efficient resource use, boosting demand for coated agrochemicals. Pharmaceutical manufacturing hubs in Hyderabad and Ahmedabad also consume polymer coatings for generic and branded drug formulations.
Brazil
Brazilian agrochemical producers increasingly adopt sustained release coatings to enhance fertilizer efficacy and reduce environmental impact. ANVISA, Brazil's health regulatory agency, also influences pharmaceutical coating requirements for local drug production. Agricultural technology centers in São Paulo and Paraná drive the integration of these materials into modern farming practices.
Sustained Release Coatings Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the sustained release coatings market. The market exhibits a tiered structure, with specialized chemical companies dominating high-value, low-volume pharmaceutical applications. Broader material suppliers serve the more cost-sensitive agrochemical and industrial segments. Strategic partnerships and portfolio diversification are common competitive moves among the larger entities.
Within the specialized chemical segment, BASF SE, a German-based chemical giant, leverages its extensive polymer science portfolio across pharmaceutical and agricultural clients. Evonik, another German-headquartered company, exemplifies a focus on advanced methacrylic acid copolymers for enteric and sustained-release functionalities. Colorcon, an integrated film coating systems provider, occupies a strong position in on-dosage finishing solutions.
| Leading Market Players |
|---|
| BASF SE |
| Evonik |
| Colorcon |
| Coating Place, Inc. |
| Ashland Inc. |
| JRS PHARMA |
| Eastman Chemical Co. |
| Spraycel Coatings |
| Panchsheel Organics Ltd. |
| Others |
Cost & Logistics Intelligence
Contract-based long-term offtake agreements for specialized polymer coatings lock in supply access for pharmaceutical manufacturers and provide price visibility for suppliers. This structure mitigates raw material volatility for critical excipients, fostering stability across the value chain.
Pricing Analysis
US FDA and Europe's EMA regulations dictate the pricing tier structure for pharmaceutical-grade coatings, commanding premium prices due to stringent validation and performance requirements. Value-based pricing models dominate high-performance applications, where precise dissolution profiles are critical. Price differentiation stems from certification level and the degree of customization required for specific drug formulations. Pricing pressure stems from raw material volatility, particularly for commodity-grade polymers used in agrochemicals. Agrochemical producers are highly price-sensitive, while drug manufacturers exhibit lower sensitivity for excipients directly impacting drug efficacy and safety.
Supply Chain Analysis
Germany and the United States anchor advanced polymer formulation and specialized coating production, leveraging strong chemical industries and pharmaceutical R&D. Key raw material dependencies include methacrylic acid and ethyl acrylate, whose supply is susceptible to petrochemical market fluctuations. This commodity price volatility represents a significant structural supply chain risk for coating manufacturers. Distribution runs through direct sales channels for large pharmaceutical and agrochemical clients, with specialized distributors serving smaller formulators and regional markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
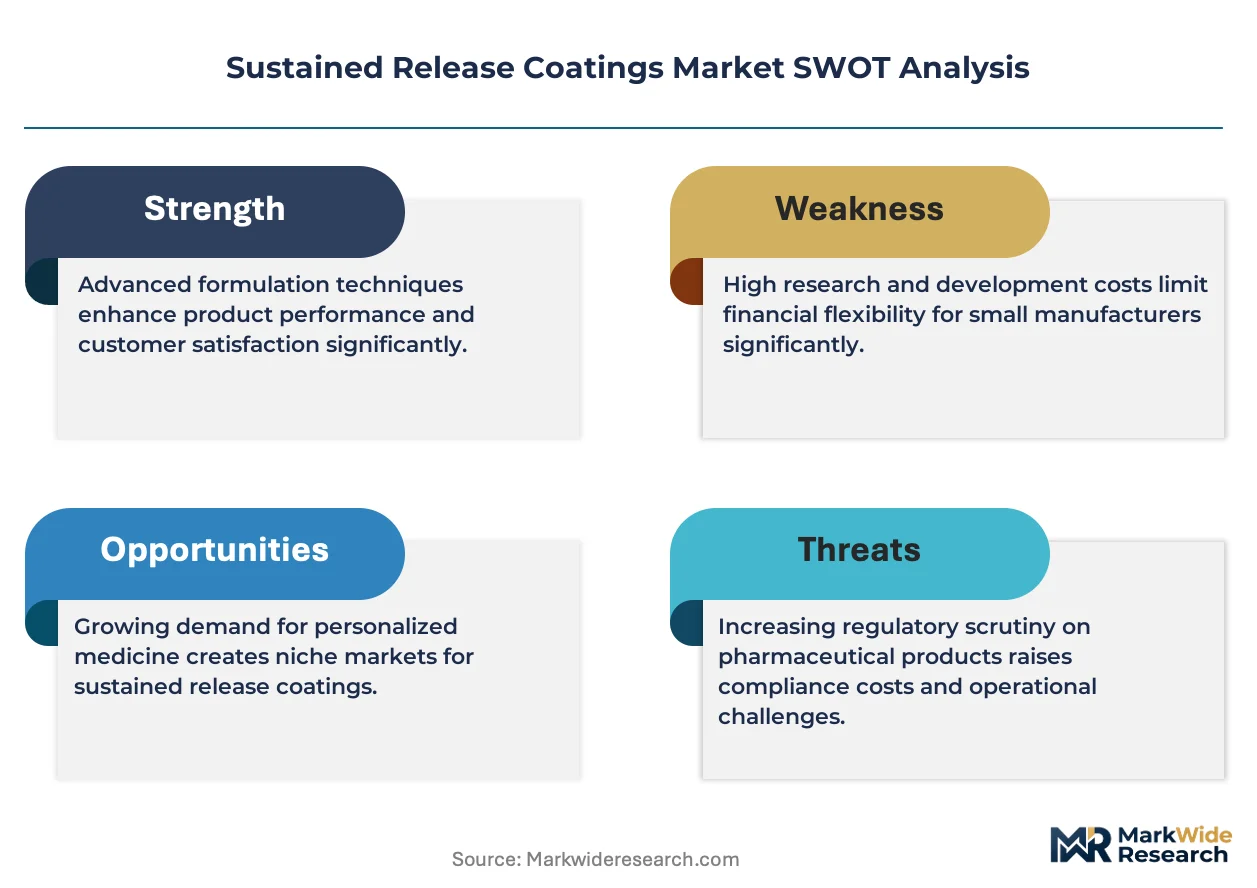
This market presents a substitution defense challenge, as incumbents must navigate the threat posed by alternative drug delivery systems and non-polymer-based solutions.
For Market Incumbents: Shield core pharmaceutical coating revenues by investing heavily in R&D for smart responsive coatings and advanced multi-layered systems. Strategic partnerships with drug developers can secure early integration of novel excipients into new drug formulations, mitigating the threat from non-polymer drug delivery. Investment in regulatory validation for next-generation excipients through US FDA and EMA pathways is a critical lever for market defense.
For New Entrants and Emerging Players: Lead with specialized, cost-effective solutions for high-volume applications in less-regulated segments. Nutraceuticals offer a penetrable white-space target, leveraging controlled-release coatings for sensitive ingredients. Southeast Asian agrochemical markets also present an opportunity for scalable spray-drying technologies. A focused go-to-market angle emphasizing rapid formulation support and localized production capabilities can differentiate new players.
For Investors and Strategic Acquirers: Niche polymer science companies with proprietary dissolution technologies represent attractive acquisition targets. The market demonstrates strong long-term viability, driven by persistent demand for precise drug delivery and agricultural efficiency over the next 5-10 years. Increased US FDA and EMA approvals for novel polymer excipients will serve as a key signal to watch for accelerated market growth and M&A activity.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in India | Increases localized supply for high-volume agrochemical and generic pharmaceutical markets in Asia. |
| Regulatory Approval Pathway Investment | Accelerates market access for novel polymer excipients under strict US FDA and EMA guidelines. |
| Strategic Partnership with Drug Developers | Ensures early integration of advanced coatings into pharmaceutical R&D pipelines for new therapies. |
| Green Manufacturing Transition | Addresses environmental concerns and aligns with sustainability mandates from European regulators. |
| Product Launch: Smart Responsive Coatings | Captures premium pricing and opens new therapeutic applications for targeted drug delivery systems. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and extensive secondary research anchors the qualitative findings of this study. This approach involved conversations with drug development executives, agrochemical R&D managers, polymer scientists, and regulatory affairs specialists. Secondary data sources included US FDA filings, EMA submissions, industry association reports, and patent databases, enabling robust bottom-up and top-down triangulation.
Sensitivity analysis underpins the forecast framework, modeling various scenarios for market evolution across the analysis window. The quantitative model captures segmentation across product type, application, technology, end user, and regional regulatory clusters. Compound annual growth rates were derived through regression analysis and market trend extrapolation. Key industry-specific forecast inputs include pharmaceutical R&D pipelines and agricultural yield targets in major consumption regions.
The analysis sits within stated boundaries; outcomes outside unforeseen regulatory changes or significant raw material price shocks would require recalibration. Forecasts reflect assumptions regarding technological adoption and market dynamics. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Electronic Protection Device (EPD) Coatings Market
Coatings
Global Solar Panel Coatings Market
Coatings
Architectural Metal Coatings Market
Coatings
Liquid-Applied Roof Coating Market
Coatings
North America Polyimide Coating Market
Coatings
Process Pipe Coating Market
Coatings
Electrical Appliance Coatings Market
Coatings
Tablet Coatings Market
Coatings
North America Anti-Friction Coatings Market
Coatings
Canada Protective Coatings Market
Coatings
2K Coatings Market
Coatings
Egypt Automotive OEM Coatings Market
Coatings
Asia-Pacific Floor Coatings Market
Coatings
Global Polytetrafluoroethylene (PTFE) Coatings Market
Coatings
Global Fluorine Carbon Coatings Market
Coatings
Transportation Coating Market