
 Field Peas Market | 2026-2036
Field Peas Market Size, Share, and Industry Trends Forecast 2026-2036
Field Peas Market Foresight
Contract farming and asset-light processing leases are narrowing the capital barrier for new entrants in field pea value chains. Bunge Limited leverages its global grain handling infrastructure to secure origination volumes across multiple growing regions. Roquette Frères sustains its position through specialized pea protein extraction capabilities that serve food ingredient buyers. AGT Foods anchors its competitiveness with integrated processing from farm gate to ingredient manufacturing.
Field peas are cool-season legumes containing approximately 20-25% protein by dry weight, cultivated primarily for human consumption, animal nutrition, and fractionation into protein isolates and starches. Yellow peas dominate ingredient processing due to higher starch content and neutral flavor profiles suited to plant-based meat analogues. Snack foods represent the fastest-growing end use as extruded pea-based products displace conventional potato and corn formulations. Organic peas command premium positioning through certified supply chains that restrict synthetic inputs and maintain identity preservation from field to package.
The USDA enforces grading standards for split and whole peas that determine export eligibility and price premiums in international trade. Health Canada and the FDA both regulate pea protein labeling claims, creating compliance complexity for cross-border ingredient suppliers. The EU Green Deal's Farm to Fork strategy imposes pesticide reduction targets that favor legume rotations including field peas. Stakeholders must monitor evolving protein content thresholds in import specifications and assess whether regional processing investments align with shifting end-user certification requirements.
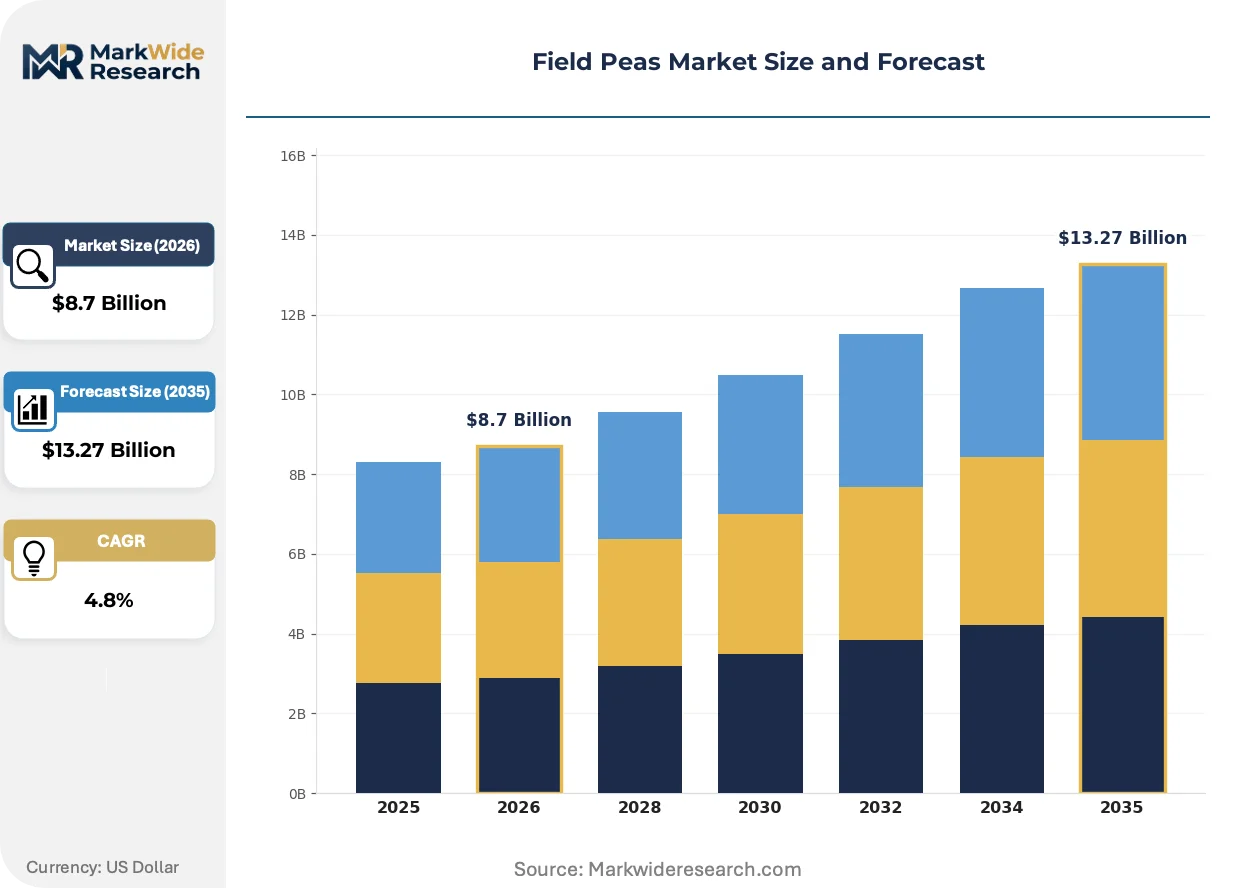
Market Dynamics
The EU Green Deal's Farm to Fork strategy is mandating pesticide reduction targets that favor legume rotations including field peas, while plant-based protein adoption in food manufacturing accelerates fractionation demand for yellow pea isolates.
Growth Catalysts
- EU Green Deal mandates:The Farm to Fork strategy imposes pesticide reduction targets that favor legume rotations including field peas, expanding cultivated acreage across member states.
- Plant-based meat analogue demand:Food manufacturers require yellow pea protein isolates for texture and binding properties in burger and sausage formulations.
- Canada-France-Australia concentration:These three countries anchor processing infrastructure and origination volumes, creating scale economies for export supply chains.
Market Restraints
- Input cost volatility:Natural gas prices directly impact nitrogen fertilizer costs for non-legume competitors, creating price instability in grain markets that affects field pea contract pricing.
- Supply concentration risk:Prairie provinces in Canada dominate exportable surplus, leaving trade flows vulnerable to regional weather shocks and rail logistics disruptions.
- Regulatory friction:Health Canada and FDA maintain divergent protein content labeling thresholds, forcing ingredient suppliers to maintain dual compliance systems for cross-border trade.
Strategic Opportunities
- Organic certification expansion:Identity-preserved organic supply chains command premium positioning through certified production that restricts synthetic inputs from field to package.
- Extruded snack application growth:Pea-based puffed and extruded products displace conventional potato and corn formulations in health-positioned snack categories.
- Fractionation technology convergence:Wet milling and air classification advances enable simultaneous protein isolate and native starch recovery, improving unit economics for processing investments.
Industry Challenges
- Protein content standardization:USDA grading standards for split and whole peas create export eligibility complexity when import specifications evolve in Asian and European destination markets.
- Processing capex intensity:Specialized pea protein extraction facilities require substantial capital for wet fractionation lines and spray drying capacity, limiting new entrant participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Field Peas Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Peas, Yellow Peas, Organic Peas, Split Peas End Use: Food Products, Animal Feed, Flour Production, Snack Foods Packaging Type: Bags, Bulk Containers, Pouches, Pallets Distribution Channel: Supermarkets, Online Retailers, Wholesalers, Direct Sales |
| Companies Covered | Bunge Limited, Roquette Frères, AGT Foods, Louis Dreyfus Company, The Scoular Company, Pioneer Hi-Bred International, Field Peas Co., Puris, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Field Peas Market Shifts & Advancements
Digital traceability platforms and precision fermentation alternatives are reshaping how field pea supply chains demonstrate provenance and compete for ingredient buyer preference.
Dry fractionation technology paired with air classification systems is virtualizing traditional wet milling infrastructure for mid-scale processors. Regional ingredient suppliers in France and Canada adopt these systems to serve craft meat analogue producers without capital-intensive spray drying investments. This technology compression is enabling distributed processing models that reduce freight costs for identity-preserved organic volumes.
The EU Green Deal's CSRD disclosure requirements now mandate supply chain emissions reporting for agricultural inputs entering European food manufacturing. Field pea rotations deliver nitrogen fixation credits that reduce Scope 3 liability for processed food companies. Ingredient buyers in Germany and the Netherlands increasingly specify legume sourcing to meet documented carbon intensity targets in corporate sustainability filings.
Contract farming structures are displacing spot market procurement for premium-grade yellow peas intended for protein fractionation. Large food ingredient buyers in North America and Europe now originate three to five year supply agreements directly with grower cooperatives, bypassing traditional grain merchant channels. This procurement consolidation concentrates origination relationships with processors possessing integrated farm gate handling infrastructure.
Field Peas Market Segmentation
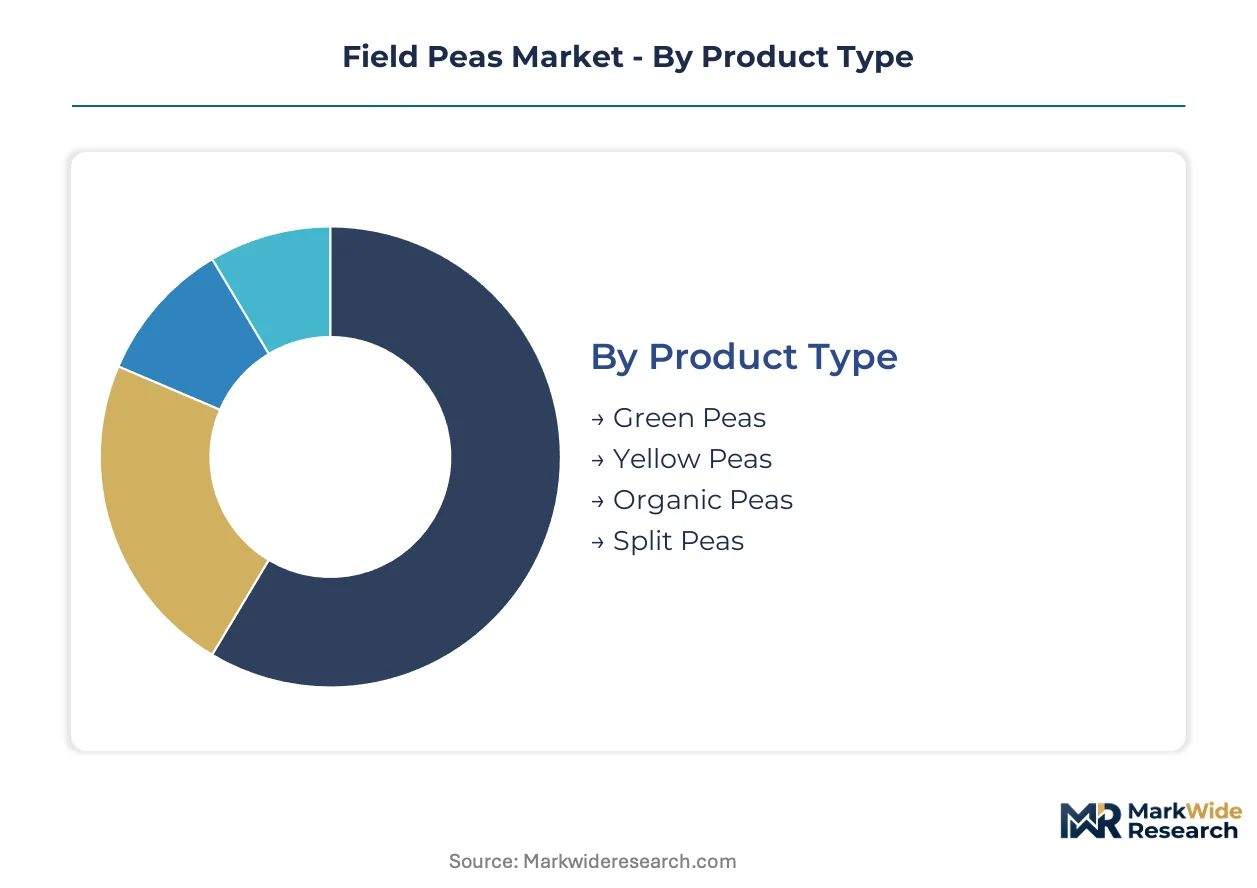
Field pea processors and ingredient buyers segment supply chains to align protein content specifications with fractionation economics and end-use certification requirements. Distinct handling protocols for yellow versus green varieties, combined with identity-preserved organic flows, create parallel channel structures that command divergent margin profiles.
Product Type:
Use-case spectrum spans commodity grain trading, premium ingredient fractionation, and certified organic food manufacturing, each demanding discrete protein content thresholds and handling protocols.
- Yellow Peas:Higher starch content and neutral flavor profiles suit wet milling operations producing protein isolates for plant-based meat analogues. Canada and France concentrate fractionation infrastructure serving North American and European food ingredient buyers. The segment anchors volume demand through long-term supply agreements with meat alternative manufacturers.
- Green Peas:Distinctive color and firmer texture retain premium positioning in whole and split pea applications for direct human consumption. Traditional Mediterranean and Middle Eastern markets sustain import demand for canning and dry packaging applications, with Australian exporters capturing consistent origination volumes.
- Organic Peas:Certified production restricts synthetic inputs and maintains identity preservation from field to package, commanding price premiums through documented provenance.
- Split Peas:USDA grading standards determine export eligibility for processed halves used in soup manufacturing and ethnic cuisine formulations.
The dominant share belongs to Yellow Peas, while Organic Peas is closing the gap fastest.
End Use:
Customer type stratification separates commodity animal nutrition buyers from premium food ingredient procurement teams with divergent protein content specifications and certification requirements.
- Food Products:Human consumption spans whole pea retail packs, canned vegetables, and protein-fortified formulations. European and North American manufacturers source yellow pea isolates through direct grower contracts bypassing traditional grain merchants.
- Snack Foods:Extruded and puffed pea-based products displace conventional potato and corn formulations in health-positioned retail categories. Air classification advances enable mid-scale processors to serve craft producers without capital-intensive spray drying infrastructure.
- Animal Feed:Compound feed manufacturers incorporate field peas as protein and energy sources in poultry and swine rations, with pricing indexed to competing soybean meal values.
- Flour Production:Milled pea fractions enter gluten-free baking applications and protein-enriched pasta formulations targeting specialty diet consumers.
Food Products retains the largest volume position, though Snack Foods exhibits the steepest expansion trajectory as extrusion technology democratizes.
Packaging Type:
Supply concentration in Prairie Canada and Australian grain belts dictates bulk handling economics for export flows versus retail-ready packaging for destination market distribution.
- Bulk Containers:Ocean freight optimization for containerized grain shipments from Vancouver and Melbourne terminals to Asian and European processors.
- Bags:Standard 25-50kg woven polypropylene units for wholesale distribution to food manufacturers and institutional buyers.
- Pallets:Unitized loads for efficient handling in automated grain elevator and port terminal operations.
- Pouches:Consumer-facing retail formats for organic and specialty varieties requiring shelf-ready presentation.
Bulk Containers dominate export volume, while Pouches expand most quickly in premium organic channels.
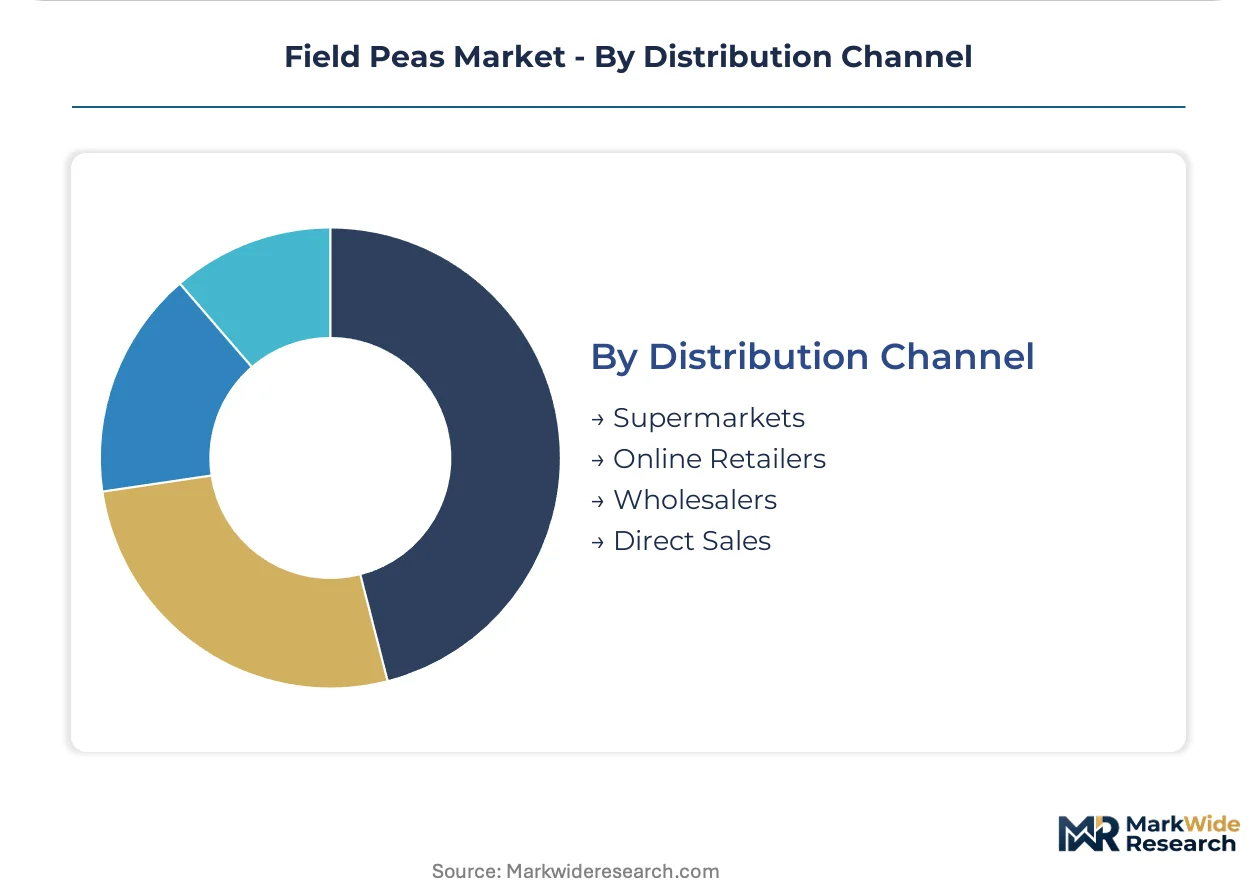
Distribution Channel:
Procurement consolidation among large food ingredient buyers is shortening channel structures and displacing traditional grain merchant intermediation.
- Direct Sales:Three to five year supply agreements between processors and grower cooperatives concentrate origination relationships with integrated farm gate handling infrastructure. Bunge Limited and AGT Foods leverage captive elevation networks to secure premium yellow pea volumes.
- Wholesalers:Regional grain merchants aggregate spot market volumes for commodity-grade whole and split peas serving smaller food manufacturers.
- Supermarkets:Retail chains source packaged whole and split peas through private label and branded supplier programs.
- Online Retailers:E-commerce platforms expand reach for organic and specialty varieties targeting direct-to-consumer subscription models.
Direct Sales commands the dominant procurement volume, with Online Retailers gaining share fastest in organic identity-preserved segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Exportable surplus concentrates in three origin zones, creating asymmetric trade flows where Prairie Canada, southeastern Australia, and northern France supply protein fractionation demand across North America, Europe, and Asia.
Canada
Prairie provinces generate the dominant exportable surplus for yellow pea protein isolates. Health Canada regulates protein content labeling thresholds that diverge from FDA standards, forcing dual compliance systems for cross-border ingredient suppliers. Port terminals at Vancouver anchor containerized shipments to Asian processors.
France
Roquette Frères sustains specialized extraction capabilities serving European food ingredient buyers. The EU Green Deal's Farm to Fork strategy mandates pesticide reduction targets that expand field pea acreage in crop rotations. Processing clusters in Hauts-de-France concentrate wet fractionation infrastructure for meat analogue manufacturers.
Australia
Southeastern grain belts supply consistent origination volumes for Middle Eastern and Asian canning markets. The TGA regulates food ingredient claims that affect export documentation requirements. Melbourne terminals optimize ocean freight for containerized shipments to destination processors.
United States
North Dakota and Montana field pea production serves domestic fractionation demand and Canadian transit flows. The USDA enforces grading standards for split and whole peas that determine export eligibility. Pacific Northwest rail corridors handle Prairie Canadian volumes destined for Asian export.
Field Peas Market Competitive Landscape
On the supply side, the industry is consolidating around integrated processors with captive elevation networks and specialized extraction capabilities. Three strategic archetypes dominate: global grain merchants with origination infrastructure, specialized pea protein extractors with fractionation technology, and integrated farm-to-ingredient processors. Competitive moves concentrate on long-term supply agreements with grower cooperatives and wet milling capacity expansion.
Among integrated processors, Bunge Limited, Roquette Frères, and AGT Foods exemplify the three dominant competitive positions. Bunge Limited represents the global grain merchant archetype with origination infrastructure spanning multiple growing regions. Roquette Frères occupies the specialized extraction tier with dedicated pea protein isolate capabilities. AGT Foods anchors the integrated farm-to-ingredient model with processing from field gate through finished ingredient manufacturing.
| Leading Market Players |
|---|
| Bunge Limited |
| Roquette Frères |
| AGT Foods |
| Louis Dreyfus Company |
| The Scoular Company |
| Pioneer Hi-Bred International |
| Field Peas Co. |
| Puris |
| Cargill |
| Others |
Supply & Pricing Matrix
Prairie provinces in Canada concentrate fractionation capacity for yellow pea protein isolates, and their elevation infrastructure dominance translates directly into origination pricing power over North American and Asian buyers. Wet milling economics hinge on securing premium-grade volumes through long-term contracts rather than spot market exposure.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock in three to five year supply agreements with grower cooperatives. Price differentiation separates certified organic identity-preserved flows from commodity-grade whole peas, with EU Green Deal carbon intensity documentation commanding additional premiums. Pricing pressure stems from natural gas volatility affecting nitrogen fertilizer costs for competing grains, compressing margins in non-legume alternatives. Commodity animal feed manufacturers exhibit highest price sensitivity, while meat analogue ingredient buyers prioritize protein content consistency over unit cost.
Supply Chain Analysis
Rail logistics disruptions between Prairie Canada and Vancouver port terminals dominate supply chain risk assessments for Asian export flows. Geographic supply concentration centers on Canada, France, and Australia, with each anchoring distinct processing specializations. Raw material dependencies include nitrogen fixation inputs, specialized wet fractionation chemicals, and spray drying energy feeds. Distribution runs through containerized ocean freight from Vancouver and Melbourne terminals to destination processors, with identity-preserved organic volumes requiring segregated handling infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
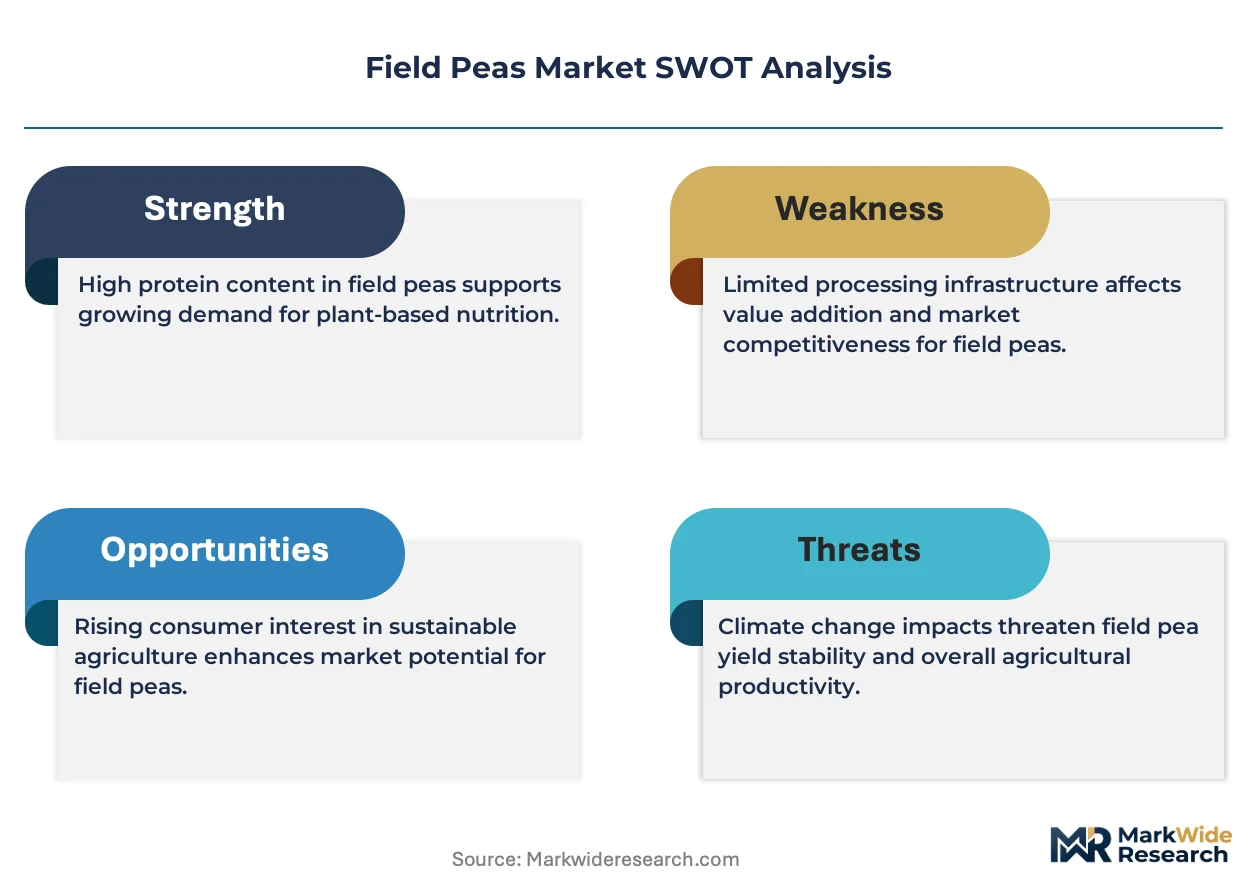
This market functions as a defensive-moat story where regulatory entrenchment through EU Green Deal Farm to Fork mandates creates durable rotation requirements favoring field pea cultivation.
For Market Incumbents: Entrench origination relationships through captive elevation networks in Prairie Canada and Hauts-de-France processing clusters. Secure three to five year supply agreements directly with grower cooperatives to preempt precision fermentation substitutes threatening protein isolate demand. Invest in wet fractionation capacity expansion ahead of CSRD disclosure requirements tightening Scope 3 liability calculations. For New Entrants and Emerging Players: Build out dry fractionation and air classification capabilities to serve craft meat analogue producers without capital-intensive spray drying infrastructure. Target organic certification expansion in southeastern Australian grain belts where identity-preserved supply chains remain underdeveloped. Pursue direct-to-processor sales models bypassing traditional grain merchant intermediation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated farm-to-ingredient processors with backward control over farm gate handling. Long-term viability rests on processors demonstrating nitrogen fixation credits that reduce corporate Scope 3 emissions liability. Acquisition targets should exhibit captive elevation infrastructure and fractionation technology convergence capabilities. Monitor EU pesticide reduction target acceleration as inflection indicator for legume rotation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Three to five year contracts with grower cooperatives bypass traditional grain merchant channels and secure premium yellow pea volumes. |
| Backward Integration | Captive elevation networks in Prairie Canada and Hauts-de-France reduce origination cost volatility and improve margin capture. |
| Green Certification Program | EU Green Deal CSRD compliance documentation enables nitrogen fixation credit claims that reduce Scope 3 liability for food manufacturers. |
| Capacity Expansion | Wet fractionation line additions in Roquette Frères processing clusters serve accelerating meat analogue ingredient demand. |
| Joint Venture | Regional partnerships between Canadian processors and Asian food manufacturers secure containerized export flows through Vancouver terminals. |
Research Methodology
Cross-validation between grower cooperative procurement officers and food ingredient buyer technical specifications anchors the qualitative findings. Primary interviews with fractionation plant managers, grain elevator operators, regulatory affairs leads at Health Canada and FDA, and sustainability officers at European food manufacturers combined with secondary validation from USDA grading standards documentation, EU Green Deal Farm to Fork strategy filings, and customs trade data. Bottom-up volume estimates from provincial agricultural statistics and top-down demand modeling from meat analogue manufacturer procurement disclosures were triangulated.
Calibration against historical acreage shifts and processing capacity utilization rates informed the analytical framework across the analysis window. Segmentation dimensions modeled include pea variety, end-use application, certification tier, and regional production cluster. CAGRs were derived from elasticity-adjusted demand projections incorporating protein content specification evolution and fractionation technology adoption curves. Industry-specific forecast inputs include EU pesticide reduction target implementation timelines and plant-based meat analogue formulation substitution rates.
Practitioners should monitor regulatory threshold revisions for protein content labeling and carbon intensity documentation requirements for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Acorn Squash Market
Vegetables
Butternut Squash Market
Vegetables
Potato Market
Vegetables
Turkey Greenhouse Horticulture Market
Vegetables
Cabbages and Other Brassicas Market
Vegetables
Canada Microgreens Market
Vegetables
Netherlands Greenhouse Horticulture Market
Vegetables
South America Peas Market
Vegetables
Dried Vegetable Market
Vegetables
Australia Greenhouse Horticulture Market
Vegetables
Carrots and Turnips Market
Vegetables
Spain Avocado Market
Vegetables
Vegetable Chutney Market
Vegetables
Microgreens Market
Vegetables
Europe Flowers and Ornamental Plants Market
Vegetables
Global Mushroom Market