
 Tanzania Fruit and Vegetables Market | 2026-2036
Tanzania Fruit and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Tanzania Fruit and Vegetables Market Outlook
Tanzania's Southern Highlands expansion in Mbeya and Iringa is reconfiguring national supply patterns for temperate-climate vegetables. Eden Fresh Produce leverages contract farming networks across the highlands to secure year-round tomato and capsicum volumes. Agro Fresh Tanzania anchors its operations in Arusha, controlling post-harvest handling infrastructure for export-oriented French beans and snow peas. Mbeya Fresh Ltd. competes through specialized cold-chain logistics that extend shelf life for domestic supermarket clients.
Tanzania fruit and vegetables encompass fresh and minimally processed edible plant products cultivated across tropical lowland and highland agro-ecological zones, with harvest-to-market cycles ranging from 45 days for leafy greens to 18 months for tree crops like avocado and mango. These products serve domestic food security, export revenue generation, and raw material supply for juice, canning, and snack processing industries. Citrus and stone fruits capture premium export margins through EU-compliant phytosanitary certification, while root vegetables dominate volume throughput for domestic wholesale channels. Retailers and restaurants represent the fastest-growing end-user category as urbanization shifts consumption toward standardized, traceable produce sourcing.
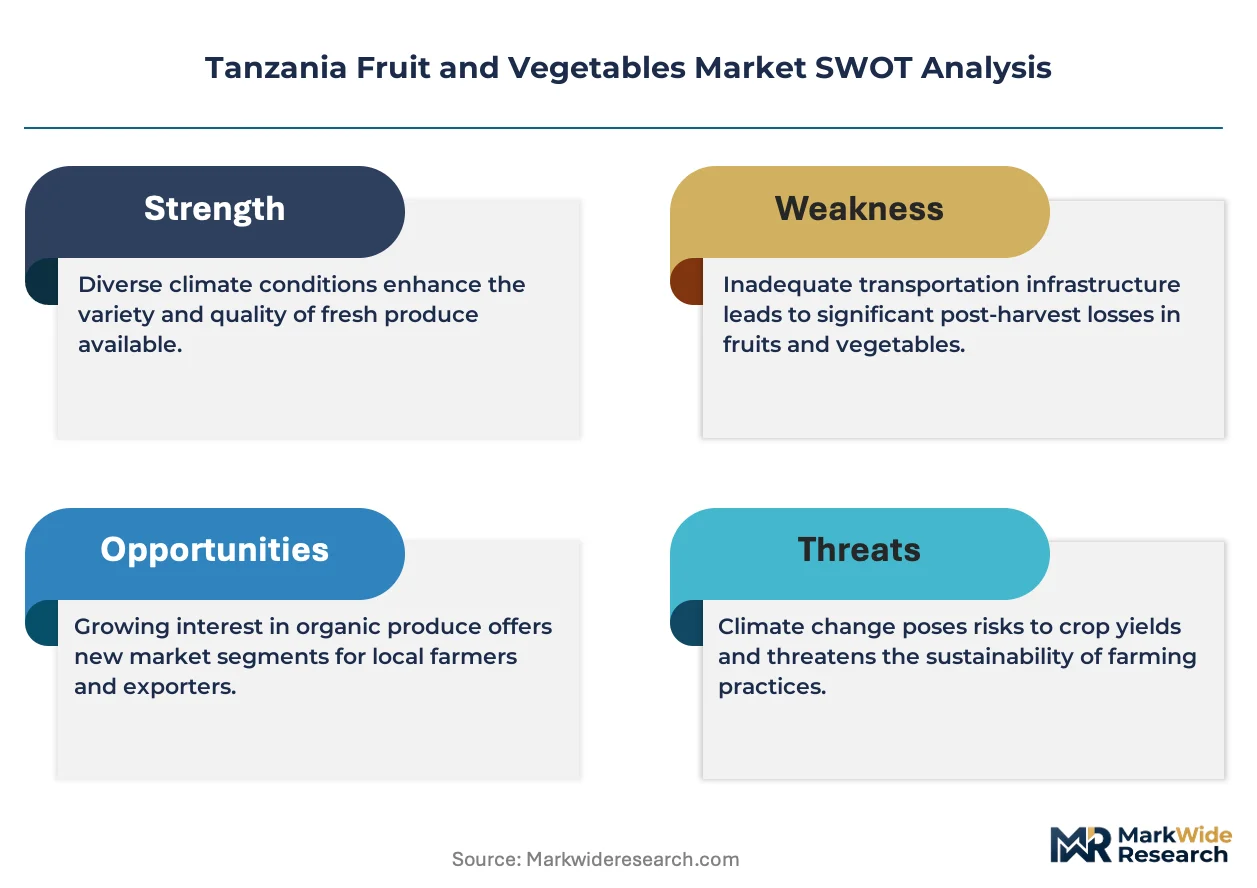
Tanzania's Plant Protection Act, enforced by the Tanzania Plant Health and Pesticides Authority, mandates residue testing and traceability documentation for all export-bound horticultural shipments. The Tanzania Bureau of Standards certifies packaging materials and grading protocols under national quality codes that align with EAC harmonized standards. Stakeholders must monitor evolving EU deforestation regulation compliance requirements and invest in digital traceability platforms to maintain market access for high-value export segments.
Market Dynamics
Urban supermarket expansion in Dar es Salaam and Arusha is compressing traditional wholesale channels, forcing upstream cold-chain investments and traceability compliance across smallholder supply networks.
Growth Catalysts
- EU Deforestation Regulation:Mandatory geolocation traceability for export-bound avocado and mango shipments is accelerating digital farm-mapping adoption across Kilimanjaro cooperatives.
- Contract farming consolidation:Year-round volume guarantees from highland tomato and capsicum growers are securing processor raw material pipelines.
- Dubai and Riyadh import demand:Middle Eastern retail chains are sourcing French beans and snow peas through Arusha-based cold-chain handlers, expanding premium export windows.
Market Restraints
- Diesel price volatility:Refrigerated transport operators face margin compression from fuel cost swings affecting Mbeya-to-Dar es Salaam logistics.
- Phytosanitary certification backlog:Tanzania Plant Health and Pesticides Authority inspection queues create 10-14 day export delays during peak harvest windows.
- Synthetic pesticide residue thresholds:EU Maximum Residue Limit compliance failures block container loads, forcing costly diversion to domestic wholesale channels.
Strategic Opportunities
- Iringa temperate vegetable zone:Underdeveloped capsicum and carrot acreage offers first-mover contract farming arrangements for supermarket supply chains.
- Blockchain-IoT convergence:Real-time temperature and location logging is opening premium pricing tiers for traceability-verified export consignments.
- Domestic e-grocery channels:Dar es Salaam mobile-commerce platforms are creating direct farm-to-consumer bypass routes for leafy greens and herbs.
Industry Challenges
- Cold-chain technician scarcity:Refrigeration equipment maintenance and reefer container handling skills lag behind infrastructure deployment in Southern Highlands.
- Phytosanitary laboratory capacity:Residue testing bottleneck at Tanzania Bureau of Standards facilities extends certification timelines beyond perishable shelf-life windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tanzania Fruit and Vegetables Market |
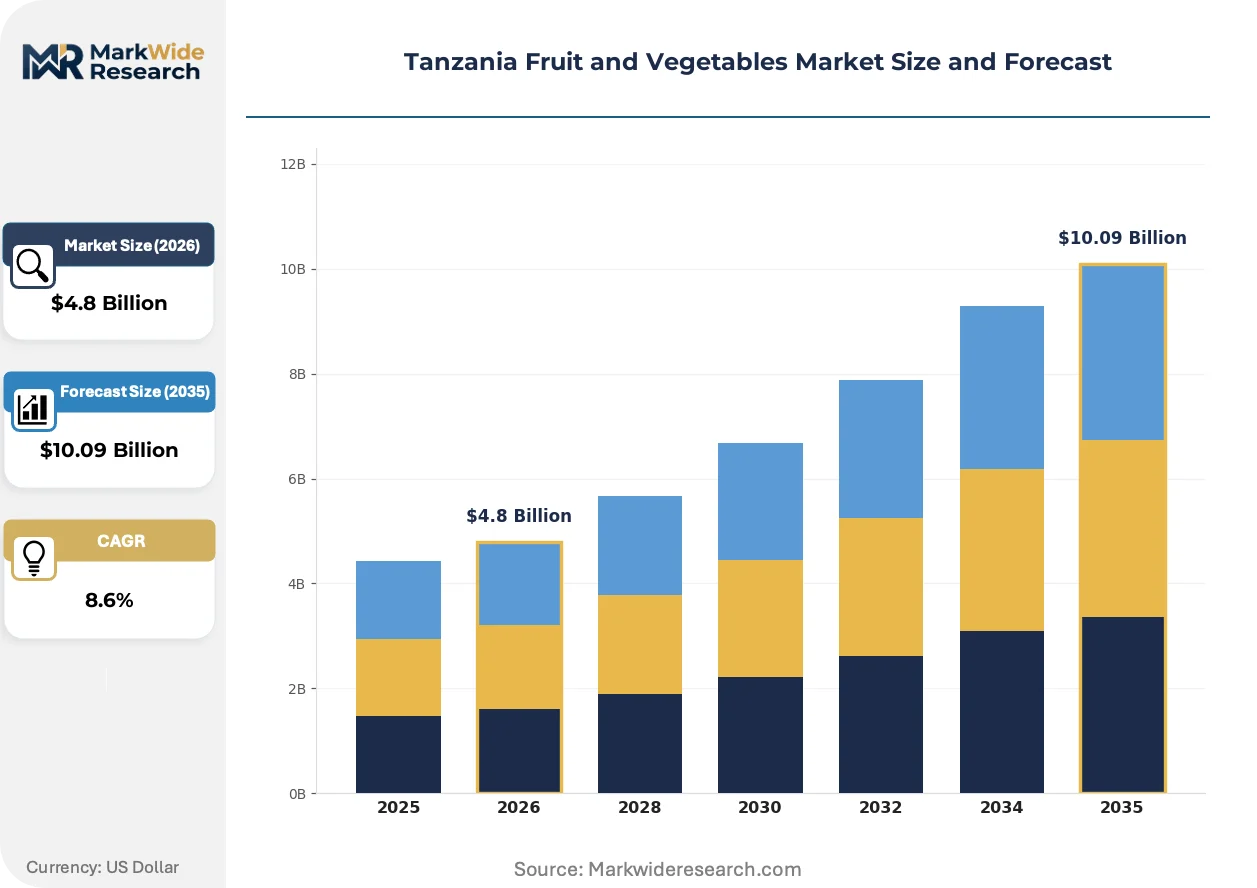
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citrus, Leafy Greens, Root Vegetables, Stone Fruits End User: Retailers, Food Processing, Exporters, Restaurants Sales Channel: Supermarkets, Farmers' Markets, Wholesale Distributors, Online Stores Packaging Type: Cartons, Baskets, Plastic Bags, Bulk Containers |
| Companies Covered | Tanzania Horticultural Association (TAHA), Eden Fresh Produce, Agro Fresh Tanzania, Mbeya Fresh Ltd., Sustainably Grown Tanzania, East Africa Foods, Darsh Industries Ltd., TAHA Fresh, Produce Tanzania, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tanzania Fruit and Vegetables Market Strategic Shifts
Digital traceability platforms and renewable-powered cold storage are compressing post-harvest loss rates while regulatory compliance costs reshape competitive positioning across export-oriented cooperatives.
Blockchain-enabled farm-to-retail tracking is digitizing custody documentation for avocado and French bean consignments bound for EU and Middle Eastern buyers. Kilimanjaro and Arusha cooperatives are deploying smartphone-based geotagging to satisfy EUDR geolocation mandates. This infrastructure investment is digitizing compliance workflows that previously relied on paper-based chain-of-custody records, compressing audit preparation cycles from weeks to days.
Tanzania's Plant Protection Act enforcement is tightening residue surveillance protocols through expanded Tanzania Plant Health and Pesticides Authority field inspection units. Export-oriented growers face mandatory pre-shipment testing for EU-regulated active ingredients. Smallholder cooperatives in the Kilimanjaro-Arusha corridor are responding by converting to Integrated Pest Management protocols and restricted pesticide lists to avoid container rejection at Rotterdam and Hamburg ports.
Supermarket procurement consolidation is displacing open-air market intermediaries for standardized produce categories. Dar es Salaam retail chains are imposing size-grading and packaging specifications previously absent in domestic trade. This specification creep is most visible in tomato and capsicum categories, where contract farming arrangements now dominate volume planning for urban retail distribution.
Tanzania Fruit and Vegetables Market Segmentation
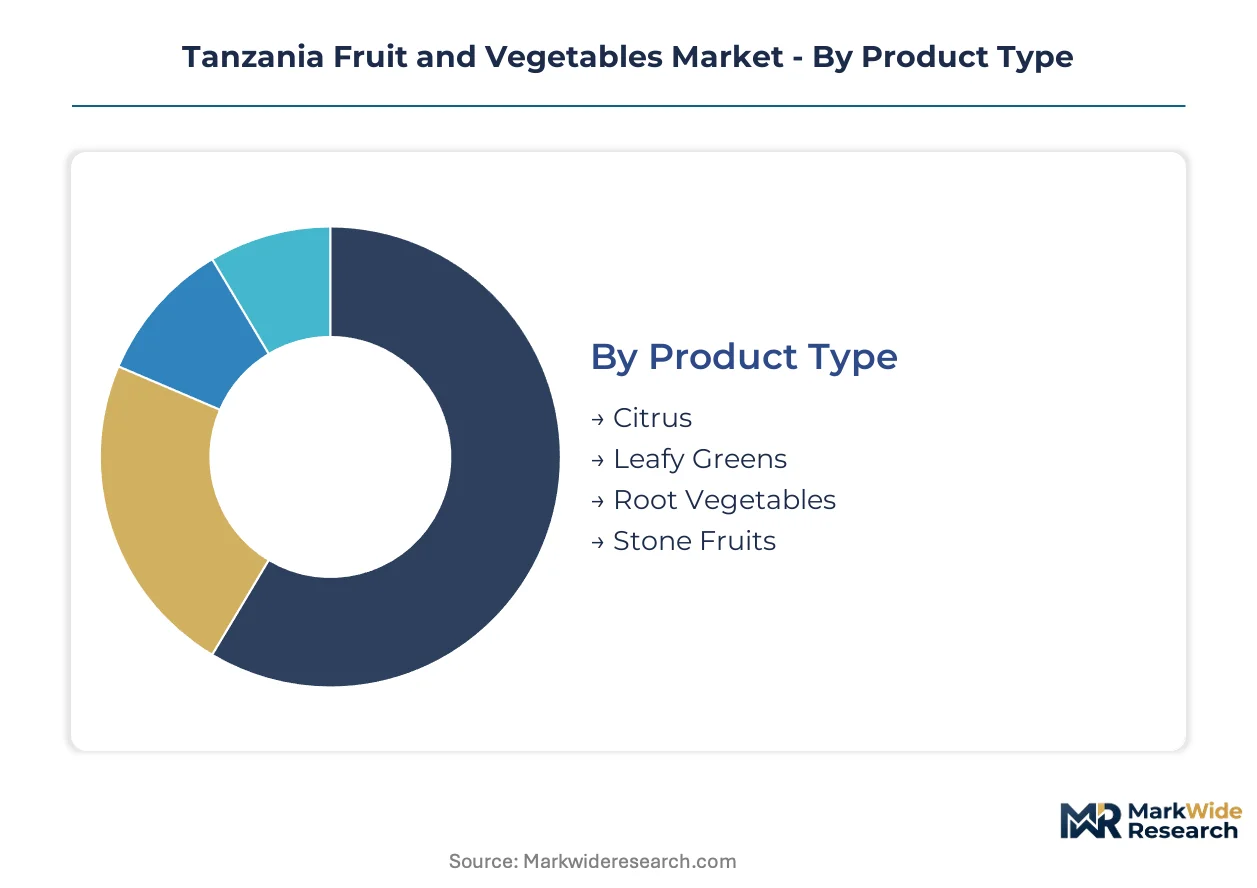
Segmentation in Tanzania's fruit and vegetables market reveals how supply chain configuration and buyer specifications diverge across domestic consumption versus export-oriented production. Each dimension—product type, end user, sales channel, and packaging—carries distinct compliance burdens and margin structures that reshape competitive positioning.
Product Type:
Mature export categories dominate revenue concentration while emerging segments respond to shifting urban dietary patterns and cold-chain infrastructure expansion.
- Stone Fruits:Avocado and mango shipments command premium pricing through EU-compliant phytosanitary certification under Tanzania Plant Health and Pesticides Authority protocols. Kilimanjaro cooperatives concentrate supply for Rotterdam and Hamburg-bound consignments, though residue testing bottlenecks at Tanzania Bureau of Standards facilities create certification delays.
- Leafy Greens:Kale, spinach, and amaranth varieties serve domestic food security demand with harvest-to-market cycles under 45 days. Dar es Salaam mobile-commerce platforms are creating direct farm-to-consumer bypass routes, compressing traditional wholesale intermediation.
- Citrus:Orange and lemon cultivation clusters in the Eastern Arc highlands supply juice processing and fresh export channels.
- Root Vegetables:Cassava, sweet potato, and carrot categories dominate volume throughput for domestic wholesale channels with minimal cold-chain dependency.
Root vegetables retain volume leadership; stone fruits hold the steepest expansion curve.
End User:
Customer type determines specification intensity, with formal retail and export buyers imposing traceability requirements absent in traditional food service procurement.
- Exporters:EU and Middle Eastern buyers mandate geolocation traceability for avocado and French bean consignments under evolving deforestation regulation compliance. Kilimanjaro-Arusha cooperatives deploy smartphone-based geotagging to satisfy documentation requirements.
- Retailers:Dar es Salaam supermarket chains impose size-grading and packaging specifications previously absent in domestic trade, forcing upstream contract farming consolidation.
- Restaurants:Urban hospitality sector demand concentrates on standardized, traceable produce sourcing for quality consistency.
- Food Processing:Juice, canning, and snack manufacturers secure year-round volume guarantees through highland tomato and capsicum contract arrangements.
Retailers are gaining share fastest; exporters maintain the highest compliance cost burden.
Sales Channel:
Channel structure reflects infrastructure maturity, with modern retail and digital platforms displacing traditional intermediation where cold-chain investment permits.
- Supermarkets:Dar es Salaam and Arusha retail expansion compresses traditional wholesale channels, forcing traceability compliance across smallholder networks. Specification creep is most visible in tomato and capsicum categories.
- Wholesale Distributors:Open-air market intermediaries retain dominance for root vegetables and non-standardized produce categories lacking retail grading requirements.
- Online Stores:Dar es Salaam e-grocery platforms create direct farm-to-consumer routes for leafy greens and herbs, bypassing physical market infrastructure.
- Farmers' Markets:Traditional assembly points persist for smallholder surplus disposal outside formal contract farming arrangements.
Wholesale distributors retain volume leadership; online stores exhibit the steepest growth trajectory.
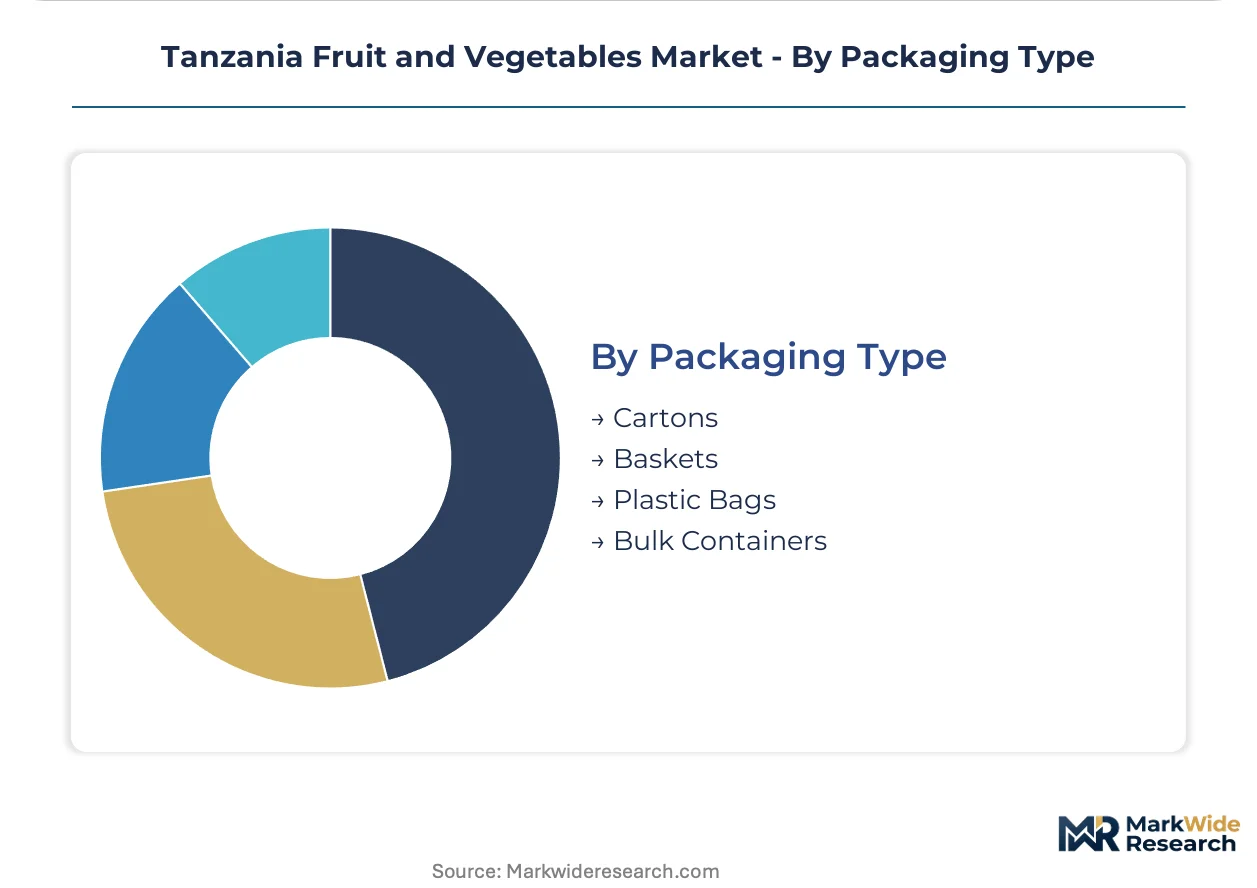
Packaging Type:
Packaging specification tiers align with buyer channel requirements, from export-grade traceability to cost-minimized domestic distribution.
- Cartons:Standardized corrugated packaging satisfies EU supermarket import specifications for French beans and snow peas, with Tanzania Bureau of Standards certification aligning to EAC harmonized codes.
- Bulk Containers:Reusable plastic crates and ventilated bins dominate highland-to-urban logistics for supermarket supply chains, enabling return-loop efficiency.
- Plastic Bags:Low-cost polyethylene packaging persists in domestic wholesale channels with minimal regulatory restriction.
- Baskets:Traditional woven containers retain utility for farmers' market and local restaurant procurement with limited shelf-life requirements.
Cartons retain export channel dominance; bulk containers are expanding most quickly in domestic retail supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The TAZARA Railway corridor linking Dar es Salaam to Zambia anchors Tanzania's horticultural export logistics, while the Kilimanjaro International Airport cold-chain terminal underwrites high-value perishable airfreight to European markets.
Kilimanjaro Region
Avocado and French bean export volumes from Moshi and Arusha municipalities drive foreign exchange earnings through Rotterdam-bound consignments. The Tanzania Plant Health and Pesticides Authority operates satellite inspection stations here to expedite phytosanitary certification. Cooperative aggregation centers in Hai District deploy smartphone-based geotagging to satisfy EU Deforestation Regulation traceability mandates.
Dar es Salaam
Urban supermarket chains and e-grocery platforms concentrate demand for standardized leafy greens and temperate vegetables. The Tanzania Bureau of Standards certifies packaging materials at portside facilities to align with EAC harmonized codes. Kariakoo wholesale market intermediaries face displacement as cold-chain procurement networks extend direct farm linkages.
Mbeya
Highland tomato and capsicum contract farming arrangements supply year-round volumes to domestic processors and retail distributors. Diesel price volatility compresses refrigerated transport margins along the 800-kilometer Mbeya-to-Dar es Salaam logistics corridor. Specialized cold-chain operators maintain controlled-atmosphere storage at the Mbalizi Road industrial zone.
Iringa
Underdeveloped temperate vegetable acreage offers first-mover opportunities for carrot and capsicum cultivation at elevation. The national agricultural extension service promotes Integrated Pest Management adoption to preempt EU Maximum Residue Limit compliance failures. Ruaha River irrigation schemes support counter-seasonal production windows for supermarket supply chains.
Arusha
French bean and snow pea exporters leverage proximity to Kilimanjaro International Airport for Middle Eastern retail chain procurement. Dubai and Riyadh buyers source through Arusha-based cold-chain handlers, expanding premium export windows beyond traditional European destinations. Post-harvest handling infrastructure here controls quality specifications for supermarket-grade consignments.
Tanzania Fruit and Vegetables Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. Tanzania's fruit and vegetables market structures around three distinct tiers: cooperative aggregators managing smallholder supply networks, integrated cold-chain operators controlling post-harvest infrastructure, and specialized logistics providers extending shelf-life for domestic retail. Competitive moves concentrate on contract farming consolidation to secure year-round volumes and digital traceability platform deployment to satisfy evolving export compliance requirements.
Within the cooperative-aggregator tier, Tanzania Horticultural Association and TAHA Fresh represent industry coordination bodies that standardize quality protocols across member smallholders. Eden Fresh Produce and Agro Fresh Tanzania occupy positions as integrated operators combining contract farming networks with post-harvest handling infrastructure. Mbeya Fresh Ltd. exemplifies the specialized cold-chain logistics archetype, focusing on domestic supermarket distribution rather than export channels.
| Leading Market Players |
|---|
| Tanzania Horticultural Association (TAHA) |
| Eden Fresh Produce |
| Agro Fresh Tanzania |
| Mbeya Fresh Ltd. |
| Sustainably Grown Tanzania |
| East Africa Foods |
| Darsh Industries Ltd. |
| TAHA Fresh |
| Produce Tanzania |
| Others |
Value Chain & Pricing Dynamics
Kilimanjaro cooperative concentration in avocado and French bean export supply pools margin capture downstream at Arusha-based cold-chain handlers and Rotterdam-bound freight consolidators. Tanzania Plant Health and Pesticides Authority certification bottlenecks create scarcity rents for compliant volume, while diesel volatility along the Mbeya-to-Dar es Salaam corridor compresses domestic distribution economics.
Pricing Analysis
The Plant Protection Act dictates the pricing tier structure across Tanzania's horticultural export channels. Three-tier pricing structure across premium, standard, and economy levels separates EU-compliant certified consignments from Middle Eastern grade and diverted domestic wholesale lots. Price differentiation hinges on phytosanitary certification status and geolocation traceability compliance under EU Deforestation Regulation mandates. Cost compression in domestic supermarket supply chains is intensifying because contract farming consolidation forces upstream cold-chain investments. Traditional wholesale intermediaries exhibit highest price sensitivity; export-oriented cooperatives with digital traceability infrastructure demonstrate lowest sensitivity due to premium market access.
Supply Chain Analysis
Eden Fresh Produce and Agro Fresh Tanzania anchor contract farming networks across the Southern Highlands and Kilimanjaro-Arusha corridor. Geographic supply concentration centers on Tanzania's Kilimanjaro Region, Arusha Municipality, and Mbeya District for temperate-climate vegetables and stone fruits. Raw material dependencies rest on synthetic pesticide inputs, corrugated packaging certified by Tanzania Bureau of Standards, and diesel fuel for refrigerated transport. Single-source vulnerability pervades the phytosanitary certification pipeline where Tanzania Plant Health and Pesticides Authority inspection queues create export delays. Distribution runs through cooperative aggregation centers to cold-chain handlers, then onward via Kilimanjaro International Airport airfreight or Dar es Salaam port reefer containers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tanzania's fruit and vegetables market sustains defensive moats through regulatory entrenchment: phytosanitary certification requirements and EU Deforestation Regulation compliance create switching costs that bind export-oriented buyers to established cooperative networks.
For Market Incumbents: Entrench position by deepening backward integration into cold-chain infrastructure at Kilimanjaro International Airport and Mbeya industrial zones, capturing margin pools currently leaking to third-party logistics operators. Accelerate digital traceability platform deployment to preempt EU regulatory tightening on geolocation requirements, neutralizing emerging entrant attempts to bypass compliance investments. Lock in multi-year contract farming arrangements with highland tomato and capsicum growers to secure processor raw material pipelines against volume poaching. For New Entrants and Emerging Players: Establish a beachhead in Iringa's underdeveloped temperate vegetable zone where first-mover contract farming arrangements for carrot and capsicum cultivation remain unclaimed by incumbent cooperative networks. Target domestic e-grocery channels in Dar es Salaam with direct farm-to-consumer leafy greens and herbs, bypassing traditional wholesale intermediaries that incumbent cold-chain operators currently supply. Pursue supermarket private-label procurement contracts as the most penetrable entry path, leveraging shorter compliance timelines than export certification demands. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cold-chain logistics specialists controlling post-harvest handling infrastructure in Arusha and Dar es Salaam. Long-term viability across the analysis window favors platforms combining cooperative aggregation networks with digital traceability compliance capabilities. Watch for EU Maximum Residue Limit enforcement tightening as the inflection indicator that separates acquisition targets with compliant infrastructure from stranded domestic wholesale operators.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Traceability Platform Deployment | Smartphone-based geotagging satisfies EU Deforestation Regulation mandates for avocado and French bean exporters. |
| Cold-Chain Infrastructure Expansion | Controlled-atmosphere storage at Mbalizi Road industrial zone extends shelf life for domestic supermarket clients. |
| Contract Farming Consolidation | Year-round volume guarantees from Mbeya and Iringa highland growers secure processor raw material pipelines. |
| Integrated Pest Management Conversion | Cooperative adoption of restricted pesticide lists preempts container rejection at Rotterdam and Hamburg ports. |
| E-Grocery Channel Partnership | Dar es Salaam mobile-commerce platforms create direct farm-to-consumer bypass routes for leafy greens and herbs. |
Study Parameters
A spread of perspectives from cooperative aggregation managers, cold-chain logistics operators, supermarket procurement directors, Tanzania Plant Health and Pesticides Authority inspectors, and export freight consolidators converged on the working assumptions driving this analysis. Primary field engagement with smallholder cooperative leaders in Hai District and Moshi Municipality combined with secondary validation against Tanzania Bureau of Standards certification records, TAZARA Railway cargo manifests, and Kilimanjaro International Airport airfreight statistics. Bottom-up volume modeling across product type, end user, and sales channel segmentation triangulated against top-down macroeconomic indicators for agricultural export earnings.
Demand-supply balance dynamics anchored the forecast framework across the projection horizon. Segmentation dimensions modeled encompass product type, end user category, sales channel, and packaging format, with additional granularity for phytosanitary certification status and geolocation traceability compliance. CAGRs were derived from trend extrapolation of historical export volume trajectories and domestic retail channel expansion rates, calibrated against cold-chain infrastructure deployment timelines and diesel price volatility assumptions. Industry-specific forecast inputs included EU Deforestation Regulation implementation pace and Tanzania Plant Health and Pesticides Authority inspection capacity expansion.
Sensitivities concentrate around EU Maximum Residue Limit enforcement stringency, diesel price volatility along the Southern Highlands logistics corridor, and phytosanitary laboratory capacity bottlenecks at Tanzania Bureau of Standards facilities. Forecasts reflect assumptions regarding cooperative digital traceability adoption rates and supermarket procurement consolidation velocity. Quarterly review of Rotterdam and Hamburg port rejection rates, Tanzania Plant Health and Pesticides Authority certification queue lengths, and Dar es Salaam e-grocery platform order volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Europe Pea Market
Vegetables
Hydroponic Vegetable Market
Vegetables
Canada Microgreens Market
Vegetables
Asparagus Market
Vegetables
Global Mushroom Market
Vegetables
South America Peas Market
Vegetables
Acorn Squash Market
Vegetables
Potato Market
Vegetables
Garden Cress Market
Vegetables
Artichokes Market
Vegetables
Greenhouse Produce Market
Vegetables
Fresh Mushroom Market
Vegetables
Air Dried Vegetables Market
Vegetables
Algeria Fruits and Vegetables Market
Vegetables
Europe Christmas Tree Market
Vegetables
Dehydrated Vegetables Market