
 Dried Vegetable Market | 2026-2036
Dried Vegetable Market Size, Share, and Industry Trends Forecast 2026-2036
Dried Vegetable Market Analysis
FDA Food Safety Modernization Act compliance timelines for supply chain traceability is collapsing the supplier base eligible for North American food manufacturing contracts. Olam International leverages its integrated African and Asian sourcing networks to sustain bulk supply contracts with multinational processors. Van Drunen Farms anchors the organic dried vegetable segment through controlled Midwestern agricultural partnerships. Symrise AG differentiates via flavor-system integration that combines dried vegetable extracts with complementary natural ingredients.
Dried vegetables comprise dehydrated plant matter with moisture content typically reduced below 10 percent through air drying, freeze drying, or drum drying processes to inhibit microbial activity and extend shelf stability for industrial food formulation and consumer preparation. The food industry end user segment dominates volume absorption, with soup manufacturers and seasoning blenders representing the largest consistent procurement channel. Powder form commands premium positioning within ingredient supply chains due to solubility advantages in instant applications, while whole dried formats retain strength in retail and home cooking channels where visual product integrity influences purchase decisions.
FDA FSMA traceability rules, EU EFSA contamination thresholds for dried produce imports, and India's FSSAI packaging and labeling standards collectively determine market access parameters and compliance cost structures across major trade corridors. The EU Green Deal's Farm to Fork sustainability targets are redirecting procurement specifications toward water-efficient dehydration technologies and shorter supply radius requirements. Stakeholders must monitor evolving mycotoxin testing protocols and carbon accounting disclosures as these criteria increasingly filter supplier eligibility in institutional purchasing frameworks.
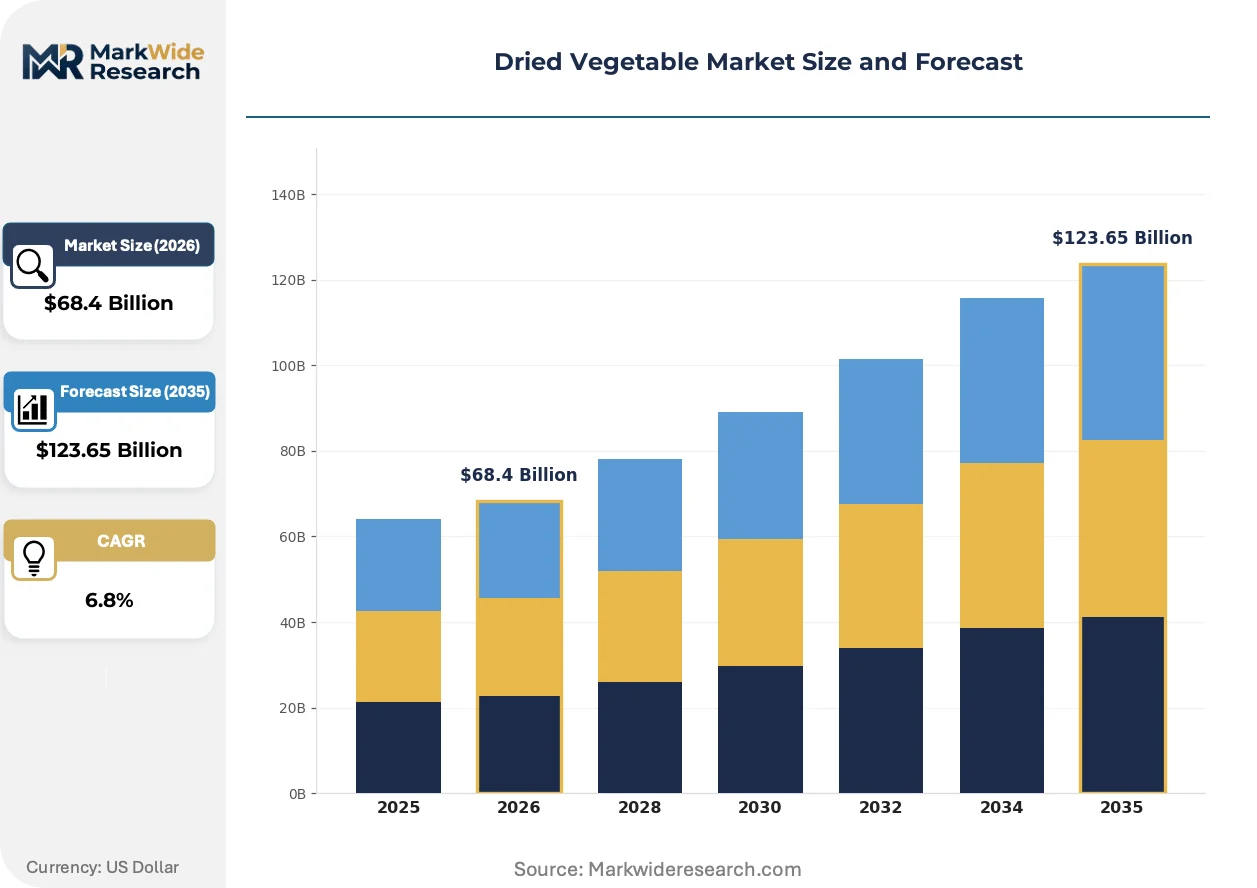
Market Dynamics
Traceability mandates under the FDA Food Safety Modernization Act are collapsing the supplier base eligible for North American food manufacturing contracts, concentrating procurement power among vertically integrated processors with captive dehydration capacity and documented chain-of-custody systems.
Growth Catalysts
- Ready-meal manufacturing expansion:Packaged soup and convenience food producers are scaling dried vegetable purchases to reduce cold-chain dependency and extend finished-product shelf stability.
- EU Green Deal water-efficiency targets:The Farm to Fork sustainability framework is redirecting procurement specifications toward low-water dehydration technologies and shorter supply radius requirements.
- India FSSAI packaging standardization:Mandatory labeling and traceability protocols are professionalizing domestic supply chains, enabling export-grade capacity expansion from Maharashtra and Gujarat production clusters.
Market Restraints
- Energy cost volatility:Natural gas and electricity price swings directly compress margins for air-drying and freeze-drying operations, particularly in European processing facilities.
- Input concentration risk:Onion, garlic, and tomato dehydration depends on seasonal harvests from specific growing belts in India, China, and California, creating single-source vulnerability.
- Mycotoxin threshold stringency:EFSA contamination limits for aflatoxin and ochratoxin in dried produce imports are disqualifying traditional suppliers from EU market access.
Strategic Opportunities
- Carbon-accounting procurement filters:Institutional buyers are embedding Scope 3 emissions disclosures into supplier scorecards, creating first-mover advantage for processors with verified low-carbon dehydration.
- Powder-form solubility premium:Instant soup and seasoning blenders are paying formulation premiums for micronized vegetable powders with enhanced dispersibility in hot liquids.
- Controlled-environment agriculture integration:Vertical farming operations in the Netherlands and Singapore are piloting on-site dehydration to eliminate post-harvest transport spoilage.
Industry Challenges
- FSMA traceability system integration:Small and mid-sized dehydrators face six-figure compliance costs to implement lot-level tracking compatible with buyer ERP systems.
- Freeze-drying technician scarcity:Specialized knowledge of sublimation cycle optimization and vacuum chamber maintenance is concentrated among aging workforce cohorts in Midwestern US processing hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dried Vegetable Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dried Beans, Dried Peas, Dried Carrots, Dried Spinach Form: Flakes, Granules, Powder, Whole End User: Food Industry, Retail, Food Service, Home Cooking Packaging Type: Bags, Jars, Pouches, Bulk |
| Companies Covered | Olam International, Sensient Technologies Corporation, BCFoods Inc., Mercer Foods LLC, ITC Limited, Jain Irrigation Systems, Van Drunen Farms, European Freeze Dry Ltd., Symrise AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dried Vegetable Market Emerging Trajectories
Dehydration technology trajectories are diverging between commodity-scale air drying and premium freeze drying, with regulatory pressure and buyer procurement models simultaneously reshaping equipment investment patterns and supplier qualification protocols.
Freeze drying is bifurcating the ingredient quality tier structure. This technology preserves cellular integrity and volatile aromatic compounds through sublimation, enabling clean-label positioning in premium soup and seasoning applications. Multinational seasoning blenders in Western Europe and North America are converting procurement specifications to specify freeze-dried content minimums. The technology is bifurcating supplier tiers into capital-intensive freeze-drying specialists versus commodity air-drying operations serving private-label retail channels.
EU EFSA mycotoxin surveillance protocols are tightening import inspection regimes for dried vegetables originating in tropical and subtropical growing regions. Randomized sampling and enhanced laboratory testing requirements are extending customs clearance timelines and increasing working capital requirements for importers. African and South Asian suppliers are responding by investing in on-farm aflatoxin prevention and third-party pre-shipment certification.
Buyer consolidation among multinational soup and ready-meal manufacturers is compressing supplier negotiation cycles and unbundling technical service from commodity supply contracts. Procurement teams at major European and North American food processors are centralizing dried vegetable purchasing into global category management functions. This concentration is most visible in Germany and the Netherlands, where Unilever and Nestlé procurement hubs are mandating unified specification standards across continental manufacturing networks.
Dried Vegetable Market Segmentation
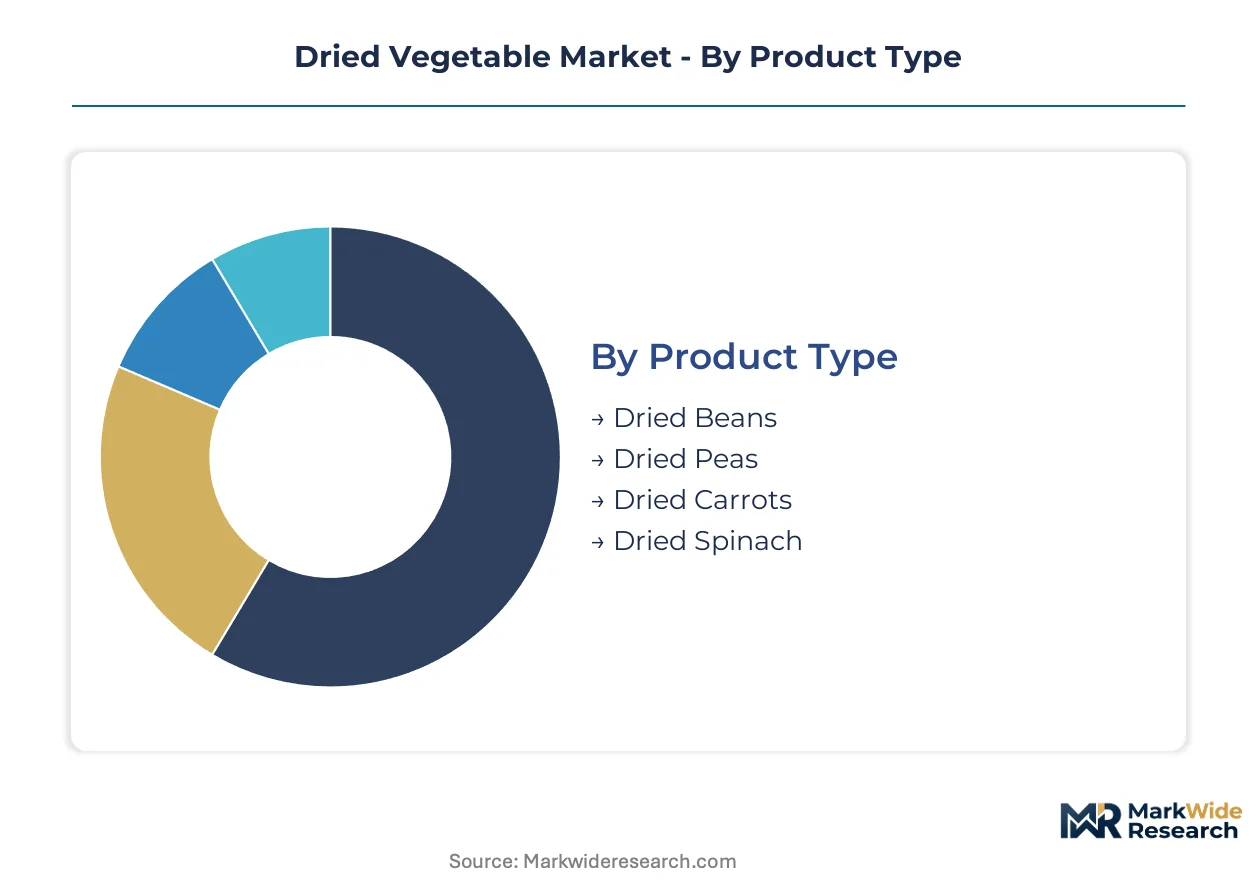
Segmentation in the dried vegetable market reveals how procurement specifications diverge between industrial formulation and consumer retail channels. Understanding these divides exposes where margin pools concentrate and where supplier qualification barriers create defensible competitive positions.
Product Type:
Margin pools concentrate in pulse-derived segments where protein content commands formulation premiums in plant-based applications.
- Dried Beans:High-protein legume varieties including kidney, black, and navy beans retain cellular structure through controlled dehydration cycles. Soup manufacturers in the US Midwest specify these for clean-label protein fortification in ready-meal lines.
- Dried Peas:Yellow and green split peas offer rapid rehydration kinetics valued by instant soup formulators. EU procurement teams are rotating specifications toward Estonian and Latvian supply to shorten carbon-accounting radius under Farm to Fork targets.
- Dried Carrots:Beta-carotene retention varies sharply by dehydration method; air-dried formats serve retail while freeze-dried dice capture seasoning blend premiums.
- Dried Spinach:Iron and folate stability depends on blanching pre-treatment protocols; powder forms dominate infant nutrition and smoothie additive channels.
Dried Beans holds installed capacity. Dried Peas is rotating up the share rankings.
Form:
Cost tier structures separate commodity air-dried formats from capital-intensive freeze-dried alternatives with tenfold price multiples.
- Powder:Micronized vegetable matter below 200 mesh enables instant solubility in hot liquids. Seasoning blenders in Germany and the Netherlands pay formulation premiums for dispersibility metrics that eliminate clumping in automated packaging lines.
- Whole:Intact cellular structure preserves visual identity for retail merchandising and home cooking applications. Indian FSSAI packaging mandates are professionalizing bulk-to-retail repackaging infrastructure in Maharashtra processing clusters.
- Flakes:Intermediate particle size suits soup base applications where rapid hydration meets texture requirements.
- Granules:Free-flowing agglomerated particles reduce dusting in industrial handling; preferred by ready-meal manufacturers with pneumatic conveying systems.
Powder captures the steepest expansion trajectory in industrial procurement. Whole defends its position in retail channel volume.
End User:
Customer type determines specification stringency, with food industry buyers imposing traceability requirements that exclude two-thirds of potential suppliers.
- Food Industry:Industrial processors including soup manufacturers, seasoning blenders, and ready-meal producers purchase bulk formats under FSMA-mandated lot-level tracking. FDA compliance timelines are collapsing the supplier base eligible for North American contracts toward vertically integrated dehydrators with captive agriculture.
- Retail:Supermarket and e-commerce channels demand consumer-unit packaging with extended shelf-life claims. EU Green Deal water-efficiency disclosures are becoming mandatory selection criteria for private-label procurement teams.
- Food Service:Restaurant and institutional buyers prioritize rehydration speed and yield consistency over flavor intensity.
- Home Cooking:Traditional retail formats serve ethnic cuisine preparation and emergency pantry stocking segments.
Food Industry holds installed capacity. Retail is rotating up the share rankings.
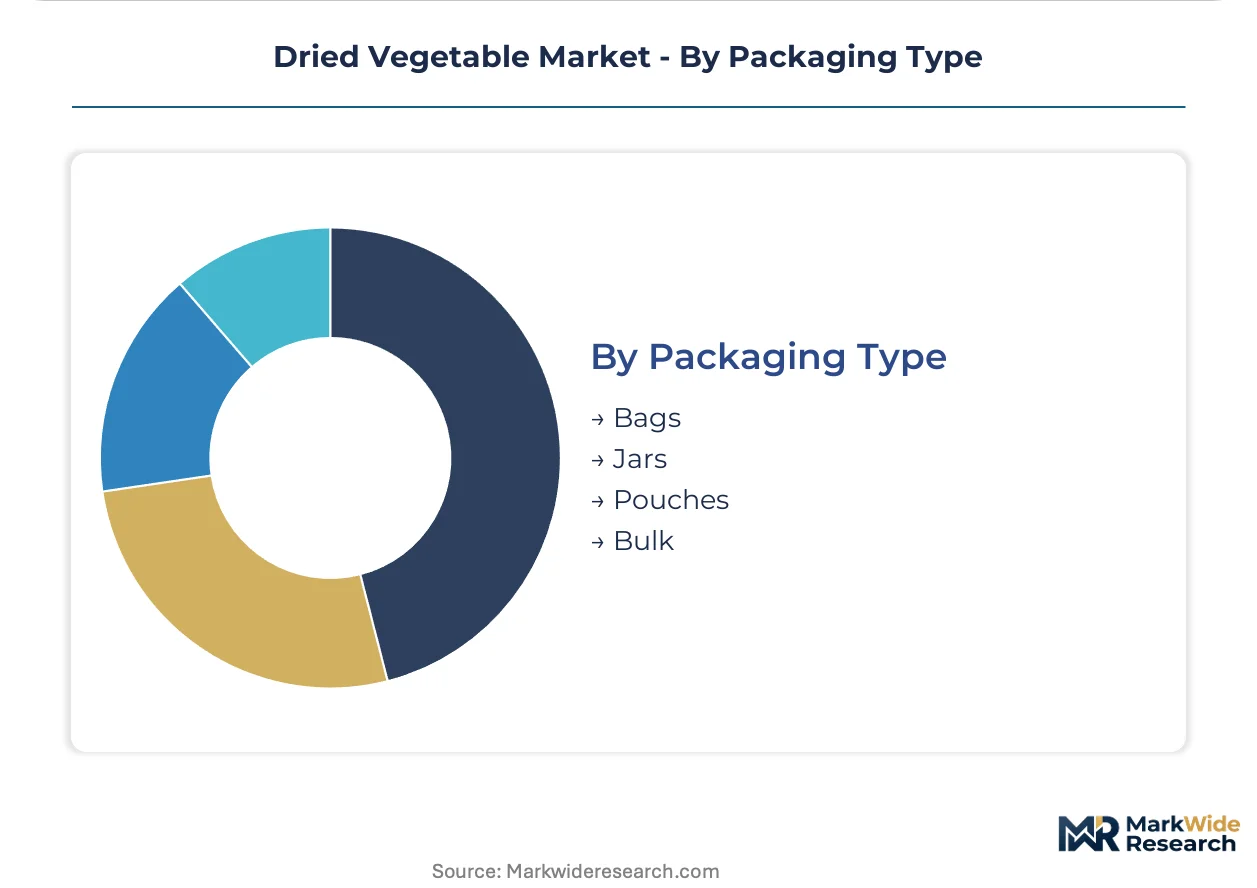
Packaging Type:
Volume concentration sits in bulk formats for industrial offtake, while unit-margin premiums accrue to portion-controlled pouches.
- Bulk:Flexible intermediate bulk containers and food-grade totes serve manufacturers with in-house blending and repackaging capabilities. California and Gujarat dehydration clusters dominate this channel with containerized export logistics.
- Pouches:Stand-up and flat pouch formats with reseal features capture camping, emergency preparedness, and single-serve convenience premiums. Dutch co-packing specialists are integrating on-site nitrogen flushing to extend shelf stability without synthetic preservatives.
- Bags:Conventional pillow packs retain cost competitiveness in commodity retail channels.
- Jars:Rigid glass packaging serves premium positioning in gift and specialty retail segments.
Bulk holds installed capacity. Pouches is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational soup and ready-meal manufacturers concentrate procurement decisions in Germany, the United States, India, the Netherlands, and China. These five markets anchor supply chain configuration through divergent regulatory pressures and processing infrastructure.
United States
Midwestern soup manufacturers drive bulk dehydrated vegetable absorption for institutional food service and retail private-label lines. FDA FSMA traceability mandates are disqualifying small dehydrators without ERP-compatible lot-tracking systems. Chicago-area processing clusters are consolidating around vertically integrated operators with captive Illinois and Indiana agricultural partnerships.
Germany
Seasoning blenders in Hamburg and Frankfurt procurement hubs specify freeze-dried content minimums for premium soup bases. EU EFSA mycotoxin surveillance protocols are extending customs clearance timelines for tropical-origin imports. Bavarian dehydration facilities are retrofitting air-drying lines with heat recovery systems to meet EU Green Deal water-efficiency disclosures.
India
Maharashtra and Gujarat production clusters supply onion, garlic, and tomato dehydration for export-grade contracts. FSSAI packaging and labeling standardization is professionalizing domestic supply chains. Jain Irrigation Systems and ITC Limited anchor processing capacity expansion around Nashik and Pune agricultural belts.
Netherlands
Unilever and Nestlé procurement hubs in Rotterdam mandate unified specification standards across continental manufacturing networks. Dutch co-packing specialists integrate nitrogen flushing for stand-up pouch formats serving camping and emergency preparedness channels. Vertical farming operations near Eindhoven pilot on-site dehydration to eliminate post-harvest transport spoilage.
China
Shandong and Xinjiang growing belts supply air-dried vegetable matter for seasoning and instant noodle applications. SAMR food safety inspections are tightening contamination thresholds for domestic distribution. Zhengzhou machinery fabricators export dehydration equipment to Southeast Asian processors upgrading from sun-drying methods.
Dried Vegetable Market Vendor Landscape
Player mix skews toward agricultural conglomerates with captive dehydration capacity and specialized freeze-drying technology operators. Market structure bifurcates between commodity-scale air dryers serving private-label retail and capital-intensive freeze-drying specialists capturing seasoning blender premiums. Strategic archetypes include vertically integrated agricultural processors, flavor-system integrators, and regional dehydration machinery fabricators. Dominant competitive moves encompass backward integration into captive agriculture and technology licensing for low-energy sublimation cycles.
Among Singapore-based agricultural conglomerates, Olam International occupies a position exemplifying integrated African and Asian sourcing networks. Within the Midwestern United States processing tier, Van Drunen Farms represents the organic segment through controlled agricultural partnerships. German flavor-system integrators include Symrise AG, which sits within the premium tier combining dried vegetable extracts with complementary natural ingredients.
| Leading Market Players |
|---|
| Olam International |
| Sensient Technologies Corporation |
| BCFoods Inc. |
| Mercer Foods LLC |
| ITC Limited |
| Jain Irrigation Systems |
| Van Drunen Farms |
| European Freeze Dry Ltd. |
| Symrise AG |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day inventory cycles among European seasoning blenders compress working capital but amplify spot-price exposure when Indian monsoon harvests underperform. This lead-time band concentrates pricing power with vertically integrated dehydrators holding captive Maharashtra and Gujarat agricultural contracts, while forcing spot-market buyers into volatile procurement auctions.
Pricing Analysis
Cost-plus contracts indexed to natural gas and electricity benchmarks dominate bulk dehydrated vegetable procurement, with freeze-dried premiums scaling tenfold above air-dried commodity baselines. Price differentiation centers on dehydration technology tier and EU EFSA mycotoxin certification grade. Pricing pressure stems from energy cost volatility compressing European processor margins. Ready-meal manufacturers exhibit highest price sensitivity, while premium seasoning blenders in Germany absorb freeze-dried premiums with minimal volume elasticity.
Supply Chain Analysis
Strategic stockpiling of onion and garlic inventories ahead of Indian monsoon seasons contrasts with just-in-time powder procurement by automated soup manufacturers. Supply concentrates in India, China, and California for core dehydration feedstocks. Raw material flows draw from seasonal harvests in Nashik, Shandong, and Central Valley growing belts. Single-source vulnerability around Indian monsoon dependency creates systemic disruption risk. Distribution runs through Rotterdam and Hamburg hub-and-spoke networks serving continental European manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts for dehydration process optimization and FSMA compliance consulting are expanding faster than commodity supply volumes, creating recurring-revenue attach opportunities for processors with captive laboratory capabilities.
For Market Incumbents: Compound defensible positioning through backward integration into captive Nashik and Pune agricultural partnerships, while embedding carbon-accounting disclosure services into long-term supply contracts. Energy price volatility threatens margin stability at European air-drying facilities. Certification investment in EU EFSA pre-shipment testing protocols secures customs clearance priority. For New Entrants and Emerging Players: Custom lot-sizing and private-label formulation services represent the service-layer gap where multinational procurement hubs under-serve mid-tier regional soup manufacturers. Target white-space in Baltic dried pea supply chains under EU Farm to Fork carbon-radius mandates. Pursue toll-dehydration partnerships with Maharashtra aggregators lacking export-grade processing infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because FDA FSMA traceability mandates are collapsing the North American supplier base toward acquirable mid-cap dehydrators with ERP-compatible lot-tracking systems. Target processors with verified low-carbon dehydration technology and established Unilever or Nestlé procurement relationships. Watch for EFSA mycotoxin threshold tightening as inflection signal for pre-certification infrastructure premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Agriculture | Maharashtra and Gujarat land partnerships secure onion and garlic supply against monsoon volatility. |
| Freeze-Drying Capacity Expansion | German seasoning blenders mandate sublimation-processed content minimums for premium soup bases. |
| Carbon-Accounting Disclosure Programs | EU Green Deal procurement filters reward processors with verified Scope 3 emissions tracking. |
| FSMA Traceability System Implementation | FDA lot-level tracking requirements disqualify two-thirds of potential North American suppliers. |
| Technical Service Contract Layering | Process optimization consulting attaches recurring revenue to commodity supply relationships. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with procurement managers at multinational soup manufacturers, dehydration plant engineers in Maharashtra and California, seasoning blender formulation chemists in Germany and the Netherlands, and regulatory compliance officers navigating FDA FSMA and EU EFSA protocols. Secondary validation drew from customs trade databases, FSSAI packaging standard filings, EU Farm to Fork policy documents, and energy cost indices for European natural gas and electricity. Bottom-up capacity assessments across Gujarat and Shandong processing clusters were triangulated against top-down absorption estimates from ready-meal production volumes.
Across the analysis window, forecasts were constructed through segmented modeling of product type, form, end user, and packaging dimensions, with dehydration technology tier treated as a cross-cutting variable. CAGRs were derived from trend extrapolation of procurement volume shifts between air-dried and freeze-dried specifications, calibrated against input cost trajectories for natural gas and agricultural labor. Modeled outputs incorporated EU EFSA mycotoxin surveillance intensity and India FSSAI export-grade capacity expansion timelines as scenario-weighting factors.
Underlying assumptions cover stable EU Green Deal water-efficiency disclosure implementation and continued FDA FSMA enforcement intensity, with deviation risk concentrated in Indian monsoon variability and European energy price volatility. Revision becomes warranted when EFSA contamination threshold tightening or FSSAI packaging mandate acceleration crosses implementation thresholds that reshape supplier eligibility faster than modeled compliance timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Field Peas Market
Vegetables
Algeria Fruits and Vegetables Market
Vegetables
Artichokes Market
Vegetables
Microgreens Market
Vegetables
Dried Mushroom Market
Vegetables
North America Microgreens Market
Vegetables
Global Indoor Plant Market
Vegetables
Global Mushroom Market
Vegetables
Peas Market
Vegetables
Turkey Greenhouse Horticulture Market
Vegetables
Garden Cress Market
Vegetables
North America Peas Market
Vegetables
Vegetable Chutney Market
Vegetables
Australia Greenhouse Horticulture Market
Vegetables
United States Microgreens Market
Vegetables
Asparagus Market