
 Zimbabwe Fruits and Vegetables Market | 2026-2036
Zimbabwe Fruits and Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
Zimbabwe Fruits and Vegetables Market Analytics
Traditional wholesale buyers is collapsing as supermarket chains and hotel procurement managers expand direct farm contracts. Nyanga Blueberry Orchards leverages its high-altitude climate advantage to supply premium-grade fruit to European retailers. Zimbabwe Citrus Export Consortium anchors its operations through controlled atmosphere storage investments in Beitbridge. Chipinge Macadamia Estates dominates the tree-nut export pipeline with integrated hulling and grading facilities.
Zimbabwe fruits and vegetables encompass fresh and minimally processed plant products cultivated across agro-ecological zones ranging from 300 to 2,000 meters above sea level, with harvest cycles tied to subtropical rainfall patterns and irrigated winter production. These products serve domestic food security needs, export revenue generation, and raw material inputs for processing industries. Mango and tomato categories lead volume throughput due to dual-purpose fresh and processing demand, while spinach cultivation sustains year-round supply through smallholder irrigation schemes. The online distribution channel records the fastest expansion as urban households in Harare and Bulawayo shift toward doorstep delivery platforms.
Zimbabwe's Agricultural Marketing Authority enforces grading and phytosanitary standards that determine export eligibility for EU and Middle Eastern buyers. The Horticulture Development Council coordinates compliance with GLOBALG.A.P. certification and cold chain protocols mandated by destination market regulators. Stakeholders must monitor water allocation rulings from the National Water Authority and decide whether to invest in on-farm solar irrigation before dry-season planting windows contract further.
Market Dynamics
Direct farm contracting by supermarket chains and hotel procurement managers is collapsing traditional wholesale buyer networks across Zimbabwe's fresh produce supply chain, rewiring price discovery and quality assurance mechanisms.
Growth Catalysts
- EU GLOBALG.A.P. Certification Uptake:Zimbabwe's Horticulture Development Council compliance programs unlock export eligibility for premium blueberry and macadamia shipments to European retailers, expanding foreign exchange revenue channels.
- Smallholder Irrigation Schemes:Spinach and tomato cultivation through decentralized water infrastructure sustains year-round supply volumes for domestic processing industries.
- Beitbridge Cold Chain Investment:Controlled atmosphere storage facilities anchor citrus export consolidation, reducing post-harvest losses and extending shelf-life for Middle Eastern buyers.
Market Restraints
- National Water Authority Allocation Rulings:Contracting dry-season planting windows force capital-intensive solar irrigation investments that smallholders cannot finance.
- Phytosanitary Compliance Friction:Zimbabwe's Agricultural Marketing Authority licensing requirements create export bottlenecks for non-compliant producers lacking traceability documentation.
- Input Cost Volatility:Fertilizer and fuel price instability compresses margins for outgrower schemes supplying processing-grade tomatoes and mangoes.
Strategic Opportunities
- Manicaland Province Cluster Expansion:Mutare's cold chain infrastructure supports blueberry and macadamia estate densification for premium European market access.
- Doorstep Delivery Platform Integration:Urban households in Harare and Bulawayo accelerate online channel penetration for fresh produce distribution.
- Processing Industry Backward Integration:Food processors expand captive tomato and mango procurement for paste and juice production, securing raw material supply.
Industry Challenges
- Traceability System Implementation:Smallholder compliance with Horticulture Development Council documentation standards requires technical assistance and capital outlay.
- Certification Timeline Compression:GLOBALG.A.P. audit cycles delay export market entry for new blueberry and citrus producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zimbabwe Fruits and Vegetables Market |
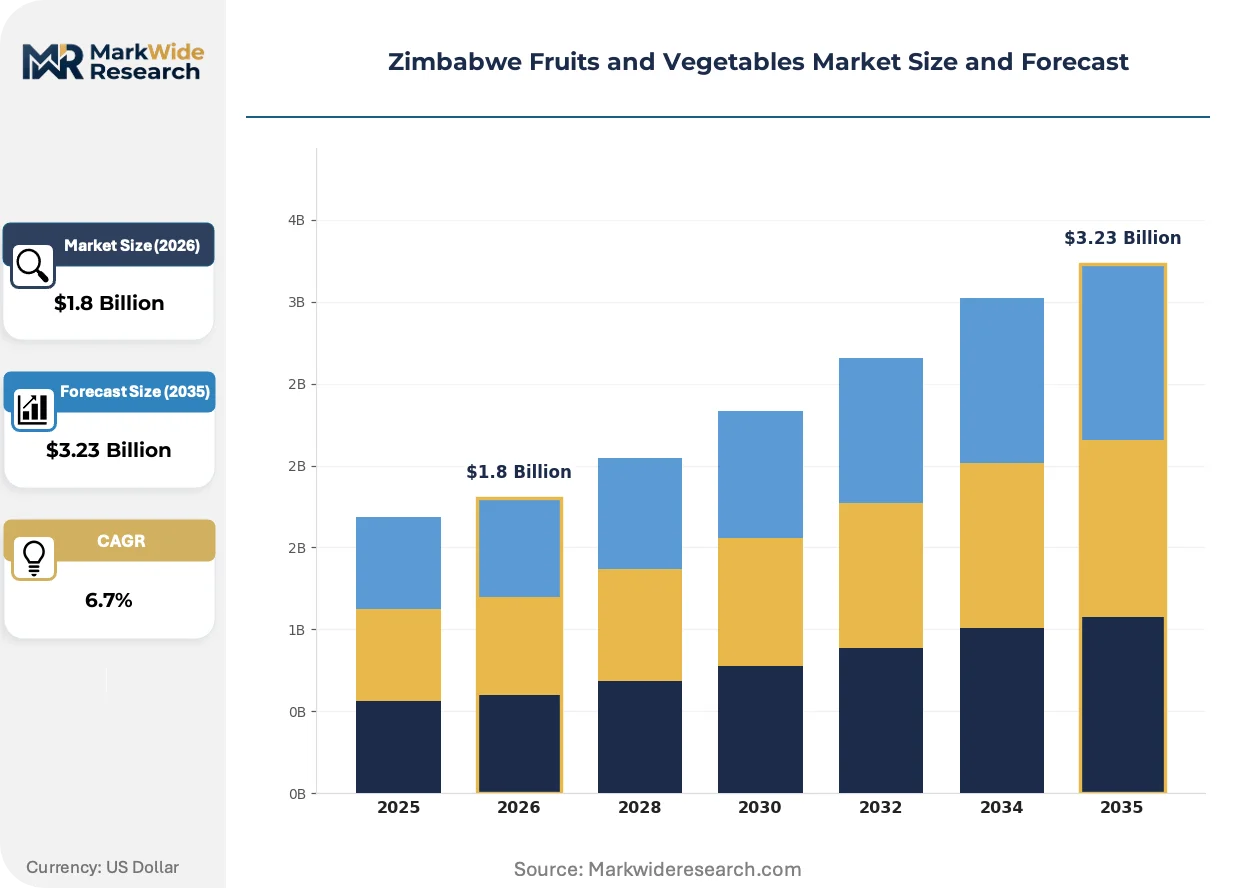
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mango, Banana, Tomato, Spinach Distribution Channel: Supermarket, Wholesale, Farmers' Market, Online Packaging Type: Box, Crate, Bag, Bulk End User: Retailers, Food Processors, Households, Hotels |
| Companies Covered | Nyanga Blueberry Orchards, Zimbabwe Citrus Export Consortium, ZimTrade, Fresh Produce Processing Companies (Tomato Paste & Frozen Chip Processors), Avocado Export Association of Zimbabwe, Horticulture Development Council, Manicaland Premium Export Horticulture Producers, Cold Chain Infrastructure Operators, Chipinge Macadamia Estates, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zimbabwe Fruits and Vegetables Market Evolving Landscape
Technology adoption and regulatory tightening are restructuring Zimbabwe's fresh produce value chain, with digital platforms and compliance frameworks displacing informal trading mechanisms.
Solar-powered drip irrigation systems are displacing flood irrigation methods across smallholder tomato and spinach schemes. Export-oriented estates in Manicaland Province deploy these systems fastest to secure water security certifications. The technology is displacing seasonal production constraints, enabling continuous harvest cycles that align with supermarket contract schedules.
Zimbabwe's Agricultural Marketing Authority enforces tightened phytosanitary grading protocols under Horticulture Development Council coordination. These rules mandate cold chain documentation and pesticide residue testing for EU-bound shipments. Blueberry exporters in Nyanga face the steepest compliance burden, investing in integrated pest management to meet maximum residue limits.
Hotel procurement managers and supermarket chains now bypass traditional wholesale markets for direct farm contracts with graded producers. This disintermediation concentrates purchasing power among large buyers while squeezing informal traders in Mbare Musika. The shift is most visible in Harare's northern suburbs, where premium-grade vegetable supply chains exclude unregistered growers.
Zimbabwe Fruits and Vegetables Market Segmentation
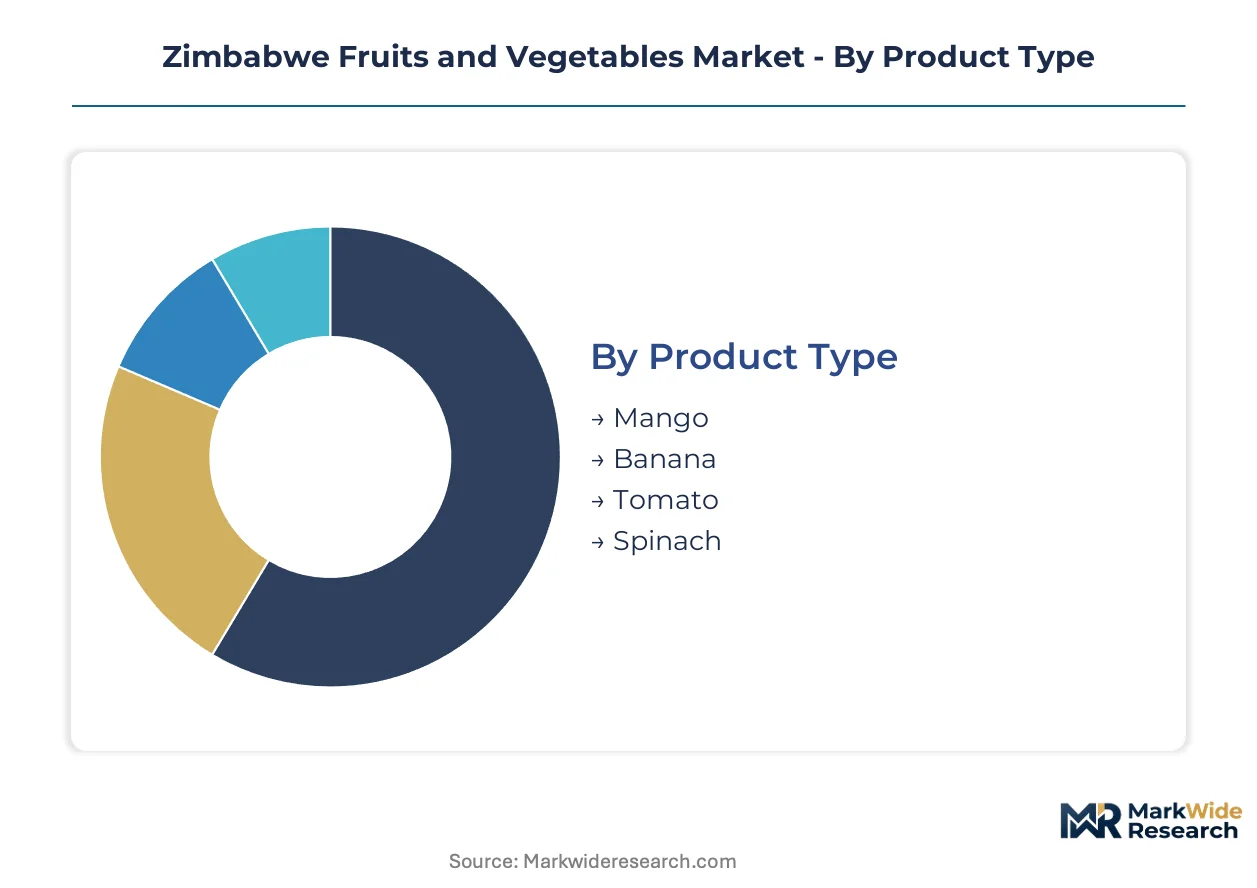
Zimbabwe's fruits and vegetables market fragments across product varieties, distribution pathways, and end-use applications. Each segment carries distinct regulatory requirements from the Agricultural Marketing Authority and Horticulture Development Council that shape commercial viability.
Product Type:
The Agricultural Marketing Authority applies differential phytosanitary grading standards across fruit and vegetable categories, with export eligibility hinging on residue testing protocols and cold chain documentation.
- Mango:Dual-purpose cultivars serve fresh export markets and processing industries for juice and paste production. Demand concentrates in food processor procurement contracts, where paste-grade volumes secure year-round supply commitments from Chipinge and Mutare orchards.
- Tomato:Processing-grade varieties dominate volume throughput through outgrower schemes supplying paste manufacturers. Smallholder irrigation schemes in Manicaland Province sustain winter production cycles aligned with supermarket contract schedules.
- Banana:Cavendish and plantain varieties circulate through domestic wholesale channels with minimal export penetration due to perishability constraints.
- Spinach:Leafy greens sustain year-round availability through decentralized smallholder irrigation, serving urban household demand in Harare and Bulawayo.
Established volume favors tomato; emerging adoption favors mango.
Distribution Channel:
Channel selection determines compliance burden and margin capture, with direct contracting bypassing traditional wholesale markups.
- Supermarket:Chains like OK Zimbabwe and TM Supermarkets enforce GLOBALG.A.P. certification requirements and direct farm contracting. Harare's northern suburbs concentrate premium-grade vegetable procurement through formal retail channels.
- Online:Doorstep delivery platforms record steepest expansion trajectory as urban households shift toward digital ordering. Harare and Bulawayo metro areas drive platform densification.
- Wholesale:Mbare Musika remains volume anchor for ungraded produce and informal trader networks despite supermarket disintermediation.
- Farmers' Market:Weekend markets in Bulawayo and Mutare serve price-sensitive households with minimal certification requirements.
Traditional wholesale retains volume dominance; online channels gain share fastest.
Packaging Type:
Packaging specifications align with destination market regulations and cold chain integrity requirements.
- Box:Corrugated containers dominate export-grade blueberry and macadamia shipments, with Horticulture Development Council mandates for traceability labeling.
- Crate:Reusable plastic crates circulate through supermarket reverse logistics systems, reducing per-unit packaging costs for tomato and spinach contracts.
- Bag:Polypropylene sacks serve bulk processing-grade mango procurement from outgrower schemes.
- Bulk:Loose transport applies to wholesale market deliveries with minimal handling protocols.
Boxed packaging commands premium export margins; crate systems expand through retail channels.
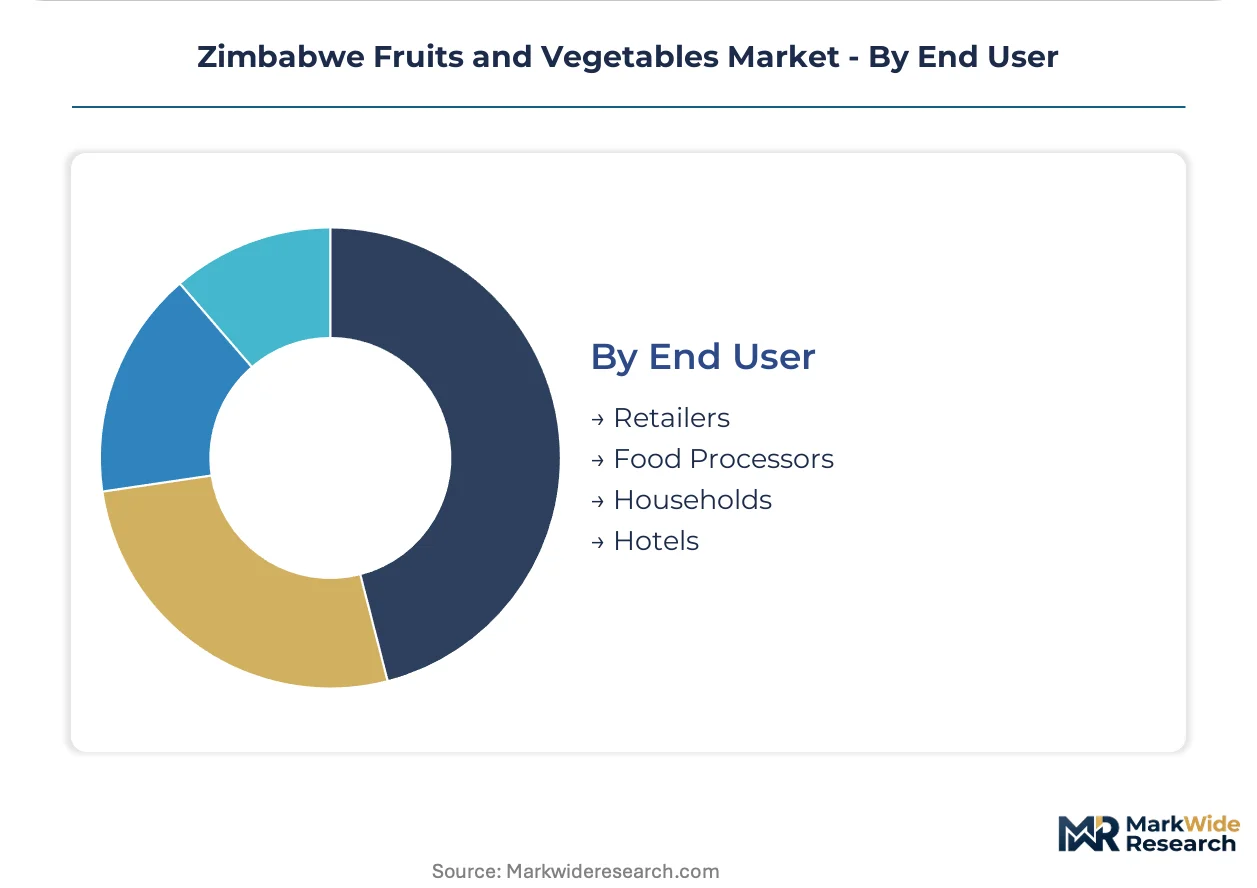
End User:
End-user categories segment by quality tier requirements and procurement sophistication.
- Food Processors:Tomato paste and mango juice manufacturers drive backward integration into captive procurement, securing supply through outgrower schemes in Manicaland.
- Retailers:Supermarket chains and independent grocers enforce graded produce standards with direct farm contracting displacing wholesale intermediaries.
- Hotels:Procurement managers in Victoria Falls and Harare bypass traditional markets for premium-grade vegetable contracts with Nyanga estates.
- Households:Urban consumers in Harare and Bulawayo split between supermarket purchases and online delivery platforms.
Food processors anchor industrial volume; hotel procurement expands premium tier fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zimbabwe's blueberry and macadamia shipments reach European retailers through South Africa's Cape Town port corridor, while citrus exports flow northward to Middle Eastern buyers via Beitbridge logistics infrastructure.
Manicaland Province
Blueberry and macadamia estates cluster around Mutare's cold chain facilities to serve premium European export contracts. The Agricultural Marketing Authority enforces phytosanitary grading standards that determine EU eligibility for Nyanga-based orchards. Chipinge Macadamia Estates anchors the province's tree-nut export pipeline with integrated hulling operations.
Mashonaland East
Tomato outgrower schemes supply processing-grade volumes to paste manufacturers through smallholder irrigation networks. National Water Authority allocation rulings constrain dry-season planting windows, forcing solar irrigation investments. Marondera and Ruwa districts concentrate winter production cycles aligned with supermarket procurement schedules.
Masvingo
Citrus cultivation supports the Zimbabwe Citrus Export Consortium's controlled atmosphere storage investments in Beitbridge. The Horticulture Development Council coordinates GLOBALG.A.P. certification compliance for Middle Eastern market access. Lowveld irrigation schemes enable year-round harvest cycles despite rainfall variability.
Harare Metropolitan
Urban household demand drives online doorstep delivery platform expansion across northern suburbs. OK Zimbabwe and TM Supermarkets enforce direct farm contracting that bypasses traditional wholesale channels. Mbare Musika retains volume anchor for ungraded produce despite supermarket disintermediation.
Bulawayo and Matabeleland
Weekend farmers' markets serve price-sensitive households with minimal certification requirements. Spinach cultivation through decentralized irrigation sustains year-round supply for domestic consumption. The city's procurement managers increasingly source premium-grade vegetables through formal retail channels rather than informal traders.
Zimbabwe Fruits and Vegetables Market Competitive Landscape
Listed leaders compete with private specialists across export certification tiers, with estate-based producers holding distinct advantages in premium-grade segments. The market structure fragments between large-scale integrated operators and smallholder outgrower networks supplying processing industries. Three archetypes dominate: high-altitude berry specialists, citrus export consolidators, and macadamia estate integrators. Competitive moves concentrate on backward integration into captive raw material supply and cold chain infrastructure investments that secure shelf-life extension.
Within the estate-integrated tier, Nyanga Blueberry Orchards exemplifies high-altitude climate advantage exploitation for European retail contracts. Zimbabwe Citrus Export Consortium anchors citrus export consolidation through Beitbridge controlled atmosphere facilities. Chipinge Macadamia Estates occupies a position as the dominant tree-nut export pipeline operator with in-house hulling and grading capabilities. These three entities represent the premium-tier vector where compliance investment separates export-eligible producers from domestic-market suppliers.
| Leading Market Players |
|---|
| Nyanga Blueberry Orchards |
| Zimbabwe Citrus Export Consortium |
| ZimTrade |
| Fresh Produce Processing Companies (Tomato Paste & Frozen Chip Processors) |
| Avocado Export Association of Zimbabwe |
| Horticulture Development Council |
| Manicaland Premium Export Horticulture Producers |
| Cold Chain Infrastructure Operators |
| Chipinge Macadamia Estates |
| Others |
Value Network & Pricing Analysis
GLOBALG.A.P. certification gates both supplier qualification and price tiering in Zimbabwe's horticulture sector, with compliant producers capturing premium export contracts while non-certified growers remain trapped in domestic spot markets. The Agricultural Marketing Authority's phytosanitary grading standards simultaneously determine cold chain eligibility and price ceilings, compressing margins for outgrowers who cannot finance traceability investments.
Pricing Analysis
Certification-grade pricing gaps separate GLOBALG.A.P.-compliant blueberry and macadamia shipments from domestic-grade produce, with prior-generation flood-irrigated volumes trading at steep discounts to solar-powered precision-irrigated harvests. Three-tier pricing structure across premium export, standard supermarket, and economy wholesale levels reflects cold chain integrity and residue testing outcomes. Cost compression in processing-grade tomato and mango tiers is intensifying because fertilizer and fuel price instability erodes outgrower scheme viability. Smallholder spinach suppliers show highest price sensitivity due to perishability and lack of storage, while European retail buyers demonstrate lowest sensitivity when sourcing Nyanga high-altitude blueberries.
Supply Chain Analysis
Beitbridge controlled atmosphere storage chokepoints anchor citrus export consolidation, with throughput constraints determining Middle Eastern market access timing. Geographic supply concentration centers on Manicaland Province for blueberry and macadamia, Mashonaland East for processing-grade tomato, and Masvingo's Lowveld for citrus. Raw material dependencies rest on fertilizer imports, fuel for irrigation pumps, and corrugated packaging for export shipments. Single-source vulnerability runs through South Africa's Cape Town port corridor for European-bound perishables. Distribution runs through supermarket reverse logistics systems for crate-circulated produce, while informal traders dominate bulk wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zimbabwe's fruits and vegetables sector sits at a high-growth inflection as solar irrigation and GLOBALG.A.P. compliance investments displace seasonal production constraints and informal trading mechanisms.
For Market Incumbents: Shield premium export positions by deepening backward integration into captive cold chain infrastructure at Beitbridge and Mutare, countering the threat of new blueberry entrants from high-altitude estates in Rwanda and Ethiopia. Prioritize Horticulture Development Council certification investment to maintain EU retailer access as maximum residue limits tighten. For New Entrants and Emerging Players: Differentiate on doorstep delivery platform integration for Harare and Bulawayo urban households, where online channel penetration remains underdeveloped relative to supermarket density. Target spinach and tomato cultivation through decentralized smallholder irrigation schemes as the most penetrable supply segment, leveraging National Water Authority allocation negotiations to secure dry-season planting windows. For Investors and Strategic Acquirers: Secondary-cycle assets sit with estate-integrated macadamia and blueberry operators that have exhausted initial growth capital but retain unexploited high-altitude acreage. Long-term viability hinges on water security certification and solar irrigation completion across the projection horizon. Watch National Water Authority ruling patterns as the signal for dry-season production capacity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Solar Irrigation Infrastructure Deployment | Manicaland estates secure water security certifications that unlock year-round supermarket contract schedules. |
| GLOBALG.A.P. Certification Acceleration | Horticulture Development Council compliance opens EU retailer channels for Nyanga blueberry shipments. |
| Cold Chain Storage Expansion | Beitbridge controlled atmosphere investments reduce post-harvest losses for citrus Middle Eastern exports. |
| Direct Farm Contracting Programs | OK Zimbabwe and TM Supermarkets bypass Mbare Musika intermediaries to capture quality premiums. |
| Processing Industry Backward Integration | Tomato paste manufacturers secure supply through Chipinge and Mutare outgrower scheme expansion. |
Research Methodology
Desk research of customs export records, Agricultural Marketing Authority licensing databases, and Horticulture Development Council certification registries preceded structured interviews with estate operations managers, supermarket procurement directors, food processor supply chain leads, and cold chain logistics operators. Secondary validation drew from National Water Authority allocation rulings, EU phytosanitary inspection reports, and solar irrigation equipment import data. Bottom-up volume estimates from provincial production clusters triangulated against top-down export value flows through South African port authorities.
Variance decomposition across the analysis window separated volume drivers (irrigation expansion, certification uptake) from price drivers (grade differentiation, export market access). Segmentation modeling captured product type, distribution channel, packaging format, and end-user application dimensions alongside agro-ecological zone altitude bands. CAGRs derived from trend extrapolation of historical export volumes and domestic consumption patterns, with inputs from National Water Authority infrastructure investment pipelines and EU retailer sourcing commitments.
The analysis sits within stated boundaries; outcomes outside sustained solar irrigation financing availability and stable fertilizer import channels would require recalibration. Forecasts reflect assumptions regarding GLOBALG.A.P. audit cycle completion rates and Beitbridge cold chain capacity expansion timelines. Practitioners should keep alternative scenarios live as National Water Authority allocation rulings and EU maximum residue limit revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Sweet Potatoes Market
Vegetables
North America Christmas Tree Market
Vegetables
Tomato Market
Vegetables
Tanzania Fruit and Vegetables Market
Vegetables
Yam Products Market
Vegetables
Europe Flowers and Ornamental Plants Market
Vegetables
Japan Greenhouse Horticulture Market
Vegetables
Microgreens Market
Vegetables
Dehydrated Vegetables Market
Vegetables
IQF Vegetables Market
Vegetables
Netherlands Greenhouse Horticulture Market
Vegetables
Greenhouse Bell Pepper Market
Vegetables
Hydroponic Vegetable Market
Vegetables
Australia Greenhouse Horticulture Market
Vegetables
Field Peas Market
Vegetables
Cameroon Fruits and Vegetables Market