
 Asia-Pacific Peas Market | 2026-2036
Asia-Pacific Peas Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Peas Market Outlook
Precision fermentation and enzymatic fractionation is reconfiguring how pea protein concentrates achieve functional parity with animal-derived alternatives. Cargill, Incorporated leverages its integrated oilseed infrastructure to secure origination advantages across Australian and Indian growing regions. Roquette Frères anchors its position through proprietary wet-fractionation technology that yields higher-protein isolates from yellow pea varieties. Shandong Jianyuan Foods Co., Ltd. dominates domestic Chinese supply through backward integration into contract farming networks in Hebei and Shandong provinces.
Peas are leguminous seeds of Pisum sativum containing approximately 20-25% protein by dry weight, with yellow peas typically yielding higher starch content and green peas offering superior flavor profiles for whole-food applications. The crop undergoes dry or wet milling to produce flours, starches, fibers, and protein isolates used in meat analogues, bakery formulations, and nutritional supplements. Yellow peas lead volume throughput due to their processing efficiency and neutral flavor, while frozen peas command premium positioning in retail channels across Japan and South Korea. Online retailers represent the fastest-growing distribution vector as direct-to-consumer protein brands bypass traditional wholesale tiers.
China's SAMR enforces GB standards for plant protein labeling and additive thresholds that determine market access for imported concentrates. Australia's TGA and FSANZ jointly regulate novel protein health claims, creating compliance complexity for functional ingredient suppliers. India's FSSAI mandates fortification guidelines that shape pea protein inclusion rates in processed foods. Stakeholders must monitor how evolving carbon accounting rules across these jurisdictions will redefine cost structures for regionally sourced versus imported pea derivatives.
Market Dynamics
China's dual carbon goals are compressing cultivation cost structures across the Asia-Pacific Peas Market, forcing processors to reconfigure supply chains around carbon-accounted origination while food manufacturers accelerate reformulation timelines for plant-based protein integration.
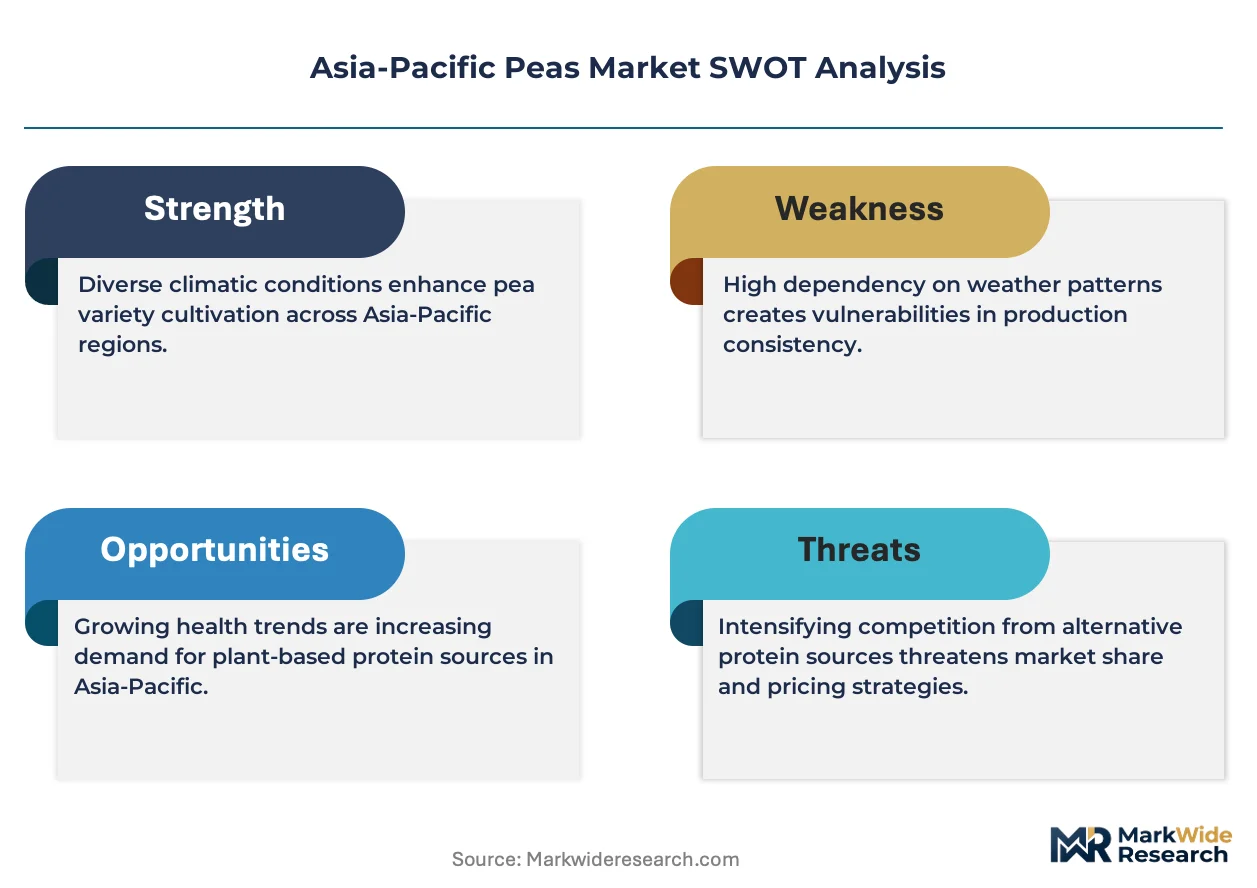
Growth Catalysts
- Carbon-efficient cultivation mandates:China's MEE enforcement of dual carbon goals is redirecting procurement toward verified low-emission growing regions, creating preferential market access for compliant suppliers.
- Meat analogue formulation demand:Food processing industries across Japan and South Korea are expanding pea protein isolate inclusion rates in burger patties and sausage applications.
- Precision fermentation advancement:Enzymatic fractionation technologies are improving protein yield efficiency from yellow pea varieties, reducing unit costs for isolate production.
Market Restraints
- Input cost volatility:Natural gas prices for wet-milling thermal processes fluctuate with regional energy markets, compressing margin predictability for starch and fiber co-products.
- Supply concentration risk:Shandong Province dominates China's protein extraction capacity, creating single-point vulnerability for port-accessible concentrate supply.
- Regulatory friction:Australia's TGA and FSANZ joint oversight of novel protein health claims imposes dual compliance burdens on functional ingredient suppliers seeking market entry.
Strategic Opportunities
- Underpenetrated Southeast Asian markets:Vietnam and Indonesia lack domestic protein isolation infrastructure, creating import substitution potential for established Australian and Chinese processors.
- Regulatory tailwind from fortification mandates:India's FSSAI fortification guidelines are embedding pea protein into government-sponsored nutrition programs, institutionalizing volume offtake.
- Direct-to-consumer channel innovation:Online retailers are bypassing traditional wholesale tiers, enabling specialty protein brands to capture margin previously allocated to distributor networks.
Industry Challenges
- Specialized technician scarcity:Wet-fractionation facility operations require skilled enzymatic process engineers, with training pipelines lagging capacity expansion timelines in Hebei and Shandong provinces.
- Certification timeline compression:GB standard compliance verification through China's SAMR is extending product registration cycles for imported concentrates, delaying revenue recognition.
- Legacy equipment integration:Retrofitting oilseed processing infrastructure for pea protein extraction demands capital reconfiguration without guaranteed throughput equivalence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Peas Market |
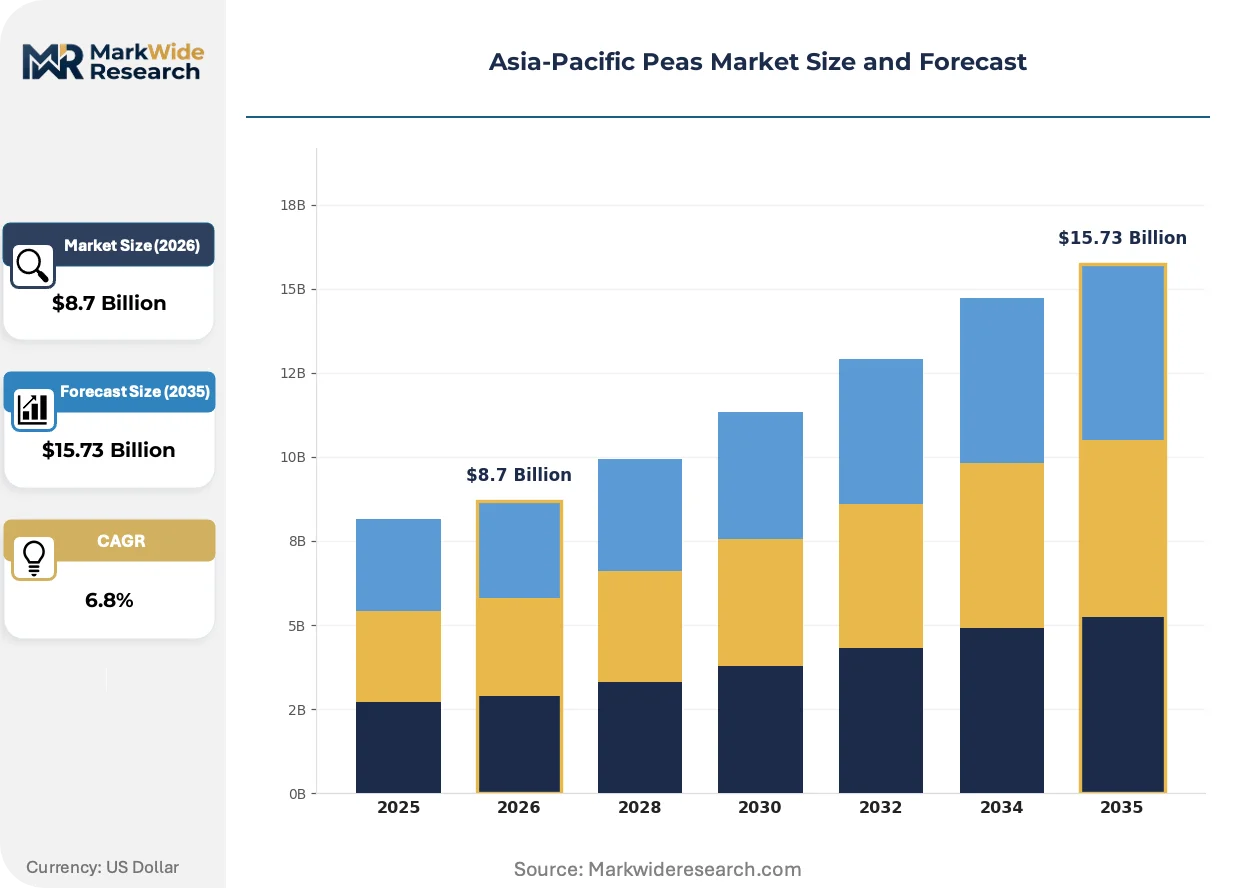
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Peas, Yellow Peas, Split Peas, Frozen Peas End User: Food Processing, Snacks, Frozen Foods, Canned Foods Distribution Channel: Supermarkets, Online Retailers, Wholesalers, Specialty Stores Packaging Type: Bags, Cans, Boxes, Pouches |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland Company, Ingredion Incorporated, Kerry Group PLC, Roquette Frères, Shandong Jianyuan Foods Co., Ltd., Yantai Oriental Protein Tech, Co., Ltd., AGT Food and Ingredients, Golden Grain Mills, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Peas Market Strategic Shifts
Functional parity between plant-derived and animal-derived proteins is accelerating processing technology investment, while regulatory carbon accounting and distribution disintermediation reshape competitive positioning across the region.
Enzymatic fractionation is collapsing the functional performance gap between pea protein isolates and dairy-derived caseinates. Meat analogue manufacturers in South Korea and Japan are adopting these isolates at compressed reformulation cycles. The technology is collapsing premium pricing tiers that previously separated plant-based from animal-based ingredient categories.
China's SAMR enforcement of GB standards for plant protein labeling is tightening additive threshold compliance. Imported concentrates face expanded testing protocols for heavy metal and microbiological contaminants. Functional ingredient suppliers are responding by pre-certifying production batches through third-party laboratories before customs submission.
Direct procurement from extraction facilities is displacing traditional distributor intermediation. Food manufacturers in eastern China's coastal cities are establishing supply agreements directly with Shandong-based processors, eliminating wholesale markups. This pattern is most visible in bakery and nutritional supplement verticals where formulation consistency demands batch-level traceability.
Asia-Pacific Peas Market Segmentation
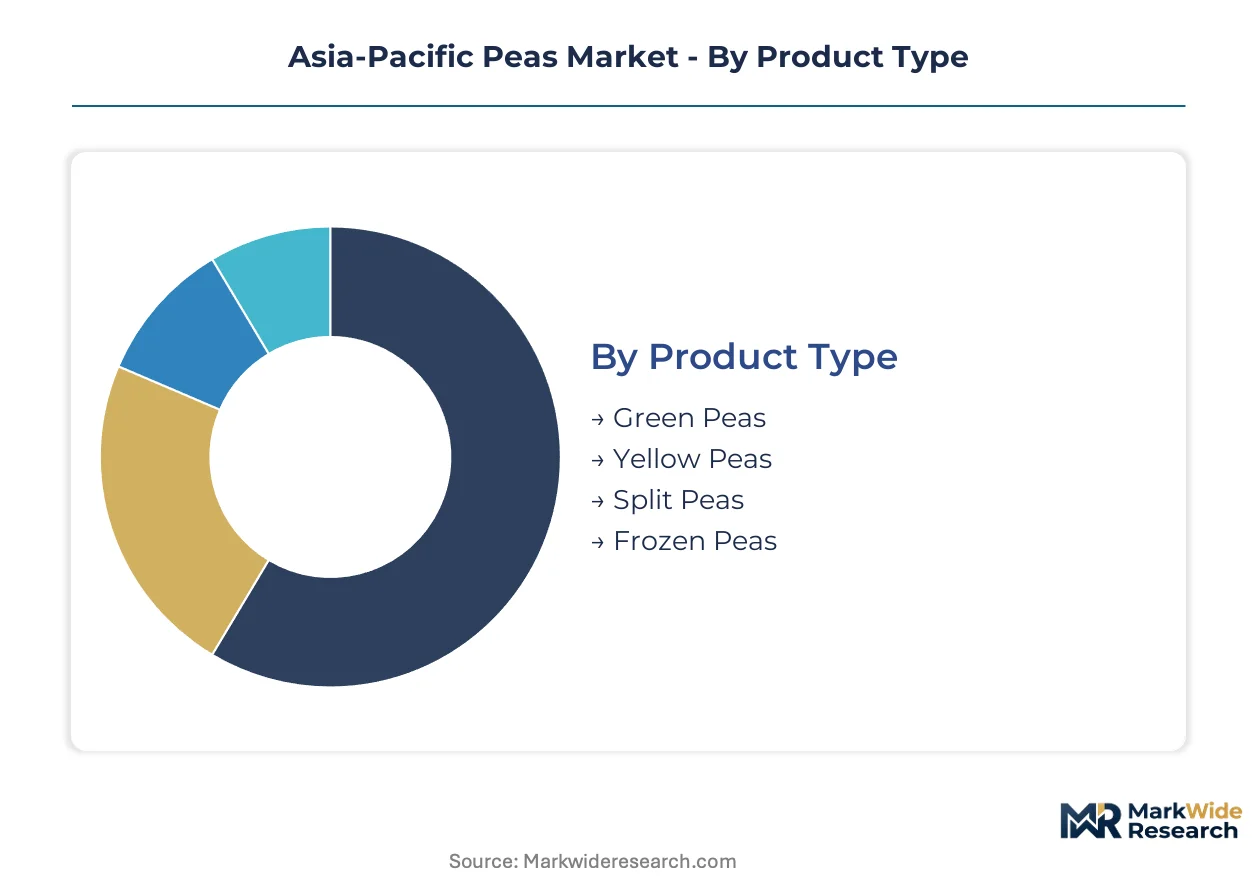
Pea derivatives flow through distinct processing tiers and channel structures that determine margin capture and formulation access. Segment boundaries reflect where protein extraction technology diverges from whole-food retail positioning across the Asia-Pacific supply base.
Product Type:
Cycle times vary sharply: protein isolates turn inventory weekly for industrial buyers while frozen retail packs sit in cold storage for months. Yellow peas move fastest through wet-milling facilities.
- Yellow Peas:Higher starch content and neutral flavor profile enable efficient wet-fractionation processing into protein isolates and starches. Demand concentrates in Shandong Province extraction facilities supplying meat analogue manufacturers across eastern China's coastal cities, driven by carbon-accounted procurement mandates from food processors seeking dual carbon compliance.
- Green Peas:Superior flavor characteristics command premium positioning in whole-food applications and frozen retail channels. Procurement concentrates in Japan and South Korea retail markets where consumer preference for intact seed texture supports frozen pea premiums, constrained by limited domestic cultivation and import dependency.
- Split Peas:Dehulled and fractured seeds accelerate cooking time for soup and dal applications across Indian subcontinent food service.
- Frozen Peas:Blanching and rapid freezing preserves cellular structure for retail and foodservice channels requiring minimal preparation time.
Yellow peas anchor the volume base while frozen peas gain share at the steepest rate.
End User:
Cost tiers separate commodity ingredient buyers from branded food manufacturers seeking traceability certification.
- Food Processing:Industrial buyers of protein concentrates, starches, and fibers for reformulation into meat analogues, bakery goods, and nutritional supplements. Procurement clusters near Shandong and Hebei province extraction capacity, with formulation demand accelerating from South Korean and Japanese meat analogue producers seeking functional parity with animal proteins.
- Snacks:Roasted, extruded, and puffed pea products targeting protein fortification claims in convenience formats. Manufacturing concentrates in Indian and Chinese contract facilities serving private-label retail programs, constrained by FSSAI and SAMR additive threshold compliance timelines.
- Frozen Foods:Ready-meal and vegetable blend applications requiring consistent pea size grading and blanching specifications.
- Canned Foods:Brined and thermally processed peas for long-shelf-life retail and institutional procurement.
Food processing commands the margin premium while snacks expand most quickly through direct-to-consumer channel disintermediation.
Distribution Channel:
Customer type determines service intensity: industrial buyers demand batch-level documentation while retail channels prioritize shelf velocity.
- Online Retailers:Direct-to-consumer platforms enabling specialty protein brands and frozen pea suppliers to bypass wholesale markups. Growth concentrates in China's tier-one cities and South Korean urban markets where cold-chain logistics maturity supports frozen delivery, driven by formulation-consistent brands seeking traceability documentation unavailable through traditional tiers.
- Supermarkets:Multi-format retail chains dominating frozen and canned pea volume through private-label and branded placement. Procurement concentrates in Japan's consolidated retail sector and Australia's supermarket duopoly, constrained by slotting fee structures and seasonal promotional calendars.
- Wholesalers:Traditional intermediaries serving foodservice and smaller retail accounts with bulk breaking and credit terms.
- Specialty Stores:Health food and organic channels targeting certified non-GMO and carbon-labeled pea derivatives.
Supermarkets retain the volume base while online retailers climb the fastest through disintermediation of protein concentrate procurement.
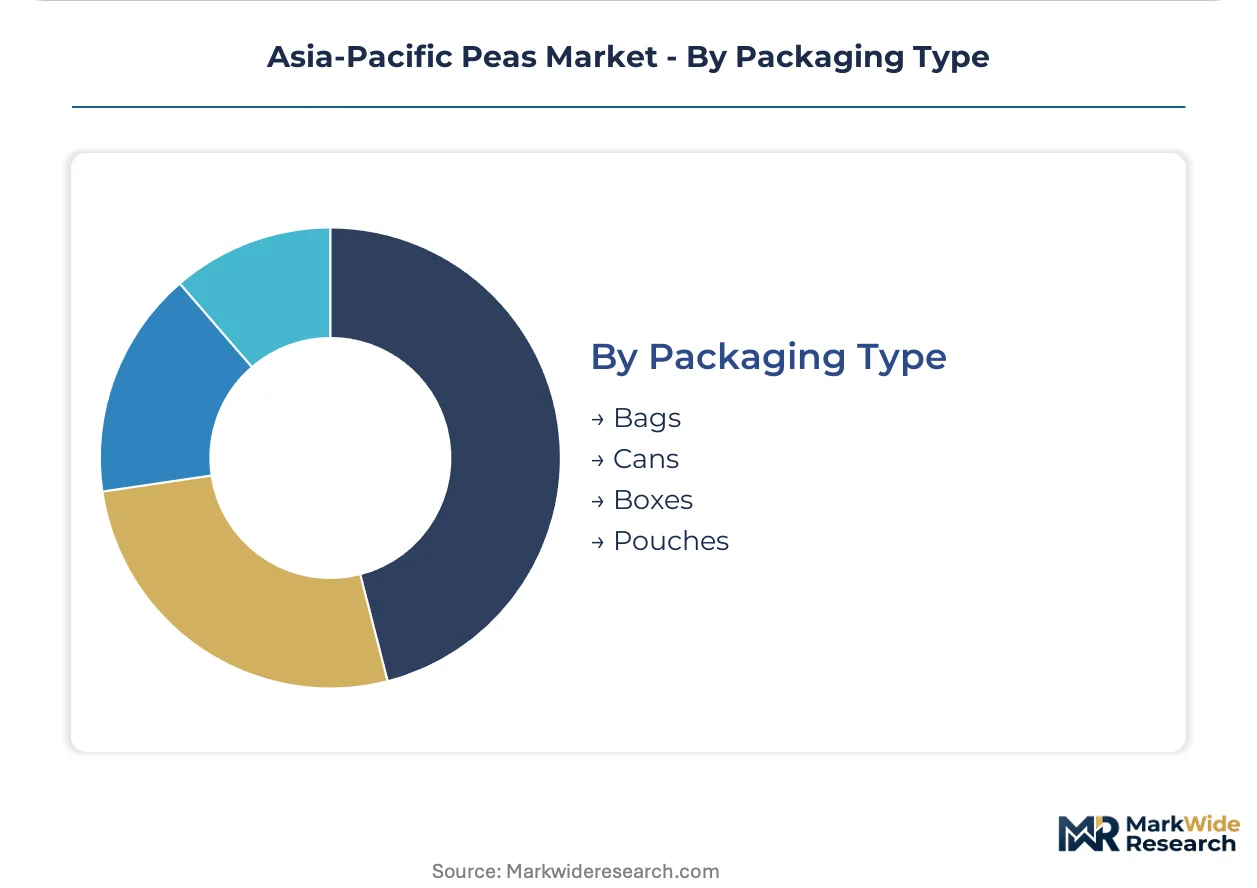
Packaging Type:
Supply concentration in flexible packaging versus rigid formats reflects cold-chain requirements and shelf-life extension needs.
- Pouches:Flexible laminated structures with modified atmosphere capabilities for protein concentrate and frozen pea applications. Adoption concentrates in Australian and Chinese export-oriented processing facilities seeking lightweight shipping economics, driven by maritime freight cost sensitivity and retail shelf-space efficiency demands.
- Bags:Woven polypropylene and paper-based formats for bulk ingredient and dried pea distribution. Procurement dominates Indian and Chinese domestic supply chains where cost minimization outweighs shelf-life extension requirements.
- Cans:Tinplate and aluminum rigid containers for thermally processed shelf-stable peas.
- Boxes:Corrugated and folding carton formats for retail-ready multi-unit presentation.
Bags dominate tonnage throughput while pouches expand most quickly through export-oriented protein isolate shipping.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian processors export pea protein isolates to Japanese and South Korean meat analogue manufacturers, establishing a carbon-accounted trade corridor that bypasses Chinese port congestion for premium formulations.
China
Shandong Province anchors regional protein extraction capacity with wet-fractionation facilities clustered near Qingdao port infrastructure. SAMR enforces GB standards for plant protein labeling that determine market access for imported concentrates. Hebei and Shandong contract farming networks supply backward-integrated processors serving eastern coastal food manufacturers.
Japan
Meat analogue producers in the Kanto region accelerate pea protein isolate inclusion rates in burger patties and sausage applications. METI oversees food additive thresholds through the Food Sanitation Act. Tokyo-Osaka logistics corridors distribute frozen pea retail packs through consolidated supermarket channels.
South Korea
Urban consumers in Seoul and Busan drive direct-to-consumer protein brand growth through mature cold-chain delivery infrastructure. MFDS regulates novel protein health claims that shape functional ingredient market entry. Gyeonggi Province food technology clusters reformulate plant-based products for functional parity with animal proteins.
India
FSSAI fortification guidelines embed pea protein into government-sponsored nutrition programs across Maharashtra and Gujarat. The regulator mandates inclusion rates that institutionalize volume offtake from domestic processors. Mumbai and Ahmedabad serve as distribution hubs for split pea dal and snack manufacturing.
Australia
TGA and FSANZ jointly oversee novel protein health claims, creating compliance complexity for functional ingredient suppliers. Sustainable agriculture standards tighten supply chain requirements for carbon-efficient cultivation. Victorian and New South Wales growing regions supply export-oriented isolate production for Northeast Asian buyers.
Asia-Pacific Peas Market Competitive Environment
On the supply side, the industry is consolidating around integrated oilseed processors and specialized wet-fractionation operators with proprietary extraction technology. Three strategic archetypes dominate: multinational agribusiness conglomerates with origination infrastructure, regional specialists with backward-integrated contract farming networks, and technology-focused isolators with enzymatic fractionation capabilities. Capacity expansion and direct procurement partnerships represent the dominant competitive moves as processors bypass wholesale intermediaries.
Among multinational agribusiness conglomerates, Cargill, Incorporated exemplifies the integrated origination archetype with Australian and Indian growing region presence. Roquette Frères occupies the technology-specialist tier through proprietary wet-fractionation capabilities. Shandong Jianyuan Foods Co., Ltd. represents the regional backward-integrated model with Hebei and Shandong province contract farming control.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| Kerry Group PLC |
| Roquette Frères |
| Shandong Jianyuan Foods Co., Ltd. |
| Yantai Oriental Protein Tech, Co., Ltd. |
| AGT Food and Ingredients |
| Golden Grain Mills |
| Others |
Value Chain & Pricing Dynamics
Qingdao-Port Shanghai freight corridors transmit cost volatility directly into protein concentrate premiums, with carbon-accounted origination from Shandong Province commanding price separation from uncertified supply while wet-milling energy costs compress margin structures across derivative tiers.
Pricing Analysis
Enzymatic fractionation technology-generation pricing gaps separate legacy dry-milled concentrates from next-generation isolates achieving functional parity with dairy caseinates. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade under China's SAMR GB standards and volume scale for industrial offtake. Pricing pressure stems from natural gas cost compression in thermal wet-milling processes, eroding co-product margin contribution. Food processing buyers exhibit highest price sensitivity due to reformulation volume exposure, while specialty supplement brands absorb premiums for batch-level traceability.
Supply Chain Analysis
Yellow pea feedstock supply concentrates in Hebei and Shandong provinces, with Australian Victorian growing regions and Indian Maharashtra fields providing secondary origination. Wet-fractionation capacity draws from natural gas inputs, enzymatic processing agents, and port-accessible logistics infrastructure. Single-source vulnerability concentrates in Shandong Province extraction facilities, creating chokepoint exposure for Northeast Asian meat analogue manufacturers. Distribution runs through direct procurement agreements between processors and coastal Chinese food manufacturers, bypassing traditional wholesale intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as carbon-accounting requirements splinter procurement pools and direct-to-consumer channels displace consolidated retail distribution across the Asia-Pacific Peas Market.
For Market Incumbents: Harden supply security through backward integration into Hebei contract farming networks and pre-certification investment for SAMR GB standard compliance. Wet-fractionation capacity expansion in alternative port-accessible locations mitigates Shandong concentration risk. Enzymatic process engineer training pipelines address specialized technician scarcity threatening throughput scaling. For New Entrants and Emerging Players: Establish a beachhead in Vietnam and Indonesia import substitution demand where domestic protein isolation infrastructure remains absent. Southeast Asian meat analogue manufacturing growth offers formulation partnership entry points. Direct-to-consumer protein brand positioning through mature cold-chain logistics in South Korean urban markets enables margin capture unavailable through wholesale channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors wet-fractionation specialists with proprietary enzymatic yield advantages over commodity dry-milling operators. Long-term viability rests on carbon-accounted supply chain integration and regulatory pre-certification capabilities. Watch for SAMR enforcement intensity on imported concentrate testing protocols as inflection signal for compliance-cost barrier elevation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contract Farming | Secures carbon-accounted origination for SAMR compliance and isolates supply from port congestion. |
| Enzymatic Fractionation Capacity Expansion | Captures functional parity premiums from South Korean and Japanese meat analogue manufacturers. |
| Direct Procurement Partnership Establishment | Eliminates wholesale markups for Shandong-based processors serving eastern coastal food manufacturers. |
| Pre-Certification Laboratory Investment | Compresses SAMR registration cycles for imported concentrates facing expanded contaminant testing. |
| Southeast Asian Distribution Infrastructure | Addresses Vietnam and Indonesia import substitution demand lacking domestic isolation capacity. |
Study Parameters
Desk research of customs trade databases, FSSAI fortification guidelines, and SAMR GB standard filings preceded structured interviews with wet-fractionation plant managers, protein procurement leads at meat analogue manufacturers, and cold-chain logistics operators across China, Japan, and South Korea. Primary fieldwork with enzymatic process engineers and contract farming coordinators in Hebei and Shandong provinces combined with secondary validation from AGT Food and Ingredients and Roquette Frères public disclosures. Bottom-up volume modeling from extraction facility throughput and top-down demand estimation from food processing reformulation rates were triangulated for convergence.
Assumptions held carbon-accounting enforcement intensity and natural gas pricing within historical bands while varying meat analogue adoption velocity and direct-to-consumer channel penetration across the projection horizon. Segmentation modeling tracked product type, end-use industry, and distribution channel dimensions with regional regulatory cluster differentiation. CAGRs were derived from fitted growth curves against protein isolate inclusion rate trajectories in Japanese and South Korean food manufacturing, with enzymatic yield efficiency improvement curves and cold-chain logistics maturity indices as industry-specific inputs.
Stress conditions across MEE dual carbon enforcement intensity, natural gas price volatility, and SAMR testing protocol expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about regulatory trajectory and technology diffusion that could revise with unexpected policy shifts or breakthrough alternative protein platforms. Cross-checking against FSSAI fortification program budget allocations and METI food technology cluster investment disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Australia Greenhouse Horticulture Market
Vegetables
IQF Vegetables Market
Vegetables
Tanzania Fruit and Vegetables Market
Vegetables
United States Microgreens Market
Vegetables
Yarrow Market
Vegetables
North America Peas Market
Vegetables
Cameroon Fruits and Vegetables Market
Vegetables
North America Microgreens Market
Vegetables
India Greenhouse Horticulture Market
Vegetables
Zimbabwe Fruits and Vegetables Market
Vegetables
Global Indoor Plant Market
Vegetables
Sweet Potatoes Market
Vegetables
Dried Vegetable Market
Vegetables
Japan Greenhouse Horticulture Market
Vegetables
Greenhouse Produce Market
Vegetables
Fresh Mushroom Market