
 Battery Powered Cultivators Market | 2026-2036
Battery Powered Cultivators Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Powered Cultivators Market Insights
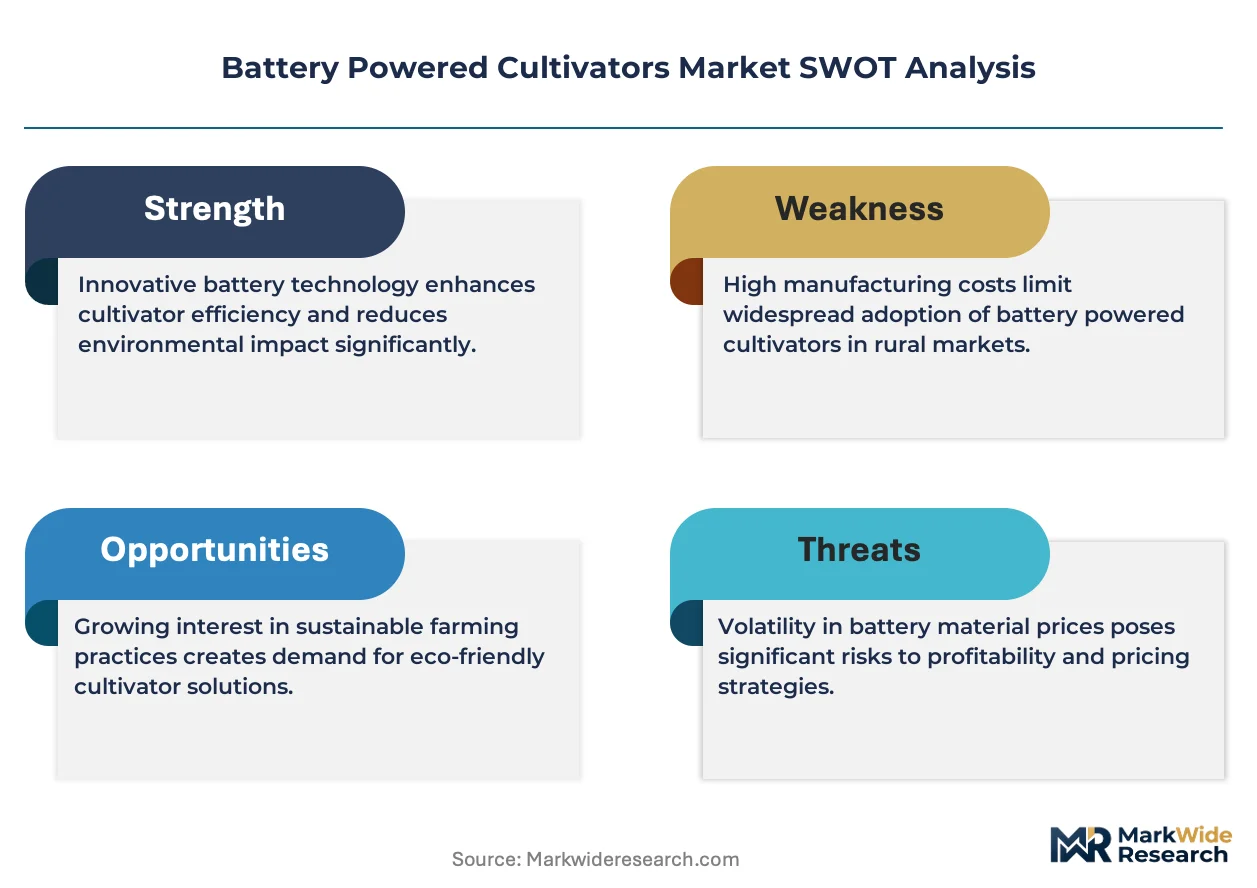
UL 2595 certification for battery-operated garden appliances is unwinding competitive access for smaller overseas manufacturers. Greenworks leverages in-house battery platform development to sustain price competitiveness across North American retail channels. Ryobi anchors its position through proprietary ONE+ battery compatibility that locks homeowners into an expanding tool ecosystem. Black+Decker competes on brand recognition and mass-market distribution density rather than premium performance specifications.
Battery powered cultivators are motorized soil-tilling machines driven by rechargeable lithium-ion battery packs, typically delivering 20V to 80V outputs with brushless DC motors generating torque between 20 Nm and 100 Nm for breaking compacted earth in residential gardens and commercial plots. Their primary purpose is replacing gasoline two-stroke engines in soil preparation, eliminating exhaust emissions and reducing noise levels below 75 dB for urban and suburban compliance. The cultivators and tillers product category dominates unit volume due to universal applicability in vegetable bed preparation and lawn renovation. Lithium-ion battery technology captures the bulk of value as energy density improvements enable runtime extension from 30 minutes to over 90 minutes per charge. Smart control systems represent the fastest-growing technology segment as torque-sensing microprocessors prevent motor stall and optimize power draw across variable soil conditions.
The EPA enforces Phase 3 emission standards that effectively ban new carbureted two-stroke engines under 19 kW, directly expanding addressable demand for battery alternatives in professional landscaping fleets. California Air Resources Board zero-emission equipment mandates for commercial operators create a regulatory template that Oregon, Washington, and New York are evaluating for adoption. The EU F-Gas Regulation and Machinery Directive 2006/42/EC impose concurrent constraints on engine cooling refrigerants and electrical safety requirements that shape product design priorities for export-oriented manufacturers. Stakeholders must monitor municipal procurement rules and landscaping fleet electrification timelines to align channel investment with the pace of gasoline equipment displacement.
Market Dynamics
EPA Phase 3 emission standards banning new carbureted two-stroke engines under 19 kW are forcing commercial landscaping fleets to electrify soil preparation equipment ahead of scheduled replacement cycles.
Growth Catalysts
- California zero-emission mandates:CARB commercial equipment rules are creating template legislation that Oregon, Washington, and New York evaluate for adoption, expanding regulated demand pools.
- Brushless DC motor efficiency:Torque density improvements in 20V to 80V systems are extending runtime per charge from 30 minutes past 90 minutes, eliminating gasoline range anxiety.
- Residential lawn care electrification:Homeowners represent the fastest-expanding buyer segment as battery-powered lawn mowers normalize complementary garden tool purchases.
Market Restraints
- Lithium-ion cell supply concentration:Cathode material processing and cell manufacturing cluster in China, exposing non-Chinese OEMs to geopolitical supply disruption and input cost volatility.
- UL 2595 certification barriers:North American electrical safety testing requirements impose six-figure compliance costs and 12-18 month approval timelines that exclude smaller overseas manufacturers.
- Gasoline equipment residual value:Professional landscapers face sunk-cost resistance from recently purchased two-stroke tillers with remaining depreciable life, slowing fleet turnover.
Strategic Opportunities
- Municipal procurement electrification:Parks departments in Germany, the United States, and China are specifying battery-powered equipment in RFPs, opening institutional volume channels.
- Torque-sensing microprocessor integration:Smart control systems that prevent motor stall across variable soil conditions represent the fastest-growing technology segment for premium positioning.
- Proprietary battery platform lock-in:Tool ecosystem compatibility creates recurring attachment sales as homeowners expand from cultivators into trimmers, blowers, and chainsaws.
Industry Challenges
- IP licensing complexity:Brushless motor control algorithms and battery management system patents held by power tool incumbents create royalty stacking or exclusion risks for new entrants.
- Field technician retraining:Diagnostic and repair workflows shift from mechanical carburetor adjustment to electrical troubleshooting, requiring upskilling of dealer service departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Powered Cultivators Market |
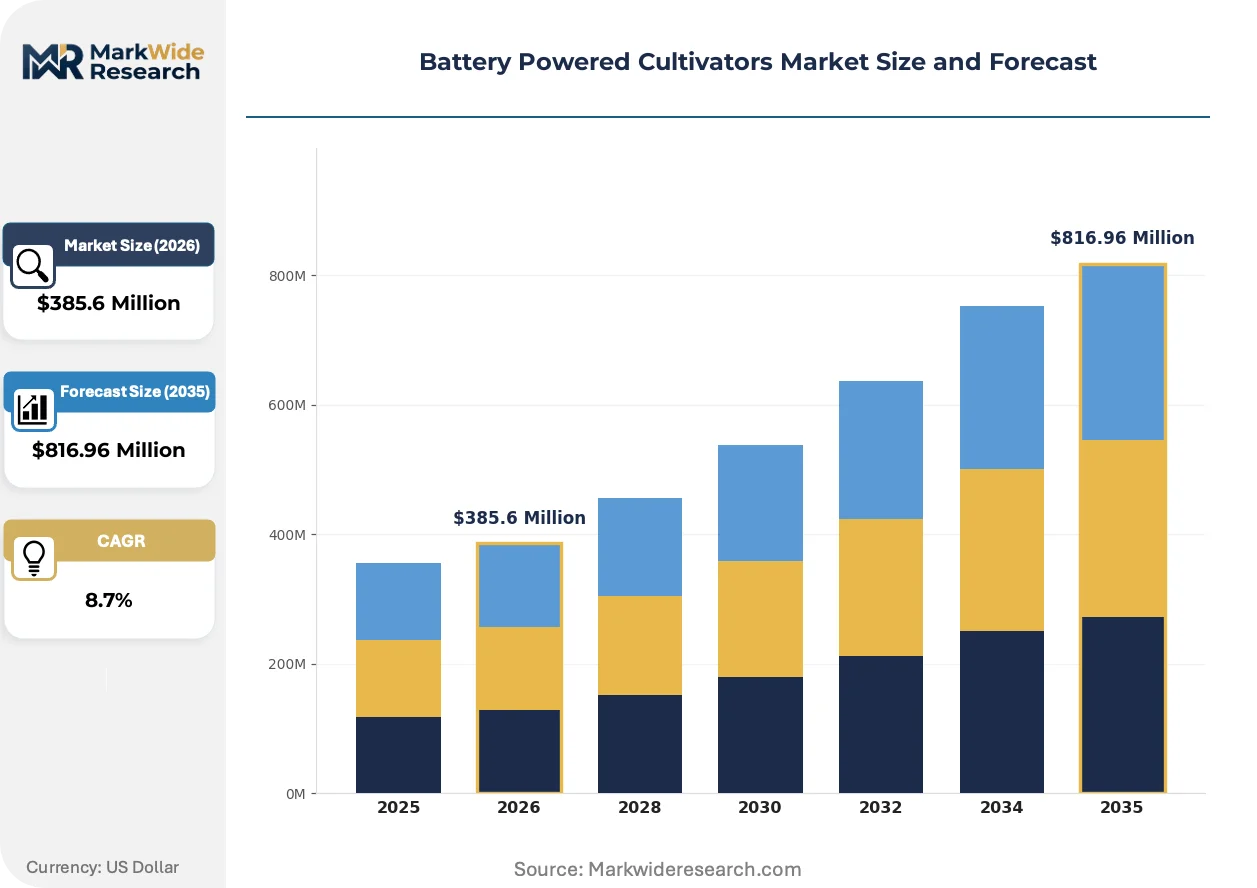
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cultivators, Tillers, Weeders, Trimmers End User: Homeowners, Professional Landscapers, Commercial Growers, Garden Centers Technology: Brushless Motors, Lithium-ion Batteries, Solar Integration, Smart Control Systems Size: Small Scale, Medium Scale, Large Scale, Compact |
| Companies Covered | Greenworks, Ryobi, Black+Decker, MZK, CRAFTSMAN, Earthwise, Sun Joe, Saker, Alloyman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Powered Cultivators Market Trends and Innovations
Electrification is compressing product development cycles as mechanical engineering yields to firmware-driven differentiation, while regulatory mandates accelerate obsolescence of combustion-based designs.
Lithium-ion cell chemistry is miniaturizing energy density improvements that enable equivalent runtime in smaller form factors. Vegetable bed preparation in compact urban gardens drives demand for lighter 20V-class units under 15 kg. This miniaturization is collapsing the traditional trade-off between soil-breaking torque and operator fatigue, opening suburban demographics previously served only by manual tools.
REACH chemical restrictions and EU F-Gas Regulation are constraining refrigerants and lubricants in garden equipment supply chains. Machinery Directive 2006/42/EC electrical safety requirements now govern battery compartment sealing and thermal runaway containment. German manufacturers face dual compliance pressure that shapes R&D prioritization toward fully sealed IP-rated battery enclosures.
Retail channel consolidation is concentrating shelf space decisions among big-box home improvement chains and specialized garden centers. Independent dealers lose floor space as direct-to-consumer brands and house labels capture endcap placement. This shift is most visible in United States suburban markets where homeowners research online but purchase through curbside pickup at physical locations.
Battery Powered Cultivators Market Segmentation
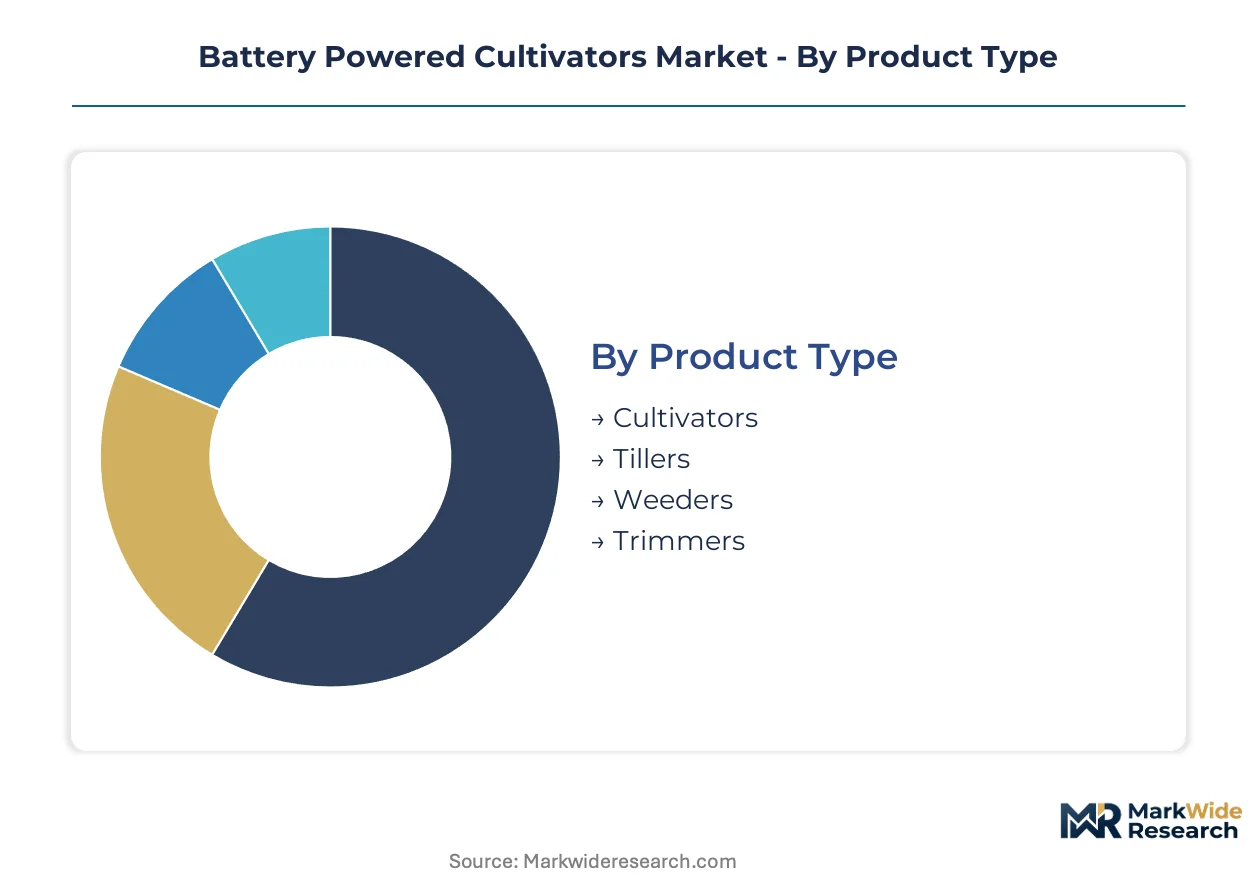
Segmentation in battery powered cultivators reveals how electrification is fragmenting a once-uniform gasoline market into distinct performance tiers and buyer ecosystems. Each dimension—product architecture, user sophistication, powertrain technology, and physical scale—carries different margin structures and competitive dynamics.
Product Type:
Margin pools concentrate in equipment that handles the heaviest soil-breaking workloads while maintaining battery efficiency.
- Cultivators:These machines deliver 20 Nm to 60 Nm torque through counter-rotating tines for shallow soil mixing in established beds. Demand clusters in United States suburban markets where homeowners renovate lawns without disturbing mature root systems. EPA Phase 3 standards are accelerating fleet turnover among municipal parks departments specifying cultivators for median maintenance.
- Tillers:Front-tine and rear-tine configurations generate 60 Nm to 100 Nm torque for primary soil breaking in new vegetable plots. Professional landscapers in Germany and China represent the fastest-expanding demand pool as these operators face tightening emission enforcement and diesel equipment bans.
- Weeders:Lightweight units under 10 kg target precision cultivation between crop rows.
- Trimmers:Dual-purpose tools combine edging functions with shallow cultivation for ornamental beds.
The dominant share belongs to Tillers, while Cultivators are closing the gap fastest through residential electrification momentum.
End User:
Volume splits sharply between price-sensitive residential buyers and durability-focused commercial operators with diverging replacement cycles.
- Homeowners:This segment purchases 20V to 40V class equipment through retail channels, prioritizing weight reduction and ecosystem compatibility over runtime extension. California zero-emission mandates are normalizing battery purchases among suburban households previously loyal to gasoline convenience.
- Professional Landscapers:Fleet operators demand 80V systems with swappable battery packs and IP-rated enclosures for all-weather deployment. Oregon and Washington are evaluating CARB-style commercial equipment rules that would mandate electrification timelines for landscaping contractors.
- Commercial Growers:Agricultural-scale operations require tillage width exceeding 60 cm for field preparation.
- Garden Centers:Institutional buyers specify equipment for demonstration plots and customer rental fleets.
Professional Landscapers command premium pricing, yet Homeowners are expanding most quickly as complementary lawn tool purchases accelerate.
Technology:
Patent density and component cost structures determine which technology layers capture value versus becoming commoditized.
- Brushless Motors:Electronically commutated designs eliminate brush friction losses, delivering 85% to 92% efficiency versus 75% for brushed alternatives. German manufacturers lead in integrated motor-drive systems that meet Machinery Directive 2006/42/EC thermal protection requirements.
- Lithium-ion Batteries:Cell chemistry improvements in nickel-manganese-cobalt and lithium-iron-phosphate formulations are extending cycle life beyond 1,000 charges. Supply concentration in Chinese cathode processing creates input cost volatility for non-Chinese OEMs.
- Solar Integration:Panel-integrated charging stations target off-grid agricultural applications.
- Smart Control Systems:Torque-sensing microprocessors adjust power draw based on soil resistance feedback.
Lithium-ion Batteries retain the largest value share, though Smart Control Systems are climbing the fastest as firmware becomes the primary differentiation vector.
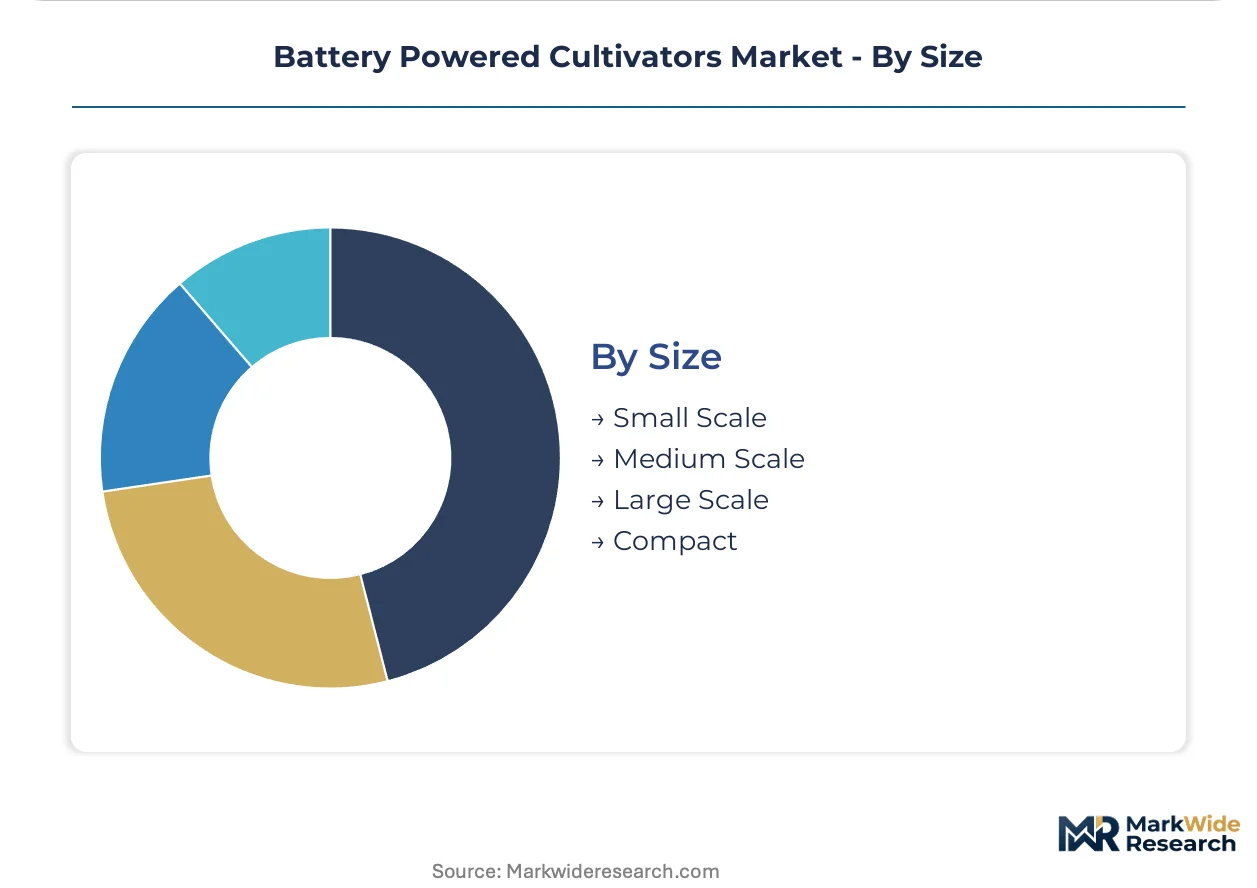
Size:
Physical scale directly maps to application intensity and corresponding battery capacity requirements.
- Small Scale:Units under 15 kg with 20V batteries suit balcony gardens and raised bed maintenance in dense urban environments. REACH chemical restrictions are driving demand for fully sealed battery enclosures that eliminate lubricant exposure.
- Medium Scale:40V to 60V systems between 15 kg and 25 kg balance runtime with maneuverability for suburban plots. United States big-box retailers concentrate shelf space in this tier as the default homeowner purchase.
- Large Scale:Self-propelled units exceeding 25 kg with dual battery bays serve commercial cultivation.
- Compact:Collapsible designs with detachable handles target storage-constrained apartments.
Medium Scale equipment holds the volume advantage, while Small Scale configurations are gaining share fastest through urban gardening expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional landscaping fleets and suburban homeowners concentrate demand in jurisdictions with aggressive emission enforcement. Battery manufacturing investments and municipal electrification mandates determine competitive access across national markets.
United States
Homeowners in suburban markets drive residential electrification as complementary lawn tool purchases normalize battery platforms. EPA Phase 3 standards banning carbureted two-stroke engines under 19 kW force commercial fleet turnover ahead of replacement cycles. California's zero-emission mandates for commercial operators create template legislation that Oregon, Washington, and New York evaluate for adoption.
Germany
Machinery Directive 2006/42/EC and REACH chemical restrictions constrain refrigerants and lubricants in garden equipment supply chains. Professional landscapers face tightening diesel equipment bans that accelerate demand for 80V battery systems with swappable packs. Industrial clusters in Baden-Württemberg and Bavaria concentrate R&D for IP-rated battery enclosures meeting dual compliance pressure.
China
Cathode material processing and cell manufacturing clusters expose non-Chinese OEMs to supply concentration risks while domestic brands capture cost advantages. Municipal parks departments in Beijing and Shanghai specify battery-powered equipment in procurement RFPs. Yangtze River Delta manufacturing hubs scale lithium-ion cell production for export-oriented garden tool electrification.
Japan
METI efficiency standards and JIS certification requirements shape product design priorities for precision cultivation tools in compact urban gardens. Kanto region homeowners demand lightweight 20V-class units under 15 kg for balcony and raised bed maintenance. Tokyo metropolitan regulations on noise and emissions accelerate displacement of gasoline equipment in dense residential zones.
Battery Powered Cultivators Market Competitive Landscape
Player mix skews toward power tool incumbents with established battery ecosystems and retail channel dominance. The vendor base concentrates around three strategic tiers: premium performance specialists leveraging proprietary motor control, mass-market brands competing on ecosystem lock-in, and value-oriented assemblers sourcing standardized cell packs. Dominant competitive moves include portfolio diversification into adjacent garden tools and geographic expansion through big-box retail partnerships.
Among North American power tool specialists, Greenworks and Ryobi anchor the ecosystem-driven tier, while Black+Decker occupies a position within the mass-market recognition segment. Greenworks exemplifies in-house battery platform development sustaining price competitiveness across retail channels. Ryobi represents proprietary battery compatibility strategies that lock homeowners into expanding tool ecosystems. Black+Decker sits within the brand-recognition archetype competing on distribution density rather than premium specifications.
| Leading Market Players |
|---|
| Greenworks |
| Ryobi |
| Black+Decker |
| MZK |
| CRAFTSMAN |
| Earthwise |
| Sun Joe |
| Saker |
| Alloyman |
| Others |
Pricing and Supply Chain Analysis
Lithium-ion cell chemistry substitution for nickel-cadmium and lead-acid alternatives simultaneously relocates cathode processing toward China's Yangtze River Delta and compresses battery pack costs by eliminating heavy metal toxicity compliance overhead. This chemistry transition concentrates pricing power among cell manufacturers with integrated cathode capacity while forcing OEMs to absorb volatility through contract structures.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate procurement between OEMs and cell suppliers, insulating manufacturers from cathode material swings while compressing margins during commodity spikes. Price differentiation rests on UL 2595 certification tier and brushless motor integration depth, with California zero-emission mandates intensifying cost compression in mid-tier 40V systems. Professional landscapers exhibit lowest price sensitivity due to fleet amortization schedules, while suburban homeowners purchasing first-time units drive volume through promotional bundling.
Supply Chain Analysis
Strategic stockpiling of lithium hydroxide and nickel-manganese-cobalt precursors characterizes procurement behavior among tier-one OEMs, contrasting with just-in-time battery pack assembly favored by value-oriented assemblers. Cathode material processing clusters in China, South Korea, and Japan, with final pack integration drawing from Mexican and Vietnamese contract manufacturers. Single-source vulnerability concentrates in electrolyte additive supply. Distribution runs through big-box home improvement chains and specialized garden centers, with direct-to-consumer channels capturing endcap placement in United States suburban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery powered cultivators represent an early-cycle electrification expansion, with EPA Phase 3 standards and California CARB mandates accelerating displacement of gasoline two-stroke equipment ahead of natural replacement cycles.
For Market Incumbents: Compound ecosystem lock-in through proprietary battery platform expansion into adjacent garden tools including trimmers, blowers, and chainsaws. Defend against emerging direct-to-consumer brands by securing exclusive retail endcap placement at big-box chains. Prioritize in-house brushless motor control algorithm development to reduce IP licensing exposure from power tool patent holders. For New Entrants and Emerging Players: UL 2595 certification fast-track through third-party testing partnerships offers regulatory bypass for overseas manufacturers excluded by six-figure compliance costs and 12-18 month approval timelines. Target the small-scale 20V-class segment for balcony and raised bed maintenance in dense urban Japanese and European markets. Pursue white-label supply agreements with direct-to-consumer brands lacking manufacturing footprint. For Investors and Strategic Acquirers: The market sits at a regulatory-acceleration phase that favors vertically integrated cell-to-tool manufacturers with captive cathode supply. Five-to-ten-year viability hinges on lithium-ion chemistry cost curves and municipal procurement electrification timelines. Monitor Oregon, Washington, and New York legislative evaluations of CARB-style commercial equipment mandates as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Battery Platform Expansion | ONE+ and compatible ecosystems lock homeowners into recurring attachment purchases across tool categories. |
| UL 2595 Certification Investment | Electrical safety approval unlocks North American retail channel access previously blocked to smaller competitors. |
| Brushless DC Motor Integration | Torque density improvements extend runtime past 90 minutes, eliminating gasoline range anxiety in professional fleets. |
| Municipal Procurement Partnership | Parks department RFP specifications in Germany and the United States open institutional volume channels. |
| Smart Control System Development | Torque-sensing microprocessors prevent motor stall and optimize power draw across variable soil conditions. |
Research Methodology
Cross-validation between primary interviews with OEM product managers, battery supply chain directors, and municipal procurement officers anchors the qualitative findings against secondary validation from EPA regulatory filings, CARB rulemaking dockets, and Machinery Directive 2006/42/EC implementation guidance. Bottom-up unit shipment estimates triangulate with top-down value projections derived from retail channel sell-through data and lithium-ion cell production disclosures.
Sensitivity analysis across variable adoption rates for zero-emission mandates and lithium carbonate price trajectories informs the projection framework. Segmentation dimensions include product architecture, end-user sophistication, powertrain technology, and physical scale, with CAGRs derived from regression against historical electrification patterns in adjacent lawn equipment categories. Brushless motor efficiency curves and battery energy density improvement timelines constitute industry-specific forecast inputs.
Underlying assumptions cover regulatory enforcement continuity, cathode material supply stability, and retail channel consolidation pace, with deviation risk concentrated in geopolitical disruption to Chinese cell manufacturing and delayed state-level adoption of California emission templates. Revision becomes warranted when municipal electrification procurement timelines or lithium-ion chemistry substitution rates cross threshold acceleration points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Equipment
Farm Equipment Market
Agricultural Equipment
Agricultural Rake Market
Agricultural Equipment
Soil Aerators Market
Agricultural Equipment
Heavy Tooth Drag Harrows Market
Agricultural Equipment
Agriculture Evaporative Cooling Pad Market
Agricultural Equipment
Plucker Machine Market
Agricultural Equipment
Oil Expellers Market
Agricultural Equipment
Agriculture Seeder Market
Agricultural Equipment
Agricultural Pumps Market
Agricultural Equipment
Commercial Grain Mill Market
Agricultural Equipment
Cotton Picker Market
Agricultural Equipment
Lawn Shredder Market
Agricultural Equipment
Forestry Equipment Market
Agricultural Equipment
Israel Agriculture Market
Agricultural Equipment
Garden Tools Market
Agricultural Equipment
Pistol Grip Sprayer Market