
 Dry Onion Market | 2026-2036
Dry Onion Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Onion Market Analysis
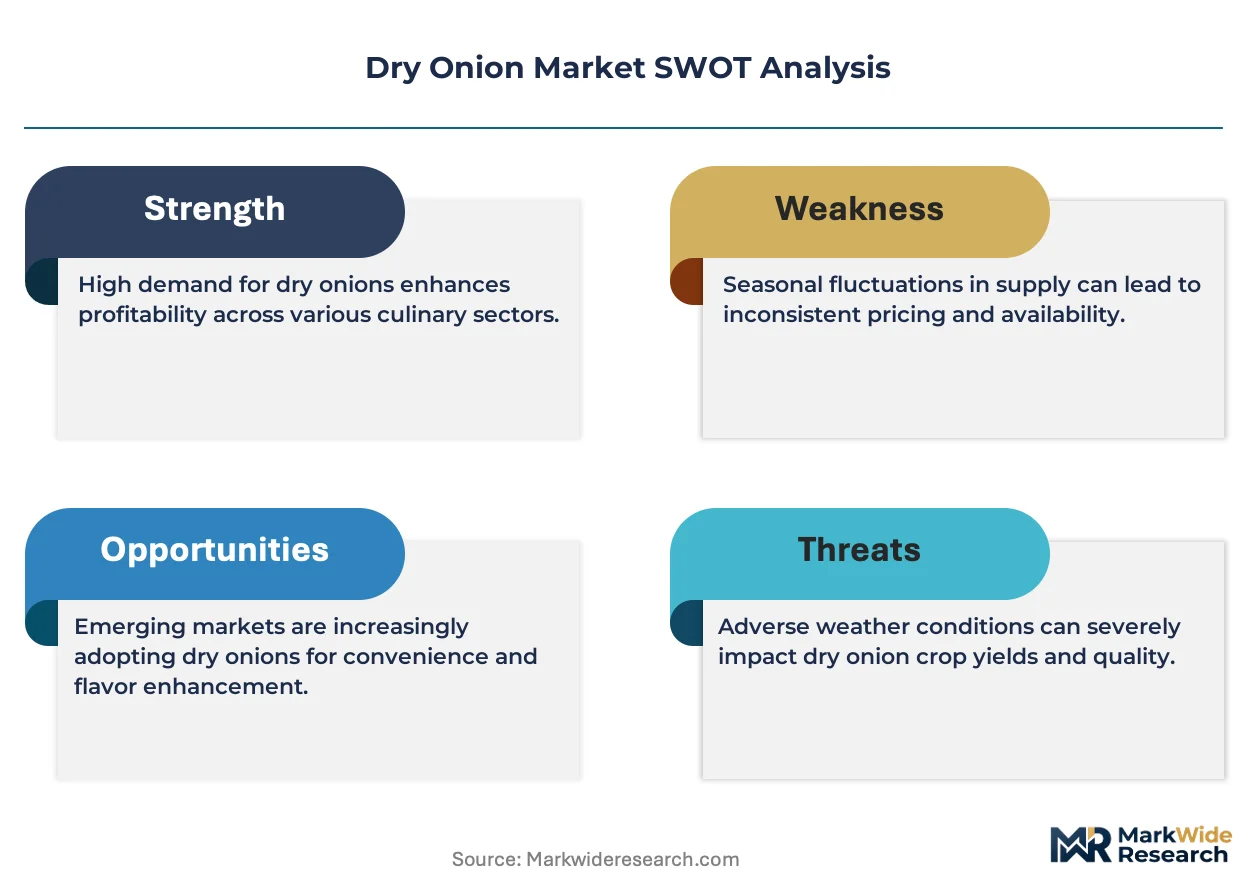
Indian dehydrators is broadening flake and granule output to serve European seasoning houses. Olam Food Ingredients leverages integrated sourcing from Gujarat and Maharashtra to sustain year-round supply consistency. Jain Farm Fresh Foods Limited anchors domestic retail distribution while extending cold-chain infrastructure into processing corridors.
Dry onion comprises Allium cepa bulbs dehydrated to moisture levels below 7 percent through air-drying or freeze-drying, yielding shelf-stable products for flavor delivery in processed foods. Dehydrated onion and onion powder command the largest volume share within product type categories, reflecting food manufacturers' preference for standardized flavor dosing. Onion flakes and granules capture faster growth in seasoning and soups applications, where visible texture and controlled rehydration properties command premium positioning.
India's FSSAI mandates pesticide residue limits and hygiene protocols for dehydrated vegetable exports, while the EU's REACH and EFSA mycotoxin standards filter market access for non-compliant processors. The USDA and FDA oversee import inspections and labeling requirements that shape North American trade flows. Stakeholders must monitor evolving allergen declaration rules and carbon footprint disclosure mandates that are beginning to influence procurement decisions across European and North American buying desks.
Market Dynamics
Food manufacturers' procurement consolidation around dehydrated onion formats is compressing supplier margins while elevating quality certification requirements across the value chain. This buyer-side concentration forces processors to invest in automated sorting and mycotoxin testing infrastructure to retain contract eligibility.
Growth Catalysts
- EU Mycotoxin Standards:EFSA's strict aflatoxin and ochratoxin limits for dehydrated vegetables are filtering out non-compliant processors in India and Egypt, creating volume capture opportunities for certified facilities in Gujarat and Maharashtra.
- Ready-Meal Manufacturing:European and North American food manufacturers are standardizing onion powder inclusion rates across soup, sauce, and seasoning formulations to ensure flavor consistency at scale.
- Solar Drying Adoption:Indian processors in Nashik and Indore are deploying solar-assisted dehydration tunnels to reduce natural gas dependence and stabilize operating costs during monsoon seasons.
Market Restraints
- Fresh Onion Price Volatility:Input costs fluctuate with Maharashtra and Karnataka harvest cycles, compressing dehydrator margins during off-season procurement windows.
- Supply Concentration Risk:Gujarat's Kutch district and Maharashtra's Nashik belt account for the majority of export-grade dehydration capacity, exposing buyers to climate disruption and logistics bottlenecks.
- Freeze-Drying Capital Intensity:Vacuum sublimation equipment requires 3-4x the capital expenditure of air-drying tunnels, limiting premium product expansion to well-capitalized processors.
Strategic Opportunities
- Organic Certification Pipeline:India's APEDA organic export incentives and the EU's Green Deal procurement preferences are opening premium positioning for certified organic onion flakes in German and Dutch retail channels.
- Pharmaceutical Extract Applications:Quercetin and sulfur compound extraction from onion waste streams is creating secondary revenue channels for processors with solvent extraction capabilities.
- Cold-Chain Integration:Jain Farm Fresh and Olam Food Ingredients are extending controlled-atmosphere storage from fresh bulb trading into dehydration corridors, reducing pre-processing spoilage losses.
Industry Challenges
- Skilled Technician Scarcity:Automated optical sorting and moisture-control systems require trained operators that remain concentrated in Gujarat's established processing clusters, constraining expansion into Bihar and Madhya Pradesh.
- Multi-Jurisdiction Certification Burden:Simultaneous compliance with India's FSSAI pesticide residue protocols, EU REACH documentation, and USDA organic equivalency creates 18-24 month approval timelines for new export entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Onion Market |
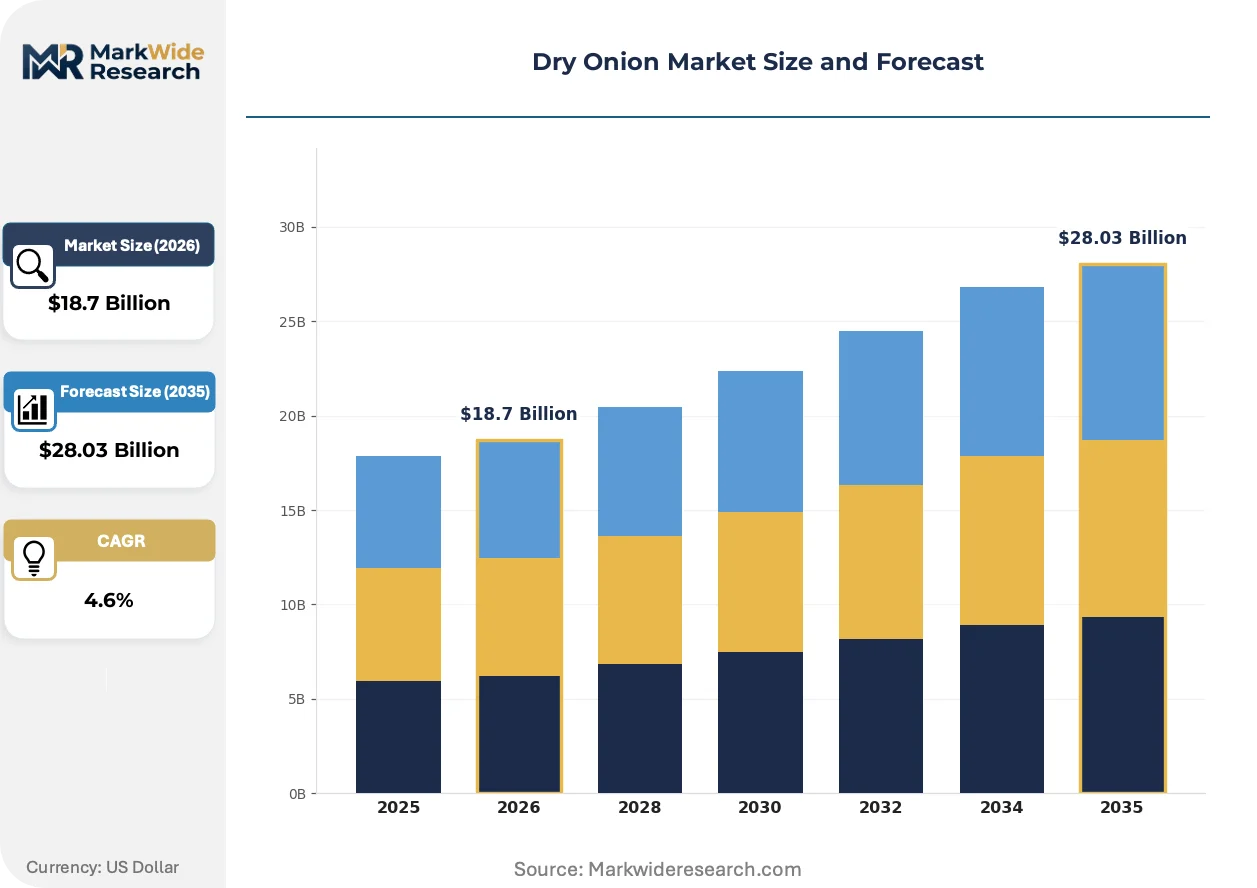
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dehydrated Onion, Onion Powder, Onion Flakes, Onion Granules Application: Food Processing, Seasoning, Soups, Sauces End User: Food Manufacturers, Restaurants, Retailers, Home Cooks Distribution Channel: Online Retail, Supermarkets, Wholesale, Direct Sales |
| Companies Covered | Olam Food Ingredients, Jain Farm Fresh Foods Limited, Sensient Natural Ingredients, Kings Dehydrated Foods Pvt. Ltd., Daksh Foods Pvt. Ltd., Van Drunen Farms, McCormick & Company, Real Dehydrates Pvt. Ltd., Earth Expo Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Onion Market Emerging Trajectories
Processing technology diffusion and regulatory disclosure mandates are restructuring competitive advantage around traceability infrastructure and energy efficiency rather than scale alone. These forces favor integrated operators with captive raw material sourcing and in-house laboratory capabilities.
Low-temperature vacuum dehydration is decentralizing production geography by reducing the energy cost penalty that historically concentrated processing in natural gas-rich regions. Mid-sized operators in Tamil Nadu and Andhra Pradesh are adopting Chinese-manufactured vacuum belt dryers to compete with Gujarat's established air-drying base. This technology diffusion is compressing the historical cost advantage of scale by enabling smaller batch production with comparable shelf stability.
REACH registration requirements for food contact substances are forcing exporters to document supply chain chemical exposure at the farm level. ECHA's expanded substance evaluation criteria now cover processing aids and packaging migrants previously exempt from disclosure. Indian exporters to Germany and the Netherlands are responding by deploying blockchain-based farm-to-facility traceability systems to satisfy downstream due diligence obligations.
Direct contracting between food manufacturers and dehydration facilities is displacing spot-market procurement through commodity traders. Large European seasoning houses now require multi-year supply agreements with embedded quality auditing rights and carbon footprint disclosure. This relationship compression is most visible in the Netherlands and Germany, where retail private-label specifications now mandate supplier-specific sustainability scorecards alongside traditional technical parameters.
Dry Onion Market Segmentation
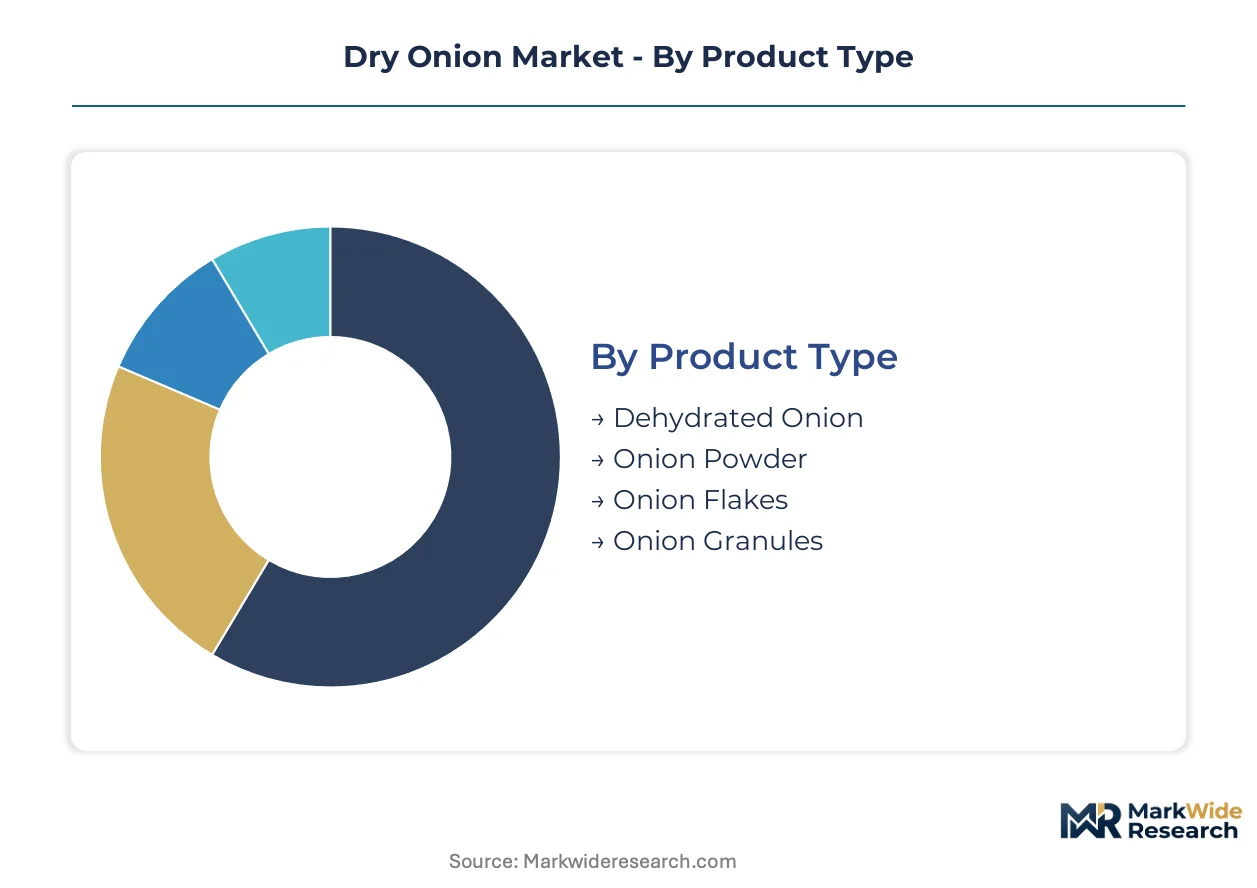
Product format selection in the dry onion market hinges on rehydration speed, flavor intensity, and visual requirements across downstream applications. Procurement managers weight moisture specification, particle size distribution, and shelf stability differently depending on whether the input serves industrial sauce bases or retail seasoning blends.
Product Type:
Buyers prioritize moisture content and particle geometry based on their formulation equipment and end-product texture requirements.
- Dehydrated Onion:Air-dried bulbs processed to below 7 percent moisture retain volatile sulfur compounds for flavor intensity. Food manufacturers in Germany and the Netherlands specify this format for soup and sauce bases where rapid rehydration in hot liquids accelerates production cycles.
- Onion Powder:Fine-ground dehydrated material passes through 80-100 mesh screens for homogeneous dispersion. Seasoning houses in Maharashtra and Gujarat blend this into standardized masala formulations where consistent flavor dosing reduces batch-to-batch variation.
- Onion Flakes:Larger cut sizes (3-10mm) provide visible texture in finished products. Retail private-label programs in European supermarkets specify flakes for premium soup mixes where consumer perception of ingredient integrity commands shelf price premiums.
- Onion Granules:Intermediate particle sizes balance solubility speed with visual presence. Quick-service restaurant chains in the United States incorporate granules into seasoning shakers and dry rub formulations where controlled dissolution prevents clumping during application.
Dehydrated onion leads on scale; onion granules lead on momentum.
Application:
Application segmentation reflects equipment compatibility and flavor delivery timing in manufacturing workflows.
- Food Processing:Industrial-scale dehydration inputs serve ready-meal manufacturers requiring year-round supply consistency. Processors in Nashik and Indore calibrate moisture specifications to match retort processing parameters for European frozen dinner contracts.
- Seasoning:Dry onion components blend with salt, spices, and anti-caking agents for table-top and industrial use. FSSAI-mandated additive disclosure requirements shape formulation choices for Indian exporters targeting Middle Eastern retail channels.
- Soups:Visible flake inclusions and rapid rehydration properties define technical specifications. German and Dutch buyers require EFSA-compliant mycotoxin documentation for dehydrated vegetable inputs in canned and dried soup production.
- Sauces:Fine powders dissolve into emulsified bases without residual grit. Hot sauce and condiment manufacturers in Louisiana and California specify low-moisture onion powder to prevent water activity spikes that compromise microbial stability.
Food processing anchors volume commitment; seasoning applications are expanding most quickly.
End User:
End-user categories separate by procurement scale, specification stringency, and quality auditing requirements.
- Food Manufacturers:Industrial buyers impose multi-year supply agreements with embedded laboratory testing rights. European seasoning houses now mandate carbon footprint disclosure alongside traditional technical parameters in supplier scorecards.
- Restaurants:Commercial kitchen procurement favors pre-portioned formats that reduce labor and waste. Chain operators in the United States specify calibrated scoop measures for consistent recipe execution across franchise locations.
- Retailers:Private-label programs require traceability documentation from farm to facility. German and Dutch supermarket chains deploy blockchain verification to satisfy EU Green Deal procurement preferences and consumer transparency demands.
- Home Cooks:Small-format retail packaging emphasizes convenience and storage stability. E-commerce platforms in India aggregate this demand through subscription models for urban households with limited fresh market access.
Food manufacturers dominate contract value; retailers are gaining share fastest.
Distribution Channel:
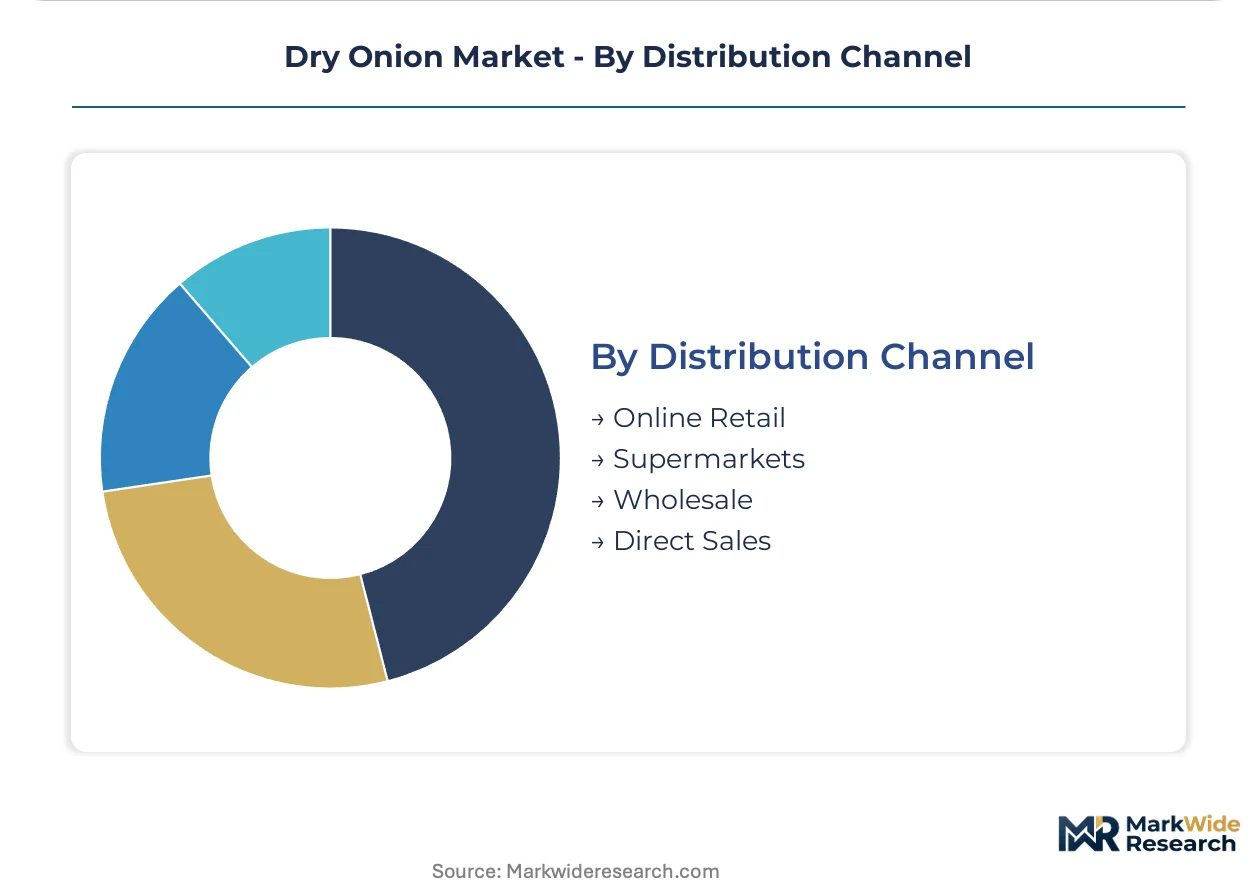
Channel selection reflects buyer scale, specification complexity, and logistics infrastructure requirements.
- Online Retail:Direct-to-consumer platforms aggregate fragmented demand for specialty formats. Indian aggregators connect Nashik processors with diaspora consumers in North America seeking specific regional onion varieties.
- Supermarkets:Mass retail channels move standardized SKUs with national brand recognition. Shelf placement negotiations in European chains increasingly weight sustainability certification alongside traditional trade terms.
- Wholesale:Volume distributors serve foodservice and small manufacturing accounts with less stringent documentation requirements. Spot-market liquidity in Gujarat's Kutch district attracts buyers seeking price arbitrage during harvest windows.
- Direct Sales:Long-term contracts between dehydration facilities and end manufacturers displace intermediary traders. Dutch and German seasoning houses now require supplier-specific sustainability scorecards embedded in multi-year agreements.
Direct sales command the steepest expansion trajectory; supermarkets retain the broadest geographic footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as processors migrate toward jurisdictions with lower compliance costs while maintaining quality certification. India's FSSAI export protocols and the EU's REACH documentation requirements create divergent cost structures that influence facility siting decisions.
India
Maharashtra's Nashik belt and Gujarat's Kutch district host the dominant dehydration capacity serving European seasoning houses. FSSAI pesticide residue mandates and APEDA organic export incentives shape processor investment decisions. Nashik processors are deploying solar-assisted tunnels to stabilize operating costs during monsoon seasons.
Germany
German seasoning manufacturers drive demand for EFSA-compliant mycotoxin documentation in dehydrated vegetable inputs. REACH registration requirements for food contact substances force exporters to document supply chain chemical exposure at the farm level. Dutch and German retail private-label programs now mandate blockchain-based farm-to-facility traceability systems.
United States
Louisiana and California hot sauce manufacturers specify low-moisture onion powder to prevent water activity spikes. USDA and FDA import inspections and labeling requirements shape North American trade flows. Quick-service restaurant chains incorporate calibrated granule formats into seasoning shakers for consistent franchise execution.
Netherlands
Dutch supermarket chains deploy blockchain verification to satisfy EU Green Deal procurement preferences. ECHA's expanded substance evaluation criteria now cover processing aids and packaging migrants previously exempt from disclosure. Direct contracting between Dutch seasoning houses and dehydration facilities is displacing spot-market procurement through commodity traders.
China
Chinese-manufactured vacuum belt dryers are diffusing to mid-sized operators in Tamil Nadu and Andhra Pradesh, compressing historical cost advantages of scale. Domestic food processors in the Yangtze River Delta region standardize onion powder inclusion rates across soup and sauce formulations. SAMR food safety standards and dual carbon goals influence equipment upgrade cycles.
Dry Onion Market Vendor Landscape
Indian producers anchor one tier; North American and European specialists hold differentiated positions in premium traceability segments. The market structures around three archetypes: integrated agribusiness operators with captive raw material sourcing, mid-scale regional dehydrators serving domestic food manufacturers, and specialty ingredient houses focused on organic and pharmaceutical-grade extraction. Capacity expansion and backward integration into controlled-atmosphere storage represent the dominant competitive moves as processors seek to reduce pre-processing spoilage losses.
Among India-based integrated operators, Olam Food Ingredients and Jain Farm Fresh Foods Limited exemplify the captive-sourcing archetype, while Sensient Natural Ingredients occupies a position within the North American specialty tier. Kings Dehydrated Foods Pvt. Ltd. and Daksh Foods Pvt. Ltd. represent the mid-scale regional fabricator segment concentrated in Maharashtra and Gujarat processing corridors. These company groupings illustrate how competitive positioning increasingly depends on traceability infrastructure and certification depth rather than dehydration capacity alone.
| Leading Market Players |
|---|
| Olam Food Ingredients |
| Jain Farm Fresh Foods Limited |
| Sensient Natural Ingredients |
| Kings Dehydrated Foods Pvt. Ltd. |
| Daksh Foods Pvt. Ltd. |
| Van Drunen Farms |
| McCormick & Company |
| Real Dehydrates Pvt. Ltd. |
| Earth Expo Company |
| Others |
Supply Flow & Price Mechanics
EU Green Deal procurement mandates gate qualified supply and premium-tier pricing access for dehydrated onion processors seeking entry into German and Dutch retail channels. Carbon footprint disclosure requirements and blockchain traceability obligations now separate contract-eligible suppliers from spot-market participants, compressing margins for non-compliant operators while elevating certified facilities to preferred-supplier status.
Pricing Analysis
Distributor margin layers in European seasoning supply compress at 15-25 percent for standard-grade dehydrated onion, while direct-to-manufacturer contracts command 8-12 percent discounts for volume commitments exceeding container-load thresholds. Three-tier pricing structure across organic-certified, conventional export-grade, and domestic-standard levels reflects FSSAI compliance depth and EFSA mycotoxin documentation completeness. Pricing pressure stems from Maharashtra harvest volatility and natural gas cost swings during monsoon seasons, forcing processors to absorb input spikes or risk contract cancellation. Small-scale food manufacturers exhibit highest price sensitivity, while Dutch supermarket private-label programs prioritize certification depth over per-kilogram cost.
Supply Chain Analysis
EFSA mycotoxin certification and REACH registration documentation gate market access for Indian dehydration facilities serving European buyers. Geographic concentration centers on India, China, and Egypt, with Maharashtra's Nashik belt and Gujarat's Kutch district anchoring export-grade capacity. Raw material dependencies draw from fresh bulb procurement cycles in Karnataka and Maharashtra, natural gas or solar thermal energy inputs, and food-grade packaging materials. Single-source vulnerability runs through Gujarat's processing corridor, where climate disruption or logistics bottlenecks cascade through European seasoning house supply chains. Distribution runs through direct long-term contracts displacing commodity traders, with blockchain-verified traceability now mandatory for German and Dutch retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between India's FSSAI-regulated export infrastructure and the EU's REACH-compliant premium tier, where compliance cost differentials of 18-24 month approval timelines create sustainable margin capture for early-certified entrants.
For Market Incumbents: Deepen captive sourcing through controlled-atmosphere storage investments in Nashik and Indore corridors to reduce pre-processing spoilage losses. Anchor contract renewals by deploying in-house mycotoxin testing laboratories that satisfy Dutch and German seasoning house audit rights. Defend against mid-scale Tamil Nadu and Andhra Pradesh competitors adopting Chinese-manufactured vacuum belt dryers by accelerating solar-assisted tunnel deployment to stabilize monsoon-season operating costs. For New Entrants and Emerging Players: Small-format retail packaging for Indian urban households with limited fresh market access represents the most penetrable white-space target. Organic-certified onion flakes for German and Dutch retail channels offer premium positioning with APEDA export incentive support. Pharmaceutical extract applications from onion waste streams provide secondary revenue channels with solvent extraction capabilities as entry wedge. Target direct-to-consumer e-commerce platforms aggregating diaspora demand in North America for specific regional onion varieties. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale regional dehydrators in Maharashtra and Gujarat lacking integrated cold-chain infrastructure but possessing FSSAI export certification. Long-term viability over the projection horizon favors processors with backward integration into controlled-atmosphere storage and in-house laboratory capabilities. Acquisition target archetype: certified facilities with underutilized capacity and pending EU organic equivalency approval. Watch solar drying adoption rates among Nashik processors as inflection indicator for operating cost competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled-Atmosphere Storage | Jain Farm Fresh and Olam Food Ingredients extend cold-chain infrastructure to reduce pre-processing spoilage losses. |
| Solar-Assisted Dehydration Tunnel Deployment | Nashik and Indore processors stabilize operating costs during monsoon seasons through natural gas substitution. |
| Blockchain Farm-to-Facility Traceability Implementation | Indian exporters satisfy ECHA substance evaluation and Dutch supermarket Green Deal procurement preferences. |
| In-House Mycotoxin Testing Laboratory Investment | Certified facilities capture volume from EFSA-compliant European seasoning houses filtering non-compliant processors. |
| Organic Certification Pipeline Development | APEDA export incentives and EU Green Deal preferences open premium positioning for certified onion flakes. |
Methodological Framework
Coverage spans India, Germany, the Netherlands, the United States, and China, with primary inputs from each region's dehydration processing corridors and seasoning manufacturing hubs. The analysis combines primary interviews with dehydration plant managers, procurement leads at European seasoning houses, APEDA export certification officers, and cold-chain logistics operators with secondary validation from FSSAI regulatory filings, EFSA mycotoxin standards documentation, EU REACH registration databases, and customs trade records. Bottom-up capacity assessments across Maharashtra and Gujarat processing facilities triangulate against top-down demand estimates from European and North American food manufacturer procurement data.
Granularity-level modeling disaggregates volume and value outputs across product type (dehydrated onion, onion powder, flakes, granules), application (food processing, seasoning, soups, sauces), and end user (food manufacturers, restaurants, retailers, home cooks) dimensions. CAGRs derive from segment-specific growth trajectories calibrated against historical price volatility in Maharashtra fresh onion markets and solar drying adoption curves. Forecast inputs incorporate FSSAI pesticide residue protocol evolution, EFSA mycotoxin limit revisions, and carbon footprint disclosure mandate diffusion across European buying desks.
Underlying measurement precision varies by segment; organic-certified and EFSA-compliant product categories carry tighter precision than domestic-standard grades due to more complete trade documentation. Forecasts reflect assumptions around regulatory stability in India-EU trade relations and solar technology cost curves. A model refresh is warranted upon material change in EU Green Deal procurement enforcement or FSSAI export protocol harmonization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Greenhouse Bell Pepper Market
Vegetables
Zimbabwe Fruits and Vegetables Market
Vegetables
Saudi Arabia Greenhouse Horticulture Market
Vegetables
Potato Market
Vegetables
Spain Greenhouse Horticulture Market
Vegetables
United States Microgreens Market
Vegetables
Roselle Market
Vegetables
Carrots and Turnips Market
Vegetables
Squash Market
Vegetables
Vegetable Chutney Market
Vegetables
Garden Cress Market
Vegetables
Dried Vegetable Market
Vegetables
Japan Greenhouse Horticulture Market
Vegetables
UAE Greenhouse Horticulture Market
Vegetables
Sprouts Market
Vegetables
Air Dried Vegetables Market