
 Cabbages and Other Brassicas Market | 2026-2036
Cabbages and Other Brassicas Market Size, Share, and Industry Trends Forecast 2026-2036
Cabbages and Other Brassicas Market Outlook
EU Green Deal is realigning the cost-of-entry calculus for European brassica producers by mandating reduced chemical inputs and traceable supply chains. Bayer leverages its seed technology portfolio to sustain competitive positioning across hybrid cabbage lines. Syngenta anchors its presence through integrated crop protection and digital farming platforms. Rijk Zwaan differentiates via proprietary high-yield cauliflower varieties bred for extended harvest windows.
Cabbages and other brassicas comprise leafy and heading vegetable crops from the species Brassica oleracea and related taxa, cultivated for their dense heads, florets, or leaves with typical field maturity ranging from 60 to 120 days depending on cultivar and climate zone. These crops serve as staple fresh vegetables, processed food inputs, and raw material for coleslaw, sauerkraut, and frozen vegetable products across retail and foodservice channels. Broccoli and cauliflower command premium shelf positioning in supermarkets as consumers prioritize cruciferous vegetable intake for perceived health benefits. Food processors concentrate procurement on bulk-grade red and green cabbage for fermentation and freezing operations where uniform bulb size reduces trimming waste.
EU Green Deal and REACH frameworks govern pesticide maximum residue limits and fertilizer composition across European production zones, while FDA and USDA grading standards shape import acceptance criteria for brassicas entering the United States. China's GB standards and Ministry of Agriculture and Rural Affairs directives regulate domestic cultivation permits and variety registration for commercial seed distribution. Stakeholders must monitor divergence between EU Farm to Fork compliance timelines and emerging market quality benchmarks to calibrate seed development and post-harvest investment priorities.
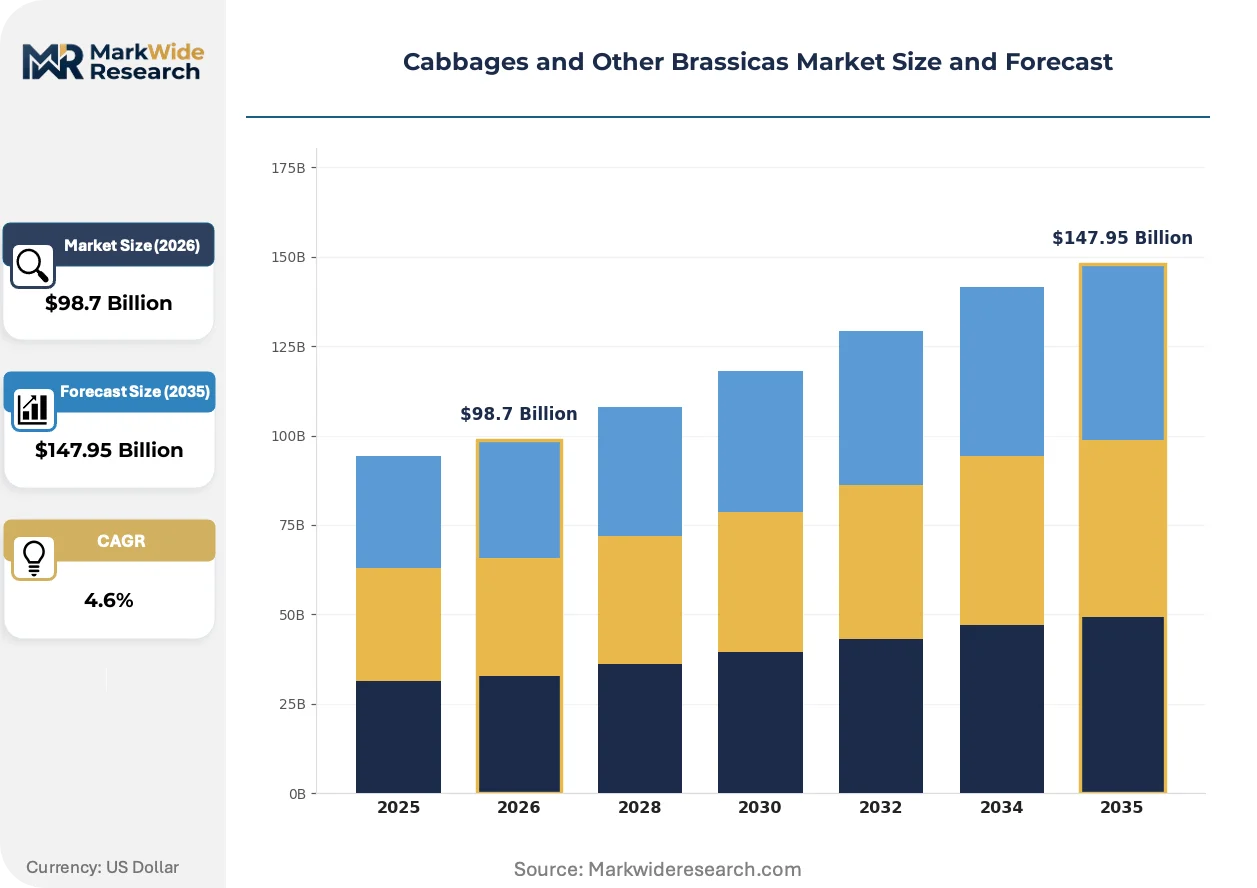
Market Dynamics
EU Green Deal pesticide residue mandates are compressing grower margins while simultaneously erecting compliance barriers that favor capitalized operations with integrated cold-chain and traceability infrastructure.
Growth Catalysts
- Foodservice Cold-Chain Expansion:Restaurant chains in China are extending procurement contracts to Yunnan and Shandong growing clusters as refrigerated logistics networks mature. This locks in year-round supply commitments that stabilize grower revenue.
- EU Farm to Fork Strategy:The regulatory framework is accelerating certified sustainable cultivation adoption by tightening maximum residue limits and mandating supply chain traceability. Premium-positioned producers gain shelf access in EU retail channels.
- Cruciferous Health Positioning:Broccoli and cauliflower are capturing expanded supermarket shelf space as consumer preference tilts toward vegetables with documented glucosinolate content. Retailers are reallocating produce section layout to feature these varieties.
Market Restraints
- Input Cost Volatility:Nitrogen fertilizer prices fluctuate with natural gas benchmarks, exposing open-field cabbage operations to margin compression during planting windows. This cost instability discourages long-term contract pricing.
- Seed Supply Concentration:Hybrid brassica germplasm development rests with a narrow base of specialized breeders, creating varietal availability bottlenecks for growers seeking region-specific disease resistance traits.
- Fresh Substitute Competition:Leafy greens from alternative botanical families compete for the same refrigerated distribution capacity and retail shelf positioning, pressuring brassica volume commitments during peak harvest periods.
Strategic Opportunities
- Processing-Grade Contracting:Bulk red and green cabbage supply for fermentation and freezing operations remains underpenetrated by vertically coordinated grower-processor partnerships. Uniform bulb size specifications reduce trimming waste and command volume premiums.
- Digital Farming Convergence:Remote sensing platforms combined with predictive harvest timing algorithms enable precision irrigation and labor scheduling. Early adopters in commercial brassica operations are compressing field maturity variance.
- India Cold-Chain Investment:National highway corridor refrigeration infrastructure is expanding distribution reach from Gujarat and Maharashtra production zones to eastern urban consumption centers. This geographic extension opens procurement relationships with organized retail.
Industry Challenges
- Integrated Pest Management Expertise Gap:Reduced chemical input mandates require agronomists trained in biological control deployment and pest population monitoring. Qualified personnel scarcity slows compliance transition timelines for mid-scale operations.
- Post-Harvest Capex Burden:Hydrocooling and controlled-atmosphere storage equipment demands upfront capital outlays that strain balance sheets. Financing access varies sharply across cooperative and independent grower structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cabbages and Other Brassicas Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $147.95 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Cabbage, Red Cabbage, Broccoli, Cauliflower Distribution Channel: Supermarkets, Farmers Markets, Online Retailers, Wholesalers End User: Households, Restaurants, Food Processors, Catering Services Packaging Type: Plastic Bags, Cartons, Bulk Bins, Trays |
| Companies Covered | Bayer, Sakata Seed, Hazera Seeds, Bejo Seeds, Enza Zaden, Rijk Zwaan, Takii Seed, Limagrain, Syngenta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cabbages and Other Brassicas Market Strategic Shifts
Biological crop protection, precision harvest timing, and supply chain digitization are converging to reshape cost structures and quality benchmarks across brassica production systems.
RNA interference-based biopesticides are consolidating their position in brassica pest management by targeting diamondback moth larvae with species-specific RNA molecules. Large-scale greenhouse operators in the Netherlands are adopting these formulations at accelerated rates. The technology is consolidating grower dependence on specialized biocontrol suppliers while reducing broad-spectrum chemical inventory.
REACH framework amendments governing fertilizer composition and soil amendment standards are forcing reformulation of conventional nitrogen delivery systems across European production zones. Growers face transition costs for compliant input sourcing and documentation. Open-field operations in Poland and Spain are responding by piloting controlled-release formulations that align with residue monitoring protocols.
Direct procurement relationships between institutional foodservice operators and regional growing cooperatives are displacing traditional wholesale auction channels. Restaurant chains are negotiating fixed-price contracts with specified quality grades and delivery windows. This pattern is most visible in China's eastern seaboard cities where cold-chain reliability now permits bypass of terminal market intermediaries.
Cabbages and Other Brassicas Market Segmentation
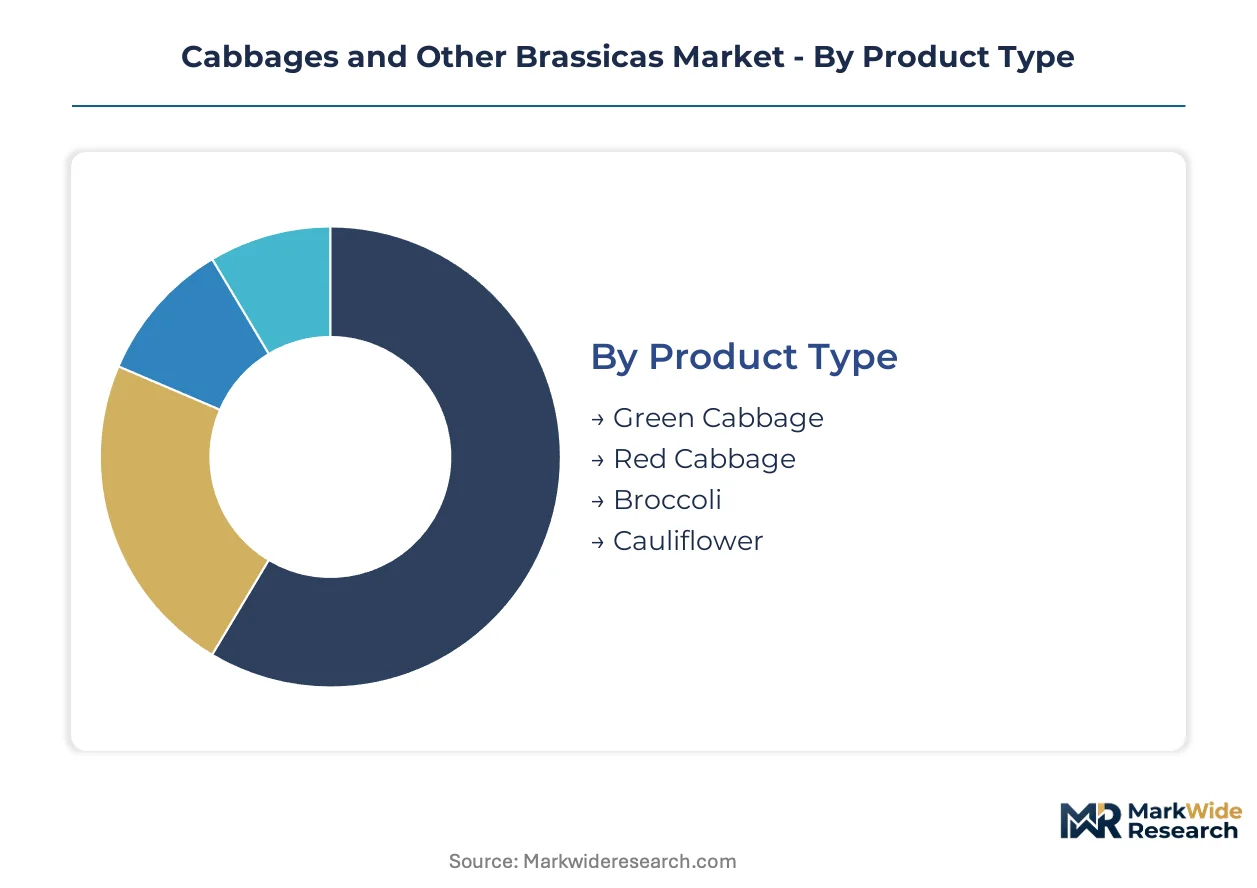
Brassica market segmentation reveals how distinct supply chains, regulatory burdens, and customer specifications fragment procurement patterns. Each dimension carries unique certification requirements and margin structures that shape competitive positioning.
Product Type:
EU Green Deal pesticide residue mandates and FDA import standards impose divergent compliance costs across fresh versus processed brassica lines. Green Cabbage and Red Cabbage face stricter maximum residue limits for foodservice contracts, while Broccoli and Cauliflower navigate glucosinolate content specifications for health-positioned retail.
- Green Cabbage:Dense-headed varieties with 60-90 day field maturity dominate fermentation and coleslaw processing. Demand concentrates in Poland and Germany where sauerkraut manufacturers require uniform bulb sizing to minimize trimming losses. EU Farm to Fork traceability mandates are compressing margins for non-certified growers.
- Broccoli:Florets with documented glucosinolate profiles command premium shelf positioning in US and Chinese supermarkets. Restaurant chains in Shanghai and Beijing are locking in year-round procurement contracts as Yunnan cold-chain infrastructure matures. Health-conscious consumers are reallocating produce budgets toward this segment.
- Red Cabbage:Anthocyanin-rich heads serve niche fresh and pickled applications with shorter harvest windows than green varieties.
- Cauliflower:Extended harvest window varieties from specialized breeders anchor fresh and frozen vegetable programs.
Leading the category by volume: Green Cabbage. Growing fastest: Broccoli.
Distribution Channel:
Channel selection dictates capital intensity and working capital cycles, with direct procurement relationships displacing traditional intermediaries fastest in markets with reliable cold-chain infrastructure.
- Supermarkets:Temperature-controlled display cases and just-in-time replenishment systems dominate fresh brassica retail in urban China and the United States. Chains are tightening residue documentation requirements and favoring suppliers with integrated traceability platforms. Shelf space allocation increasingly favors cruciferous health-positioned varieties.
- Online Retailers:Same-day delivery platforms in China's eastern seaboard cities are capturing household brassica purchases through subscription vegetable boxes. Cold-chain reliability investments by JD.com and Meituan are compressing delivery windows and expanding geographic reach from Yunnan and Shandong production clusters.
- Farmers Markets:Direct producer-to-consumer sales bypass wholesale markups but face seasonal availability constraints.
- Wholesalers:Terminal market intermediaries retain dominance where cold-chain gaps persist, though restaurant chains are bypassing this channel where possible.
Supermarkets retain volume leadership. Online Retailers are expanding most quickly in organized retail corridors.
End User:
Customer type determines specification stringency, with institutional foodservice operators imposing the most demanding quality grading and delivery window requirements.
- Food Processors:Bulk-grade red and green cabbage procurement for fermentation and freezing operations demands uniform bulb size to reduce trimming waste. Polish and German processors are negotiating fixed-price contracts with specified delivery windows. This segment commands volume premiums for compliant supply.
- Restaurants:Chain operators in China are extending procurement contracts to Yunnan and Shandong growing clusters as refrigerated logistics networks mature. Consistent year-round supply specifications are displacing spot market purchasing for brassica-intensive menu items.
- Households:Price-sensitive fresh purchases concentrate in supermarket and online channels with high frequency, low basket size patterns.
- Catering Services:Institutional volume requirements favor wholesalers with scale, though direct contracting is emerging where cold-chain permits.
Food Processors lead by procurement volume. Restaurants are gaining share fastest through contract consolidation.
Packaging Type:
Packaging selection reflects trade-offs between shelf-life extension, retail presentation requirements, and sustainability compliance pressures.
- Plastic Bags:Polyethylene films dominate fresh retail brassica packaging for cost and moisture retention. EU REACH framework amendments on plastic composition are forcing reformulation investments. Retailers in Germany and France are accelerating transitions to compliant specifications.
- Cartons:Corrugated containers with modified atmosphere properties serve longer-distance distribution from Shandong to China's eastern seaboard. Stackability and printability for branding favor this format in organized retail channels.
- Bulk Bins:Reusable containers dominate foodservice and processing procurement where handling efficiency outweighs presentation requirements.
- Trays:Pre-portioned formats with film overwrap capture premium positioning for convenience-oriented household segments.
Plastic Bags lead by deployment volume. Cartons are climbing the fastest on sustainability-driven retailer mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yunnan and Shandong provinces anchor China's brassica supply expansion through cold-chain infrastructure investments connecting western growing clusters to eastern consumption centers.
China
Restaurant chains in Shanghai and Beijing are locking in year-round procurement contracts as refrigerated logistics networks mature from Yunnan and Shandong production zones. GB standards and Ministry of Agriculture directives regulate variety registration and cultivation permits for commercial seed distribution. Eastern seaboard cities now receive direct shipments bypassing traditional wholesale intermediaries.
United States
Supermarkets are reallocating produce section layout toward broccoli and cauliflower varieties with documented glucosinolate content for health-conscious consumers. FDA and USDA grading standards shape import acceptance criteria for brassicas entering through Pacific and Atlantic ports. California's Central Valley and Arizona's Yuma growing districts supply the bulk of domestic fresh production.
Germany
Sauerkraut manufacturers in Bavaria and Saxony require uniform green cabbage bulb sizing to minimize trimming losses in fermentation operations. EU Green Deal Farm to Fork Strategy mandates tightened pesticide residue thresholds and traceable supply chains for retail channel access. Polish border regions supply cross-border processing-grade volumes under integrated contracting arrangements.
India
National highway corridor refrigeration infrastructure is extending distribution reach from Gujarat and Maharashtra production zones to eastern urban consumption centers. FSSAI regulations govern food safety standards for interstate vegetable commerce. Organized retail in Delhi-NCR and Mumbai are establishing direct procurement relationships with cooperative growing clusters.
Netherlands
Large-scale greenhouse operators are adopting RNA interference-based biopesticides for diamondback moth management at accelerated rates. REACH framework amendments force reformulation of conventional nitrogen delivery systems and soil amendment standards. Westland and North Brabant growing regions pilot controlled-release fertilizer formulations aligning with residue monitoring protocols.
Cabbages and Other Brassicas Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across hybrid seed development and integrated crop protection platforms. The vendor base clusters around three strategic archetypes: multinational agrochemical conglomerates with seed technology portfolios, specialized vegetable breeding houses with proprietary germplasm libraries, and regional seed distributors with localized variety adaptation capabilities. Dominant competitive moves include technology licensing agreements for trait insertion and backward integration into captive germplasm development.
Among diversified agrochemical conglomerates, Bayer and Syngenta exemplify scale-driven positioning through integrated crop protection and digital farming platforms. Specialized breeding houses include Rijk Zwaan and Sakata Seed, which occupy positions defined by proprietary high-yield varieties and extended harvest window genetics. These archetypes represent contrasting strategic postures: breadth versus depth in germplasm control.
| Leading Market Players |
|---|
| Bayer |
| Sakata Seed |
| Hazera Seeds |
| Bejo Seeds |
| Enza Zaden |
| Rijk Zwaan |
| Takii Seed |
| Limagrain |
| Syngenta |
| Others |
Value Chain & Pricing Dynamics
RNA interference-based biopesticide adoption among Dutch greenhouse operators simultaneously compresses per-hectare pest management costs and consolidates supplier dependence toward specialized biocontrol firms, reshaping procurement economics for brassica growers across integrated and open-field systems.
Pricing Analysis
Premium pricing attaches to short-lead-time delivery windows for fresh broccoli and cauliflower consignments to Shanghai restaurant chains, while spot inventory of bulk-grade green cabbage for Polish fermentation processors trades at discounted levels. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade under EU Farm to Fork traceability mandates and volume scale for institutional contracts. Cost compression in open-field cabbage operations is intensifying because nitrogen fertilizer price volatility tied to natural gas benchmarks exposes growers to margin erosion during planting windows. Food processors negotiating fixed-price contracts demonstrate lowest price sensitivity due to waste-reduction specifications, while spot-market-dependent wholesalers face acute margin pressure.
Supply Chain Analysis
Certification gating through EU Green Deal pesticide residue mandates and FDA import standards fragments supplier eligibility, with only capitalized operations bearing integrated cold-chain and traceability infrastructure qualifying for premium channel access. Geographic supply concentrates in China, the Netherlands, and Poland, with Yunnan and Shandong clusters feeding eastern seaboard cities, Westland greenhouses serving European retail, and Polish border regions supplying German sauerkraut manufacturers. Raw material dependencies center on hybrid brassica germplasm from specialized breeders, nitrogen fertilizer formulations, and controlled-release soil amendments. Single-source vulnerability in hybrid seed development creates varietal availability bottlenecks for region-specific disease resistance traits. Distribution runs through direct procurement relationships between restaurant chains and growing cooperatives where cold-chain reliability permits, displacing traditional wholesale auction channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal compliance timelines and input cost volatility are forcing consolidation among mid-scale brassica growers lacking integrated cold-chain infrastructure, privileging capitalized operations with traceability platforms and biological control expertise.
For Market Incumbents: Lock in germplasm exclusivity through captive breeding programs or long-term licensing with Rijk Zwaan and Sakata Seed to defend against varietal commoditization. Secure backward integration into hydrocooling and controlled-atmosphere storage equipment to reduce post-harvest capex burden exposure and tighten margin control across the value chain. For New Entrants and Emerging Players: Restaurant chain procurement officers represent the most accessible entry point, as direct contracting relationships with Yunnan and Shandong growing clusters remain underpenetrated by digitally native supply platforms. Target processing-grade red and green cabbage supply for Polish and German fermentation operations where uniform bulb size specifications command volume premiums and incumbent coordination lags. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified agrochemical conglomerates seeking germplasm libraries and regional variety adaptation capabilities. Mid-scale cooperatives with integrated cold-chain infrastructure and EU Farm to Fork certification readiness offer strongest five-to-ten-year viability. Watch RNA interference biopesticide adoption rates among Dutch operators as inflection indicator for biological control supplier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Cold-Chain Investment | Direct procurement contracts with Shanghai restaurant chains bypass wholesale intermediaries and stabilize grower revenue. |
| Biological Crop Protection Adoption | RNA interference-based diamondback moth management reduces chemical inventory for Dutch greenhouse operators. |
| Processing-Grade Contracting | Fixed-price agreements with Polish sauerkraut manufacturers minimize trimming waste through uniform bulb specifications. |
| Digital Farming Platform Deployment | Predictive harvest timing algorithms enable precision irrigation scheduling for commercial brassica operations. |
| Certification Compliance Investment | EU Farm to Fork traceability mandates secure premium shelf access in German and French retail channels. |
Study Parameters
Independent corroboration across seed company technical directors, food processor procurement leads, and cold-chain logistics operators underwrites the qualitative findings. Primary interviews with brassica breeders, agronomists at cooperative growing clusters, restaurant chain supply chain managers, and supermarket category buyers combined with secondary validation from EU pesticide residue monitoring databases, Chinese customs trade records, and SEC filings of diversified agrochemical conglomerates. Bottom-up variety registration data and top-down regional production estimates were triangulated.
Comparable-period anchoring to historical cold-chain infrastructure buildout phases and biological control adoption curves shaped the projection horizon. Segmentation modeling spanned product type, distribution channel, end user, and packaging format dimensions across the analysis window. CAGRs were derived from supply-demand balance assessments incorporating germplasm development pipelines, nitrogen fertilizer price elasticity, and regulatory compliance cost trajectories. Forecast inputs included Yunnan-Shandong logistics maturity indicators and EU REACH amendment implementation schedules.
Caveats apply where RNA interference biopesticide regulatory approval delays or nitrogen fertilizer supply disruptions could materially shift the outlook. Forecasts reflect assumptions regarding cold-chain reliability improvements and substitution elasticity between brassica varieties and leafy greens from alternative botanical families. A model refresh is warranted upon material change in EU Farm to Fork maximum residue limit enforcement intensity or Chinese GB standards revision timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vegetables
Asparagus Market
Vegetables
UAE Greenhouse Horticulture Market
Vegetables
Yarrow Market
Vegetables
Fresh Mushroom Market
Vegetables
Hydroponic Vegetable Market
Vegetables
Dried Mushroom Market
Vegetables
Australia Greenhouse Horticulture Market
Vegetables
Greenhouse Bell Pepper Market
Vegetables
Cameroon Fruits and Vegetables Market
Vegetables
Qatar Greenhouse Market
Vegetables
Dried Peas Market
Vegetables
North America Peas Market
Vegetables
Global Indoor Plant Market
Vegetables
Peas Market
Vegetables
Europe Christmas Tree Market
Vegetables
Japan Greenhouse Horticulture Market